
 Complexion Analysis System Market | 2026-2036
Complexion Analysis System Market Size, Share, and Industry Trends Forecast 2026-2036
Complexion Analysis System Market Analysis
Dermatology clinics are rotating toward workstation systems with embedded machine learning pipelines, displacing standalone handheld devices in premium service tiers. Canfield Scientific leverages its R&D intensity across multispectral imaging hardware and cloud-based analytics platforms. MeituEve anchors consumer-to-clinic channel control through its beauty app ecosystem and professional device spinouts. FotoFinder Systems specializes in dermoscopy-to-complexion workflow integration, sustaining technology leadership in European dermatology networks.
Complexion analysis systems combine optical sensors, spectral imaging arrays, and algorithmic skin feature extraction to quantify pigmentation, texture, vascularity, and hydration with micron-level resolution. These systems serve dermatological diagnostics, cosmetic personalization, and treatment outcome verification across clinical and retail environments. Workstation systems capture the dominant margin pool due to bundled software-hardware service contracts and recurring calibration revenue. Machine learning segments are expanding fastest as computer vision architectures displace rule-based image processing in real-time skin assessment protocols.
FDA 510(k) software-as-medical-device pathways and EU MDR Class IIa certification requirements are reshaping product development cycles and market access timelines for complexion analysis platforms. ISO 13485 quality management standards govern manufacturing processes for systems deployed in clinical settings across North America and Europe. Stakeholders must monitor evolving regulatory distinctions between wellness-oriented beauty devices and diagnostic medical equipment, as classification decisions determine reimbursement eligibility and distribution channel requirements.
Market Dynamics
Machine learning pipelines embedded in spectroscopy hardware are compressing diagnostic timelines from hours to seconds, forcing dermatology clinics to retire standalone imaging devices and absorb workstation-level capital commitments.
Growth Catalysts
- FDA 510(k) software-as-medical-device pathway:The streamlined clearance mechanism accelerates commercialization for algorithmic skin assessment platforms, reducing regulatory friction for developers targeting US clinical deployment.
- South Korea medical aesthetics corridor:Seoul and Gangnam district clinic chains standardize on AI-powered diagnostic protocols, creating concentrated demand pull for integrated hardware-software systems.
- Cloud-native analytics architectures:Remote model updates and federated learning capabilities enable continuous algorithm refinement without hardware replacement cycles.
Market Restraints
- Multispectral sensor supply concentration:German and Japanese optical component manufacturers control critical imaging array supply, exposing device makers to single-source fragility.
- EU MDR Class IIa certification timelines:Extended conformity assessment procedures delay European market entry by 18-24 months versus predecessor directives.
- Handheld device margin erosion:Commoditized smartphone attachment peripherals undercut professional-grade hardware pricing in consumer-adjacent segments.
Strategic Opportunities
- Telemedicine integration protocols:Remote skin consultation platforms in Australia and Canada create demand for cloud-connected diagnostic devices with audit-grade image capture.
- Cosmetic personalization engines:Beauty retailers deploy complexion analysis for foundation matching and skincare regimen customization, opening non-clinical revenue channels.
- India PLI scheme for medical electronics:Domestic manufacturing incentives attract system assembly operations targeting price-sensitive Asian markets.
Industry Challenges
- Computer vision specialist scarcity:Dermatological algorithm development requires rare cross-training in clinical pathology and convolutional neural network architecture.
- ISO 13485 quality system implementation:Small developers face 12-18 month certification timelines before regulatory submission eligibility.
- Legacy PACS integration complexity:Hospital network procurement committees prioritize seamless connectivity with existing radiology infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Complexion Analysis System Market |
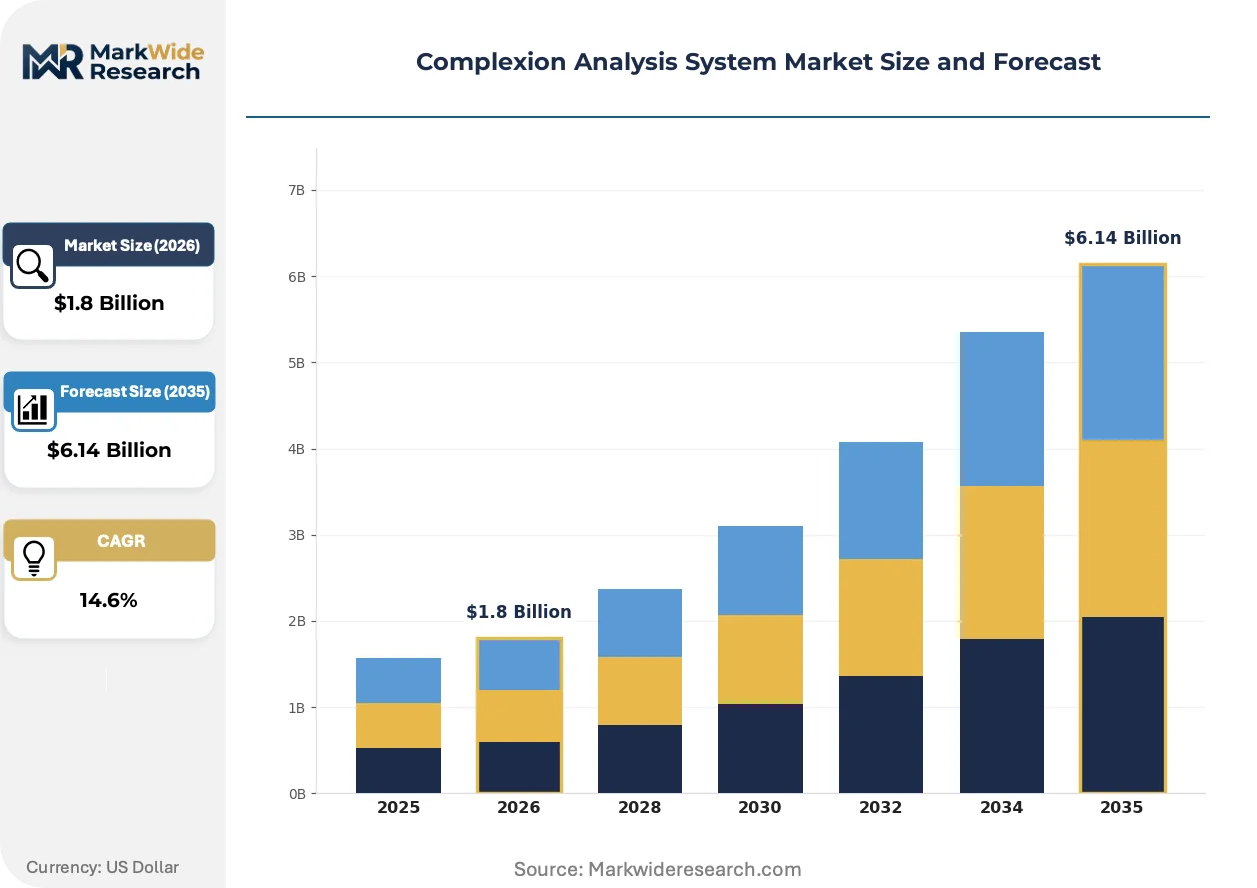
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Software Solutions, Workstation Systems, API Integrations Technology: Machine Learning, Computer Vision, Infrared Imaging, Spectroscopy End User: Dermatology Clinics, Beauty Salons, Research Institutions, Retail Stores Application: Skin Health Assessment, Cosmetic Formulation, Treatment Monitoring, Dermatological Research |
| Companies Covered | Canfield Scientific, MeituEve, Vibrant Skin Dermatology and Laser, FotoFinder Systems, Cortex Technology, NeoDerma Medical, Visiomed Group SA, Bio-Therapeutic Inc., Callegari Srl, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Complexion Analysis System Market Emerging Trajectories
Optical sensor miniaturization and edge computing deployment are collapsing the physical footprint of diagnostic-grade imaging while elevating real-time analytical throughput across clinical and retail environments.
Hyperspectral imaging arrays are decomposing the traditional separation between surface photography and subsurface vascular mapping. Seoul-based dermatology networks deploy these sensors for simultaneous melanin, hemoglobin, and collagen density quantification. The technology is decomposing standalone dermoscopy workflows into unified assessment protocols that compress patient chair time by 60%.
EU MDR Class IIa certification requirements are tightening clinical evidence standards for software-as-medical-device claims. Manufacturers must now submit prospective validation studies against histopathology reference standards. European dermatology networks delay procurement decisions pending notified body clearance, compressing competitive windows for first movers.
Subscription-based device access models are displacing capital purchase structures in mid-tier clinic chains. Korean and Australian aesthetic networks favor per-scan pricing bundled with algorithm update guarantees. This financing rotation concentrates vendor risk in utilization forecasting while lowering clinical customer entry barriers.
Complexion Analysis System Market Segmentation
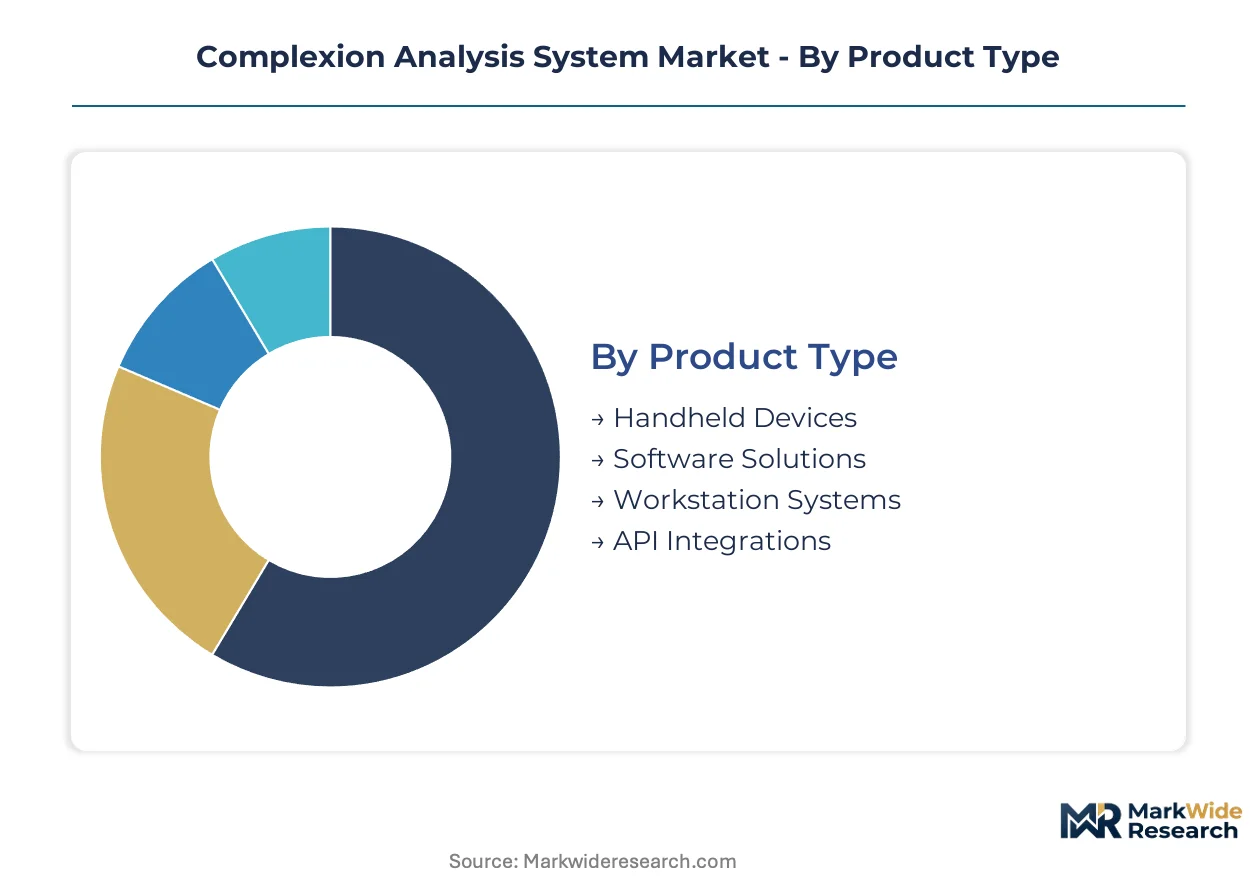
Channel economics in the complexion analysis system market diverge sharply between clinical procurement committees and retail impulse purchases. Workstation systems flow through capital equipment distributors with bundled service contracts, while handheld devices reach beauty salons through e-commerce marketplaces with minimal technical support.
Product Type:
Handheld devices penetrate beauty retail channels with minimal sales cycle friction, while workstation systems require clinical engineering validation and PACS integration testing before procurement approval.
- Workstation Systems:These integrated hardware-software platforms combine multispectral imaging arrays with embedded machine learning pipelines for real-time skin feature extraction. Seoul's Gangnam district dermatology chains standardize on these systems for melanin and hemoglobin quantification, absorbing capital commitments that compress diagnostic timelines from hours to seconds.
- Software Solutions:Cloud-native analytics platforms deliver algorithmic skin assessment through API architectures and federated learning capabilities. Australian telemedicine networks deploy these for remote consultation protocols with audit-grade image capture requirements, creating recurring subscription revenue streams independent of hardware replacement cycles.
- Handheld Devices:Smartphone-attachable peripherals and standalone imaging wands serve price-sensitive beauty salon segments in India and Southeast Asia.
- API Integrations:Embedded algorithm modules integrate into existing electronic health record systems and cosmetic personalization engines.
Workstation systems dominate installed base in clinical settings. API integrations are where expansion concentrates as telemedicine platforms demand seamless embedding.
Technology:
Cost tier stratification separates premium spectroscopy hardware from commoditized computer vision software, with infrared imaging occupying a mid-tier position in aesthetic clinic budgets.
- Spectroscopy:Hyperspectral imaging arrays decompose surface photography and subsurface vascular mapping into unified assessment protocols. Seoul-based dermatology networks deploy these sensors for simultaneous collagen density quantification, compressing patient chair time substantially while elevating diagnostic precision to histopathology-correlated standards.
- Machine Learning:Convolutional neural network architectures displace rule-based image processing in real-time skin assessment. FDA 510(k) software-as-medical-device pathways accelerate commercialization for these algorithmic platforms, though computer vision specialist scarcity constrains development velocity across the vendor landscape.
- Computer Vision:Traditional edge-detection and color-space analysis methods persist in entry-level handheld devices.
- Infrared Imaging:Subsurface vascular mapping and hydration assessment capabilities serve mid-tier clinic chains seeking diagnostic upgrade paths without full spectroscopy investment.
Spectroscopy commands premium pricing in clinical procurement. Machine learning is gaining share fastest as regulatory pathways mature and cloud-native deployment reduces infrastructure barriers.
End User:
Application requirements diverge between diagnostic-grade evidence standards in medical settings and experiential engagement priorities in retail environments.
- Dermatology Clinics:These clinical environments demand ISO 13485-certified systems with FDA 510(k) or EU MDR Class IIa clearance for diagnostic claims. European dermatology networks delay procurement pending notified body validation against histopathology reference standards, compressing competitive windows for algorithm developers.
- Beauty Salons:Korean and Australian aesthetic networks favor per-scan pricing models bundled with algorithm update guarantees, concentrating vendor risk in utilization forecasting while lowering customer entry barriers.
- Research Institutions:Academic dermatology departments and cosmetic science laboratories require raw spectral data export and custom algorithm development access.
- Retail Stores:Beauty retailers deploy foundation matching and skincare regimen customization systems for consumer engagement without clinical diagnostic claims.
Dermatology clinics anchor professional-grade revenue. Beauty salons are where volume expansion concentrates as subscription-based access models displace capital purchases.
Application:
Maturity gradients separate established diagnostic workflows from emerging cosmetic personalization use cases, with treatment monitoring occupying a transitional position in clinical adoption curves.
- Skin Health Assessment:Comprehensive pigmentation, texture, vascularity, and hydration quantification with micron-level resolution serves diagnostic dermatology and preventive skincare protocols. This application demands the highest regulatory compliance burden, with EU MDR Class IIa certification requiring prospective validation studies that extend European market entry timelines substantially.
- Treatment Monitoring:Baseline documentation and outcome verification workflows for laser therapy, chemical peels, and injectable procedures generate recurring per-scan revenue. Korean clinic chains integrate these protocols into standardized treatment pathways, creating concentrated demand pull for systems with seamless electronic health record connectivity.
- Cosmetic Formulation:Personalized skincare regimen design and foundation matching algorithms serve retail and direct-to-consumer channels.
- Dermatological Research:Longitudinal skin aging studies and therapeutic efficacy trials require spectral data archival and statistical analysis tool integration.
Skin health assessment dominates clinical installed base. Cosmetic formulation is where non-clinical channel expansion concentrates as beauty retailers seek differentiation through technology-enabled personalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical component manufacturing concentrates in German and Japanese precision engineering clusters, while clinical deployment accelerates in South Korea's medical aesthetics corridor and North American dermatology networks. Regulatory divergence between FDA 510(k) pathways and EU MDR timelines fragments commercialization calendars across jurisdictions.
United States
FDA 510(k) software-as-medical-device pathways accelerate algorithmic skin assessment commercialization, compressing regulatory timelines versus hardware-centric submissions. HIPAA compliance requirements shape cloud-native analytics architectures for telemedicine integration. Dermatology networks in California and New York Metro standardize on workstation systems with embedded machine learning pipelines.
South Korea
Seoul's Gangnam district clinic chains drive concentrated demand for spectroscopy-based diagnostic protocols, absorbing capital commitments that displace handheld devices. MFDS medical device regulations govern clinical claims for AI-powered skin assessment platforms. The Seoul Capital Area anchors Asia-Pacific adoption curves for integrated hardware-software systems.
Germany
EU MDR Class IIa certification requirements tighten clinical evidence standards, extending notified body assessment timelines substantially. REACH and RoHS compliance frameworks govern optical component manufacturing for export markets. Bavaria's precision optics clusters supply critical multispectral imaging arrays to global device manufacturers.
Japan
PMDA regulatory frameworks distinguish wellness-oriented beauty devices from diagnostic medical equipment, determining reimbursement eligibility. METI industrial policy supports domestic manufacturing of medical electronics components. Osaka-based dermatology equipment distributors prioritize seamless PACS integration for hospital network procurement committees.
Australia
TGA medical device regulations align with international standards while permitting accelerated market entry for software-as-medical-device platforms. Cloud-connected diagnostic devices serve remote skin consultation protocols across vast geographic distances. Sydney and Melbourne aesthetic networks favor subscription-based per-scan pricing models over capital purchases.
Complexion Analysis System Market Vendor Landscape
Concentration sits with integrated hardware-software specialists and cloud-native analytics platforms. The vendor base spans three tiers: precision imaging hardware fabricators with captive optical component supply, algorithm developers leveraging FDA 510(k) pathways for software-only deployment, and beauty ecosystem operators controlling consumer-to-clinic channel access. Competitive moves center on strategic partnerships for PACS integration and geographic licensing arrangements for regulatory-constrained markets.
Among precision imaging specialists, Canfield Scientific and FotoFinder Systems exemplify workstation-centric archetypes with embedded machine learning pipelines. MeituEve occupies a distinct position bridging consumer beauty applications and professional device deployment through app ecosystem control. These three anchors represent divergent strategic vectors: hardware-software bundling, clinical workflow integration, and channel verticalization.
| Leading Market Players |
|---|
| Canfield Scientific |
| MeituEve |
| Vibrant Skin Dermatology and Laser |
| FotoFinder Systems |
| Cortex Technology |
| NeoDerma Medical |
| Visiomed Group SA |
| Bio-Therapeutic Inc. |
| Callegari Srl |
| Others |
Supply Flow & Price Mechanics
Machine learning pipelines displacing rule-based image processing simultaneously concentrate supply geography in German and Japanese optical clusters while compressing pricing premiums for hardware-only vendors. This substitution dynamic forces workstation manufacturers to absorb multispectral sensor cost volatility while software-native entrants capture margin through cloud-native deployment.
Pricing Analysis
FDA 510(k) software-as-medical-device pathways dictate the pricing tier structure across clinical deployment segments. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified workstation systems from handheld peripherals and API-only subscriptions. Price differentiation hinges on certification grade and bundled service contracts. Cost compression in handheld tiers is intensifying because smartphone-attachable peripherals commoditize entry-level imaging. Beauty salon chains exhibit highest price sensitivity, while hospital procurement committees prioritize PACS integration over unit cost.
Supply Chain Analysis
Bavarian precision optics clusters and Osaka-based component fabricators constitute the critical chokepoint for multispectral imaging array supply. Manufacturing draws from germanium substrates, CMOS sensors, and specialized optical coatings. Single-source vulnerability concentrates in German and Japanese suppliers controlling hyperspectral array fabrication. Distribution runs through capital equipment distributors for workstation systems and e-commerce marketplaces for handheld devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The complexion analysis system market exhibits cyclical recovery characteristics as FDA 510(k) pathway maturation and EU MDR implementation timelines create alternating windows of regulatory access. Capital expenditure cycles in dermatology clinic chains drive demand volatility.
For Market Incumbents: Consolidate algorithm development capabilities through targeted acquisition of computer vision specialists scarce in the labor market. Deepen captive supply arrangements with Bavarian optical component manufacturers to mitigate single-source fragility. Prioritize ISO 13485 certification maintenance as EU MDR Class IIa evidence standards tighten competitive moats against unqualified entrants. For New Entrants and Emerging Players: FDA 510(k) software-as-medical-device fast-tracks offer the most penetrable regulatory pathway for algorithm-only deployment. Target Australian telemedicine networks and Korean aesthetic clinic chains where subscription-based per-scan pricing lowers customer acquisition barriers. Pursue cloud-native API integration as the primary go-to-market angle, bypassing hardware manufacturing capital requirements entirely. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed workstation manufacturers holding installed base relationships but lacking machine learning differentiation. Five-to-ten year viability favors vendors controlling both spectral hardware fabrication and federated learning software architectures. Monitor FDA 510(k) clearance velocity as the critical inflection signal for algorithmic platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Software Pathway Investment | Accelerates commercialization timelines for algorithm developers targeting US clinical deployment. |
| Cloud-Native Analytics Platform Development | Enables federated learning capabilities without hardware replacement cycles for telemedicine networks. |
| Optical Component Supply Agreement | Secures multispectral imaging array allocation from Bavarian and Japanese precision manufacturers. |
| PACS Integration Partnership | Unlocks hospital network procurement committee approval through seamless radiology infrastructure connectivity. |
| Subscription-Based Device Access Model | Concentrates vendor risk in utilization forecasting while lowering clinical customer entry barriers. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dermatology clinic directors, biomedical equipment procurement managers, optical component manufacturing executives, and cloud analytics platform engineers. Secondary validation drew from FDA 510(k) submission databases, EU MDR notified body clearance records, MFDS medical device registration filings, and hospital capital equipment procurement databases. Bottom-up installed base estimates and top-down market sizing triangulated volume and value outputs.
Across the projection horizon, the analytical framework modeled segmentation dimensions including product type, technology architecture, end-user environment, and application workflow. CAGRs derived from historical growth pattern analysis and forward-looking regulatory pathway maturation curves. Spectroscopy hardware shipment data and software-as-medical-device clearance velocity informed forecast inputs specific to this industry.
The analysis sits within stated boundaries; outcomes outside FDA 510(k) pathway stability or EU MDR notified body capacity constraints would require recalibration. Forecasts reflect assumptions regarding optical component supply continuity and dermatology clinic capital expenditure cycles. Practitioners should keep alternative scenarios live as MFDS regulatory alignment and telemedicine reimbursement policy evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Global PH Electrochemical Electrodes Market
Analytical Instruments
Tunable Diode Laser Analyzer Market
Analytical Instruments
Global Q-TOF Mass Spectrometry Market
Analytical Instruments
Bolometer Market
Analytical Instruments
Energy Dispersive X-Ray Spectrometer Market
Analytical Instruments
Electrochemistry Meters Market
Analytical Instruments
Laser Diffraction Analyzer Market
Analytical Instruments
Digital Multichannel Analyzer Market
Analytical Instruments
Global Fixed Zirconia Oxygen Analyzer Market
Analytical Instruments
Ultraviolet (UV) Analyzer Market
Analytical Instruments
Digital Moisture Analyzer Market
Analytical Instruments
Nanoparticle Size Analysis Instruments Market
Analytical Instruments
Africa Digital Thermometer Market
Analytical Instruments
Universal Probe Library Market
Analytical Instruments
Handheld XRF Spectrometer Market
Analytical Instruments
Metal Analyzers Market