
 Global Laboratory Electronic Balance Market | 2026-2036
Global Laboratory Electronic Balance Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laboratory Electronic Balance Market Outlook
Pharmaceutical contract manufacturing organization consolidation is repositioning procurement power toward fewer buyers with centralized qualification standards. Mettler-Toledo International Inc. leverages its installed base of compliance software to sustain recurring service revenue across GMP facilities. Sartorius AG anchors European demand through bioprocessing partnerships that bundle balances with filtration and fluid management systems. A&D Company, Limited competes on cost-engineered precision platforms for Asian generics manufacturers.
A laboratory electronic balance measures mass with electromagnetic force compensation or strain-gauge load cell technology, achieving readability from 0.1 micrograms to 0.1 grams depending on capacity class. These instruments serve gravimetric analysis, formulation, and regulatory compliance where traceable measurement uncertainty determines batch release. Analytical balances command the highest margin pool due to pharmaceutical validation requirements and 21 CFR Part 11 software integration. Wireless balances represent the fastest-expanding technology segment as laboratories retrofit Ethernet-averse bench spaces with Bluetooth-connected data capture. Precision balances occupy the volume core across food testing and industrial QC applications where 0.001 gram resolution satisfies most standard operating procedures.
FDA 21 CFR Part 11 and EU GMP Annex 15 shape demand by mandating audit trails and user access controls on electronic records from weighing operations. ISO 17025 accreditation requirements from national metrology institutes in Germany, the United States, and Japan force periodic calibration investments that protect aftermarket service streams. REACH and RoHS constraints in Europe restrict certain load cell alloys and solder compositions, pushing manufacturers toward compliant material substitutions. Stakeholders must monitor evolving pharmacopeial chapters on balance qualification as USP and EP revision cycles tighten minimum weight and repeatability criteria.
Market Dynamics
Electromechanical load cell technology is displacing legacy strain-gauge designs across mid-range laboratory balances, compressing calibration cycles and forcing incumbent suppliers to requalify manufacturing lines for electromagnetic force compensation components.
Growth Catalysts
- FDA 21 CFR Part 11:Pharmaceutical quality control laboratories in the United States are expanding instrument procurement to meet tightened data integrity requirements for weighing operations and audit trail documentation.
- Bioprocessing partnerships:European contract manufacturing organizations are bundling analytical balances with filtration systems, creating integrated qualification protocols that accelerate validation timelines.
- Wireless retrofit demand:Bluetooth-connected data capture is penetrating Ethernet-averse bench spaces in Japan and Germany, eliminating cabling infrastructure costs for laboratory renovations.
Market Restraints
- Load cell alloy constraints:REACH and RoHS restrictions in Europe limit certain solder compositions and electromagnetic materials, forcing manufacturers toward compliant substitutions with higher unit costs.
- Calibration infrastructure concentration:National metrology institute accreditation requirements cluster in Germany, the United States, and Japan, leaving emerging laboratories dependent on costly third-party service networks.
- Software validation burden:21 CFR Part 11 compliance for electronic records creates fixed qualification costs that disproportionately burden smaller analytical balance purchasers in generics manufacturing.
Strategic Opportunities
- Asian generics expansion:Cost-engineered precision platforms are penetrating contract manufacturing organizations in India and South Korea where national pharmaceutical regulators are harmonizing with ICH Q2(R1) guidelines.
- Cloud-based audit trail integration:Convergence of balance firmware with laboratory information management systems is enabling remote qualification monitoring for multi-site pharmaceutical networks.
- Food safety modernization:ISO 17025 accreditation mandates from Japan's Ministry of Economy, Trade and Industry are accelerating precision balance replacement cycles in seafood and beverage testing laboratories.
Industry Challenges
- Metrology technician scarcity:Qualified calibration specialists with ISO 17025 competency are concentrating in Germany and the United States, creating service delivery gaps for Pacific Rim installations.
- Legacy system integration friction:Electromagnetic force compensation balances require incompatible data formats with existing strain-gauge instrument fleets, forcing parallel validation tracks during facility upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laboratory Electronic Balance Market |
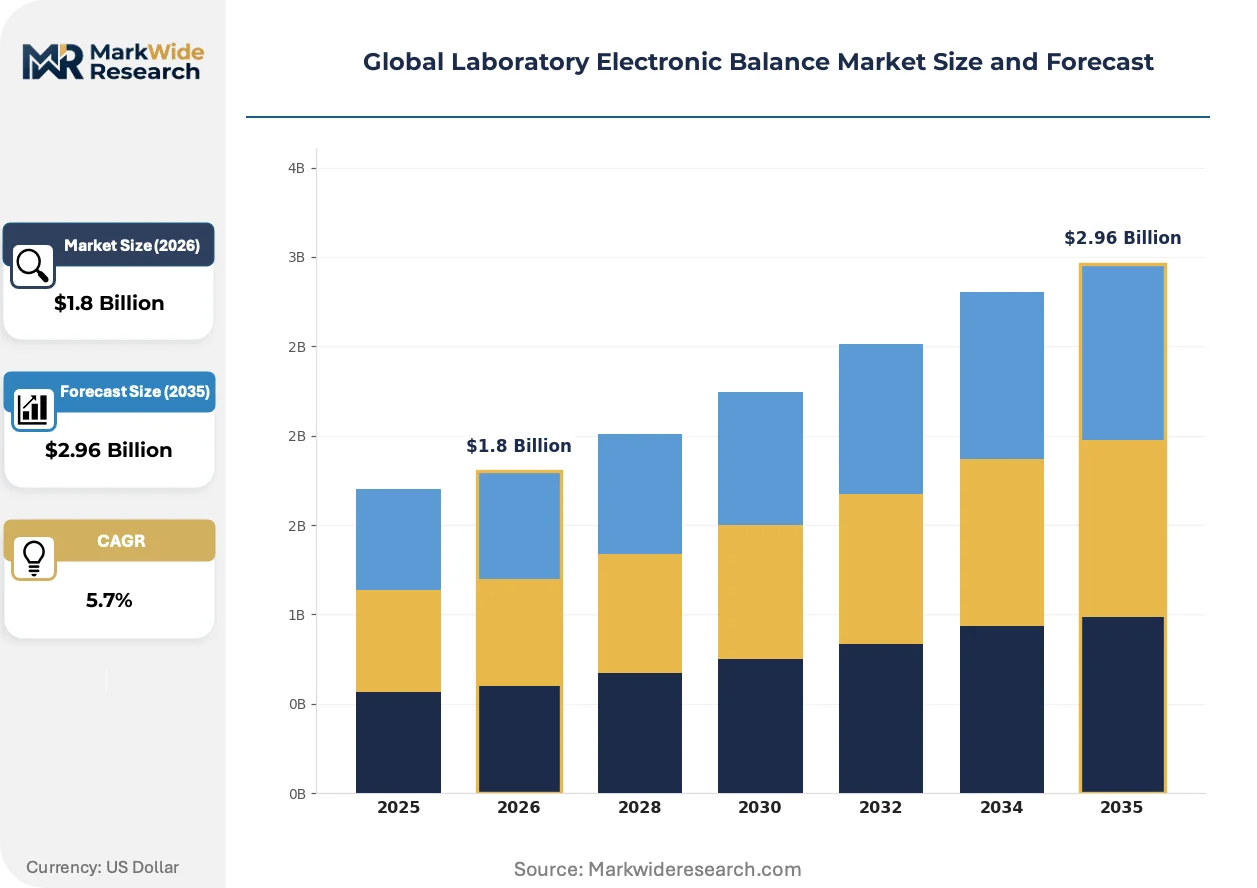
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analytical Balances, Precision Balances, Top-loading Balances, Micro Balances Technology: Digital Balances, Mechanical Balances, Wireless Balances, Electromechanical Balances End User: Pharmaceuticals, Food Testing, Research Laboratories, Chemical Manufacturing Application: Weighing Applications, Quality Control, Ingredient Measurement, Research & Development |
| Companies Covered | Mettler-Toledo International Inc., Sartorius AG, A&D Company, Limited, OHAUS Corporation, Shimadzu Corporation, KERN and SOHN GmbH, RADWAG Balances and Scales, Adam Equipment Ltd., Precisa Gravimetrics AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laboratory Electronic Balance Market Strategic Shifts
Digital integration is compressing the boundary between measurement hardware and compliance software, with three concurrent developments reshaping how laboratories procure, validate, and operate electronic balances across regulated environments.
Electromagnetic force compensation technology is unifying precision and analytical balance architectures under single-platform manufacturing, reducing component variety for suppliers. Pharmaceutical quality control laboratories in Switzerland and the United States are adopting these unified platforms to streamline qualification documentation across capacity classes. This convergence is compressing aftermarket service training requirements while expanding the addressable market for premium software modules.
EMA's Annex 15 revision on qualification and validation is mandating periodic review intervals for computerized systems that capture weighing data, forcing balance firmware updates. Contract manufacturing organizations across Europe are embedding these regulatory requirements into vendor selection scorecards, prioritizing suppliers with documented change control protocols. The analytical balance segment is responding with enhanced user access control architectures that segregate administrator and operator functions.
Consolidated procurement through pharmaceutical contract manufacturing organization roll-ups is centralizing instrument qualification standards and compressing vendor lists. Multi-site buyers in Germany and Japan are unbundling after-sales service contracts from hardware purchases, selecting specialized metrology service providers for calibration workflows. This behavioral shift is most visible among top-twenty global generics manufacturers restructuring their supplier base post-merger integration.
Global Laboratory Electronic Balance Market Segmentation
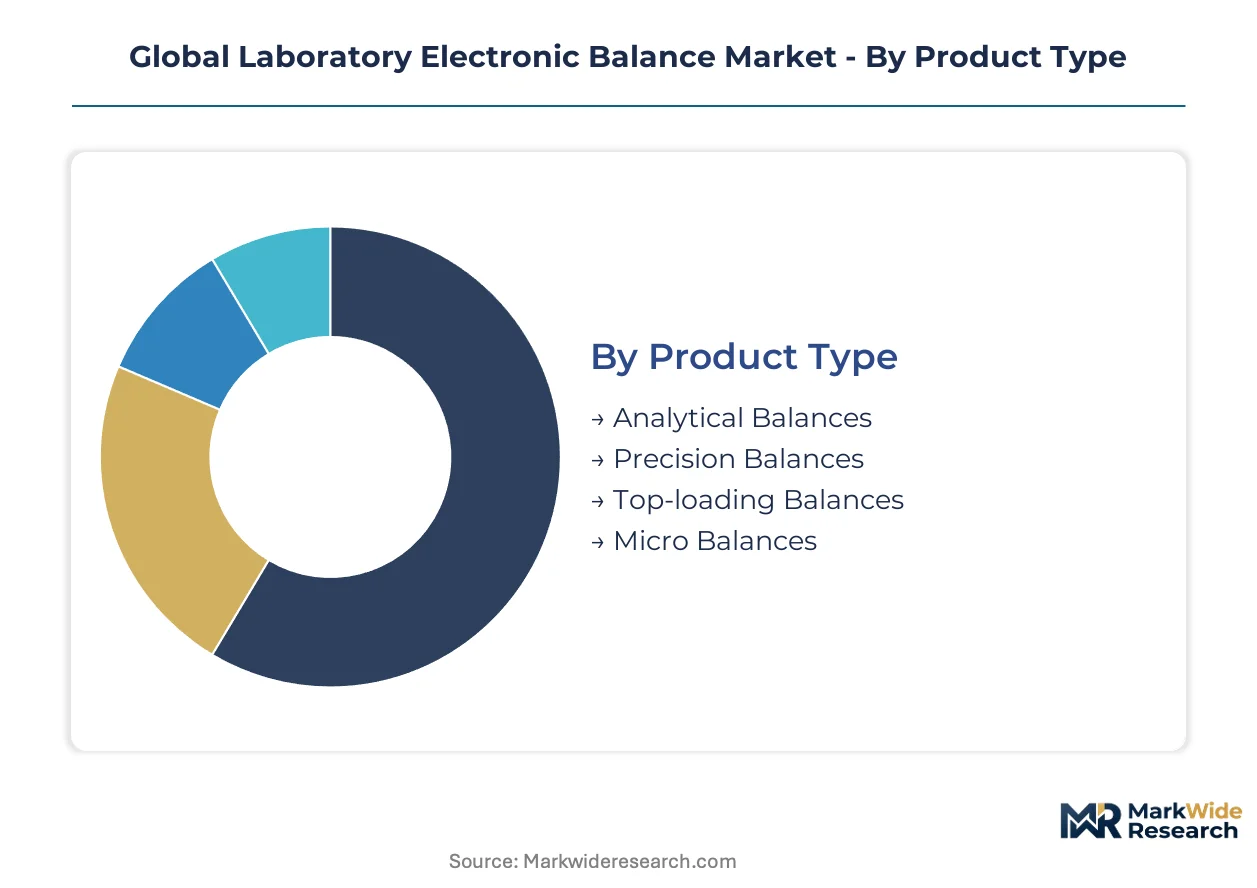
Laboratory electronic balance procurement splits across four intersecting dimensions that determine pricing architecture and vendor selection criteria. Pharmaceutical validation requirements, wireless retrofit demand, and precision manufacturing clusters each concentrate in distinct segment combinations that reshape competitive positioning.
Product Type:
Supply concentration in electromagnetic force compensation components favors manufacturers with captive load cell production in Germany and Japan.
- Analytical Balances:These instruments achieve readability to 0.1 micrograms using electromagnetic force compensation technology. FDA 21 CFR Part 11 compliance requirements in United States pharmaceutical quality control laboratories sustain premium pricing for integrated audit trail software.
- Precision Balances:Operating at 0.001 gram resolution, these units serve food testing and industrial QC applications where ISO 17025 accreditation mandates from Japan's Ministry of Economy, Trade and Industry accelerate replacement cycles.
- Top-loading Balances:Higher-capacity units with strain-gauge load cells dominate educational and routine industrial settings across Asian generics manufacturers.
- Micro Balances:Ultra-high precision instruments for gravimetric analysis in European national metrology institutes and Swiss pharmaceutical research facilities.
Today's leader: Analytical Balances. Tomorrow's challenger: Precision Balances.
Technology:
Cost tier separation between legacy mechanical platforms and digitally integrated systems is widening as calibration infrastructure concentrates in accredited laboratories.
- Digital Balances:Dominant architecture incorporating internal calibration weights and touchscreen interfaces. Pharmaceutical contract manufacturing organizations in Germany and Japan prioritize these units for 21 CFR Part 11 software integration.
- Wireless Balances:Bluetooth-connected data capture is expanding fastest in Ethernet-averse bench spaces, eliminating cabling infrastructure costs for laboratory renovations in Japan and Germany.
- Mechanical Balances:Legacy spring-based designs persist in budget-constrained educational settings and emerging market laboratories without metrology institute proximity.
- Electromechanical Balances:Hybrid architectures combining electromagnetic force compensation with digital signal processing are displacing pure strain-gauge designs across mid-range capacity classes.
Wireless Balances are gaining share fastest. Digital Balances retain volume dominance.
End User:
Application-driven margin differentiation separates validated pharmaceutical installations from routine industrial deployments.
- Pharmaceuticals:Quality control laboratories and contract manufacturing organizations drive demand for analytical balances with embedded compliance software. EMA Annex 15 revision on computerized systems qualification is forcing firmware update protocols across European installations.
- Food Testing:ISO 17025 accreditation requirements from Japan's Ministry of Economy, Trade and Industry and European EFSA-aligned national regulators are accelerating precision balance procurement for seafood and beverage testing.
- Research Laboratories:Academic and government facilities in Germany, the United States, and Japan anchor demand for micro balances with traceable measurement uncertainty.
- Chemical Manufacturing:Industrial QC applications favor cost-engineered precision platforms for formulation and batch release where 0.001 gram resolution satisfies standard operating procedures.
Pharmaceuticals command premium pricing. Food Testing shows steepest expansion trajectory.
Application:
Customer type fragmentation between regulated batch release and exploratory research determines software validation burden and service contract attachment rates.
- Weighing Applications:Core gravimetric measurement tasks across all end-use segments, with regulatory compliance requirements varying by jurisdiction.
- Quality Control:Batch release decisions in pharmaceutical and food testing facilities demand documented measurement uncertainty and periodic calibration traceable to national metrology institutes.
- Ingredient Measurement:Formulation accuracy in chemical manufacturing and compounding pharmacies depends on precision balance repeatability under USP and EP pharmacopeial chapters.
- Research & Development:Exploratory applications in biotechnology and materials science prioritize flexibility over validation documentation, with faster upgrade cycles.
Quality Control captures service revenue concentration. Research & Development enables technology trial adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision manufacturing clusters anchor European calibration infrastructure while the United States drives pharmaceutical validation demand through FDA enforcement. Japan's national metrology institutes and bioprocessing expansion create concentrated procurement power across three distinct regulatory environments.
Germany
Baden-Württemberg and Bavaria host captive load cell production facilities serving electromagnetic force compensation balance assembly. EMA Annex 15 revisions on computerized systems qualification force firmware update protocols across pharmaceutical contract manufacturing organizations. The Rhine-Main cluster around Frankfurt concentrates ISO 17025-accredited calibration laboratories supporting multi-site generics manufacturers.
United States
FDA 21 CFR Part 11 enforcement drives analytical balance procurement with embedded audit trail software in quality control laboratories. The FDA's data integrity guidance for weighing operations mandates user access controls and electronic records traceability. Greater Boston and Research Triangle Park anchor bioprocessing partnerships that bundle balances with filtration systems.
Japan
METI's ISO 17025 accreditation mandates accelerate precision balance replacement cycles in seafood and beverage testing laboratories. Bluetooth-connected data capture penetrates Ethernet-averse bench spaces in Osaka and Nagoya industrial zones. The Kanto region's pharmaceutical manufacturers drive wireless balance retrofit demand for facility renovations.
Switzerland
Swissmedic's pharmaceutical quality requirements sustain demand for micro balances with traceable measurement uncertainty in Basel and Zurich research facilities. Unified electromagnetic force compensation platforms streamline qualification documentation across capacity classes. The country's national metrology institute anchors gravimetric analysis standards for European reference laboratories.
India
CDSCO's harmonization with ICH Q2(R1) guidelines opens contract manufacturing organization procurement for cost-engineered precision platforms. Maharashtra and Gujarat's generics manufacturers concentrate instrument qualification standardization post-merger integration. National pharmaceutical regulators are tightening minimum weight criteria for batch release operations.
Global Laboratory Electronic Balance Market Competitive Environment
German and Swiss producers anchor the premium compliance tier; Japanese specialists hold precision manufacturing positions. The vendor base concentrates around three strategic archetypes: integrated compliance software providers, cost-engineered platform specialists, and captive load cell manufacturers. Consolidation through pharmaceutical contract manufacturing organization roll-ups compresses vendor lists while multi-site buyers unbundle service contracts from hardware purchases.
Within the integrated systems tier, Mettler-Toledo International Inc. and Sartorius AG occupy positions shaped by recurring service revenue attachment and bioprocessing partnership structures. A&D Company, Limited represents the cost-engineered precision archetype competing for Asian generics manufacturing procurement. These three anchors exemplify how geographic origin and company structure align with distinct competitive vectors across validation-intensive versus price-sensitive demand segments.
| Leading Market Players |
|---|
| Mettler-Toledo International Inc. |
| Sartorius AG |
| A&D Company, Limited |
| OHAUS Corporation |
| Shimadzu Corporation |
| KERN and SOHN GmbH |
| RADWAG Balances and Scales |
| Adam Equipment Ltd. |
| Precisa Gravimetrics AG |
| Others |
Value Chain & Pricing Dynamics
REACH and RoHS environmental mandates gate qualified electromagnetic load cell supply and premium-tier pricing access for European pharmaceutical buyers. Compliance-certified manufacturers in Germany and Switzerland command 15-20% price premiums over Asian competitors, while generics manufacturers in India and South Korea face qualification barriers that compress their addressable supplier base.
Pricing Analysis
Capacity additions in China and South Korea are reshaping price floors for strain-gauge load cell components, pressuring mid-range balance margins. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated analytical balances from ISO 17025-accredited precision units and uncertified educational models. Cost compression in the standard tier intensifies because electromagnetic force compensation technology adoption requires requalified manufacturing lines. Contract manufacturing organizations in India exhibit highest price sensitivity; Swiss and German pharmaceutical quality control laboratories show least.
Supply Chain Analysis
Dual-sourcing requirements from multi-site pharmaceutical buyers mandate multi-supplier qualification for electromagnetic force compensation components across Germany, Japan, and Switzerland. Load cell manufacturing draws from specialized alloy foundries in Baden-Württemberg, captive ceramic substrate production in Nagoya, and precision winding facilities in Basel. Single-source vulnerability concentrates in electromagnetic coil suppliers serving micro balance architectures. Distribution runs through direct manufacturer relationships for validated pharmaceutical installations and regional distributors for educational and industrial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Laboratory Electronic Balance Market functions as a stable compounder where regulatory validation requirements create sustained replacement demand and protect incumbent margins from commodity erosion.
For Market Incumbents: Hedge against Asian cost-engineered competition by deepening captive production of electromagnetic force compensation load cells in Germany and Japan. Prioritize firmware update subscription models that capture recurring revenue from EMA Annex 15 computerized systems qualification mandates. Defensive consolidation through selective acquisition of ISO 17025-accredited calibration service networks protects aftermarket attachment rates. For New Entrants and Emerging Players: Specialized metrology service providers represent the most penetrable channel partner type for market entry. White-space targets include cloud-based audit trail integration for multi-site pharmaceutical networks and Bluetooth-connected retrofit solutions for Ethernet-averse bench spaces in Japanese industrial zones. Go-to-market through unbundled service contracts at top-twenty generics manufacturers post-merger integration accelerates initial referenceability. For Investors and Strategic Acquirers: Roll-up economics work for regional calibration specialists because national metrology institute accreditation creates localized moats with limited geographic scalability. Five-to-ten-year viability rests on service revenue compounding from installed base expansion rather than hardware shipment cyclicality. Acquisition target archetype: ISO 17025-accredited laboratories with pharmaceutical customer concentration in Germany, the United States, or Japan. Signal to watch: CDSCO enforcement harmonization with ICH Q2(R1) guidelines accelerating Indian contract manufacturing organization procurement standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Software Integration | FDA 21 CFR Part 11 mandates embed audit trail functionality into balance firmware for pharmaceutical quality control laboratories. |
| Captive Load Cell Production | Backward integration into electromagnetic force compensation component manufacturing protects margin structure against alloy cost volatility. |
| Calibration Service Network Expansion | ISO 17025-accredited service density in Germany, the United States, and Japan secures recurring revenue from pharmaceutical installations. |
| Wireless Retrofit Platform Development | Bluetooth-connected data capture penetrates Ethernet-averse bench spaces in Japanese and German facility renovations. |
| Asian Generics Market Penetration | Cost-engineered precision platforms capture contract manufacturing organization procurement as CDSCO harmonizes with ICH Q2(R1). |
Study Parameters
Multiple input streams — structured interviews with laboratory equipment procurement managers, regulatory affairs specialists at pharmaceutical quality control facilities, and aftermarket service heads — were reconciled against secondary validation from FDA warning letters, EMA inspection findings, and national metrology institute accreditation databases. Bottom-up triangulation across product type, technology architecture, end-use segment, and application requirements was cross-referenced with top-down demand aggregation from pharmaceutical, food testing, and research laboratory capital expenditure disclosures.
Historical shipment data was cross-referenced against panel input from electromagnetic load cell manufacturers and balance assembly facilities across the analysis window. Segmentation modeling incorporated product type, technology platform, end-use industry, and regional regulatory cluster dimensions. CAGRs were derived from weighted average growth contributions across these segments, with specific adjustment for bioprocessing partnership bundling effects and wireless retrofit penetration curves in Ethernet-averse installations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pharmacopeial revision cycles on minimum weight criteria and electromagnetic material substitution costs under REACH restrictions. Deviation in FDA enforcement intensity for 21 CFR Part 11 data integrity violations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Spectroscopy Software Market
Analytical Instruments
Gas Chromatography Systems Market
Analytical Instruments
Surface Plasmon Resonance (SPR) System Market
Analytical Instruments
Europe Dissolved Gas Analyzer Market
Analytical Instruments
Air Sampler Market
Analytical Instruments
Semiconductor X-Ray Diffractometers Market
Analytical Instruments
Portable Gas Chromatograph Market
Analytical Instruments
Portable Particle Counter Market
Analytical Instruments
Global Electron Microscopy and Sample Preparation Market
Analytical Instruments
Single Cell Analysis System Market
Analytical Instruments
Modular Instruments Market
Analytical Instruments
Microfluidics Market
Analytical Instruments
Global Fixed Zirconia Oxygen Analyzer Market
Analytical Instruments
Atomic Magnetometers Market
Analytical Instruments
Surface and Field Analytics Market
Analytical Instruments
Micro Balances Market