
 Analytical Instrumentation Market | 2026-2036
Analytical Instrumentation Market Size, Share, and Industry Trends Forecast 2026-2036
Analytical Instrumentation Market Intelligence
Software-as-a-service (SaaS) for data analysis and instrument control is restructuring how analytical instrumentation is acquired and operated, shifting focus from one-time capital sales to recurring revenue models. Thermo Fisher Scientific Inc. leverages its extensive portfolio to offer integrated hardware and software ecosystems. Agilent Technologies Inc. competes on workflow automation and open-platform connectivity, appealing to labs with multi-vendor environments. Waters Corporation specializes in liquid chromatography and mass spectrometry, focusing on high-performance applications in life sciences and materials science.
Analytical instrumentation encompasses a class of devices used to separate, identify, and quantify the chemical or physical properties of a substance. These instruments operate on principles like spectroscopy, chromatography, and electrochemistry to provide precise molecular and atomic level characterization. Their primary purpose is to support quality control, research, and process monitoring across numerous industries. Chromatography systems, particularly liquid chromatography, maintain a large market share due to extensive use in pharmaceutical testing. Mass spectrometry technology represents the fastest-growing segment, driven by its sensitivity in proteomics and environmental analysis.
Regulatory frameworks are a primary determinant of instrument specifications and market access. The US FDA's 21 CFR Part 11 guidelines dictate requirements for data integrity and electronic records, shaping software development for all major vendors. In parallel, the EU's REACH regulation mandates detailed chemical characterization, directly creating demand for spectrometers and chromatographs. The critical decision for instrument manufacturers is how to allocate R&D between enhancing core hardware performance and building compliant, user-friendly software platforms that simplify validation for end users.
Market Dynamics
The convergence of hardware miniaturization with cloud-based software analytics is the central force shaping the market. This shift enables decentralized testing outside traditional labs, driven by regulations like the FDA's PAT framework demanding real-time process monitoring in pharmaceutical manufacturing.
Growth Catalysts
- Regulatory Mandates:The EU's REACH regulation requires detailed chemical safety assessments for market access, directly spurring demand for chromatography and spectrometry systems to characterize substances.
- Application Expansion:The rise of proteomics and metabolomics research in biotechnology clusters like Boston and Shanghai requires increasingly sensitive mass spectrometry instruments for biomarker discovery and development.
- Food Safety Standards:China's stringent GB standards for food contaminants and additives create consistent demand for liquid chromatography systems for quality control in the food and beverage industry.
Market Restraints
- High Capital Cost:The significant upfront investment for high-performance systems like nuclear magnetic resonance spectrometers limits adoption by smaller academic labs and startups without substantial funding.
- Proprietary Consumables:Dependency on vendor-specific consumables, such as specialized chromatography columns and reagents, creates customer lock-in and exposes labs to supply chain disruptions and price volatility.
- Skilled Personnel Scarcity:Operating advanced instrumentation requires highly trained technicians, creating a bottleneck where a scarcity of experienced chromatographers and mass spectrometrists exists.
Strategic Opportunities
- Portable and Handheld Devices:Development of field-deployable spectrometers for environmental monitoring, agricultural testing, and raw material identification opens new markets beyond the centralized laboratory.
- AI-Powered Data Analysis:Integrating artificial intelligence for automated spectral interpretation and predictive maintenance can reduce operator skill requirements, improve instrument uptime, and accelerate data analysis.
- Emerging Economies:Investment in pharmaceutical and chemical manufacturing infrastructure in countries like India and Brazil presents a significant growth vector for instrument sales and service contracts.
Industry Challenges
- Data Integrity Compliance:Ensuring software platforms comply with evolving electronic record regulations, such as FDA 21 CFR Part 11 and its international equivalents, is a constant and costly development challenge.
- System Integration Complexity:Integrating new instruments with a laboratory's existing information management systems and multi-vendor hardware environments often requires custom development and complex validation processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Analytical Instrumentation Market |
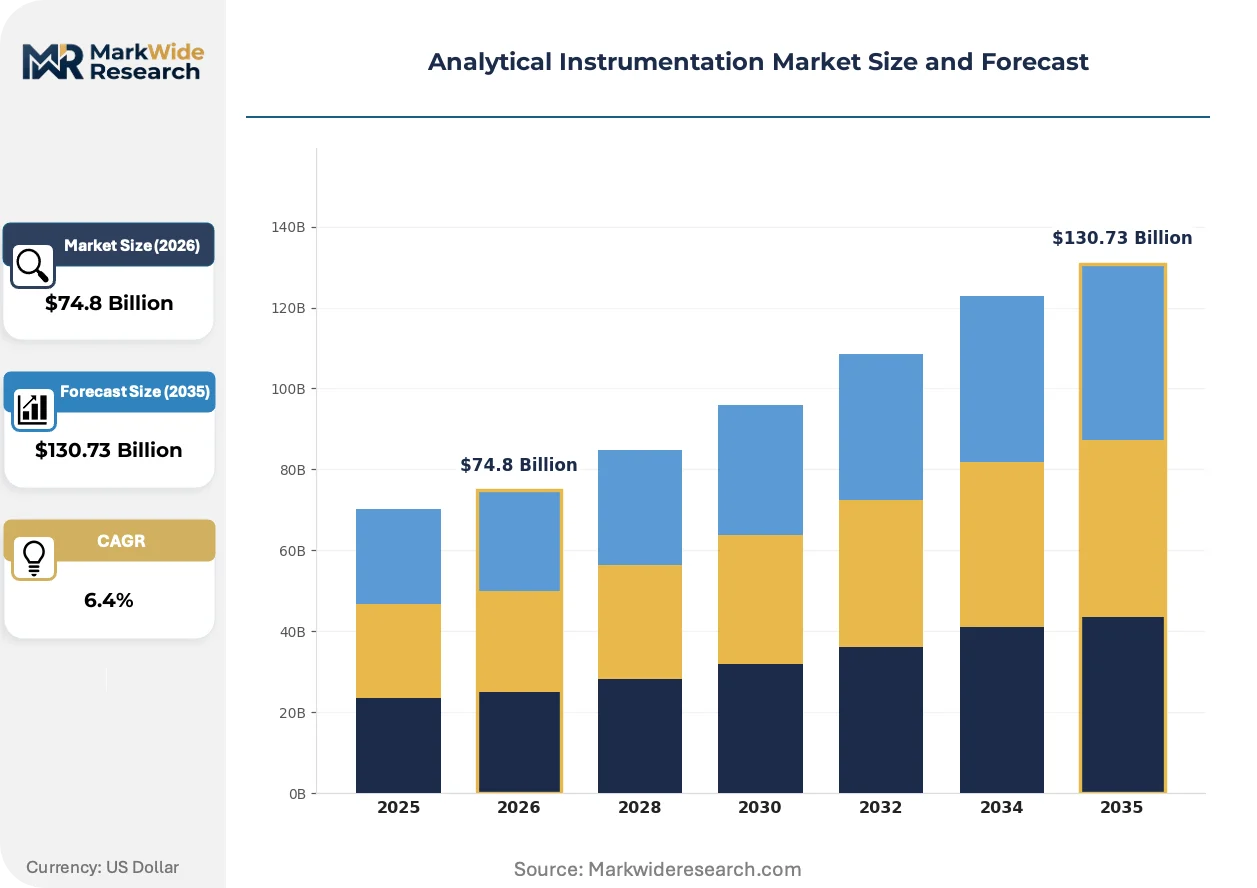
| Market Size in 2026 | $74.8 Billion |
| Market Size in 2035 | $130.73 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spectrometers, Chromatographs, Microscopes, Titrators, Thermal Analyzers Technology: Mass Spectrometry, Nuclear Magnetic Resonance, Gas Chromatography, Liquid Chromatography, Atomic Absorption Application: Pharmaceutical Testing, Environmental Analysis, Food Safety, Chemical Characterization, Material Science End User: Research Laboratories, Quality Control Departments, Forensic Centers, Academic Institutions, Biotechnology Firms |
| Companies Covered | Shimadzu Corporation, Waters Corporation, Thermo Fisher Scientific Inc., Sartorius AG, PerkinElmer Inc., Agilent Technologies Inc., Bruker Corporation, Mettler-Toledo International Inc., Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analytical Instrumentation Market Strategic Shifts & Innovations
Automation and data science are fusing to redefine instrument capability and operational efficiency. This evolution pushes instrumentation from a pure measurement tool towards an integrated component of automated, data-driven decision-making workflows within regulated industries.
Miniaturized mass spectrometry uses microfluidic chips and novel ion sources to perform rapid chemical analysis. Pharmaceutical process analytical technology and point-of-care diagnostics are key adopters demanding real-time results. This accessibility is electrifying the market by moving high-end analysis from centralized labs directly to the production line and clinic.
The European Union's Medical Device Regulation (MDR) imposes stricter requirements for the materials used in medical devices. This directly affects manufacturers who must now provide more detailed chemical characterization data for regulatory submission. Consequently, demand for techniques like gas chromatography-mass spectrometry is increasing to screen for extractables and leachables in polymers.
A shift towards subscription-based access for analytical software and instrument control is gaining traction over traditional one-time capital purchases. This model disrupts the direct sales channel by offering lower initial costs and continuous software updates. The change is most prominent in biotechnology startups and contract research organizations seeking greater financial flexibility.
Analytical Instrumentation Market Segmentation
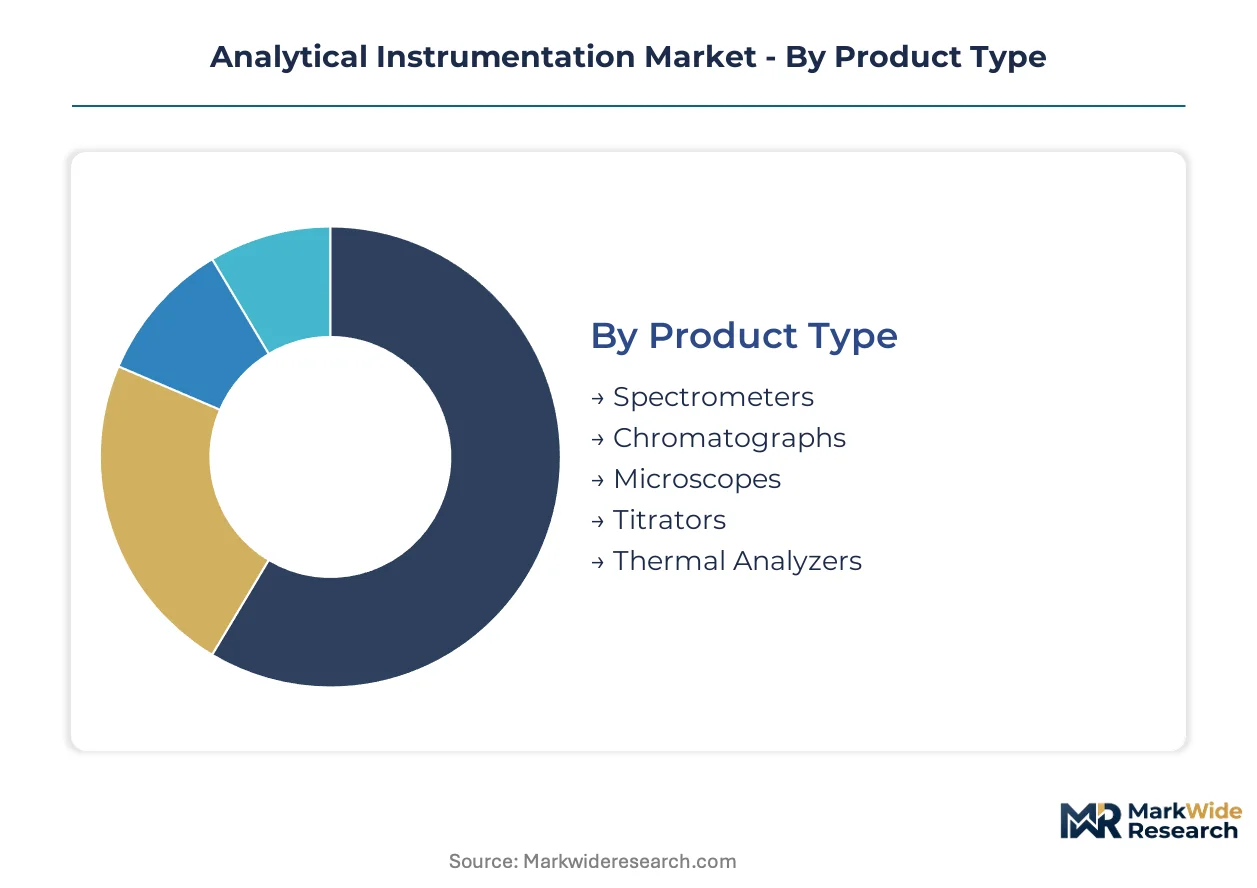
Understanding the analytical instrumentation market requires a granular view of its diverse components. Segmentation helps delineate distinct demand patterns, technological preferences, and end-user requirements across various industry verticals. This structural breakdown reveals where innovation is concentrated and where specific regulatory pressures drive procurement decisions.
Product Type:
Buyers in this category differentiate primarily by the specific analytical task required, influencing their choice of instrument. Each product type offers distinct operational principles and measurement capabilities, from molecular identification to physical property assessment.
- Spectrometers:These instruments measure the interaction of electromagnetic radiation with matter, providing detailed information about atomic and molecular structure. Demand concentrates in pharmaceutical research, driven by the need for precise drug component identification and purity analysis.
- Chromatographs:Systems like gas and liquid chromatographs separate complex mixtures into individual components, enabling their quantification and identification. Extensive use in food safety standards, such as China's GB standards, drives procurement for contaminant detection.
- Microscopes:Optical and electron microscopes provide magnified images for detailed visual inspection and structural analysis at micro and nano scales. Material science labs utilize these for surface characterization.
- Titrators:These devices perform volumetric chemical analysis to determine the concentration of a substance in a solution. Quality control departments in chemical manufacturing employ titrators for process monitoring.
- Thermal Analyzers:Instruments such as differential scanning calorimeters measure changes in material properties as a function of temperature. Polymer and plastics industries use thermal analyzers for material characterization.
Volume sits with Chromatographs; growth tilts toward Spectrometers.
Technology:
The application space dictates the selection of analytical technology, with each method offering unique advantages in sensitivity, specificity, and throughput. Advancements in these technologies often enable new scientific discoveries and regulatory compliance pathways.
- Mass Spectrometry:This technique measures the mass-to-charge ratio of ions, providing highly sensitive and specific identification of compounds. Proteomics research in biotechnology clusters like Boston requires increasingly sensitive mass spectrometry instruments for biomarker discovery.
- Liquid Chromatography:A separation technique widely used for non-volatile and thermally unstable compounds, particularly in complex biological matrices. Pharmaceutical quality control relies heavily on liquid chromatography for drug impurity profiling and stability testing.
- Nuclear Magnetic Resonance:NMR spectroscopy provides detailed structural information about molecules based on their magnetic properties. Academic institutions use NMR for advanced chemical research.
- Gas Chromatography:GC separates volatile compounds by passing them through a column, often coupled with mass spectrometry for identification. Environmental analysis utilizes GC for detecting airborne pollutants.
- Atomic Absorption:This spectroscopic method determines the concentration of specific metal elements in a sample. Food safety laboratories use atomic absorption for heavy metal detection.
Liquid Chromatography systems hold significant market share, while Mass Spectrometry shows the steepest expansion trajectory.
Application:
Customer type and regulatory mandates primarily drive demand within specific application segments, shaping instrument design and software requirements. Each application area presents distinct analytical challenges and compliance needs.
- Pharmaceutical Testing:This segment involves rigorous analysis throughout drug discovery, development, and manufacturing, ensuring product safety and efficacy. FDA's PAT framework demands real-time process monitoring, driving instrumentation sales for quality assurance.
- Environmental Analysis:Monitoring pollutants in air, water, and soil requires sensitive and robust analytical instruments to comply with regulations like the EU's REACH. Laboratories use chromatography and spectroscopy for detecting hazardous substances.
- Food Safety:Ensuring consumer health by detecting contaminants, adulterants, and allergens in food products is a critical application. China's GB standards create consistent demand for liquid chromatography systems.
- Chemical Characterization:Identifying and quantifying chemical components in various industrial products and raw materials is essential for quality control. Spectrometers are fundamental for material composition analysis.
- Material Science:Investigating the physical and chemical properties of materials, including polymers, metals, and composites, supports product development. Thermal analyzers and microscopes are key tools in this field.
Pharmaceutical Testing represents the largest demand area, with Environmental Analysis exhibiting strong, consistent growth.
End User:
The maturity of research and development infrastructure significantly influences the type and volume of analytical instrumentation procured by various end-user groups. Specialized facilities often require high-performance, dedicated systems.
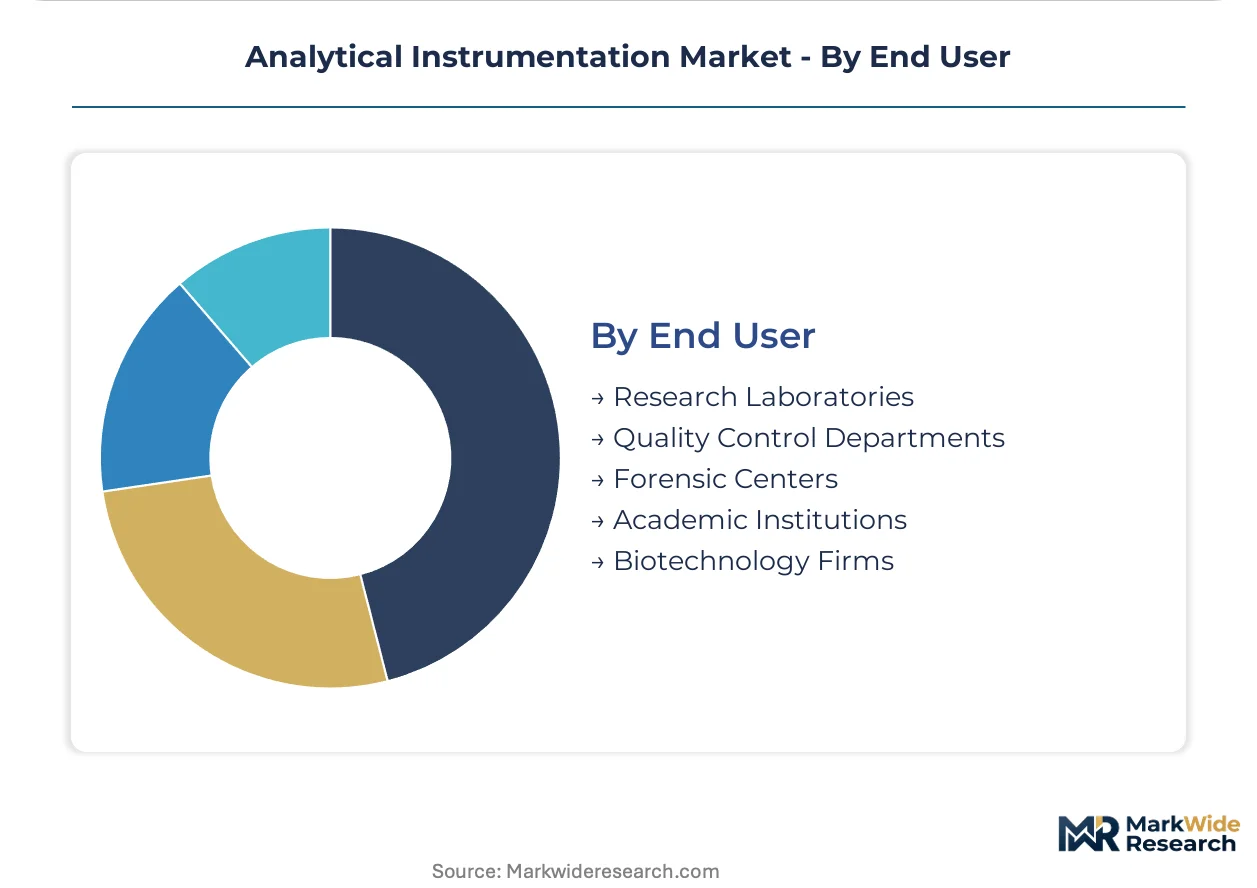
- Research Laboratories:These facilities, ranging from academic to corporate R&D, focus on discovery and method development, requiring versatile and high-performance instruments. Investment in novel technologies, like miniaturized mass spectrometry, is common for pushing scientific boundaries.
- Biotechnology Firms:Companies in this sector concentrate on drug discovery, diagnostics, and bioprocessing, driving demand for advanced analytical tools for complex biological samples. Proteomics and metabolomics research require highly sensitive mass spectrometry instruments.
- Quality Control Departments:Industrial QC labs focus on routine analysis to ensure product specifications and regulatory compliance. These departments frequently procure robust, automated systems for high-throughput testing.
- Forensic Centers:These specialized labs analyze evidence for legal purposes, requiring highly sensitive and specific instrumentation for toxicology and trace analysis. Gas chromatography-mass spectrometry is a standard tool.
- Academic Institutions:Universities and colleges use analytical instruments for teaching, fundamental research, and training future scientists. Budget constraints often influence their purchasing decisions towards multi-purpose systems.
Research Laboratories lead in overall instrument installations, while Biotechnology Firms are expanding most quickly in advanced system procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The analytical instrumentation market exhibits a clear divide between established manufacturing hubs and rapidly expanding consumption centers. Production capabilities for advanced systems often concentrate in developed economies, while demand for quality control and research tools accelerates in emerging industrial sectors. This dynamic shapes regional investment patterns and technology transfer initiatives.
United States
Demand for analytical instrumentation in the United States remains robust, driven by extensive pharmaceutical R&D and biotechnology innovation. The FDA's 21 CFR Part 11 regulations mandate strict data integrity, influencing software development for instrument manufacturers. Major life science clusters in Boston and San Francisco continue to spur adoption of high-performance mass spectrometry and chromatography systems.
China
China's market expansion is fueled by stringent food safety standards and significant investments in pharmaceutical manufacturing. The country's GB standards for contaminants consistently drive procurement of liquid chromatography systems for quality control. Industrial parks in Shanghai and Guangzhou are becoming major centers for analytical instrument deployment in various industries.
Germany
German analytical instrumentation demand stems from its strong chemical and automotive industries, alongside a robust academic research sector. The EU's REACH regulation necessitates detailed chemical characterization, increasing the need for advanced spectrometers and chromatographs. Research institutions and industrial hubs in Bavaria and North Rhine-Westphalia lead in technology adoption.
Japan
Japanese industries, particularly in electronics and materials science, require precise analytical tools for quality assurance and innovation. Japan's PMDA (Pharmaceuticals and Medical Devices Agency) regulations influence instrument specifications for pharmaceutical testing. Technology clusters around Tokyo and Osaka are key areas for advanced microscopy and thermal analysis applications.
India
India presents a significant growth vector for analytical instrumentation, propelled by expanding pharmaceutical manufacturing and environmental monitoring needs. The country's national pharmaceutical regulator (CDSCO) increasingly emphasizes quality control, driving instrument sales. Hyderabad and Ahmedabad are emerging as major pharmaceutical manufacturing centers, boosting demand for analytical solutions.
Analytical Instrumentation Market Key Industry Players
Top-tier vendors anchor the high-performance and integrated solutions segment, while a diverse array of specialized and regional players cater to niche applications and cost-sensitive markets. The market structure is tiered, with larger entities offering comprehensive portfolios and smaller firms focusing on specific technologies or services. Strategic partnerships and targeted acquisitions are common competitive moves, alongside continuous R&D investment in software and automation.
Specialists in integrated hardware and software ecosystems include Thermo Fisher Scientific Inc., exemplifying a strategy of leveraging broad portfolios. Agilent Technologies Inc. represents firms competing on workflow automation and open-platform connectivity for multi-vendor laboratory environments. Waters Corporation anchors the high-performance applications segment, particularly in liquid chromatography and mass spectrometry for life sciences.
| Leading Market Players |
|---|
| Shimadzu Corporation |
| Waters Corporation |
| Thermo Fisher Scientific Inc. |
| Sartorius AG |
| PerkinElmer Inc. |
| Agilent Technologies Inc. |
| Bruker Corporation |
| Mettler-Toledo International Inc. |
| Danaher Corporation |
| Others |
Cost & Logistics Intelligence
Global semiconductor chip pricing, a critical input for advanced analytical instruments, cascades through the supply chain, influencing component costs and ultimately impacting tiered instrument pricing. This dynamic shapes procurement decisions for end-users seeking both performance and cost efficiency.
Pricing Analysis
Cost-down pressure on instrument manufacturers accelerates due to intense competition and demand for accessible entry points. The market generally operates on a hybrid capital purchase and subscription model, particularly for software. Instrument precision and regulatory compliance certifications are primary price differentiation drivers. Biotechnology startups exhibit high price sensitivity, while large pharmaceutical corporations prioritize validated high-performance systems.
Supply Chain Analysis
Reverse logistics for instrument calibration and refurbishment flows through specialized service centers, often managed directly by original equipment manufacturers. Geographic supply concentration for high-precision components rests with Germany and Japan, while general manufacturing occurs in China. The supply chain relies heavily on specialized optical components and high-purity chemical reagents. Single-source vulnerability for highly specialized sensors represents a structural risk. Distribution runs through direct sales channels supplemented by specialized distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The analytical instrumentation market is undergoing a technology-transition phase, with miniaturized mass spectrometry displacing traditional benchtop systems in certain applications. This shift creates both challenges and opportunities across the value chain.
For Market Incumbents:
Anchor market position by deepening software integration into hardware ecosystems, offering comprehensive data analysis platforms. Expand data analytics capabilities to simplify complex workflows and ensure compliance with FDA 21 CFR Part 11. Emerging AI-powered data analysis platforms pose a threat to traditional software offerings. Investments in compliant software platforms and advanced sensor R&D are crucial to maintain leadership.
For New Entrants and Emerging Players:
Small academic labs and biotechnology startups represent underserved buyer archetypes seeking flexible analytical solutions. Point-of-care diagnostics and field-deployable environmental monitoring are highly penetrable segments. Offering subscription-based access models with integrated AI for simplified data interpretation provides a strong go-to-market angle. Focus on developing portable and handheld devices to capture decentralized testing demand.
For Investors and Strategic Acquirers:
The window for entry favors specialized software firms and developers of miniaturized analytical technologies with strong intellectual property. Long-term viability is driven by continuous regulatory mandates and scientific advancements in life sciences. Acquisition targets should include specialized software firms and developers of miniaturized analytical technologies. Increased regulatory enforcement for data integrity and specific chemical characterization acts as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-as-a-Service Expansion | Shifts revenue models towards recurring streams for greater financial stability. |
| Miniaturization Technology R&D | Enables decentralized testing and opens new markets beyond traditional laboratories. |
| AI-Powered Data Interpretation | Reduces operator skill requirements and accelerates complex analytical workflows for end-users. |
| Emerging Market Manufacturing Footprint | Captures demand from expanding pharmaceutical and chemical industries in India and Brazil. |
| Regulatory Compliance Platform Development | Ensures instruments meet evolving data integrity standards like FDA 21 CFR Part 11 for global market access. |
Research Approach
Multi-period observation of market adoption rates and regulatory compliance trends anchored the analysis, supplemented by interviews with pharmaceutical R&D scientists and quality control managers. Secondary validation involved reviewing FDA 21 CFR Part 11 guidelines and EU REACH regulation documents. This approach utilized both bottom-up market sizing and top-down validation for robust data integration.
An input-output matrix structured the forecast framework, integrating historical data with projected market dynamics across the analysis window. Segmentation dimensions included product type, core technology, key application areas, and end-user categories, alongside regional regulatory landscape. Compound annual growth rates were derived from historical trends and anticipated technological advancements. Key inputs included R&D investment flows and evolving regulatory mandate timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to unforeseen regulatory shifts and rapid technological obsolescence. Projections reflect current assumptions about market evolution. Practitioners should monitor new scientific breakthroughs and major policy changes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Spectrophotometers Market
Analytical Instruments
Air Sampler Market
Analytical Instruments
Global Potentiostat Market
Analytical Instruments
Mass Spectrometer Market
Analytical Instruments
Bolometer Market
Analytical Instruments
Global Nuclear Magnetic Resonance (NMR) Spectrometer Market
Analytical Instruments
Terahertz Spectroscopic System Market
Analytical Instruments
Power Device Analyzer Market
Analytical Instruments
Infrared Thermometers Market
Analytical Instruments
Boron Analyzer Market
Analytical Instruments
Global Q-TOF Mass Spectrometry Market
Analytical Instruments
Laser Scanning Microscopes Market
Analytical Instruments
Illuminometer Market
Analytical Instruments
Single Cell Analysis System Market
Analytical Instruments
Atomic Magnetometers Market
Analytical Instruments
Gas Analyzer Market