
 Surface Plasmon Resonance (SPR) System Market | 2026-2036
Surface Plasmon Resonance (SPR) System Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Plasmon Resonance (SPR) System Market Insights
Multi-source procurement for optical biosensor components is rebalancing as vendors diversify coating and detector suppliers to mitigate lead-time volatility. Cytiva leverages its chromatography-installed base to cross-sell integrated SPR workflows into bioprocess development labs. Bio-Rad Laboratories anchors its position through sustained R&D spending on high-throughput array formats for drug screening. Nicoya Life Sciences differentiates by competing on open-fluidic architectures that reduce per-run consumable costs for academic end users.
Surface Plasmon Resonance systems exploit evanescent wave phenomena at metal-dielectric interfaces to quantify binding kinetics in real time without fluorescent or radioactive labels, typically operating at refractive index resolutions of 10^-7 RIU and detecting molecular masses down to 100 Da. Their primary commercial purpose spans kinetic characterization of antibody-antigen interactions, small-molecule screening, and quality control of biotherapeutic purity. Benchtop systems dominate installed bases in pharmaceutical quality labs, while imaging systems capture expanding share in spatialomics and cell-based assay development where parallel spot analysis accelerates throughput. Multi-channel configurations command premium positioning by sustaining higher margins through reduced per-sample operator time in contract research settings.
The FDA enforces 21 CFR Part 11 compliance for electronic data integrity in GxP environments, compelling SPR vendors to embed audit trails and user-access controls that extend development cycles but secure pharmaceutical procurement channels. The EU MDR and REACH frameworks from ECHA impose material biocompatibility and chemical safety documentation on sensor chips and fluidic consumables, shaping regional product configurations. Japan's PMDA aligns with ICH Q2(R1) validation guidelines for analytical instrumentation, creating additional conformance layers for market entry. Stakeholders must monitor evolving harmonization between FDA and EMA data-integrity expectations to anticipate retrofit obligations across installed instrument fleets.
Market Dynamics
Label-free biosensor architectures are displacing legacy fluorescence-based workflows in biopharmaceutical quality control, compressing assay development timelines from weeks to days while elevating data integrity requirements under 21 CFR Part 11 and EU MDR frameworks.
Growth Catalysts
- Cell and gene therapy pipelines:Biologics developers in Boston-Cambridge and San Diego clusters require kinetic characterization for novel modalities, driving instrument procurement for antibody and cell therapy programs.
- 21 CFR Part 11 electronic records mandates:FDA enforcement of audit trails and user-access controls compels pharmaceutical buyers to validate SPR platforms for GxP environments, securing vendor procurement channels.
- High-throughput array formats:Drug screening operations demand parallel spot analysis capabilities, expanding imaging SPR adoption over single-channel benchtop configurations.
Market Restraints
- Gold sensor chip cost volatility:Precious metal pricing and specialized surface chemistry coatings concentrate consumable expenses, constraining academic lab adoption.
- Optical detector supply concentration:Photodiode and CMOS sensor fabrication concentrates in East Asian foundries, exposing lead-time risks for instrument manufacturers.
- Refractive index interference limits:Complex biological matrices and crude lysates generate background noise that degrades binding signal resolution below 100 Da detection thresholds.
Strategic Opportunities
- India biologics manufacturing expansion:CDSCO regulatory alignment with ICH guidelines creates validation pathways for SPR systems in emerging biosimilar production hubs.
- Spatialomics integration:Convergence of SPR imaging with mass spectrometry and single-cell transcriptomics enables multi-omic binding site mapping for precision medicine applications.
- Open-fluidic architectures:Academic end users seek reduced per-run consumable costs through modular cartridge designs that bypass proprietary closed-system lock-in.
Industry Challenges
- Surface chemist talent scarcity:Specialized expertise in thiol-based self-assembled monolayers and polymer brush functionalization lags instrument sales growth, extending customer onboarding.
- Legacy LIMS integration friction:Pharmaceutical IT departments face middleware development burdens connecting SPR data outputs to established electronic laboratory management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface Plasmon Resonance (SPR) System Market |
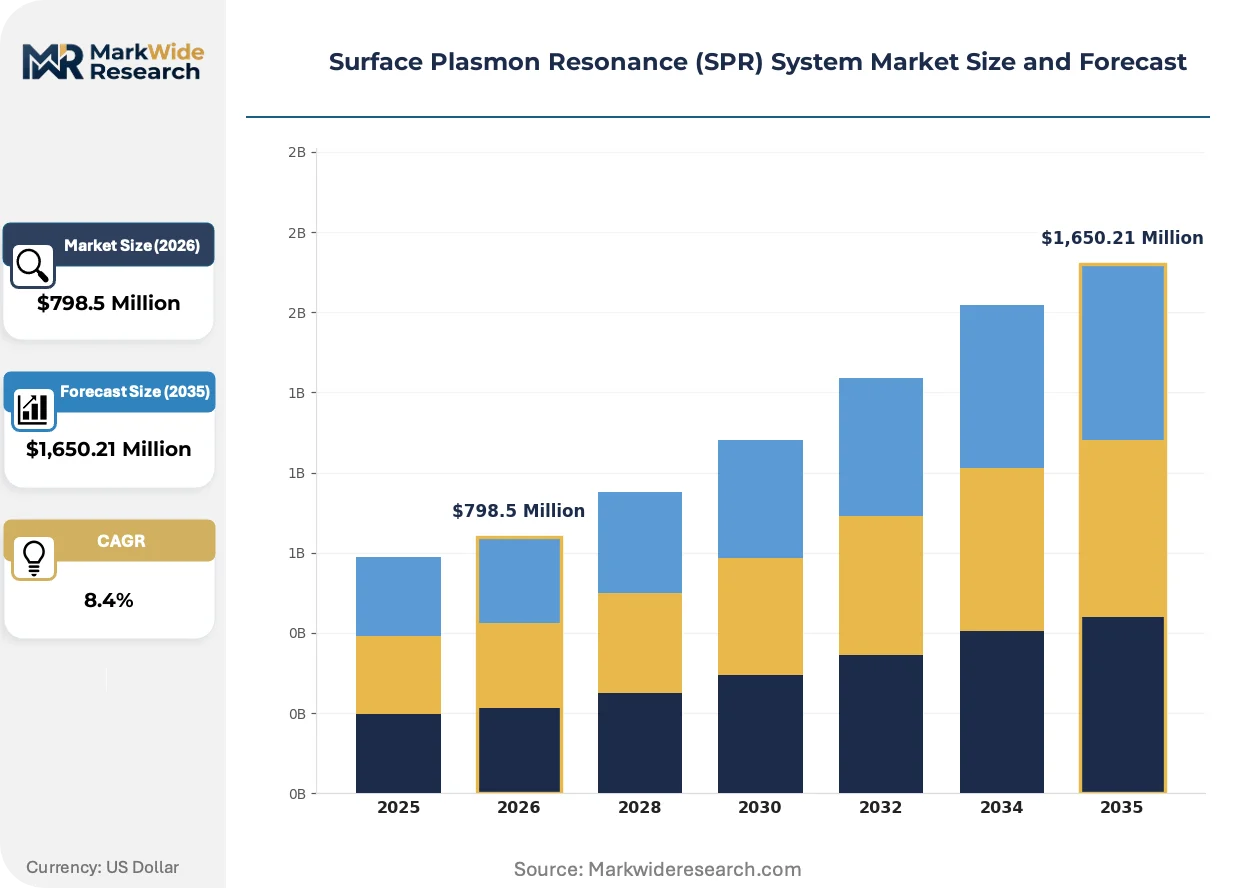
| Market Size in 2026 | $798.5 Million |
| Market Size in 2035 | $1,650.21 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Benchtop Systems, Portable Systems, Imaging Systems, Multi-channel Systems Application: Biomolecular Interactions, Drug Discovery, Clinical Diagnostics, Environmental Monitoring End User: Academic Institutions, Pharmaceutical Companies, Contract Research Organizations, Biotechnology Firms Technology: Label-free Detection, Real-time Monitoring, Surface Functionalization, Mass Transport Optimization |
| Companies Covered | Cytiva, AMETEK, General Electric, Bio-Rad Laboratories, Horiba, Carterra, Reichert Technologies, Nicoya Life Sciences, Biosensing Instrument, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Plasmon Resonance (SPR) System Market Trends and Innovations
Instrument architectures are fragmenting across performance tiers as biopharmaceutical quality demands diverge from academic throughput priorities, forcing vendors to modularize optical engines and fluidic cartridges rather than pursue universal platform designs.
Localized SPR sensors using fiber-optic and prism-free configurations are decentralizing kinetic analysis from centralized core facilities into distributed bioprocess development labs. Biologics manufacturers in Ireland and Singapore deploy these compact units at-line for real-time titer monitoring during upstream cell culture. The shift compresses decision cycles from days to hours but fragments data standardization across sites.
EU MDR material biocompatibility documentation requirements are reshaping sensor chip supply chains. ECHA REACH compliance for gold surface chemistries and fluidic polymers now extends development cycles by four to six months for CE-marked instruments. German and Swiss instrument vendors bear disproportionate certification burdens compared to US counterparts serving research-use-only segments.
Service unbundling is altering aftermarket revenue models. Pharmaceutical procurement teams now separate hardware validation, operator training, and maintenance contracts rather than accepting bundled multi-year agreements. This pattern concentrates in United States biotech clusters where capital efficiency metrics govern equipment lifecycle decisions. Vendors respond with tiered support tiers calibrated to GxP versus R&D operating environments.
Surface Plasmon Resonance (SPR) System Market Segmentation
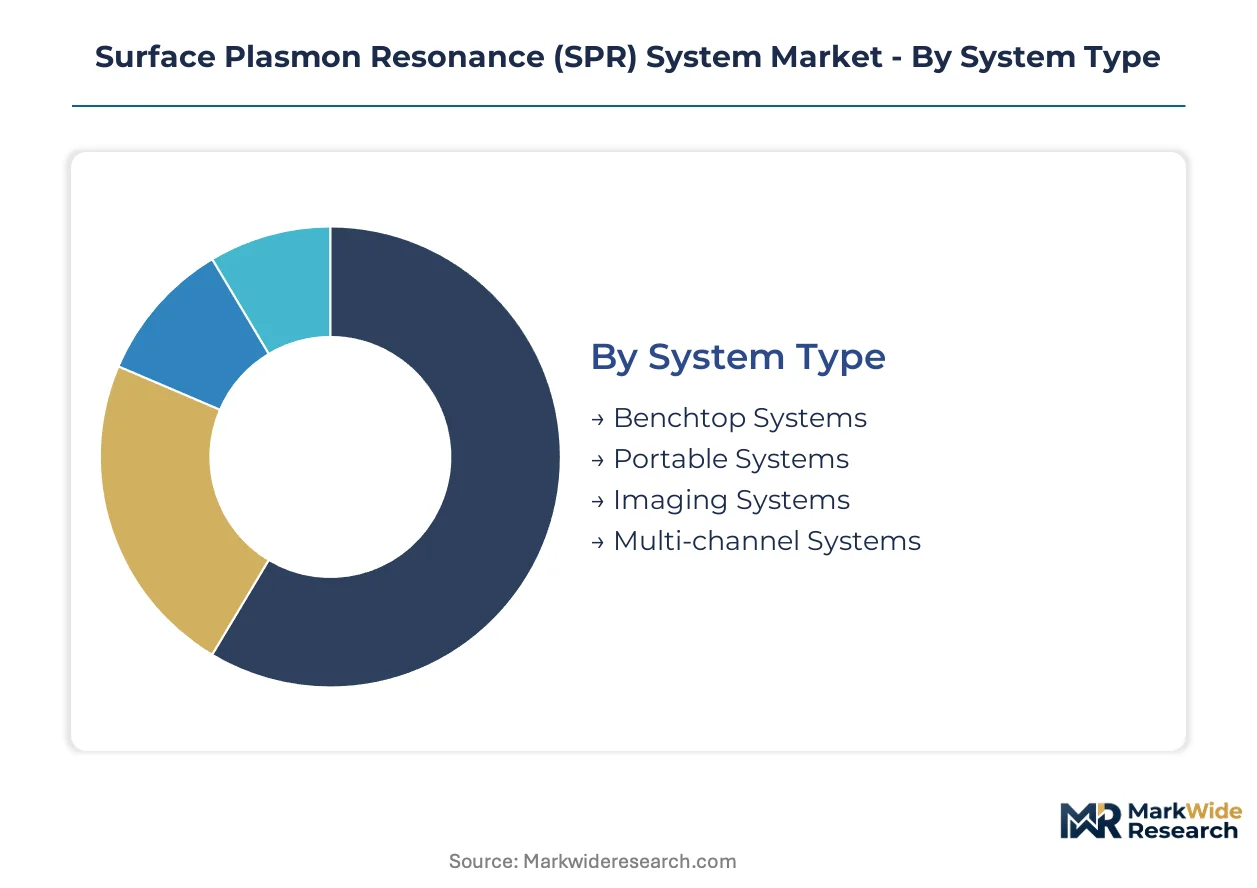
SPR system procurement diverges sharply between regulated pharmaceutical workflows demanding 21 CFR Part 11 validation and academic environments prioritizing consumable flexibility. Segment boundaries increasingly blur as imaging architectures penetrate quality control labs while benchtop units adopt modular fluidics.
System Type:
Capital allocation intensity and throughput requirements dictate buyer selection across optical configurations.
- Benchtop Systems:Single-channel or limited-channel configurations dominate pharmaceutical quality labs for antibody-antigen kinetic validation under FDA 21 CFR Part 11 protocols. Demand concentrates in United States biotech clusters where GxP compliance mandates secure vendor procurement channels through embedded audit trails.
- Imaging Systems:Parallel spot analysis capabilities enable spatial resolution of binding events across microarray formats for drug screening operations. Adoption accelerates in Boston-Cambridge cell therapy programs requiring high-density interaction mapping.
- Portable Systems:Compact fiber-optic and prism-free designs decentralize kinetic analysis into distributed bioprocess development labs.
- Multi-channel Systems:Configurations commanding premium positioning reduce per-sample operator time in contract research settings through simultaneous sample processing.
Volume sits with Benchtop Systems; growth tilts toward Imaging Systems.
Application:
Workflow integration depth separates segments by regulatory exposure and assay complexity.
- Drug Discovery:High-throughput kinetic screening of small-molecule libraries and biologics candidates drives imaging SPR adoption. Operations in San Diego and Basel cluster demand reduced cycle times from weeks to days.
- Biomolecular Interactions:Real-time quantification of binding kinetics, affinity constants, and thermodynamic parameters constitutes the core technical function across all system architectures.
- Clinical Diagnostics:Point-of-care and laboratory-based detection of disease biomarkers requires simplified fluidics and robust surface regeneration protocols.
- Environmental Monitoring:Trace contaminant detection in water and soil matrices applies SPR refractive index sensitivity to pollutant quantification.
Drug Discovery commands current revenue concentration; Clinical Diagnostics shows steepest expansion trajectory as regulatory pathways mature.
End User:
Budget authority and validation requirements fragment procurement patterns across organizational types.
- Pharmaceutical Companies:GxP-compliant kinetic characterization for biotherapeutic development and quality control mandates validated systems with comprehensive documentation packages. FDA 21 CFR Part 11 enforcement secures premium vendor relationships.
- Academic Institutions:Open-fluidic architectures and reduced consumable costs drive procurement for mechanistic biology and training programs.
- Contract Research Organizations:Multi-channel throughput and rapid turnaround requirements prioritize instrument utilization metrics.
- Biotechnology Firms:Early-stage antibody and cell therapy developers balance capital constraints against kinetic data requirements for investor due diligence.
Pharmaceutical Companies anchor installed base; Biotechnology Firms expand most quickly through venture-funded pipeline growth.
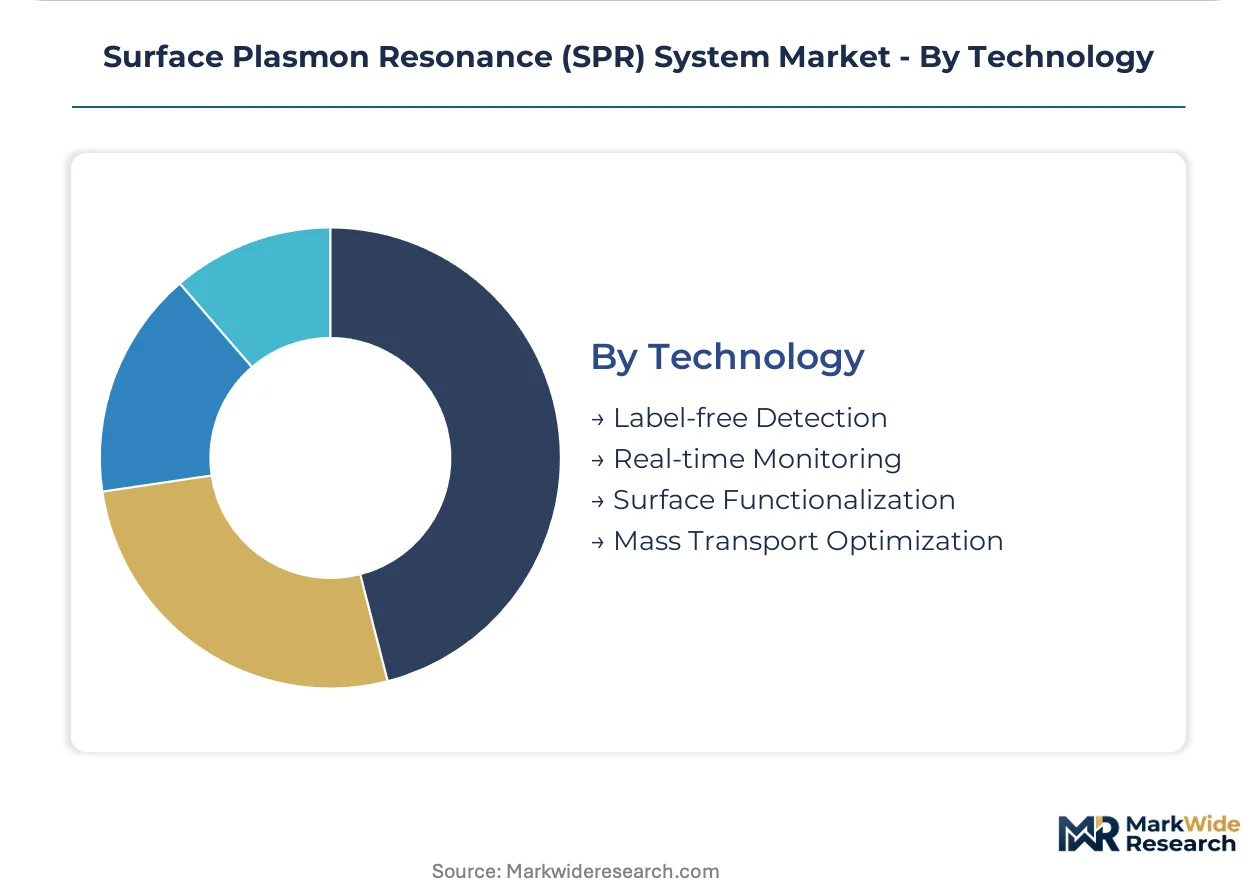
Technology:
Core optical and surface engineering capabilities differentiate competitive positioning.
- Label-free Detection:Evanescent wave quantification of refractive index changes eliminates fluorescent or radioactive tags, operating at resolutions of 10^-7 RIU with 100 Da molecular mass thresholds.
- Real-time Monitoring:Continuous binding curve acquisition enables kinetic rate constant determination without endpoint assays.
- Surface Functionalization:Thiol-based self-assembled monolayers and polymer brush chemistries concentrate specialized expertise bottlenecks.
- Mass Transport Optimization:Microfluidic design mitigates diffusion limitations for accurate kinetic parameter extraction.
Label-free Detection underpins all commercial value; Surface Functionalization represents capability scarcity constraining customer onboarding velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gold sensor chip fabrication concentrates in German and Swiss precision coating facilities, while optical detector foundries cluster in East Asian manufacturing zones. Instrument assembly and validation operations distribute across North American, European, and Asia-Pacific pharmaceutical hubs to satisfy regional regulatory requirements.
United States
Boston-Cambridge and San Diego biotech clusters drive procurement for antibody and cell therapy kinetic characterization programs. FDA 21 CFR Part 11 enforcement mandates embedded audit trails and user-access controls, securing premium vendor relationships with pharmaceutical quality labs. Massachusetts and California instrument installations concentrate in GxP-compliant bioprocess development facilities.
Germany
Biologics manufacturers in Bavaria and North Rhine-Westphalia deploy SPR systems for real-time titer monitoring during upstream cell culture operations. ECHA REACH compliance requirements for gold surface chemistries and fluidic polymers extend CE-marked instrument development cycles by four to six months. Frankfurt-Rhine-Main pharmaceutical corridors anchor high-throughput screening demand for imaging configurations.
Japan
PMDA alignment with ICH Q2(R1) validation guidelines creates additional conformance layers for analytical instrumentation market entry. Osaka-Kobe biotech manufacturing zones require kinetic characterization systems for biosimilar development programs. Tokyo-Yokohama research institutes prioritize modular fluidic architectures that reduce per-run consumable costs.
Switzerland
Basel pharmaceutical headquarters mandate comprehensive documentation packages for validated SPR platforms in biotherapeutic quality control workflows. Swissmedic oversight of medical device classifications shapes sensor chip biocompatibility documentation requirements. Zurich instrument vendors bear disproportionate EU MDR certification burdens compared to research-use-only competitors.
India
CDSCO regulatory alignment with ICH guidelines creates validation pathways for SPR systems in emerging biosimilar production hubs. Maharashtra and Karnataka biologics manufacturing expansion drives demand for label-free detection platforms in contract development facilities. Hyderabad and Bangalore clusters prioritize open-fluidic architectures to reduce capital constraints for academic end users.
Surface Plasmon Resonance (SPR) System Market Competitive Landscape
Global majors compete with regional champions across validation depth and consumable pricing vectors. The vendor base stratifies into three tiers: integrated life science conglomerates with chromatography-installed bases, specialized optical biosensor pure-plays, and modular open-system disruptors targeting academic price sensitivity. Consolidation pressures concentrate around GxP-compliant documentation capabilities and multi-year service contract bundling.
Within the integrated conglomerate tier, Cytiva leverages its chromatography-installed base to cross-sell workflows into bioprocess development labs. Bio-Rad Laboratories anchors the high-throughput screening segment through sustained array format investments. Nicoya Life Sciences exemplifies the open-architecture disruptor archetype, competing on reduced consumable costs for academic end users.
| Leading Market Players |
|---|
| Cytiva |
| AMETEK |
| General Electric |
| Bio-Rad Laboratories |
| Horiba |
| Carterra |
| Reichert Technologies |
| Nicoya Life Sciences |
| Biosensing Instrument |
| Others |
Pricing and Supply Chain Analysis
ECHA REACH compliance documentation for gold surface chemistries and fluidic polymers gates qualified supply access and premium-tier pricing power for CE-marked instruments, extending development cycles by four to six months while concentrating margin capture among German and Swiss vendors with established certification infrastructure.
Pricing Analysis
Extended warranty and validation service unbundling now dominates procurement negotiations, with pharmaceutical buyers separating hardware, operator training, and maintenance contracts rather than accepting bundled multi-year agreements. Three-tier pricing structure across premium, standard, and economy levels reflects GxP certification grade and embedded audit trail depth. Cost compression in academic-tier configurations is intensifying because open-fluidic disruptors bypass proprietary consumable lock-in. Contract research organizations exhibit highest price sensitivity due to utilization metric pressures, while pharmaceutical quality labs demonstrate lowest sensitivity given 21 CFR Part 11 compliance mandates.
Supply Chain Analysis
Regional distribution centers in Massachusetts, California, and Basel coordinate hub-and-spoke patterns for instrument validation and field service deployment. Gold sensor chip fabrication concentrates in German and Swiss precision coating facilities, while photodiode and CMOS sensor production rests on East Asian foundries in Taiwan, South Korea, and Japan. Single-source vulnerability in optical detector supply exposes lead-time risks for instrument manufacturers. Downstream distribution feeds from direct sales forces for GxP-compliant systems and channel partners for research-use-only segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around GxP-compliant documentation capabilities, with FDA 21 CFR Part 11 enforcement and EU MDR certification burdens forcing weaker players without validation infrastructure toward research-use-only niches or exit.
For Market Incumbents: Deploy embedded service contracts as the primary retention mechanism, anchoring pharmaceutical relationships through multi-year validation support and audit trail maintenance. Cytiva and Bio-Rad Laboratories should deepen backward integration into gold surface chemistry coating to secure consumable margin control against precious metal volatility. Incumbents must neutralize open-fluidic disruptors by modularizing fluidic cartridges that balance flexibility with regulatory documentation depth. For New Entrants and Emerging Players: Begin with academic price sensitivity in India and Southeast Asia, where CDSCO regulatory alignment creates validation pathways without incumbent certification overhead. Contract development organizations in Maharashtra and Karnataka represent the most penetrable segment due to capital constraints and rapid biosimilar expansion. Go-to-market execution should emphasize per-run consumable cost transparency and modular cartridge architectures that bypass proprietary closed-system lock-in. For Investors and Strategic Acquirers: FDA warning letter volume targeting data integrity violations is the leading indicator that GxP-compliant SPR platform demand is accelerating, signaling durable premium pricing power for validated vendors. Over a five-to-ten year horizon, acquisition targets should surface among mid-tier optical biosensor pure-plays with incomplete 21 CFR Part 11 documentation packages but established installed bases in pharmaceutical quality labs. Watch for inflection when EU MDR enforcement extends beyond device classification into active analytical instrumentation, triggering retrofit obligations across legacy instrument fleets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gold Surface Chemistry | Cytiva secures consumable margin control against ECHA REACH documentation burdens. |
| Open-Fluidic Architecture Launch | Nicoya Life Sciences reduces per-run costs for academic end users in Bangalore. |
| CE Marking Pathway Acceleration | Swiss vendors compress four-to-six month certification cycles for EU MDR compliance. |
| Multi-Channel Throughput Expansion | Contract research organizations in San Diego prioritize simultaneous sample processing. |
| Spatialomics Platform Integration | Imaging SPR convergence with mass spectrometry enables precision medicine binding site mapping. |
Research Methodology
Independent corroboration across primary interviews with bioprocess development executives, regulatory affairs leads at pharmaceutical quality labs, academic principal investigators, and SPR instrument procurement managers, combined with secondary validation through FDA 21 CFR Part 11 guidance documents, EMA MDR implementation reports, ECHA REACH substance databases, and SEC 10-K filings from listed life science conglomerates, underwrites the qualitative findings. Bottom-up and top-down triangulation reconciles instrument shipment data with end-user budget allocation surveys.
Rate-of-change decomposition separates volume expansion from value capture across system type, application workflow, end-user organizational category, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derive from logistic diffusion modeling of imaging SPR adoption curves and benchtop replacement cycles. Industry-specific forecast inputs incorporate biosimilar pipeline counts from Boston-Cambridge and San Diego clusters, plus CDSCO regulatory alignment milestones for Indian manufacturing expansion.
Underlying measurement precision varies by segment; pharmaceutical company procurement data carries tighter precision than academic institution budget estimates. Forecasts reflect documented assumptions regarding FDA enforcement intensity and EU MDR harmonization timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Scanning Electron Microscopes (SEM) Market
Analytical Instruments
Automated Microplate Handling Systems Market
Analytical Instruments
Flame Photometer Market
Analytical Instruments
Asia-Pacific Dissolved Gas Analyzer Market
Analytical Instruments
Surface and Field Analytics Market
Analytical Instruments
Signal Analyzer Market
Analytical Instruments
Spectrum and Signal Analyzers Market
Analytical Instruments
Global PH Electrochemical Electrodes Market
Analytical Instruments
Precision Balances Market
Analytical Instruments
Seawater Refractometers Market
Analytical Instruments
Benchtop Ph Meters Market
Analytical Instruments
Microfluidics Market
Analytical Instruments
Kinetic Chromogenic Spectrophotometer Market
Analytical Instruments
Dissolved Gas Analyzer Market
Analytical Instruments
Analytical Instrumentation Market
Analytical Instruments
ESR Analyzer Market