
 Absorbent Tray Liners Market | 2026-2036
Absorbent Tray Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Absorbent Tray Liners Market Outlook
Biodegradable fiber mat technology is narrowing the performance gap between traditional plastic liners and sustainable alternatives. Sealed Air Corporation leverages its film-to-fiber R&D pipeline to anchor North American food service accounts. Novipax LLC sustains European healthcare penetration through superabsorbent polymer formulations that meet clinical fluid-management protocols. Thrace Group competes on nonwoven manufacturing scale, supplying spunmelt and needlepunched substrates to private-label tray liner converters.
Absorbent tray liners are engineered sheet structures—typically comprising superabsorbent polymers, cellulose fluff pulp, or thermally bonded nonwovens—designed to capture and retain exudates, condensation, or purge fluids within food trays, medical containers, and retail packaging. Their primary commercial purpose centers on extending product presentation quality, reducing cross-contamination risk, and minimizing cleaning labor in high-throughput environments. The plastic segment still occupies the largest volume share due to cost efficiency and moisture-barrier performance, though the eco-friendly category is registering the fastest growth as food service chains face Scope 3 emissions reporting obligations. Heavy-duty thickness grades command the strongest margin pools, particularly in healthcare and protein packaging applications where fluid loads exceed standard absorbent capacity.
The FDA governs indirect food-contact materials through 21 CFR regulations, while the EU F-Gas Regulation and REACH constrain fluorinated barrier chemistries in absorbent liner coatings. EPA guidelines on municipal composting infrastructure influence whether biodegradable tray liners achieve end-of-life claims in the United States. Stakeholders must monitor evolving extended producer responsibility frameworks and material certification standards to secure shelf placement with sustainability-committed retail buyers.
Market Dynamics
Material substitution pressure from the EU Single-Use Plastics Directive is compressing traditional polymer-based tray liner margins while accelerating fiber-based capacity investments across European converters. This regulatory compression is redistributing competitive advantage toward nonwoven manufacturers with certified compostable substrate pipelines.
Growth Catalysts
- Superabsorbent Polymer Formulations:Healthcare fluid-management protocols in Germany and France are mandating higher absorbency standards for surgical and post-operative tray applications. Clinical procurement teams are specifying SAP-loaded liners to reduce nursing labor and cross-contamination incidents.
- REACH-Compliant Barrier Coatings:The EU F-Gas Regulation and REACH restrictions on fluorinated chemistries are creating compliant-product premiums. Liner converters with PFAS-free coating certifications are securing multi-year supply agreements with pan-European retail chains.
- Quick-Service Restaurant Standardization:Moisture-control specifications for protein and produce presentation are spreading from Germany into Austria and the Netherlands. Central kitchen operators are requiring absorbent liners as a condition of franchise approval.
Market Restraints
- Fluff Pulp Input Volatility:Softwood pulp prices tied to Scandinavian and Brazilian supply swings compress margin stability for cellulose-based liner producers. Spot market exposure in fluff pulp procurement erodes forward contract pricing power.
- Composting Infrastructure Gaps:EPA guidelines on municipal composting create end-of-life claim uncertainty for biodegradable tray liners in the United States. Certification without disposal pathway realization risks greenwashing liability.
- Plastic Cost Efficiency:Polyethylene and polypropylene substrates maintain 30-40% unit cost advantages over fiber alternatives in high-volume food service applications. Budget-constrained institutional buyers resist material switching without mandated compliance triggers.
Strategic Opportunities
- Hospital System Consolidation:German Klinikverbünde and French Groupements Hospitaliers de Territoire are centralizing procurement for hygiene disposables. National framework agreements for absorbent tray liners offer three-to-five-year volume commitments to qualified suppliers.
- Dual Carbon Policy Alignment:China's MIIT dual carbon goals and SAMR green product labeling are opening certification pathways for exported fiber-based liners. Early movers in GB-standards compliance are securing pilot programs with state-owned food logistics enterprises.
- Active Packaging Convergence:Integration of moisture-absorbing liners with ethylene scavenging and antimicrobial layers is creating premium produce packaging tiers. Fresh-cut salad processors in the Netherlands are testing multi-functional liner systems for extended shelf-life claims.
Industry Challenges
- Compostability Certification Timelines:TÜV Austria and BPI certification cycles for new fiber formulations extend 12-18 months. Product development pipelines stall awaiting end-of-life validation for retail buyer acceptance.
- Nonwoven Process Engineering Talent:Spunmelt and needlepunch optimization for absorbent applications requires specialized polymer and mechanical engineering expertise. European technical universities produce insufficient graduates for converter expansion plans.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Absorbent Tray Liners Market |
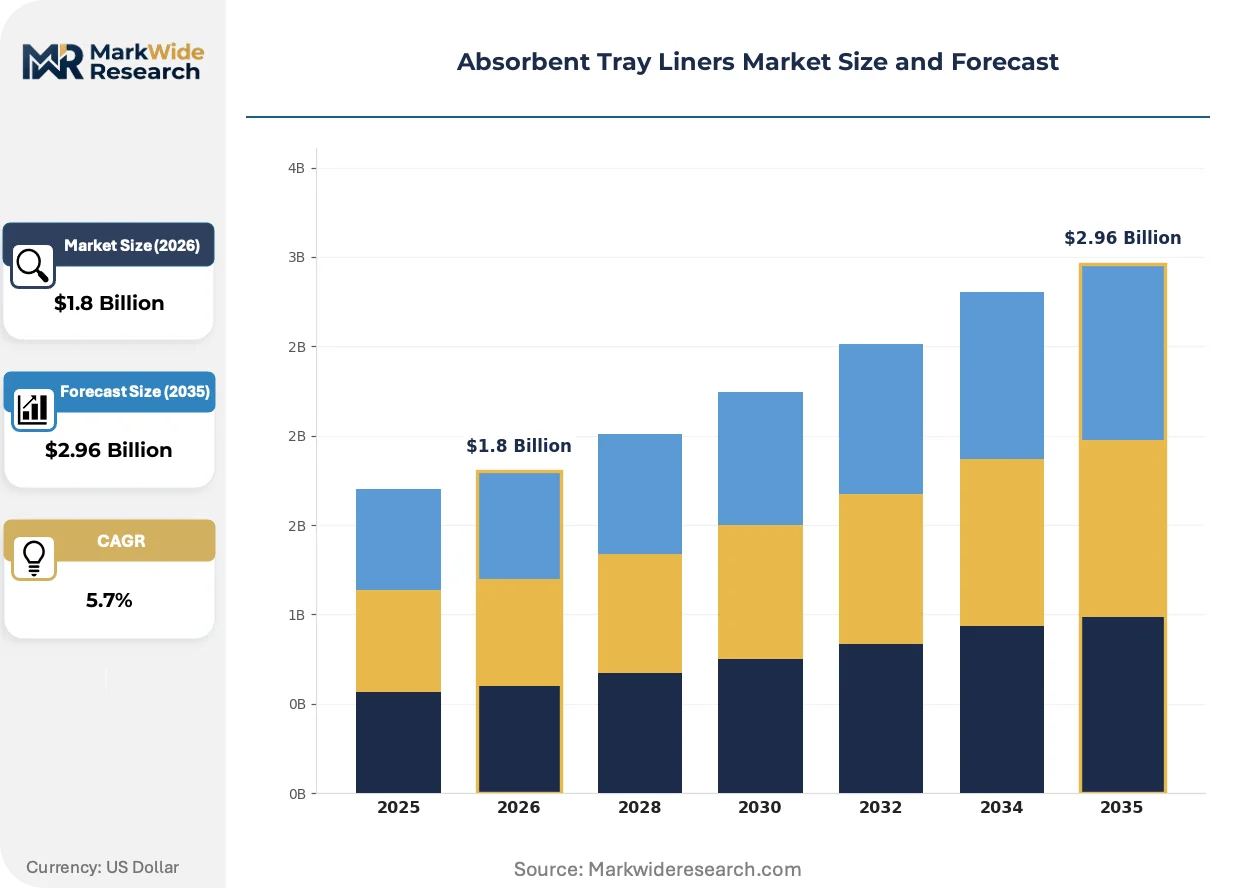
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Paper, Foam, Eco-friendly End User: Food Service, Healthcare, Retail, Pet Care Thickness: Lightweight, Standard, Heavy-duty, Extra Heavy-duty Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Novipax LLC, Thrace Group, Sealed Air Corporation, Drylock Technologies, Elliott Absorbents Ltd, Paper Pak Industries, Gelok International Corporation, Sirane Ltd, McAirlaid's Vliesstoffe GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Absorbent Tray Liners Market Strategic Shifts
Fiber-based material engineering is narrowing performance gaps with plastic substrates while digital specification tools are compressing buyer-supplier matching cycles. These shifts are reconfiguring how tray liner value propositions are constructed and validated.
Biodegradable fiber mat technology is virtualizing the traditional trade-off between moisture-barrier performance and end-of-life sustainability. Quick-service restaurant chains in Germany and the Netherlands are specifying certified compostable liners for protein packaging to meet Scope 3 emissions reporting obligations. The technology is virtualizing polymer-dependent supply relationships by enabling fiber converters to displace incumbent plastic suppliers on functional parity rather than compliance penalty alone.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating fluorinated barrier coatings from EU-sourced tray liners. Laminators are pivoting to bio-based wax and polylactic acid sealant layers that meet EFSA food-contact safety assessments. Protein packaging applications requiring grease and moisture resistance are absorbing the highest reformulation costs and driving consolidation among coating technology providers.
Centralized procurement platforms operated by German food retail cooperatives and French hospital purchasing groups are compressing supplier qualification cycles. Legacy distributor relationships are yielding to direct specification-by-certificate models where TÜV or BPI compostability documentation substitutes for historical vendor trust. The Netherlands and Belgium exhibit the most advanced platform adoption, with buyer concentration enabling standard-setting power over liner performance thresholds.
Absorbent Tray Liners Market Segmentation
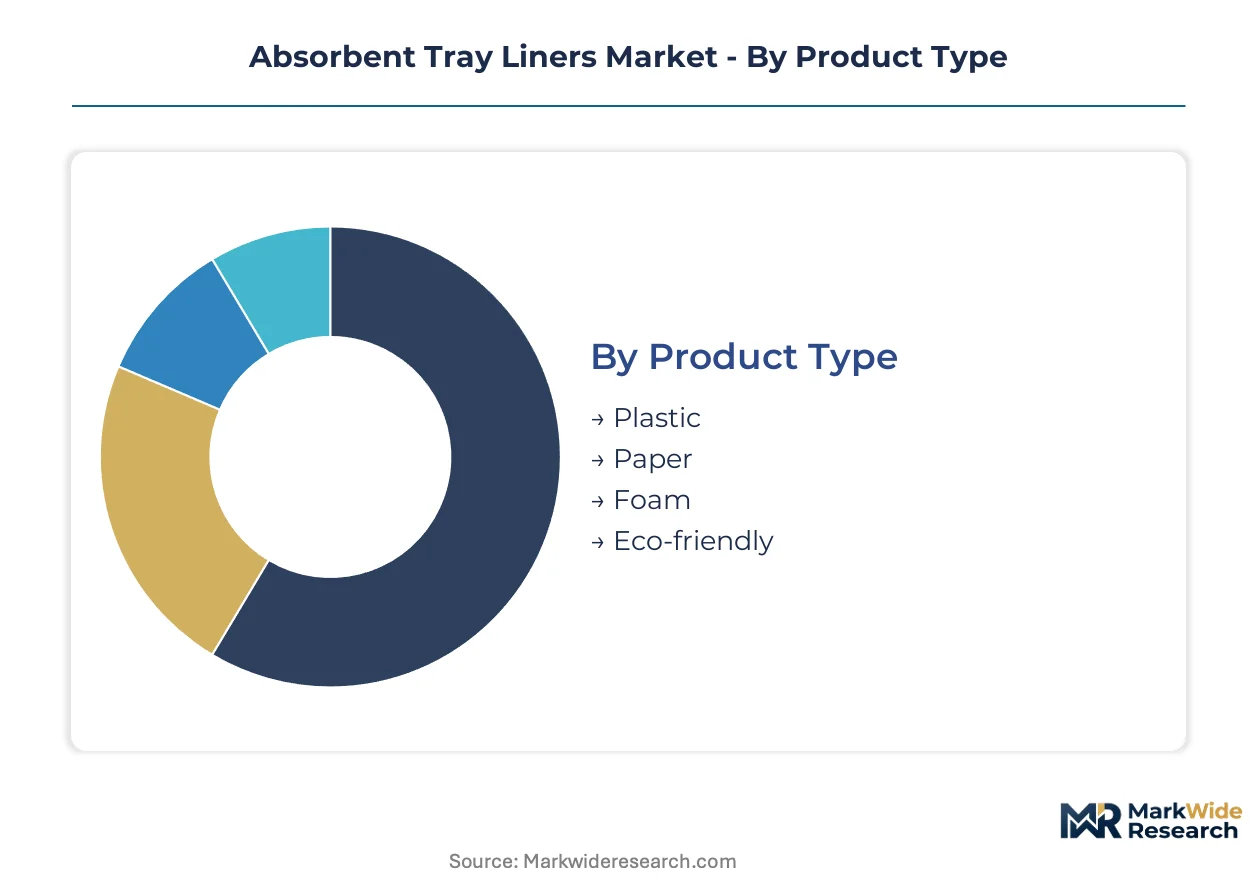
Segmentation in absorbent tray liners reveals divergent technical requirements across hygiene-sensitive end-uses. Material specifications, thickness grades, and channel strategies must align precisely with fluid-load demands and regulatory compliance thresholds in each vertical.
Product Type:
Mature polymer substrates dominate volume throughput while emerging fiber formats capture sustainability-driven specification shifts.
- Plastic:Polyethylene and polypropylene substrates deliver moisture-barrier performance and cost efficiency for high-volume food service applications. German quick-service restaurant chains specify plastic liners for protein packaging where fluid containment trumps end-of-life claims. Budget-constrained institutional buyers resist switching without mandated compliance triggers.
- Eco-friendly:Certified compostable fiber mats comprising cellulose fluff pulp and bio-based coatings are displacing polymer-dependent supply relationships. Dutch fresh-cut salad processors and German hospital systems specify these liners to meet Scope 3 emissions reporting obligations and EU Single-Use Plastics Directive requirements. TÜV Austria and BPI certification cycles extend 12-18 months, stalling product pipelines.
- Paper:Thermally bonded kraft and molded pulp structures serve cost-sensitive retail produce presentation with limited reusability.
- Foam:Open-cell polyurethane and polystyrene variants absorb grease and condensation in hot-food tray applications.
Plastic handles the majority of throughput; eco-friendly is expanding most quickly on specification share.
End User:
Application-specific fluid-management protocols create divergent performance thresholds and procurement authority structures.
- Healthcare:Surgical and post-operative tray applications in Germany and France mandate superabsorbent polymer formulations that meet clinical fluid-management protocols. German Klinikverbünde centralize procurement for hygiene disposables, offering multi-year framework agreements to qualified suppliers. Nursing labor reduction and cross-contamination risk mitigation drive specification authority.
- Food Service:Moisture-control specifications for protein and produce presentation spread from Germany into Austria and the Netherlands. Central kitchen operators require absorbent liners as a condition of franchise approval. Quick-service restaurant standardization concentrates demand around certified compostable formats.
- Retail:Food retail chains standardize absorbent liner protocols for shelf presentation quality and hygiene compliance.
- Pet Care:Veterinary practices and pet boarding facilities specify liners for cage and carrier hygiene management.
Healthcare commands premium pricing through clinical certification requirements; food service offers the steepest volume expansion trajectory.
Thickness:
Fluid-load capacity stratifies margin pools and manufacturing complexity across the specification range.
- Heavy-duty:Multi-layer structures with elevated superabsorbent polymer loading manage protein purge volumes and post-surgical exudates. Healthcare and protein packaging applications absorb the highest reformulation costs for REACH-compliant barrier coatings. These grades command the strongest margin pools.
- Extra Heavy-duty:Maximum absorbency configurations address specialized medical waste containment and industrial food processing.
- Standard:Single-ply or lightly laminated constructions serve routine retail produce and general food service moisture control.
- Lightweight:Minimal absorbent capacity for condensation management in beverage tray and display applications.
Heavy-duty captures the majority of value extraction; extra heavy-duty is gaining specification fastest in clinical segments.
Distribution Channel:
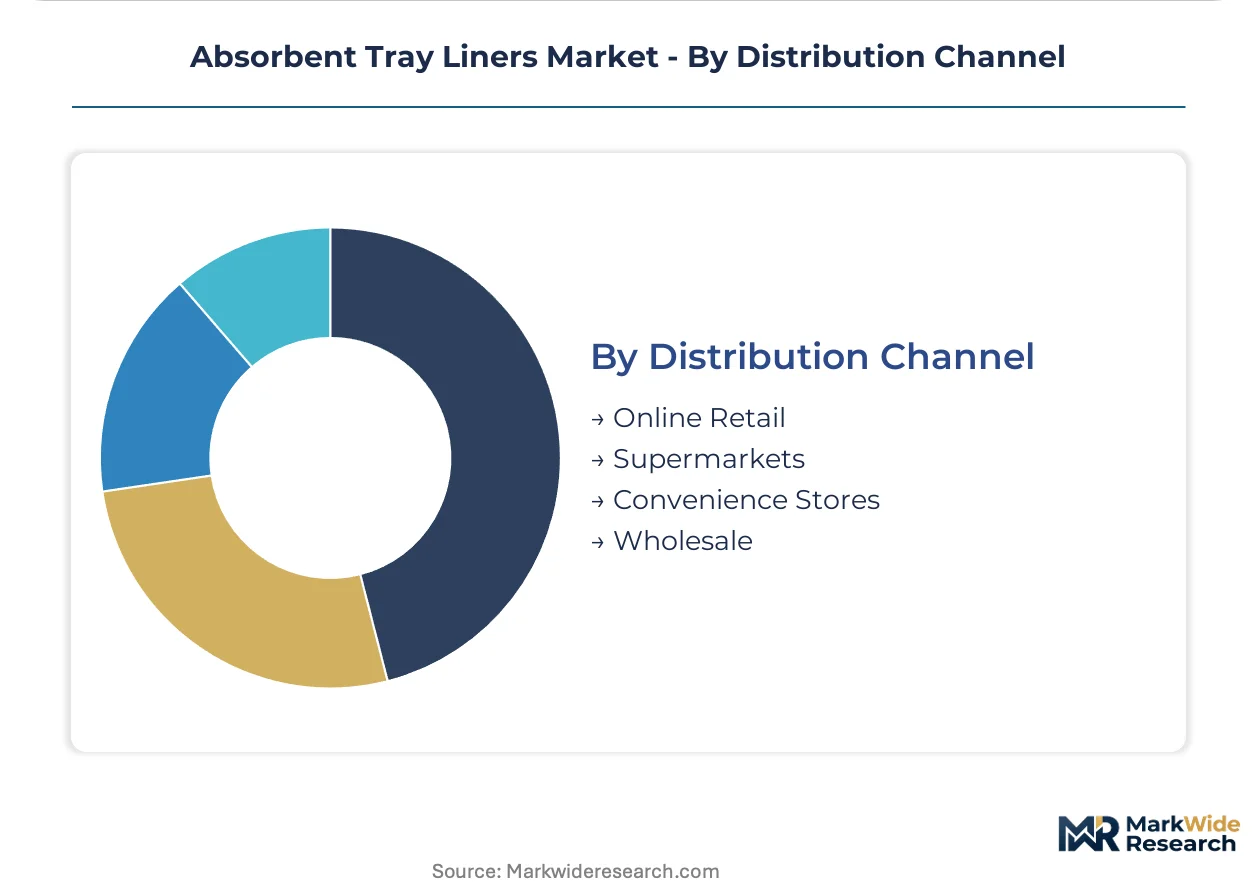
Channel selection reflects buyer scale, certification requirements, and procurement centralization trends.
- Wholesale:Institutional buyers and food service operators source through dedicated distribution for volume pricing and technical specification support. German food retail cooperatives and French hospital purchasing groups operate centralized procurement platforms that compress supplier qualification cycles.
- Online Retail:Digital specification-by-certificate models enable direct matching between compostability documentation and sustainability-committed buyers. The Netherlands and Belgium exhibit the most advanced platform adoption.
- Supermarkets:Private-label tray liner programs for consumer-facing produce packaging.
- Convenience Stores:Small-format grab-and-go food service applications with limited inventory depth.
Wholesale manages the majority of institutional volume; online retail is climbing the fastest on specification transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters export fiber-based absorbent tray liners to Dutch and Belgian food retail chains seeking EU Single-Use Plastics Directive compliance. This trade corridor channels certified compostable substrates into centralized procurement platforms across the Low Countries.
Germany
Hospital procurement centralization through Klinikverbünde drives superabsorbent polymer specification for surgical tray applications. The EU F-Gas Regulation and REACH constrain fluorinated barrier chemistries, forcing coating reformulation. Bavarian nonwoven manufacturers supply spunmelt substrates to private-label converters serving quick-service restaurant chains.
France
Groupements Hospitaliers de Territoire consolidate hygiene disposable purchasing for post-operative fluid management. ANSM clinical safety protocols mandate absorbency certification for medical tray liners. The Lyon-Grenoble corridor hosts coating technology providers pivoting to bio-based wax sealants.
Netherlands
Fresh-cut salad processors test multi-functional liner systems combining moisture absorption with ethylene scavenging. EFSA food-contact assessments govern bio-based coating approvals. Rotterdam-based logistics enterprises pilot imported fiber-based liners under China's MIIT dual carbon alignment programs.
United States
Quick-service restaurant chains face Scope 3 emissions reporting obligations without matching municipal composting infrastructure. EPA guidelines on end-of-life disposal create greenwashing liability risks for biodegradable liner claims. Chicago-area food service distributors maintain plastic liner dominance due to unit cost advantages.
China
State-owned food logistics enterprises pilot GB-standards-compliant fiber-based liners through SAMR green product labeling pathways. MIIT dual carbon goals accelerate domestic certification for export-oriented converters. Yangtze River Delta manufacturers develop active packaging convergence technologies for premium produce segments.
Absorbent Tray Liners Market Competitive Environment
On the supply side, the industry is structured around three distinct capability tiers. Film-to-fiber R&D pipelines, superabsorbent polymer formulation expertise, and nonwoven manufacturing scale define competitive positioning. Strategic archetypes include integrated material science conglomerates, specialized absorbent technology developers, and substrate-scale nonwoven producers. Capacity expansion in certified compostable substrates and backward integration into fluff pulp supply represent the dominant competitive moves.
Within the integrated material science tier, Sealed Air Corporation anchors North American food service account relationships through film-to-fiber transition capabilities. Novipax LLC occupies a position exemplifying clinical fluid-management specialization for European healthcare penetration. Thrace Group represents the scale-driven nonwoven manufacturing archetype, supplying spunmelt and needlepunched substrates to private-label converters across European markets.
| Leading Market Players |
|---|
| Novipax LLC |
| Thrace Group |
| Sealed Air Corporation |
| Drylock Technologies |
| Elliott Absorbents Ltd |
| Paper Pak Industries |
| Gelok International Corporation |
| Sirane Ltd |
| McAirlaid's Vliesstoffe GmbH & Co. KG |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in European spunmelt nonwoven production is compressing converter margins while granting procurement leverage to German hospital purchasing groups and Dutch food retail cooperatives. This utilization imbalance forces substrate suppliers to absorb fluff pulp volatility through contract pricing rather than pass-through mechanisms.
Pricing Analysis
The technology-generation pricing gap between legacy polyethylene liners and next-generation fiber-based alternatives spans three distinct performance tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—TÜV Austria and BPI compostable certifications command substantial premiums over uncertified fiber alternatives. Cost compression in the plastic segment intensifies because Brazilian and Scandinavian fluff pulp spot markets expose cellulose-based producers to margin instability. Budget-constrained institutional buyers in United States food service demonstrate highest price sensitivity, while German Klinikverbünde purchasing committees show lowest sensitivity due to clinical compliance mandates.
Supply Chain Analysis
Upstream feedstock concentration in fluff pulp draws from Scandinavian softwood plantations, Brazilian eucalyptus operations, and North American timberlands. Superabsorbent polymer supply rests on petrochemical complexes in Germany, China, and South Korea. Single-source vulnerability in PFAS-free coating chemistry creates bottleneck risk for EU REACH-compliant barrier formulations. Distribution runs through wholesale procurement platforms operated by French Groupements Hospitaliers de Territoire and German food retail cooperatives, with online retail channels gaining specification transparency in Netherlands and Belgium.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment—EU Single-Use Plastics Directive compliance timelines and 12-18 month compostability certification cycles create structural barriers to rapid competitive displacement.
For Market Incumbents: Pre-empt coating technology consolidation by securing backward integration into bio-based wax and polylactic acid sealant supply before REACH Annex XVII restrictions eliminate remaining fluorinated chemistry options. Expand spunmelt capacity in Bavaria to capture Klinikverbünde framework agreement volumes before nonwoven process engineering talent scarcity constrains competitor expansion.
For New Entrants and Emerging Players: Pursue white-space opportunities in active packaging convergence—specifically multi-functional liner systems combining moisture absorption with ethylene scavenging for Netherlands fresh-cut salad processors. Target United States quick-service restaurant chains facing Scope 3 emissions reporting obligations without domestic composting infrastructure, offering hybrid fiber-plastic laminated solutions that bridge performance and compliance gaps.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among clinical fluid-management specialists serving German and French hospital purchasing groups through multi-year framework agreements. Long-term viability over the projection horizon favors acquisition targets with certified compostable substrate pipelines and established TÜV Austria validation records. Watch for inflection signals in China's MIIT dual carbon goal implementation pace, which would accelerate GB-standards compliance requirements for export-oriented converters.
| Strategic Initiative | Industry Significance |
|---|---|
| Certified Compostable Capacity Expansion | TÜV Austria and BPI validation secures shelf placement with EU Single-Use Plastics Directive-committed retail buyers. |
| Backward Integration into Fluff Pulp Supply | Captive softwood pulp sourcing insulates margin stability from Scandinavian and Brazilian spot market volatility. |
| PFAS-Free Coating Technology Acquisition | REACH Annex XVII compliance eliminates fluorinated barrier chemistry competitors from pan-European supply agreements. |
| Hospital System Framework Agreements | German Klinikverbünde and French GHT procurement centralization locks in three-to-five-year volume commitments. |
| Active Packaging Convergence R&D | Multi-functional liner systems with ethylene scavenging capture premium produce packaging tiers in Netherlands. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and hospital procurement databases. Interviews with nonwoven manufacturing plant managers, hygiene disposable procurement leads at German Klinikverbünde, coating technology R&D directors, and quick-service restaurant central kitchen operators informed demand-side validation. Secondary sources included ECHA REACH substance restrictions, EU F-Gas Regulation implementation guidance, EPA municipal composting infrastructure assessments, and TÜV Austria compostability certification records. Bottom-up segment modeling triangulated against top-down macroeconomic drivers.
Forecast inputs incorporate material substitution rates under EU Single-Use Plastics Directive, fluff pulp price trajectory assumptions, and certification timeline distributions across the analysis window. Segmentation dimensions span product type, end user vertical, thickness grade, and distribution channel. CAGRs derived from regression analysis of historical volume shifts against regulatory compliance deadline proximity. Industry-specific inputs include Klinikverbünde procurement centralization pace and MIIT dual carbon goal implementation velocity in China.
Sensitivities concentrate around REACH Annex XVII expansion scope, municipal composting infrastructure buildout rates in United States, and fluff pulp supply disruptions from Scandinavian forestry labor actions. Forecasts reflect assumptions on certification cycle durations and buyer switching cost thresholds. Material shifts in EU extended producer responsibility framework adoption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Kraft Packaging Market
Packaging Materials
VCI Films Market
Packaging Materials
3D Printed Packaging Market
Packaging Materials
MDO Films Market
Packaging Materials
Non-Plastic Punnets Market
Packaging Materials
Flow Wraps Market
Packaging Materials
Shrink Packaging Market
Packaging Materials
Mylar Market
Packaging Materials
Expendable Packaging Market
Packaging Materials
Packaging Materials Market
Packaging Materials
Desiccant Market
Packaging Materials
Collapsible Tube Packaging Market
Packaging Materials
Nonwoven Packaging Market
Packaging Materials
Tube and Stick Packaging Market
Packaging Materials
Europe Airless Packaging Market
Packaging Materials
Mailer Packaging Market