
 Window Packaging Market | 2026-2036
Window Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Window Packaging Market Analytics
Food-grade clarity specifications is reorganizing procurement priorities across the window packaging value chain. Owens-Illinois leverages its furnace technology leadership to sustain premium glass window container output. Vetropack anchors Central European supply through integrated melting and forming operations. Ardagh Group competes on lightweighting innovation for reduced material intensity in window glass formats.
Window packaging denotes transparent or semi-transparent panels integrated into primary or secondary packaging to enable visual product inspection without seal breach, typically achieved through thermoformed PET films, cut-out apertures with laminated films, or molded glass windows bonded to paperboard substrates. The construction demands optical clarity standards, barrier coherence against moisture and oxygen, and mechanical compatibility with automated filling lines across ambient and chilled distribution. Boxes and pouches command the largest volume positions, though trays are gaining fastest in prepared meal and fresh produce applications where shelf visibility drives purchase conversion. Glass window segments retain premium margin pools in spirits and cosmetics, while plastic films dominate unit economics in mass-market food packaging.
The EU Green Deal and REACH frameworks mandate recyclability thresholds and restricted substance limits for window films and adhesives, compelling converters to validate mono-material compatibility. The FDA maintains optical clarity and migration testing protocols for food-contact window layers in the United States. Stakeholders must monitor evolving extended producer responsibility schemes and material-specific recycling infrastructure investments to align product development with compliance trajectories and collection system capabilities.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing design cycles as converters scramble to validate mono-material window constructions before recyclability mandates take full effect.
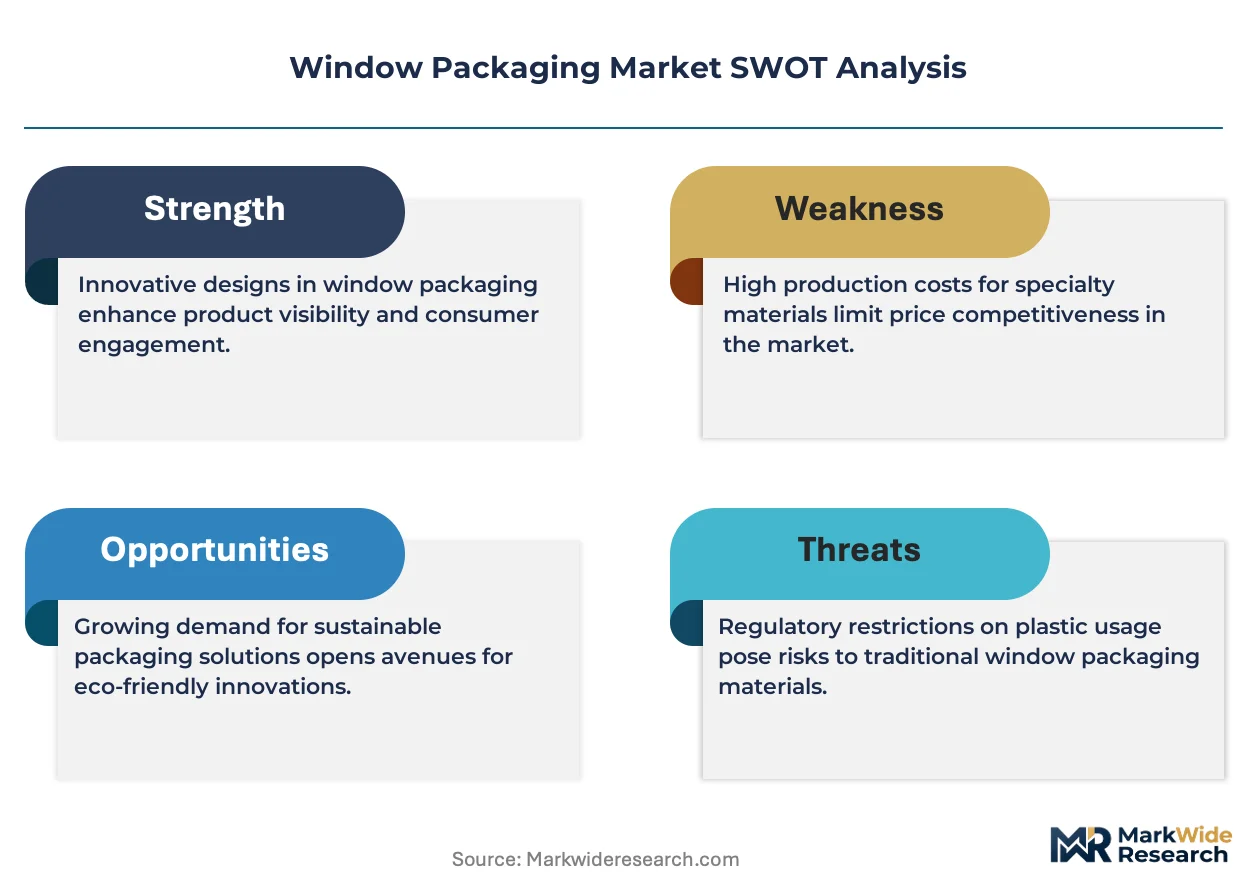
Growth Catalysts
- EU Green Deal compliance:Food & Beverage brands across Germany, France, and Italy are accelerating transparent packaging procurement to preempt regulatory penalties and secure shelf access in major retail chains.
- Prepared meal visibility demand:Fresh produce and ready-to-eat segments are driving tray format adoption where optical clarity directly influences purchase conversion at point-of-sale.
- Furnace technology advancement:Premium spirits and cosmetics manufacturers are expanding glass window specifications as optical clarity standards tighten for luxury positioning.
Market Restraints
- Recyclable adhesive scarcity:Validated chemistries compatible with both optical clarity and post-consumer paperboard recovery remain limited, constraining converter output flexibility.
- Central European supply concentration:Integrated melting and forming operations in Austria and Czechia create geographic vulnerability for glass window sourcing during energy price spikes.
- Barrier performance trade-offs:Mono-material PET films struggle to match multi-layer laminates for oxygen transmission rates, restricting shelf-life extension in ambient distribution.
Strategic Opportunities
- Extended producer responsibility alignment:Early investment in deposit-return infrastructure partnerships in Sweden and Netherlands secures preferential access to recycled feedstock pools.
- Smart packaging convergence:Integration of printed electronics behind transparent windows enables freshness indicators without compromising visual inspection functionality.
- Direct-to-consumer channel expansion:E-commerce fulfillment specifications for damage-resistant window constructions are creating premium tier demand unmet by conventional corrugated solutions.
Industry Challenges
- Migration testing backlog:FDA and EFSA queue delays for novel food-contact window layers are extending product launch timelines by 8-14 months for reformulated adhesives.
- Legacy equipment retrofit costs:Automated filling lines designed for opaque substrates require substantial modification to handle optical quality inspection and reduced mechanical tolerance windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Window Packaging Market |
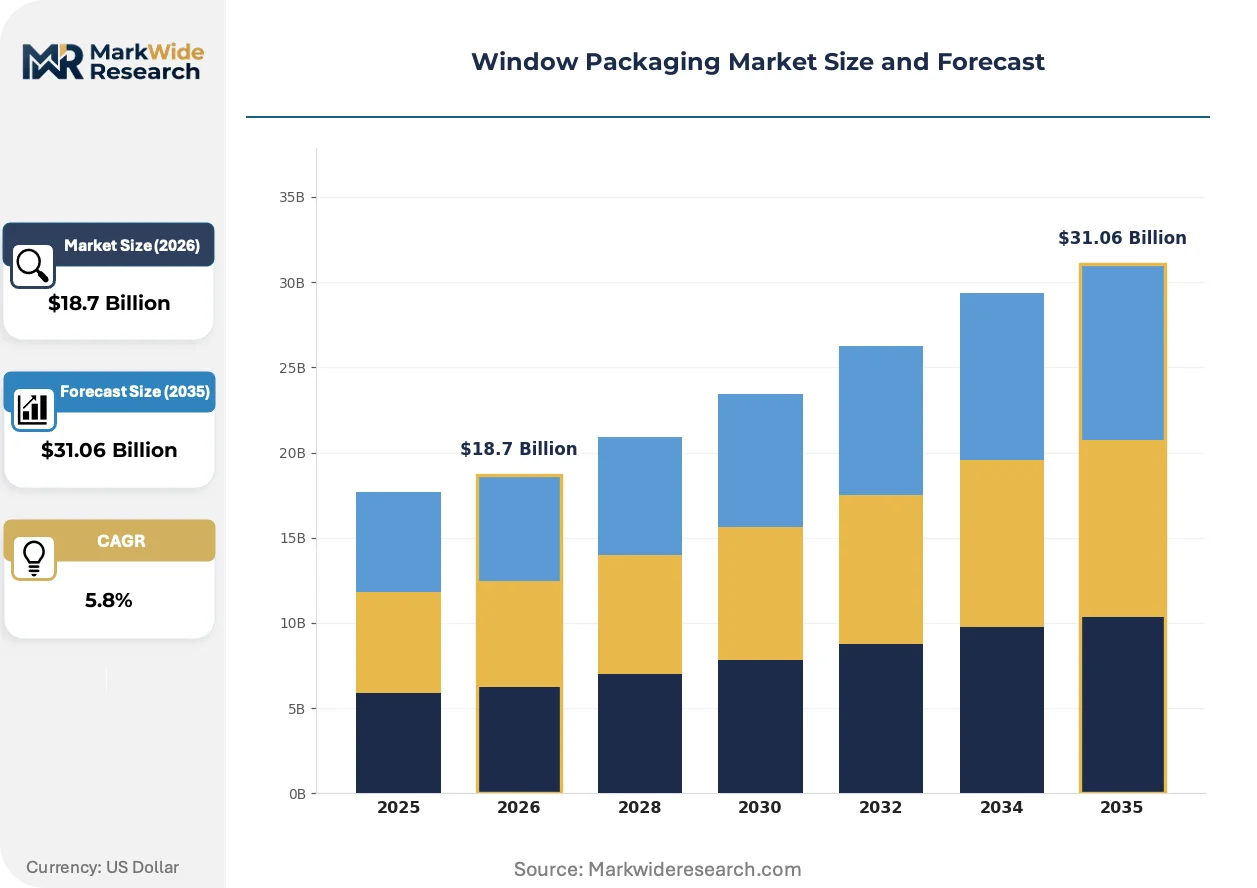
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Bags, Pouches, Trays Material: Plastic, Paper, Glass, Metal End User: Food & Beverage, Cosmetics, Electronics, Pharmaceuticals Feature: Recyclable, Durable, Waterproof, Tamper-Proof |
| Companies Covered | Anadolu Cam, BA Glass BV, Owens-Illinois, Vetropack, Gerresheimer, Ardagh Group, Vidrala, Pochet SAS, Verallia SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Window Packaging Market Evolving Landscape
Material science breakthroughs and enforcement tightening are compressing legacy multi-layer constructions while opening premium positioning for validated sustainable alternatives.
Cellulose-based transparent films are decomposing the PET dominance in ambient food windows. Organic and natural product lines in German retail are specifying these materials at 15-20% price premiums. The technology is decomposing the historical barrier-to-recyclability trade-off that protected conventional film margins.
REACH substance restriction expansions are forcing adhesive reformulation across the European converter base. ECHA's updated candidate list for SVHCs now captures several common window lamination chemistries previously grandfathered under transitional provisions. Premium chocolate and confectionery brands with export exposure to both EU and Swiss markets are consolidating supplier qualification around pre-validated mono-material platforms.
Retail buyer consolidation is compressing supplier negotiation leverage. Three pan-European grocery alliances now control the majority of private-label window packaging specifications, shifting volume commitments toward multi-year framework agreements with technical performance guarantees. This concentration is most visible in fresh produce categories where German discounters and French hypermarkets coordinate seasonal packaging transitions.
Window Packaging Market Segmentation
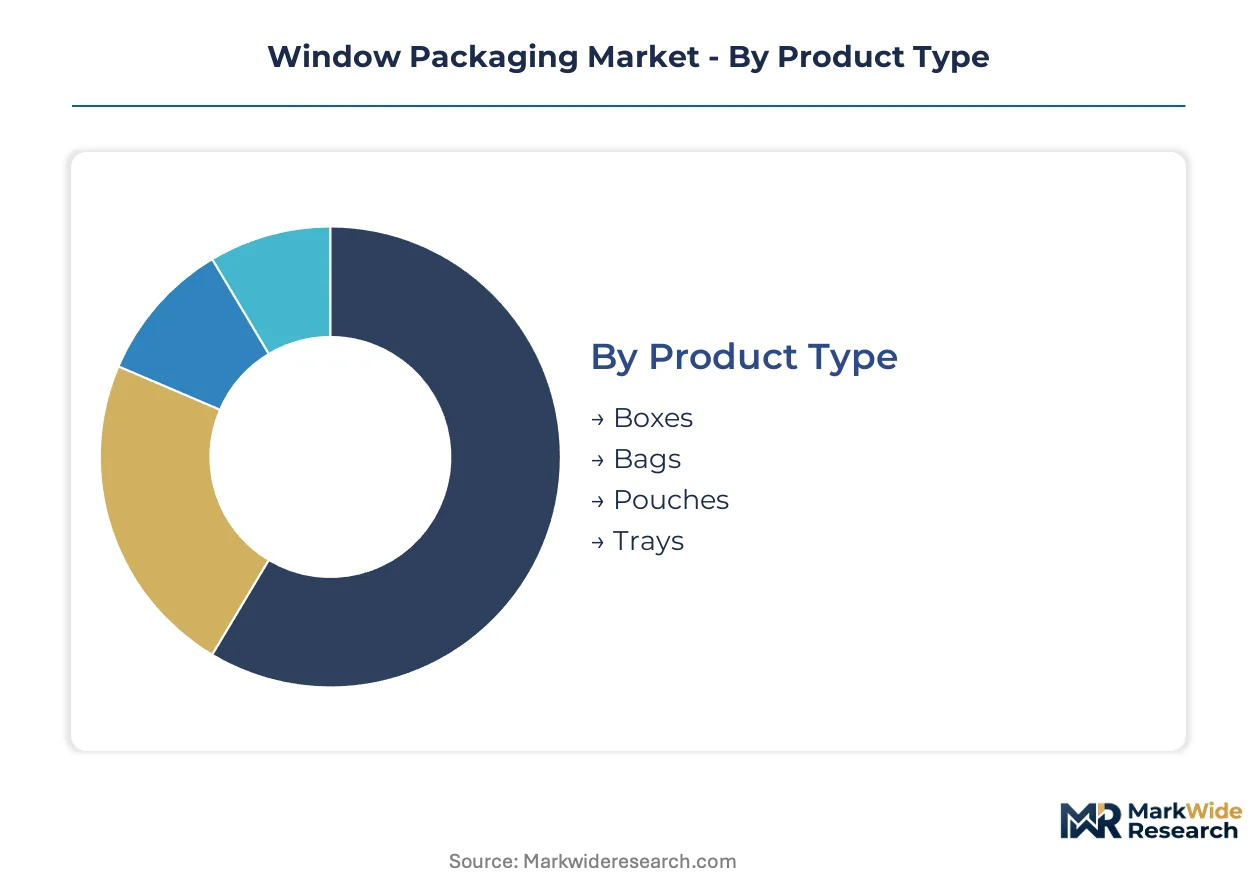
Window packaging procurement decisions split across technical specifications, regulatory compliance tiers, and end-use visibility requirements. Material and format selections determine recyclability validation pathways under EU Packaging and Packaging Waste Regulation mandates.
Product Type:
EU Green Deal recyclability thresholds are forcing converters to redesign aperture geometries and film-to-substrate bonding methods across all formats.
- Boxes:Corrugated fiberboard structures with die-cut apertures laminated to transparent films dominate ambient retail distribution. German and French grocery chains specify these for dry goods where shelf visibility drives private-label conversion.
- Pouches:Flexible stand-up and flat pouch configurations with integrated film windows are expanding fastest in snack and confectionery segments. Italian processors favor mono-material PET constructions to preempt EPR penalties.
- Trays:Thermoformed plastic or molded fiber bases with lidding film windows serve prepared meals and fresh produce. Austrian retailers are consolidating specifications around these formats for chilled distribution.
- Bags:Pinch-bottom and gusseted paper bags with film windows retain niche positions in specialty coffee and artisan food segments.
Boxes handle the majority of throughput; trays are gaining share fastest as fresh prepared meal penetration deepens in Central European retail.
Material:
Paper substrates command volume leadership through corrugated and folding carton integration, though their film lamination requirements complicate recyclability claims.
- Plastic:PET, PP, and bio-based films deliver optical clarity and forming flexibility for thermoformed trays and pouch windows. REACH SVHC restrictions are accelerating adhesive reformulation for Czech and Polish converter bases.
- Paper:Kraft and coated paperboard provide printable surfaces for secondary branding while requiring laminated films for window functionality. Swedish deposit-return systems favor these for fiber recovery rates.
- Glass:Molded window panels bonded to paperboard sleeves or integrated into rigid containers serve premium spirits and cosmetics. Energy price volatility in Austrian and Czech melting operations is compressing margin pools.
- Metal:Tinplate or aluminum apertures with transparent inserts occupy minimal share in luxury confectionery and gift packaging.
Plastic films dominate unit economics; paper substrates are climbing the fastest on EPR alignment and retailer sustainability scorecards.
End User:
Food-contact migration testing backlogs at EFSA and FDA are extending qualification timelines for window layer reformulations.
- Food & Beverage:Ambient, chilled, and frozen applications span bakery, confectionery, dairy, and ready meals. German discounters and French hypermarkets coordinate seasonal transitions that consolidate supplier frameworks.
- Cosmetics:Premium skincare and fragrance brands specify glass or high-clarity plastic windows for luxury positioning. Swiss and German regulatory overlap on SVHC compliance is narrowing qualified supplier pools.
- Pharmaceuticals:Blister packs and compliance packaging with transparent windows for medication verification face stringent EMA stability testing requirements.
- Electronics:Anti-static film windows for component visibility in retail packaging represent a peripheral segment with specialized barrier demands.
Food & Beverage commands the volume base; Cosmetics is expanding most quickly on premiumization and optical clarity specification tightening.
Feature:
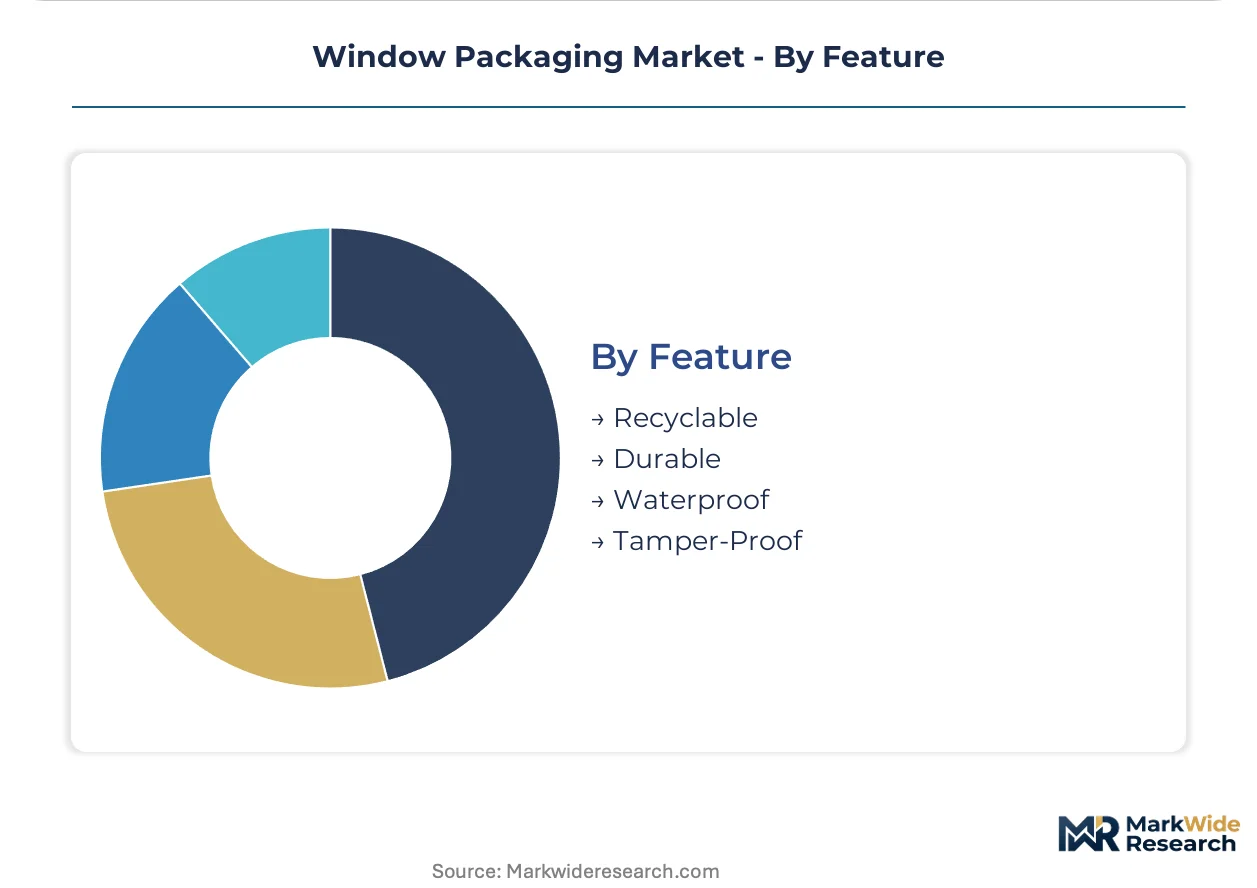
Recyclability validation now functions as a gatekeeper feature rather than a value-add, with mono-material constructions required for EPR compliance in core EU markets.
- Recyclable:Mono-material PET or paperboard-film combinations validated for post-consumer recovery streams. Netherlands and Swedish infrastructure investments are creating preferential feedstock access for early adopters.
- Tamper-Proof:Break-seal films and irreversible closure indicators satisfy FDA food defense guidelines and EU food contact material safety requirements.
- Waterproof:Moisture barrier coatings and film laminations protect hygroscopic products in chilled distribution. Austrian dairy processors specify these for extended shelf-life requirements.
- Durable:Puncture-resistant film specifications and reinforced paperboard structures withstand e-commerce fulfillment stress testing.
Recyclable features handle regulatory compliance throughput; tamper-proof specifications are gaining share fastest on food safety audit intensification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated glass melting and forming operations cluster in Austria and Czechia, creating geographic vulnerability for premium window container sourcing. Paperboard-film lamination converters concentrate in Germany and Poland to serve Central European retail networks.
Germany
Discounters and hypermarkets coordinate seasonal packaging transitions that consolidate supplier frameworks for dry goods and fresh produce. The EU Packaging and Packaging Waste Regulation mandates recyclability thresholds that compress design cycles for mono-material constructions. The Rhine-Ruhr industrial corridor hosts major converter operations supplying private-label specifications.
France
Hypermarket chains drive tray format adoption for chilled prepared meals where optical clarity influences purchase conversion. ECHA's updated SVHC candidate list captures common window lamination chemistries, forcing adhesive reformulation across the converter base. The Île-de-France region anchors premium spirits glass window demand for luxury positioning.
Italy
Processors favor mono-material PET pouch constructions to preempt extended producer responsibility penalties in snack and confectionery segments. Swiss and German regulatory overlap on SVHC compliance narrows qualified supplier pools for export-oriented brands. Emilia-Romagna hosts integrated flexible packaging operations serving pan-European distribution.
Sweden
Deposit-return infrastructure investments create preferential access to recycled feedstock pools for early adopters of paperboard-film combinations. The EU Green Deal accelerates transparent packaging procurement to secure shelf access in consolidated retail chains. Stockholm-based retail alliances coordinate sustainability scorecards that favor fiber recovery rates.
Netherlands
EPR alignment investments position converters for preferential feedstock access as recyclability validation becomes a gatekeeper feature. REACH substance restriction expansions compel validation of mono-material compatibility for window films and adhesives. The Randstad logistics hub enables rapid fulfillment of seasonal packaging transitions across Benelux retail networks.
Window Packaging Market Competitive Landscape
Concentration sits with integrated glass manufacturers and specialized paperboard converters serving distinct premium and mass-market tiers. Three structural archetypes define competitive positioning: furnace-technology leaders sustaining optical clarity specifications, mono-material specialists validating recyclability pathways, and flexible packaging converters optimizing unit economics for high-volume food applications. Strategic moves center on lightweighting innovation for reduced material intensity and backward integration into recycled feedstock supply.
Among furnace-technology leaders, Owens-Illinois and Vetropack exemplify premium glass window container production. Ardagh Group occupies a position within the lightweighting innovation archetype. These named entities anchor industry-level commentary on material intensity reduction and optical clarity standard advancement without specifying individual strategic actions or financial performance.
| Leading Market Players |
|---|
| Anadolu Cam |
| BA Glass BV |
| Owens-Illinois |
| Vetropack |
| Gerresheimer |
| Ardagh Group |
| Vidrala |
| Pochet SAS |
| Verallia SA |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day adhesive qualification lead times for REACH-compliant window lamination chemistries concentrate pricing power with pre-validated German and Austrian converter networks while compressing margin pools for second-tier suppliers scrambling to secure ECHA-compliant feedstock.
Pricing Analysis
The EU Packaging and Packaging Waste Regulation dictates the pricing tier structure across the window packaging value chain, enforcing a three-tier pricing structure across premium, standard, and economy levels differentiated by mono-material certification grade and optical clarity performance. Price differentiation hinges on EPR-aligned recyclability validation and furnace-technology optical specifications, with premium glass window containers commanding substantial markups over mass-market PET film constructions. Cost compression in standard-tier paperboard-film laminates is intensifying because REACH SVHC reformulation expenses are flowing through to converter quotations without full pass-through elasticity. German discounters exhibit the highest price sensitivity in volume procurement, while Swiss cosmetics houses demonstrate minimal elasticity for luxury-grade glass window specifications.
Supply Chain Analysis
Austrian and Czechia melting furnace capacity underwrites premium glass window container availability for spirits and cosmetics brands across Central Europe. Raw material flows draw from soda ash deposits in Germany, recycled cullet streams from Swedish deposit-return systems, and specialized optical-grade sand from selected Bavarian quarries. Single-source vulnerability concentrates in integrated glass forming operations where energy price spikes in Central European gas markets transmit directly to container cost structures. Distribution runs through Rhine-Ruhr logistics hubs for paperboard-film laminates and specialized temperature-controlled networks for chilled tray formats serving French hypermarket chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with the regulatory-driven bifurcation between legacy multi-layer window constructions and validated mono-material platforms, as EPR compliance deadlines carve out distinct supplier tiers that mid-scale converters can exploit through targeted certification investments.
For Market Incumbents: Shield furnace-technology leadership in premium glass segments through captive optical sand sourcing agreements and backward integration into Bavarian quarry operations. Prioritize lightweighting R&D to offset energy cost volatility in Austrian melting operations. Mono-material adhesive validation represents the critical defensive lever against emerging cellulose-film specialists capturing German organic product line specifications. For New Entrants and Emerging Players: E-commerce damage-resistant window construction specifications present the most penetrable white-space target, as incumbent corrugated suppliers under-serve direct-to-consumer fulfillment requirements for optical clarity retention under shipping stress. Target prepared meal tray formats for Austrian and Dutch retailers where seasonal packaging transitions create supplier qualification windows. Lead with rapid prototyping capabilities and short-run flexibility to bypass incumbent volume-commitment frameworks. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with under-optimized window packaging divisions lacking dedicated mono-material R&D infrastructure. Long-term viability favors specialists with validated EPR-aligned platforms and established retailer sustainability scorecard relationships. Watch Swedish and Netherlands deposit-return infrastructure expansion rates as the signal indicating recycled feedstock pool depth for paperboard-film combination scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Platform Validation | REACH-compliant adhesive R&D secures EPR alignment for German and French retail access. |
| Lightweighting Technology Investment | Reduced material intensity in glass formats defends margin pools against energy price spikes. |
| Deposit-Return Infrastructure Partnership | Swedish and Dutch feedstock agreements lock in preferential recycled cullet supply positions. |
| Smart Packaging Integration | Printed electronics behind transparent windows enables freshness indicators for prepared meal trays. |
| E-Commerce Fulfillment Specification Development | Damage-resistant constructions capture premium tier demand from direct-to-consumer brand expansions. |
Research Methodology
Cross-validation between converter production data and retail buyer procurement specifications anchors the qualitative findings in this study. Primary interviews with adhesive formulation chemists, paperboard lamination plant managers, grocery chain category buyers, and EPR scheme administrators combined with secondary validation from ECHA SVHC candidate list updates, EU Packaging and Packaging Waste Regulation impact assessments, and Swedish deposit-return system performance disclosures. Bottom-up capacity modeling and top-down demand aggregation triangulate volume estimates across the value chain.
Sensitivity analysis around regulatory enforcement timing and energy price volatility scenarios shapes the analytical framework. Segmentation dimensions span product format, material substrate, end-use application, and recyclability validation tier across the projection horizon. CAGRs derive from installed capacity expansion schedules, retailer sustainability scorecard adoption curves, and migration testing queue duration assumptions at EFSA and FDA. Forecast inputs incorporate Austrian furnace utilization rates and German discounter private-label conversion velocity.
Forecasts assume regulatory continuity in EU REACH and Packaging and Packaging Waste Regulation regimes; material policy shifts would require re-modeling of adhesive qualification timelines and recyclability threshold enforcement. Scenario risks include ECHA SVHC list expansion beyond currently anticipated chemistries and Central European energy infrastructure disruptions affecting glass melting operations. Practitioners should keep alternative scenarios live as EPR scheme rollout schedules and retailer consolidation patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Stick Packaging Market
Packaging Materials
Global Anti Counterfeit Automobile Packaging Market
Packaging Materials
Vacuum Packaging Market
Packaging Materials
Direct Thermal Printing Films Market
Packaging Materials
Cork Packaging Market
Packaging Materials
Book Wraps Market
Packaging Materials
Urn Liners Market
Packaging Materials
Packaging Lacquering Market
Packaging Materials
Lidding Foil Market
Packaging Materials
MDO Films Market
Packaging Materials
Hygiene Packaging Market
Packaging Materials
Collagen Sausage Casings Market
Packaging Materials
Bakeable Trays Market
Packaging Materials
VCI Shrink Films Market
Packaging Materials
Africa Packaging Market
Packaging Materials
Greaseproof Sheets Market