
 Pressure Ulcer Devices Market | 2026-2036
Pressure Ulcer Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Ulcer Devices Market Insights
The capital-intensity divergence between high-end dynamic surface manufacturers and commodity static pad producers is unwinding competitive boundaries across the pressure ulcer devices landscape. Stryker Corp. leverages integrated hospital bed systems to bundle pressure redistribution with telemetry infrastructure. Hill-Rom Services Inc. anchors its position through dedicated wound care surfaces and connected patient monitoring platforms. ArjoHuntleigh competes via specialized bariatric and microclimate management configurations for acute care environments.
Pressure ulcer devices comprise therapeutic surfaces, wound dressings, and patient positioning systems engineered to redistribute tissue load, manage moisture, and maintain perfusion across at-risk anatomical zones. Alternating air mattresses typically cycle pressure between 5-10 minute intervals to mimic physiological tissue loading patterns, while silicone foam dressings absorb exudate without adhering to granulating wound beds. Dynamic technology segments command premium positioning as hospitals prioritize predictive skin integrity protocols, yet static overlays retain volume dominance in nursing homes where capital budgets constrain electrified surface adoption. Dressings represent the most fragmented margin pool, with advanced hydrocolloid and antimicrobial formulations capturing disproportionate value per unit against basic gauze alternatives.
The FDA enforces 510(k) substantial equivalence for powered pressure-redistribution devices, while ISO 10993 biocompatibility standards govern prolonged skin-contact materials across export markets. Medicare's Hospital-Acquired Condition Reduction Program directly ties reimbursement penalties to pressure injury incidence, compelling capital investment in preventive surface technologies. Stakeholders must monitor evolving CMS quality metrics and EU MDR technical documentation requirements as regulatory stringency reshapes product development pipelines and market access timelines.
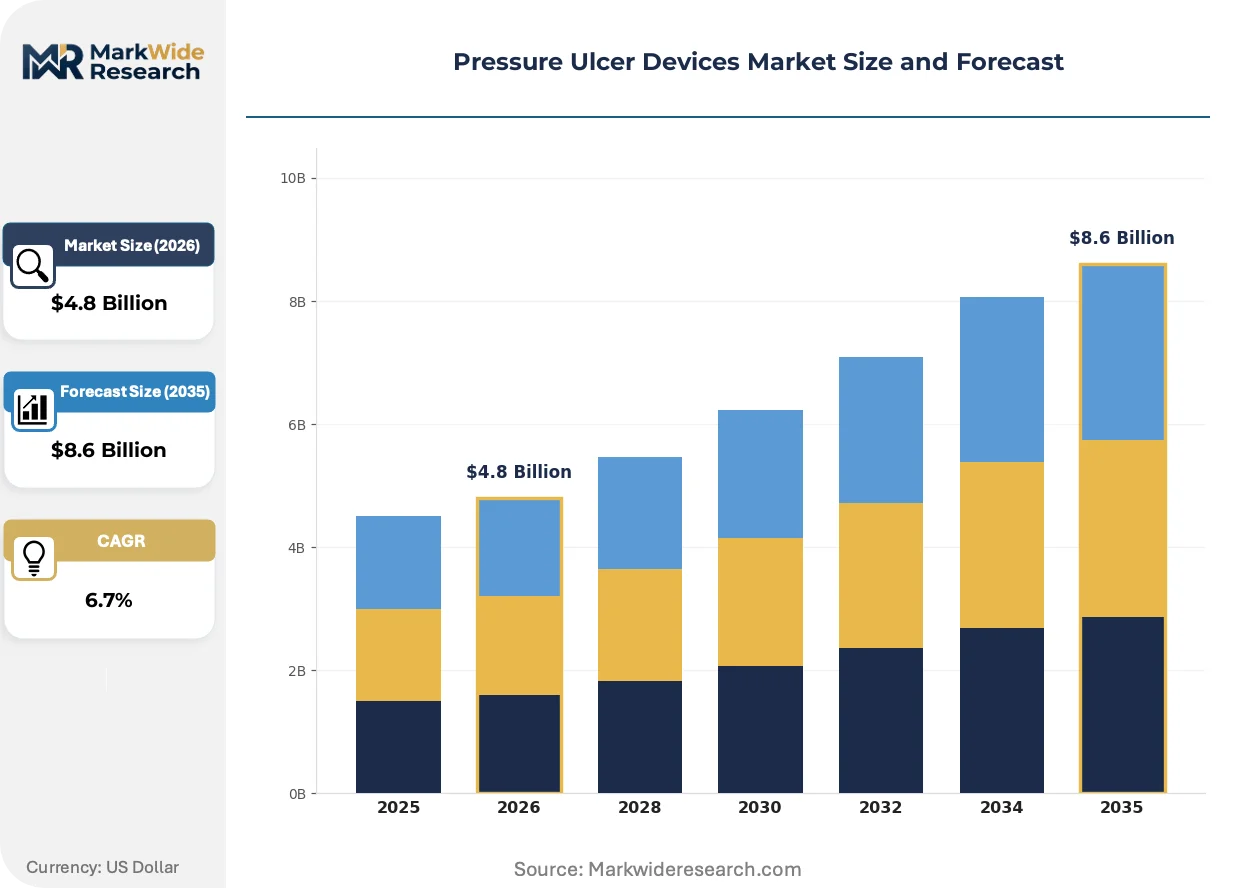
Market Dynamics
Powered pressure-redistribution surfaces are compressing procurement cycles as Medicare reimbursement penalties for hospital-acquired pressure injuries force capital allocation toward predictive prevention technologies over reactive wound management.
Growth Catalysts
- CMS Hospital-Acquired Condition Reduction Program:Medicare reimbursement penalties tied to pressure injury incidence compel US hospitals to prioritize preventive surface investments over episodic treatment costs.
- Silicone foam dressing formulations:Advanced exudate management without wound bed adherence accelerates healing trajectories and reduces dressing change frequency in acute care settings.
- Long-term care facility expansion:Aging demographics across Japan, Germany, and the United States intensify bed-bound patient volumes requiring specialized bariatric and microclimate management configurations.
Market Restraints
- Capital intensity of dynamic surface electrification:Alternating air mattress systems require substantial upfront investment and ongoing maintenance contracts that constrain adoption in nursing home environments with fixed per-bed reimbursement rates.
- Raw material concentration in medical-grade silicone:Supply chain dependencies on specialized polymer producers create input cost volatility for advanced hydrocolloid and antimicrobial dressing manufacturers.
- Technical limitation in moisture vapor transmission:Current multi-layer dressing architectures struggle to balance exudate absorption with adequate breathability across heavily draining wound presentations.
Strategic Opportunities
- Underpenetrated home care segment:Reimbursement expansion for remote patient monitoring creates entry points for connected pressure-redistribution surfaces in post-acute discharge pathways across the United States.
- EU MDR technical documentation requirements:Stricter biocompatibility validation standards favor established manufacturers with robust quality management systems, compressing competitive entry for commodity producers.
- Convergence of telemetry infrastructure with therapeutic surfaces:Integrated patient monitoring platforms that correlate position data with skin integrity risk scores enable predictive intervention protocols in intensive care units.
Industry Challenges
- Specialized wound care clinician shortage:Certified enterostomal therapy nurses remain concentrated in academic medical centers, limiting protocol adherence in community hospital and skilled nursing facility settings.
- ISO 10993 biocompatibility testing timelines:Extended cytotoxicity and sensitization study durations delay product launch schedules for novel skin-contact materials seeking export market access.
- Legacy electronic health record integration:Pressure injury risk assessment algorithms require custom API development to feed documentation into existing patient data architectures without workflow disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Ulcer Devices Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mattresses, Cushions, Overlays, Dressings End User: Hospitals, Nursing Homes, Home Care, Rehabilitation Centers Technology: Static, Dynamic, Alternating, Monitoring Devices Application: Wound Management, Patient Care, Post-operative Recovery, Long-term Care |
| Companies Covered | Stryker Corp., Smith & Nephew Plc., Hill-Rom Services Inc., Medtronic, Paramount Bed Holdings Co. Ltd., Invacare Corporation, ArjoHuntleigh, Talley Group Limited, ConvaTec Group Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Ulcer Devices Market Trends and Innovations
Sensor-embedded therapeutic surfaces are redefining competitive boundaries by converting passive pressure redistribution into active physiological monitoring, while regulatory stringency and procurement model evolution simultaneously reshape vendor-customer relationships.
Microclimate management technology is supplanting conventional moisture-wicking approaches in high-acuity settings. These systems actively regulate temperature and humidity at the skin-surface interface rather than merely absorbing exudate. Intensive care units and burn centers in the United States and Germany are adopting these configurations at accelerated procurement cycles. The structural consequence is compression of commodity foam overlay margins as purchasers prioritize physiological parameter control over basic pressure redistribution.
EU MDR recertification requirements for legacy pressure-redistribution devices are forcing substantial technical documentation investments across the European market. Manufacturers must now demonstrate clinical equivalence through expanded biocompatibility and performance testing for products previously cleared under the Medical Device Directive. Powered surface categories face the steepest compliance burden, with German and French notified bodies imposing extended review timelines that delay market access for updated product lines.
Hospital purchasing consortia are consolidating procurement authority for pressure ulcer prevention technologies into centralized value analysis committees. Individual nursing units in US health systems increasingly lose autonomy to select surface technologies, with standardized enterprise contracts replacing fragmented departmental acquisitions. This concentration is most visible in multi-hospital integrated delivery networks across Texas, California, and Florida, where capital equipment committees now bundle bed frame, surface, and monitoring infrastructure into single-vendor arrangements.
Pressure Ulcer Devices Market Segmentation
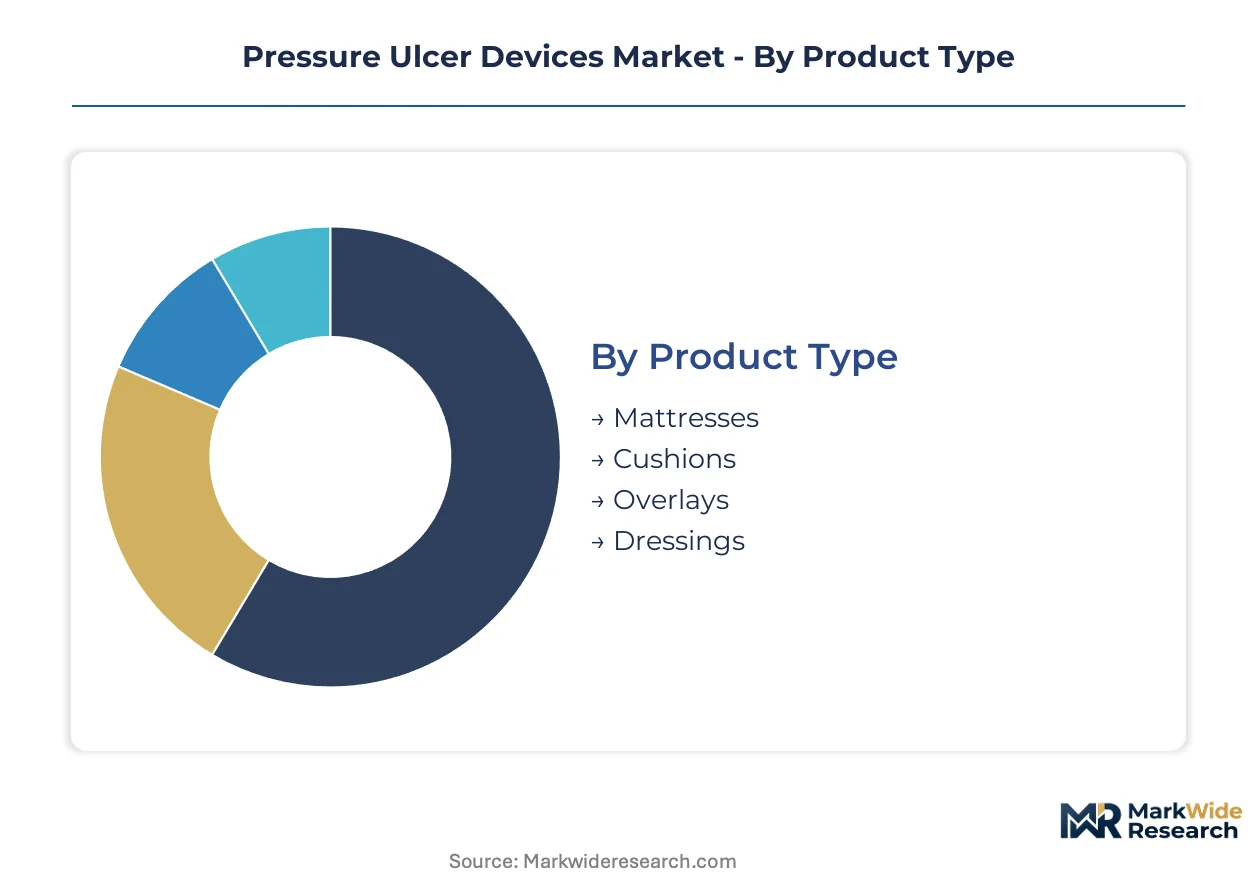
Pressure ulcer device segmentation reveals divergent regulatory pathways and reimbursement incentives across product categories. FDA 510(k) clearance requirements for powered surfaces create tiered compliance burdens that reshape competitive positioning within each segment.
Product Type:
FDA classifies powered pressure-redistribution mattresses as Class II medical devices requiring substantial equivalence demonstrations, while static overlays fall under simpler regulatory pathways.
- Mattresses:Integrated bed systems with embedded air cells or foam cores redistribute tissue load across sacral and heel zones. US hospitals prioritize these configurations under Medicare's Hospital-Acquired Condition Reduction Program penalties. Alternating air models cycle pressure at 5-10 minute intervals to mimic physiological tissue loading patterns.
- Dressings:Advanced hydrocolloid and silicone foam formulations manage exudate without adhering to granulating wound beds. These products capture disproportionate value per unit in acute care settings where dressing change frequency directly impacts nursing labor costs and infection risk protocols.
- Cushions:Seat and heel offloading devices using gel, air, or viscoelastic foam compositions target seated patients and wheelchair users in rehabilitation environments.
- Overlays:Portable pressure-redistribution surfaces placed atop standard mattresses serve capital-constrained nursing homes where per-bed reimbursement rates limit electrified system adoption.
Mattresses handle the majority of throughput; dressings are expanding most quickly on share.
End User:
Reimbursement model differentiation across care settings drives divergent procurement priorities and technology adoption timelines.
- Hospitals:Acute care facilities in the United States deploy integrated monitoring surfaces to avoid Medicare reimbursement penalties tied to pressure injury incidence. These institutions command premium dynamic technology volumes through centralized capital equipment committees.
- Nursing Homes:Long-term care facilities represent the fastest-expanding buyer segment as aging demographics intensify bed-bound patient volumes across Japan, Germany, and the United States. Fixed per-bed reimbursement rates constrain adoption of electrified surfaces in favor of static overlays and positioning cushions.
- Home Care:Post-acute discharge pathways create entry points for connected pressure-redistribution surfaces as remote patient monitoring reimbursement expands across US Medicare Advantage plans.
- Rehabilitation Centers:Transitional care facilities balance mobility protocols with pressure injury prevention, prioritizing seated positioning systems and bariatric configurations.
Nursing homes are gaining share fastest; hospitals retain the dominant procurement volume position.
Technology:
Electrification intensity separates premium positioning from commodity competition across regulatory and reimbursement landscapes.
- Dynamic:Powered surfaces with active pressure modulation command premium hospital procurement as predictive skin integrity protocols displace reactive wound management. These systems require FDA 510(k) clearance and ongoing maintenance contracts that limit nursing home penetration.
- Alternating:Cyclic pressure redistribution technology cycles between inflated and deflated air cells to mimic physiological tissue perfusion patterns. German and French intensive care units are adopting these configurations at accelerated rates.
- Static:Non-powered foam and gel surfaces dominate nursing home volumes where capital budgets and per-bed reimbursement constraints limit electrified adoption. These products face compressed margins as purchasers prioritize physiological parameter control.
- Monitoring Devices:Sensor-embedded surfaces that correlate position data with skin integrity risk scores enable predictive intervention protocols in US intensive care units.
Dynamic technology commands the steepest price tier; monitoring devices show the steepest expansion trajectory.
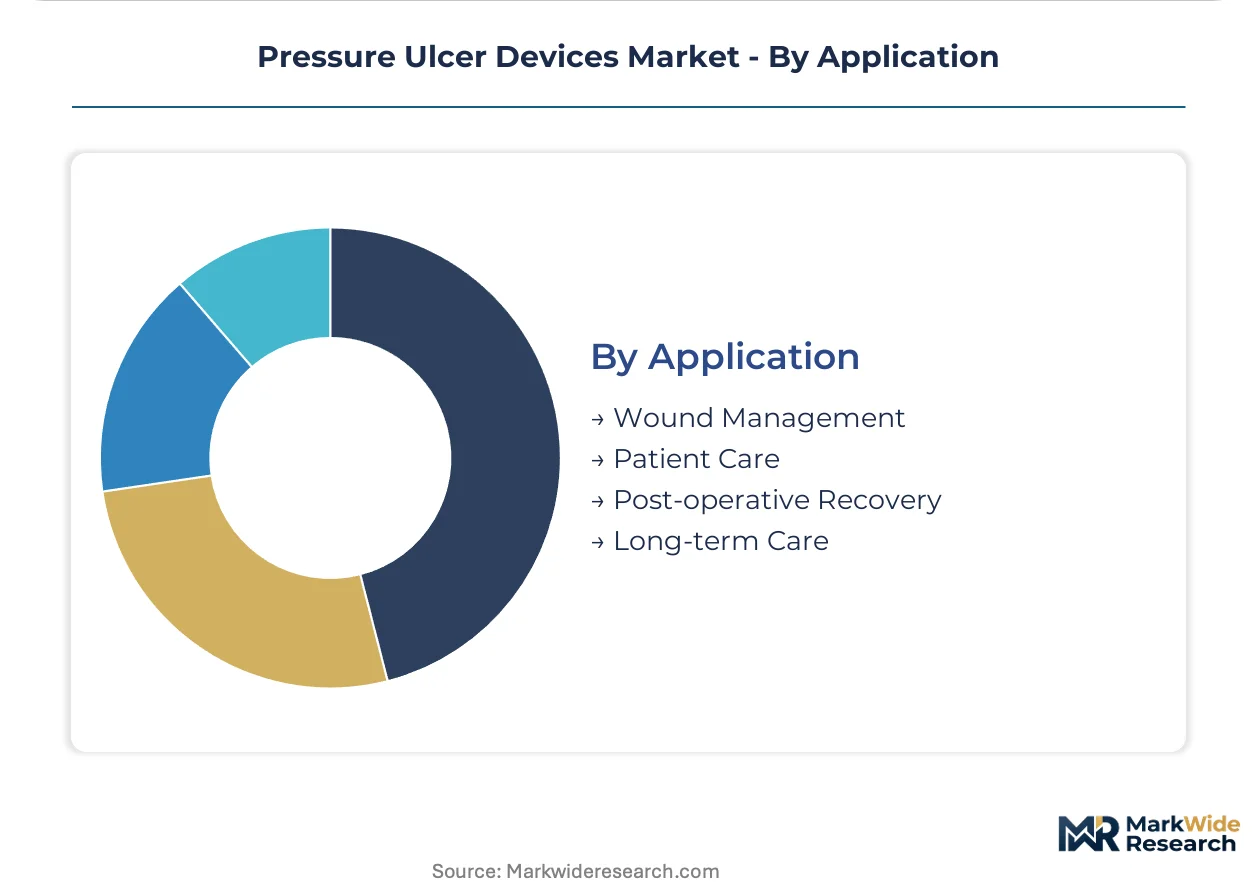
Application:
Clinical setting and patient acuity determine functional requirements and procurement authority concentration.
- Long-term Care:Extended bed-bound populations across aging demographics in Japan, Germany, and the United States require specialized bariatric and microclimate management configurations. These applications prioritize durability and ease of cleaning over acute-care monitoring integration.
- Wound Management:Active pressure injury treatment protocols in US hospitals combine advanced dressings with offloading surfaces to accelerate healing trajectories and reduce readmission penalties.
- Patient Care:General prevention protocols across community hospitals and skilled nursing facilities emphasize standardized surface deployment without telemetry integration.
- Post-operative Recovery:Surgical units prioritize rapid patient turnover with surfaces that accommodate varying mobility levels and anesthesia recovery protocols.
Long-term care absorbs the greatest device volume; wound management commands the highest technology premium per bed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. US hospitals prioritize electrified predictive surfaces under penalty-driven reimbursement models, while Japanese and German long-term care facilities emphasize durability and bariatric specialization over capital-intensive monitoring integration.
United States
Medicare's Hospital-Acquired Condition Reduction Program penalizes facilities for pressure injury incidence, compelling capital allocation toward powered redistribution surfaces. The FDA maintains 510(k) clearance requirements for dynamic mattress systems. Texas and Florida health systems lead enterprise-scale procurement through centralized value analysis committees.
Germany
Intensive care units in Bavaria and North Rhine-Westphalia accelerate adoption of alternating-pressure technology with microclimate management. The EU MDR imposes extended biocompatibility documentation timelines on powered surface recertification. Stuttgart-based medical device clusters concentrate notified body expertise for technical file preparation.
Japan
Aging demographics intensify bed-bound patient volumes in long-term care facilities across Kanto and Kansai regions. METI guidelines emphasize preventive care infrastructure investment in municipal care networks. Osaka manufacturers specialize in compact bariatric configurations optimized for space-constrained nursing homes.
United Kingdom
NHS procurement frameworks standardize pressure ulcer prevention protocols across acute and community care settings. NICE clinical guidelines mandate risk assessment documentation that drives surface technology specification. London and Southeast England health systems pilot integrated telemetry-surface platforms in ICU environments.
France
ANSM oversight of Class II medical devices shapes market access timelines for powered redistribution systems. Regional hospital groups in Île-de-France consolidate purchasing authority through GHT structures. Lyon-based rehabilitation centers prioritize seated positioning systems for transitional care protocols.
Pressure Ulcer Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital intensity and regulatory compliance capability determining tier boundaries. The upper tier commands bundled hospital contracts combining bed frames, surfaces, and monitoring infrastructure. Specialist competitors differentiate through bariatric configurations, microclimate management, or dedicated wound care platforms. Dominant competitive moves include strategic partnerships with health system purchasing consortia and portfolio diversification into connected patient monitoring.
Among US-based integrated manufacturers, Stryker Corp. and Hill-Rom Services Inc. occupy positions exemplifying the bundled-system archetype, leveraging hospital bed platforms to anchor comprehensive pressure redistribution offerings. ArjoHuntleigh represents the specialized European competitor archetype, with Swedish-origin positioning in bariatric and acute care surface configurations. These three entities illustrate the structural divide between capital-intensive integrated leaders and focused specialists.
| Leading Market Players |
|---|
| Stryker Corp. |
| Smith & Nephew Plc. |
| Hill-Rom Services Inc. |
| Medtronic |
| Paramount Bed Holdings Co. Ltd. |
| Invacare Corporation |
| ArjoHuntleigh |
| Talley Group Limited |
| ConvaTec Group Plc |
| Others |
Pricing and Supply Chain Analysis
Silicone foam substitution for hydrocolloid base layers in advanced dressings simultaneously redraws raw material sourcing maps toward German and Japanese polymer specialists and compresses margin pools for commodity gauze producers unable to absorb formulation cost premiums. This input transition concentrates pricing power with medical-grade silicone suppliers while forcing tiered procurement strategies across acute care and long-term care buyers.
Pricing Analysis
After-sales service contracts and preventive maintenance subscriptions generate lifetime value multiples exceeding initial hardware margins for powered surface manufacturers. Three-tier pricing structure across premium dynamic systems, standard alternating mattresses, and economy static overlays reflects FDA certification tiers and telemetry integration depth. Pricing pressure stems from Medicare per-diem constraints in nursing homes where electrified surface adoption remains capital-prohibitive. Long-term care facilities exhibit acute price sensitivity compared to hospital value analysis committees prioritizing penalty avoidance over acquisition cost.
Supply Chain Analysis
Inventory buffers for medical-grade silicone and specialized air-cell polymers stretch lead times when notified body inspections disrupt European component flows. Manufacturing concentrates in the United States, Germany, and Japan for powered surfaces, while dressings draw from Ireland, China, and Mexico for hydrocolloid substrates and antimicrobial coatings. Single-source vulnerability pervades FDA-registered foam suppliers qualified for 510(k) submissions. Distribution runs through group purchasing organizations and health system consortia rather than direct nursing unit procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue layers including predictive maintenance subscriptions and remote monitoring software expand faster than hardware sales as hospitals prioritize uptime guarantees over capital acquisition. Recurring revenue from telemetry platform licenses now commands valuation premiums exceeding traditional equipment financing multiples.
For Market Incumbents: Fortify position through backward integration into medical-grade silicone compounding and captive air-cell manufacturing to neutralize raw material cost volatility. Deepen hospital system partnerships through bundled telemetry-surface contracts that raise switching costs for competitive displacement. Prioritize ISO 10993 biocompatibility certification investments ahead of EU MDR recertification deadlines to compress entry timelines for commodity challengers.
For New Entrants and Emerging Players: Anchor in the underpenetrated home care segment where Medicare Advantage reimbursement expansion creates first-mover advantages for connected pressure-redistribution surfaces. Target bariatric specialty configurations for long-term care facilities in Japan and Germany where aging demographics intensify demand but incumbent portfolios lack dedicated sizing. Pursue white-label manufacturing partnerships with Osaka-based compact equipment specialists to bypass capital-intensive FDA establishment registration.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed wound care dressing platforms seeking telemetry integration to defend against surface manufacturer forward integration. Five-to-ten year viability hinges on recurring revenue transition rather than transactional hardware sales. Monitor FDA 510(k) clearance velocity for sensor-embedded surfaces as inflection indicator for predictive prevention technology maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Bundled contracts with Texas and Florida IDNs consolidate procurement authority and raise competitive barriers. |
| CE Marking Pathway | EU MDR technical documentation investments favor established manufacturers with robust quality management systems. |
| Software Companion Development | Sensor-embedded surfaces with predictive risk scoring algorithms command premium positioning in ICU environments. |
| Reimbursement Strategy | Medicare Advantage remote monitoring codes create viable economics for post-acute connected surface deployment. |
| Backward Integration | In-house silicone compounding neutralizes supply chain volatility for advanced hydrocolloid dressing formulations. |
Research Methodology
Desk research of FDA 510(k) clearances, CMS Medicare reimbursement databases, and EU MDR technical documentation preceded structured interviews with hospital purchasing committee directors, long-term care facility administrators, biomedical engineers, and GPO contracts managers. Secondary validation drew from hospital procurement databases, medical device trade customs records, and SEC filings of publicly traded manufacturers. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume assumptions across the analysis window.
Variance decomposition across product type, end user facility, technology tier, and regional regulatory cluster shaped the analytical framework. Modeled segmentation captured dynamic versus static technology splits, acute care versus long-term care demand patterns, and powered versus non-powered surface categories. CAGRs derived from regression analysis of historical Medicare spending patterns and demographic bed-bound population projections. Forecast inputs included FDA clearance velocity, EU notified body inspection backlogs, and CMS penalty threshold adjustments.
Decision-makers should treat outputs as directional under assumptions of stable Medicare reimbursement incentives and silicone supply continuity; material deviation in regulatory stringency or raw material concentration would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
United States Minimally Invasive Surgery Device Market
Medical Devices
Memory Implants Market
Medical Devices
Syringe Scale Magnifiers Market
Medical Devices
South Korea Minimally Invasive Surgery Devices Market
Medical Devices
Global Hydrogel Based Drug Delivery System Market
Medical Devices
North America Biopsy Devices Market
Medical Devices
Photorejuvenation Devices Market
Medical Devices
Electronic Nasal Spray Devices Market
Medical Devices
Canada Contraceptive Devices Market
Medical Devices
Insulin Delivery Devices (Idd) Market
Medical Devices
United States Stair Lift Market
Medical Devices
Manometry System Market
Medical Devices
Cervical Retractors Market
Medical Devices
Hemoconcentrators Market
Medical Devices
Veterinary Procedure Lights Market
Medical Devices
Europe Spinal Surgery Devices Market