
 Pressure Ulcer Prevention Market | 2026-2036
Pressure Ulcer Prevention Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Ulcer Prevention Market Intelligence
A shift from single-source contracts to multi-vendor procurement models by large hospital networks is repositioning competitive dynamics. This trend allows facilities to access specialized products, such as advanced wound dressings from Smith & Nephew plc. Stryker leverages its extensive distribution network and broad portfolio of support surfaces to maintain a strong market presence. Meanwhile, specialists like Arjo compete on the basis of integrated patient handling and mobility solutions.
Pressure ulcer prevention involves products and protocols designed to mitigate tissue injury from prolonged pressure, shear, or friction. These solutions often incorporate materials with specific cell structures, such as open-cell polyurethane foam, to optimize pressure redistribution and microclimate management. Foam-based mattresses command a significant share due to their cost-effectiveness, while air-filled systems represent a higher-cost, higher-efficacy segment for critical care. The hospital application segment remains the largest, but home care is showing rapid expansion.
Product approval and market access are governed by bodies like the US FDA, which classifies devices, and Europe's CE marking under the Medical Device Regulation (MDR). These regulations mandate stringent clinical data for efficacy claims and post-market surveillance, influencing product development timelines and costs. Future differentiation will hinge on integrating smart monitoring capabilities with support surfaces to provide real-time patient data to clinicians.
Market Dynamics
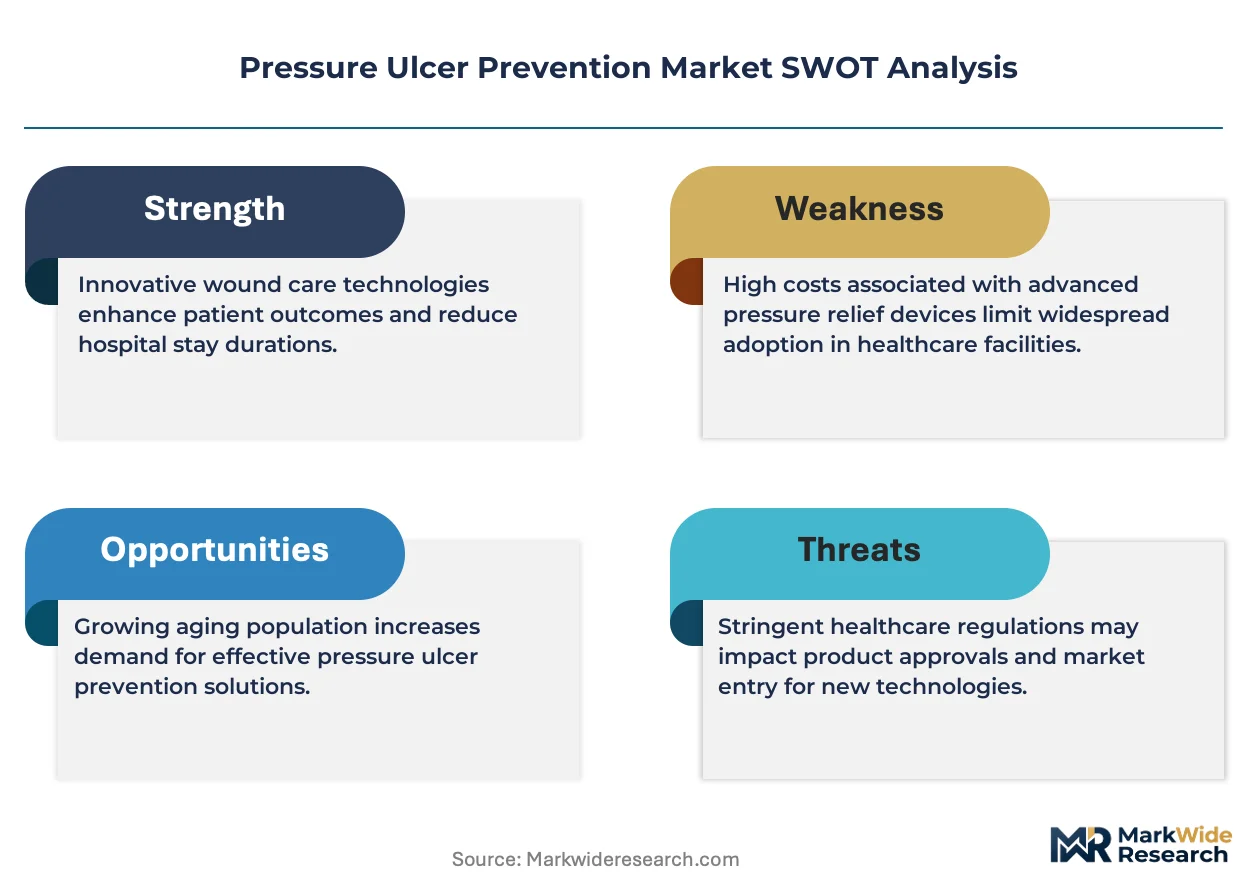
The convergence of demographic shifts and heightened regulatory oversight is the central force shaping the pressure ulcer prevention market. An aging global population, particularly in developed nations like Japan and Germany, expands the at-risk patient base, while stricter rules like the EU's Medical Device Regulation demand higher standards of clinical proof for product efficacy.
Growth Catalysts
- Policy-Driven Care Standards:Government and payer initiatives, such as value-based care models in the United States, incentivize healthcare facilities to invest in effective prevention protocols to reduce the incidence of costly hospital-acquired pressure injuries.
- Expanding Geriatric Population:The rising number of elderly individuals in countries with advanced healthcare systems, including Germany and Japan, directly increases the addressable patient population requiring long-term and critical care, thereby sustaining demand for prevention products.
- Material and Design Advancement:The adoption of materials with specific properties, such as open-cell polyurethane foam for microclimate management and pressure redistribution, enhances product efficacy and drives replacement cycles in hospital and long-term care settings.
Market Restraints
- High Acquisition Costs:The significant upfront investment required for advanced systems, such as alternating pressure air mattresses, creates a substantial barrier for budget-constrained healthcare facilities, particularly in emerging economies.
- Reimbursement Limitations:Inconsistent or insufficient reimbursement codes for higher-end preventative surfaces in certain healthcare systems can limit their adoption, favoring lower-cost, less effective standard foam mattresses.
- Stringent Regulatory Hurdles:The extensive clinical data and post-market surveillance mandated by regulations like the EU's MDR increase development costs and lengthen time-to-market, restraining the pace of new product introductions.
Strategic Opportunities
- Smart Surface Integration:Incorporating sensor technology and data analytics into support surfaces to provide real-time monitoring of patient position and pressure points offers a significant avenue for product differentiation and improved clinical outcomes.
- Home Care Segment Expansion:The growing preference for aging-in-place and post-acute care at home creates an underpenetrated market for simplified, cost-effective pressure prevention solutions tailored for non-clinical users and caregivers.
- Specialized Application Development:Adapting pressure redistribution technologies for niche segments, such as bariatric patients, pediatric care, or operating room tables, opens new revenue streams beyond traditional hospital bed applications.
Industry Challenges
- Compliance and Reporting Burden:Adhering to continuous post-market surveillance and data reporting obligations under frameworks from the US FDA and European authorities requires significant, ongoing operational resources from manufacturers.
- Interoperability with Health IT:Integrating new smart support surfaces with diverse and often proprietary electronic health record (EHR) systems within hospitals presents a significant technical and logistical challenge for both vendors and healthcare providers.
- Clinical Staff Training:Ensuring that nursing and caregiver staff are adequately trained on the proper use, programming, and maintenance of sophisticated air-filled and integrated systems is critical for achieving therapeutic benefits and avoiding misuse.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Ulcer Prevention Market |
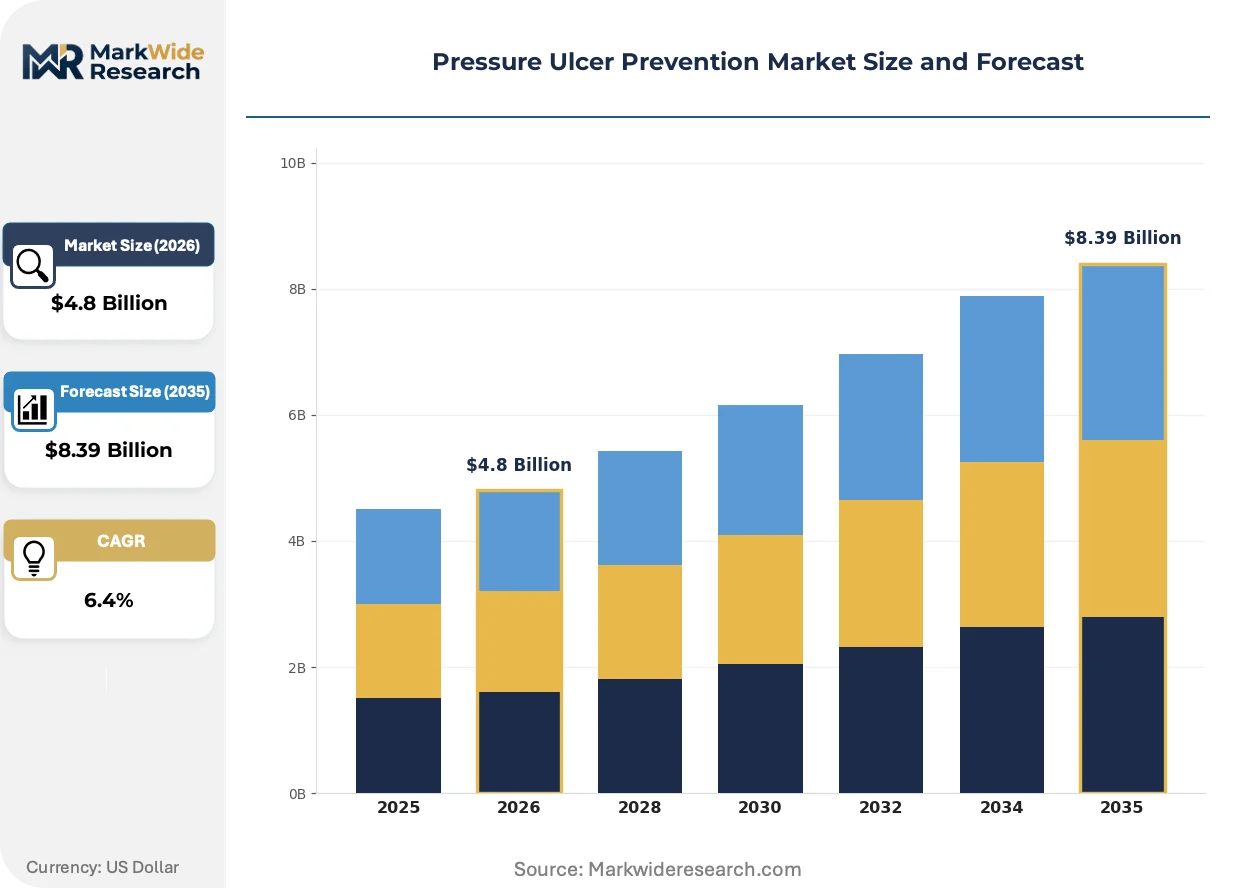
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mattresses, Cushions, Dressings, Devices Application: Hospitals, Long-term Care, Home Care, Rehabilitation Technology: Air-filled, Gel-infused, Foam-based, Electrical End User: Nursing Homes, Assisted Living, Clinics, Individuals |
| Companies Covered | Stryker, Baxter, Arjo, Mölnlycke Health Care AB, Invacare Corporation, Medline Industries, LP, Smith & Nephew plc, 3M, Integra LifeSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Ulcer Prevention Market Strategic Shifts & Innovations
The evolution from passive, material-based prevention to active, data-informed patient management is fundamentally altering product design and clinical workflows. This transition is driven by the integration of digital technologies into traditional support surfaces, creating intelligent care platforms.
Support surfaces with integrated micro-sensors for pressure mapping and moisture detection represent a key technological shift. Critical care units and specialized long-term care facilities are adopting these systems to gain real-time insights into patient status. This active monitoring technology is overtaking conventional, time-based patient turning schedules, allowing for more personalized and effective prevention strategies based on direct feedback.
Regulatory frameworks are becoming more stringent, directly influencing product development and market access. The European Union's Medical Device Regulation (MDR) now requires manufacturers to provide more robust clinical evidence of efficacy and to conduct rigorous post-market surveillance. This affects producers of all device classes, especially for support surfaces making therapeutic claims, forcing greater investment in clinical trials to maintain CE marking.
A notable behavioral shift is occurring as large hospital networks and group purchasing organizations move from single-vendor to multi-vendor procurement models. This change allows facilities to source best-in-class products for specific needs, such as advanced wound dressings from one supplier and specialized support surfaces from another. The trend is most prominent in the United States and parts of Europe, where it fragments large contracts and intensifies competition on a product-by-product basis.
Pressure Ulcer Prevention Market Segmentation
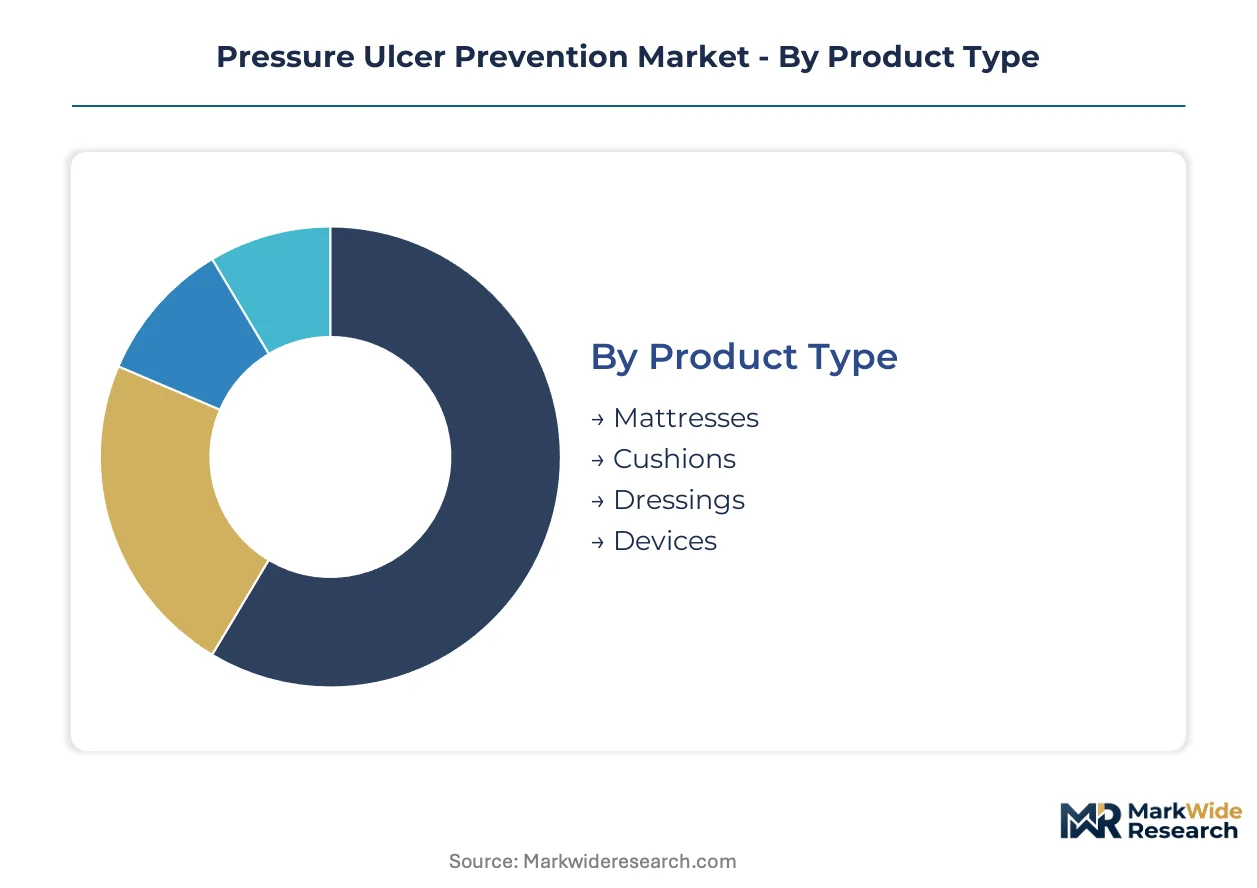
Pressure ulcer prevention requires tailored solutions for diverse patient needs and care settings. Understanding market segments reveals how product features, application environments, and underlying technologies drive adoption. This granular view helps manufacturers align offerings with specific clinical requirements and economic realities.
Product Type:
The product type category highlights the spectrum from highly standardized consumables to complex, customizable support systems.
- Mattresses:These primary support surfaces are engineered for pressure redistribution across a patient's entire body. Demand concentrates heavily in hospital settings and long-term care facilities, driven by the need for continuous, passive prevention for immobile patients.
- Dressings:Advanced wound dressings feature specialized materials designed to protect skin and manage microclimate at specific pressure points. Their demand is increasing in both acute care and home care for targeted prevention and early-stage ulcer management, supported by evolving clinical protocols.
- Cushions:These smaller, localized support items are used for seating or specific body areas to relieve pressure effectively.
- Devices:This segment includes various mechanical or electronic aids, such as turning systems or specialized boots, for targeted pressure relief.
Leading the category by volume: Mattresses. Growing fastest: Dressings.
Application:
The application segment differentiates solutions based on the intensity of patient care and the operational scale of the facility.
- Hospitals:Acute care settings demand high-performance pressure prevention products for critically ill or post-operative patients. Product procurement in hospitals focuses on efficacy and integration with existing patient management systems.
- Home Care:This rapidly expanding segment addresses patient needs in non-clinical environments, emphasizing ease of use and affordability for caregivers. Demand for home care solutions is fueled by aging populations preferring to age in place and increasing post-acute care transfers.
- Long-term Care:Facilities like nursing homes require durable and cost-effective solutions for residents with chronic conditions and extended stays.
- Rehabilitation:This segment focuses on prevention for patients undergoing recovery, often needing dynamic support surfaces to aid mobility and function.
The growing preference for aging-in-place drives expansion in Home Care, while Hospitals maintain the largest share due to patient acuity.
Technology:
Technology types reflect varying approaches to pressure redistribution and microclimate management, often correlating with cost and clinical efficacy.
- Foam-based:These mattresses and cushions utilize open-cell polyurethane foam for static pressure redistribution and microclimate control. Their cost-effectiveness makes them prevalent in general wards and long-term care facilities, providing foundational prevention.
- Air-filled:Dynamic air systems, including alternating pressure and low-air-loss mattresses, actively redistribute pressure and manage skin moisture. These high-efficacy solutions are crucial in critical care units and for high-risk patients, despite higher acquisition costs.
- Gel-infused:Products incorporating gel layers offer enhanced pressure relief and cooling properties, providing a balance of comfort and prevention.
- Electrical:This technology category includes powered systems that manage air pressure or facilitate patient turning, offering advanced and automated prevention.
Foam-based solutions dominate for their balance of cost and performance, while innovation centers on advanced Air-filled systems for complex patient needs.
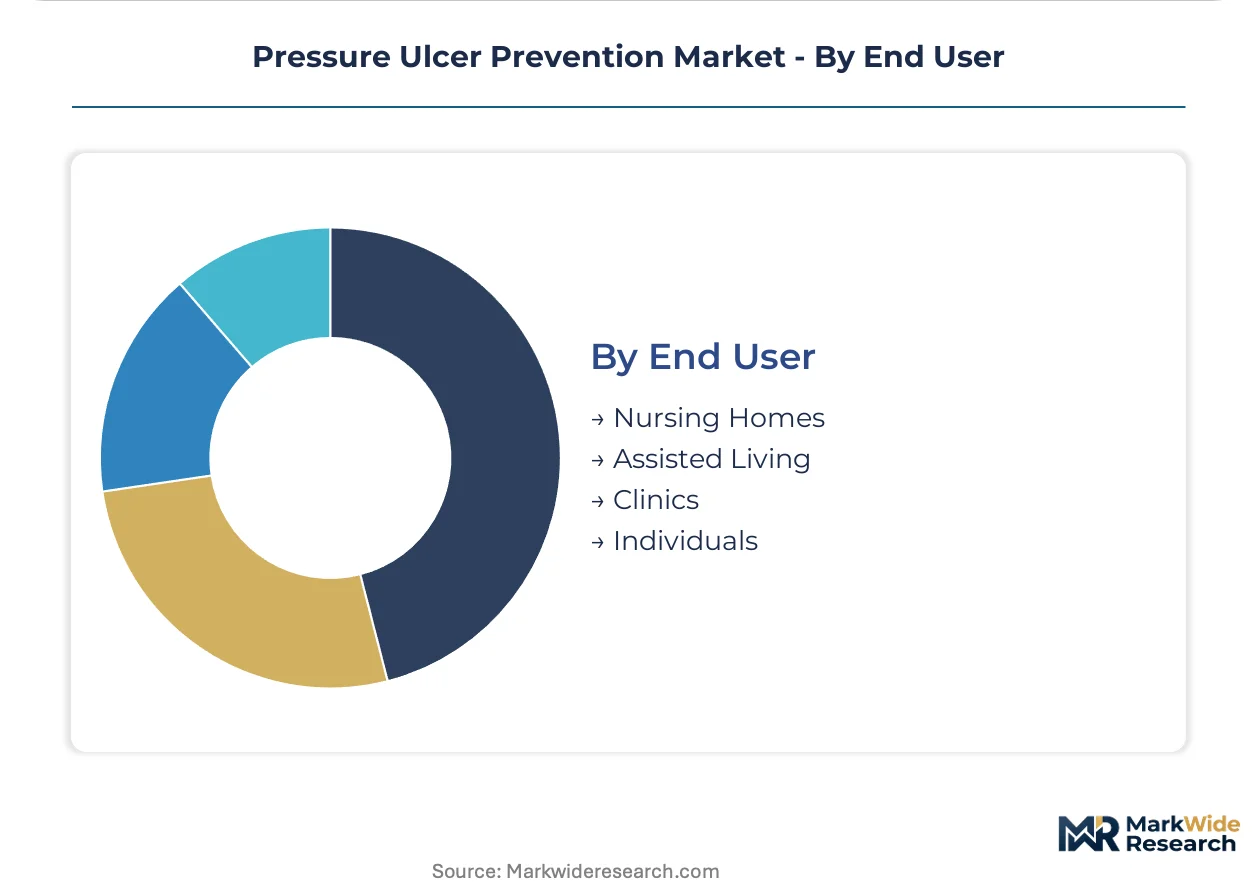
End User:
End-user segments highlight differences in patient autonomy, caregiver involvement, and the institutional or personal nature of care.
- Nursing Homes:These facilities provide residential care for elderly or chronically ill individuals, requiring durable and easy-to-maintain pressure prevention products. The large patient population in nursing homes drives consistent demand for bulk procurement.
- Individuals:This segment comprises patients and their caregivers managing pressure ulcer prevention in their private residences. Product selection for individuals prioritizes user-friendliness, portability, and solutions suitable for non-professional care.
- Assisted Living:Residents in assisted living facilities often require moderate levels of support, leading to demand for comfortable and unobtrusive prevention solutions.
- Clinics:Outpatient clinics use specialized prevention products for short-term patient visits or specific procedures, focusing on hygiene and rapid application.
Evolving care models are increasing the direct procurement by Individuals, while Nursing Homes remain a foundational market for continuous care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration in the pressure ulcer prevention market is evident across countries with robust healthcare infrastructure and significant aging populations. These nations prioritize advanced patient care solutions to manage chronic conditions effectively. Regulatory frameworks in these regions also drive investments in high-efficacy prevention protocols.
Germany
Germany's substantial geriatric population drives consistent demand for pressure ulcer prevention products within its extensive network of hospitals and long-term care facilities. The EU's Medical Device Regulation (MDR) mandates stringent clinical data for devices, influencing product development and market access for manufacturers. Major medical technology clusters around Munich and North Rhine-Westphalia foster innovation in support surface technologies.
Japan
Japan faces an exceptionally high proportion of elderly individuals, creating a critical need for advanced pressure prevention solutions in both acute and home care settings. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees product approvals, emphasizing safety and clinical efficacy for medical devices. Tokyo and Osaka serve as key centers for medical device research and manufacturing, integrating new sensor technologies.
United States
United States healthcare facilities are incentivized by value-based care models to invest in effective pressure injury prevention, reducing costly hospital-acquired conditions. The US FDA classifies medical devices, requiring rigorous pre-market and post-market surveillance for therapeutic claims. Major medical technology hubs in Boston and California are at the forefront of developing smart support surfaces with real-time monitoring capabilities.
Canada
Canada's aging population and universal healthcare system sustain a steady demand for pressure ulcer prevention solutions, particularly in long-term care and home care environments. Health Canada regulates medical devices, ensuring products meet national safety and efficacy standards before market entry. Healthcare innovation clusters in Toronto and Montreal actively explore integrated patient management systems.
France
French healthcare experiences consistent demand for pressure ulcer prevention products due to its aging demographic and established long-term care sector. The EU's Medical Device Regulation (MDR) directly impacts product availability and compliance requirements for all medical devices sold within France. Paris and Lyon represent significant centers for medical device companies and research institutions focused on patient comfort and safety.
Pressure Ulcer Prevention Market Key Industry Players
Strategic differentiation through technology integration dominates the current landscape, as companies vie for market share in advanced pressure ulcer prevention. The market exhibits a tiered structure, with large diversified medical technology corporations competing alongside specialized solution providers. Key strategic archetypes include broad portfolio players, advanced wound care specialists, and innovators focusing on smart surface technologies. Competitive moves primarily involve portfolio diversification, strategic partnerships for technology co-development, and geographic expansion into underserved markets.
Within the diversified medical technology segment, Stryker and Smith & Nephew plc represent global players leveraging extensive distribution networks and comprehensive product portfolios. Stryker occupies a strong position with its broad range of support surfaces and patient handling solutions. Smith & Nephew plc, a global medical technology company, exemplifies leadership in advanced wound dressings and related prevention products. Arjo, in contrast, anchors the specialized segment, focusing on integrated patient handling and mobility solutions that incorporate pressure injury prevention.
| Leading Market Players |
|---|
| Stryker |
| Baxter |
| Arjo |
| Mölnlycke Health Care AB |
| Invacare Corporation |
| Medline Industries, LP |
| Smith & Nephew plc |
| 3M |
| Integra LifeSciences |
| Others |
Cost & Logistics Intelligence
A clear performance divergence between foam-based and advanced air-filled systems significantly shapes both pricing and supply chain configurations within the pressure ulcer prevention market. This stratification influences procurement strategies, material sourcing, and distribution networks, creating distinct pathways for different product tiers.
Pricing Analysis
Volume-driven sales of basic foam mattresses contrast with higher-margin advanced air-filled systems. The dominant pricing model remains per-unit transactional, often influenced by long-term contracts with large hospital networks. Price differentiation stems from clinical efficacy, material innovation, and brand reputation, particularly for specialized solutions. Pricing softness in the foam segment reflects intense competition and limited reimbursement for standard products. Budget-constrained healthcare facilities and home care users exhibit the most price sensitivity, favoring cost-effective options, while critical care units prioritize efficacy over cost.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke networks manage the logistics of bulky support surfaces across major markets. Supply concentration for advanced components, such as micro-sensors and specialized polymers, draws from technology hubs in Germany, Japan, and the United States. Raw material dependencies include open-cell polyurethane foam, advanced fabrics, and electronic components for smart surfaces. Regulatory restrictions, particularly the EU's Medical Device Regulation, represent a structural risk by lengthening market entry for new products. Distribution runs through a mix of direct sales teams for large institutional buyers and third-party distributors for smaller facilities and the expanding home care segment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pressure ulcer prevention market is a supply-constrained story, with stringent regulatory hurdles creating a bottleneck for advanced product introductions and propping up pricing for compliant solutions.
For Market Incumbents:Deploy continuous R&D investment to integrate smart monitoring capabilities into support surfaces. This strategy helps differentiate offerings against emerging threats from specialized technology firms and addresses the shift to multi-vendor procurement. Secure robust clinical evidence for existing and new products, ensuring compliance with evolving regulations like the EU's MDR and maintaining market access in key European healthcare systems. Focus on expanding after-sales service and training programs for complex air-filled systems.
For New Entrants and Emerging Players:A significant price-point gap exists between premium critical care solutions and basic prevention products, presenting an opportunity for disruptive innovation. Target the underpenetrated home care segment with simplified, user-friendly, and cost-effective solutions. A viable go-to-market angle involves leveraging digital platforms for direct-to-consumer sales and remote patient monitoring, bypassing traditional institutional procurement channels. Develop specialized application products, such as bariatric or pediatric prevention systems, to carve out niche markets.
For Investors and Strategic Acquirers:Exit pathways concentrate in specialized technology providers and firms with robust clinical data portfolios, offering long-term viability fueled by demographic shifts. Evaluate companies with strong intellectual property in smart surface technologies or those demonstrating efficient navigation of complex regulatory landscapes. The primary acquisition target archetype involves firms offering proven solutions for the expanding home care market or those with established distribution networks in high-growth regions. A key signal to watch is the pace of reimbursement expansion for advanced preventative technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Surface R&D | Integrates sensor technology, providing clinicians real-time patient data for proactive intervention. |
| MDR Compliance Investment | Secures CE marking for products, maintaining market access in European healthcare systems. |
| Home Care Product Development | Addresses the growing preference for aging-in-place, supporting non-clinical user needs. |
| Strategic Partnerships | Accelerates integration of advanced materials or digital platforms, enhancing product efficacy. |
| Clinical Evidence Generation | Validates product claims with robust data, meeting stringent US FDA and EU MDR requirements. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for market sizing and trend identification. This was triangulated with primary interviews involving GPO contracts managers, hospital purchasing committees, clinicians, and biomedical engineers. Secondary sources included US FDA databases, EU MDR guidelines, PMDA publications, and medical device industry reports, ensuring comprehensive data collection. Both bottom-up and top-down approaches were employed to validate market estimates.
Granular modeling of product types, applications, technologies, and end-user segments provided detailed market insights across the analysis window. The analytical framework also incorporated regional regulatory frameworks and healthcare expenditure patterns. Compound annual growth rates were derived from historical trends, identified market drivers, and expert consensus. Key industry-specific forecast inputs included geriatric population growth rates and the adoption of value-based care models.
Inputs from clinical trial outcomes and regulatory updates were available through the study window; gaps in real-world post-market surveillance data introduce uncertainty bands. Forecasts reflect assumptions regarding evolving reimbursement policies and new material science breakthroughs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Consumer Healthcare Market
Healthcare Products
Smoking Cessation Aids Market
Healthcare Products
Dementia Care Products Market
Healthcare Products
Elderly Walker Market
Healthcare Products
Birth Tissue Products Market
Healthcare Products
Hand Sanitizer Market
Healthcare Products
Medical Products Market
Healthcare Products
Blood and Organ Bank Market
Healthcare Products
Italy Hand Sanitizer Market
Healthcare Products
Nursing Products Market
Healthcare Products
Antimicrobial Furniture Market
Healthcare Products
Europe Hand Sanitizer Market
Healthcare Products
Global Life Science Products Market
Healthcare Products
Global Healthcare Distribution Market
Healthcare Products
Global Clinical Trial Consumables Market
Healthcare Products
Automatic Hand Sanitizer Dispenser Market