
 US Wireless Sensors Market | 2026-2036
US Wireless Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
US Wireless Sensors Market Analytics
Industrial distributor networks is reconfiguring around embedded IoT procurement bundles that combine hardware with cloud analytics subscriptions. Honeywell International Inc. leverages its building automation heritage to dominate integrated environmental sensing suites for commercial facilities. Emerson Electric Co. sustains deep penetration in process manufacturing through its Plantweb digital ecosystem. Texas Instruments Incorporated anchors the component layer with its broad portfolio of wireless connectivity chipsets and sensor signal conditioners.
US wireless sensors are self-contained measurement devices that integrate a sensing element, signal conditioning circuitry, a microprocessor, and a radio transceiver operating typically in the 2.4 GHz ISM band or sub-GHz licensed-exempt spectrum, designed to transmit calibrated physical data to gateway or edge-computing nodes without hardwired connections. Temperature sensors and pressure sensors occupy the most mature product tiers, with established calibration protocols and replacement cycles driving recurring revenue, while proximity sensors and motion sensors are gaining faster traction in smart home and security applications where battery life and millimeter-wave resolution matter. Bluetooth and Wi-Fi technologies dominate indoor consumer-facing deployments, whereas LoRaWAN extends its reach across agricultural telemetry and outdoor infrastructure monitoring where kilometer-range links and minimal power draw offset lower data rates.
The FCC governs radio frequency emissions and spectrum allocation, NHTSA influences automotive crash-avoidance sensor mandates, and OSHA sets workplace exposure thresholds that drive industrial air-quality and vibration monitoring installations. These frameworks collectively push manufacturers toward certified modules and documented traceability. Stakeholders must weigh spectrum congestion risks against the operational savings of untethered measurement architectures as deployment density rises.
Market Dynamics
FCC spectrum expansions in sub-GHz ISM bands are compressing hardware design cycles while manufacturing automation mandates from OSHA and plant-level digital transformation budgets create synchronized pull for untethered measurement architectures.
Growth Catalysts
- OSHA workplace exposure mandates:Industrial facilities in Texas and California deploy air-quality and vibration monitoring arrays to maintain compliance thresholds. These installations generate recurring replacement cycles for calibrated sensor nodes.
- Condition-monitoring arrays:Manufacturing plants accelerate retrofit deployments to eliminate unplanned downtime. Wireless architectures cut installation labor versus wired alternatives in brownfield environments.
- FCC unlicensed spectrum allocations:Expanded ISM band access enables longer-range, lower-power radio modules. Module vendors now certify multi-band transceivers that switch between 2.4 GHz and sub-GHz operation.
Market Restraints
- Lithium battery supply concentration:Primary cell sourcing for battery-powered nodes depends on limited domestic processing capacity. Price volatility in lithium carbonate feeds directly into bill-of-materials pressure.
- Radio module certification backlog:FCC Part 15 authorization timelines stretch deployment schedules for new product variants. Pre-certified module premiums compress margin on cost-sensitive agricultural telemetry.
- Wired sensor substitution in high-reliability zones:Nuclear and aerospace applications maintain hardwired architectures for deterministic latency. These verticals resist wireless migration despite total-cost advantages.
Strategic Opportunities
- IRA clean energy manufacturing incentives:Battery gigafactories and solar assembly plants in Arizona and Georgia require environmental monitoring at scale. Greenfield construction permits embed sensor infrastructure from commissioning.
- Edge-AI convergence with mmWave sensing:Proximity modules now embed on-chip inference for gesture recognition. Smart home OEMs in California integrate these for security and occupancy applications.
- Direct-to-plant procurement platforms:Distributor marketplaces bundle hardware with cloud analytics subscriptions. Procurement teams in Midwest automotive corridors bypass traditional component stocking.
Industry Challenges
- RF engineering talent scarcity:Sub-GHz antenna design and mesh networking protocol optimization require specialized expertise. Midwest industrial automation hubs compete with consumer electronics for limited practitioner pools.
- Legacy SCADA integration complexity:Brownfield manufacturing sites operate proprietary industrial Ethernet. Wireless gateway vendors must maintain protocol translation stacks for decade-old control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Wireless Sensors Market |
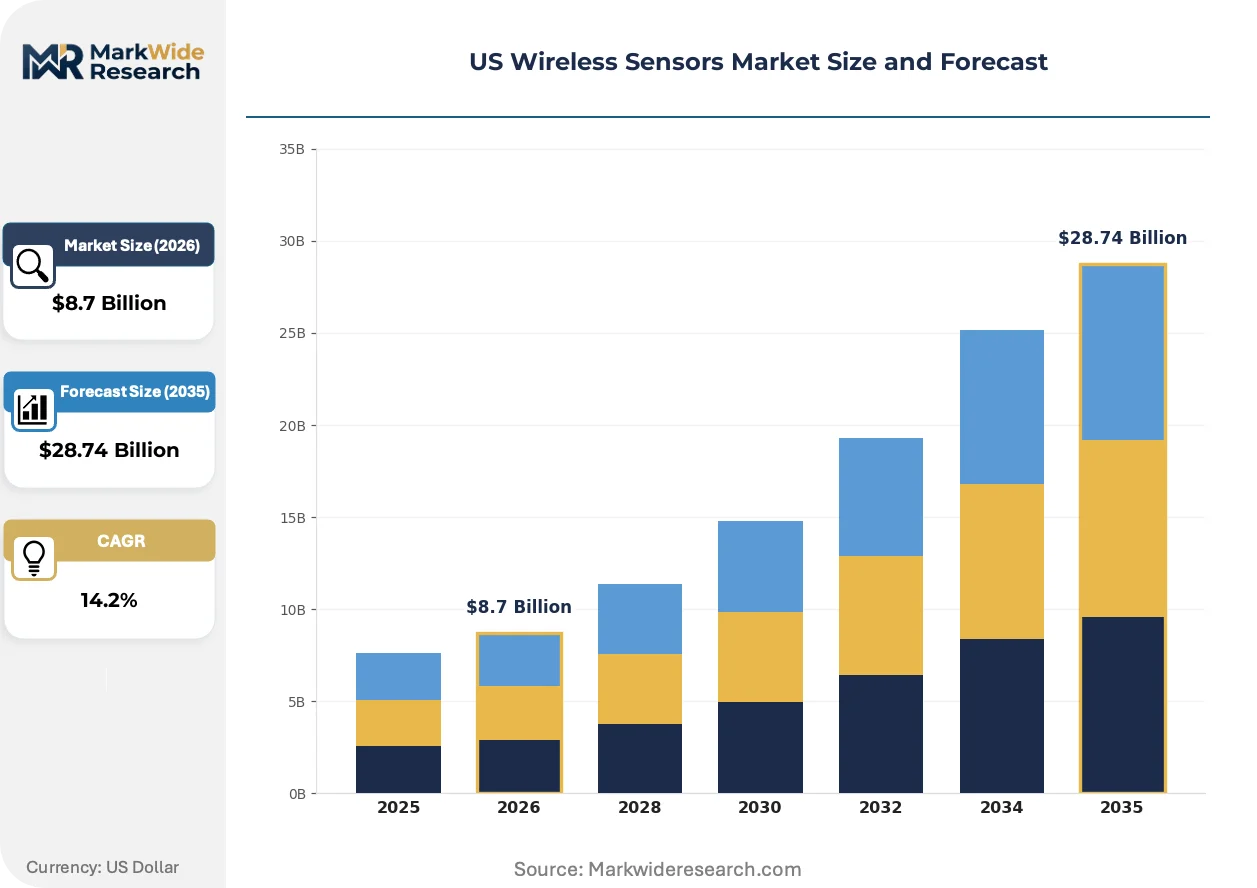
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Pressure Sensors, Proximity Sensors, Motion Sensors Technology: Bluetooth, Zigbee, Wi-Fi, LoRaWAN End User: Manufacturing, Healthcare, Smart Home, Agriculture Deployment: Indoor, Outdoor, Industrial, Commercial |
| Companies Covered | Honeywell International Inc., Emerson Electric Co., Texas Instruments Incorporated, ABB Ltd., Pasco Scientific, Monnit Corporation, Phoenix Sensors LLC, Schneider Electric, TE Connectivity Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Wireless Sensors Market Evolving Landscape
Silicon integration and spectrum policy are compressing hardware form factors while procurement patterns shift toward bundled hardware-software contracts. Three developments dominate current investment allocation.
Ultra-wideband (UWB) ranging chipsets are digitizing indoor positioning accuracy for asset tracking and personnel safety. Automotive suppliers in Michigan adopt UWB for hands-free entry systems, while warehouse operators in Illinois deploy centimeter-resolution location for automated guided vehicle coordination. The technology is digitizing spatial awareness applications previously served by camera arrays or RFID triangulation.
FCC Part 95 rulemaking for the 902-928 MHz band expansion reduces transmit power restrictions for spread-spectrum devices. Agricultural telemetry networks in the Central Valley now deploy longer-range LoRaWAN gateways without site licensing. Midwest grain elevator operators respond by consolidating sensor counts per gateway, cutting infrastructure capital per acre monitored.
Facility managers increasingly specify hardware-software bundles with guaranteed uptime service-level agreements. Traditional component distributors in Texas and Ohio lose volume to vertically integrated platform vendors offering predictive maintenance dashboards. This consolidation is most visible in commercial building automation, where Honeywell and Johnson Controls capture specification authority through bundled environmental sensing suites.
US Wireless Sensors Market Segmentation
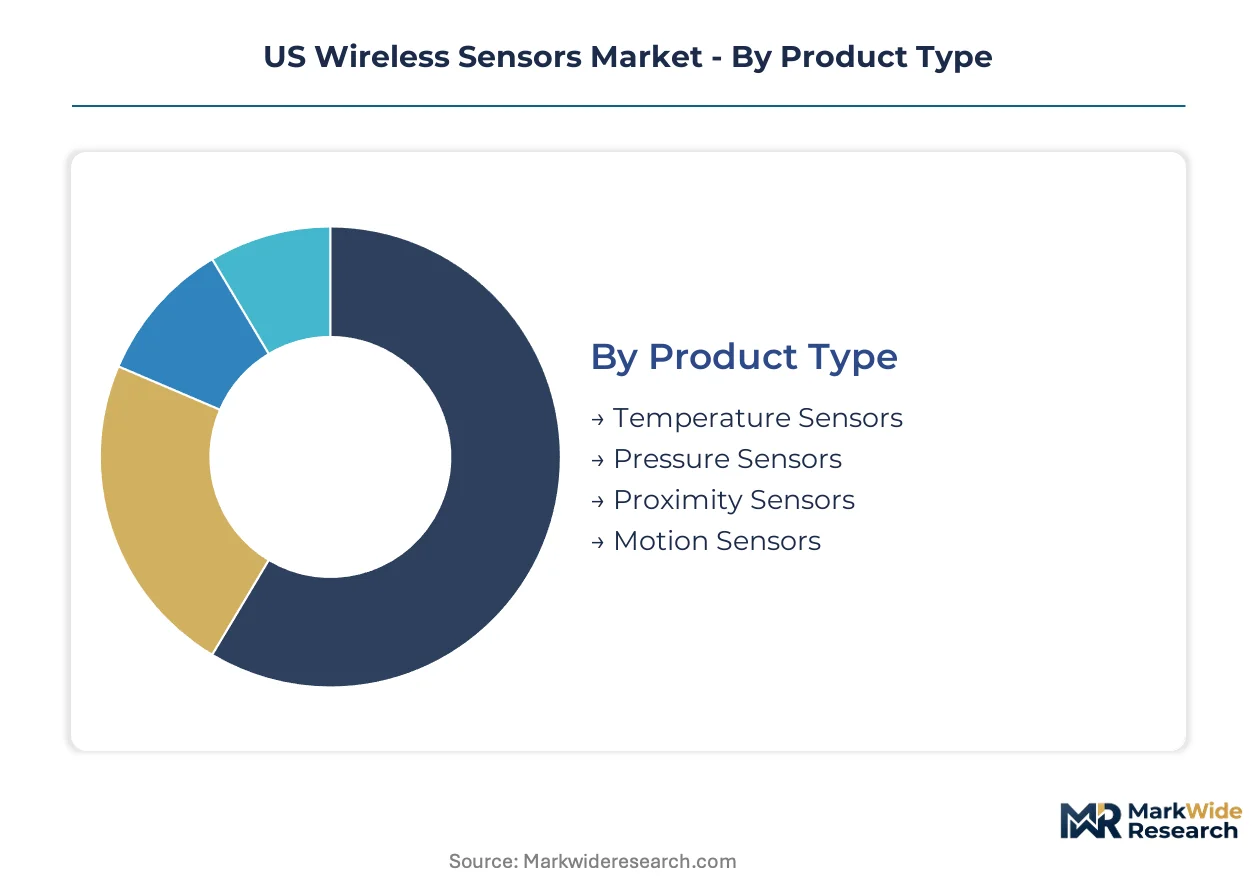
US wireless sensors fragment across four distinct classification axes. Product type and technology dimensions capture hardware differentiation, while end-user and deployment categories map demand concentration to specific facility types and environmental conditions.
Product Type:
Cost tier stratification separates mature calibrated products from emerging high-resolution modules. Replacement cycles and certification requirements drive divergent margin structures across these four hardware categories.
- Temperature Sensors:Thermocouple, RTD, and semiconductor junction elements transmit calibrated thermal data through sub-GHz or 2.4 GHz links. Process manufacturing in Texas and California sustains bulk procurement for reactor vessel and pipeline monitoring, with OSHA thermal exposure mandates forcing quarterly calibration protocols that lock in recurring revenue streams.
- Pressure Sensors:Piezoelectric and MEMS capacitive transducers measure gauge, absolute, and differential pressure states. Oil and gas infrastructure across the Permian Basin deploys explosion-rated wireless pressure nodes on wellheads and transmission lines, where battery-powered architectures eliminate ignition risks from conduit runs in hazardous area classifications.
- Proximity Sensors:Inductive, capacitive, and ultrasonic variants detect object presence without physical contact. Automotive assembly plants in Michigan and Ohio specify these for robotic collision avoidance and part-present verification on flexible manufacturing lines.
- Motion Sensors:PIR, mmWave, and accelerometer-based modules detect movement and vibration signatures. Security integrators in Florida and Arizona specify battery-operated motion nodes for perimeter protection where trenching for power is cost-prohibitive.
Temperature sensors hold installed capacity. Proximity sensors are rotating up the share rankings.
Technology:
Application requirements dictate radio selection across range, power, and data rate tradeoffs. Indoor consumer deployments favor high-throughput protocols while agricultural and infrastructure monitoring prioritizes kilometer-range links.
- Bluetooth:2.4 GHz frequency-hopping spread spectrum delivers 1-3 Mbps throughput for short-range personal area networks. Smart home OEMs in California integrate Bluetooth Low Energy chipsets for door locks, lighting controls, and occupancy sensors where smartphone gateway integration drives consumer preference.
- Zigbee:Mesh-capable IEEE 802.15.4 protocol supports thousands of nodes per network with sub-100 mW power draw. Commercial building automation contractors in Illinois and New York specify Zigbee for lighting and HVAC control where self-healing mesh topology ensures reliability across multi-floor deployments.
- Wi-Fi:High-bandwidth 802.11a/b/g/n/ac/ax standards enable video-capable sensor streams. Healthcare facilities in Massachusetts and Pennsylvania deploy Wi-Fi connected patient monitoring devices that require continuous waveform transmission to central nursing stations.
- LoRaWAN:Chirp spread spectrum modulation achieves 15 km range in rural terrain at sub-50 mW transmit power. Grain elevator cooperatives across Iowa and Nebraska consolidate soil moisture and weather monitoring onto LoRaWAN gateways that cover entire county-scale farming operations without cellular subscription costs.
Bluetooth dominates node shipments. LoRaWAN is gaining share fastest in outdoor telemetry.
End User:
Customer type segmentation maps to divergent procurement authority and specification complexity. Industrial buyers prioritize integration with legacy control systems while consumer-facing channels demand out-of-box configurability.
- Manufacturing:Discrete and process automation facilities specify ruggedized IP67-rated nodes for condition monitoring. Automotive stamping plants in the Midwest deploy vibration and thermal arrays on critical spindle bearings to trigger predictive maintenance work orders before catastrophic failure.
- Healthcare:FDA-regulated medical devices and unregulated wellness monitors split this category. Remote patient monitoring startups in Boston and San Francisco ship Bluetooth-connected pulse oximeters and weight scales to homebound Medicare populations under reimbursement codes that require documented data transmission.
- Smart Home:Retail channels and professional integrators serve security, comfort, and energy management use cases. DIY installation preference in suburban Texas and Florida drives demand for battery-operated environmental sensors with five-year cell life and smartphone onboarding flows.
- Agriculture:Precision farming operations and commodity grain handlers deploy soil, weather, and equipment tracking sensors. Central Valley almond growers in California optimize irrigation scheduling through soil volumetric water content probes that transmit hourly readings to cloud-based evapotranspiration models.
Manufacturing commands specification authority. Smart home is climbing the fastest on volume.
Deployment:
Environmental exposure and regulatory jurisdiction create distinct hardware requirements. Indoor commercial spaces face fire code compliance while outdoor industrial sites contend with NEMA enclosure ratings and lightning protection.
- Indoor:Climate-controlled environments enable polymer enclosure materials and standard lithium primary cells. Corporate campuses in Seattle and Austin deploy indoor air quality nodes that measure CO2, VOCs, and particulates to optimize HVAC energy consumption under LEED certification requirements.
- Outdoor:UV-stabilized housings and extended temperature ratings accommodate unprotected exposure. Municipal water authorities in Arizona and Nevada deploy pressure and flow sensors on distribution mains where solar-battery hybrid power eliminates trenching through paved roadways.
- Industrial:Hazardous area classifications and electromagnetic immunity standards dominate specifications. Chemical processing complexes along the Gulf Coast specify intrinsically safe wireless transmitters for tank level and pressure monitoring in Class I Division 1 zones where wired alternatives require expensive explosion-proof conduit.
- Commercial:Mixed-use facilities balance aesthetic integration with functional performance. Retail chains in Georgia and North Carolina standardize on wireless environmental monitoring across thousands of locations to maintain consistent product storage conditions and reduce energy spend through centralized building management system integration.
Industrial deployment holds replacement volume. Commercial is expanding most quickly on greenfield construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin pipeline network and Gulf Coast petrochemical corridor anchor Texas as the dominant deployment zone for industrial wireless sensor arrays. California's Central Valley irrigation infrastructure and coastal technology corridors generate parallel demand concentrations for agricultural telemetry and smart building automation.
Texas
Oil and gas infrastructure operators deploy explosion-rated pressure and temperature nodes across wellheads and transmission corridors. OSHA Process Safety Management mandates drive recurring calibration cycles for hazardous area monitoring equipment. Houston and the Permian Basin host the densest concentration of battery-powered wireless transmitters for tank level monitoring in Class I Division 1 zones.
California
Central Valley almond growers optimize irrigation through soil volumetric water content probes transmitting hourly data to cloud-based evapotranspiration models. FCC unlicensed spectrum allocations in sub-GHz bands enable longer-range LoRaWAN gateways without site licensing. Silicon Valley and Los Angeles industrial corridors concentrate smart building automation deployments integrating environmental sensing suites.
Michigan
Automotive stamping plants deploy vibration and thermal arrays on critical spindle bearings to trigger predictive maintenance work orders. NHTSA crash-avoidance sensor mandates influence supplier specifications for proximity and motion detection modules. Detroit and Grand Rapids manufacturing corridors anchor the Midwest's densest concentration of condition-monitoring retrofits.
Illinois
Commercial building automation contractors specify Zigbee mesh networks for lighting and HVAC control across multi-floor deployments. LEED certification requirements drive indoor air quality monitoring for CO2, VOCs, and particulates in corporate campuses. Chicago and Rockford industrial hubs concentrate procurement of self-healing mesh topology systems.
Arizona
Municipal water authorities deploy pressure and flow sensors on distribution mains where solar-battery hybrid power eliminates trenching through paved roadways. IRA clean energy manufacturing incentives attract battery gigafactories requiring environmental monitoring at scale. Phoenix and Tucson construction permits embed sensor infrastructure from commissioning in greenfield commercial developments.
US Wireless Sensors Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated platform vendors that bundle hardware with predictive maintenance dashboards. Tiered competition separates component-layer specialists, integrated system providers, and cloud-analytics platform operators. Dominant competitive moves include distributor marketplace consolidation and edge-AI capability integration into proximity sensing modules.
Within the integrated system provider tier, Honeywell International Inc. and Emerson Electric Co. exemplify archetypes that leverage building automation heritage and process manufacturing ecosystems respectively. Texas Instruments Incorporated anchors the component layer. These three occupy positions that reflect divergent strategic foundations: automation legacy, digital ecosystem penetration, and semiconductor connectivity portfolios.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Emerson Electric Co. |
| Texas Instruments Incorporated |
| ABB Ltd. |
| Pasco Scientific |
| Monnit Corporation |
| Phoenix Sensors LLC |
| Schneider Electric |
| TE Connectivity Ltd. |
| Others |
Value Network & Pricing Analysis
Lithium carbonate price volatility compresses tier spreads between economy-grade consumer nodes and industrial-certified modules while simultaneously forcing procurement teams toward multi-source battery cell strategies. FCC certification backlogs and tariff exposure on Asian radio module imports amplify cost differentials across the hardware stack.
Pricing Analysis
Volume-discount tiering structures separate calibrated industrial nodes from consumer-grade hardware. Three-tier pricing stratifies across premium certified modules, standard commercial units, and economy OEM chipsets, with FCC Part 15 certification tiers driving the primary differentiation. Pricing pressure intensifies in agricultural telemetry segments where pre-certified module premiums erode margins. Smart home OEMs exhibit highest price sensitivity, while Gulf Coast petrochemical operators absorb premium tiers for hazardous area ratings.
Supply Chain Analysis
Tariff exposure between China and the United States dominates procurement risk calculations for radio transceiver modules and lithium primary cells. Manufacturing concentrates in China, Taiwan, and South Korea for chipsets, with domestic assembly in Texas and California for final node integration. Raw material dependencies center on lithium carbonate from Chile and Australia, rare earth elements for antenna substrates, and silicon wafers. Distribution runs through industrial distributor networks reconfiguring around bundled IoT procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as brownfield manufacturing digitization creates specification niches for protocol-translation specialists. Procurement authority is dispersing from traditional distributors to direct-to-plant platform vendors.
For Market Incumbents: Entrench position through backward integration into FCC pre-certified module production and captive lithium cell sourcing. Honeywell and Emerson should expand edge-AI capability integration into proximity sensing modules to defend against emerging platform vendors. Channel control through specification authority in commercial building automation remains the critical defensive lever. For New Entrants and Emerging Players: Pursue agricultural telemetry white space in the Central Valley and Midwest grain corridors where LoRaWAN gateway consolidation is reducing infrastructure capital per acre. The most penetrable segment lies in mid-sized manufacturing facilities lacking legacy SCADA integration expertise. A direct-to-plant procurement platform bundling hardware with predictive maintenance dashboards offers the strongest go-to-market angle. For Investors and Strategic Acquirers: RF engineering talent aggregators with sub-GHz antenna design capabilities and mesh networking protocol optimization expertise represent priority acquisition targets. Long-term viability hinges on positioning for edge-AI convergence with mmWave sensing across the next decade. The signal to monitor is IRA clean energy manufacturing incentive disbursement velocity in Arizona and Georgia, which will determine greenfield sensor infrastructure deployment cadence.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Module Integration | On-chip inference capability in proximity sensors enables gesture recognition for Michigan automotive suppliers. |
| FCC Pre-Certification Investment | Multi-band transceiver certification reduces deployment delays for Texas oil and gas infrastructure operators. |
| Direct-to-Plant Platform Launch | Bundled hardware-software contracts bypass traditional distributors in Midwest automotive corridors. |
| Lithium Cell Sourcing Diversification | Domestic processing capacity expansion mitigates bill-of-materials pressure from Chilean carbonate volatility. |
| LoRaWAN Gateway Consolidation | Longer-range agricultural telemetry in Iowa and Nebraska cuts infrastructure capital per acre monitored. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with plant engineers, industrial automation procurement leads, FCC regulatory affairs specialists, and agricultural telemetry network operators; and secondary validation against FCC Part 15 authorization databases, OSHA enforcement records, EIA energy infrastructure disclosures, and customs import data for radio module classifications. Bottom-up node shipment estimates triangulated against top-down manufacturing facility digitization budget surveys.
Forecast inputs considered technology adoption curves across Bluetooth, LoRaWAN, Zigbee, and Wi-Fi protocols; end-user segmentation spanning manufacturing, healthcare, smart home, and agriculture; and deployment environment specifications from indoor commercial to hazardous industrial zones. CAGRs derived from installation base growth modeling and replacement cycle analysis. Industry-specific inputs included FCC spectrum allocation rulemaking timelines and IRA clean energy manufacturing incentive disbursement patterns.
Sensitivities concentrate around lithium carbonate price trajectories, FCC certification backlog durations, and brownfield SCADA integration complexity. Forecasts reflect assumptions on regulatory enforcement consistency and spectrum policy continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
HVAC Sensor Market
Sensors and Controls
Automation Control Components and Devices Market
Sensors and Controls
US Pressure Sensors Market
Sensors and Controls
Tip Location Devices Market
Sensors and Controls
China PV Monitoring Systems Market
Sensors and Controls
Smart Level Probe Market
Sensors and Controls
Biomedical Pressure Sensors Market
Sensors and Controls
Global Thermocouple Temperature Sensors Market
Sensors and Controls
Magnetic Proximity Sensor Market
Sensors and Controls
MEMS-Based IMU Market
Sensors and Controls
China Digital Thermometer Market
Sensors and Controls
Fingerprint Module Market
Sensors and Controls
Sensor Data Analytics Market
Sensors and Controls
Global Pyrometer Market
Sensors and Controls
Global Optogenetics Actuators and Sensors Market
Sensors and Controls
Room Pressure Monitor Market