
 Europe Gas Sensors Market | 2026-2036
Europe Gas Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Gas Sensors Market Foresight
A shift from single-source to multi-source procurement of MEMS sensing elements is realigning supply chain resilience across the European gas sensor value chain. Sensirion AG leverages its Swiss fabrication footprint to sustain wafer-level cost advantages in electrochemical sensor production. Bosch Sensortec GmbH anchors its position through deep integration with German automotive OEM diagnostic platforms.
Europe gas sensors are transducer devices that detect and quantify gas concentrations through electrochemical reaction, infrared absorption, or metal-oxide resistance change, typically operating across detection ranges from parts-per-billion to percentage levels for safety and process control. Electrochemical sensors dominate industrial safety applications due to their established calibration protocols and regulatory acceptance, while infrared sensors command premium positioning in environmental monitoring where cross-sensitivity rejection drives specification value. IoT-based technology is expanding fastest among technology segments as edge-computing architectures enable predictive maintenance integration.
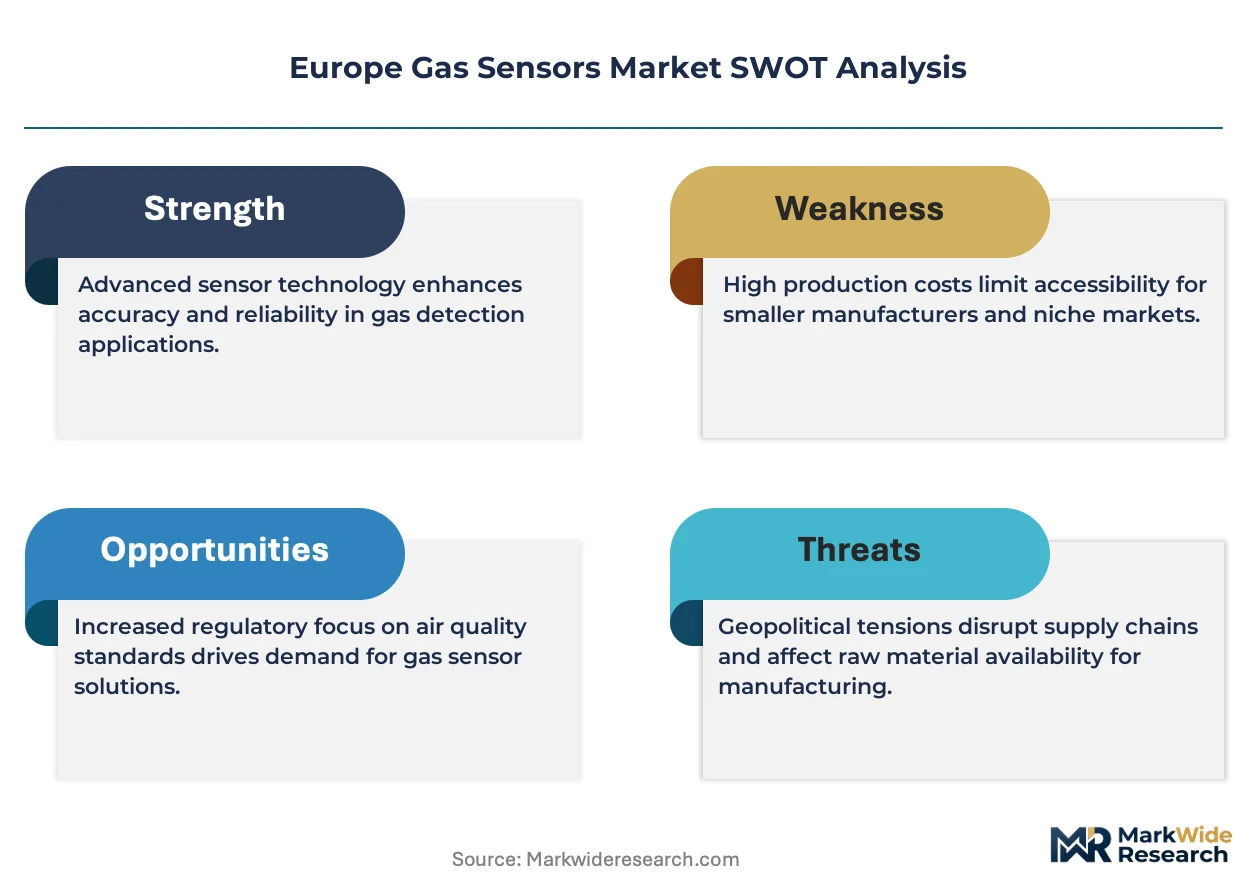
The EU F-Gas Regulation and REACH framework mandate phasedown of fluorinated greenhouse gases and full material disclosure, forcing sensor manufacturers to validate alternative refrigerant detection chemistries. CE marking under the EU AI Act adds conformity layers for smart sensing systems with embedded decision algorithms. Stakeholders must monitor how ECHA substance restriction proposals reshape acceptable sensing materials before committing to multi-year platform designs.
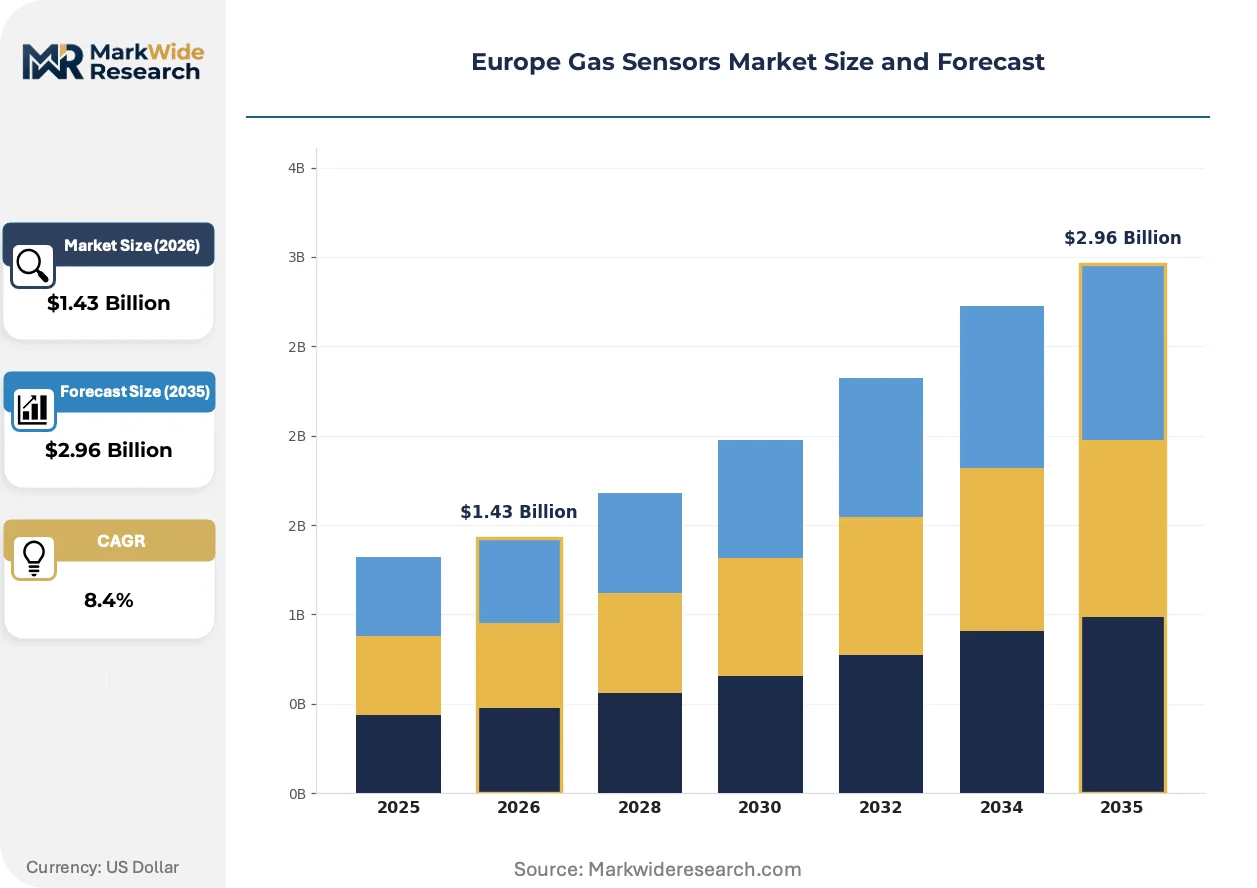
Market Dynamics
The EU F-Gas Regulation's phasedown mandates are compressing replacement cycles for legacy detection equipment across European industrial facilities, forcing simultaneous technology transitions in multiple end-use verticals.
Growth Catalysts
- REACH framework material disclosure:Chemical manufacturers must validate alternative refrigerant detection chemistries, expanding demand for multi-gas sensor arrays in German and French process plants.
- Industrial safety mandates:German chemical sector expansion requires electrochemical sensor deployments for toxic gas monitoring in confined spaces and process vessels.
- MEMS fabrication scale:Swiss and German foundry capacity for wafer-level sensor production is lowering unit costs for high-volume environmental monitoring applications.
Market Restraints
- Palladium catalyst cost volatility:Electrochemical sensor electrodes depend on platinum-group metal inputs subject to supply disruption from South African and Russian export channels.
- Infrared source supply concentration:Nondispersive infrared sensor manufacturing relies on germanium and lead selenide detector substrates with limited European domestic sourcing.
- Cross-sensitivity technical limitation:Metal-oxide semiconductor sensors face inherent selectivity constraints in multi-contaminant industrial atmospheres, restricting deployment in complex process environments.
Strategic Opportunities
- Poland industrial corridor expansion:Central European manufacturing relocation is creating greenfield demand for integrated gas detection systems in new chemical and pharmaceutical facilities.
- EU AI Act smart sensor mandate:Embedded decision algorithms in safety-critical applications require CE conformity assessment, opening premium positioning for validated intelligent sensing platforms.
- Edge-to-cloud architecture convergence:LoRaWAN and 5G private network integration is enabling predictive maintenance service models for distributed industrial sensor fleets.
Industry Challenges
- Calibration technician scarcity:Electrochemical sensor drift correction requires certified personnel with diminishing availability across European industrial maintenance workforces.
- ATEX/IECEx certification timelines:Explosion-proof equipment approval processes for hazardous area deployments extend product launch schedules by 12-18 months.
- Legacy system integration friction:Analog 4-20mA sensor replacements must interface with decades-old distributed control systems lacking digital communication protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Gas Sensors Market |
| Market Size in 2026 | $1.43 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal-Oxide Sensors, Electrochemical Sensors, Infrared Sensors, Photonic Sensors Application: Industrial Safety, Environmental Monitoring, Home Automation, Automotive Diagnostics End User: Manufacturing, Oil & Gas, Healthcare, Residential Technology: Wireless, IoT-Based, Smart Sensing, Analog |
| Companies Covered | Sensirion AG, Bosch Sensortec GmbH, Honeywell International Inc., Draegerwerk AG & Co. KGaA, Siemens AG, ABB Ltd., Amphenol Corporation, ams-OSRAM AG, Emerson Electric Co., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Gas Sensors Market Shifts & Advancements
Photonic and microelectronic fabrication advances are enabling chip-scale gas detection platforms that merge sensitivity gains with form factor reduction, reshaping competitive requirements across European industrial and environmental monitoring segments.
Silicon photonics is integrating infrared absorption spectroscopy onto CMOS-compatible substrates, replacing discrete optical benches with waveguide-integrated photodetectors. Dutch and German automotive OEMs are qualifying these devices for cabin air quality management at production scale. The technology is integrating environmental and safety sensing into single semiconductor packages, compressing supplier margins for discrete component vendors.
The EU AI Act's CE marking requirements for embedded decision systems are mandating conformity assessment procedures for smart gas detectors with autonomous alarm thresholds. Industrial safety integrators must now document algorithm validation for edge-computing sensor nodes deployed in critical infrastructure. French and German notified bodies are developing specialized accreditation pathways for machine-learning-enabled detection equipment, creating compliance differentiation among platform suppliers.
Buyers are consolidating sensor procurement through framework agreements with industrial automation distributors, displacing direct manufacturer relationships for standard detection products. German chemical operators now specify multi-year sensor-as-a-service contracts bundling hardware, calibration, and predictive analytics. This pattern concentrates most visible in the Rhine-Ruhr industrial cluster, where integrated facility management providers negotiate enterprise-wide gas detection supply arrangements.
Europe Gas Sensors Market Segmentation
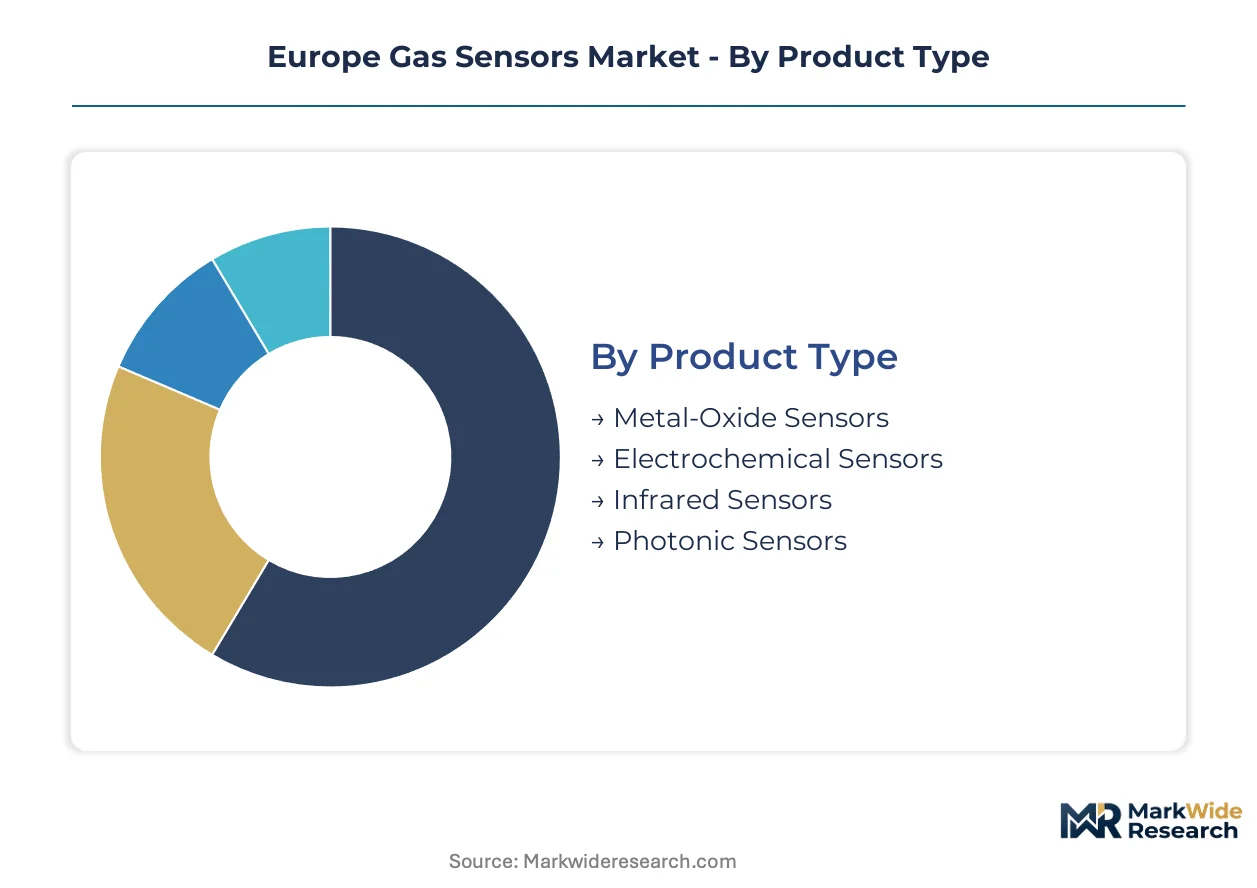
Gas sensor segmentation in Europe reflects divergent integration architectures. Standalone detection systems dominate industrial safety deployments. Embedded sensing modules are penetrating automotive and consumer electronics platforms. Procurement patterns differ sharply between these integration modes.
Product Type:
Standalone sensor packages require external signal conditioning and calibration infrastructure. Embedded variants integrate directly into host system electronics with factory-programmed compensation algorithms.
- Metal-Oxide Sensors:Semiconductor films of tin dioxide or zinc oxide change electrical resistance upon gas adsorption, operating at elevated temperatures requiring heater elements. German automotive cabin air quality systems embed these for volatile organic compound detection, though cross-sensitivity to humidity and temperature complicates signal processing. Demand concentrates in cost-sensitive residential carbon monoxide alarms across Poland and Spain.
- Electrochemical Sensors:Three-electrode cells generate current proportional to target gas concentration through redox reactions at catalytic surfaces. French and German chemical plants specify these for hydrogen sulfide and chlorine monitoring in confined spaces, driven by ATEX mandatory inspection intervals. Palladium electrode costs create margin pressure for mid-tier suppliers.
- Infrared Sensors:Nondispersive absorption spectroscopy using broadband sources and narrowband filters enables selective detection without consumable electrodes. Process industries in the Netherlands deploy these for refrigerant leak detection under F-Gas Regulation compliance timelines.
- Photonic Sensors:Silicon photonics integration merges infrared waveguides with CMOS detectors for chip-scale form factors. Dutch foundry partnerships are qualifying these for next-generation automotive HVAC systems.
Electrochemical sensors lead volumes today; photonic sensors are gaining share fastest.
Application:
Application segmentation tracks divergent performance specifications. Safety-critical deployments demand SIL-rated reliability with documented failure modes. Environmental monitoring accepts wider accuracy bands for distributed network economics.
- Industrial Safety:Fixed-point detection systems with 4-20mA or digital outputs integrate into plant distributed control architectures. German chemical corridor operators mandate redundant sensor arrays for toxic gas releases, with calibration records audited by trade liability insurers.
- Environmental Monitoring:Low-power nodes for urban air quality networks prioritize sensor density over individual measurement precision. French agglomerations deploy electrochemical ozone sensors at tram stops and school perimeters under regional health authority protocols.
- Home Automation:Battery-powered devices with cloud connectivity enable consumer smartphone alerts. Spanish building code amendments are mandating networked smoke and carbon monoxide detection in new residential construction.
- Automotive Diagnostics:Cabin air quality modules and powertrain emissions sensors require AEC-Q100 automotive qualification. Stuttgart and Munich OEMs specify multi-gas arrays for recirculation control and leak detection.
Industrial safety commands premium pricing; environmental monitoring shows steepest volume expansion trajectory.
End User:
End user segmentation reveals procurement sophistication gaps. Asset-intensive industries negotiate multi-year sensor-as-a-service contracts. Residential channels compete on retail shelf price with minimal technical support.
- Manufacturing:Chemical, pharmaceutical, and food processing facilities operate under combined REACH and ATEX compliance obligations. Rhine-Ruhr cluster operators consolidate procurement through industrial automation distributors.
- Oil & Gas:Upstream platforms and downstream refineries require explosion-proof enclosures with IECEx certification. North Sea operators specify infrared sensors for methane detection to minimize false alarms from humidity interference.
- Healthcare:Anesthesia gas monitoring and incubator oxygen control demand medical device regulation conformity. Swiss and German hospital procurement specifies electrochemical oxygen sensors with drift compensation algorithms.
- Residential:Standalone carbon monoxide and natural gas alarms represent price-commoditized volume. Polish and Romanian distribution channels favor basic electrochemical units without connectivity features.
Manufacturing absorbs the highest sensor value per facility; healthcare shows tightest specification tolerances.
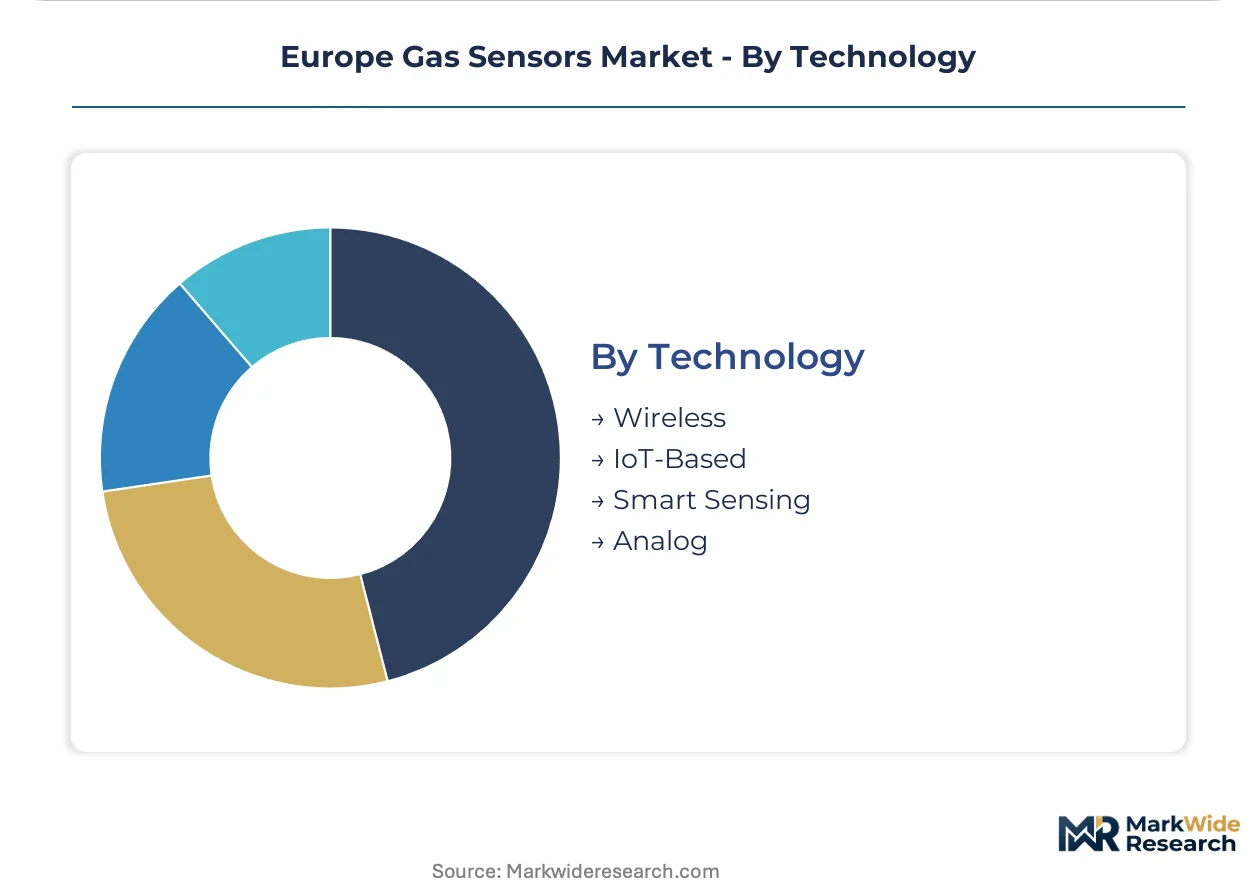
Technology:
Technology segmentation captures connectivity architecture evolution. Analog legacy installations persist in brownfield industrial sites. Digital platforms enable predictive maintenance business models.
- Wireless:Battery-powered nodes using LoRaWAN or proprietary protocols eliminate cabling costs in remote monitoring. French environmental agencies deploy these for landfill perimeter methane surveillance.
- IoT-Based:Edge-computing architectures with cloud analytics enable fleet-wide calibration optimization. German chemical operators pilot these for predictive replacement scheduling.
- Smart Sensing:Embedded algorithms with autonomous alarm thresholds trigger EU AI Act CE marking requirements. Notified bodies in France and Germany are developing conformity assessment pathways.
- Analog:4-20mA current loops dominate legacy distributed control system interfaces. Integration friction with digital platforms constrains upgrade economics.
Analog technology retains installed base dominance; IoT-based architectures are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor anchors European gas sensor demand through its dense concentration of chemical processing and petrochemical refining capacity. German operators under ATEX and REACH obligations are replacing legacy detection systems with multi-gas arrays. French environmental agencies are deploying distributed sensor networks for urban air quality compliance.
Germany
Chemical sector expansion in North Rhine-Westphalia and Lower Saxony is driving electrochemical sensor procurement for toxic gas monitoring in confined process vessels. The EU F-Gas Regulation mandates accelerated replacement of refrigerant detection equipment, compressing technology transition timelines. Stuttgart automotive OEMs are qualifying silicon photonics sensors for cabin air quality management in next-generation HVAC systems.
France
Environmental monitoring authorities in Île-de-France and Auvergne-Rhône-Alpes are deploying low-power ozone and nitrogen dioxide sensors at transit hubs and school perimeters. Regional health authority protocols under the EU Green Deal air quality directives are standardizing sensor density requirements. Lyon-based industrial automation integrators are negotiating multi-year sensor-as-a-service contracts with chemical operators.
Netherlands
Process industries in Rotterdam and Eindhoven are deploying infrared sensors for refrigerant leak detection under F-Gas Regulation compliance deadlines. Dutch foundry partnerships with photonics specialists are qualifying chip-scale spectroscopy devices for automotive applications. Randstad region environmental agencies are piloting LoRaWAN methane monitoring networks for landfill perimeter surveillance.
Switzerland
Swiss pharmaceutical manufacturing in Basel and Zurich requires medical-grade electrochemical oxygen sensors with drift compensation algorithms for cleanroom environments. Swissmedic conformity assessment pathways are tightening specification tolerances for anesthesia gas monitoring equipment. Sensirion AG leverages domestic wafer fabrication capacity to sustain cost advantages in high-volume environmental sensor production.
Poland
Central European manufacturing relocation is creating greenfield demand for integrated gas detection systems in new chemical and pharmaceutical facilities near Wrocław and Kraków. Polish building code amendments are mandating networked carbon monoxide detection in residential construction. Distribution channels favor basic electrochemical units without connectivity features for price-sensitive consumer segments.
Europe Gas Sensors Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue silicon photonics and edge-computing architectures. The vendor base stratifies across three maturity levels: integrated industrial conglomerates with safety system portfolios, specialized sensor fabricators with MEMS capabilities, and photonics startups leveraging Dutch and German foundry partnerships. Dominant competitive moves include backward integration into wafer-level fabrication and strategic partnerships with automotive OEMs for platform qualification.
Within the specialized fabricator tier, Sensirion AG and Bosch Sensortec GmbH exemplify contrasting geographic anchoring strategies. Sensirion AG occupies a position tied to Swiss MEMS production infrastructure, while Bosch Sensortec GmbH represents deep integration with German automotive diagnostic platforms. Honeywell International Inc. sits within the industrial conglomerate archetype, leveraging safety system integration capabilities across process industries.
| Leading Market Players |
|---|
| Sensirion AG |
| Bosch Sensortec GmbH |
| Honeywell International Inc. |
| Draegerwerk AG & Co. KGaA |
| Siemens AG |
| ABB Ltd. |
| Amphenol Corporation |
| ams-OSRAM AG |
| Emerson Electric Co. |
| Others |
Supply & Pricing Matrix
The EU F-Gas Regulation's refrigerant phasedown mandates gate qualified supply access and premium-tier pricing power, compressing replacement cycles for legacy detection equipment while validating alternative chemistries at higher specification tiers. German chemical operators and Dutch process industries now face bifurcated procurement economics between certified multi-gas arrays and commoditized single-point detectors.
Pricing Analysis
Input-cost pass-through from platinum-group metal volatility shapes electrode pricing for electrochemical sensors, with palladium catalyst expenses compressing margins for mid-tier suppliers. Pricing stratifies across SIL-rated safety systems, ATEX-certified industrial packages, and basic residential alarms without connectivity features. Cost compression in the economy tier intensifies because Polish and Romanian distributors favor stripped-down electrochemical units. Manufacturing buyers show least price sensitivity due to bundled sensor-as-a-service contracts, while residential channels compete on retail shelf positioning.
Supply Chain Analysis
Germanium and lead selenide detector substrate supply rests on limited European domestic sourcing, with infrared sensor manufacturing drawing from South African and Russian platinum-group metal export channels. Palladium electrode inputs, CMOS-compatible silicon photonics wafers, and tin dioxide semiconductor films anchor raw material dependencies. Single-source vulnerability concentrates in specialty photonics foundry capacity for chip-scale spectroscopy devices. Distribution runs through industrial automation distributors consolidating procurement for Rhine-Ruhr chemical operators, displacing direct manufacturer relationships for standard detection products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Gas Sensors Market functions as a regulatory compounder where REACH material disclosure and F-Gas phasedown mandates create successive demand waves for validated detection platforms across industrial and environmental verticals.
For Market Incumbents: Extend calibration service infrastructure to capture recurring revenue from drift-prone electrochemical sensor fleets, while deepening backward integration into Swiss and German MEMS foundry capacity to offset palladium cost volatility. Silicon photonics startups threaten discrete optical bench margins; certification investment in EU AI Act CE marking pathways for embedded decision algorithms defends premium positioning against intelligent sensing entrants. For New Entrants and Emerging Players: The EU AI Act in France and Germany opens a window for machine-learning-enabled detection platforms requiring notified body accreditation, creating compliance differentiation against legacy analog suppliers. Poland's greenfield chemical corridor presents the most penetrable geography for integrated gas detection systems without legacy distributed control system integration friction. A sensor-as-a-service go-to-market angle bundles hardware, predictive analytics, and certified calibration to bypass capital expenditure approval cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among analog-centric sensor fabricators lacking IoT platform architecture, as digital enablement premiums concentrate in edge-computing and photonics specialists. Long-term viability over the next decade hinges on regulatory compliance automation and predictive maintenance service attachment rates. Watch ECHA substance restriction proposals as the critical inflection signal for multi-year platform design commitments and acceptable sensing material pivots.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Foundry Capacity | Swiss wafer fabrication secures cost advantages for high-volume environmental sensor production. |
| EU AI Act CE Marking Pathway | French and German notified body accreditation differentiates intelligent sensing platforms in safety-critical applications. |
| Sensor-as-a-Service Contract Model | German chemical operators bundle hardware, calibration, and predictive analytics through industrial automation distributors. |
| Silicon Photonics Platform Qualification | Dutch foundry partnerships enable chip-scale spectroscopy integration for next-generation automotive HVAC systems. |
| LoRaWAN Network Infrastructure Partnership | French environmental agencies deploy distributed methane monitoring for landfill perimeter surveillance. |
Research Methodology
Coverage spans Western Europe and Central Europe, with primary inputs from each region combining interviews with plant engineers, industrial automation procurement leads, calibration service technicians, and regulatory affairs directors at sensor manufacturers. Secondary validation draws from ECHA substance restriction proposals, EU F-Gas Regulation implementation timelines, ATEX certification databases, and SEC filings from listed industrial conglomerates. Bottom-up sensor deployment estimates triangulate against top-down industrial safety spending patterns across chemical, pharmaceutical, and oil and gas verticals.
Granularity-level modeling captures technology segmentation across analog, wireless, IoT-based, and smart sensing architectures, with application splits across industrial safety, environmental monitoring, home automation, and automotive diagnostics. End-user disaggregation tracks manufacturing, oil and gas, healthcare, and residential procurement sophistication gaps. CAGRs derive from replacement cycle compression under regulatory mandates and volume expansion in distributed sensor networks, with inputs from palladium price volatility indices and foundry capacity utilization rates.
Revisions become necessary when ECHA substance restrictions reshape acceptable sensing materials, platinum-group metal export disruptions alter electrode economics, or notified body accreditation bottlenecks delay EU AI Act compliance timelines. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Light Detection and Ranging (Lidar) Market
Sensors and Controls
Non-Contact Infrared Thermometer Market
Sensors and Controls
Underwater Ultrasonic Sensor Market
Sensors and Controls
Piezoelectric Materials Market
Sensors and Controls
Air Quality Monitoring System Market
Sensors and Controls
Global Single Loop Controller Market
Sensors and Controls
Middle East and Africa Pressure Sensors Market
Sensors and Controls
Meteorological Devices Market
Sensors and Controls
Wearable Temperature Sensors Market
Sensors and Controls
RET Controller Market
Sensors and Controls
ECG Sensor Market
Sensors and Controls
Biomedical Pressure Sensors Market
Sensors and Controls
Mass Flow Controller Market
Sensors and Controls
Global Tilt Sensor Market
Sensors and Controls
Europe Wireless Sensors Market
Sensors and Controls
France Air Purifier Market