
 Europe Switchgear Market | 2026-2036
Europe Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Switchgear Market Foresight
Digital substation architecture with IEC 61850 protocol integration is tilting procurement criteria toward intelligent, communicative switchgear platforms. ABB Ltd. leverages its software-embedded breaker portfolios to anchor premium positioning in Nordic retrofit programs. Siemens AG sustains manufacturing scale across its German and Austrian facilities, competing on delivery reliability for large utility tenders. Schneider Electric differentiates through EcoStruxure-connected switchgear, occupying the commercial and industrial microgrid segment with cloud-native asset management.
Switchgear comprises electrical apparatus designed to control, protect, and isolate power circuits, typically rated by voltage class from low-voltage panels below 1 kV to high-voltage assemblies exceeding 36 kV, with insulating media ranging from air and vacuum to sulfur hexafluoride alternatives. Its primary purpose is ensuring grid stability, personnel safety, and operational continuity across generation, transmission, and distribution networks. Medium voltage switchgear carries the deepest margin pools in Europe, driven by offshore wind interconnection and urban ring-main upgrades where space constraints favor gas-insulated and hybrid technologies. Vacuum interruption technology leads new installations due to F-Gas phase-down mandates, while air-insulated variants retain cost advantages in rural utility applications with lower switching frequency requirements.
The EU F-Gas Regulation and ECHA restrictions on fluorinated greenhouse gases are forcing manufacturers to accelerate SF6-free insulation development, reshaping R&D allocation across European engineering centers. CE marking under the Low Voltage Directive and Medium Voltage Directive governs market access, with notified bodies in Germany, France, and Italy conducting conformity assessments that create differentiated compliance burdens. Stakeholders must monitor the trajectory of delegated acts under the EU Green Deal's industrial decarbonization package, as carbon-border adjustments and embodied-carbon disclosure rules will soon filter into switchgear procurement specifications.
Market Dynamics
The EU F-Gas Regulation is compressing SF6-dependent product lifecycles while accelerating vacuum and air-insulated alternatives across European utility procurement specifications.
Growth Catalysts
- Offshore wind interconnection mandates:Germany and Denmark require 66 kV ring-main units for North Sea converter stations, pulling gas-insulated switchgear into harbor substations.
- EU Green Deal industrial decarbonization package:Carbon-border adjustment mechanisms are embedding embodied-carbon thresholds into utility tender evaluations.
- Urban space constraints:London, Paris, and Milan distribution networks favor compact hybrid switchgear for underground vault installations where air-insulated footprints fail.
Market Restraints
- Copper and aluminum price volatility:Busbar material costs swing with LME commodity indices, compressing margin predictability for panel builders.
- SF6 gas supply concentration:Three European chemical conglomerates control fluorinated gas production, creating input bottlenecks during regulatory quota periods.
- Vacuum interrupter ceramic sealing limitations:Current brazing technologies cap production throughput for 24 kV and 36 kV ratings.
Strategic Opportunities
- Polish and Romanian grid modernization:EU cohesion funds are financing 110 kV substation rebuilds where air-insulated switchgear retains cost advantages.
- Digital twin integration:IEC 61850-9-2LE process bus architectures enable predictive maintenance contracts with industrial microgrid operators.
- F-Gas quota trading mechanisms:Early SF6-free product certification creates transferable compliance credits for manufacturers with advanced R&D pipelines.
Industry Challenges
- Medium-voltage protection engineering talent scarcity:European universities graduate fewer relay setting specialists than utilities require for digital substation commissioning.
- CE marking timeline compression:Notified body backlogs in Germany and France extend Low Voltage Directive conformity assessments by eight to fourteen months.
- Legacy electromechanical protocol integration:IEC 61850 migration requires parallel running costs during brownfield substation retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Switchgear Market |
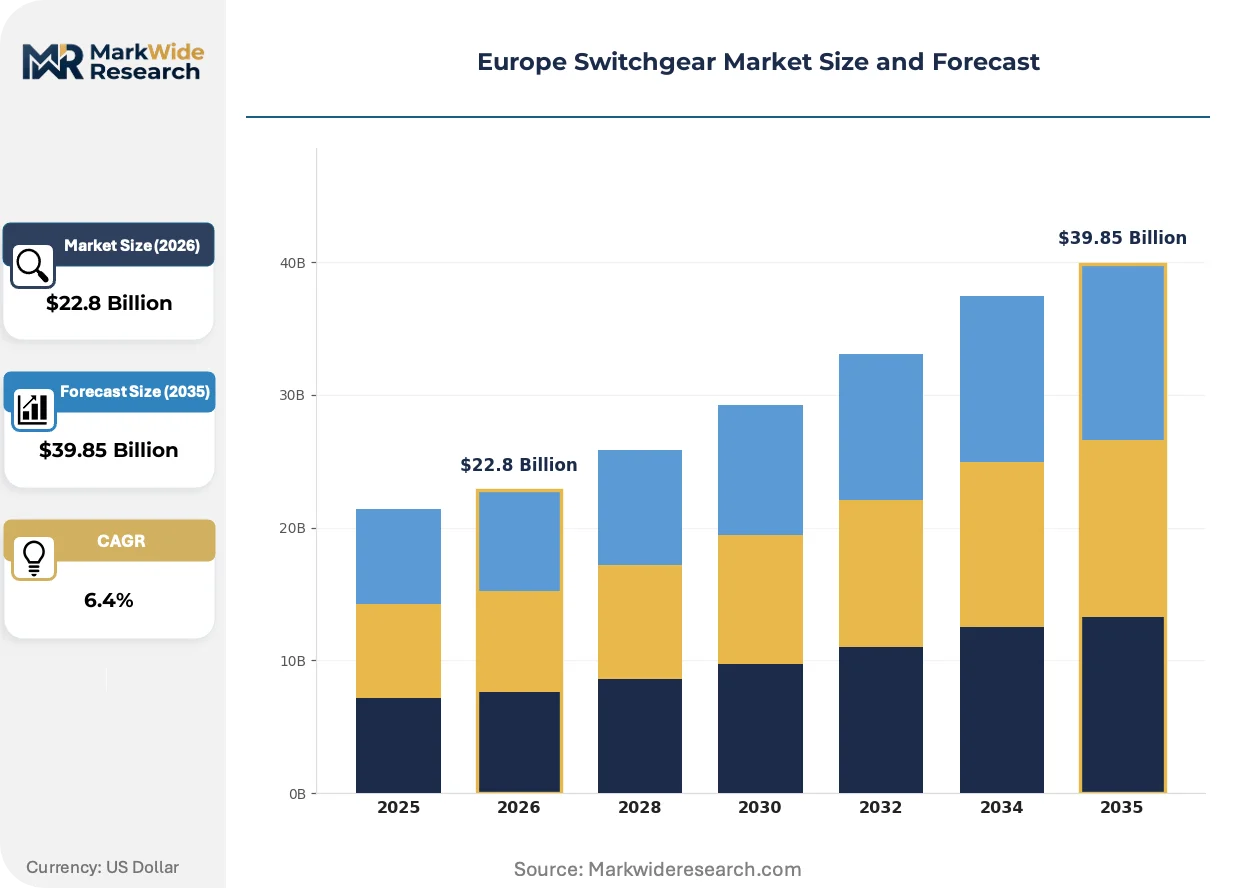
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $39.85 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medium Voltage, Low Voltage, High Voltage, Miniature Technology: Air Insulated, Gas Insulated, Hybrid, Vacuum End User: Utilities, Industrial, Commercial, Residential Installation: Outdoor, Indoor, Portable, Fixed |
| Companies Covered | Eaton Corporation, Hitachi Ltd., ABB Ltd., Mitsubishi Electric Corporation, Rockwell Automation, Siemens AG, Honeywell International, Toshiba Corporation, Schneider Electric, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Switchgear Market Shifts & Advancements
Switchgear architecture is bifurcating between premium intelligent platforms and cost-optimized passive units as procurement criteria harden around lifecycle carbon metrics and remote operability.
Vacuum interruption technology is migrating from distribution utilities into offshore wind collector platforms. Danish and German North Sea developers specify 36 kV vacuum circuit breakers for turbine transformer protection, displacing SF6-insulated alternatives before F-Gas phase-down deadlines. This migration is compressing R&D timelines for ceramic envelope designs rated for saline atmospheres.
The EU F-Gas Regulation delegated acts are tightening SF6 leak-rate thresholds and mandatory recycling quotas. Manufacturers must redesign gas handling procedures and training protocols for field service teams. Medium-voltage original equipment manufacturers in Germany and Austria face the steepest compliance curves due to their historical dependence on gas-insulated product lines.
Utility procurement departments are unbundling switchgear supply from installation and commissioning contracts. French and Spanish distribution system operators now tender equipment and integration separately, compressing vendor margins while opening channels for specialized system integrators. This unbundling is most visible in urban ring-main unit deployments where civil works complexity exceeds electrical engineering scope.
Europe Switchgear Market Segmentation
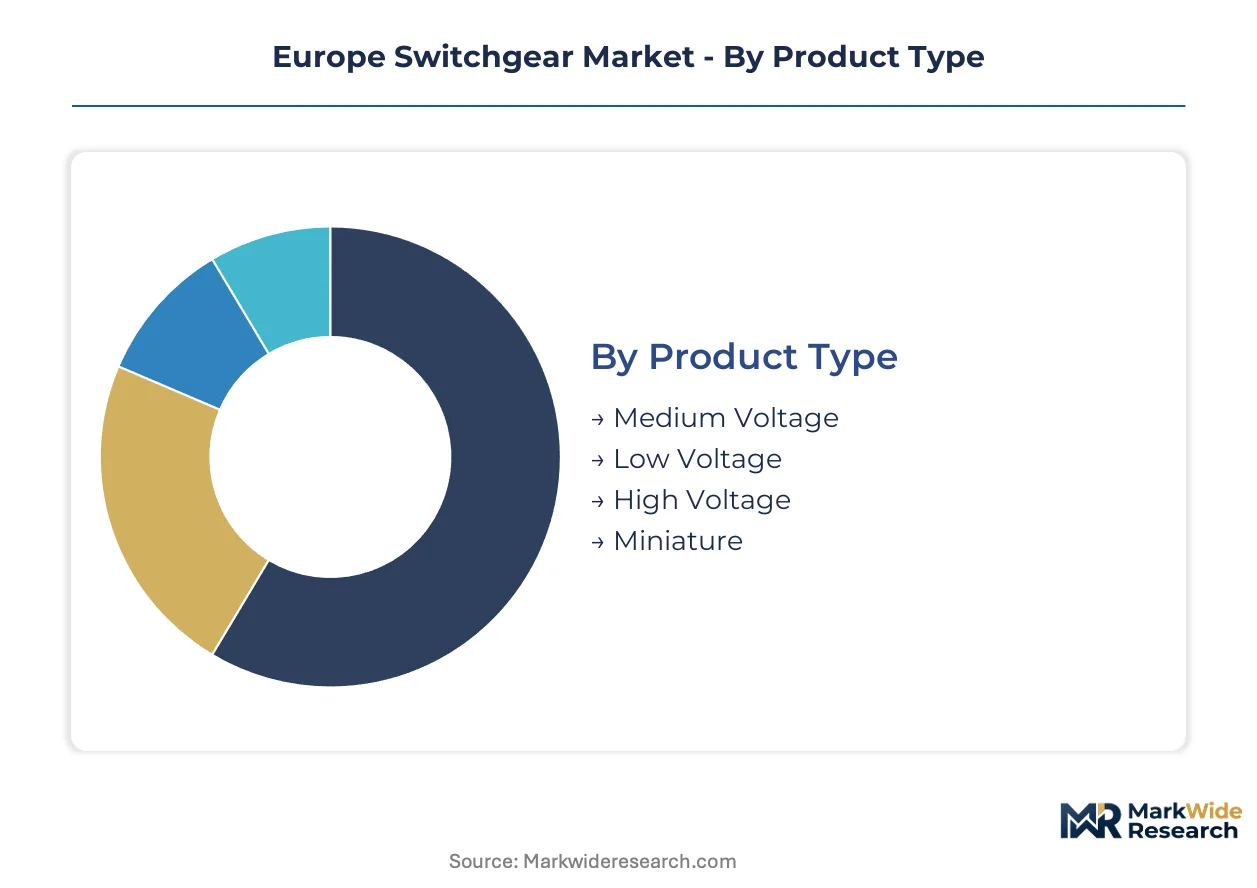
Switchgear procurement across Europe fragments across voltage classes, insulation technologies, and deployment contexts that each carry distinct margin structures and compliance burdens. Understanding these segment boundaries clarifies where F-Gas Regulation pressures concentrate and where digital substation investments yield differentiation.
Product Type:
Cost tier segmentation separates capital-intensive infrastructure investments from standardized panel replacements, with voltage rating directly correlating to engineering complexity and project duration.
- Medium Voltage:Assemblies rated 1 kV to 36 kV dominate utility and industrial procurement, integrating vacuum interrupters and gas-insulated compartments for ring-main units and substation feeders. German North Sea offshore wind interconnection mandates pull 66 kV variants into harbor substations, compressing delivery timelines for specialized manufacturers.
- Low Voltage:Panels below 1 kV serve building distribution and motor control centers with standardized IEC 61439 compliance. French and Spanish commercial construction markets favor modular withdrawable designs for data center and hospital applications where uptime guarantees dominate procurement scoring.
- High Voltage:Installations exceeding 36 kV require site-specific engineering for transmission substations and grid interconnectors.
- Miniature:Compact units address residential and small commercial load centers with cost-optimized thermal-magnetic protection.
Medium voltage commands the established base. The steepest expansion runs through low voltage as building electrification and EV charging infrastructure multiply distribution endpoints.
Technology:
Insulation medium selection increasingly reflects regulatory trajectory rather than pure technical optimization, with F-Gas quotas redrawing competitive boundaries between established and emerging approaches.
- Air Insulated:Open-contact designs with ambient air dielectric retain first-cost advantages for rural utilities and Polish cohesion-funded substation rebuilds where switching frequency remains moderate. Bavarian and Romanian distribution operators specify these for 110 kV outdoor yards with ample site footprint.
- Vacuum:Ceramic-enclosed interrupters eliminate atmospheric dependence and enable maintenance-free operation across 20,000+ mechanical cycles. Danish and German North Sea developers now specify 36 kV vacuum circuit breakers for turbine transformer protection, displacing SF6 alternatives ahead of regulatory deadlines.
- Gas Insulated:SF6-based compact assemblies face shrinking procurement eligibility under tightening EU F-Gas Regulation delegated acts.
- Hybrid:Combined air and gas insulation addresses urban space constraints in London, Paris, and Milan underground vault installations.
Air insulated retains the installed base across rural and cohesion-funded infrastructure. Vacuum technology is gaining share fastest as offshore wind procurement specifications harden around SF6-free alternatives.
End User:
Customer type segmentation reveals divergent procurement sophistication, with utilities tendering on lifecycle cost and industrial buyers prioritizing integration speed and digital asset management.
- Utilities:Transmission and distribution system operators specify switchgear for grid stability, renewable interconnection, and outage management. German utilities anchor regional demand through industrial corridor modernization programs and offshore wind collector platform specifications.
- Industrial:Manufacturing, mining, and process industries require arc-flash rated assemblies with IEC 61850 process bus integration for predictive maintenance contracts. Nordic pulp and paper facilities drive retrofit demand for intelligent, communicative platforms.
- Commercial:Office, retail, and hospitality developers specify standardized low-voltage panels with space-efficient footprints.
- Residential:Multi-unit housing and single-family construction rely on miniature and compact low-voltage distribution boards.
Utilities command the established base. Industrial microgrid deployments are expanding most quickly as on-site generation and storage integration demands intelligent protection coordination.
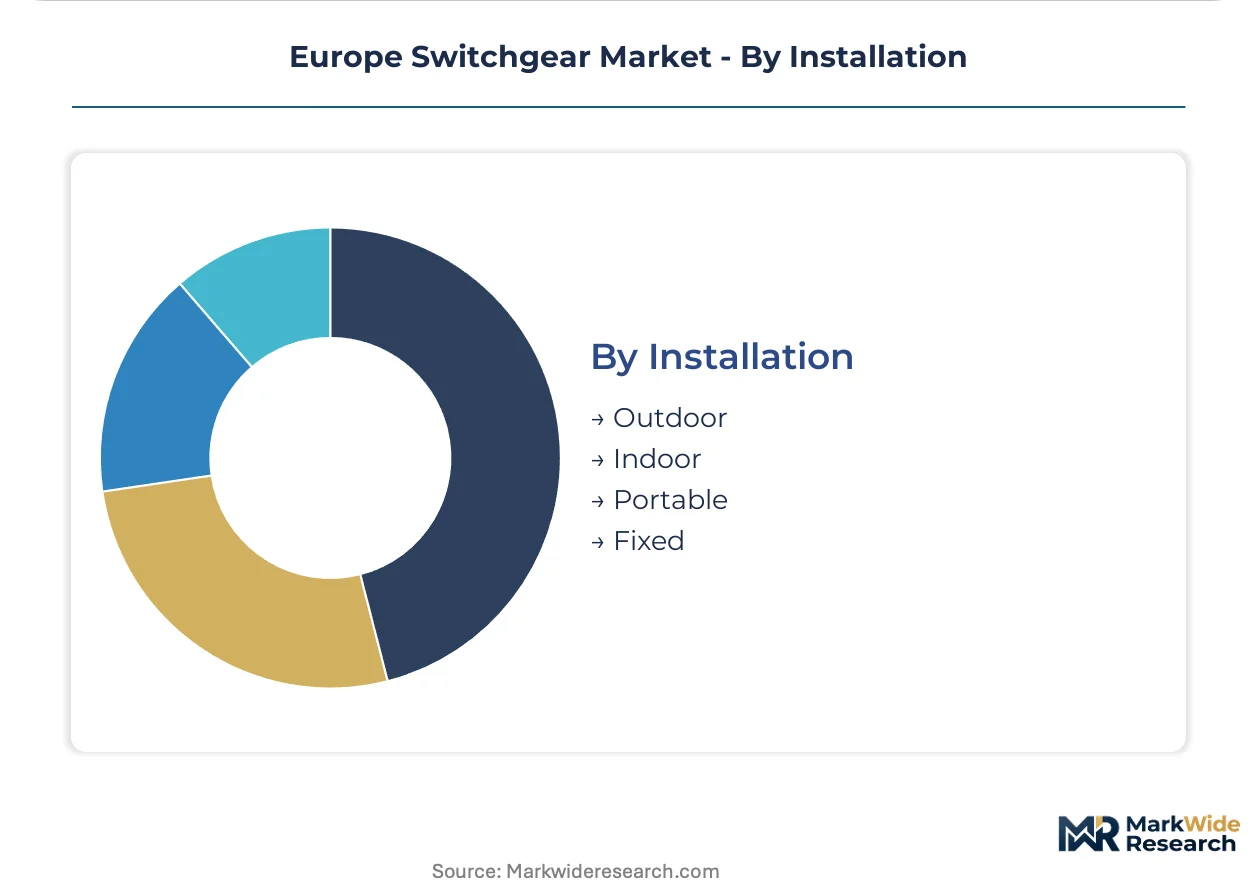
Installation:
Deployment context determines environmental hardening requirements and civil engineering scope, with fixed outdoor installations carrying the longest asset lifecycles and most complex foundation work.
- Indoor:Controlled-environment installations in substation buildings and industrial facilities enable standard IP ratings and simplified maintenance access. German automotive manufacturing campuses and Dutch greenhouse complexes favor these for medium-voltage distribution halls.
- Outdoor:Weather-hardened assemblies withstand temperature cycling, precipitation, and pollution for transmission substations and rural distribution. Austrian alpine utilities and Finnish distribution operators specify these for remote 110 kV switching stations.
- Fixed:Permanent bolted or pad-mounted installations constitute the majority of grid infrastructure.
- Portable:Trailer-mounted or skid-based units address temporary construction power, emergency restoration, and event infrastructure.
Fixed outdoor commands the established base. Indoor installations are climbing the fastest as urban densification drives underground substation construction and industrial facility electrification intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German utilities anchor procurement volume through offshore wind interconnection mandates and industrial corridor electrification programs. French and Spanish distribution operators drive standardization around digital substation protocols. Nordic retrofit markets favor intelligent platforms with predictive maintenance integration.
Germany
North Sea offshore wind collector platforms demand 66 kV ring-main units for harbor substations. The EU F-Gas Regulation compresses SF6-dependent product lifecycles while accelerating vacuum alternatives. Bavarian distribution operators specify air-insulated switchgear for 110 kV outdoor yards with ample site footprint.
Denmark
Danish North Sea developers specify 36 kV vacuum circuit breakers for turbine transformer protection. ECHA restrictions on fluorinated greenhouse gases displace gas-insulated alternatives ahead of regulatory deadlines. Copenhagen-area harbor infrastructure concentrates procurement for converter station assemblies.
France
French distribution system operators unbundle switchgear supply from installation contracts, compressing vendor margins. CE marking under the Low Voltage Directive governs market access through notified bodies. Paris underground vault installations favor compact hybrid switchgear where air-insulated footprints fail.
Poland
EU cohesion funds finance 110 kV substation rebuilds where air-insulated switchgear retains cost advantages. The EU Green Deal's industrial decarbonization package embeds embodied-carbon thresholds into utility tender evaluations. Silesian industrial corridors drive medium-voltage demand for mining and heavy manufacturing electrification.
United Kingdom
London distribution networks favor compact hybrid switchgear for underground vault installations with severe space constraints. The UK regulator enforces F-Gas phase-down timelines parallel to EU delegated acts. Scottish offshore wind development pulls gas-insulated assemblies into North Sea converter platforms.
Europe Switchgear Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement tiers defined by voltage class and insulation technology. The vendor base clusters around three strategic archetypes: integrated electrical conglomerates with software-embedded portfolios, manufacturing-scale specialists competing on delivery reliability, and connectivity-focused platform providers occupying microgrid segments. Dominant competitive moves include portfolio diversification into SF6-free alternatives and geographic expansion through EU cohesion-funded infrastructure programs.
Within the integrated conglomerate tier, ABB Ltd., Siemens AG, and Schneider Electric exemplify divergent positioning strategies. ABB Ltd. anchors premium positioning in Nordic retrofit programs through software-embedded breaker portfolios. Siemens AG occupies the manufacturing-scale archetype with sustained production across German and Austrian facilities. Schneider Electric represents the connectivity-focused vector through cloud-native asset management platforms serving commercial and industrial microgrid deployments.
| Leading Market Players |
|---|
| Eaton Corporation |
| Hitachi Ltd. |
| ABB Ltd. |
| Mitsubishi Electric Corporation |
| Rockwell Automation |
| Siemens AG |
| Honeywell International |
| Toshiba Corporation |
| Schneider Electric |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine freight corridor's container rate volatility transmits directly into switchgear landed costs, amplifying price spreads between German-manufactured vacuum interrupters and Asian-sourced ceramic housings while compressing margins for distributors serving Polish and Romanian cohesion-funded projects.
Pricing Analysis
Cost-plus contracts indexed to LME copper and aluminum benchmarks dominate utility procurement, with busbar material pass-through clauses protecting panel builders from commodity swings. Price differentiation hinges on IEC 61850 certification tier and after-sales service bundling. Pricing pressure stems from unbundled installation contracts in France and Spain. Rural utilities in Poland exhibit highest price sensitivity; offshore wind developers in Germany and Denmark show lowest.
Supply Chain Analysis
Export controls on vacuum interrupter brazing equipment limit technology transfer to Chinese and Indian manufacturers, preserving European ceramic sealing advantages. Supply concentrates in Germany, Austria, and Switzerland for gas-insulated assemblies; vacuum interrupters draw from Czech and Slovak production hubs. Copper busbar, ceramic envelopes, and epoxy resin constitute critical inputs. Single-source vulnerability runs through three European chemical conglomerates controlling SF6 production. Distribution runs through authorized electrical wholesalers with regional stocking agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against solid-state circuit breaker technology, which threatens to displace electromechanical switchgear in data center and semiconductor fab applications before the end of the analysis window.
For Market Incumbents: Build certification moats around SF6-free product portfolios to preempt F-Gas Regulation compliance thresholds. Accelerate vacuum interrupter ceramic sealing capacity in Czech and Slovak facilities. Secure backward integration into copper busbar production to buffer LME volatility. Defend against solid-state circuit breaker entrants by anchoring predictive maintenance contracts with IEC 61850-9-2LE integration.
For New Entrants and Emerging Players: Polish distribution networks outside Silesian industrial corridors offer underpenetrated terrain for air-insulated switchgear specialists. Romanian 110 kV substation rebuilds financed by EU cohesion funds present white-space entry points. Target commercial microgrid operators in Nordic pulp and paper facilities with cloud-native asset management platforms. Partner with German engineering consultancies for digital substation commissioning credibility.
For Investors and Strategic Acquirers: Niche vacuum interrupter ceramic specialists with saline-atmosphere ratings represent the priority acquisition archetype. Long-term viability hinges on R&D pipelines delivering 66 kV vacuum alternatives before North Sea offshore wind procurement deadlines. Monitor ECHA delegated acts on F-Gas quota trading mechanisms as the inflection signal for compliance credit valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| SF6-Free Product Certification | ECHA F-Gas quota trading creates transferable compliance credits for early movers. |
| Vacuum Interrupter Capacity Expansion | Czech and Slovak ceramic sealing investments address 36 kV offshore wind demand. |
| Digital Twin Integration | IEC 61850-9-2LE architectures enable predictive maintenance contracts with microgrid operators. |
| Backward Integration into Copper Processing | In-house busbar production buffers LME volatility for German panel builders. |
| Cohesion Fund Project Partnerships | Polish and Romanian 110 kV rebuilds open channels for air-insulated specialists. |
Research Methodology
A spread of perspectives from utility planning officers, EPC contractors, switchgear procurement managers, and aftermarket service heads converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings, customs trade data, ECHA regulatory submissions, and F-Gas quota registries. Bottom-up project pipelines and top-down grid investment forecasts were triangulated to anchor volume estimates.
Demand-supply balance modeling across the projection horizon segmented by voltage class, insulation technology, end-user archetype, and installation context. CAGRs were derived from utility capital expenditure trajectories, offshore wind interconnection mandates, and industrial electrification programs. Forecast inputs incorporated EU Green Deal industrial decarbonization timelines and F-Gas Regulation delegated act implementation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese vacuum interrupter manufacturers would shift outcomes. Material shifts in ECHA F-Gas quota allocation or Rhine-Alpine logistics costs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
In-Wall Smart Switch Market
Switches
5G Solid State Switches Market
Switches
Canada Switch Gear Market
Switches
Japan Reed Sensors Switches Market
Switches
Panel Mounted Disconnect Switch Market
Switches
Matrix Switches Market
Switches
High-Voltage Disconnect Switch Market
Switches
Saudi Arabia Switchgear Market
Switches
Off-Road Machine Ruggedized Switch and Indicator Systems Market
Switches
Antenna Switch Module Market
Switches
North America Push Buttons & Signaling Devices Market
Switches
Miniature-Circuit Breaker Market
Switches
Global High Voltage Switchgear Market
Switches
South Korea Reed Sensors Switches Market
Switches
Oil Level Switches Market
Switches
Australia Switchgear Market