
 Matrix Switches Market | 2026-2036
Matrix Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Matrix Switches Market Analytics
Aftermarket service revenue is tilting toward firmware-managed remote diagnostics and predictive maintenance contracts. Extron Electronics leverages its North American channel density to sustain premium positioning in corporate AV deployments. Kramer Electronics anchors its competitive stance through in-house ASIC design for low-latency switching. National Instruments competes in test-and-measurement matrix configurations where precision routing determines instrument fidelity.
A matrix switch is an electronic routing device that connects multiple input signals to multiple outputs through a configurable crosspoint array, typically supporting bandwidth specifications from standard-definition baseband through 12G-SDI and HDMI 2.1 protocols. Its primary purpose is to enable flexible, non-blocking signal distribution across broadcast facilities, command centers, and enterprise AV environments without physical cable reconfiguration. IP-based technology is displacing legacy baseband infrastructure as broadcasters migrate to SMPTE ST 2110 and NMOS-compliant architectures. HDMI switches retain dominance in home theater and small-scale commercial installations where consumer-electronics compatibility governs purchasing decisions. AV matrix switches occupy the highest margin pool in enterprise and government verticals requiring redundant power supplies, redundant crosspoints, and centralized management platforms.
FCC Part 15 emissions standards, CE marking under the EU Electromagnetic Compatibility Directive, and China's GB 9254 radio disturbance limits collectively shape product certification requirements and market access timelines for matrix switch manufacturers. REACH substance restrictions and RoHS compliance obligations add material-cost and supply-chain complexity to PCB and connector sourcing decisions. Stakeholders must monitor convergence between broadcast IP standards and IT network security frameworks as signal-routing infrastructure becomes indistinguishable from enterprise data switching.
Market Dynamics
The migration from baseband SDI to IP-based routing infrastructure is collapsing traditional hardware refresh cycles and forcing vendors to rearchitect product roadmaps around software-defined signal management.
Growth Catalysts
- SMPTE ST 2110 adoption:Broadcast facilities in the United States are deploying NMOS-compliant architectures to enable uncompressed IP video transport, eliminating dedicated coaxial infrastructure.
- China's media infrastructure modernization:Domestic broadcasters and streaming platforms are upgrading control rooms with 12G-SDI and HDMI 2.1 matrix switches to support 4K/8K production workflows.
- FCC Part 15 emissions enforcement:Stricter electromagnetic compatibility testing is accelerating replacement of aging analog routing gear with certified digital matrix switches in North American installations.
Market Restraints
- ASIC supply concentration:Taiwan-based foundries dominate fabrication of low-latency switching chips, exposing vendors to geopolitical supply disruptions and extended lead times.
- Copper and rare earth input costs:PCB substrates and connector alloys face price volatility from mining output constraints and energy-intensive refining requirements.
- HDMI specification licensing:Proprietary HDCP and HDMI Forum certification fees add fixed cost burdens to consumer-facing switch products, compressing margins at volume tiers.
Strategic Opportunities
- Edge broadcast facilities in India:Regional news networks and OTT platforms require compact, fanless matrix switches for remote production trucks and temporary event infrastructure.
- Healthcare surgical integration:Hybrid operating rooms need medical-grade KVM matrix switches to route 4K endoscope feeds, imaging systems, and telepresence equipment through sterile field controls.
- EU Green Deal circularity mandates:REACH substance restrictions and WEEE directives are creating competitive openings for modular, field-upgradable switch architectures with replaceable crosspoint cards.
Industry Challenges
- IP/network engineering skill gaps:Broadcast technicians lack training in VLAN segmentation, PTP timing, and multicast routing required to troubleshoot ST 2110 installations.
- Legacy SDI interoperability:Hybrid facilities must maintain signal integrity across asynchronous boundary conversions between 3G-SDI sources and IP destinations, introducing latency and jitter management complexity.
- Certification timeline compression:CE marking under the EU Electromagnetic Compatibility Directive and China's GB 9254 radio disturbance testing require parallel submission tracks, straining regulatory affairs teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Matrix Switches Market |
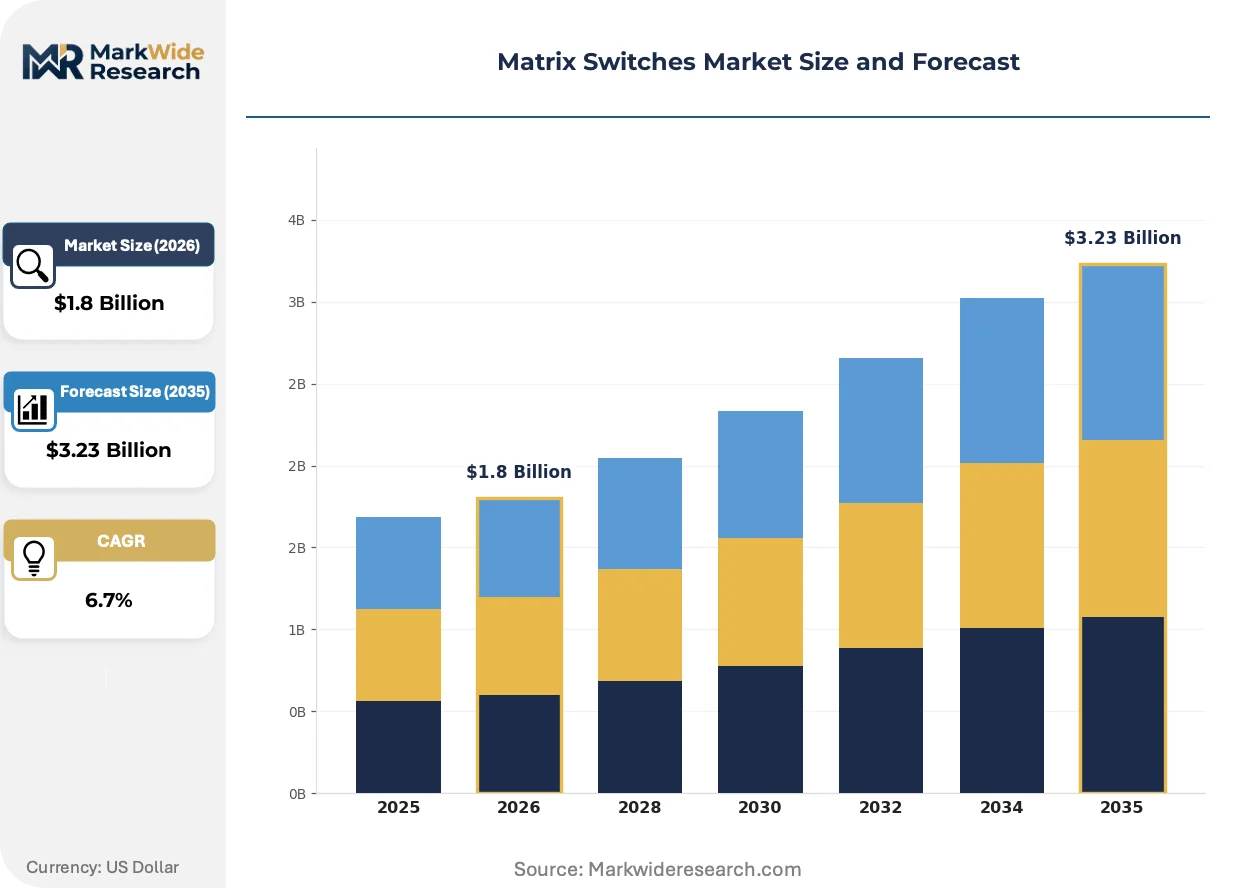
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HDMI Switches, AV Matrix Switches, Video Switchers, Audio Switchers Technology: Digital, Analog, IP-Based, Hybrid Application: Broadcasting, Corporate, Education, Home Theater End User: Telecommunications, Entertainment, Retail, Government |
| Companies Covered | Extron Electronics, Kramer Electronics, National Instruments, Black Box Corporation, ATEN International, Barco, AMX, JFW Industries, Keysight Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Matrix Switches Market Evolving Landscape
Signal routing infrastructure is converging with enterprise IT architectures, dissolving traditional boundaries between broadcast engineering and network operations centers. This fusion demands new competency models and procurement frameworks.
Software-defined video networking is collapsing the distinction between hardware matrix switches and virtualized routing instances. Cloud-native broadcasters and distributed production teams are adopting containerized signal processing on commodity servers. This architecture compresses capital requirements for facility buildouts while enabling elastic capacity scaling for live events.
REACH substance restrictions and RoHS compliance obligations are reshaping material selection for PCB assemblies and connector systems. European manufacturers face mandatory disclosure of hazardous substance content across supply chains. Asian component suppliers are accelerating halogen-free substrate development to maintain market access without redesign cycles.
Enterprise AV buyers are consolidating vendor relationships around unified management platforms rather than discrete hardware purchases. Corporate IT departments now specify matrix switches through network equipment procurement channels, favoring SNMP monitoring and REST API integration over standalone control interfaces. This pattern concentrates contract value with vendors offering centralized configuration tools.
Matrix Switches Market Segmentation
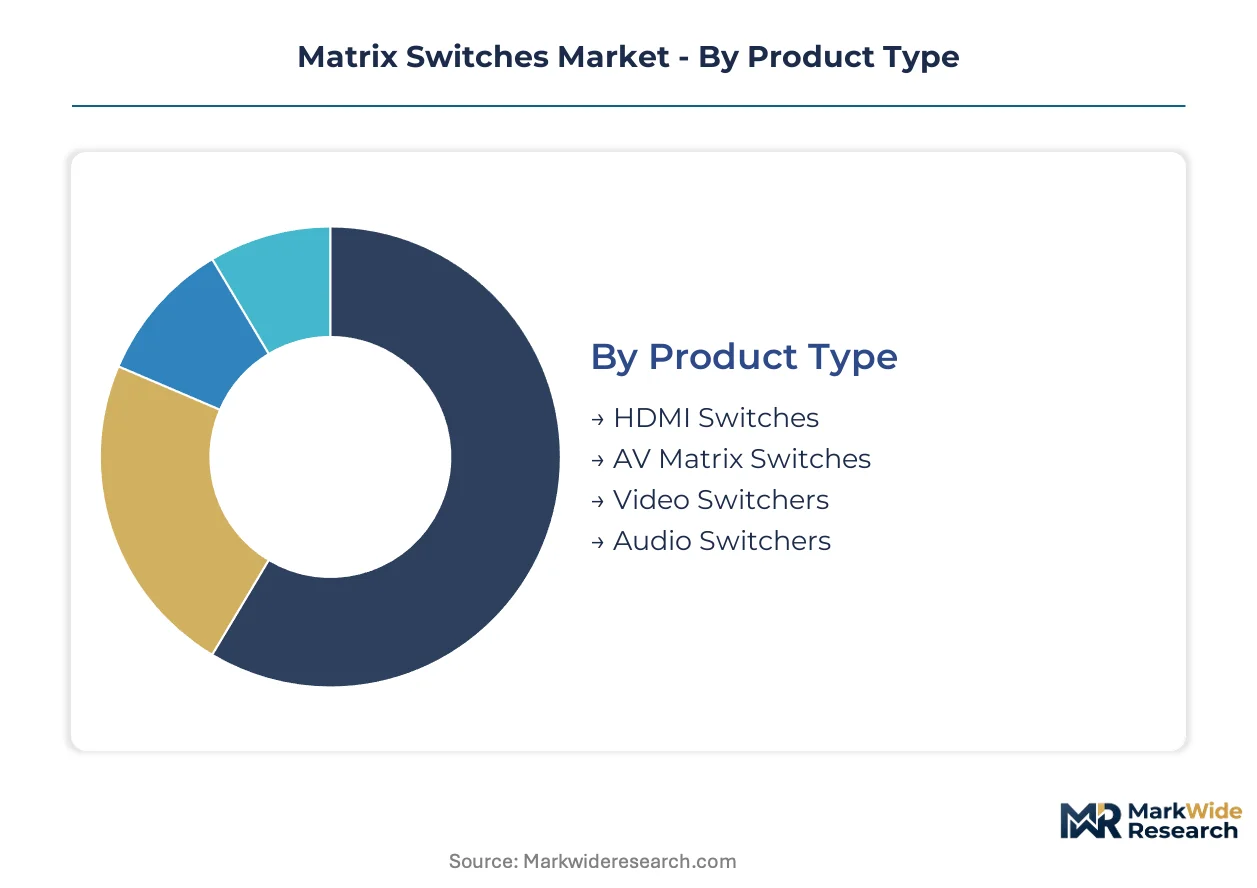
Matrix switch architectures fragment across signal formats, routing protocols, and installation environments. Procurement patterns diverge sharply between broadcast facilities demanding uncompressed IP transport and commercial integrators prioritizing plug-and-play HDMI interoperability.
Product Type:
Cost tier stratification separates consumer-grade HDMI switches from enterprise AV matrix switches carrying redundant power and crosspoint architectures.
- HDMI Switches:Consumer-electronics devices supporting HDCP 2.3 and HDMI 2.1 bandwidth specifications for 4K/120Hz and 8K/60Hz signal paths. Retail installations in the United States and European home theater markets drive volume procurement, constrained by HDMI Forum licensing fees that compress margins at entry price points.
- AV Matrix Switches:Enterprise-grade routing platforms with modular crosspoint cards, redundant power supplies, and centralized SNMP management. Corporate campuses and government command centers in Germany and Japan specify these systems for 24/7 operational continuity.
- Video Switchers:Production routing hardware for live event and broadcast facility signal management.
- Audio Switchers:Dedicated routing matrices for professional audio installations and DSP-integrated environments.
AV matrix switches command the established base. The steepest expansion runs through HDMI switches.
Technology:
Signal processing methodology determines interoperability boundaries, latency performance, and infrastructure upgrade trajectories across installation types.
- IP-Based:SMPTE ST 2110 and NMOS-compliant architectures enabling uncompressed video, audio, and metadata transport over standard Ethernet. Broadcasting facilities in the United States and United Kingdom deploy these systems to eliminate dedicated coaxial plant, though multicast routing complexity demands network engineering competencies scarce among traditional broadcast technicians.
- Digital:SDI and HDMI baseband switching with deterministic latency for synchronous production environments. China's domestic media infrastructure upgrades concentrate demand for 12G-SDI digital matrices supporting 4K/8K workflows.
- Analog:Legacy composite and component video routing for retained equipment compatibility.
- Hybrid:Boundary devices bridging asynchronous SDI sources to IP destinations with PTP timing and format conversion.
Digital architectures retain the installed base. IP-based platforms are climbing the fastest.
Application:
Environmental requirements dictate form factor, thermal design, and management interface specifications across deployment scenarios.
- Broadcasting:Control room and mobile production truck installations requiring non-blocking routing with frame-accurate switching. China's state broadcasters and India's regional news networks drive replacement cycles as FCC Part 15 and TRAI technical standards tighten electromagnetic compliance.
- Corporate:Conference room and digital signage integration demanding REST API compatibility with unified communications platforms. Enterprise IT procurement channels in the United States and Germany now specify matrix switches through network equipment vendor relationships.
- Education:Campus AV distribution for lecture capture and hybrid learning infrastructure.
- Home Theater:Residential entertainment routing prioritizing consumer-electronics compatibility and automated source switching.
Broadcasting applications anchor revenue concentration. Corporate deployments are gaining share fastest.
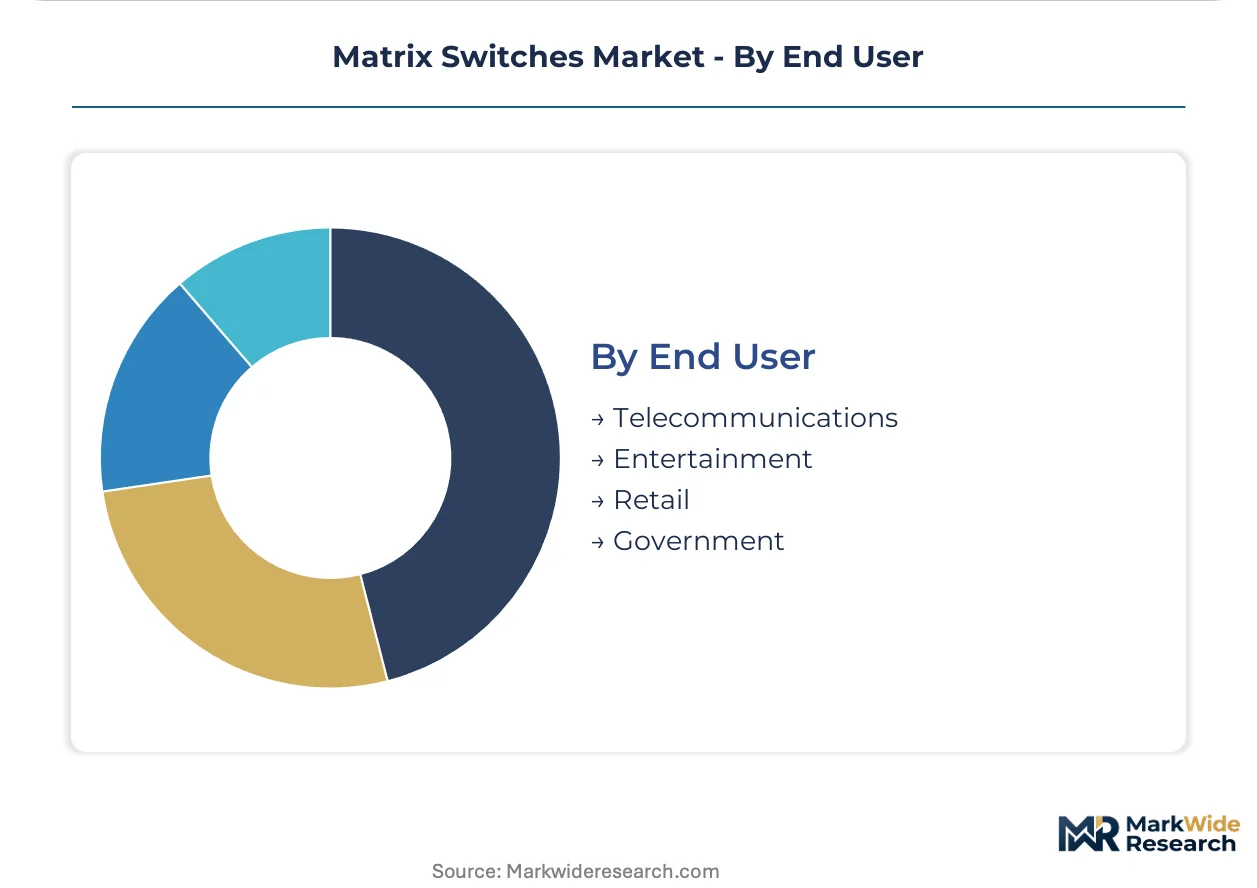
End User:
Customer procurement authority shapes pricing negotiations, service contract structures, and certification requirements.
- Telecommunications:Network operations centers and central office facilities requiring carrier-grade reliability with NEBS compliance and redundant controller architectures. Tier-1 operators in Japan and Germany specify these systems for video headend signal management.
- Entertainment:Streaming platforms, post-production houses, and live event producers routing uncompressed content. OTT broadcasters in India and Brazil deploy compact matrices for remote production infrastructure.
- Retail:Digital signage networks and customer experience installations with distributed content synchronization.
- Government:Secure facilities and command centers mandating TEMPEST shielding and domestic supply chain verification.
Telecommunications end users dominate contract value. Entertainment sector procurement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States broadcasters prioritize IP-based routing infrastructure for uncompressed video transport, while Chinese buyers concentrate procurement on 12G-SDI digital matrices for 4K/8K production workflows. European demand tilts toward modular, field-upgradable architectures compliant with circular economy mandates.
United States
FCC Part 15 emissions enforcement accelerates replacement of aging analog routing gear with certified digital matrix switches. ATSC standards and licensing frameworks push broadcasters toward compliant signal distribution architectures. Los Angeles and New York City control rooms drive rising adoption of SMPTE ST 2110 infrastructure for streaming platform integration.
China
Domestic media infrastructure upgrades concentrate demand for high-bandwidth switching platforms supporting 8K broadcast workflows. GB 9254 radio disturbance limits and MIIT certification requirements shape product development timelines. Beijing and Shanghai broadcast facilities anchor procurement volume as state media modernizes production capabilities.
Germany
Enterprise AV deployments in corporate campuses and government command centers specify redundant power and crosspoint architectures for 24/7 continuity. REACH substance restrictions and RoHS compliance obligations add material-cost complexity to PCB sourcing. Munich and Frankfurt industrial clusters concentrate systems integration expertise for mission-critical installations.
India
Regional news networks and OTT platforms require compact, fanless matrix switches for remote production trucks and temporary event infrastructure. TRAI technical standards tighten electromagnetic compliance requirements for broadcast equipment. Mumbai and Bengaluru media production hubs drive replacement cycles as streaming platforms expand original content operations.
Japan
Telecommunications network operations centers specify carrier-grade reliability with NEBS compliance for video headend signal management. METI industrial standards and JIS certification frameworks govern procurement specifications for Tier-1 operators. Tokyo and Osaka metropolitan areas concentrate demand for redundant controller architectures in central office facilities.
Matrix Switches Market Competitive Landscape
Capability concentration sits with specialized broadcast technology developers; scale advantage sits with diversified electronics conglomerates. The vendor base organizes around three tiers: premium-positioned specialists serving enterprise AV and government verticals, mid-market players competing on channel density, and volume manufacturers supplying consumer HDMI switches. Two dominant competitive moves are reshaping positioning: firmware-managed service contracts replacing hardware-centric revenue models, and in-house ASIC design for latency-sensitive switching applications.
Within the specialized broadcast tier, Extron Electronics and Kramer Electronics exemplify divergent strategic anchors. Extron leverages North American channel density to sustain premium positioning in corporate AV deployments. Kramer anchors its stance through proprietary semiconductor design capabilities for low-latency applications. National Instruments occupies a distinct test-and-measurement position where precision routing determines instrument fidelity. These three represent how technical specialization, geographic channel control, and vertical application focus create defensible market positions without direct confrontation.
| Leading Market Players |
|---|
| Extron Electronics |
| Kramer Electronics |
| National Instruments |
| Black Box Corporation |
| ATEN International |
| Barco |
| AMX |
| JFW Industries |
| Keysight Technologies |
| Others |
Value Network & Pricing Analysis
Taiwan-based foundry concentration for low-latency switching ASICs feeds directly into margin pool capture by vendors with captive semiconductor design capabilities. Buyers of enterprise AV matrix switches absorb premium pricing for redundant architectures, while HDMI switch margins compress under licensing fee burdens.
Pricing Analysis
Long-term service contracts with predictive maintenance clauses dominate enterprise procurement, displacing transactional hardware purchases. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in consumer HDMI tiers intensifies because HDCP and HDMI Forum licensing fees scale per-unit. Corporate IT buyers show lowest price sensitivity, prioritizing SNMP integration and REST API compatibility over unit cost.
Supply Chain Analysis
Copper substrate and rare earth connector alloys draw from mining operations concentrated in Chile, China, and Australia. PCB fabrication rests on halogen-free substrate development by Asian component suppliers responding to REACH substance restrictions. Single-source vulnerability sits with Taiwan-based foundries fabricating low-latency switching chips. Distribution runs through specialized AV integrators in North America and direct OEM relationships in European corporate campuses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of IP/network engineering talent capable of troubleshooting SMPTE ST 2110 multicast routing and PTP timing configurations constrains facility upgrade velocity. This capability gap creates asymmetric returns for vendors investing in training ecosystems and simplified management interfaces.
For Market Incumbents: Entrench position by deepening in-house ASIC design capabilities to reduce foundry dependency exposure. Expand firmware-managed remote diagnostics contracts to capture recurring revenue streams and raise switching costs against substitute software-defined routing platforms.
For New Entrants and Emerging Players: India's regional news networks and OTT platforms present underpenetrated demand for compact, fanless matrix switches in remote production trucks. Target healthcare surgical integration with medical-grade KVM matrices routing 4K endoscope feeds through sterile field controls. Lead with simplified NMOS-compliant architectures requiring minimal network engineering competency.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists with captive semiconductor design and established channel density in enterprise AV verticals. Long-term viability favors vendors bridging broadcast engineering and IT network operations competency models. Monitor convergence between broadcast IP standards and enterprise IT security frameworks as inflection signal for infrastructure procurement authority shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| In-house ASIC Design Investment | Reduces Taiwan foundry dependency and enables sub-microsecond latency differentiation in broadcast routing. |
| Firmware-Managed Service Contracts | Captures recurring revenue from predictive maintenance and remote diagnostics in corporate AV deployments. |
| NMOS Simplification Engineering | Lowers network engineering barriers for traditional broadcast technicians adopting ST 2110 infrastructure. |
| Healthcare KVM Certification | Opens hybrid operating room segment requiring sterile field control of 4K medical imaging routing. |
| EU Circularity-Compliant Modularity | Aligns product architecture with WEEE directives and REACH restrictions for sustainable market access. |
Research Methodology
Cross-validation between primary interviews with broadcast engineering directors, IT procurement officers, and systems integration specialists anchors the qualitative findings. Secondary validation draws from FCC equipment authorization databases, MIIT certification filings, SMPTE standards documentation, and hyperscaler capex disclosures for streaming infrastructure. Bottom-up triangulation across product-type demand curves and top-down macroeconomic calibration ensures segmentation integrity.
Calibration against historical replacement cycles in baseband SDI infrastructure and observed migration velocity to IP-based routing informs the analytical framework across the projection horizon. Segmentation dimensions span signal format, routing protocol, installation environment, and end-user procurement authority. CAGRs derive from elasticity-adjusted adoption curves and facility upgrade pipeline visibility.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified electronics conglomerates would shift outcomes. Quarterly review of foundry capacity allocations and broadcast IP standard certification timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Timer Switch Socket Market
Switches
5G Solid State Switches Market
Switches
Intelligent Power Switches Market
Switches
Temperature and Pressure Switches Market
Switches
United States Circuit Breaker Market
Switches
Fixed Switch Cabinet Market
Switches
High-Voltage Disconnect Switch Market
Switches
India Switchgear Market
Switches
Pad-Mounted Switchgear Market
Switches
North America MV Switchgear Market
Switches
Canada Switch Gear Market
Switches
Safety Limit Switches Market
Switches
DC Circuit Breaker Market
Switches
Power Load Switches Market
Switches
Haptic Feedback Switch and Button Platforms Market
Switches
Electromechanical Microwave Switch Market