
 Electric Switch Market | 2026-2036
Electric Switch Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Switch Market Analysis
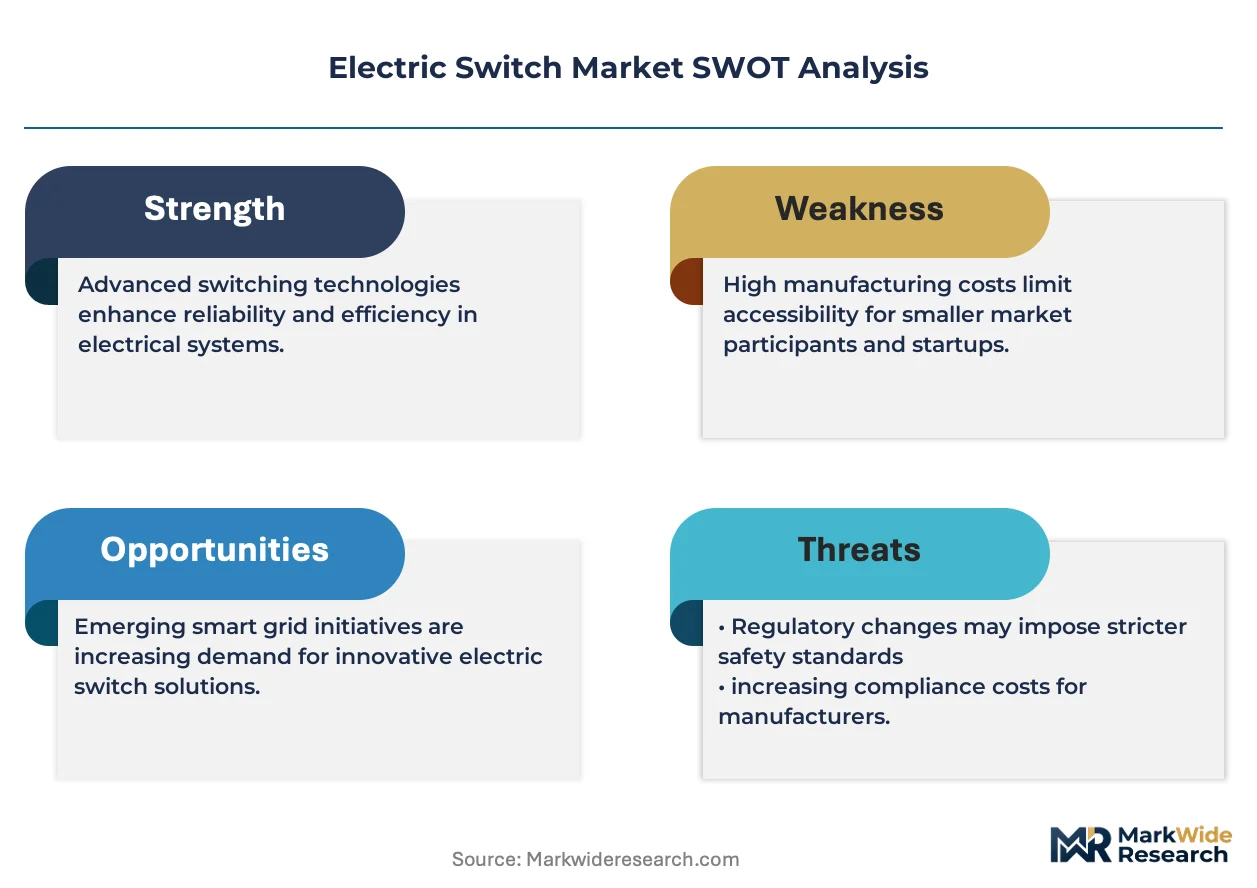
UL 916 certification for energy management equipment is unwinding the competitive set, forcing smaller suppliers to absorb testing costs or exit commercial building segments. Hubbell leverages its North American manufacturing footprint to sustain specification-grade product lines for electrical contractors. Omron competes through precision electronic switching portfolios that anchor its position in factory automation and process control applications.
An electric switch is an electromechanical device that opens or closes electrical circuits through physical actuation, typically rated for contact currents from milliamps to thousands of amperes depending on construction class. Its primary purpose is to enable safe, reliable control of power distribution and signal routing across residential, commercial, and industrial installations. Toggle switches occupy the largest revenue share in mature replacement markets where durability and cost predictability dominate procurement criteria. Smart switches represent the fastest-expanding technology segment as building management systems integrate IoT-enabled controls for lighting and HVAC loads.
The US Environmental Protection Agency enforces energy efficiency standards that shape demand for low-standby-power designs in residential and commercial switch categories. OSHA electrical safety regulations mandate specific disconnect and lockout capabilities that filter which products qualify for industrial maintenance applications. China's MIIT administers GB standards for electromagnetic compatibility that govern market access for imported electronic switching components. Stakeholders must monitor how evolving interoperability protocols between smart switches and building automation platforms reshape specification requirements and supplier qualification timelines.
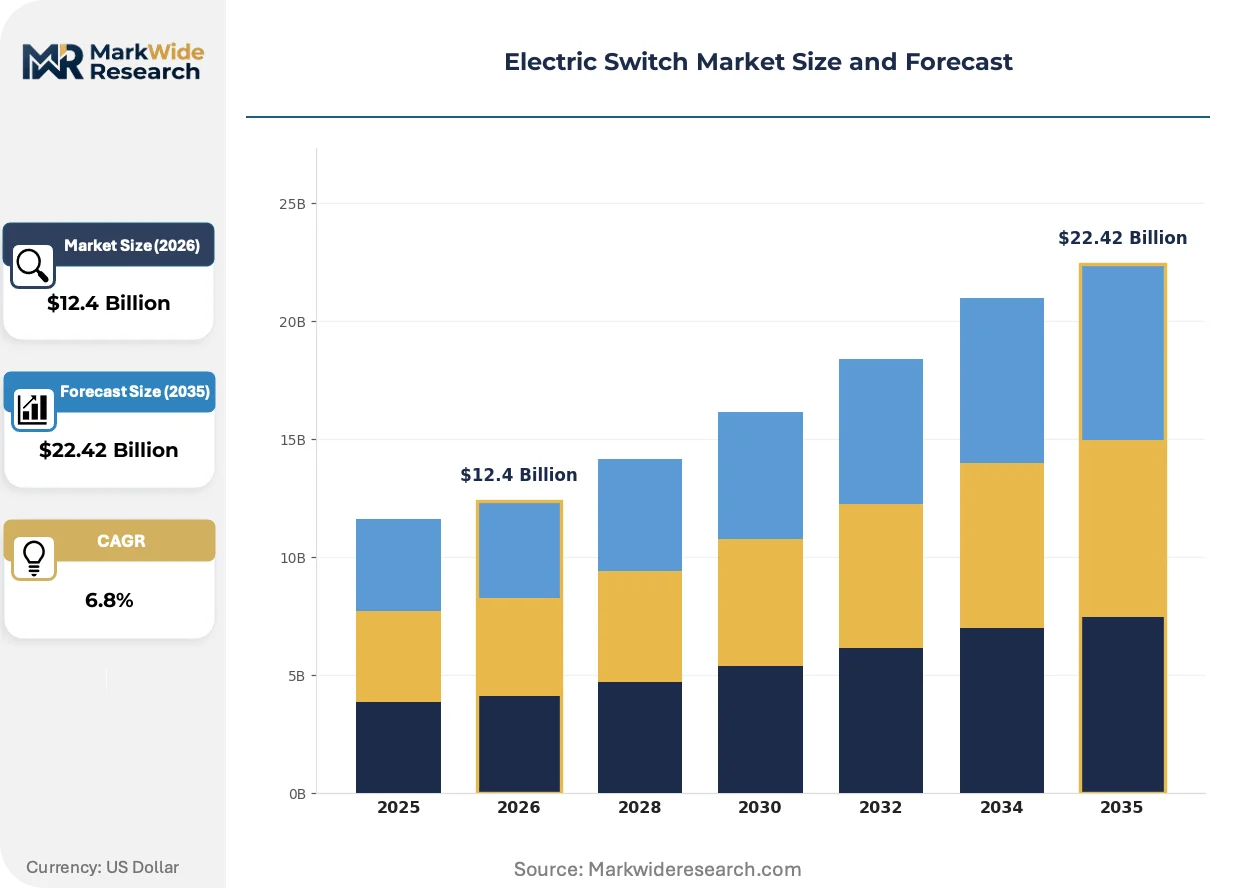
Market Dynamics
Smart building deployments are compressing specification cycles for connected switchgear, forcing suppliers to reconcile legacy electromechanical reliability with IoT interoperability demands.
Growth Catalysts
- IEC 60947 certification harmonization:Cross-border standard alignment is reducing duplicate testing burdens for industrial switchgear manufacturers supplying multiple jurisdictions.
- China grid expansion programs:State-backed infrastructure modernization is driving volume procurement of high-amperage switching components for transmission and distribution networks.
- Building management system integration:IoT-enabled lighting and HVAC controls are pulling smart switch adoption through specification-grade commercial real estate projects.
Market Restraints
- Copper and silver contact material volatility:Precious metal price swings compress margin predictability for electromechanical switch manufacturers locked into annual supply contracts.
- East Asian component concentration:Semiconductor shortages and logistics bottlenecks in Taiwan and South Korea constrain electronic switching module availability.
- UL 916 testing cost escalation:Energy management equipment certification fees are filtering smaller suppliers from commercial building segments.
Strategic Opportunities
- India industrial electrification:BIS standards alignment and CEA grid codes are opening specification pathways for imported switching equipment in factory automation.
- Wireless protocol convergence:Matter and Zigbee interoperability is enabling single-platform smart switch deployment across mixed-vendor building automation ecosystems.
- Retrofit channel development:Electrical contractor direct sourcing platforms are compressing traditional distribution layers in mature replacement markets.
Industry Challenges
- Embedded firmware talent scarcity:Smart switch development requires scarce expertise in real-time operating systems and cybersecurity hardening.
- Legacy system integration complexity:BACnet and Modbus protocol fragmentation forces custom gateway development for building automation retrofits.
- RoHS substance restriction compliance:Cadmium-free contact material qualification extends product development timelines for European market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Switch Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toggle Switches, Push Button Switches, Rotary Switches, Slide Switches Technology: Manual, Smart, Electronic, Mechanical Application: Residential, Commercial, Industrial, Automotive End User: Contractors, OEMs, Distributors, Maintenance Providers |
| Companies Covered | Hubbell, Amphenol Nexus Technologies, Incorporated, Clippard, STMicroelectronics, Omron, Electro-Mech Components, Inc., Osaka Automatic Electric Co., Ltd., Highly Electric Co., Ltd., OTTO Engineering, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Switch Market Emerging Trajectories
Solid-state switching technologies are displacing mechanical contacts in precision power control applications, while regulatory pressure on standby power consumption is reshaping residential product architectures.
Silicon carbide power semiconductors are miniaturizing thermal management requirements in high-frequency switching applications. Data center operators and electric vehicle charging infrastructure deployers are specifying these devices for reduced cooling overhead. The technology is miniaturizing enclosure footprints and enabling higher density panel configurations that mechanical contactors cannot match.
EPA energy efficiency standards for standby power are tightening permissible leakage current thresholds in residential and commercial switch categories. Manufacturers are redesigning power supply circuits and adopting zero-cross detection architectures to meet sub-watt consumption mandates. The regulatory pressure is accelerating displacement of legacy electromechanical designs in new construction specifications.
Electrical contractors are consolidating procurement through vertically integrated distributor platforms that bundle specification-grade switches with complementary wiring devices. Traditional wholesale channels face margin compression as contractor buying groups negotiate direct manufacturer relationships. This channel restructuring is most pronounced in North American commercial construction markets where specification lock-in determines project profitability.
Electric Switch Market Segmentation
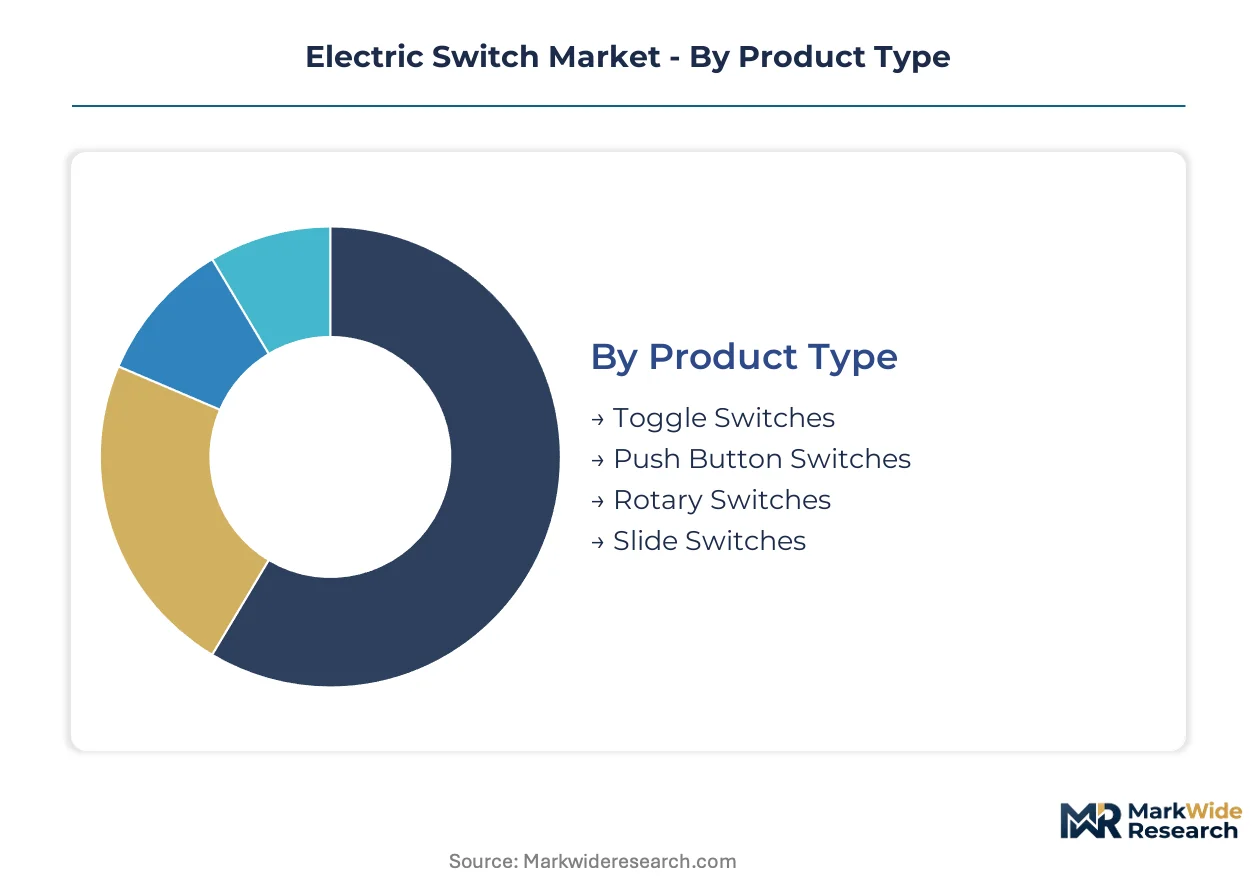
Segmentation in the electric switch market reveals how specification requirements diverge across installation environments and procurement channels. Procurement patterns for connected switchgear differ sharply between new construction and replacement cycles, while certification standards fragment addressable markets by end-use.
Product Type:
Margin pools concentrate in specification-grade electromechanical switches where durability premiums command contractor loyalty and repeat specification.
- Toggle Switches:Lever-actuated mechanisms with snap-action contact systems rated for residential through heavy-duty industrial loads. Demand concentrates in North American replacement markets where electrical contractors prioritize proven longevity over connected features, though smart home retrofits are compressing growth in new residential construction.
- Push Button Switches:Momentary or maintained contact devices with illuminated and non-illuminated variants for control panel and machinery interfaces. Factory automation in China's Yangtze River Delta and Germany's Baden-Württemberg region drives volume procurement, with IP67 sealing requirements filtering supplier qualification for outdoor and washdown applications.
- Rotary Switches:Multi-position selectors for circuit switching and control sequencing in industrial equipment. HVAC original equipment manufacturers in the US Midwest specify these for fan speed and mode selection.
- Slide Switches:Compact linear-actuation devices for consumer electronics and appliance subassemblies. East Asian contract manufacturers dominate procurement through vertically integrated supply relationships.
Toggle switches hold installed capacity. Push button switches are rotating up the share rankings.
Technology:
Technology segmentation tracks the displacement curve from electromechanical reliability toward semiconductor-enabled control precision.
- Smart:IoT-enabled devices with embedded radios, microcontrollers, and cloud connectivity for remote switching and energy monitoring. Commercial real estate developers in Singapore and Dubai specify these for LEED certification and operational efficiency dashboards, though BACnet protocol fragmentation complicates integration with legacy building management systems.
- Electronic:Solid-state switching using thyristors, IGBTs, and silicon carbide MOSFETs for zero-crossing and phase-angle control. Data center power distribution units and EV charging infrastructure in Norway and California deploy these for reduced thermal footprint and higher switching frequency.
- Manual:Direct human-actuated mechanisms without electronic intermediation. Residential electrical contractors in mature markets default to these for cost predictability in repair and remodel work.
- Mechanical:Spring-loaded contact assemblies with defined electrical and mechanical endurance ratings. Industrial maintenance providers in India's Maharashtra and Gujarat states specify these for lockout-tagout compliance and field serviceability.
Mechanical switches anchor current revenue. Electronic switching is climbing the fastest as power semiconductor costs decline.
Application:
Application segmentation maps how installation environment dictates certification burden, performance specification, and channel access.
- Industrial:Heavy-duty switching for motor control, power distribution, and process automation with IEC 60947 and UL 508 compliance requirements. State Grid Corporation of China's transmission expansion and manufacturing reshoring initiatives in Vietnam and Mexico concentrate demand for high-amperage contactors and disconnect switches.
- Commercial:Specification-grade devices for office, retail, and institutional buildings with energy management and occupancy integration. JLL and CBRE property management platforms in London, New York, and Sydney are standardizing on smart switch specifications for net-zero retrofit programs.
- Residential:Consumer-facing switches for lighting and small appliance control with UL 916 and equivalent EMC compliance. Big-box retail channels in the US and DIY chains in Germany and France dominate procurement, with Matter protocol adoption simplifying cross-brand interoperability.
- Automotive:Sealed, vibration-resistant switching for vehicle interior and powertrain applications. Tier-1 suppliers to Volkswagen Group, Toyota, and BYD manage qualification through IATF 16949-certified manufacturing footprints.
Industrial applications hold installed capacity. Commercial building automation is gaining share fastest.
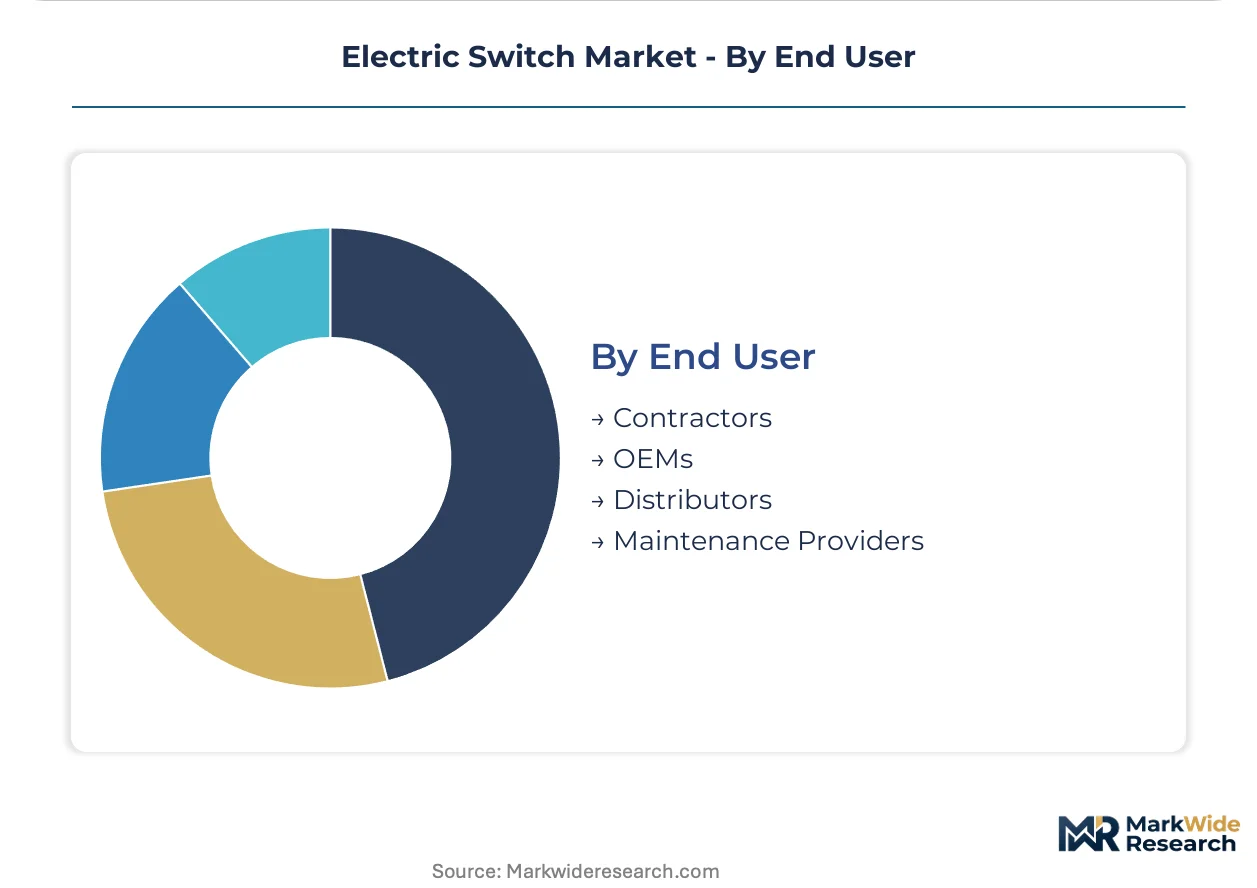
End User:
End user segmentation exposes how procurement authority and technical specification competence shape supplier relationships.
- OEMs:Original equipment manufacturers with captive engineering teams defining switch specifications for embedded integration. Appliance and HVAC equipment builders in South Korea's Gyeonggi Province and Italy's Lombardy region qualify suppliers through production part approval processes.
- Contractors:Electrical installation firms with specification influence in new construction and retrofit projects. Consolidated buying groups in Texas, Florida, and Ontario are negotiating direct manufacturer relationships, bypassing traditional distribution markups.
- Distributors:Inventory-carrying intermediaries with local technical support and same-day availability. Rexel and Wesco branches in France and Canada maintain specification-grade stock for emergency replacement.
- Maintenance Providers:Facility management and industrial service firms with reactive procurement patterns. Mining and oilfield operators in Western Australia and Alberta prioritize interchangeable footprints over brand loyalty.
Contractors hold installed capacity. OEM direct sourcing is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-backed infrastructure programs are redirecting procurement volumes toward Asia-Pacific manufacturing clusters while certification harmonization eases cross-border qualification for industrial switchgear suppliers.
China
State Grid Corporation transmission expansion and dual carbon grid modernization are driving volume procurement of high-amperage contactors. MIIT-administered GB standards for electromagnetic compatibility filter import access for electronic switching components. Yangtze River Delta factory automation clusters in Jiangsu and Zhejiang provinces specify precision push-button switches for machinery interfaces.
United States
Commercial real estate net-zero retrofit programs and data center power distribution expansion are accelerating smart switch specification. EPA energy efficiency standards for standby power reshape residential product architectures toward sub-watt consumption designs. Texas and Florida electrical contractor buying groups negotiate direct manufacturer relationships, bypassing traditional distribution markups.
Germany
Industrial electrification and factory automation reshoring initiatives concentrate demand for IEC 60947-compliant switchgear. REACH substance restrictions and RoHS cadmium-free mandates extend contact material qualification timelines for European market access. Baden-Württemberg automotive and machinery OEMs in Stuttgart industrial corridor specify sealed push-button switches for control panel integration.
India
CEA grid code alignment and BIS standards harmonization are opening specification pathways for imported industrial switching equipment. Maharashtra and Gujarat state manufacturing clusters specify mechanical lockout-tagout switches for maintenance compliance. Mining and oilfield operators in Western Australia prioritize interchangeable footprints over brand loyalty.
Japan
METI energy efficiency directives and building automation integration standards accelerate displacement of legacy electromechanical designs. JIS certification requirements maintain qualification barriers for foreign suppliers in precision electronic switching segments. Kanto region data center operators specify silicon carbide solid-state switches for reduced thermal footprint.
Electric Switch Market Vendor Landscape
Player mix skews toward diversified electromechanical specialists with captive manufacturing footprints and precision electronics fabricators serving factory automation. Market structure concentrates specification-grade revenue among North American and European incumbents with contractor channel relationships, while East Asian suppliers dominate volume production for consumer electronics subassemblies. Three archetypes anchor competitive positioning: vertically integrated electromechanical manufacturers, semiconductor-enabled switching specialists, and contract fabrication platforms serving appliance OEMs. Consolidation through distributor acquisition and backward integration into contact material supply chains represent dominant competitive moves.
Within the diversified electromechanical tier, Hubbell and Omron exemplify contrasting geographic and technological positioning. Hubbell occupies a North American manufacturing footprint serving electrical contractor specification channels. Omron anchors precision electronic switching portfolios for factory automation and process control applications. STMicroelectronics sits within the semiconductor-enabled archetype, supplying solid-state switching components for power management integration.
| Leading Market Players |
|---|
| Hubbell |
| Amphenol Nexus Technologies, Incorporated |
| Clippard |
| STMicroelectronics |
| Omron |
| Electro-Mech Components, Inc. |
| Osaka Automatic Electric Co., Ltd. |
| Highly Electric Co., Ltd. |
| OTTO Engineering, Inc. |
| Others |
Supply Flow & Price Mechanics
Sixteen-week lead times for IEC 60947-certified industrial contactors concentrate pricing power with Yangtze River Delta manufacturers, while copper and silver contact material volatility compresses margin predictability for electromechanical switch suppliers locked into annual procurement contracts.
Pricing Analysis
Certification level creates the primary spread between premium specification-grade and economy-tier products, with UL 916 energy management compliance adding testing cost premiums that filter smaller suppliers from commercial building segments. Three-tier pricing structure across specification-grade, contractor-grade, and retail-economy levels stratifies procurement channels, with electrical contractor buying groups in Texas and Florida negotiating direct manufacturer relationships that bypass traditional distribution markups. Cost compression in economy-tier residential switches intensifies because big-box retail channels consolidate procurement volumes, while OEM direct sourcing from appliance manufacturers in South Korea's Gyeonggi Province shows lowest price sensitivity due to production part approval process lock-in.
Supply Chain Analysis
Twenty-two-day inventory cycles for semiconductor-enabled switching modules expose vulnerability to Taiwan and South Korea fabrication constraints, with silicon carbide MOSFET availability particularly constrained for data center power distribution applications. East Asian component concentration in Jiangsu and Zhejiang provinces draws from copper contact material suppliers in Chile and silver refiners in Mexico, while logistics bottlenecks through Shanghai and Busan ports create single-source vulnerability for electronic switching module delivery. Distribution runs through vertically integrated distributor platforms like Rexel and Wesco branches that bundle specification-grade switches with complementary wiring devices for emergency replacement availability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrical contractor buying group consolidation across Texas, Florida, and Ontario shifts procurement leverage toward direct manufacturer negotiation, fragmenting traditional distribution channel control.
For Market Incumbents: Shield specification-grade revenue by deepening captive manufacturing footprints in North America to sustain UL 916 certification compliance without absorbing offshore logistics volatility. Prioritize backward integration into cadmium-free contact material supply chains to preempt REACH substance restriction compliance delays that extend European market access timelines for competitors. For New Entrants and Emerging Players: BIS standards fast-track alignment with CEA grid codes opens specification pathways for imported industrial switching equipment in Maharashtra and Gujarat state manufacturing clusters. Target India's factory automation retrofit segment through mechanical lockout-tagout switch offerings that prioritize field serviceability over smart connectivity, leveraging contractor-grade pricing acceptance in maintenance-provider procurement patterns. For Investors and Strategic Acquirers: Long-term, this sits as a semiconductor-electromechanical convergence play because solid-state switching technologies displace mechanical contacts in precision power control applications across data center and EV charging infrastructure deployment. Acquisition target archetype: precision electronics fabricators with silicon carbide MOSFET design capability and existing IATF 16949 automotive qualification. Monitor silicon carbide substrate capacity expansion announcements as inflection indicator for electronic switching cost curve acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment in UL 916 Compliance | Energy management equipment testing cost escalation filters competitive set in commercial building segments. |
| Backward Integration into Contact Material Supply | Cadmium-free contact qualification timelines shorten for REACH-compliant European market access. |
| Silicon Carbide Semiconductor Design Capability | Data center operators specify reduced thermal footprint switches for higher density panel configurations. |
| Direct Contractor Platform Development | Texas and Florida buying groups bypass traditional distribution markups through manufacturer relationships. |
| Wireless Protocol Convergence Investment | Matter and Zigbee interoperability enables single-platform deployment across mixed-vendor building automation ecosystems. |
Methodological Framework
Initial hypotheses were tested against primary input from electrical contractor specification managers, OEM procurement leads in appliance and HVAC equipment, distributor branch managers, and industrial maintenance directors, and refined through secondary validation against SEC 10-K filings, customs and trade data, IEC certification registries, and building automation integration protocol documentation. Bottom-up demand modeling triangulated with top-down macroeconomic factor assessment across the analysis window.
Variance decomposition across product type, technology platform, application environment, and end-user procurement authority anchored the analytical framework, with CAGRs derived from segment-level growth trajectory reconciliation against aggregate market expansion patterns. Forecast inputs incorporated copper and silver commodity price volatility assumptions, semiconductor fabrication capacity utilization trends, and regulatory harmonization timelines for IEC 60947 cross-border standard alignment.
Decision-makers should treat outputs as directional under assumptions of continued state-backed infrastructure modernization in China and sustained commercial real estate net-zero retrofit program momentum; material deviation in precious metal price trajectories or semiconductor supply chain normalization would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Electronic Shift-By-Wire Selector Modules Market
Switches
Touchpad Market
Switches
Cross Point Switch Market
Switches
South America Low Voltage Switchgear Market
Switches
Low Voltage Disconnect Switch Market
Switches
Saudi Arabia Switchgear Market
Switches
Asia-Pacific High Voltage Switchgear Market
Switches
Dual Power Transfer Switches Market
Switches
Oil Level Switches Market
Switches
Australia Switchgear Market
Switches
Level Switches Market
Switches
Global Float Level Switches Market
Switches
Carrier Router Switch Market
Switches
China Switchgear Market
Switches
Contactor-based Transfer Switch Market
Switches
Smart Circuit Breaker Market