
 Smart Dimmer Switch Market | 2026-2036
Smart Dimmer Switch Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Dimmer Switch Market Insights
Premium-grade load capacity ratings is bifurcating the competitive landscape as manufacturers race to support higher-wattage LED and incandescent configurations. Lutron leverages its proprietary Clear Connect RF protocol to sustain dominance in professional installation channels. TP-Link competes aggressively on price while extending its Kasa sub-brand into mass-market retail.
A smart dimmer switch is an electronically controlled wall-mounted device that modulates voltage amplitude to adjust light output intensity, typically supporting loads from 150 to 600 watts and integrating wireless transceivers for remote operation. Its primary commercial purpose is to reduce energy consumption and extend lamp lifespan while enabling automated lighting scenes through building management systems. Wi-Fi dimmers lead consumer awareness but Zigbee dimmers capture stronger margins through hub-based ecosystem lock-in. Phase-cut technology occupies the bulk of legacy retrofit volumes, though MOSFET-based designs are gaining traction for silent operation and broader LED compatibility.
FCC certification governs radio frequency emissions for all wireless dimmers sold in the United States, while the EU Radio Equipment Directive mandates CE marking and interoperability testing for products entering European markets. California Title 24 building energy codes directly shape product specification requirements by mandating dimming capability in new commercial and high-rise residential construction. Stakeholders must monitor evolving cybersecurity labeling requirements and protocol fragmentation risks as governments tighten connected device standards.
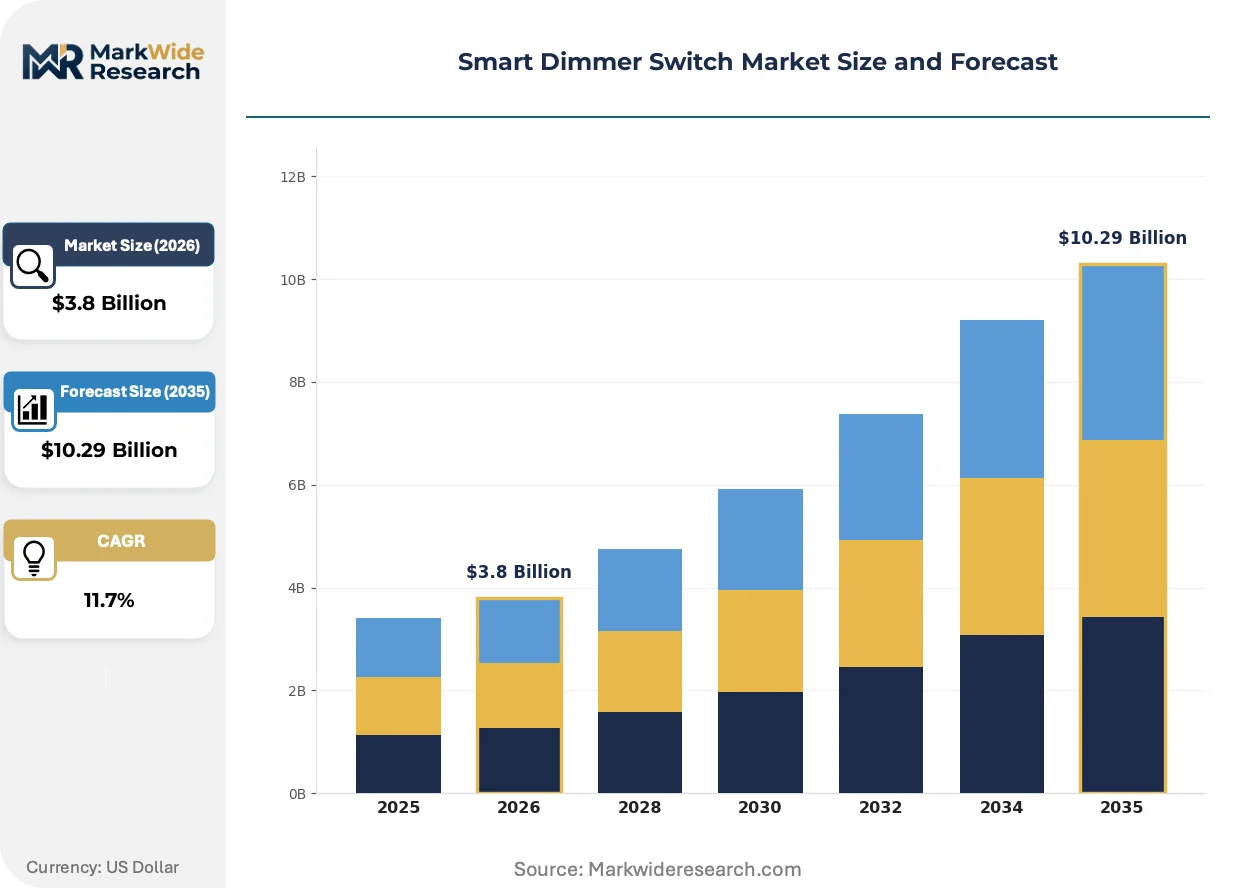
Market Dynamics
The smart dimmer switch market is restructuring around protocol convergence as Matter certification dissolves ecosystem silos that previously locked consumers into single-brand environments. This interoperability push is compressing hardware margins while expanding addressable market reach.
Growth Catalysts
- California Title 24 mandates:New commercial and high-rise residential construction in California must include dimming capability, creating specification pull-through for certified products.
- Utility rebate programs:United States electricity providers offer point-of-sale incentives for ENERGY STAR-qualified dimmers, reducing effective consumer price points.
- LED load proliferation:Residential and commercial building retrofits are replacing incandescent fixtures with dimmable LED arrays that require compatible control hardware.
Market Restraints
- Copper and semiconductor input volatility:MOSFET-based dimmer designs depend on stable pricing for power transistors and PCB substrates, exposing margins to commodity swings.
- Hub dependency for Zigbee protocols:Ecosystem lock-in requirements create friction for consumers unwilling to invest in bridge hardware alongside switch purchases.
- Phase-cut LED incompatibility:Legacy TRIAC dimming circuits produce flicker and reduced lifespan when paired with modern LED drivers, limiting retrofit applicability.
Strategic Opportunities
- India building electrification:Urban residential construction and smart city initiatives create first-mover advantage for Matter-certified entrants in an underpenetrated market.
- Commercial building management convergence:Integration of lighting controls with HVAC and security systems through BACnet and Modbus protocols opens specification channels.
- EU Green Deal renovation wave:Building efficiency mandates across member states prioritize lighting retrofits as lowest-capex decarbonization measures.
Industry Challenges
- FCC Part 15 certification timelines:Radio frequency emission testing for Wi-Fi and proprietary RF protocols extends product launch cycles by four to six months.
- Legacy electrical contractor skill gaps:Silent-operation MOSFET designs require different installation practices than familiar phase-cut products, slowing trade adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Dimmer Switch Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Remote Control Dimmer, Wi-Fi Dimmer, Zigbee Dimmer, Bluetooth Dimmer Technology: Phase Cut, Zero Crossing, MOSFET, TRIAC End User: Residential, Commercial, Industrial, Hospitality Installation Type: New Installation, Retrofit, DIY, Professional |
| Companies Covered | TP-Link, Kasa, Philips Hue, BESTTEN, Cloudy Bay, Lutron, GE, Maxxima, Leviton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Dimmer Switch Market Trends and Innovations
Wireless protocol unification is collapsing the technical barriers that once segmented the competitive landscape. Manufacturers are rearchitecting product roadmaps around certification stacks rather than proprietary ecosystems.
MOSFET-based dimming circuitry is decomposing the historical dominance of phase-cut TRIAC designs in residential retrofit applications. Custom home installers specify silent-operation silicon solutions for high-end LED installations where audible buzzing compromises occupant experience. The technology is decomposing price premiums previously commanded by specialty architectural dimming brands.
The EU Radio Equipment Directive now mandates interoperability testing and CE marking for all wireless lighting controls entering European markets. This regulatory friction is elevating compliance costs for smaller manufacturers while creating specification advantage for pre-certified product families. Germany and France are enforcing these requirements most stringently, with customs authorities blocking non-compliant shipments at ports.
Professional electrical contractors now specify dimmers through distributor digital platforms rather than traditional counter sales. Ferguson and Graybar are capturing specification influence by integrating compatibility databases and real-time inventory into their e-commerce interfaces. This channel migration is most advanced in United States metropolitan construction markets where project timelines compress procurement cycles.
Smart Dimmer Switch Market Segmentation
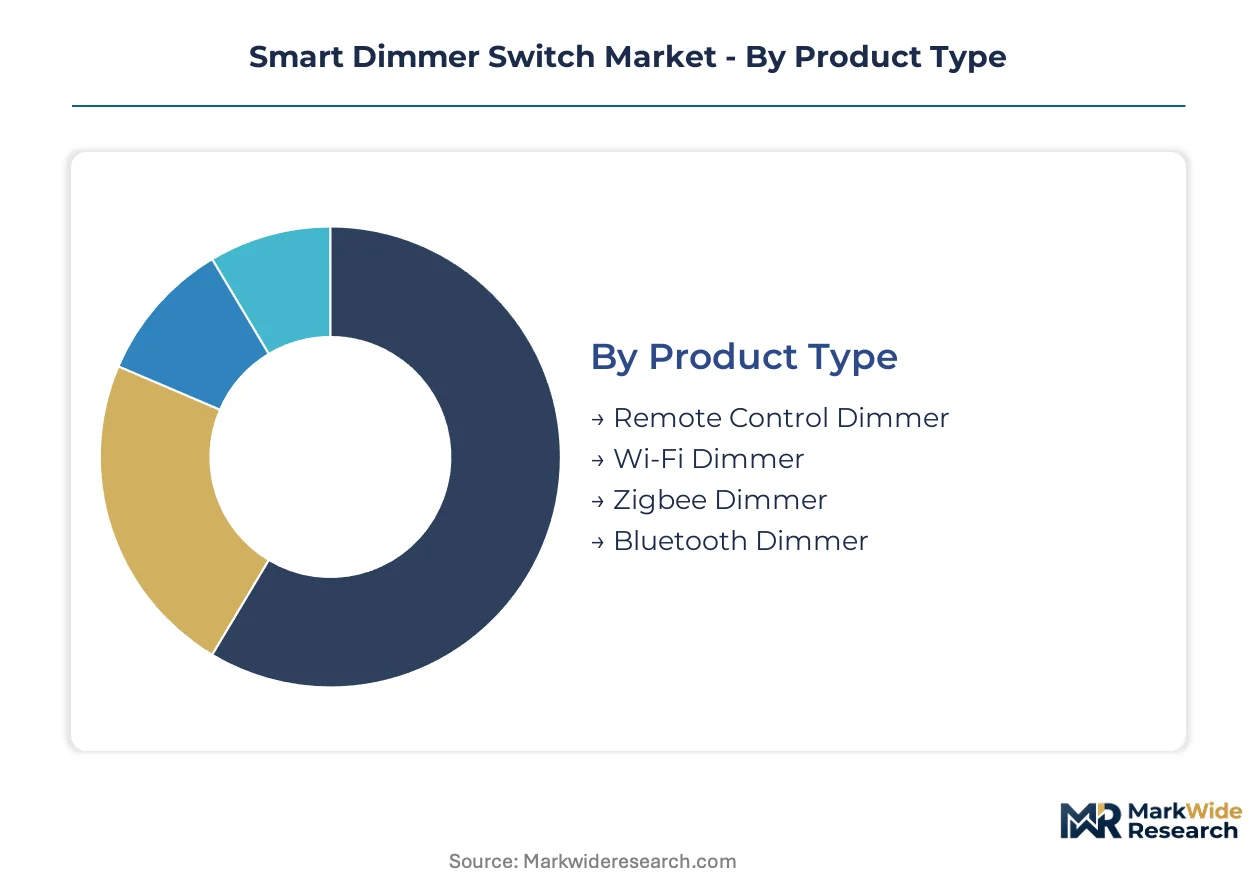
Smart dimmer switch segmentation reveals how protocol choices and installation contexts reshape procurement patterns across residential and commercial channels. Manufacturers calibrate certification investments and channel partnerships against the technical requirements and margin profiles of each segment cluster.
Product Type:
Wi-Fi dimmers dominate domestic retail volumes in the United States, while Zigbee variants anchor professional specification channels that export across European markets. Bluetooth dimmers concentrate in retrofit applications where hub-free operation appeals to cost-sensitive homeowners.
- Wi-Fi Dimmer:Direct router connectivity eliminates bridge hardware, reducing consumer friction in mass-market retail. Demand concentrates in United States big-box channels where TP-Link and similar brands compete on price point and smartphone app integration. FCC Part 15 certification timelines extend launch cycles, favoring established manufacturers with regulatory expertise.
- Zigbee Dimmer:Mesh networking enables whole-home scalability with lower per-device power consumption than Wi-Fi alternatives. Specification pull concentrates in California Title 24 commercial projects and European professional channels where Matter certification now dissolves ecosystem silos. Hub dependency creates margin compression at entry price points.
- Remote Control Dimmer:Proprietary RF protocols sustain niche presence in legacy Lutron installations and specialized architectural lighting.
- Bluetooth Dimmer:Point-to-point connectivity serves single-room retrofits where consumers prioritize immediate setup over ecosystem expansion.
Wi-Fi dimmers command the established base. The steepest expansion runs through Zigbee dimmers as Matter certification dissolves ecosystem barriers.
Technology:
Cost tier stratification separates legacy phase-cut designs from premium MOSFET solutions, with zero-crossing and TRIAC variants occupying intermediate positions based on load compatibility requirements.
- MOSFET:Silicon-based dimming eliminates audible buzzing in high-end LED installations, addressing occupant experience priorities in luxury residential and hospitality segments. Demand concentrates in custom home markets across California, Florida, and Texas where silent operation justifies price premiums. Installation requires updated electrical contractor training, slowing trade adoption.
- Phase Cut:TRIAC-based legacy designs dominate retrofit volumes where incandescent compatibility remains relevant. Cost concentration in Asian manufacturing supports aggressive pricing in developing markets, though LED incompatibility limits applicability in efficiency-focused regions.
- Zero Crossing:Synchronized switching reduces electromagnetic interference in commercial environments with sensitive equipment loads.
- TRIAC:Mature supply chains and familiar installation practices sustain presence in price-sensitive residential replacement cycles.
Phase cut technology retains volume leadership. MOSFET designs are climbing the fastest as LED load proliferation accelerates specification upgrades.
End User:
Application context determines protocol selection, with commercial and hospitality segments prioritizing building management integration while residential buyers emphasize standalone convenience.
- Commercial:BACnet and Modbus protocol integration enables HVAC and security convergence, opening specification channels through building automation distributors. California Title 24 mandates create regulatory pull-through for dimming-capable new construction. Procurement runs through Ferguson and Graybar digital platforms with compressed project timelines.
- Residential:Retrofit acceleration drives volume as homeowners replace incandescent fixtures with dimmable LED arrays. Utility rebate programs in United States electricity markets reduce effective price points for ENERGY STAR-qualified hardware. Matter certification streamlines ecosystem interoperability.
- Hospitality:Guest experience requirements prioritize silent operation and scene programming in renovation cycles.
- Industrial:Harsh environment ratings and robust load capacity specifications differentiate procurement from commercial channels.
Residential applications anchor volume shipments. Commercial building management convergence represents the steepest expansion trajectory for integrated control systems.
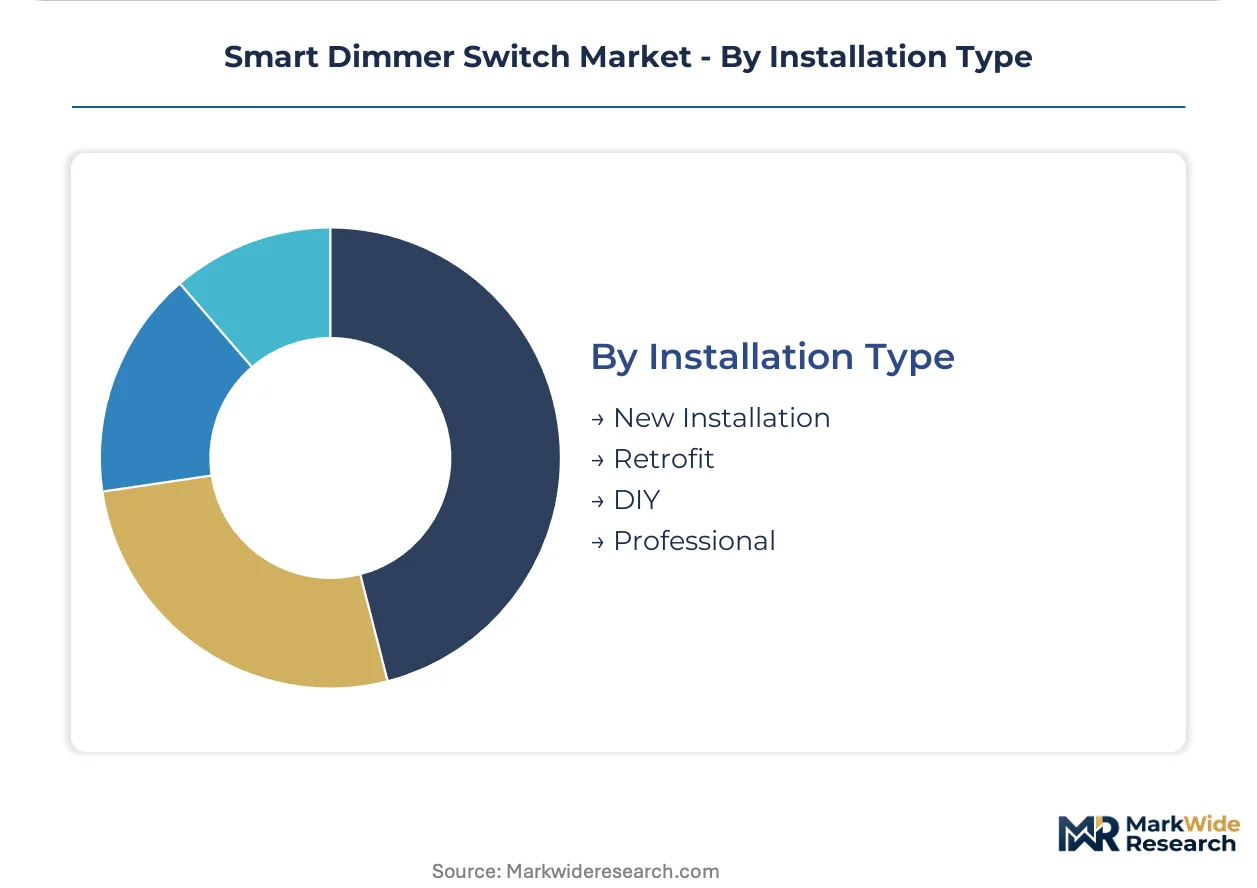
Installation Type:
Customer capability and project timing separate DIY retail purchases from professional specification channels, with retrofit volumes accelerating as building stock electrification expands.
- Retrofit:Single-gang replacement of existing switches captures homeowners upgrading to LED-compatible controls without rewiring. Demand concentrates in United States metropolitan markets where aging electrical infrastructure meets smart home adoption trends. Phase-cut LED incompatibility creates specification friction requiring consumer education.
- Professional:Electrical contractors specify through distributor digital platforms with integrated compatibility databases and real-time inventory. New commercial and high-rise residential construction in California mandates dimming capability, creating specification pull. Lutron's Clear Connect RF protocol sustains dominance in this channel.
- New Installation:Integrated design from electrical rough-in enables whole-home ecosystem planning and load capacity optimization.
- DIY:Retail packaging and app-guided setup instructions target consumers with basic electrical competency.
Professional installation commands the established base in commercial channels. Retrofit applications are gaining share fastest as residential LED conversion accelerates replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. United States buyers absorb premium pricing for Matter-certified ecosystem compatibility, while Indian and Southeast Asian markets prioritize sub-$25 entry points that sacrifice interoperability for immediate functionality.
United States
Residential retrofit volumes dominate as homeowners replace legacy switches with LED-compatible controls during kitchen and living room renovations. FCC Part 15 certification requirements extend product launch timelines, favoring established manufacturers with regulatory expertise. California's Title 24 building codes mandate dimming capability in new commercial and high-rise residential construction, creating specification pull-through concentrated in Los Angeles and San Francisco metropolitan construction markets.
Germany
EU Green Deal renovation wave priorities position lighting retrofits as lowest-capex decarbonization measures for aging commercial building stock. The EU Radio Equipment Directive mandates interoperability testing and CE marking, with German customs authorities enforcing non-compliant shipment blocks at Hamburg and Bremerhaven ports. Industrial clusters in Bavaria and North Rhine-Westphalia concentrate professional electrical contractor specification through distributor digital platforms.
China
Domestic demand concentrates in premium residential developments across Shanghai and Shenzhen where smart home pre-installation rates climb. MIIT certification requirements for radio frequency devices create compliance friction for export-oriented manufacturers. Yangtze River Delta manufacturing hubs supply cost-optimized phase-cut designs for developing Southeast Asian markets while domestic consumption shifts toward MOSFET-based silent operation specifications.
India
Urban residential construction and smart city initiatives create first-mover advantage for Matter-certified entrants in an underpenetrated market. BIS certification requirements for electrical accessories remain inconsistently enforced, creating quality tier fragmentation. Maharashtra and Karnataka state governments prioritize building electrification programs that accelerate switch replacement cycles in Mumbai and Bangalore metropolitan housing stock.
United Kingdom
Retrofit acceleration follows energy price volatility as homeowners seek demand-side efficiency measures. CE marking alignment post-Brexit creates transitional certification complexity for products entering English and Scottish markets. London and Southeast England concentrate specification influence through electrical contractor networks serving high-end residential renovation segments.
Smart Dimmer Switch Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, producing a bifurcated market structure. Proprietary protocol specialists command premium positioning in professional installation channels, while mass-market retailers compete aggressively on price point with Wi-Fi-native designs. The competitive landscape segments into ecosystem architects, component assemblers, and private-label suppliers. Dominant competitive moves include Matter certification racing and distributor platform integration.
Within the proprietary protocol tier, Lutron anchors professional specification channels through its Clear Connect RF ecosystem. TP-Link and its Kasa sub-brand occupy the mass-market retail vector, competing on price point and smartphone app integration. Philips Hue exemplifies the ecosystem lock-in archetype, leveraging hub-based Zigbee mesh networking to capture recurring accessory purchases.
| Leading Market Players |
|---|
| TP-Link |
| Kasa |
| Philips Hue |
| BESTTEN |
| Cloudy Bay |
| Lutron |
| GE |
| Maxxima |
| Leviton |
| Others |
Pricing and Supply Chain Analysis
Component scale economies in Yangtze River Delta manufacturing clusters concentrate MOSFET transistor sourcing and PCB assembly, compressing unit economics for Wi-Fi and Zigbee dimmer variants while establishing price floors that shield premium silent-operation designs from commoditization pressure.
Pricing Analysis
FCC Part 15 certification dictates the pricing tier structure across United States commercial and residential channels. Three-tier pricing structure across premium, standard, and economy levels separates Matter-certified ecosystem hubs from uncertified direct-to-consumer imports and professional-grade architectural specifications. Price differentiation hinges on wireless protocol complexity and load capacity ratings, with hub-dependent Zigbee systems commanding hardware premiums against standalone Wi-Fi alternatives. Cost compression in economy-tier phase-cut designs is intensifying because of raw material volatility in copper and semiconductor inputs. Mass-market retail buyers exhibit highest price sensitivity, while commercial specification channels absorb premium positioning for BACnet-integrated building management compatibility.
Supply Chain Analysis
Inventory lead times for FCC-certified radio modules extend product launch cycles by four to six months, forcing manufacturers to pre-position component stock ahead of seasonal construction demand. Manufacturing concentrates in China, with Yangtze River Delta hubs supplying cost-optimized phase-cut designs and domestic consumption shifting toward MOSFET-based silent operation specifications. Power transistor supply draws from Taiwanese foundries and South Korean packaging facilities, while PCB substrates rest on copper pricing from Chilean and Indonesian mining operations. Single-source vulnerability in proprietary RF protocol chipsets creates specification risk for Lutron Clear Connect ecosystem dependents. Distribution runs through Ferguson and Graybar digital platforms in United States metropolitan construction markets, with real-time inventory integration compressing procurement cycles for professional electrical contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Matter certification is dissolving ecosystem silos that previously locked consumers into single-brand environments, transforming hardware margins into platform-economics battles for recurring accessory revenue and specification influence.
For Market Incumbents: Secure distributor platform integration with Ferguson and Graybar to maintain specification influence as procurement migrates to digital channels. Deepen backward integration into MOSFET transistor sourcing to insulate margins from commodity volatility in copper and semiconductor inputs. Matter certification racing against emerging entrants represents the primary threat to ecosystem lock-in advantages.
For New Entrants and Emerging Players: Matter certification fast-track through Connectivity Standards Alliance accelerates market entry without proprietary hub hardware investment. India building electrification programs and Maharashtra state smart city initiatives offer the most penetrable geography for first-mover advantage in underpenetrated residential construction. Target professional electrical contractor training partnerships to overcome legacy skill gaps in silent-operation MOSFET installation practices.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hub-based Zigbee ecosystem architects with accessory attachment rates. Long-term viability over the projection horizon favors manufacturers with vertical integration into radio module certification expertise and distributor platform data access. Acquisition target archetype: mid-cap specialists with pre-certified Matter product families and established California Title 24 specification relationships. Watch Matter adoption velocity in European professional channels as inflection indicator for ecosystem consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Certification Acceleration | Connectivity Standards Alliance pre-certification dissolves ecosystem silos and expands addressable market reach. |
| Distributor Platform Integration | Ferguson and Graybar digital specification interfaces capture procurement influence in compressed project timelines. |
| Silent-Operation MOSFET Transition | Silicon-based dimming eliminates audible buzzing in high-end LED installations and commands price premiums. |
| India Market Entry | Maharashtra and Karnataka building electrification programs accelerate switch replacement cycles in metropolitan housing. |
| Professional Contractor Training | Updated electrical contractor certification overcomes legacy skill gaps in MOSFET installation practices. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FCC certification databases, utility rebate program filings, and building code regulatory texts. Primary interviews engaged product managers at wireless protocol semiconductor suppliers, specification directors at electrical distributor platforms, and procurement leads at commercial building automation integrators. Secondary validation drew from California Energy Commission Title 24 documentation, EU Radio Equipment Directive interoperability standards, and MIIT radio frequency device certification records. Bottom-up unit shipment modeling triangulates against top-down construction spending allocation across residential retrofit and commercial new-build segments.
Segmentation dimensions modeled include wireless protocol type, dimming technology architecture, end-user application context, and installation method preference across the analysis window. CAGRs derive from regression analysis of historical shipment velocity against construction permit flows and LED retrofit penetration curves. Forecast inputs incorporate Matter certification adoption trajectories, utility rebate program budget allocations, and copper price volatility indices.
Decision-makers should treat outputs as directional under assumptions of sustained Matter ecosystem convergence and stable regulatory enforcement of cybersecurity labeling requirements; material deviation in protocol fragmentation or certification timeline delays would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
United States Switchgear Market
Switches
Optical Cross Connect (OXC) Switches Market
Switches
North America MV Switchgear Market
Switches
Miniature-Circuit Breaker Market
Switches
United States Circuit Breaker Market
Switches
Outdoor Boundary Vacuum Load Switch Market
Switches
Contactor-based Transfer Switch Market
Switches
Mexico Rocker Switch Market
Switches
Zero Speed Switch Market
Switches
Rocker Switch Market
Switches
Asia-Pacific Low Voltage Switchgear Market
Switches
Static Transfer Switches Market
Switches
Global Float Level Switches Market
Switches
Low Voltage Switchgear Market
Switches
North America Switchgear Market
Switches
Optical Switches Market