
 Australia and New Zealand Medium Voltage Switchgear Market | 2026-2036
Australia and New Zealand Medium Voltage Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
Australia and New Zealand Medium Voltage Switchgear Market Insights
Utility sector procurement in Australia and New Zealand is shifting toward higher-specification switchgear as coal plant retirements accelerate renewable connection projects. Schneider Electric leverages its Pacific distribution network to dominate service-intensive segments. ABB sustains technology leadership through integrated digital monitoring platforms. Siemens anchors large-scale infrastructure bids with modular installation capabilities.
Medium voltage switchgear encompasses electrical apparatus rated between 1 kV and 52 kV designed to control, protect, and isolate power circuits through breaker, contactor, and fuse mechanisms. Vacuum interruption technology has displaced oil-based systems across Australian installations due to reduced maintenance intervals and elimination of fire risks in remote mining locations. Gas insulated switchgear commands premium positioning in space-constrained urban substations across both countries, while air insulated variants retain cost advantages in greenfield industrial zones. Smart grid technology integration is reshaping competitive positioning as utilities mandate remote diagnostics and predictive maintenance protocols.
Standards Australia and Electrical Regulatory Authorities Council shape product certification requirements across jurisdictions, with AS 62271 governing switchgear performance benchmarks. Energy Safe Victoria and WorkSafe New Zealand enforce installation compliance through periodic inspection regimes. Stakeholders must monitor evolving grid code requirements for distributed energy resource interconnection as both nations deepen renewable penetration targets.
Market Dynamics
Coal plant retirements across Australia's National Electricity Market are forcing synchronous infrastructure replacement, with network operators prioritizing switchgear capable of managing bidirectional renewable flows and voltage instability from distributed solar penetration.
Growth Catalysts
- Renewable interconnection mandates:Australia's Clean Energy Council grid codes require fault ride-through capabilities that only modern vacuum and gas insulated switchgear deliver, accelerating replacement cycles in Queensland and Victoria transmission zones.
- Urban densification pressures:Auckland's Unitary Plan and Sydney's metropolitan strategy restrict substation footprints, compressing demand toward compact gas insulated variants in land-constrained zones.
- Mining automation requirements:Western Australia's autonomous haulage and processing facilities demand arc-resistant switchgear with remote monitoring to reduce personnel exposure in Pilbara iron ore corridors.
Market Restraints
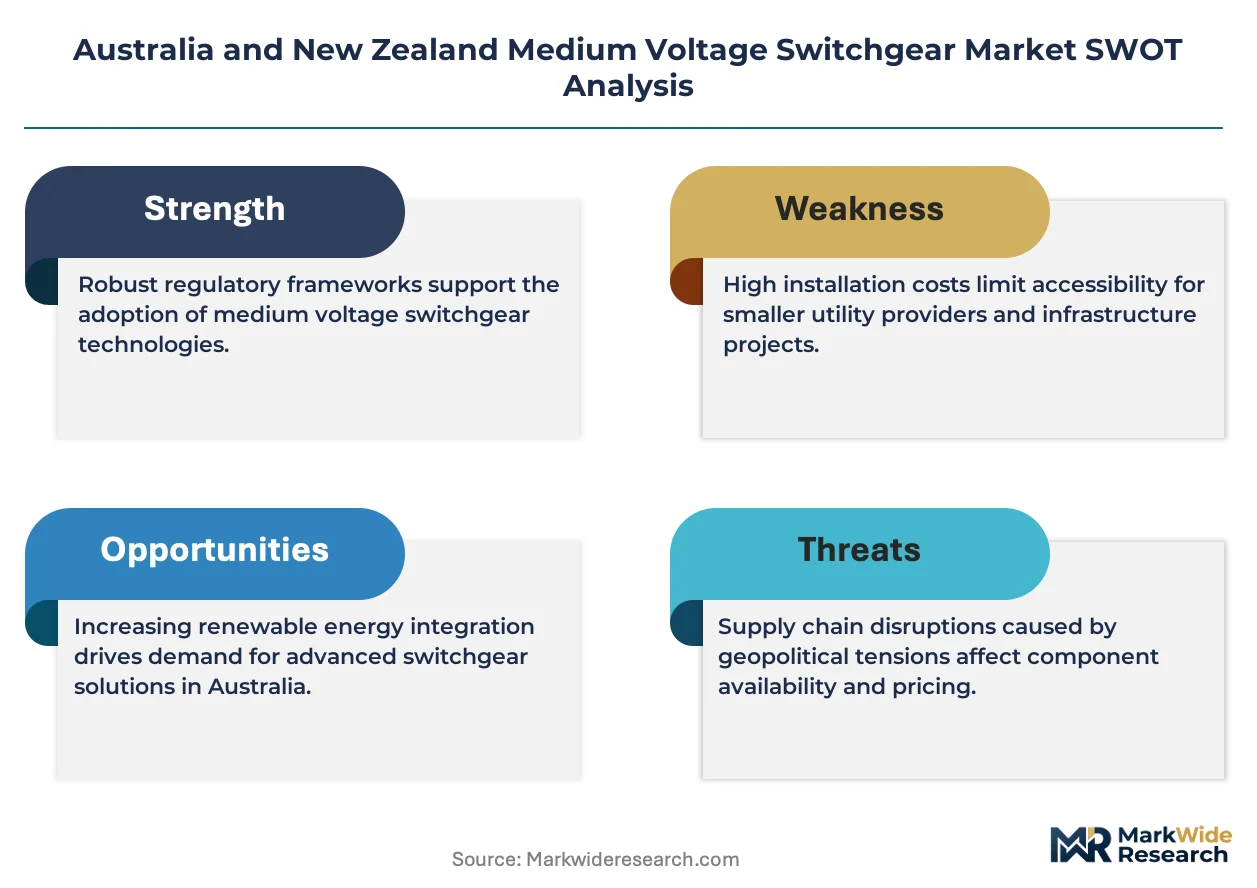
- Copper and aluminum price volatility:Busbar and conductor material costs constitute 35-45% of air insulated switchgear manufacturing, exposing domestic fabricators to London Metal Exchange fluctuations without long-term hedging capacity.
- Specialized engineering concentration:Gas insulated switchgear design expertise concentrates among three multinational technology licensors, constraining local assembly flexibility and service response times.
- Sulfur hexafluoride regulatory pressure:New Zealand's updated electrical safety regulations and Australia's anticipated F-gas alignment impose handling protocols and leakage monitoring that elevate lifecycle costs for gas insulated installations.
Strategic Opportunities
- Offshore wind preparatory procurement:Victoria's declared offshore wind zones and proposed New Zealand South Island developments require marine-grade switchgear with corrosion resistance specifications absent from current utility inventories.
- Digital twin integration:Convergence of switchgear condition monitoring with SCADA analytics enables predictive maintenance contracts that capture recurring revenue streams from asset-light network operators.
- Second-tier city infrastructure:Tasmania's Battery of the Nation interconnector and regional Queensland renewable energy zones present underpenetrated demand for modular air insulated switchgear in greenfield substation construction.
Industry Challenges
- High-voltage engineering talent scarcity:Australian universities produce fewer than fifty specialized switchgear design engineers annually, forcing manufacturers to recruit from European and Asian competitor pools.
- AS 62271 certification timelines:Standards Australia's testing queue extends 14-18 months for new product variants, delaying market entry for innovative arc interruption technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia and New Zealand Medium Voltage Switchgear Market |
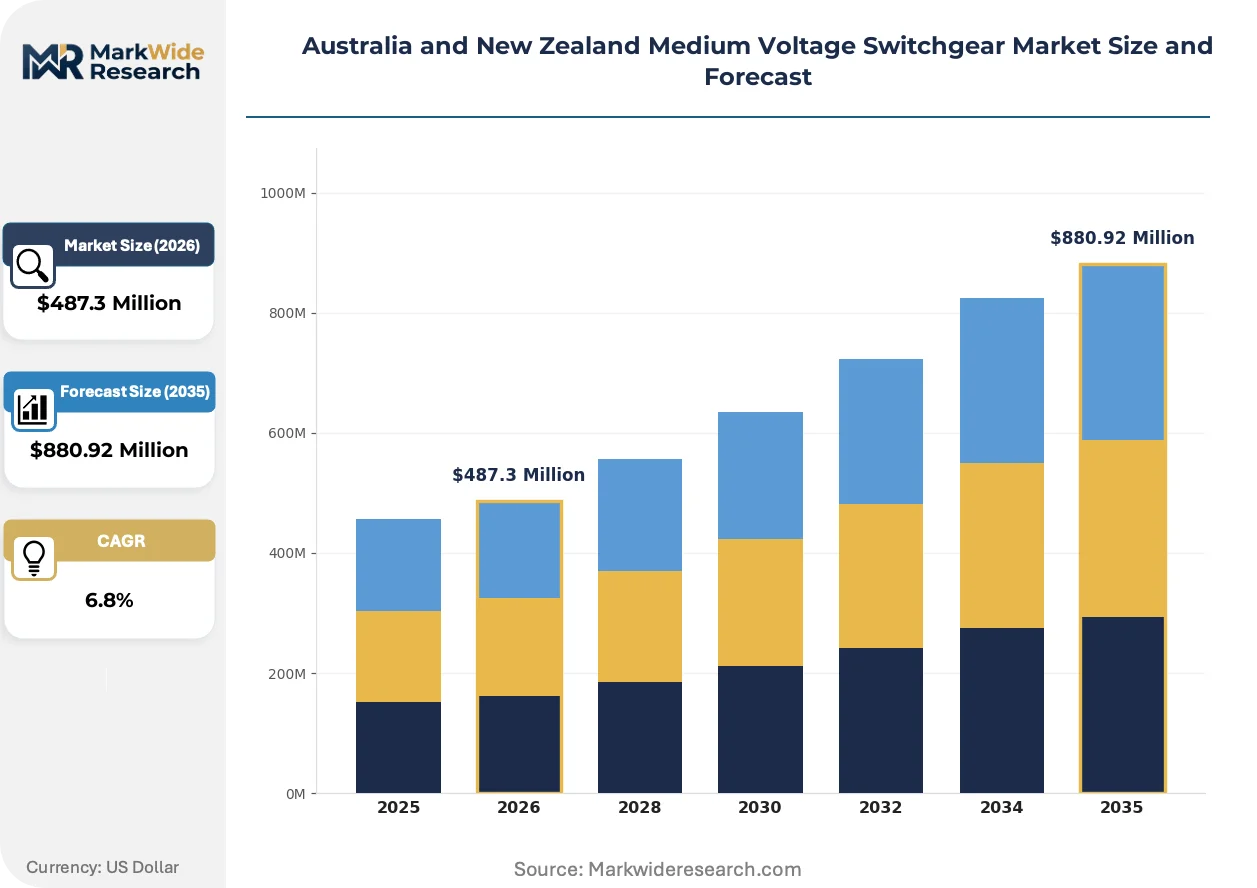
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Insulated Switchgear, Gas Insulated Switchgear, Hybrid Switchgear, Vacuum Switchgear End User: Utilities, Industrial, Commercial, Infrastructure Installation Type: Indoor, Outdoor, Mobile, Modular Technology: Smart Grid, Digital, Conventional, Integrated |
| Companies Covered | Schneider Electric, ABB, Siemens, Eaton, Legrand, Hager, Clipsal, Preece Cardew, Baxter Electrical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia and New Zealand Medium Voltage Switchgear Market Trends and Innovations
Vacuum interruption technology is consolidating its position as the dominant arc extinction method across Australian installations, displacing legacy oil and air blast systems through reliability improvements and maintenance reduction.
Vacuum interrupters utilize sealed ceramic enclosures with copper-chromium contacts to extinguish arcs without insulating oil or compressed air systems. Mining operators in Queensland and Western Australia have standardized on vacuum mechanisms to eliminate fire risks in remote, unmanned substations. This technology is consolidating supplier margins by reducing aftermarket parts dependency and enabling longer warranty terms that compress competitor service revenue.
WorkSafe New Zealand's 2024 electrical safety regulations mandate arc flash containment and remote racking capabilities for new switchgear installations in commercial and industrial applications. The regulations impose documented risk assessments and personnel protection boundaries that favor manufacturers with integrated safety interlock systems. Auckland's distribution network operators are responding by specifying arc-resistant switchgear with pressure relief channels in all new 11kV substations.
Asset management contracts are displacing traditional equipment purchase models as Australian utilities unbundle capital expenditure from operational responsibility. Network operators in New South Wales and Victoria now prefer ten-year performance agreements where manufacturers retain ownership and guarantee availability metrics. This shift concentrates procurement authority among integrated service providers and marginalizes pure equipment vendors without maintenance infrastructure.
Australia and New Zealand Medium Voltage Switchgear Market Segmentation
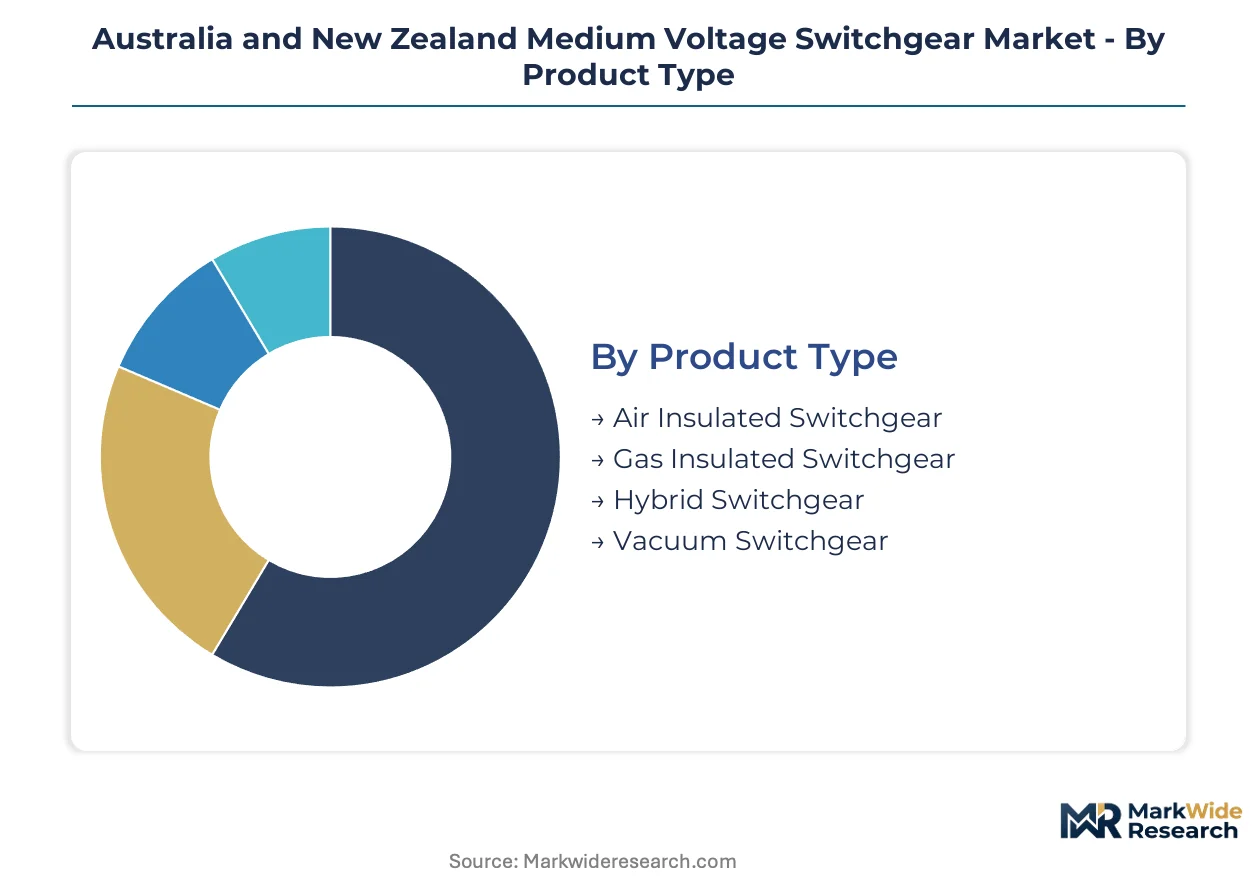
Switchgear procurement across Australia and New Zealand fragments across technical specifications, installation constraints, and operational environments. Understanding these divisions reveals where margin concentrates and which technology transitions will reshape vendor positioning.
Product Type:
Supply concentration tilts toward gas insulated variants where three multinational licensors control core intellectual property, constraining local assembly flexibility.
- Air Insulated Switchgear:Open-air busbar configurations with exposed conductors dominate greenfield industrial zones and regional Queensland renewable energy substations. Queensland's mining corridor and Western Australia's Pilbara iron ore operations specify these units for cost-sensitive remote installations where maintenance crews remain accessible.
- Gas Insulated Switchgear:Sealed sulfur hexafluoride enclosures compress equipment footprints by 70-80% compared to air insulated equivalents. Auckland's Unitary Plan restrictions and Sydney's metropolitan density mandates are accelerating procurement for land-constrained urban substations, despite elevated lifecycle costs from F-gas handling protocols.
- Hybrid Switchgear:Combines air insulated busbars with gas insulated circuit breakers for intermediate footprint and cost positioning.
- Vacuum Switchgear:Ceramic-enclosed copper-chromium contacts eliminate fire risks in unmanned mining substations.
Today's leader: Gas Insulated Switchgear. Tomorrow's challenger: Vacuum Switchgear.
End User:
Cost tier differentiation separates capital-rich utilities from price-sensitive commercial operators, with industrial buyers occupying a contested middle ground demanding performance guarantees.
- Utilities:Network operators across Australia's National Electricity Market and Transpower New Zealand prioritize bidirectional power flow capability and fault ride-through specifications. These buyers are unbundling capital expenditure from operational responsibility through ten-year performance agreements that transfer asset ownership to manufacturers.
- Industrial:Mining automation requirements in Western Australia and Queensland specify arc-resistant enclosures with remote racking to reduce personnel exposure. Processing facilities demand integrated condition monitoring for predictive maintenance in hazardous environments.
- Commercial:Shopping centers, hospitals, and data centers in Sydney and Melbourne prioritize compact indoor installations with minimal footprint.
- Infrastructure:Rail electrification and airport expansions across both countries require modular delivery schedules aligned with construction timelines.
Utilities command premium pricing through performance contracting. Industrial buyers are gaining procurement sophistication fastest.
Installation Type:
Application requirements dictate environmental protection levels, with outdoor specifications dominating mining and rural utility deployments while indoor variants capture urban densification projects.
- Indoor:Metal-enclosed switchgear for climate-controlled substation buildings. Auckland's distribution network operators specify arc-resistant units with pressure relief channels for all new 11kV commercial installations under WorkSafe New Zealand regulations.
- Outdoor:Weatherproof enclosures rated for dust, moisture, and temperature extremes. Western Australia's autonomous haulage corridors and Queensland's coastal renewable zones drive specification of marine-grade corrosion protection.
- Mobile:Skid-mounted or trailer-deployed units for temporary construction power and emergency restoration.
- Modular:Prefabricated substation blocks enabling rapid deployment for Tasmania's Battery of the Nation interconnector and regional Queensland renewable energy zones.
Outdoor installations retain volume dominance. Modular formats are climbing the fastest as greenfield renewable projects accelerate.
Technology:
Customer type stratification separates asset-heavy incumbents investing in digital transformation from conservative operators extending conventional equipment lifecycles.
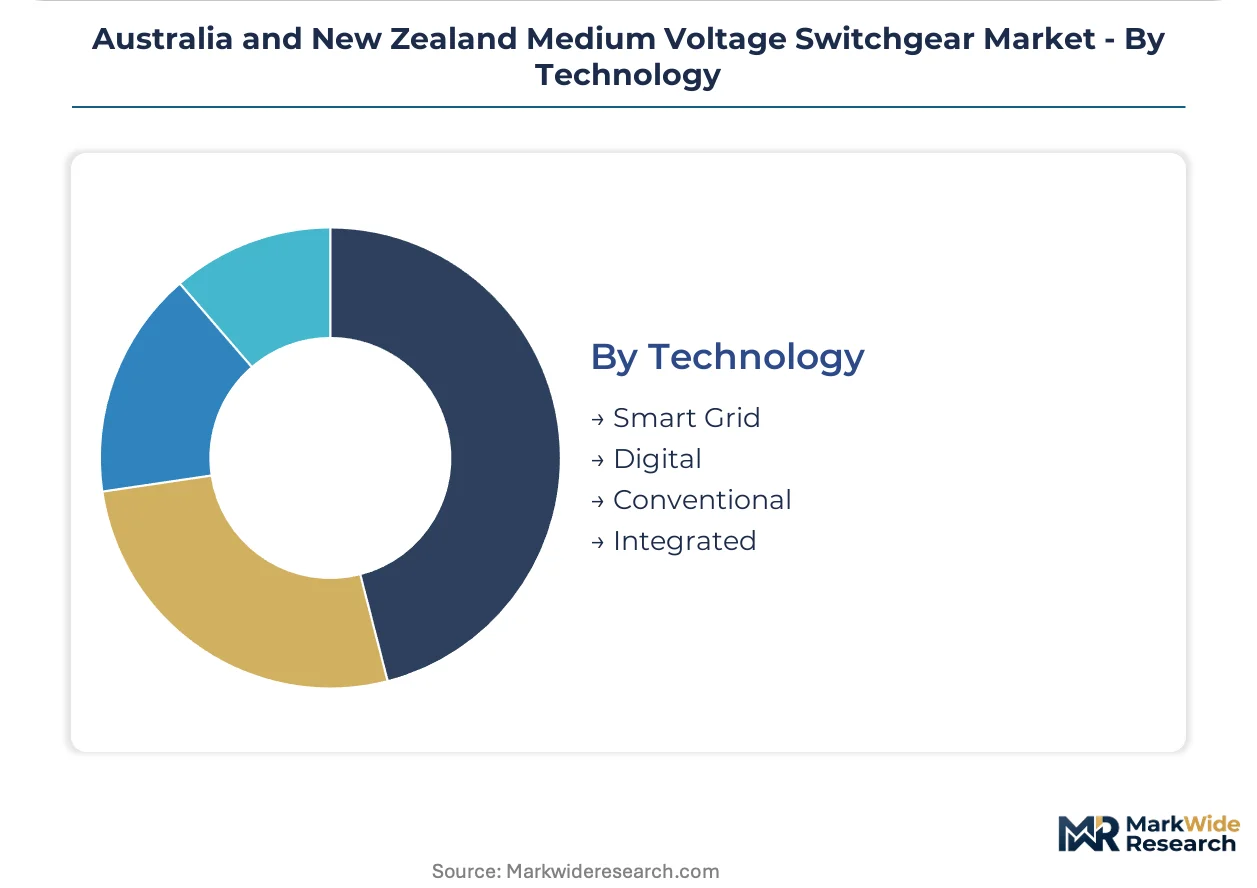
- Smart Grid:Integrated sensors, communications modules, and edge computing enabling autonomous fault isolation and self-healing networks. Australian utilities mandate remote diagnostics and predictive maintenance protocols that favor manufacturers with established SCADA integration capabilities.
- Digital:Condition monitoring platforms with cloud-connected analytics for asset performance optimization without full grid automation.
- Conventional:Electromechanical protection and manual operation retaining cost advantage in price-sensitive regional deployments.
- Integrated:Combined switchgear-transformer packages with unified monitoring and control systems for space-constrained urban substations.
Smart Grid commands technology premiums. Digital represents the steepest expansion trajectory as mid-tier utilities modernize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between Australian states and New Zealand are redirecting switchgear procurement toward jurisdictions with streamlined certification pathways. Manufacturers exploit regulatory arbitrage by concentrating assembly in zones with shorter AS 62271 testing queues.
New South Wales
Network operators in Sydney's metropolitan corridor prioritize compact gas insulated switchgear for land-constrained urban substations. Energy Safe New South Wales enforces installation compliance through periodic inspection regimes. The state's renewable energy zones in the Central-West Orana region are accelerating procurement of bidirectional-capable switchgear for solar and wind interconnection.
Victoria
Declared offshore wind zones in Bass Strait are generating preparatory procurement of marine-grade switchgear with corrosion resistance specifications. Energy Safe Victoria mandates arc flash containment for new commercial installations. Melbourne's distribution network operators are unbundling capital expenditure through ten-year performance agreements that transfer asset ownership to manufacturers.
Queensland
The mining corridor from Mount Isa to the Bowen Basin specifies arc-resistant switchgear with remote racking to reduce personnel exposure in autonomous haulage zones. The state's electrical safety regulator requires documented risk assessments for high-voltage installations. Regional renewable energy zones are driving modular air insulated switchgear demand for greenfield substation construction.
Western Australia
Pilbara iron ore operations standardize on vacuum interruption technology to eliminate fire risks in remote unmanned substations. The state's mining safety regulations impose strict handling protocols for sulfur hexafluoride installations. Perth's urban infrastructure renewal is compressing demand toward compact indoor switchgear formats.
New Zealand
Auckland's Unitary Plan restrictions are accelerating procurement of gas insulated variants for distribution network densification. WorkSafe New Zealand's 2024 electrical safety regulations mandate arc flash containment and remote racking capabilities. Transpower New Zealand is prioritizing switchgear capable of managing bidirectional flows from distributed solar penetration.
Australia and New Zealand Medium Voltage Switchgear Market Competitive Landscape
Strategic partnerships dominate the current landscape as multinational licensors seek local assembly flexibility to circumvent AS 62271 certification bottlenecks. The vendor base organizes around three tiers: integrated service providers capturing utility performance contracts, technology licensors controlling gas insulated switchgear intellectual property, and regional fabricators serving price-sensitive industrial segments. Competitive positioning hinges on SCADA integration capabilities and predictive maintenance infrastructure.
Among European-headquartered multinationals, Schneider Electric and ABB exemplify the integrated service provider archetype through their Pacific distribution networks. Siemens occupies a position on the large-scale infrastructure vector with modular installation capabilities. These three anchors represent the technology-licensor tier that constrains local assembly flexibility for gas insulated variants. Regional specialists including Preece Cardew and Baxter Electrical sit within the service-intensive segment focused on aftermarket support and maintenance contracts.
| Leading Market Players |
|---|
| Schneider Electric |
| ABB |
| Siemens |
| Eaton |
| Legrand |
| Hager |
| Clipsal |
| Preece Cardew |
| Baxter Electrical |
| Others |
Pricing and Supply Chain Analysis
Utility procurement concentration across Australia's National Electricity Market and Transpower New Zealand anchors project-based contract pricing with long-term performance guarantees. Manufacturers capture value through bundled service agreements rather than equipment markups alone.
Pricing Analysis
Distributor margins for imported gas insulated switchgear components compress final pricing by 12-18% before installation contracting. Three-tier pricing structure across premium, standard, and economy levels separates integrated digital monitoring packages from conventional electromechanical units. Pricing pressure stems from copper and aluminum volatility on the London Metal Exchange, which exposes domestic fabricators without hedging capacity. Industrial mining buyers in Queensland and Western Australia exhibit highest price sensitivity, while utilities accepting ten-year performance contracts prioritize availability metrics over unit cost.
Supply Chain Analysis
Regional distribution centers in Sydney, Melbourne, and Auckland operate hub-and-spoke patterns to serve remote mining corridors and urban substation projects. Manufacturing concentration rests on Germany, Switzerland, and Finland for vacuum interrupter ceramic enclosures and gas insulated switchgear core assemblies. Raw material dependencies include copper-chromium contact alloys, sulfur hexafluoride gas, and epoxy resin insulators. Single-source vulnerability concentrates in gas insulated switchgear intellectual property held by three multinational licensors. Distribution runs through authorized service partners for aftermarket parts and commissioning support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia and New Zealand medium voltage switchgear functions as a stable compounder underpinned by mandatory renewable interconnection codes that force replacement cycles regardless of macroeconomic conditions.
For Market Incumbents: Anticipate margin compression from regional fabricators in Southeast Asia seeking AS 62271 certification entry. Defend positioning by deepening backward integration into vacuum interrupter refurbishment capabilities and captive copper-chromium contact supply. Prioritize certification investment to maintain queue priority at Standards Australia testing facilities. For New Entrants and Emerging Players: Begin with Tasmania's Battery of the Nation interconnector and regional Queensland renewable energy zones where incumbent service infrastructure remains thin. Target modular air insulated switchgear for greenfield substation construction where specification barriers sit lower than urban gas insulated variants. Pursue direct EPC contractor relationships to bypass established distribution hierarchies. For Investors and Strategic Acquirers: Integrated electrical infrastructure conglomerates are the most active acquirer in this space, seeking predictive maintenance platforms and SCADA integration capabilities. Five-to-ten year viability hinges on digital twin technology adoption rates among asset-light network operators. Monitor AS 62271 certification queue lengths as inflection indicator for new entrant supply capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Captures recurring revenue from Transpower New Zealand and Australian NEM operators unbundling capital expenditure. |
| Marine-Grade Corrosion Certification | Qualifies equipment for Victoria's Bass Strait offshore wind zones and South Island developments. |
| Vacuum Interrupter Refurbishment Capacity | Reduces aftermarket parts dependency and extends warranty terms in Queensland mining corridors. |
| Arc-Resistant Safety Interlock Systems | Meets WorkSafe New Zealand 2024 mandates for Auckland commercial installations. |
| Modular Prefabricated Substations | Aligns delivery schedules with Tasmania interconnector and regional Queensland REZ construction timelines. |
Research Methodology
Multiple input streams — utility procurement officer interviews, EPC contractor project databases, and Standards Australia certification records — were reconciled against secondary validation from Electrical Regulatory Authorities Council filings and Clean Energy Council grid code documentation. Primary discussions included network planning engineers, mining maintenance directors, switchgear service technicians, and distribution channel managers. Secondary sources encompassed AS 62271 test reports, WorkSafe New Zealand safety bulletins, and London Metal Exchange copper pricing archives. Bottom-up project pipeline aggregation and top-down utility capital expenditure forecasts were cross-referenced for triangulation.
Historical installation data across New South Wales, Victoria, Queensland, Western Australia, and New Zealand regions were compared against expert panel assessments of replacement cycle timing and renewable interconnection mandates. Segmentation modeling incorporated product type, end user category, installation format, and technology tier dimensions throughout the forecast period. CAGRs were derived from weighted average of utility infrastructure investment trajectories and mining automation procurement patterns.
Several conditions sit outside the modeled scope, including unannounced coal plant retirement accelerations, abrupt F-gas regulatory phase-outs, and geopolitical disruptions to copper-chromium alloy supply. Forecasts reflect documented assumptions regarding standards compliance timelines and grid code stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Asia-Pacific Low Voltage Switchgear Market
Switches
Transfer Switch Market
Switches
Europe Low Voltage Switchgear Market
Switches
Carrier Router Switch Market
Switches
Cross Point Switch Market
Switches
Global Electrical Switches Market
Switches
Panel Mounted Disconnect Switch Market
Switches
Intelligent Power Switches Market
Switches
Smart Circuit Breaker Market
Switches
United States Circuit Breaker Market
Switches
India Reed Sensors Switches Market
Switches
Contactor-based Transfer Switch Market
Switches
Asia Pacific Safety Switches Market
Switches
Smart Plugs and Switches Market
Switches
Global Float Level Switches Market
Switches
North America Switchgear Market