
 Vibration Level Switch Market | 2026-2036
Vibration Level Switch Market Size, Share, and Industry Trends Forecast 2026-2036
Vibration Level Switch Market Intelligence
REACH compliance is expanding the cost-of-entry calculus for vibration level switch vendors serving European process industries. Endress+Hauser leverages its Swiss manufacturing base and deep calibration expertise to sustain premium positioning across chemical and pharmaceutical accounts. VEGA Grieshaber anchors its competitive stance through specialized radar and ultrasonic extensions that navigate harsh-media applications where piezoelectric designs dominate. Emerson Electric competes on manufacturing scale, with broad channel control across North American oil refineries and power generation facilities.
A vibration level switch detects material presence or absence at a specific point using mechanical resonance frequency shifts, typically operating at excitation frequencies between 350 Hz and 1,000 Hz with stainless steel or Hastelloy fork assemblies rated for pressures exceeding 100 bar. Its primary industrial purpose is to prevent overflow, dry-running, or interlock failures in tanks, silos, and pipelines across continuous and batch processes. Non-contact level switch designs are capturing margin pools in food and pharmaceutical applications where product contamination risks disqualify intrusive probes, while point level switch configurations remain the volume backbone in mining and bulk solids handling. Piezoelectric technology leads on unit economics and field-proven durability, though electromagnetic alternatives are gaining traction in high-temperature reactor vessels where ceramic insulation limits conventional approaches.
FDA cGMP guidelines and EU MDR requirements shape product validation protocols for switches deployed in pharmaceutical and food-grade environments, while EPA effluent standards at US water treatment plants mandate redundant level-sensing architectures. ISO 9001 and IEC 61508 functional safety certifications function as de facto market access filters, particularly for vendors targeting power generation and chemical processing accounts. Stakeholders must monitor how evolving SIL ratings and cybersecurity appendices to IEC standards reshape R&D allocation across contact and non-contact product lines.
Market Dynamics
The EU F-Gas Regulation is accelerating displacement of refrigerant-dependent level sensors across European chemical corridors, forcing facilities toward mechanical resonance alternatives with lower environmental compliance burdens. This regulatory pressure intersects with process automation upgrade cycles in Germany's industrial belt, creating concentrated demand pull for piezoelectric fork designs rated for high-pressure reactor vessels.
Growth Catalysts
- REACH compliance deadlines:ECHA substance restrictions are disqualifying mercury-based float switches in pharmaceutical and food-grade tanks, redirecting specification authority toward vibration-based mechanical alternatives with simpler material declarations.
- Hydrogen economy infrastructure:Electrolyzer and fuel cell manufacturing facilities in the Netherlands and Denmark are specifying Hastelloy-ceramic fork assemblies for cryogenic and high-purity water level interlocks.
- Batch process digitization:Chemical processors are retrofitting legacy silos with SIL-rated vibration switches to enable ISA-88 compliant recipe automation without invasive vessel modifications.
Market Restraints
- Piezoelectric ceramic supply concentration:High-purity PZT ceramic sourcing concentrates among Japanese and Chinese specialty material suppliers, exposing lead times to export control volatility.
- Stainless steel alloy cost volatility:316L and Hastelloy C-276 price swings compress margin stability for vendors with fixed-price frame contracts across multi-year municipal water treatment projects.
- Non-contact radar substitution:80 GHz FMCW radar units are capturing specification authority in food and pharmaceutical applications where CIP/SIP protocols favor completely external mounting.
Strategic Opportunities
- Polish and Czech chemical corridor expansion:EU cohesion fund investments in Central European specialty chemical parks are greenfielding automation specifications without incumbent vendor lock-in.
- IIoT-enabled predictive maintenance bundles:Vibration switches with integrated HART-IP diagnostics and edge analytics are commanding specification authority in Scandinavian offshore platform retrofits.
- EU Green Deal process efficiency mandates:National implementation frameworks in France and Italy are subsidizing level-sensing upgrades that eliminate overflow incidents and reduce feedstock waste.
Industry Challenges
- SIL 2/3 functional safety certification timelines:IEC 61508 third-party validation cycles extend 14-18 months, compressing product launch windows for vendors targeting power generation and nuclear balance-of-plant applications.
- Legacy 4-20 mA infrastructure integration:Brownfield chemical facilities in Belgium and northern England retain predominantly analog control architectures, forcing hybrid signal design complexity for digital-native switch platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vibration Level Switch Market |
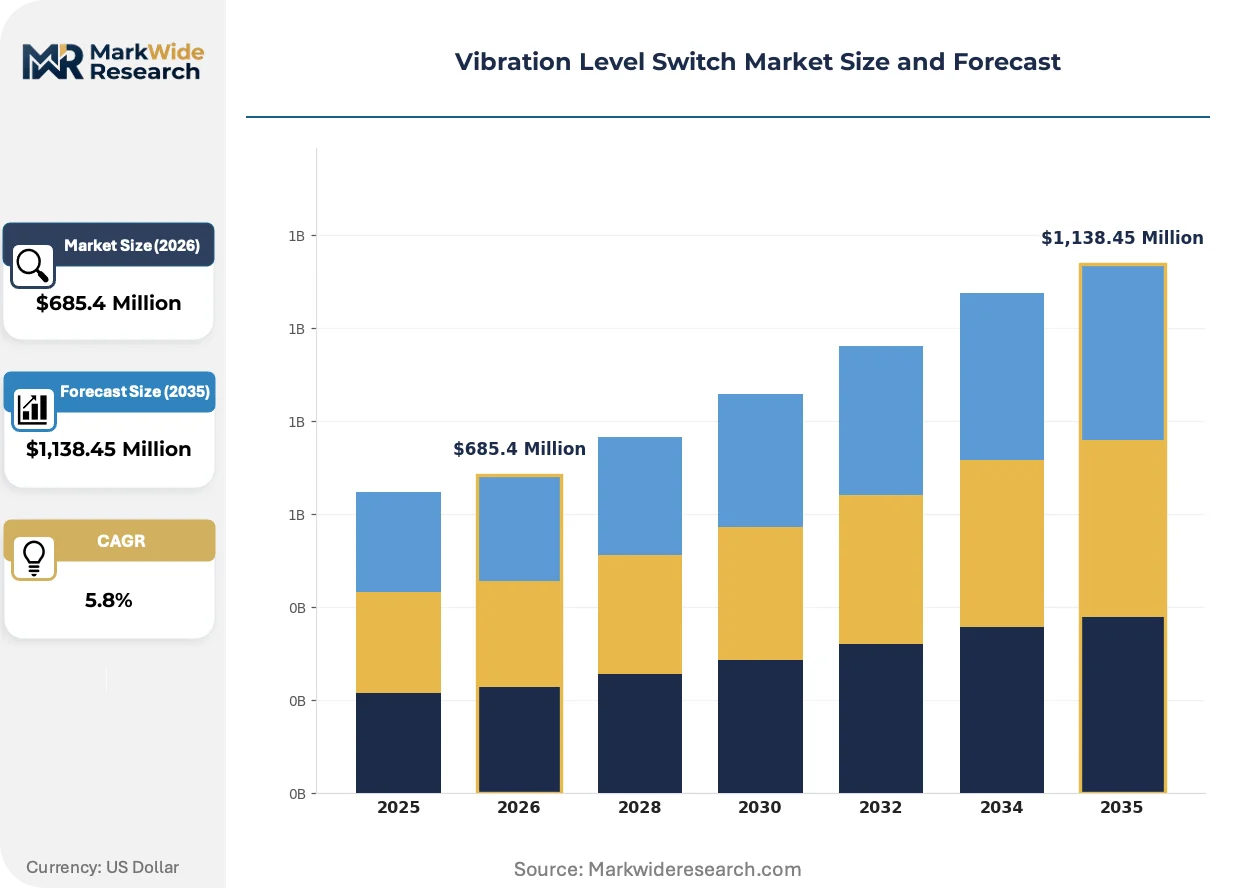
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact Level Switch, Non-Contact Level Switch, Point Level Switch, Continuous Level Switch Technology: Piezoelectric, Capacitive, Ultrasonic, Radar, Electromagnetic Application: Water Treatment, Chemical Processing, Food & Beverage, Pharmaceutical, Mining End User: Manufacturing Plants, Power Generation Facilities, Oil Refineries, Waste Management Sites |
| Companies Covered | Endress+Hauser, VEGA Grieshaber, Emerson Electric, Siemens, ABB, KROHNE Messtechnik, AMETEK, Magnetrol International, Pepperl+Fuchs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vibration Level Switch Market Strategic Shifts & Innovations
Electromagnetic excitation architectures are displacing conventional piezoelectric drive systems in high-temperature reactor applications above 400°C, where ceramic insulation degradation limits field reliability. This materials transition is reshaping R&D allocation and vendor capability claims across the European process automation supply base.
Electromagnetic drive technology is electrifying level switch design for molten salt and thermal oil systems in concentrated solar power plants and chemical heat transfer loops. Spanish and Italian energy developers are specifying these units for diurnal cycling duty where piezoelectric stacks experience fatigue failure. The technology is electrifying competitive positioning for vendors with in-house magnetic actuator expertise, compressing the addressable market for pure-play piezoelectric specialists.
EU F-Gas Regulation phase-down schedules are mandating refrigerant leak detection and containment protocols that disqualify float and capacitive switches with internal cavities. Chemical processors in Germany's Ruhr region and Rotterdam's port complex are rewriting instrumentation specifications to favor hermetically sealed vibration forks. This regulatory compression is accelerating specification authority shifts toward mechanical resonance designs in applications previously served by electronic alternatives.
Lifecycle service contracting is displacing transactional hardware procurement in municipal water and wastewater utilities. French and British operators are unbundling installation, calibration, and 10-year replacement guarantees into subscription structures. This procurement evolution concentrates vendor selection authority on service network density and response time commitments rather than unit cost alone, favoring established channel operators with regional technical service presence.
Vibration Level Switch Market Segmentation
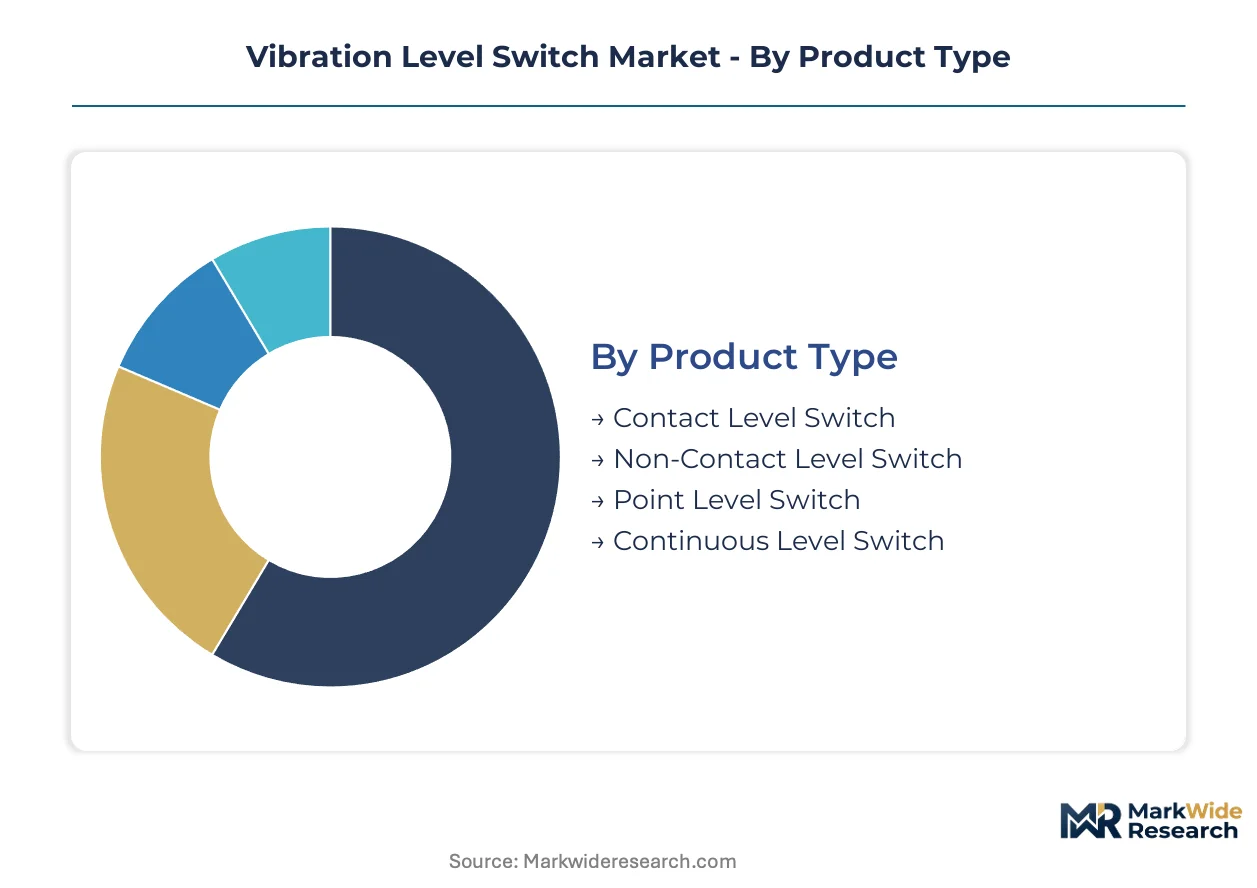
Vibration level switch segmentation reveals how technical specifications align with process severity and contamination risk. Procurement patterns diverge sharply between bulk solids handling, where mechanical durability dominates, and hygienic processing, where cleanability and material traceability command premium positioning.
Product Type:
Volume concentration clusters in point-level configurations for silo and tank overflow protection, while premium margins attach to continuous measurement systems for inventory management.
- Contact Level Switch:Fork or rod assemblies physically immerse in process media, with 316L stainless steel or Hastelloy C-276 wetted parts rated for pressures exceeding 100 bar. Demand concentrates in German chemical processing corridors where REACH substance restrictions disqualify mercury-based float alternatives and hermetic sealing prevents fugitive emissions.
- Non-Contact Level Switch:External mounting eliminates product contact through radar or ultrasonic beam propagation, typically employing 80 GHz FMCW or guided wave radar architectures. Newer deployment concentrates in Danish and Dutch pharmaceutical facilities where FDA cGMP and EU MDR validation protocols mandate elimination of intrusion risks for sterile batch operations.
- Point Level Switch:Binary presence/absence detection at discrete heights using piezoelectric resonance frequency shift, the workhorse configuration for high-low alarm and pump control interlocks. Mature deployment sits with mining and bulk solids handling across Poland's expanding lignite extraction belt.
- Continuous Level Switch:Analog output proportional to fill height enables inventory tracking and trend-based predictive maintenance. Deployment is expanding fastest in French and Italian water treatment utilities where EU Green Deal efficiency mandates subsidize overflow prevention infrastructure.
Mature deployment sits with Point Level Switch. Newer deployment is concentrated in Continuous Level Switch.
Technology:
Cost tier stratification separates field-proven piezoelectric economics from electromagnetic premiums for extreme temperature service.
- Piezoelectric:Ceramic stack excitation at 350-1,000 Hz delivers resonant frequency shift detection with no moving parts, dominating unit economics across chemical and water treatment applications. Supply chain exposure to Japanese and Chinese PZT ceramic suppliers creates lead time volatility for European vendors.
- Electromagnetic:Magnetic actuator drive systems operate above 400°C where ceramic insulation degrades, capturing specification authority in Spanish concentrated solar power molten salt storage and Italian thermal oil heat transfer loops. Deployment is climbing the fastest as reactor vessel temperatures escalate across process intensification projects.
- Capacitive:Dielectric constant measurement between probe and vessel wall suits conductive and non-conductive liquids with moderate coating tolerance. Belgian brownfield chemical facilities specify hybrid capacitive-vibration designs for analog-to-digital control system transitions.
- Ultrasonic:Time-of-flight pulse echo measurement avoids media contact through air or vapor space propagation, common in open channel flow and weir level monitoring. British wastewater utilities favor ultrasonic for external mounting on concrete clarifier structures.
- Radar:Frequency modulated continuous wave or guided wave architectures penetrate foam, vapor, and dust for reliable level detection in challenging process conditions. Czech specialty chemical greenfield projects specify radar where aggressive media coating risks disable mechanical alternatives.
Established volume sits with Piezoelectric. Technology transition is accelerating toward Electromagnetic.
Application:
Margin structure inverts between commodity water treatment specifications and pharmaceutical validation-intensive procurement.
- Chemical Processing:High-pressure reactor vessels and corrosive media storage demand Hastelloy or titanium fork assemblies with SIL-rated safety integrity. Rotterdam's port complex and Germany's Ruhr region anchor European demand as F-Gas Regulation phase-downs rewrite instrumentation specifications.
- Pharmaceutical:Aseptic processing and active pharmaceutical ingredient containment require 3-A sanitary standards, surface finish documentation, and material certificates for wetted parts. Scandinavian contract manufacturing organizations command premium pricing for validation protocol support.
- Water Treatment:Municipal and industrial effluent management specifies redundant level sensing for pump protection and overflow prevention under EPA effluent standards. French lifecycle service contracting models concentrate vendor selection on regional technical response capability.
- Food & Beverage:Clean-in-place and steam-in-place protocols favor non-contact designs or hygienic fork geometries with minimal crevices for bacterial harborage. Italian pasta and dairy processors drive specification toward EHEDG-compliant surface finishes.
- Mining:Abrasive slurries and bulk solids handling stress mechanical durability over precision, with heavy-duty fork designs rated for impact and material buildup. Polish and Czech coal and mineral extraction operations specify reinforced probe geometries for silo level interlocks.
Volume concentration remains with Chemical Processing. Margin expansion is concentrating in Pharmaceutical.
End User:
Customer type determines procurement modality, from municipal utility lifecycle contracts to oil refinery frame agreements.
- Manufacturing Plants:Discrete and process manufacturing across automotive, electronics, and specialty materials production employ vibration switches for coolant, lubricant, and chemical storage. German industrial automation upgrade cycles concentrate demand in Baden-Württemberg and Bavaria.
- Power Generation Facilities:Nuclear balance-of-plant and thermal power cycle applications require IEC 61508 SIL 2/3 certification with extended validation timelines. British and French nuclear operators specify dual-redundant architectures for safety-related level indication.
- Oil Refineries:Hydrocarbon storage, process vessel, and flare knockout drum applications demand explosion-proof enclosures and materials compatibility with sour crude fractions. North Sea platform retrofits and Rotterdam refining cluster sustain specification volume.
- Waste Management Sites:Leachate collection, biogas digester, and hazardous liquid containment applications combine environmental compliance with aggressive corrosion conditions. Dutch circular economy infrastructure investments expand addressable scope for hermetically sealed designs.
Procurement maturity sits with Oil Refineries. Contracting innovation is advancing in Waste Management Sites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Industrieparks anchor European demand concentration through tax-advantaged zones accelerating process automation retrofits. The EU F-Gas Regulation and REACH compliance deadlines are redirecting specification authority toward mechanical resonance alternatives across industrial corridors.
Germany
Baden-Württemberg and Bavaria's automotive-chemical clusters drive specification volume for SIL-rated fork assemblies in high-pressure reactor vessels. The F-Gas Regulation phase-down forces Rotterdam-connected Ruhr facilities toward hermetically sealed vibration designs. Dortmund's process automation upgrade cycles concentrate demand for piezoelectric interlocks in legacy tank farms.
United States
EPA effluent standards at municipal water treatment plants mandate redundant level-sensing architectures across the Great Lakes and Gulf Coast refining corridors. The Inflation Reduction Act's hydrogen hub designations accelerate electrolyzer instrumentation specifications in Texas and California. Houston's petrochemical complex sustains frame contract volumes for explosion-proof enclosures.
Netherlands
Rotterdam's port complex and North Sea platform retrofits pull demand for IIoT-enabled predictive maintenance bundles with HART-IP diagnostics. EU Green Deal national implementation frameworks subsidize level-sensing upgrades eliminating feedstock waste. Eindhoven's high-tech systems sector concentrates specification authority for pharmaceutical-grade validation protocols.
China
Dual carbon goals and process intensification projects escalate reactor vessel temperatures beyond piezoelectric ceramic limits in the Yangtze River Delta. GB standards alignment with IEC 61508 functional safety certifications filters market access for power generation applications. Shanghai's specialty chemical parks greenfield automation specifications without incumbent vendor lock-in.
France
Île-de-France's nuclear balance-of-plant operators specify dual-redundant architectures with extended IEC 61508 validation timelines. ANSM pharmaceutical guidelines and EU MDR requirements shape product validation for aseptic processing applications. Lyon's water utilities pioneer lifecycle service contracting unbundling installation and calibration into subscription structures.
Vibration Level Switch Market Key Industry Players
Swiss and German producers anchor the premium tier through calibration expertise and manufacturing precision; North American specialists hold scale advantages across oil refining and power generation corridors. The vendor base stratifies across three capability clusters: full-line process automation houses, instrumentation-focused mid-caps, and regional fabrication specialists. Dominant competitive moves include portfolio diversification into adjacent sensing technologies and geographic expansion through distribution partnerships in Central European chemical corridors.
Within the premium-tier vector, Endress+Hauser and VEGA Grieshaber exemplify European manufacturing-base positioning sustained through deep calibration expertise and specialized harsh-media applications. Emerson Electric occupies a scale-driven position across North American oil refineries and power generation facilities. These three anchors represent contrasting archetypes: Swiss precision manufacturing, German sensor specialization, and diversified industrial automation conglomeration.
| Leading Market Players |
|---|
| Endress+Hauser |
| VEGA Grieshaber |
| Emerson Electric |
| Siemens |
| ABB |
| KROHNE Messtechnik |
| AMETEK |
| Magnetrol International |
| Pepperl+Fuchs |
| Others |
Cost & Logistics Intelligence
High-purity PZT ceramic sourcing from Japanese and Chinese specialty suppliers feeds through three distinct pricing tiers for vibration level switch procurement, with contract manufacturers absorbing lead time premiums while municipal utilities exploit volume scale for standard-grade discounts.
Pricing Analysis
Lead time premiums compress pricing flexibility across the European vendor base, with expedited delivery of Hastelloy-ceramic fork assemblies commanding substantial markups over standard 316L stainless steel configurations. Three-tier pricing structure across premium, standard, and economy levels separates SIL-certified pharmaceutical-grade units from industrial water treatment specifications and bulk solids handling commodities. Cost compression in the standard tier is intensifying because fixed-price municipal frame contracts expose vendors to 316L alloy volatility. Water treatment utilities exhibit the highest price sensitivity due to lifecycle service contracting models, while pharmaceutical CMOs prioritize validation protocol support over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from German automotive-chemical clusters, while authorized distribution partners serve fragmented municipal utility procurement across France and Britain. Manufacturing concentrates in Switzerland, Germany, and the United States, with final assembly tethered to calibration expertise clusters in Baden-Württemberg and the Chicago metropolitan area. Raw material dependencies center on Japanese PZT ceramic suppliers, Chinese rare earth processing for magnetic actuators, and Swedish specialty steel for high-pressure fork forgings. Single-source vulnerability in piezoelectric ceramic supply exposes lead times to export control volatility. Distribution runs through regional technical service networks that concentrate vendor selection authority on response time commitments rather than hardware cost alone.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-purity PZT ceramic supply concentration props pricing power for vendors with captive Japanese supplier relationships, constraining capacity expansion for European competitors lacking long-term material offtake agreements.
For Market Incumbents: Lock in backward integration into PZT ceramic supply through equity stakes in Japanese specialty material producers or long-term exclusive offtake contracts. Expand SIL 2/3 certification capacity in Switzerland and Germany to extend validation timeline advantages against emerging competitors. The 80 GHz FMCW radar substitution threat in pharmaceutical applications demands preemptive bundling of vibration switches with IIoT-enabled predictive maintenance diagnostics to preserve specification authority. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany and the Netherlands opens a window for hermetically sealed mechanical resonance designs in chemical corridor retrofits previously served by refrigerant-dependent float switches. Polish and Czech greenfield chemical parks offer the most penetrable geography, lacking incumbent vendor lock-in and accelerating automation specifications through EU cohesion fund investments. A go-to-market angle anchored to lifecycle service contracting—unbundling installation, calibration, and replacement guarantees—sidesteps pure price competition against established channel operators. For Investors and Strategic Acquirers: Electromagnetic excitation architecture patent filings above 400°C service temperature is the leading indicator that molten salt energy storage and process intensification projects are scaling beyond piezoelectric reliability limits. Long-term viability favors vendors with in-house magnetic actuator expertise and harsh-media application track records, positioning them for reactor vessel temperature escalation across chemical and concentrated solar power deployment. Acquisition target archetype: mid-cap European instrumentation specialists with existing SIL certification infrastructure and underserved Central European channel presence. Watch for ECHA substance restriction expansion beyond mercury-based floats as the inflection signal for accelerated mechanical resonance substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PZT Ceramic Supply | Captive sourcing from Japanese specialty producers insulates against export control volatility and lead time compression. |
| SIL 2/3 Certification Capacity Expansion | Extended IEC 61508 validation timelines in Swiss and German facilities create defensive moats against faster-moving competitors. |
| IIoT-Enabled Predictive Maintenance Bundling | HART-IP diagnostics integration commands specification authority in Scandinavian offshore platform retrofits against radar substitution. |
| Lifecycle Service Contracting Model | Subscription structures unbundling installation and calibration concentrate vendor selection on regional technical response capability. |
| Electromagnetic Drive Technology Development | Magnetic actuator expertise above 400°C captures molten salt storage specifications in Spanish and Italian energy projects. |
Research Approach
Independent corroboration across process automation procurement managers, instrumentation R&D directors, and municipal utility maintenance heads underwrites the qualitative findings, with secondary validation drawing from ECHA regulatory filings, IEC standards documentation, and SEC 10-K disclosures from listed industrial automation conglomerates. Bottom-up triangulation across vendor shipment data and top-down reconciliation against end-use capital expenditure patterns anchor volume estimates. Primary fieldwork concentrated on German chemical corridor facilities, Dutch pharmaceutical CMOs, and French water treatment operators.
Comparable-period anchoring to historical process automation upgrade cycles across the analysis window informs the projection framework, with segmentation dimensions spanning contact versus non-contact product architectures, piezoelectric versus electromagnetic excitation technologies, and chemical processing versus pharmaceutical versus water treatment application verticals. CAGRs derive from installed base replacement rates and greenfield automation specification velocity. Forecast inputs incorporate EU F-Gas Regulation phase-down schedules and REACH compliance deadline clustering.
The model assumes a particular technology adoption path; alternative pathways for electromagnetic excitation above 400°C would alter the outlook if ceramic insulation degradation proves less severe than projected. Forecasts reflect assumptions regarding PZT ceramic supply continuity, stainless steel alloy price stability, and SIL certification timeline standardization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Smart Home Switches Market
Switches
Differential Pressure Switches Market
Switches
Proximity Switches Market
Switches
Europe Push Buttons and Signaling Devices Market
Switches
Temperature and Pressure Switches Market
Switches
United States Circuit Breaker Market
Switches
Optical Switches Market
Switches
Paralleling Switchgear Market
Switches
Push Button Dropper Market
Switches
North America Switchgear Market
Switches
ASEAN Switchgear Market
Switches
North America Push Buttons & Signaling Devices Market
Switches
Surface Mount Switch Market
Switches
Disconnect Switch Market
Switches
Optical Cross Connect (OXC) Switches Market
Switches
Global Push Buttons and Signalling Devices Market