
 Level Switches Market | 2026-2036
Level Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Level Switches Market Outlook
Stainless steel is realigning level switch economics as manufacturers substitute legacy brass and aluminum housings to meet corrosive-process durability requirements. Endress+Hauser leverages its vertical integration in sensor electronics to sustain margin advantages in hygienic applications. VEGA Grieshaber anchors its position through specialized radar-level technology leadership for extreme-temperature environments. Emerson Electric competes across the full electromechanical-to-digital portfolio with broad channel control in North American process industries.
Level switches are electromechanical or electronic devices that detect the presence, absence, or height of liquid, solid, or slurry materials within a vessel, typically operating through buoyancy, capacitance, ultrasonic time-of-flight, or magnetostrictive float principles with accuracy tolerances ranging from ±1 mm to ±10 mm depending on technology grade. Their primary industrial purpose is to automate inventory management, prevent overflow or dry-run pump damage, and enable safety interlocks in continuous or batch processing operations. Capacitive switches command premium positioning in chemical processing due to non-contact measurement reliability with aggressive media, while ultrasonic variants represent the fastest-expanding technology segment as food and beverage processors adopt CIP-compatible designs. Electromechanical float technology remains the mature volume base in water management utilities where simplicity and decades of field-proven durability outweigh digital feature requirements.
EPA effluent guidelines under the Clean Water Act, EU F-Gas Regulation restricting fluorinated greenhouse gases in industrial refrigeration, and China's GB standards for measurement instrumentation collectively elevate barrier-to-entry requirements for level switch certification and cross-border market access. FDA 21 CFR Part 11 compliance for pharmaceutical batch records and USDA dairy equipment sanitation standards further bifurcate product development paths between hygienic and industrial-grade portfolios. Stakeholders must monitor evolving interoperability demands between legacy 4-20 mA outputs and Industrial Ethernet protocols to avoid stranded asset risk in brownfield modernization programs.
Market Dynamics
Water utilities are retrofitting aging infrastructure with contactless sensing technologies while EPA and EU F-Gas Regulation tighten equipment specifications, compressing procurement cycles for electromechanical replacements.
Growth Catalysts
- EPA Clean Water Act effluent guidelines:Municipal utilities in the United States face mandated infrastructure upgrades, accelerating replacement of legacy float switches with corrosion-resistant capacitive and ultrasonic alternatives in wastewater treatment facilities.
- EU F-Gas Regulation phase-down:Industrial refrigeration and cold-chain operators across Germany, France, and Italy must retrofit systems with compliant level monitoring, creating pull-through demand for hermetically sealed switch designs.
- Stainless steel substitution:Chemical processors are abandoning brass and aluminum housings for 316L stainless steel variants that withstand aggressive media, expanding addressable market for premium-grade contactless sensors.
Market Restraints
- Semiconductor input volatility:Magnetostrictive and ultrasonic switch production depends on rare-earth magnet supply concentrated in Chinese processing facilities, exposing manufacturers to price swings and allocation constraints.
- Technical limitation in foam applications:Ultrasonic time-of-flight sensors generate false positives in aerated liquids, restricting deployment in pharmaceutical fermentation and food processing where foam presence is routine.
- Regulatory friction from China's GB standards:Cross-border certification requirements for measurement instrumentation create 12-18 month approval timelines that delay market entry for European and North American suppliers.
Strategic Opportunities
- Underpenetrated Indian municipal water sector:The country's Smart Cities Mission and AMRUT 2.0 program fund digitization of distribution networks, opening deployment channels for battery-powered wireless level monitors in remote pumping stations.
- Technology convergence of radar and IIoT:Integration of 80 GHz FMCW radar with edge computing platforms enables predictive maintenance algorithms, commanding premium positioning in chemical tank farms.
- Regulatory tailwind from FDA 21 CFR Part 11:Pharmaceutical batch record digitization mandates are forcing CMOs to replace mechanical switches with validated electronic systems that output tamper-proof data logs.
Industry Challenges
- Skill gap in field calibration:Ultrasonic and radar technologies require technicians trained in time-of-flight parameter adjustment, a capability scarce in municipal maintenance departments accustomed to mechanical float servicing.
- Capex intensity for hygienic certification:3A Sanitary Standards and EHEDG validation demand specialized surface finishing and documentation that adds 40-60% to production costs for food and beverage switch variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Level Switches Market |
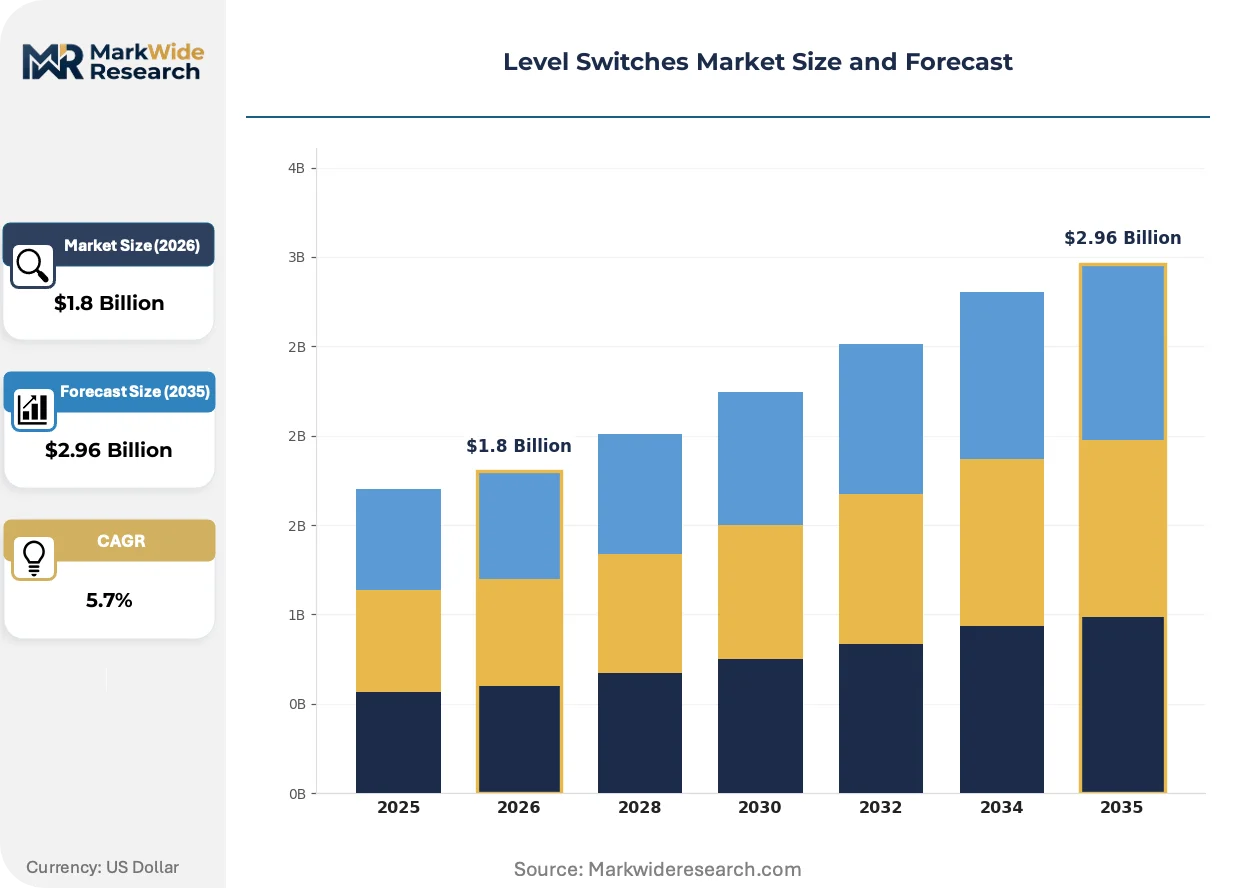
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Float Switches, Capacitive Switches, Ultrasonic Switches, Magnetostrictive Switches Technology: Electromechanical, Magnetic, Optical, Pneumatic Application: Water Management, Oil & Gas, Chemical Processing, Food & Beverage End User: Manufacturing, Utilities, HVAC, Pharmaceuticals |
| Companies Covered | Endress+Hauser, VEGA Grieshaber, Emerson Electric, ABB, AMETEK, Magnetrol International, Bürkert Fluid Control Systems, Pepperl+Fuchs, Nivelco Process Control, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Level Switches Market Strategic Shifts
Sensor miniaturization and edge intelligence are compressing the gap between discrete level detection and continuous measurement, blurring traditional product category boundaries.
Silicon carbide (SiC) sensing elements are electrifying high-temperature level detection in molten metal and slag applications. Steel foundries in Germany and Japan are adopting these ceramic-based switches at pilot scale. The technology is electrifying a market segment previously served by mechanical chain-and-float systems with 10-year replacement cycles.
REACH substance restrictions on nickel alloys are forcing European manufacturers to redesign wetted components. The regulation bans certain nickel coatings in prolonged skin-contact applications, though industrial exemptions remain under review. Process industries are responding by accelerating qualification of hastelloy and titanium alternatives in chemical handling equipment.
Buyers are consolidating vendor relationships around full-stack automation suppliers capable of integrating level switches with PLC and SCADA architectures. System integrators in the United States are bundling sensor procurement with commissioning services, displacing traditional distribution channels. This concentration is most visible in Texas and Louisiana petrochemical corridors where EPC firms specify approved vendor lists.
Level Switches Market Segmentation
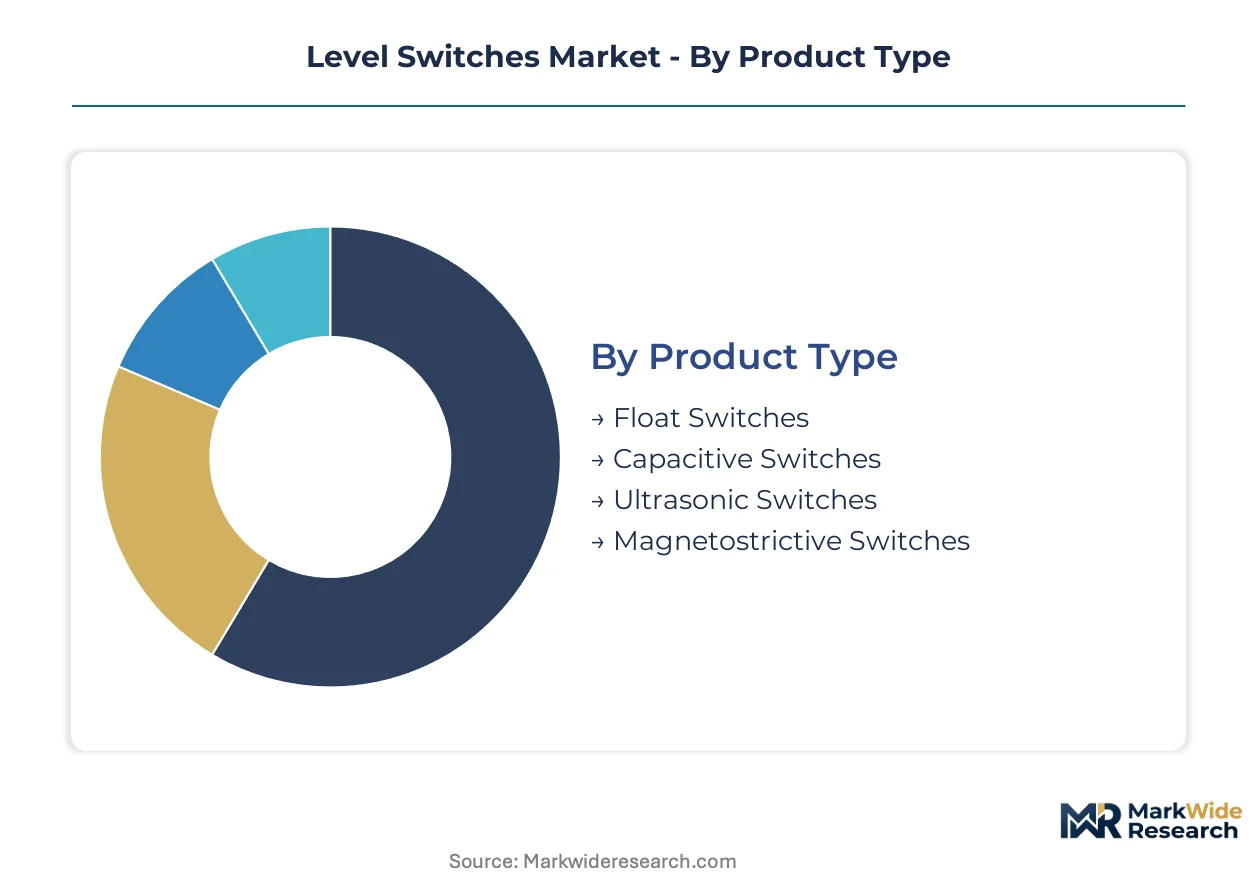
Technology selection in level switches hinges on media aggressiveness, temperature extremes, and cleanliness requirements. Buyers trade acquisition cost against total lifecycle expense, including calibration frequency and replacement intervals in corrosive or hygienic environments.
Product Type:
Procurement patterns diverge sharply between utilities seeking decades of field durability and chemical processors prioritizing non-contact measurement reliability.
- Float Switches:Electromechanical buoyancy devices with sealed reed switches or microswitches activated by magnet-equipped floats. Water management utilities in Germany and the United States specify these for raw sewage lift stations where simplicity outweighs digital sophistication, though brass housing corrosion drives 316L stainless substitution.
- Capacitive Switches:Non-contact sensors detecting dielectric constant changes between probe and vessel wall, eliminating moving parts. Chemical processing facilities in Texas and Louisiana deploy these for aggressive acids and caustics where mechanical wear would trigger frequent maintenance shutdowns.
- Ultrasonic Switches:Time-of-flight sensors emitting high-frequency pulses to detect liquid surfaces. Food and beverage CIP systems specify these for tank level monitoring where probe contact risks contamination.
- Magnetostrictive Switches:Precision devices measuring float position via sonic pulse travel time along a waveguide. Oil and gas tank farms adopt these for custody transfer accuracy where ±1 mm tolerance justifies premium positioning.
Volume sits with float switches; growth tilts toward ultrasonic variants.
Technology:
Retrofit decisions in brownfield facilities weigh legacy 4-20 mA compatibility against Industrial Ethernet migration timelines.
- Electromechanical:Mature reed switch and microswitch architectures dominating municipal water budgets. Indian Smart Cities Mission procurement specifications favor these for battery-powered remote pumping stations where power reliability is intermittent.
- Magnetic:Hall-effect and magnetoresistive sensors offering solid-state reliability without mechanical contacts. HVAC chiller systems specify these for refrigerant level monitoring under EU F-Gas Regulation compliance deadlines.
- Optical:Infrared or laser-based detection for transparent or highly reflective liquids. Semiconductor wafer fabrication facilities deploy these for ultrapure chemical handling where metallic contamination is prohibited.
- Pneumatic:Air-displacement or bubble tube systems for explosive atmospheres where electrical ignition risks are unacceptable. Offshore oil platforms maintain these for slop tank monitoring in Zone 0 hazardous areas.
Electromechanical commands installed base; optical climbs fastest on semiconductor capex cycles.
Application:
End-use sector selection determines housing material, sealing specification, and certification burden.
- Water Management:Municipal and industrial wastewater treatment demanding corrosion-resistant wetted components. EPA effluent guidelines under the Clean Water Act accelerate capacitive and ultrasonic adoption in United States facilities replacing legacy float installations.
- Oil & Gas:Upstream production separators and downstream tank farms requiring SIL-rated safety interlocks. Magnetostrictive technology penetrates this segment on custody transfer accuracy requirements.
- Chemical Processing:Aggressive media handling with Hastelloy or titanium wetted parts. REACH substance restrictions on nickel alloys force European processors to requalify alternative metallurgies.
- Food & Beverage:3A Sanitary Standards and EHEDG validation mandatory for dairy and beverage contact. Surface finish specifications add 40-60% production cost premium over industrial grades.
Water management anchors procurement volume; food and beverage expands most quickly on hygienic digitization mandates.
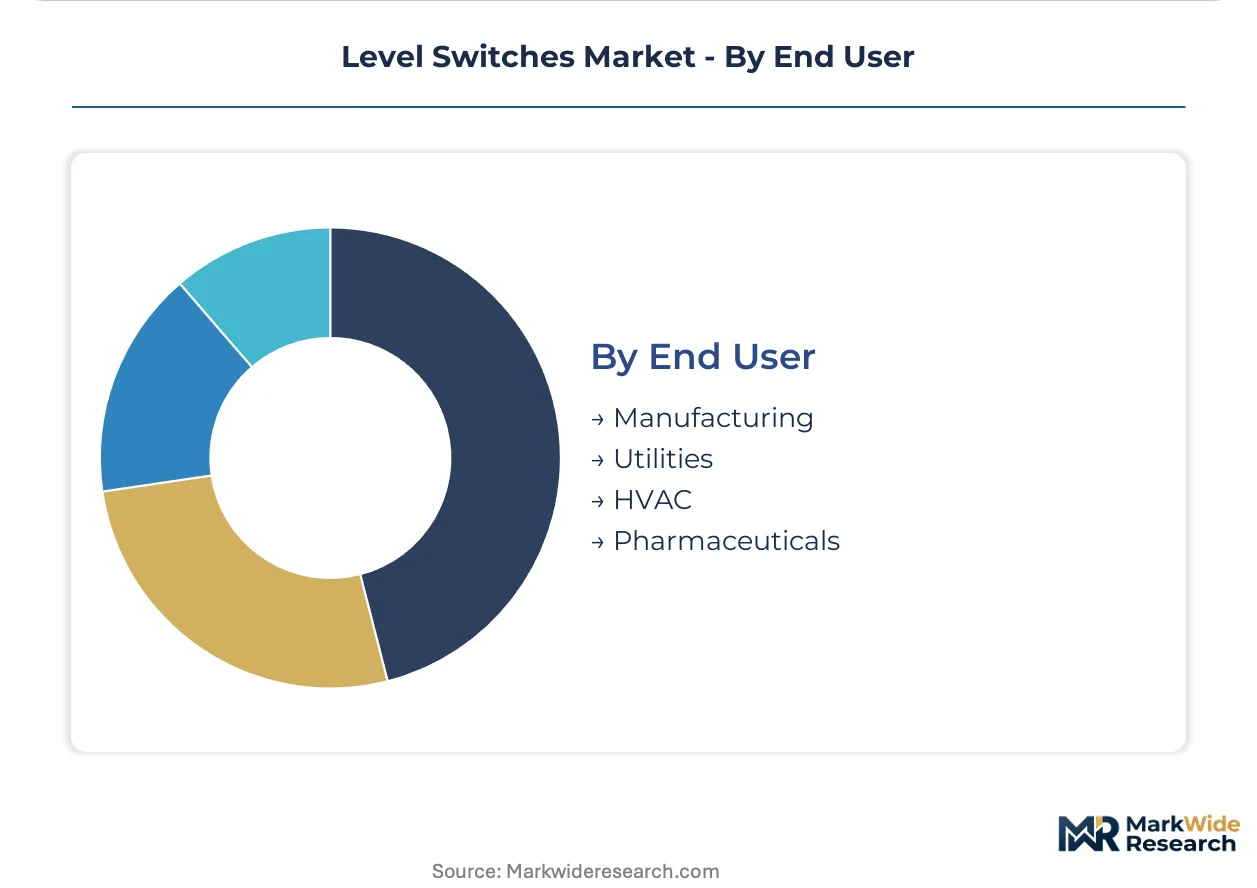
End User:
Capital intensity and regulatory exposure shape specification authority and vendor consolidation patterns.
- Manufacturing:Discrete and process production lines integrating level switches with PLC architectures. United States system integrators bundle sensor procurement with commissioning services, displacing traditional distribution.
- Utilities:Municipal water, wastewater, and district energy operators with decades-long asset horizons. Electromechanical float technology persists here where maintenance departments lack ultrasonic calibration training.
- HVAC:Commercial and industrial climate systems facing refrigerant phase-down regulations. EU F-Gas Regulation drives hermetic sealing requirements for cold-chain level monitoring.
- Pharmaceuticals:FDA 21 CFR Part 11 compliance mandates tamper-proof electronic data logging. Contract manufacturing organizations replace mechanical switches with validated electronic systems for batch record integrity.
Utilities dominate replacement volume; pharmaceuticals command steepest expansion trajectory on regulatory digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for level switches concentrates in Germany, the United States, and China as municipal utilities and chemical processors retrofit aging infrastructure with contactless sensing technologies. Procurement cycles compress where EPA effluent guidelines and EU F-Gas Regulation mandate equipment replacements.
United States
Municipal water utilities in Texas and Louisiana prioritize magnetostrictive switches for custody transfer accuracy in petrochemical tank farms. EPA Clean Water Act effluent guidelines force wastewater treatment facilities to abandon legacy float switches for corrosion-resistant capacitive alternatives. Houston-Galveston chemical corridor procurement specifications now require SIL-rated safety interlocks.
Germany
Steel foundries in the Ruhr region pilot silicon carbide sensing elements for molten metal level detection at extreme temperatures. EU F-Gas Regulation phase-down deadlines accelerate hermetic sealing requirements for industrial refrigeration level monitors. Bavarian automotive suppliers specify hygienic-certified switches for battery electrolyte handling systems.
China
GB standards for measurement instrumentation impose 12-18 month certification timelines that delay European supplier market entry. Yangtze River Delta chemical processors substitute brass housings with 316L stainless steel variants for aggressive media durability. Shanghai municipal utilities deploy battery-powered wireless level monitors under Smart Cities infrastructure programs.
India
AMRUT 2.0 program funding digitizes distribution networks across Maharashtra and Gujarat state water authorities. BIS certification requirements for measurement instrumentation create compliance hurdles for imported electromechanical float switches. Tamil Nadu textile processors adopt ultrasonic variants for dye bath monitoring where probe contact risks contamination.
Japan
Semiconductor wafer fabrication facilities in Kyushu specify optical level detection for ultrapure chemical handling where metallic contamination is prohibited. METI industrial efficiency standards promote predictive maintenance algorithms integrating radar sensors with edge computing platforms. Kansai region pharmaceutical contract manufacturers replace mechanical switches with FDA 21 CFR Part 11 validated electronic systems.
Level Switches Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with full-stack automation suppliers consolidating procurement relationships while component specialists defend niche technology positions. The vendor base organizes around three archetypes: diversified industrial conglomerates with broad electromechanical-to-digital portfolios, sensor-focused specialists leveraging vertical integration in electronics, and regional fabricators serving price-sensitive utility procurement. Competitive dynamics center on backward integration into sensor element production and bundling sensor procurement with system integration services.
Among diversified industrial conglomerates, Endress+Hauser and Emerson Electric occupy positions spanning hygienic applications through process industries. VEGA Grieshaber exemplifies the technology-specialist archetype with concentrated expertise in radar-level measurement. These three companies anchor the premium tier where specification authority rests with engineering-procurement-construction firms and system integrators rather than traditional distribution channels.
| Leading Market Players |
|---|
| Endress+Hauser |
| VEGA Grieshaber |
| Emerson Electric |
| ABB |
| AMETEK |
| Magnetrol International |
| Bürkert Fluid Control Systems |
| Pepperl+Fuchs |
| Nivelco Process Control |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists in Germany and Japan anchor premium-tier supply, translating captive sensor-element production into pricing discipline that resists commoditization pressure from Asian contract manufacturers. Their ownership structure insulates long-term certification investments from quarterly margin scrutiny, compressing price competition in hygienic and SIL-rated segments while forcing volume players toward bare-bones float switch economics.
Pricing Analysis
Volume concentrates in electromechanical float switches where municipal utilities prioritize acquisition cost over lifecycle expense, while margins accrue to capacitive and magnetostrictive variants serving chemical and oil and gas custody-transfer applications. Price differentiation hinges on certification grade—FDA 21 CFR Part 11 validation and 3A Sanitary Standards add 40-60% production cost premiums—and geographic delivery cost differentials between European integrated producers and Asian fabricators. Cost compression in standard-grade ultrasonic variants is intensifying as Chinese manufacturers scale 80 GHz radar module output. Water management utilities exhibit highest price sensitivity, deferring contactless upgrades until regulatory mandates force procurement; pharmaceutical contract manufacturers show lowest sensitivity, accepting premium positioning for tamper-proof electronic data logging compliance.
Supply Chain Analysis
Workforce availability constraints in Bavarian and Baden-Württemberg sensor electronics clusters limit expansion of high-frequency radar module assembly, pushing VEGA Grieshaber and Endress+Hauser toward automation investments. Manufacturing concentrates in Germany, China, and the United States, with Yangtze River Delta facilities supplying 316L stainless steel housings and sealed reed switch subassemblies. Raw material dependencies rest on rare-earth magnet supply for magnetostrictive waveguides, ceramic substrates for silicon carbide sensing elements, and specialty nickel alloys facing REACH substance restriction reviews. Single-source vulnerability in Chinese rare-earth processing exposes magnetostrictive switch producers to allocation constraints. Distribution runs through system integrators in Texas and Louisiana petrochemical corridors, displacing traditional industrial distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EPA effluent guidelines and EU F-Gas Regulation phase-down deadlines erect barrier-to-entry moats for players with validated certification portfolios, marginalizing undifferentiated competitors unable to absorb 12-18 month approval timelines.
For Market Incumbents: Deepen backward integration into ceramic sensing element production to secure silicon carbide supply for molten metal applications, insulating margin structure from rare-earth price volatility. Fortify channel control in North American process industries by bundling level switch procurement with SCADA commissioning services, countering displacement threat from full-stack automation suppliers. For New Entrants and Emerging Players: A $400-600 per-unit price gap between premium radar-level systems and economy float switches creates entry space for mid-tier ultrasonic variants targeting Indian municipal water authorities under AMRUT 2.0 funding. Penetrate Maharashtra and Gujarat state water departments with battery-powered wireless monitors, leveraging local system integrator relationships to bypass BIS certification delays for imported electromechanical alternatives. For Investors and Strategic Acquirers: Distressed-cycle entries favor sensor-focused specialists with captive radar module production in southern Germany, where family ownership transitions create acquisition windows without strategic auction premiums. Watch FDA 21 CFR Part 11 enforcement intensity against pharmaceutical contract manufacturers as inflection indicator—accelerated warning letter activity signals replacement demand inflection for validated electronic systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Sensing Elements | Captive silicon carbide supply secures high-temperature level detection positioning in German steel foundries. |
| System Integrator Partnership Program | Bundled sensor-commissioning contracts displace traditional distribution in Texas petrochemical corridors. |
| FDA 21 CFR Part 11 Validation Investment | Tamper-proof data logging capability opens pharmaceutical CMO replacement cycles. |
| Wireless Battery-Powered Product Line | Remote monitoring alignment captures Indian Smart Cities Mission infrastructure funding. |
| REACH-Compliant Alloy Qualification | Hastelloy and titanium alternatives future-proof European chemical processor supply relationships. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with maintenance directors at municipal water utilities, procurement leads at Texas and Louisiana chemical processors, and aftermarket service heads at German sensor manufacturers. Secondary validation drew from EPA effluent guideline enforcement databases, EU F-Gas Regulation implementation reports, and China GB standards certification timelines. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Data-stream reconciliation between shipment volumes reported by sensor electronics suppliers and end-use procurement records from water management utilities ensured forecast consistency. Segmentation modeling spanned technology type, housing material grade, application sector, and regional regulatory cluster. CAGRs were derived from regression analysis of replacement cycle compression and regulatory mandate acceleration, with specific weighting for semiconductor input cost trajectories and rare-earth magnet supply availability.
Inputs from FDA warning letter databases and EU ECHA substance restriction consultations were available through the study window; gaps in real-time Indian AMRUT 2.0 disbursement data introduce uncertainty bands around South Asia demand trajectories. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and certification timeline stability. Material deviation in EPA Clean Water Act enforcement intensity or REACH nickel alloy exemption reviews warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Differential Pressure Switches Market
Switches
High-Voltage Disconnect Switch Market
Switches
Argentina Automotive Reed Sensors Switches Market
Switches
Power Load Switches Market
Switches
5G Solid State Switches Market
Switches
United States Switchgear Market
Switches
North America Switchgear Market
Switches
Mexico Rocker Switch Market
Switches
Global Float Level Switches Market
Switches
Rotary Limit Switches Market
Switches
India Switchgear Market
Switches
Smart Home Switches Market
Switches
Residual Current Circuit Breaker Market
Switches
Middle-East and Africa Low Voltage Switchgear Market
Switches
Asia-Pacific High Voltage Switchgear Market
Switches
Panel Mounted Disconnect Switch Market