
 Acetylene Market | 2026-2036
Acetylene Market Size, Share, and Industry Trends Forecast 2026-2036
Acetylene Market Analysis
Premium electronic-grade acetylene is decoupling from commodity industrial-grade supply chains on purity specifications and captive production requirements. BASF SE leverages its Ludwigshafen integrated site to sustain vertical control over acetylene derivative streams for specialty chemicals. Linde plc anchors global merchant gas distribution through cryogenic and cylinder supply networks spanning multiple continents. Air Liquide differentiates via on-site generation contracts for semiconductor fabs requiring sub-ppm impurity thresholds.
Acetylene is a hydrocarbon gas with the chemical formula C₂H₂, produced commercially through calcium carbide hydrolysis or thermal cracking of hydrocarbons, and characterized by a triple bond that enables high-temperature combustion reaching approximately 3,100°C in oxygen. Its primary industrial purpose centers on oxy-acetylene welding and cutting, plus as a feedstock for chemical synthesis of plastics, solvents, and synthetic rubber intermediates. Chemical synthesis applications lead absolute volume consumption due to vinyl acetate monomer and 1,4-butanediol derivative demand, while electronic grade commands the steepest price premiums from semiconductor fabrication requirements. Welding and cutting segments remain mature in developed economies but retain replacement demand cycles in construction and shipbreaking yards across South and Southeast Asia.
OSHA mandates workplace exposure limits and cylinder handling protocols that shape safety equipment bundling and service contract structures in the United States. EPA air emissions standards for carbide furnace operations constrain brownfield expansion and elevate compliance capital for domestic producers. China's MEE enforces dual carbon targets that tighten energy intensity benchmarks for calcium carbide routes, favoring natural gas-based acetylene investments in new capacity. Stakeholders must monitor regulatory divergence between carbide-based and hydrocarbon cracking production pathways as carbon border adjustments reshape competitive economics across supply regions.
Market Dynamics
China's MEE enforcement of dual carbon targets is forcing carbide-based acetylene producers toward natural gas cracking alternatives, fundamentally restructuring feedstock economics and capital allocation across the supply base.
Growth Catalysts
- Vinyl Acetate Monomer Expansion:Polymer manufacturers in East China chemical clusters are scaling derivative capacity, pulling acetylene feedstock demand upward through integrated petrochemical complexes.
- Electronic-Grade Purity Requirements:Semiconductor fabrication standards below sub-ppm thresholds are creating captive production mandates that bypass commodity supply chains entirely.
- MEE Dual Carbon Enforcement:China's tightening emissions benchmarks for calcium carbide routes are redirecting investment toward cleaner hydrocarbon cracking technologies.
Market Restraints
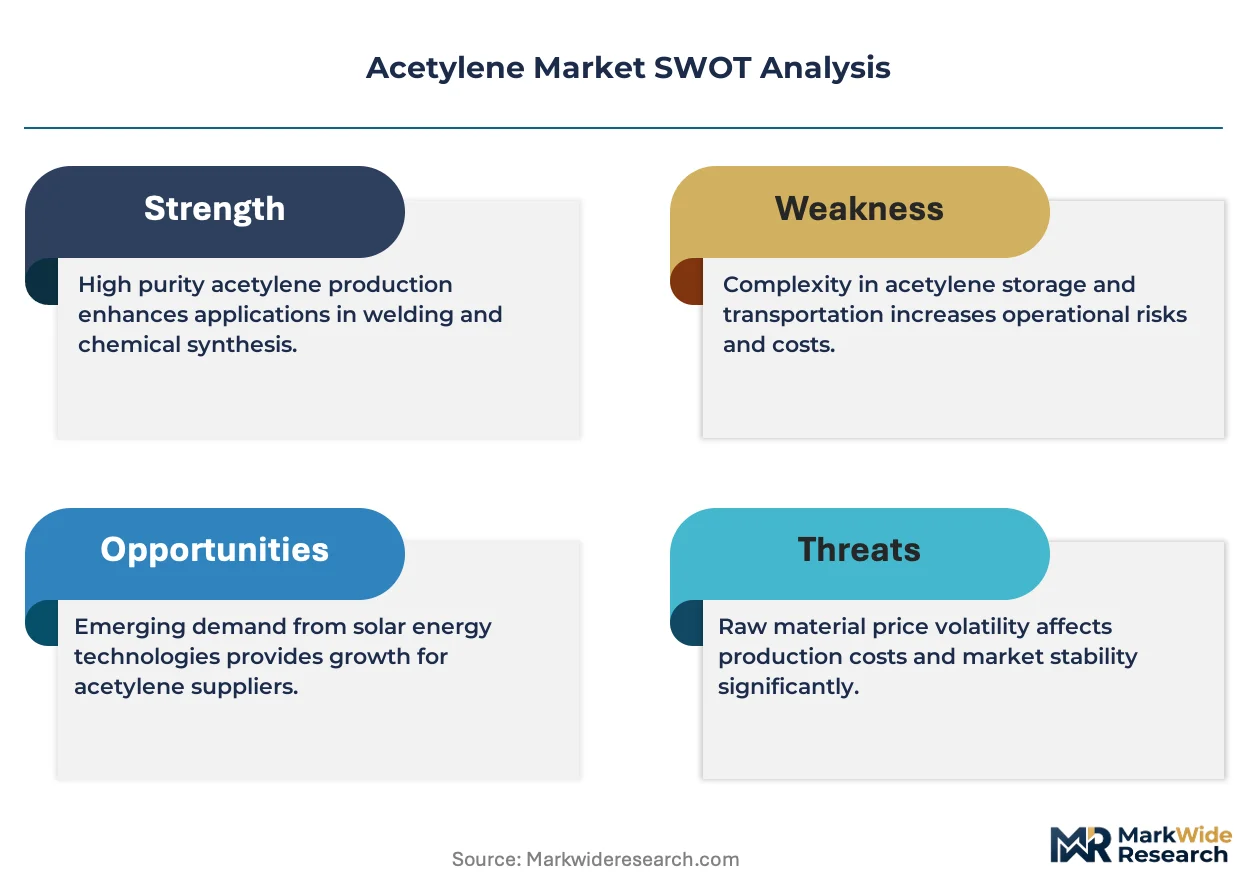
- Calcium Carbide Input Volatility:Energy-intensive carbide production faces escalating electricity cost exposure in regions with carbon-adjusted power tariffs.
- Supply Concentration Risk:Carbide-based capacity clusters in Northwestern China dominate global merchant supply, creating geographic single-point vulnerability.
- Natural Gas Feedstock Limitation:Hydrocarbon cracking requires pipeline proximity and cryogenic infrastructure unavailable in legacy carbide-producing regions.
Strategic Opportunities
- On-Site Generation Contracts:Semiconductor fabs are adopting captive acetylene production models that eliminate cylinder logistics and purity degradation risks.
- South and Southeast Asia Welding Demand:Shipbreaking yards and construction activity in Bangladesh, India, and Vietnam sustain replacement cylinder cycles for industrial-grade supply.
- EU Green Deal Carbon Border Adjustments:Import tariffs on high-emission acetylene derivatives are creating competitive openings for low-carbon production pathways.
Industry Challenges
- Cryogenic Logistics Expertise Gap:Natural gas cracking expansion requires specialized cold-chain handling capabilities scarce in legacy carbide-operator workforces.
- Electronic-Grade Certification Timelines:Semiconductor supplier qualification protocols extend months, freezing out new entrants regardless of technical capability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acetylene Market |
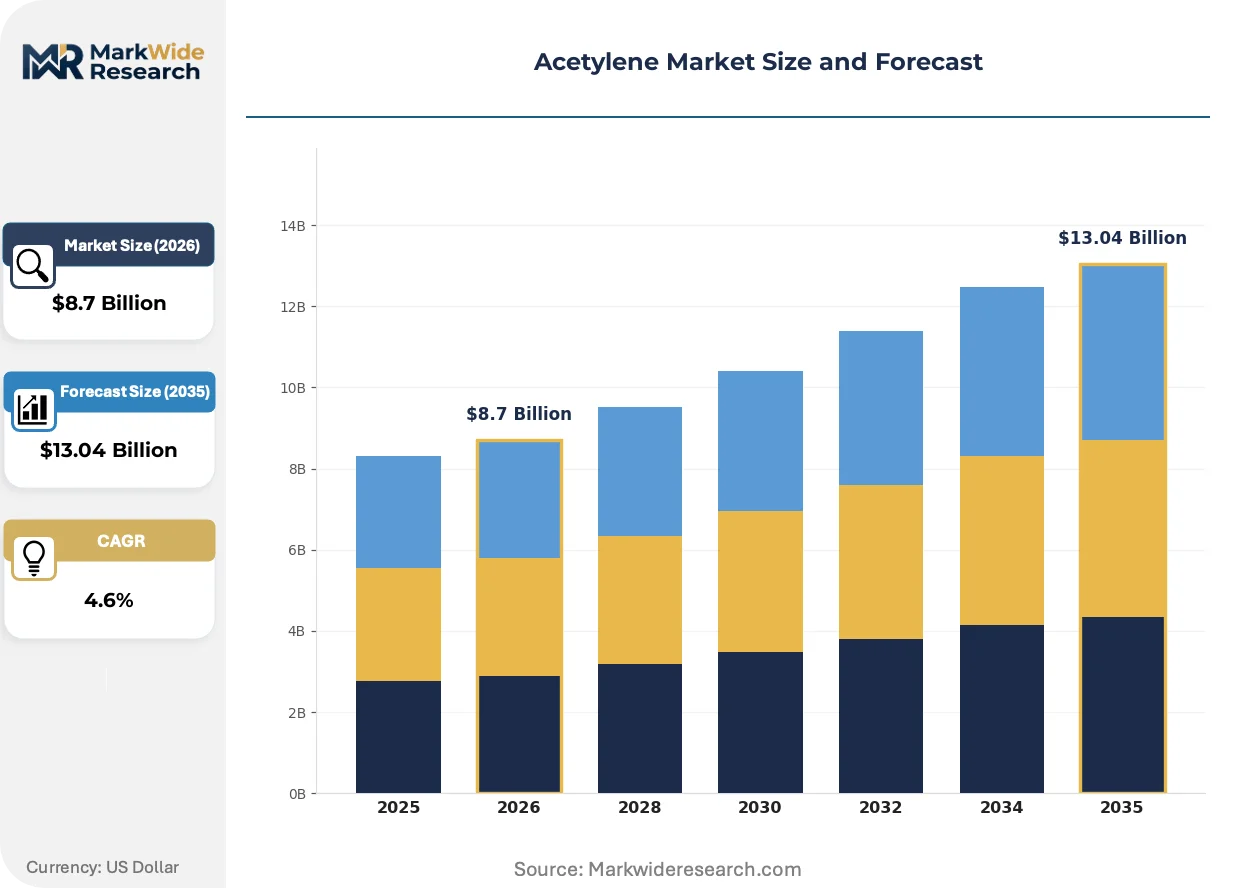
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Welding, Cutting, Chemical Synthesis, Lighting Product Type: Industrial Grade, Laboratory Grade, Medical Grade, Electronic Grade End User: Manufacturing, Construction, Pharmaceuticals, Electronics Distribution Channel: Direct Sales, Online Sales, Distributors, Retail Stores |
| Companies Covered | Airgas, Gulf Cryo, Linde plc, Praxair, Toho Acetylene Co. Ltd, Air Liquide, China Petroleum and Chemical Corporation, Sinopec, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acetylene Market Emerging Trajectories
Acetylene supply chains are bifurcating between commodity industrial-grade bulk distribution and ultra-high-purity captive production, with technology choices and regulatory compliance requirements diverging sharply between these pathways.
Plasma-assisted hydrocarbon cracking is unifying temperature control and feedstock flexibility in next-generation acetylene production. Petrochemical operators in integrated complexes are piloting this technology to displace carbide-based units. The approach is unifying process efficiency gains with carbon intensity reductions that satisfy MEE audit protocols.
REACH substance registration requirements in Europe are tightening traceability mandates for acetylene derivatives used in polymer manufacturing. Chemical producers must now document feedstock origin and production pathway carbon intensity across supply chains. Vinyl acetate monomer suppliers serving EU coatings markets are restructuring procurement to exclude carbide-based acetylene from qualified supplier lists.
Long-term on-site generation contracts are displacing traditional cylinder merchant supply for semiconductor fabrication facilities. Air separation specialists are embedding acetylene production units directly within fab perimeters, eliminating transport purity risks. This model concentrates in East Asian memory and logic chip manufacturing clusters where sub-ppm contamination thresholds are non-negotiable.
Acetylene Market Segmentation
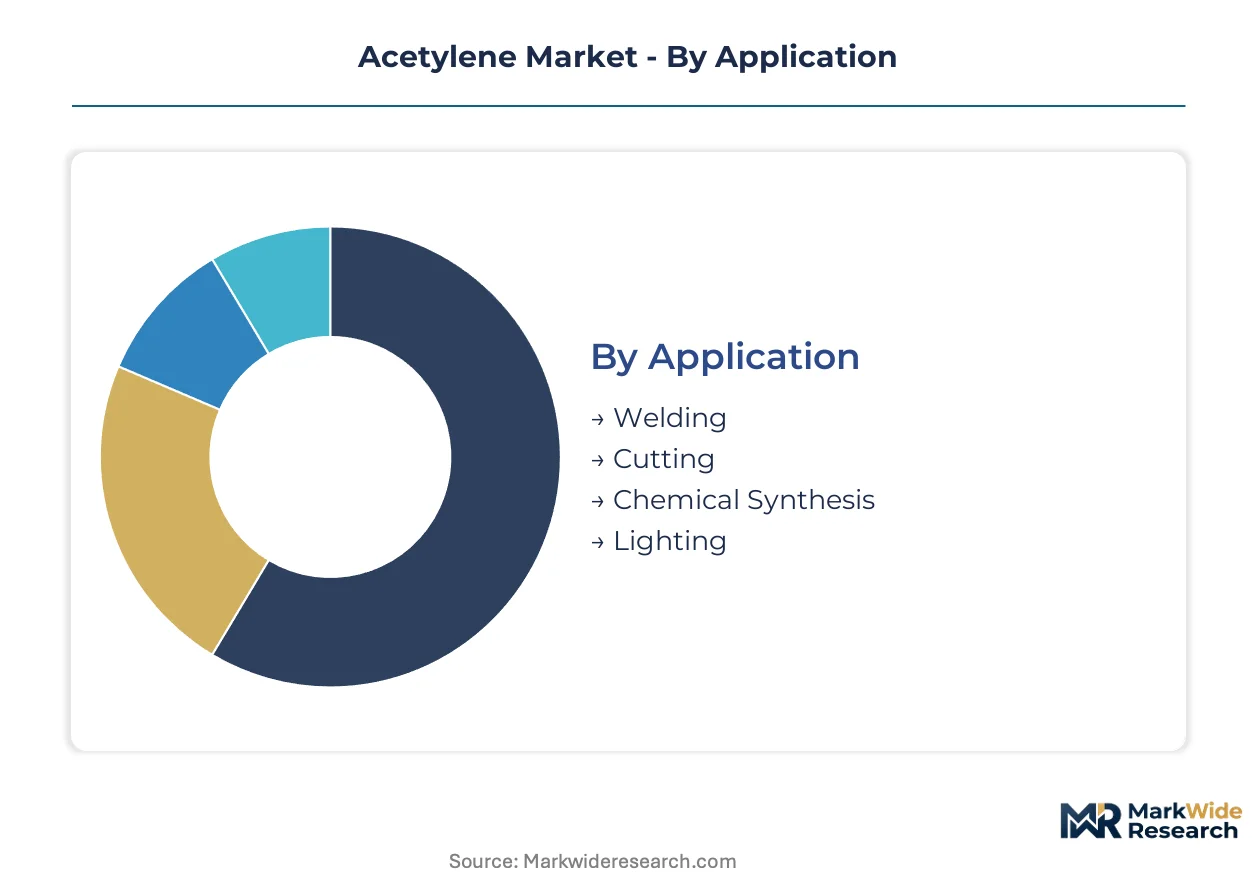
Acetylene market segmentation reveals divergent supply chain economics across purity grades and end-use applications. Each category reflects distinct buyer priorities—from semiconductor fabs demanding sub-ppm contamination thresholds to shipyards prioritizing cylinder reliability over specification stringency.
Application:
Buyers in this category separate by process temperature requirements and feedstock integration depth.
- Chemical Synthesis:Vinyl acetate monomer and 1,4-butanediol producers consume acetylene as a primary feedstock for polymer intermediates. East China chemical clusters around Nanjing and Ningbo anchor demand through integrated petrochemical complexes that consume derivatives at scale. This segment leads absolute volume consumption due to continuous process requirements and captive supply arrangements.
- Welding:Oxy-acetylene torch operators require consistent flame temperature reaching approximately 3,100°C in oxygen for metal joining operations. Shipbreaking yards in Bangladesh, India, and Vietnam sustain replacement cylinder cycles where construction activity outpaces automated welding adoption. Mature demand in developed economies contrasts with sustained growth in South and Southeast Asian fabrication yards.
- Cutting:Thermal lancing and metal severing applications prioritize portability and cylinder logistics over purity specifications.
- Lighting:Carbide lamp heritage applications persist in specialized mining and caving equipment niches.
Chemical Synthesis leads volumes today; Welding is gaining share fastest in emerging Asian construction markets.
Product Type:
Specification tiers in this category stratify by impurity tolerance measured in parts per million.
- Electronic Grade:Sub-ppm impurity thresholds mandate captive production units embedded within semiconductor fab perimeters. Memory and logic chip manufacturers in East Asia bypass traditional cylinder supply entirely to eliminate transport contamination risks. This grade commands the steepest price premiums and requires months-long supplier qualification protocols that freeze out new entrants.
- Industrial Grade:Standard purity specifications serve welding, cutting, and general chemical synthesis where trace contaminant tolerance exceeds semiconductor requirements. Bulk distribution through cryogenic and cylinder networks spans multiple continents with replacement demand cycles tied to construction activity. This grade dominates merchant gas revenue through volume scale rather than unit margin.
- Laboratory Grade:Intermediate purity for analytical instrumentation and research applications.
- Medical Grade:Specialized specifications for respiratory therapy and surgical equipment sterilization.
Industrial Grade anchors current revenue; Electronic Grade is expanding most quickly as semiconductor fabrication capacity multiplies.
End User:
Customer type in this category determines contract structure—from long-term on-site generation to spot cylinder purchases.
- Electronics:Semiconductor fabs require acetylene for deposition processes where metallic impurity levels below one part per billion prevent chip defects. Air separation specialists and gas majors compete through on-site generation contracts that eliminate logistics risk and secure decade-long revenue streams. This end user commands the most stringent supplier qualification timelines in the market.
- Manufacturing:Polymer producers and metal fabricators balance feedstock security against working capital efficiency in procurement decisions. Integrated petrochemical complexes in China favor backward integration into acetylene production while smaller fabricators rely on merchant cylinder supply. MEE dual carbon enforcement is redirecting investment toward natural gas cracking alternatives for this customer base.
- Construction:Project-based demand from infrastructure and shipbuilding creates irregular cylinder replacement cycles.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis and packaging sterilization drive specialized purity requirements.
Manufacturing captures the largest volume share; Electronics is climbing the fastest as captive production models displace traditional supply.
Distribution Channel:
Channel selection in this category hinges on delivery frequency, volume scale, and technical service requirements.
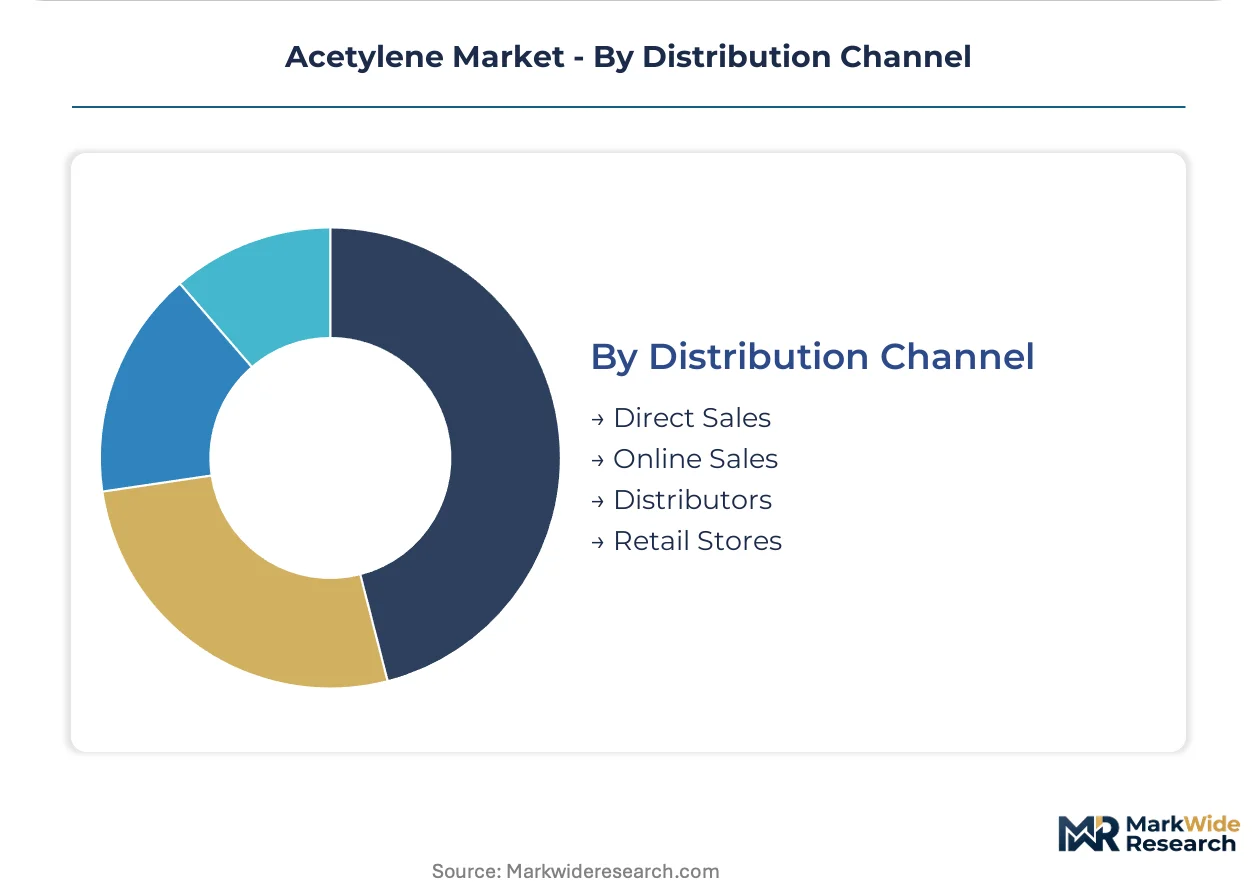
- Direct Sales:Large-volume consumers in chemical synthesis and electronics negotiate directly with producers for on-site generation or pipeline supply. These arrangements bundle technical service, safety equipment, and regulatory compliance support into multi-year contracts. Direct relationships dominate where cylinder logistics costs would erode margins on high-volume consumption.
- Distributors:Regional gas specialists aggregate demand from small and mid-size fabricators, construction contractors, and maintenance shops. These intermediaries manage cylinder exchange programs, safety training, and localized inventory positioning that producers cannot economically replicate. Distributor networks concentrate in industrial corridors where customer density justifies route optimization.
- Online Sales:Digital procurement platforms serve small-volume buyers with standardized cylinder specifications and transparent pricing.
- Retail Stores:Hardware and welding supply outlets cater to individual tradespeople and emergency replacement needs.
Distributors handle the greatest transaction volume; Direct Sales is expanding most quickly as semiconductor fabs adopt captive production models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized welding technicians and petrochemical process engineers concentrate in coastal industrial corridors where acetylene derivatives feed integrated chemical complexes. Regional demand patterns diverge sharply between semiconductor fabrication clusters requiring electronic-grade purity and construction markets dependent on cylinder logistics.
China
Vinyl acetate monomer producers in Nanjing and Ningbo chemical clusters consume acetylene derivatives at continuous process scale. MEE dual carbon enforcement tightens energy intensity benchmarks for calcium carbide routes, redirecting new investment toward natural gas cracking alternatives in pipeline-proximate regions. Northwestern carbide-based capacity faces stranded asset risk as coastal petrochemical complexes secure cleaner feedstock supply.
United States
OSHA-mandated workplace exposure limits and cylinder handling protocols shape safety equipment bundling across construction and fabrication yards. EPA air emissions standards constrain brownfield expansion for carbide furnace operations, elevating compliance capital requirements for domestic producers. Gulf Coast petrochemical corridors leverage existing hydrocarbon infrastructure to sustain acetylene derivative output for polymer intermediates.
Germany
REACH substance registration requirements tighten traceability mandates for acetylene derivatives entering EU coatings markets. ECHA enforcement pressures vinyl acetate monomer suppliers to document feedstock origin and production pathway carbon intensity. Ludwigshafen and other Rhineland chemical clusters maintain integrated acetylene derivative streams through backward integration into captive production.
Japan
METI industrial policy supports semiconductor fabrication capacity expansion, pulling electronic-grade acetylene demand toward sub-ppm purity thresholds. Memory and logic chip manufacturers in Kyushu and Kanto regions adopt on-site generation contracts that eliminate transport contamination risks. Supplier qualification protocols extending months freeze out new entrants regardless of technical capability.
South Korea
Busan-Ulsan shipbreaking yards sustain replacement cylinder cycles for industrial-grade acetylene where oxy-acetylene cutting outpaces automated alternatives. MFDS and national industrial safety frameworks govern cylinder handling and workplace exposure in fabrication facilities. Seoul Capital Area semiconductor fabs concentrate captive acetylene production investment to secure decade-long supply contracts.
Acetylene Market Vendor Landscape
Capital-heavy producers compete with asset-light distributors across a bifurcated structure separating integrated chemical manufacturers from regional gas specialists. The market consolidates around three tiers: multinational industrial gas majors with cryogenic infrastructure, petrochemical operators with backward-integrated captive supply, and regional cylinder distributors managing localized route optimization. Dominant competitive moves include on-site generation contract expansion to displace merchant supply, and strategic partnerships with semiconductor fabs to embed production units within facility perimeters.
Among European-integrated chemical operators, BASF SE anchors specialty acetylene derivative streams through its Ludwigshafen complex. Linde plc and Air Liquide occupy positions spanning cryogenic distribution networks and on-site generation contracting for semiconductor fabrication. Toho Acetylene Co. Ltd represents the Asia-Pacific specialist tier with concentrated regional cylinder logistics expertise.
| Leading Market Players |
|---|
| Airgas |
| Gulf Cryo |
| Linde plc |
| Praxair |
| Toho Acetylene Co. Ltd |
| Air Liquide |
| China Petroleum and Chemical Corporation |
| Sinopec |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Captive production integration at semiconductor fabrication facilities anchors both supply security and pricing power for electronic-grade acetylene, while commodity industrial-grade supply chains remain exposed to carbide input volatility and carbon-adjusted electricity tariffs. China's MEE dual carbon enforcement is bifurcating feedstock economics between legacy calcium carbide routes and natural gas cracking alternatives, with coastal petrochemical complexes capturing margin premiums through cleaner production pathways.
Pricing Analysis
Bundled on-site generation contracts for semiconductor fabs command substantial premiums over unbundled cylinder merchant supply due to purity guarantees and logistics elimination. Price differentiation rests on certification grade—electronic-grade sub-ppm specifications versus industrial-grade welding tolerances—and volume scale through long-term offtake arrangements. Cost compression in carbide-based supply is intensifying because MEE energy intensity benchmarks raise electricity input costs for Northwestern Chinese producers. Small fabricators and construction contractors exhibit highest price sensitivity, while semiconductor fabs prioritize supply security over unit cost.
Supply Chain Analysis
Semiconductor supplier qualification protocols extending months gate entry for electronic-grade acetylene, freezing out unproven producers regardless of technical capability. Geographic supply concentrates in China, Germany, and the United States, with carbide-based capacity clustering in Northwestern China and hydrocarbon cracking dominating coastal petrochemical corridors. Raw material dependencies center on calcium carbide, natural gas feedstock, and specialized cylinder alloys for high-pressure containment. Single-source vulnerability runs through carbide furnace operations facing stranded asset risk from MEE enforcement. Distribution runs through cryogenic bulk networks for chemical synthesis and regional cylinder exchange programs for welding applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acetylene demand functions as a regulatory compounder where China's MEE dual carbon targets and EU REACH traceability mandates are restructuring procurement qualification criteria across polymer and electronics supply chains.
For Market Incumbents: Cement backward integration into natural gas cracking capacity at pipeline-proximate coastal sites to preempt MEE enforcement exposure on legacy carbide assets. Defend electronic-grade positioning through captive production unit expansion at semiconductor fab perimeters, neutralizing purity degradation risks from cylinder logistics. Prioritize REACH-compliant feedstock documentation to maintain EU vinyl acetate monomer supplier qualification. For New Entrants and Emerging Players: Capture welding and cutting cylinder replacement cycles in South and Southeast Asian shipbreaking yards where construction activity outpaces automated alternatives. Target distributor partnerships in Bangladesh, India, and Vietnam rather than competing against integrated chemical complexes in East China. Lead with safety equipment bundling and localized route optimization that multinational gas majors cannot economically replicate. For Investors and Strategic Acquirers: Consolidation pressure builds where carbide-based capacity faces stranded asset risk from tightening emissions benchmarks and carbon border adjustments. Long-term viability favors producers with dual feedstock flexibility and semiconductor fab on-site generation contract backlogs. Watch MEE enforcement intensity and EU carbon border adjustment implementation as inflection indicators for asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Gas Cracking | MEE dual carbon compliance secures feedstock flexibility for coastal petrochemical complexes. |
| On-Site Generation Contract Expansion | Captive production at semiconductor fabs eliminates transport purity risks and locks decade-long revenue. |
| REACH-Compliant Feedstock Documentation | ECHA traceability mandates restructure EU vinyl acetate monomer procurement qualification criteria. |
| Distributor Network Consolidation | Regional cylinder logistics specialists aggregate fragmented construction and fabrication demand. |
| Electronic-Grade Certification Investment | Sub-ppm purity protocols extend supplier qualification timelines that freeze out unproven entrants. |
Methodological Framework
Multiple input streams—executive interviews with industrial gas procurement leads, plant manager surveys at vinyl acetate monomer facilities, and distributor operational data—were reconciled against customs trade records, SEC filings from integrated chemical operators, and MEE emissions disclosure databases. Primary engagement spanned acetylene derivative producers, semiconductor fab supply chain managers, and regional cylinder logistics specialists. Secondary validation drew from petrochemical industry association reports, EPA air emissions compliance filings, and REACH substance registration documentation. Bottom-up capacity modeling and top-down demand estimation were triangulated to cross-verify volume assumptions.
Data-stream reconciliation across grade tier, end-use application, and regional production hub dimensions shaped the analytical framework over the projection horizon. Segmentation modeling captured electronic-grade, industrial-grade, and laboratory-grade purity specifications alongside chemical synthesis, welding, and electronics end-use splits. CAGRs were derived from demand elasticity analysis against vinyl acetate monomer capacity expansion and semiconductor fabrication buildout trajectories. Forecast inputs incorporated MEE enforcement intensity scenarios and EU carbon border adjustment implementation timelines.
Underlying measurement precision varies by segment; electronic-grade acetylene carries tighter precision due to captive production contract visibility, while merchant cylinder supply exhibits higher uncertainty from spot procurement volatility. Forecasts reflect assumptions around MEE dual carbon target achievement rates and natural gas infrastructure buildout pacing. A model refresh is warranted upon material change in semiconductor fab capacity expansion schedules or carbide furnace retirement acceleration under tightened emissions enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
India Acetic Acid Market
Industrial Chemicals
Hydro Fluorocarbon Market
Industrial Chemicals
Explosive Chargers Market
Industrial Chemicals
Asia Neopentyl Glycol (NPG) Market
Industrial Chemicals
Global N-Methyl-2-Pyrrolidone (NMP) Market
Industrial Chemicals
Calciner Market
Industrial Chemicals
Technical Enzymes Market
Industrial Chemicals
Nano-Bubble Generator Market
Industrial Chemicals
Northern Europe Calcium Sulphate Market
Industrial Chemicals
Ferrocene Market
Industrial Chemicals
Wood Preservative Market
Industrial Chemicals
Perchloroethylene Market
Industrial Chemicals
Paraffin Inhibitors Market
Industrial Chemicals
Shea Olein Market
Industrial Chemicals
E-Fluids Market
Industrial Chemicals
Global Chemical Mechanical Planarization Market