
 North America Biocides Market | 2026-2036
North America Biocides Market Size, Share, and Industry Trends Forecast 2026-2036
North America Biocides Market Insights
The United States is reconfiguring its biocide production footprint through capacity additions along the Texas-Louisiana chemical corridor. Ecolab leverages its integrated water treatment and hygiene platform to dominate institutional and industrial accounts across the region. BASF SE anchors its position through backward integration into key active ingredient precursors. LANXESS competes on halogenated chemistry specialization, particularly for oilfield and marine applications.
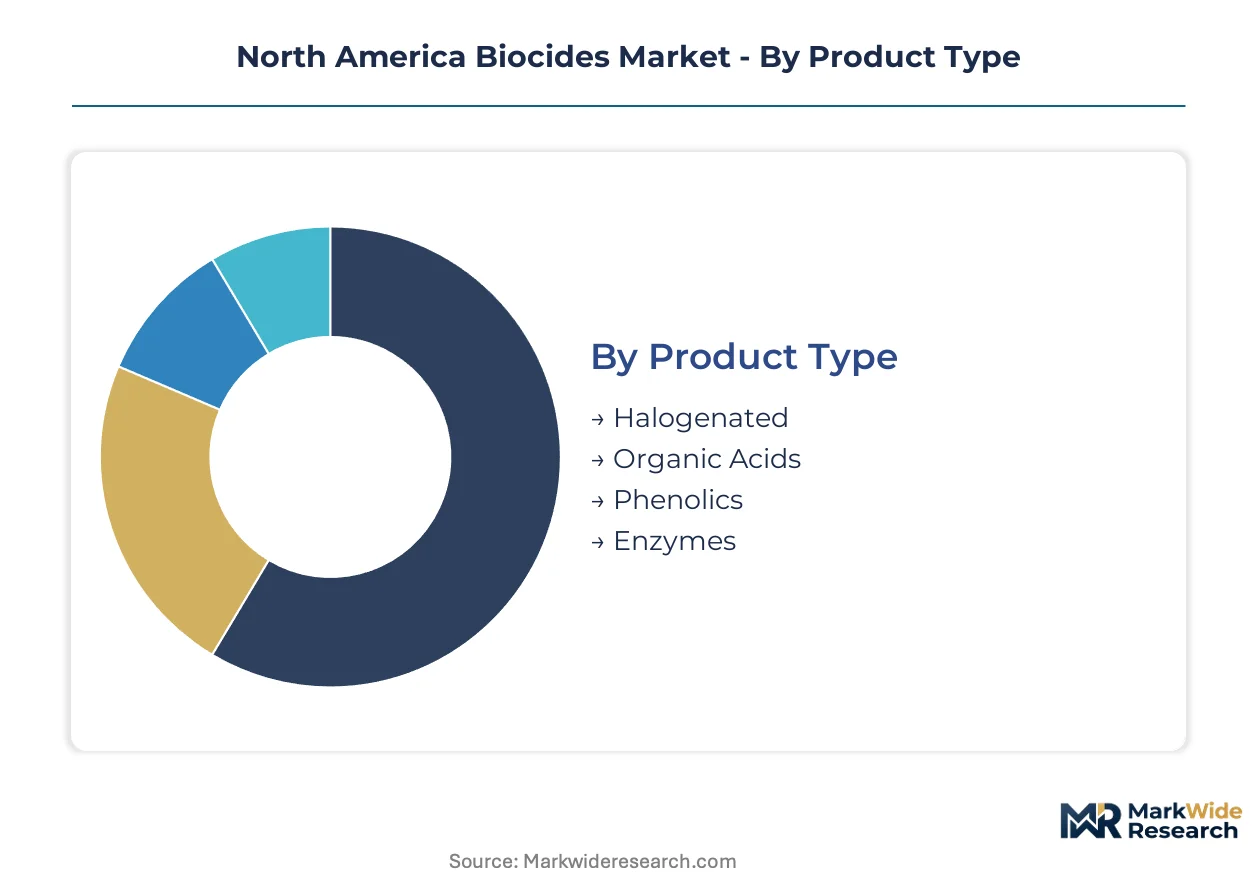
Biocides encompass chemical substances or microorganisms intended to destroy, deter, or exert controlling effects on harmful organisms, with active concentrations typically ranging from parts-per-million to low-percentage formulations depending on target pathogen and exposure protocol. These compounds serve essential functions in preserving material integrity, preventing biofouling, and ensuring sanitary conditions across industrial and consumer systems. Halogenated biocides, particularly chlorine and bromine derivatives, occupy the largest share of the North American product mix due to cost-effectiveness and broad-spectrum efficacy in water treatment. The food and beverage application segment registers the fastest structural expansion as processors face intensifying sanitation mandates and clean-label preservation requirements. Phenolic biocides retain stable demand in healthcare surface disinfection, though growth moderates amid substitution pressures from quaternary ammonium and peroxide alternatives.
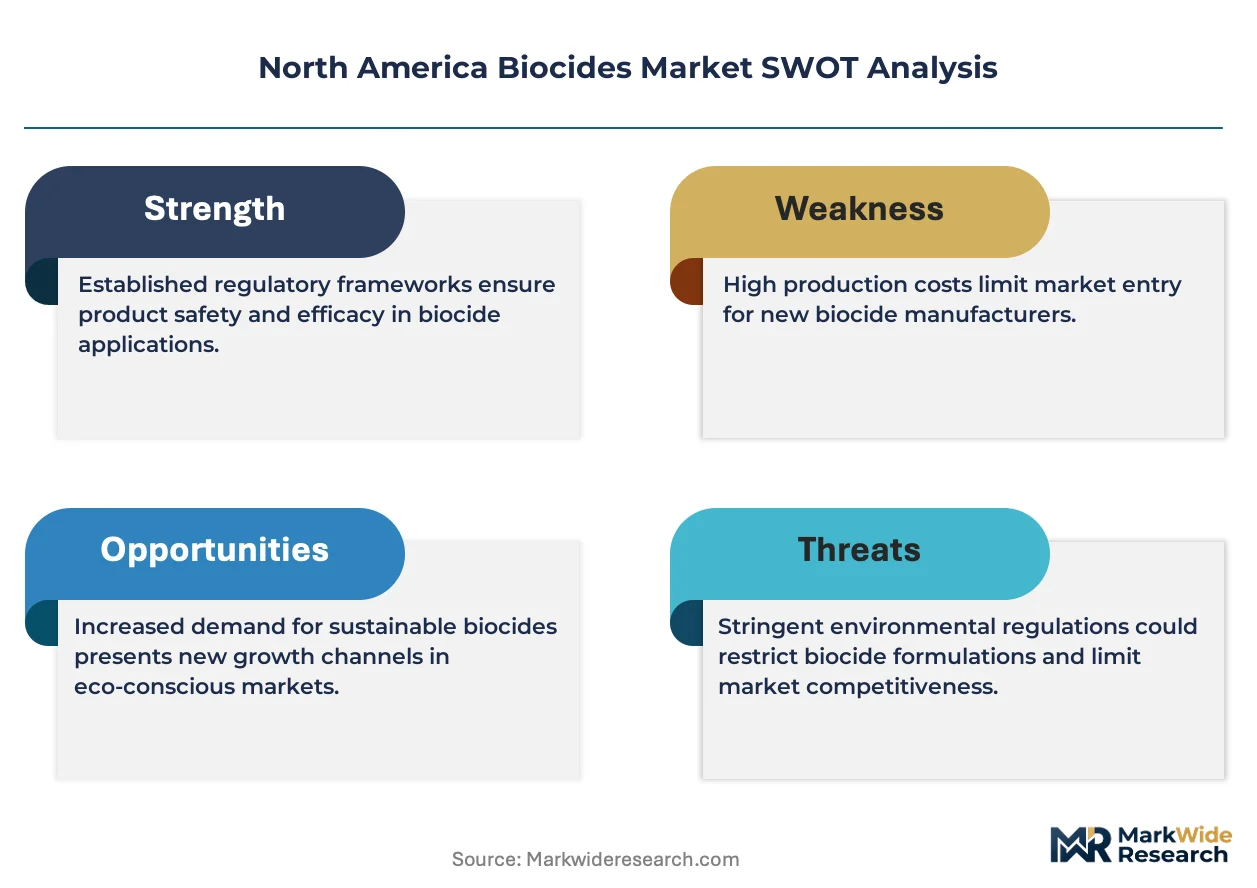
The EPA's FIFRA registration framework and the OSHA Hazard Communication Standard jointly determine product compliance burdens and end-use accessibility across the United States. Health Canada and PMRA administer parallel regulatory gatekeeping for Canadian market entry, with divergent timelines creating asynchronous product availability between jurisdictions. State-level discharge limitations under the Clean Water Act, particularly in California and the Great Lakes basin, increasingly restrict certain biocide chemistries in aquatic applications. Stakeholders must monitor evolving EPA re-registration outcomes and state-level precursor restrictions to anticipate portfolio obsolescence risks and redirect formulation investments toward compliant alternatives.
Market Dynamics
The EPA's ongoing FIFRA re-evaluation of antimicrobial active ingredients is compressing product lifecycles and forcing reformulation investments across the North American biocides sector. This regulatory pressure is reshaping competitive positioning as manufacturers redirect R&D toward compliant chemistries ahead of registration deadlines.
Growth Catalysts
- Membrane disinfection protocols:Water treatment utilities across the United States are expanding biocide procurement for reverse osmosis and ultrafiltration system maintenance. Municipal and industrial facilities now require continuous microbial control to prevent biofouling and extend membrane service life.
- OSHA Hazard Communication Standard alignment:Workplace safety mandates are tightening documentation and labeling requirements for industrial biocide handlers. This is driving formalized training programs and certified application services across manufacturing and petrochemical facilities.
- Texas-Louisiana chemical corridor concentration:Refinery and chemical processing operations along the U.S. Gulf Coast generate concentrated demand for cooling tower biocides and oilfield microbial control. Continuous production cycles require 24/7 biocide dosing systems.
Market Restraints
- Halogen precursor supply volatility:Chlorine and bromine derivative production depends on concentrated brine extraction and electrolytic processing. Supply disruptions at key Gulf Coast chlor-alkali facilities create input cost spikes and formulation shortages.
- Clean Water Act discharge limitations:State-level implementations in California and the Great Lakes basin restrict residual halogenated biocide concentrations in aquatic effluents. This is narrowing the addressable market for certain chemistries in sensitive watersheds.
- Quaternary ammonium substitution pressure:Phenolic biocides face displacement in healthcare surface disinfection as hospitals adopt peroxide and QAC alternatives with faster contact times and lower residue profiles.
Strategic Opportunities
- Canadian regulatory arbitrage:Health Canada and PMRA operate asynchronous review timelines versus EPA processes, creating temporary product availability gaps. Early registrants can capture market share before U.S. competitors receive parallel approvals.
- Clean-label food preservation:Food and beverage processors face intensifying sanitation mandates and consumer preference shifts toward minimal-synthetic ingredient panels. This opens demand for fermentation-derived and enzyme-based antimicrobial systems.
- Electrochemical generation systems:On-site chlorine dioxide and mixed-oxidant production equipment is virtualizing traditional bulk chemical delivery models. This technology convergence reduces transportation costs and storage liabilities for large water treatment operators.
Industry Challenges
- Toxicology data generation timelines:EPA FIFRA re-registration requires extensive environmental fate and human health endpoint studies. Contract research organization capacity constraints are extending submission preparation cycles and compressing effective patent windows.
- Legacy cooling tower infrastructure compatibility:Older industrial facilities operate fixed-dose biocide feed systems incompatible with modern oxidant-stable corrosion inhibitors. Retrofit capex requirements slow adoption of advanced formulation packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Biocides Market |
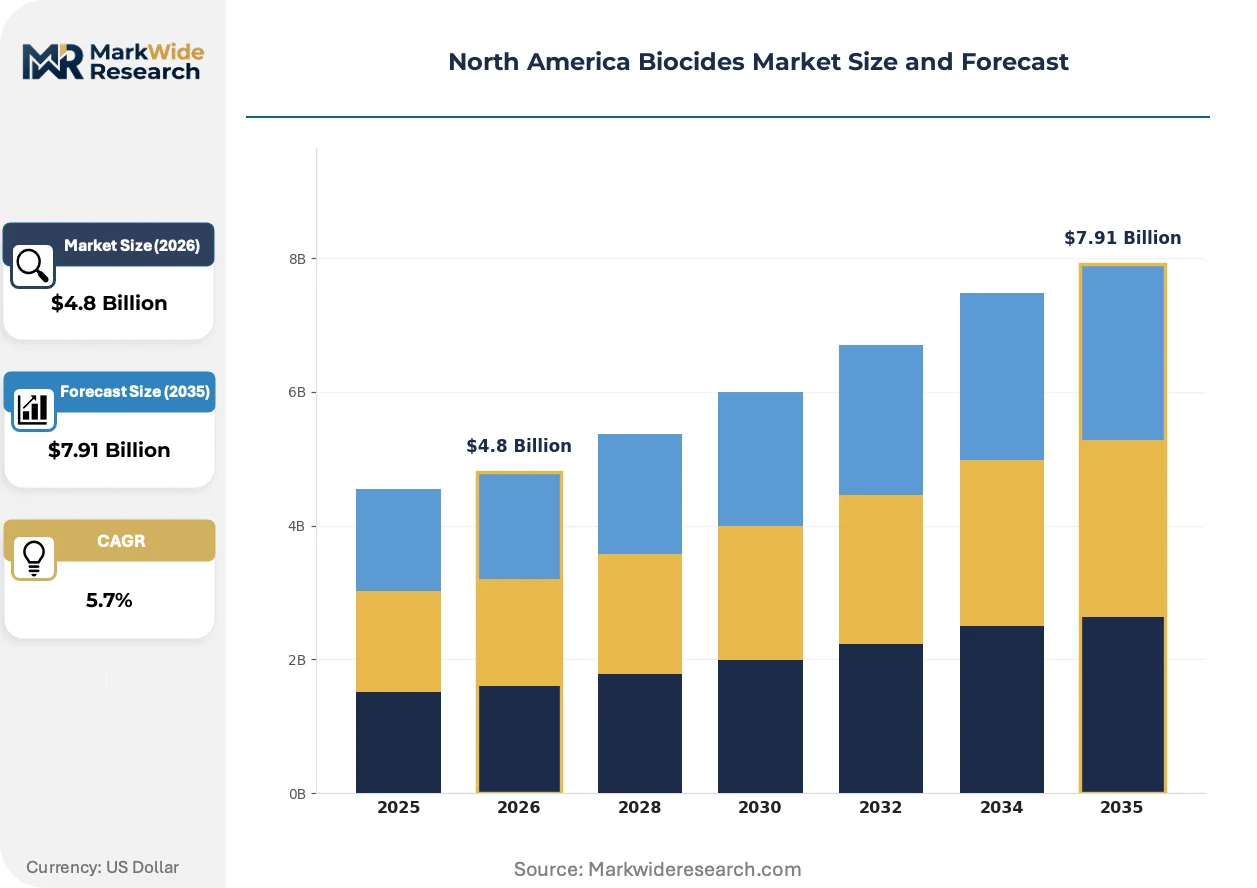
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Halogenated, Organic Acids, Phenolics, Enzymes Application: Agriculture, Water Treatment, Food & Beverage, Healthcare End User: Manufacturers, Distributors, Retailers, Service Providers Formulation: Liquid, Powder, Granules, Emulsions |
| Companies Covered | Ecolab, BASF SE, The Lubrizol Corporation, LANXESS, Solvay, Lonza Group, The Dow Chemical Company, Arxada AG, Clariant, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Biocides Market Trends and Innovations
Digital monitoring and electrochemical generation technologies are displacing conventional bulk chemical delivery models across industrial water treatment. These shifts are compressing supply chain structures and redefining service relationships between biocide suppliers and end-use operators.
Peracetic acid formulations are gaining traction as cold-chain sanitizers in food processing and beverage bottling operations. PAA decomposes to acetic acid and water, leaving minimal residue and eliminating quarantine periods required for chlorine-based systems. Major protein processors and dairy cooperatives are adopting PAA for equipment and environmental sanitation, particularly in facilities serving export markets with stringent maximum residue limits.
EPA's accelerated antimicrobial resistance monitoring under FIFRA is tightening efficacy demonstration requirements for surface disinfectant registrations. The agency now requires quantitative carrier test data against specific pathogen panels, elevating R&D costs and extending development timelines. Healthcare and institutional cleaning product manufacturers are responding by consolidating formulation platforms around multi-claim chemistries that satisfy both EPA List N emergency pathogen requirements and routine sanitation standards.
Integrated service contracts are displacing transactional chemical procurement in large industrial accounts. Water treatment specialists now bundle biocide supply with remote monitoring, automated dosing control, and regulatory compliance reporting. This model shift is most visible across the U.S. Gulf Coast petrochemical corridor, where refinery operators prioritize guaranteed microbial control uptime over unit chemical pricing.
North America Biocides Market Segmentation
Biocide purchasing decisions in North America diverge sharply across end-use contexts, from continuous industrial dosing systems to intermittent agricultural applications. Understanding these segment boundaries clarifies where formulation investments yield returns and where regulatory compliance costs concentrate.
Product Type:
Halogenated derivatives dominate volume across cooling tower and municipal water applications, while enzymatic alternatives capture emerging clean-label demand.
- Halogenated:Chlorine and bromine derivatives deliver broad-spectrum efficacy at parts-per-million concentrations. Refinery operations along the Texas-Louisiana corridor consume continuous volumes for cooling water microbial control, though EPA discharge limitations in California and Great Lakes states constrain addressable markets.
- Organic Acids:Peracetic acid and lactic acid formulations decompose to benign residuals, eliminating quarantine periods. Major protein processors and dairy cooperatives adopt these chemistries for equipment sanitation, particularly in facilities serving export markets with stringent maximum residue limits.
- Phenolics:Retain stable demand in healthcare surface disinfection despite substitution pressures.
- Enzymes:Fermentation-derived antimicrobial systems gain traction amid consumer preference shifts toward minimal-synthetic ingredient panels.
Established volume favors halogenated chemistries; emerging adoption favors enzyme-based alternatives.
Application:
Regulatory intensity varies dramatically across use cases, with food contact and healthcare applications facing the most stringent EPA and FDA compliance burdens.
- Water Treatment:Municipal and industrial facilities require continuous microbial control for reverse osmosis and ultrafiltration membrane maintenance. Utilities across the United States expand procurement as biofouling prevention extends membrane service life and reduces replacement capital.
- Food & Beverage:Processors face intensifying sanitation mandates from FDA and converging consumer clean-label expectations. Cold-chain sanitizers and environmental surface treatments command premium positioning due to residue limitations and export compliance requirements.
- Healthcare:Surface disinfectant registrations now require quantitative carrier test data against specific pathogen panels under EPA's accelerated antimicrobial resistance monitoring.
- Agriculture:Crop protection and post-harvest preservation applications face divergent state-level precursor restrictions.
Water treatment commands the largest installed base; food and beverage applications are climbing the fastest amid regulatory and consumer pressure convergence.
End User:
Channel structure determines service intensity, with large industrial accounts demanding integrated supply contracts and compliance reporting.
- Manufacturers:Petrochemical and food processing operators prioritize guaranteed microbial control uptime over unit chemical pricing. Gulf Coast refinery operators bundle biocide supply with remote monitoring and automated dosing control through multi-year service agreements.
- Service Providers:Water treatment specialists capture margin through outcome-based contracts that virtualize traditional bulk chemical delivery with on-site electrochemical generation equipment.
- Distributors:Intermediate channel for smaller industrial accounts and agricultural applicators.
- Retailers:Consumer and small commercial surface disinfectant sales through institutional supply chains.
Manufacturers concentrate procurement volume; service providers are gaining share fastest through technology-enabled delivery models.
Formulation:
Physical form factors align with dosing infrastructure compatibility and storage liability profiles across end-use environments.
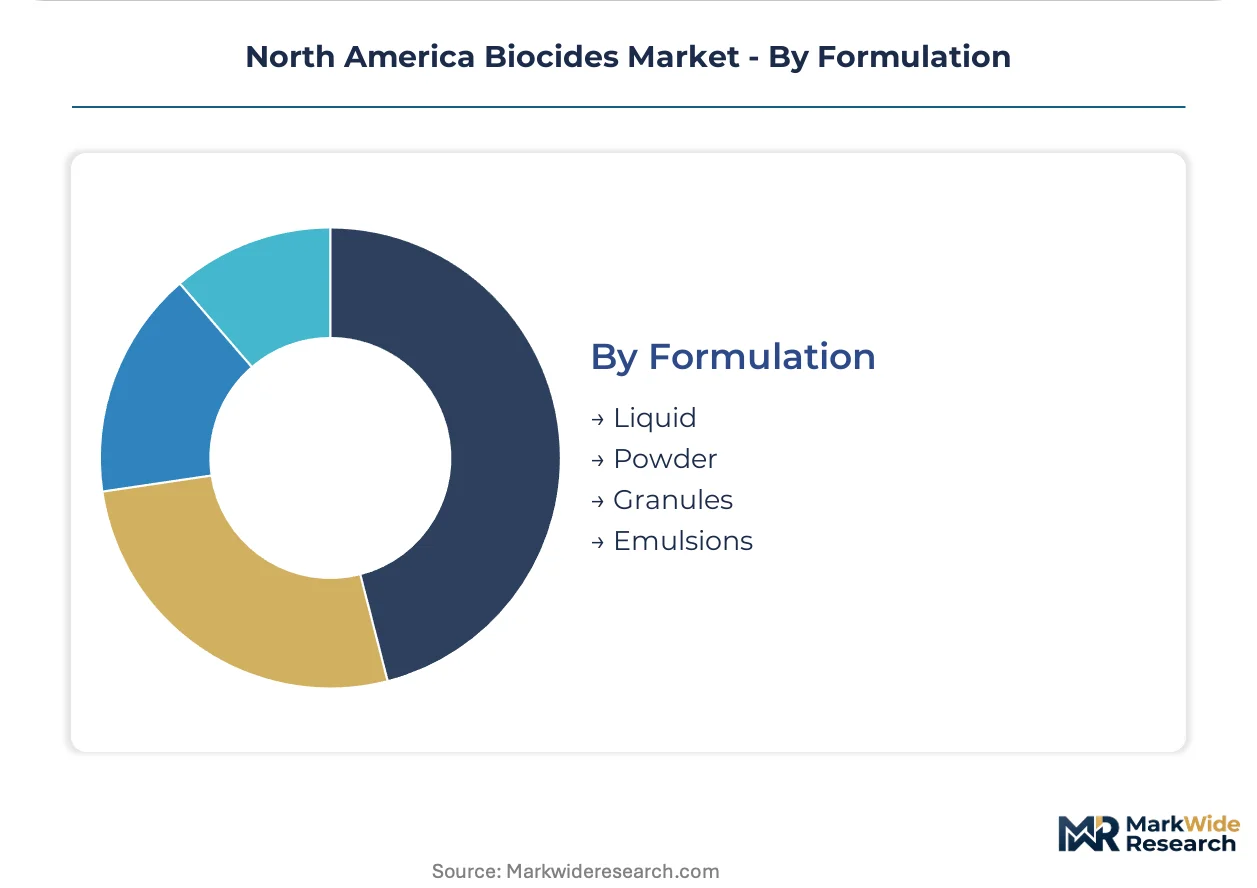
- Liquid:Dominates industrial continuous-dose systems with established feed pump infrastructure. Chlorine dioxide and mixed-oxidant precursors ship in bulk tanker configurations to large water treatment operators.
- Powder:Concentrated active ingredients reduce transportation costs for remote agricultural and oilfield applications.
- Granules:Controlled-release formulations for extended-duration water treatment.
- Emulsions:Stabilized dispersions for specialized surface treatment applications.
Liquid formulations retain the broadest infrastructure compatibility; powder formats are expanding most quickly in cost-sensitive remote applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Colonial Pipeline and its Gulf Coast feeder systems anchor biocide logistics across the southeastern United States. Cross-border chemical rail corridors link Canadian production nodes to Great Lakes industrial demand centers. Mexican petrochemical infrastructure expansion is reshaping regional supply geometry.
United States
Water treatment utilities from California to Florida are expanding membrane disinfection procurement for reverse osmosis maintenance. EPA FIFRA re-registration timelines are compressing effective patent windows for legacy active ingredients. The Texas-Louisiana chemical corridor concentrates cooling tower biocide demand from refinery and chemical processing operations running continuous production cycles.
Canada
Oil sands extraction operations in Alberta require specialized microbial control for produced water and bitumen processing circuits. Health Canada and PMRA operate review timelines asynchronous to EPA processes, creating temporary product availability windows. Ontario's manufacturing belt around Toronto and Hamilton generates steady institutional sanitation demand from food processing and healthcare facilities.
Mexico
Pemex refinery modernization and private petrochemical investments are expanding cooling water treatment requirements along the Gulf Coast. Mexican environmental regulators are tightening discharge standards for industrial effluents in watersheds feeding the Rio Grande. The Altamira-Tampico chemical cluster is attracting biocide formulation investments to serve regional manufacturing growth.
California
State-level Clean Water Act implementation restricts residual halogenated biocide concentrations in aquatic discharges to sensitive coastal watersheds. The Central Valley agricultural belt generates seasonal demand for post-harvest preservation and irrigation system sanitation. Bay Area biotechnology and food processing facilities drive premium demand for clean-label antimicrobial systems with minimal synthetic residues.
Great Lakes Basin
State discharge limitations in Michigan, Ohio, and Wisconsin constrain certain biocide chemistries in municipal and industrial water treatment. Heavy manufacturing corridors around Detroit, Cleveland, and Milwaukee maintain cooling tower infrastructure requiring continuous microbial control. Regional utilities are retrofitting older facilities with electrochemical generation systems to reduce bulk chemical storage liabilities.
North America Biocides Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying active ingredients and formulation packages. The North American biocides sector exhibits tiered concentration, with a handful of integrated water treatment platforms serving large industrial accounts while numerous regional formulators compete for mid-market share. Three archetypes dominate: integrated hygiene platforms bundling biocide supply with monitoring services, backward-integrated chemical majors controlling precursor production, and specialized halogenated chemistry houses serving oilfield and marine niches. Competitive moves center on electrochemical generation technology licensing and multi-year outcome-based service contracting.
Among integrated hygiene platforms, Ecolab anchors the system tier through its combined water treatment and institutional sanitation footprint. BASF SE exemplifies the backward-integrated archetype with captive supply positions in key active ingredient precursors. LANXESS occupies the specialized chemistry tier, with halogenated expertise particularly visible in oilfield and marine applications. These three patterns—platform integration, precursor control, and niche specialization—structure competitive positioning across the region.
| Leading Market Players |
|---|
| Ecolab |
| BASF SE |
| The Lubrizol Corporation |
| LANXESS |
| Solvay |
| Lonza Group |
| The Dow Chemical Company |
| Arxada AG |
| Clariant |
| Others |
Pricing and Supply Chain Analysis
EPA FIFRA re-registration timelines determine both pricing tier spreads and supply chain shape across the North American biocides sector. Compressed product lifecycles force manufacturers to recover reformulation costs through premium positioning while redirecting procurement toward compliant precursor sources.
Pricing Analysis
Volume-discount tiering structures dominate procurement relationships between Gulf Coast petrochemical operators and biocide suppliers. Three-tier pricing separates certified food-grade formulations from standard industrial grades and economy bulk halogenated derivatives, with differentiation anchored in EPA registration status and after-sales compliance reporting. Pricing pressure stems from electrochemical generation equipment reducing bulk chemical offtake volumes. Municipal utilities exhibit the highest price sensitivity due to fixed budget appropriations, while integrated refinery operators prioritize guaranteed uptime over unit costs.
Supply Chain Analysis
Tariff exposure between the United States and China concentrates risk for bromine derivative precursors and specialized organic acid intermediates. Active ingredient production draws from domestic chlor-alkali facilities along the Texas-Louisiana corridor, Canadian oil sands chemical complexes, and Mexican petrochemical expansions around Altamira-Tampico. Single-source vulnerability persists for electrolytic chlorine cell components and specialized catalyst systems. Distribution runs through chemical tanker networks feeding Colonial Pipeline terminals and cross-border rail corridors serving Great Lakes manufacturing belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against enzyme-based and electrochemical alternatives that threaten halogenated chemistry volumes. Peracetic acid systems and on-site oxidant generation equipment are capturing share in food processing and municipal water treatment applications.
For Market Incumbents: Insulate core halogenated positions through backward integration into Gulf Coast brine extraction and electrolytic processing assets. Accelerate EPA List N multi-claim registrations to consolidate surface disinfectant platforms before quaternary ammonium and peroxide alternatives complete efficacy demonstrations. Prioritize multi-year service contracts bundling biocide supply with remote monitoring to lock in refinery and chemical processing accounts. For New Entrants and Emerging Players: Build out clean-label fermentation-derived antimicrobial capacity to serve Bay Area biotechnology and Central Valley food processing facilities facing consumer pressure for minimal-synthetic ingredient panels. Target Canadian oil sands microbial control applications where Health Canada asynchronous review timelines create temporary product availability windows. Pursue electrochemical generation equipment licensing as a service-based entry point that virtualizes traditional bulk chemical distribution. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated hygiene platforms with captive water treatment monitoring capabilities. Long-term viability over the next decade hinges on regulatory compliance infrastructure rather than standalone formulation expertise. Acquisition candidates should demonstrate EPA FIFRA registration management systems and established service relationships with Gulf Coast petrochemical operators. Watch for EPA re-registration outcome announcements as the critical inflection signal indicating which active ingredient portfolios face obsolescence versus extension.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | Captive brine extraction and electrolytic processing insulates margins from Gulf Coast chlor-alkali supply disruptions. |
| Electrochemical Generation Technology Licensing | On-site chlorine dioxide production virtualizes bulk chemical delivery and reduces transportation liability exposure. |
| Multi-Claim EPA Registration Consolidation | Single platforms satisfying both List N emergency pathogen requirements and routine sanitation standards compress R&D overhead. |
| Canadian Regulatory Arbitrage Positioning | Early PMRA approvals capture market share before U.S. competitors complete parallel Health Canada submissions. |
| Integrated Service Contract Expansion | Outcome-based agreements bundling biocide supply with remote monitoring lock in refinery operator loyalty. |
Research Methodology
The analysis maps halogenated derivatives, organic acids, phenolics, and enzymatic biocide categories, each validated through technical directors at water treatment utilities, procurement leads at Gulf Coast refineries, regulatory affairs managers at formulation houses, and distribution channel partners. Primary interview findings were cross-referenced against EPA FIFRA registration databases, Health Canada PMRA submission records, SEC 10-K filings from integrated chemical majors, and American Chemistry Council production surveys. Bottom-up volume estimates from end-use facility consumption patterns were reconciled with top-down industry association shipment data.
Assumptions held EPA re-registration timelines and state-level Clean Water Act discharge limitations fixed at current trajectories across the modeling period, while electrochemical generation adoption rates and clean-label substitution elasticities were varied under sensitivity scenarios. Segmentation dimensions modeled include product chemistry class, application context, end-user channel structure, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to historical procurement patterns and adjusted for documented capacity additions. Forecast inputs incorporated membrane disinfection protocol expansion rates and food processor sanitation mandate intensification.
The forecast holds incumbent behavior within observed patterns; aggressive moves by electrochemical equipment manufacturers or enzyme-based formulation startups would shift outcomes beyond projected ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Fluidizers in Plasterboard Market
Industrial Chemicals
High Viscosity Mixer Market
Industrial Chemicals
Global Foundry Chemicals Market
Industrial Chemicals
Mining Explosives Consumables Market
Industrial Chemicals
Mass Transfer Trays Market
Industrial Chemicals
Plant-Based Hydraulic Oil Market
Industrial Chemicals
2-Ethoxy Propene Market
Industrial Chemicals
Industrial Grade Urea Market
Industrial Chemicals
Global N-Methyl-2-Pyrrolidone (NMP) Market
Industrial Chemicals
Gypsum Market
Industrial Chemicals
India Acetic Acid Market
Industrial Chemicals
1-Octanol Market
Industrial Chemicals
Nitrous Oxide Market
Industrial Chemicals
North America Molecular Sieve Market
Industrial Chemicals
Reconditioned Drums Market
Industrial Chemicals
LAMEA Deoxidizer Market