
 Europe Biocides Market | 2026-2036
Europe Biocides Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Biocides Market Analysis
Water treatment and healthcare disinfection is rebalancing demand toward halogen-based and peroxygen biocide systems. BASF SE leverages its integrated chlorine dioxide precursor supply chain to serve municipal water utilities across the Rhine basin. LANXESS anchors industrial cooling tower applications with its bromine derivative portfolio manufactured at Leverkusen. Evonik Industries AG specializes in advanced peracetic acid formulations for food processing hygiene, competing on efficacy against emerging pathogen strains.
Biocides comprise chemical substances or microorganisms intended to destroy, deter, or control harmful organisms, typically formulated with active concentrations ranging from ppm to percent levels depending on target organism and exposure time. Their primary commercial purpose spans preservation of manufactured goods, disinfection of surfaces and water, and protection of structural materials against biological degradation. Preservatives in personal care and coatings command mature margin pools with stable offtake, while disinfectants for institutional and healthcare settings capture faster growth trajectories driven by post-pandemic hygiene protocols. Liquid formulations dominate volume shipments due to ease of dosing and compatibility with existing application equipment, though powder formats gain traction in agricultural seed treatment where transport economics favor reduced water content.
EMA and ECHA jointly govern biocide authorization through the BPR framework, with ECHA's Biocidal Products Committee evaluating active substance approvals and EMA contributing on human health exposure assessments. REACH compliance and the EU Green Deal chemical sustainability criteria are progressively restricting legacy organotin and formaldehyde-releasing actives, redirecting R&D investment toward bio-based and enzyme-derived alternatives. Stakeholders must monitor the pending revision of BPR annexes and the Commission's criteria for essential use exemptions to anticipate which chemistries retain market access versus forced phase-out timelines.
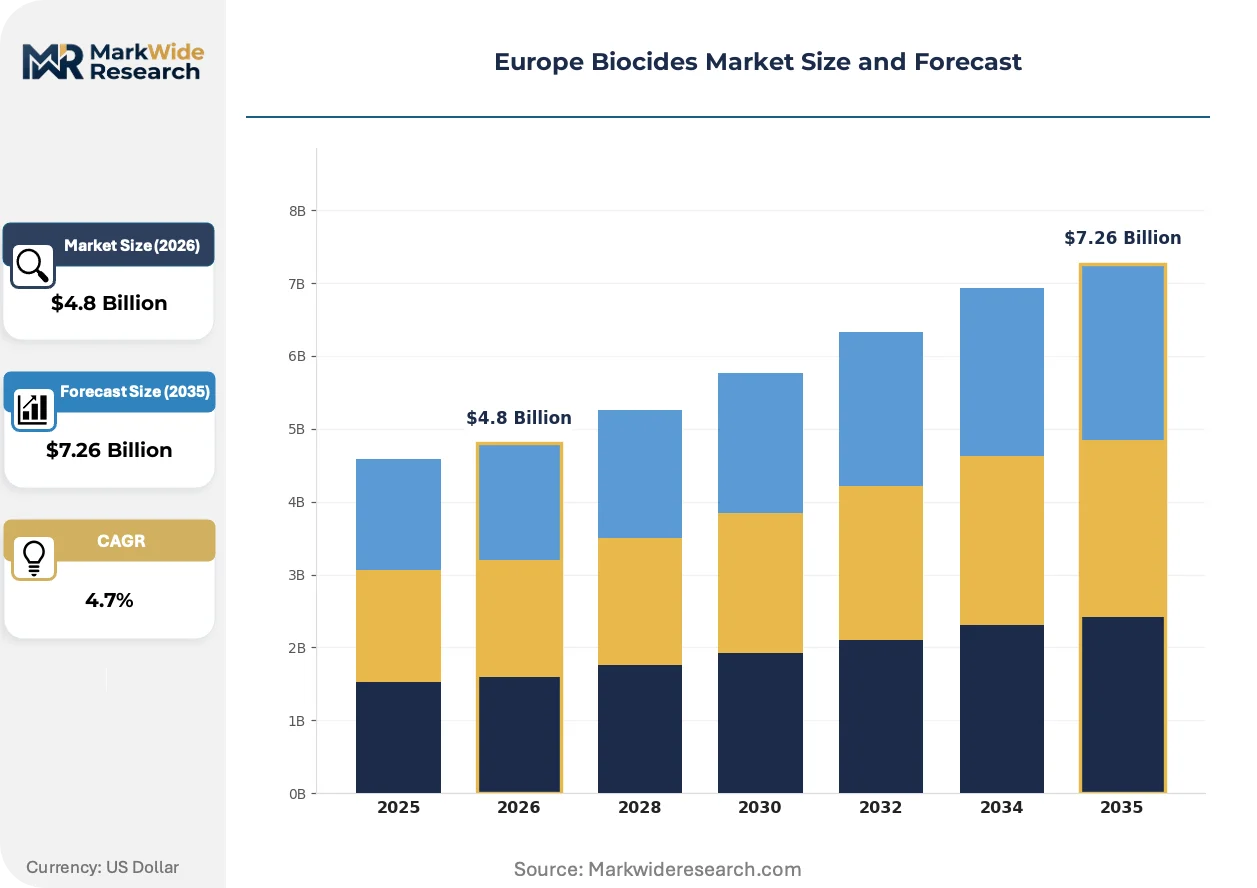
Market Dynamics
EU BPR authorization timelines are compressing competitive lead times while REACH substance restrictions force active ingredient substitution across legacy preservative portfolios.
Growth Catalysts
- Water treatment infrastructure:Municipal utilities across the Rhine basin are upgrading chlorine dioxide generation capacity to meet stricter drinking water pathogen limits.
- REACH Article 57 restrictions:Formaldehyde-releaser phase-outs are redirecting coating and adhesive formulators toward isothiazolinone and organic acid alternatives.
- Healthcare hygiene protocols:Post-pandemic institutional disinfection standards in France and Germany sustain elevated peracetic acid and quaternary ammonium compound offtake.
Market Restraints
- Bromine supply concentration:Dead Sea and Arkansas brine operations control 80% of elemental bromine feedstock, exposing European derivative manufacturers to freight and energy cost volatility.
- ECHA active substance evaluation delays:Biocidal Products Committee backlog extends authorization timelines for novel actives, freezing commercialization of enzyme-based and bio-derived candidates.
- Chlorine dioxide generation capex:On-site precursor systems require utility-scale capital commitment that fragments municipal procurement into multi-year tender cycles.
Strategic Opportunities
- Poland and Czech Republic industrial zones:Automotive and electronics manufacturing clusters lack mature cooling water treatment service infrastructure, creating first-mover positioning for bromine-based biocide formulators.
- EU Green Deal chemical sustainability criteria:Bio-based active substance certification pathways reward R&D investment in agricultural and food processing applications.
- Peroxygen-quaternary ammonium hybrid systems:Synergistic formulations targeting Candida auris and other emerging healthcare pathogens command premium positioning against single-active alternatives.
Industry Challenges
- Toxicology and ecotoxicology specialist scarcity:BPR-compliant dossier preparation requires rare expertise in exposure modeling and risk characterization, constraining SME participation.
- Legacy cooling tower infrastructure:Industrial facilities in the Ruhr and northern England operate mixed-metal systems incompatible with oxidizing biocide chemistries, complicating product substitution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Biocides Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disinfectants, Preservatives, Pesticides, Wood Treatments Application: Household, Industrial, Agricultural, Institutional Form: Liquid, Powder, Granular, Emulsifiable Concentrate End User: Manufacturers, Service Providers, Government Agencies, Research Institutions |
| Companies Covered | BASF SE, LANXESS, Clariant, Dow Chemical Company, Evonik Industries AG, Lonza Group Ltd, Henkel AG & Co KGaA, Ecolab, Nouryon, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Biocides Market Emerging Trajectories
Formulation science and regulatory chemistry are intersecting to reshape product development pipelines, with sustainability metrics now embedded in technical specification criteria.
Electrochemical on-site generation is converging with precursor logistics networks to eliminate chlorine dioxide transport hazards. Dutch and Belgian water utilities are piloting membrane-cell systems that convert sodium chlorite at point-of-use. This distributed production model is compressing regional supply chain vulnerability while shifting value capture toward equipment-service bundling.
ECHA's 2024-2025 substance evaluation work program targets organotin compounds and certain isothiazolinones for restriction proposal development. Industrial coating and marine antifouling formulators face forced reformulation toward copper-free and organic biocide alternatives. The Netherlands and Germany host the most advanced substitution research consortia, leveraging national chemical agency funding to accelerate candidate screening.
Hospital procurement groups in France and Italy are consolidating disinfectant purchasing through framework agreements that specify minimum biocidal efficacy spectrum against EN 14885 test organisms. This buyer concentration is displacing fragmented spot purchasing and favoring suppliers with comprehensive portfolio breadth and dossier documentation capabilities. Southern European healthcare systems exhibit the fastest contract consolidation velocity.
Europe Biocides Market Segmentation
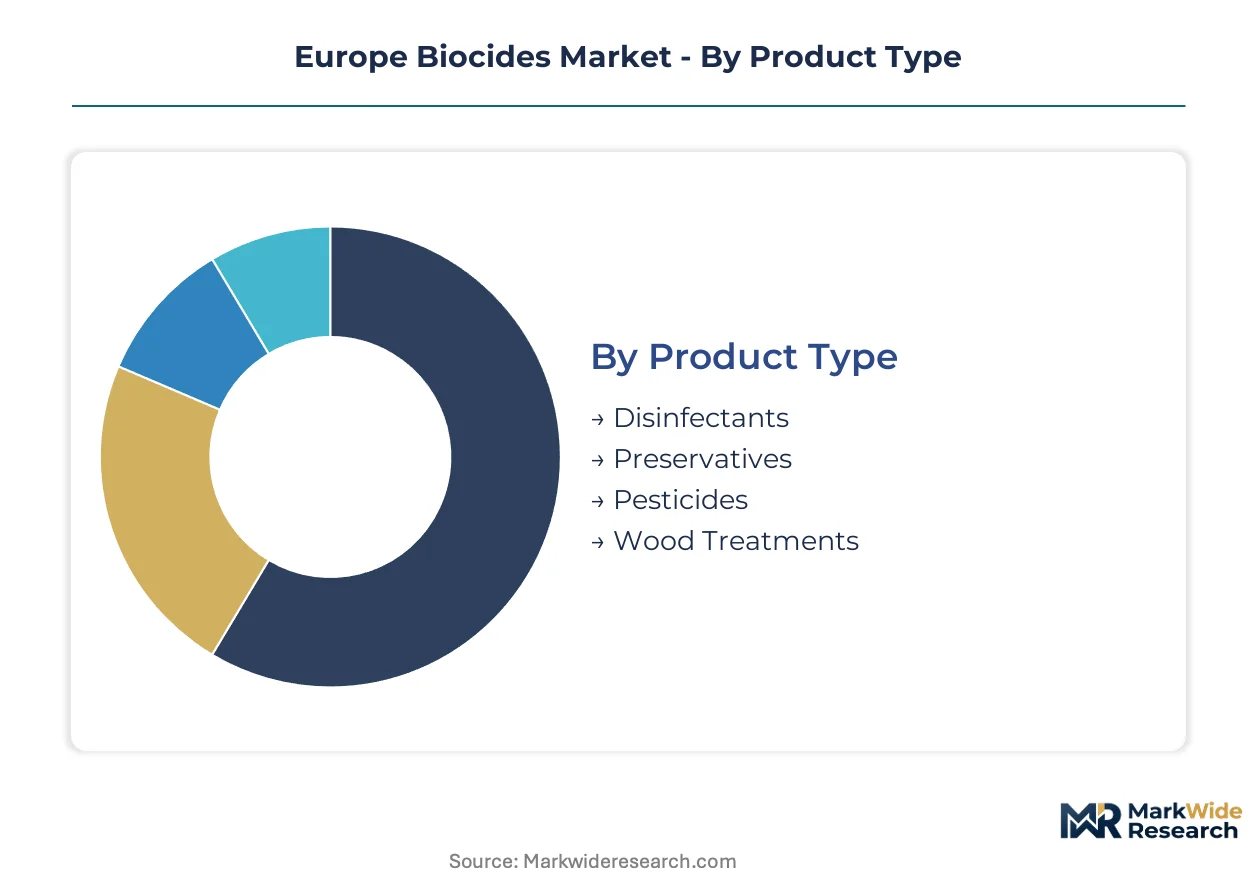
Biocide segmentation in Europe tracks divergent compliance burdens and application economics across product categories. Formulation choices directly determine REACH authorization pathways and end-user switching costs.
Product Type:
Upgrade cycles in water treatment and coating preservation are forcing active ingredient substitutions that reshape segment economics.
- Disinfectants:These formulations employ oxidizing agents including chlorine dioxide, peracetic acid, and quaternary ammonium compounds at concentrations calibrated for log-reduction targets against EN 14885 test organisms. Demand concentrates in French and German hospital procurement frameworks where post-pandemic hygiene protocols mandate broad-spectrum efficacy documentation. ECHA evaluation delays on novel actives freeze enzyme-based alternatives, preserving market share for halogen and peroxygen systems.
- Preservatives:Isothiazolinone, organic acid, and formaldehyde-releasing chemistries protect manufactured goods from microbial degradation during storage and use. Coating and adhesive formulators in the Netherlands and Belgium face forced reformulation as REACH Article 57 restrictions phase out legacy organotin compounds. Substitution research consortia leverage national chemical agency funding to accelerate candidate screening.
- Pesticides:Agricultural biocides control crop and non-crop pests through seed treatment and foliar applications. Powder formulations dominate transport economics for Eastern European grain belt distribution.
- Wood Treatments:These products protect structural timber and outdoor lumber from fungal decay and insect infestation. Creosote replacement pressures in Nordic markets redirect demand toward copper-organic alternatives.
Volume placements concentrate in Preservatives; the faster expansion belongs to Disinfectants.
Application:
Customer procurement maturity separates price-sensitive spot purchasing from long-term framework agreements with embedded compliance documentation.
- Household:Consumer-facing surface cleaners and laundry additives employ lower-concentration actives with reduced toxicity profiles. Retail shelf-space competition in Germany and France favors suppliers with consolidated brand portfolios.
- Industrial:Cooling water treatment, metalworking fluids, and oilfield applications demand high-performance biocides compatible with mixed-metal infrastructure. Ruhr basin facilities operate legacy systems incompatible with oxidizing chemistries, complicating product substitution.
- Agricultural:Seed treatment and crop protection biocides face residue limit scrutiny under EU Green Deal sustainability criteria. Polish and Czech industrial zones lack mature treatment service infrastructure.
- Institutional:Healthcare, education, and government facilities specify EN-standard efficacy documentation for disinfection contracts. Italian and French hospital procurement groups consolidate purchasing through framework agreements that favor suppliers with comprehensive dossier capabilities.
Industrial applications absorb the highest absolute volumes; institutional procurement is climbing the fastest on contract consolidation velocity.
Form:
Transport economics and dosing equipment compatibility determine format selection across supply chain configurations.
- Liquid:These formulations dominate volume shipments due to ease of dosing and compatibility with existing application equipment. Municipal water utilities across the Rhine basin prefer liquid precursors for on-site chlorine dioxide generation.
- Powder:Reduced water content favors long-distance transport to agricultural seed treatment operations. Eastern European distribution networks optimize freight costs through powder concentration.
- Granular:Slow-release formulations suit soil treatment and structural wood protection applications. Nordic timber treatment facilities specify granular copper-organic systems.
- Emulsifiable Concentrate:These formulations enable active ingredient stabilization in oil-based carrier systems. Specialty agricultural applications in Mediterranean horticulture demand emulsion stability under variable temperature conditions.
Liquid formats retain volume dominance; powder alternatives are gaining share fastest on transport cost optimization.
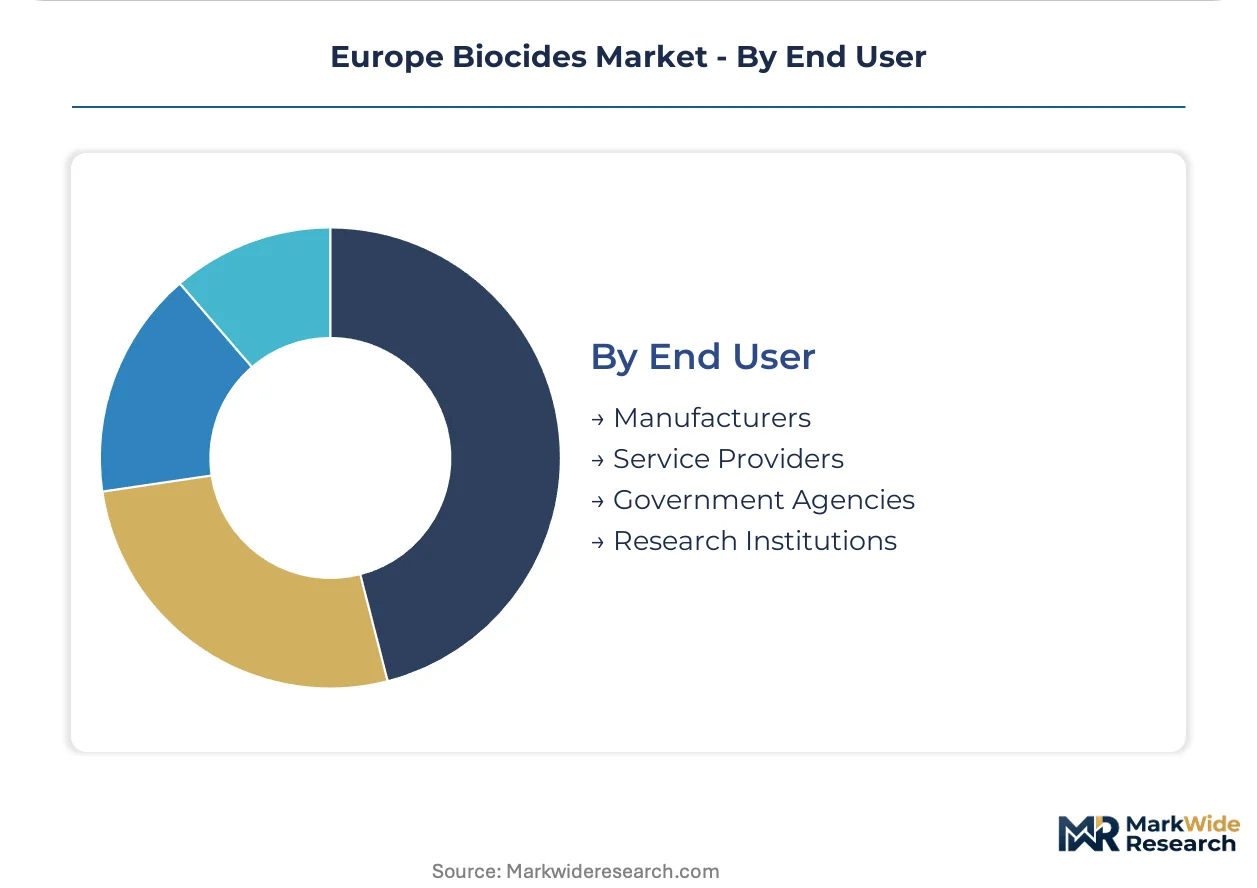
End User:
Technical specification authority and compliance liability exposure separate direct manufacturers from intermediated service channels.
- Manufacturers:Coating, adhesive, and personal care formulators embed biocides as raw material inputs. REACH registration obligations concentrate with substance manufacturers rather than downstream users.
- Service Providers:Water treatment and industrial hygiene contractors specify biocide programs for client facilities. Cooling tower service contracts in the Netherlands bundle chemical supply with equipment monitoring.
- Government Agencies:Municipal utilities and public health authorities procure disinfectants through multi-year tender cycles with embedded efficacy certification requirements. Rhine basin chlorine dioxide generation capex fragments procurement timelines.
- Research Institutions:Academic and contract laboratories evaluate novel active substances for BPR dossier preparation. Toxicology and ecotoxicology specialist scarcity constrains SME participation in authorization processes.
Manufacturers represent the largest volume channel; service providers are expanding most quickly on outsourcing trends in industrial water treatment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr chemical corridor and Rotterdam-Antwerp port zone concentrate EU biocide manufacturing under REACH and BPR jurisdiction. Industrial density in these hubs drives formulation demand while regulatory enforcement tightens active substance approvals.
Germany
Rhine basin municipal utilities upgrade chlorine dioxide generation capacity for drinking water pathogen limits. The Federal Environment Agency enforces BPR compliance timelines strictly. Leverkusen and Ludwigshafen host bromine derivative production serving cooling tower applications across heavy industry clusters.
Netherlands
Rotterdam port logistics anchor precursor chemical distribution for on-site generation systems. The National Institute for Public Health and the Environment accelerates substance evaluation under EU Green Deal criteria. Dutch water utilities pilot membrane-cell electrochemical systems eliminating transport hazards.
France
Hospital procurement frameworks in Paris and Lyon consolidate disinfectant purchasing through multi-year agreements. ANSM coordinates with EMA on human health exposure assessments for healthcare biocides. The Grand Est region hosts coating formulators reformulating away from organotin preservatives under REACH pressure.
Belgium
Antwerp's chemical processing infrastructure supports preservative manufacturing for personal care and coatings. The Federal Public Service Health mandates BPR dossier completeness for active substance approvals. Flemish industrial zones drive demand for metalworking fluid biocides in automotive supply chains.
Poland
Automotive and electronics manufacturing clusters in Silesia and Greater Poland lack mature cooling water treatment infrastructure. The Chief Inspectorate of Environmental Protection implements REACH restrictions with lag versus Western enforcement. These industrial zones create first-mover positioning opportunities for service providers.
Europe Biocides Market Vendor Landscape
Top-tier vendors anchor integrated chemical supply chains, while mid-tier specialists concentrate on formulation expertise and regional service bundling. The vendor base stratifies between substance manufacturers with REACH registration obligations and downstream formulators managing BPR product authorization. Three archetypes dominate: diversified chemical conglomerates with captive active ingredient production, regional formulation houses serving niche applications, and water treatment service providers bundling chemical supply with equipment monitoring. Competitive moves center on backward integration into precursor manufacturing and geographic expansion into underpenetrated Central European industrial zones.
Among German-based chemical conglomerates, BASF SE and LANXESS occupy positions spanning active substance production through formulated product distribution. Evonik Industries AG exemplifies the specialty chemical archetype with concentrated expertise in peroxygen systems. These three entities represent the spectrum from integrated supply chain control to targeted formulation science, with each archetype responding differently to ECHA authorization timelines and REACH restriction schedules.
| Leading Market Players |
|---|
| BASF SE |
| LANXESS |
| Clariant |
| Dow Chemical Company |
| Evonik Industries AG |
| Lonza Group Ltd |
| Henkel AG & Co KGaA |
| Ecolab |
| Nouryon |
| Others |
Supply Flow & Price Mechanics
Electrochemical on-site generation systems for chlorine dioxide are compressing transport economics while redistributing value capture toward equipment-service bundling across Rhine basin utilities. This distributed production transition simultaneously elevates capital intensity for municipal buyers and fragments procurement into multi-year tender cycles, insulating incumbent precursor suppliers from spot price competition.
Pricing Analysis
Short lead-time premiums attach to BPR-authorized active substances facing ECHA evaluation backlogs, while spot inventory discounts emerge for legacy chemistries approaching REACH restriction deadlines. Contract-based long-term offtake dominates municipal water treatment procurement, with price differentiation resting on certification grade and volume scale. Cost compression in coating preservatives is intensifying because formulators accelerate substitution away from organotin compounds. Small and medium enterprises exhibit highest price sensitivity due to toxicology specialist scarcity constraining dossier preparation capabilities.
Supply Chain Analysis
REACH and BPR certification gating concentrates authorized active substance supply in Germany, the Netherlands, and Belgium. Elemental bromine feedstock draws from Dead Sea and Arkansas brine operations, while sodium chlorite precursors and peracetic acid formulations hinge on Antwerp-Rotterdam chemical corridor infrastructure. Single-source vulnerability runs through concentrated bromine supply geography exposing European derivative manufacturers to freight and energy cost volatility. Distribution runs through integrated chemical conglomerates with captive active ingredient production serving downstream formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active substance approval bottlenecks at ECHA's Biocidal Products Committee constrain supply expansion, propping pricing power for authorized chemistries amid forced substitution demand.
For Market Incumbents: Extend backward integration into precursor manufacturing to secure supply continuity against Dead Sea bromine concentration risk. Deepen service bundling in cooling water treatment to lock in multi-year contracts before Central European industrial zones mature. Regulatory authorization delays on novel actives threaten margin erosion from bio-based substitutes once ECHA backlog clears. For New Entrants and Emerging Players: Enter via Poland and Czech Republic automotive clusters where cooling water treatment infrastructure remains underdeveloped. Target seed treatment powder formulations for Eastern European grain belt distribution where transport economics favor concentrated products. Pursue equipment-service bundling models rather than commodity chemical supply to differentiate from established precursor distributors. For Investors and Strategic Acquirers: Re-rating potential sits with specialty peroxygen formulators given EU Green Deal chemical sustainability criteria redirecting agricultural and food processing demand. Long-term viability favors candidates with established BPR dossier capabilities and research institution partnerships addressing toxicology specialist scarcity. Watch ECHA substance evaluation work program acceleration as inflection signal for enzyme-based active commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Manufacturing | Captive sodium chlorite supply secures Rhine basin utility contracts against transport hazard regulations. |
| Electrochemical On-Site Generation Partnership | Membrane-cell system deployment with Dutch utilities shifts value from chemical sales to service fees. |
| Bio-Based Active Substance Certification | EU Green Deal compliance pathways unlock agricultural applications facing residue limit scrutiny. |
| Central European Service Network Expansion | Polish and Czech industrial zone penetration captures first-mover positioning in automotive cooling treatment. |
| Peroxygen-Quaternary Ammonium Hybrid Development | Synergistic formulations targeting Candida auris command premium positioning in French hospital procurement frameworks. |
Methodological Framework
Document review covered ECHA Biocidal Products Committee evaluation records, REACH restriction proposal databases, and EU Green Deal chemical sustainability criteria, complemented by interviews with plant managers at German chemical conglomerates, procurement leads at Dutch water utilities, and technical R&D directors at specialty biocide formulators. Secondary validation drew from Cefic industry reports, customs trade data for precursor chemicals, and SEC filings of listed chemical manufacturers. Bottom-up active substance demand modeling triangulated against top-down market sizing across product type, application, and form dimensions.
Segment-level value outputs were derived through application-intensity coefficients and end-use pricing stratification across the projection horizon. The analytical framework modeled disinfectant, preservative, pesticide, and wood treatment categories against industrial, institutional, agricultural, and household demand clusters. CAGRs were synthesized from replacement cycle analysis, regulatory phase-out timelines, and infrastructure investment patterns in water treatment and healthcare hygiene.
Revisions become necessary when ECHA authorization timelines materially compress, REACH restriction schedules accelerate, or bromine supply disruptions from Dead Sea operations materialize. Forecasts reflect assumptions regarding BPR compliance enforcement consistency and EU Green Deal implementation pace. A model refresh is warranted upon material change in ECHA Biocidal Products Committee evaluation velocity or essential use exemption criteria revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Nitrogen Trifluoride (NF3) Market
Industrial Chemicals
North America Molecular Sieve Market
Industrial Chemicals
Molecular Sieves Market
Industrial Chemicals
Antiscalant Market
Industrial Chemicals
LAMEA Deoxidizer Market
Industrial Chemicals
Europe and Middle East Lime Market
Industrial Chemicals
Adblue Market
Industrial Chemicals
Singapore Sealants Market
Industrial Chemicals
Fischer-Tropsch (FT) Wax Market
Industrial Chemicals
Aerosol Sprayers Market
Industrial Chemicals
Chrome Plating Market
Industrial Chemicals
Potassium Acetate Market
Industrial Chemicals
Diesel Exhaust Fluid Market
Industrial Chemicals
Lignin Market
Industrial Chemicals
Global Antifreeze Market
Industrial Chemicals
Fluidizers in Plasterboard Market