
 Spain Computed Tomography Market | 2026-2036
Spain Computed Tomography Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Computed Tomography Market Analytics
Artificial intelligence-integrated detector materials are recalibrating total cost of ownership for CT platforms across Spanish healthcare networks. GE HealthCare leverages its deep installed base in Iberian hospital systems to sustain service contract renewals. Siemens Healthineers anchors its position through direct technical training partnerships with regional health ministries. Canon Medical Systems competes on spectral imaging upgrades that extend equipment lifecycles without full replacement.
Computed tomography denotes an X-ray-based imaging modality wherein rotating gantry assemblies capture cross-sectional anatomical data through differential attenuation measurements, typically employing detector arrays with sub-millimeter spatial resolution to reconstruct three-dimensional volumetric datasets for diagnostic interpretation. Multi-slice CT systems dominate installed capacity in Spanish hospitals due to throughput requirements for emergency and oncology workflows, while portable CT configurations represent the fastest-expanding installation category as intensive care units seek point-of-care neuroimaging without patient transport. Cone beam CT applications in dental and maxillofacial settings occupy a mature niche with stable replacement cycles, whereas cardiac CT segments attract premium positioning amid coronary artery calcium scoring expansion in preventive cardiology programs.
Spain's national medical device regulator, the Spanish Agency for Medicines and Health Products, enforces CE marking compliance under EU MDR requirements that lengthen approval timelines for new CT system introductions. The EU AI Act classification rules for clinical decision-support algorithms will reshape software upgrade pathways for AI-enabled reconstruction and lesion detection modules. Hospital procurement directors must evaluate total cost of ownership implications as detector technology refresh cycles compress and regulatory documentation burdens intensify.
Market Dynamics
AI-integrated reconstruction algorithms are compressing detector refresh cycles across Spanish hospital networks, forcing procurement directors to recalculate equipment economics beyond hardware depreciation schedules.
Growth Catalysts
- EU AI Act compliance pathways:The classification rules for clinical decision-support algorithms create regulatory clarity that accelerates software upgrade investments in Madrid and Barcelona oncology centers.
- Intensive care neuroimaging demand:Portable CT configurations are displacing fixed-room installations as Spanish ICUs prioritize point-of-care diagnostics without patient transport risks.
- Coronary artery calcium scoring expansion:Preventive cardiology programs in Catalonia are driving cardiac CT protocol standardization across regional health service procurement frameworks.
Market Restraints
- Detector material cost volatility:Rare earth element price swings in gadolinium-based scintillator supply chains compress manufacturer margins on mid-range system configurations.
- EU MDR documentation burdens:Extended CE marking timelines for new CT introductions delay product launches by 12-18 months versus pre-2021 regulatory pathways.
- Specialized service engineer scarcity:Concentration of trained personnel in Madrid and Barcelona creates maintenance response gaps for installations in Galicia and Andalusia.
Strategic Opportunities
- Andalusian healthcare infrastructure gaps:Underpenetrated provinces offer first-mover positioning for spectral imaging upgrades before regional budget cycles consolidate.
- Hybrid operating room integration:Convergence of intraoperative CT with surgical navigation systems creates new placement categories outside traditional radiology departments.
- Public-private imaging networks:Diagnostic outsourcing partnerships with private clinic chains are reshaping equipment financing models in Valencia and Murcia.
Industry Challenges
- AI algorithm validation complexity:Spanish Agency for Medicines and Health Products requires site-specific performance documentation that fragments software deployment timelines.
- Legacy PACS integration friction:Older hospital information systems in Basque Country networks resist seamless data handoff from new reconstruction engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Computed Tomography Market |
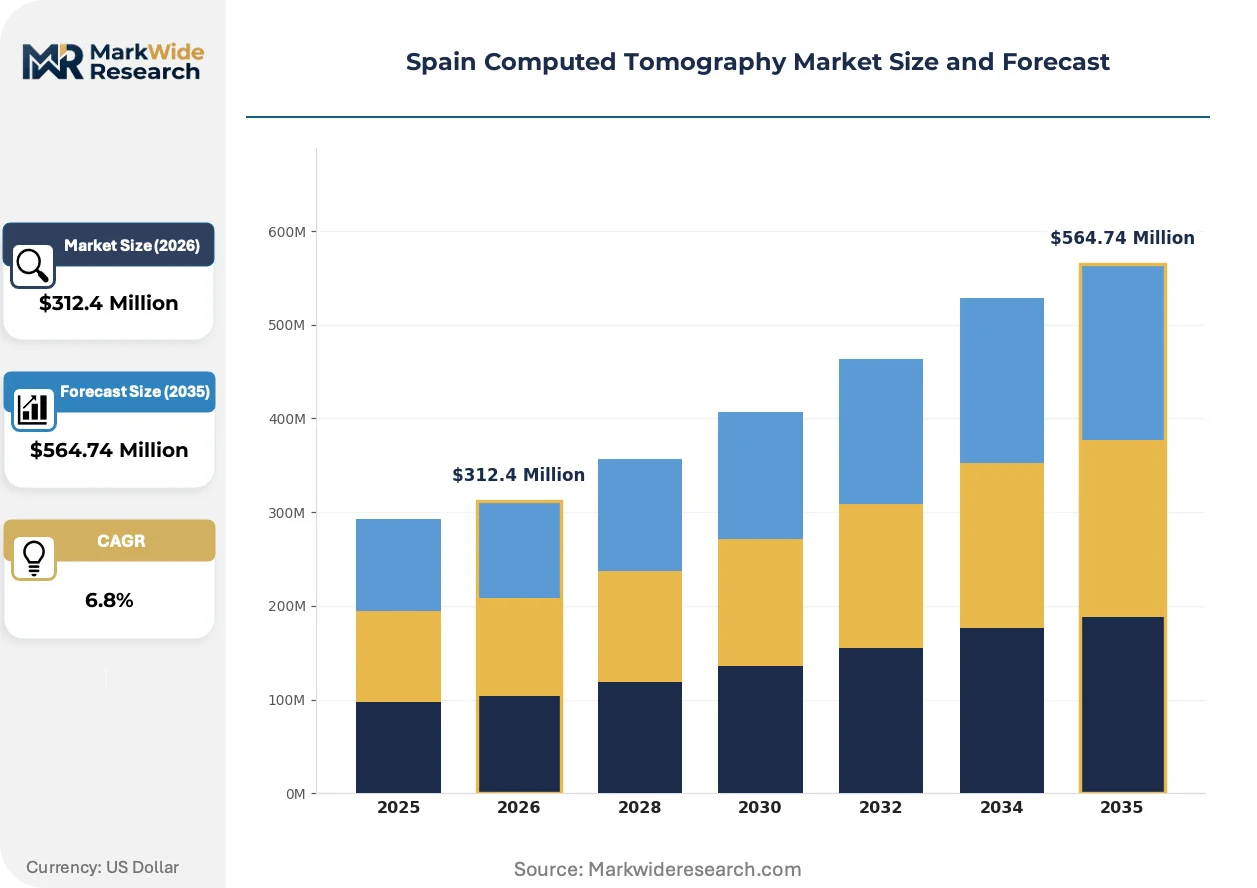
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multi-Slice CT, Cone Beam CT, Portable CT, Desktop CT Application: Oncology, Neurology, Cardiology, Trauma End User: Hospitals, Diagnostic Centers, Research Institutions, Outpatient Facilities Installation: Fixed, Mobile, Integrated, Retrofitted |
| Companies Covered | Canon Medical Systems, Carestream Health, GE HealthCare, Esaote, Shimadzu Corporation, Siemens Healthineers, Fujifilm Holdings Corporation, Hologic, Koninklijke Philips, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Computed Tomography Market Evolving Landscape
Photon-counting detector architectures are forcing a recalculation of equipment lifecycle economics across Spanish radiology departments, compressing the traditional ten-year replacement horizon.
Photon-counting CT detectors with cadmium telluride substrates are rewriting spatial resolution benchmarks for cardiac and pulmonary angiography protocols. University hospitals in Madrid and Barcelona are piloting these systems for coronary stenosis quantification. The technology is rewriting service contract structures as manufacturers bundle detector replacement guarantees into premium pricing tiers.
The EU AI Act's risk classification framework for clinical decision-support software is mandating algorithm validation documentation that extends procurement review periods. Spanish hospital procurement directors must now evaluate AI-enabled lesion detection modules as distinct medical devices rather than software accessories. Cardiac CT segments face the steepest compliance burdens due to automated calcium scoring algorithms falling under Class IIa device categorization.
Subscription-based equipment access models are displacing capital purchase structures among medium-sized Spanish hospital networks. Regional health ministries in Catalonia and Andalusia are piloting per-scan pricing arrangements that transfer obsolescence risk to manufacturers. The shift is most visible in emergency department CT installations where throughput volatility makes fixed-cost depreciation difficult to justify.
Spain Computed Tomography Market Segmentation
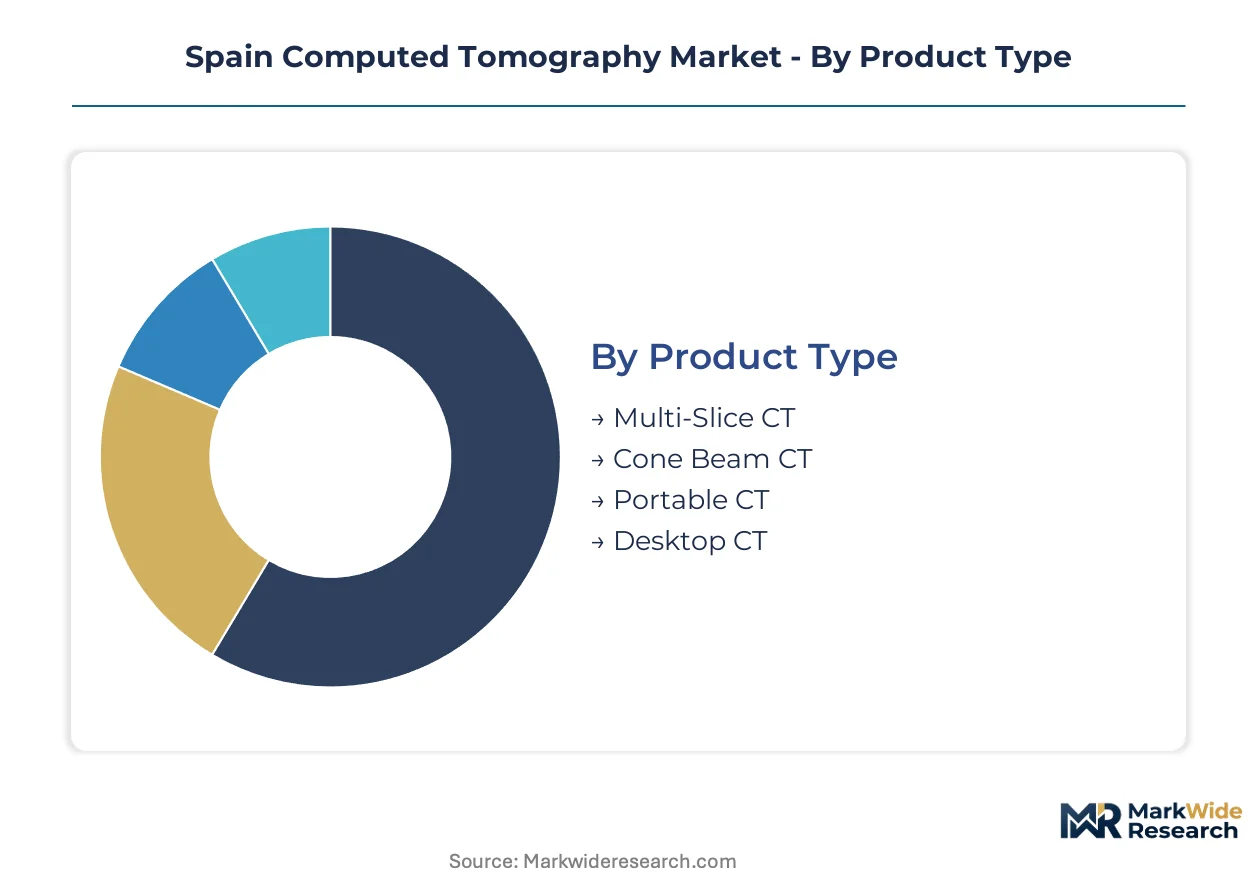
Procurement directors across Spanish healthcare networks evaluate CT platforms through four intersecting lenses: throughput capacity, clinical specialization, facility infrastructure, and financing flexibility. These segmentation dimensions determine equipment specifications, service contract structures, and upgrade pathways for installations from Madrid oncology centers to Andalusian diagnostic clinics.
Product Type:
Hospital procurement committees prioritize slice count and detector refresh economics when selecting system configurations for emergency and scheduled imaging workflows.
- Multi-Slice CT:Systems with 64 to 320 detector rows deliver sub-millimeter spatial resolution for high-throughput oncology and trauma protocols. Demand concentrates in Catalonia and Madrid where specialized centers require continuous patient flow capacity.
- Cone Beam CT:Flat-panel detector architectures capture volumetric datasets with reduced radiation exposure for dental and maxillofacial applications. Replacement cycles in Barcelona and Valencia dental clinics stabilize as the segment reaches equipment maturity.
- Portable CT:Self-contained gantry units on motorized bases enable neuroimaging at the bedside without ICU patient transport. Intensive care units in Galicia and Andalusia are expanding installations fastest.
- Desktop CT:Compact systems with limited field-of-view serve preclinical research and small specimen analysis. University laboratories in Madrid and Barcelona anchor demand for this configuration.
Multi-Slice CT leads on scale; Portable CT leads on momentum.
Application:
Reimbursement protocol revisions from Spain's Ministry of Health are redirecting capital allocation toward preventive screening and early-stage detection programs.
- Oncology:Whole-body staging protocols and treatment response monitoring drive the highest scan volumes across Spanish hospital networks. Catalonia's regional health service prioritizes procurement for lung and colorectal screening expansion.
- Neurology:Stroke protocol standardization and trauma triage requirements sustain demand for rapid head imaging. Galician emergency departments are retrofitting older systems for perfusion imaging capability.
- Cardiology:Coronary artery calcium scoring for cardiovascular risk stratification is gaining protocol standardization. Preventive cardiology programs in Madrid private hospital chains are climbing the fastest.
- Trauma:Polytrauma assessment and emergency department throughput requirements demand rapid reconstruction speeds. Andalusian public hospital networks concentrate replacement investments here.
Oncology leads on scale; Cardiology leads on momentum.
End User:
Facility type determines financing structure, with public hospital networks favoring capital purchases while private diagnostic chains explore per-scan arrangements.
- Hospitals:Acute care facilities with 24-hour emergency operations require highest reliability guarantees and fastest service response. Madrid and Barcelona hospital clusters anchor the installed base.
- Diagnostic Centers:Outpatient imaging facilities prioritize throughput economics and scheduling flexibility. Private chains in Valencia and Murcia are expanding through equipment leasing partnerships.
- Research Institutions:University hospitals and clinical trial centers demand spectral imaging and advanced reconstruction algorithms. Barcelona's biomedical research park drives specialized procurement.
- Outpatient Facilities:Ambulatory surgery centers and specialty clinics seek compact footprints with limited technical staffing requirements. Andalusian regional health ministry pilots are expanding this category.
Hospitals lead on scale; Diagnostic Centers lead on momentum.
Installation:
Physical integration requirements shape total cost of ownership calculations as facilities weigh construction costs against equipment mobility.
- Fixed:Permanent room installations with radiation shielding and dedicated power infrastructure dominate existing hospital radiology departments. Basque Country networks maintain the densest concentration of legacy fixed systems.
- Mobile:Transportable units on dedicated vehicles serve rural areas and temporary screening campaigns. Castile and León health authorities are expanding mobile lung cancer detection fleets.
- Integrated:Hybrid operating room configurations combine intraoperative CT with surgical navigation for neurosurgery and orthopedics. Madrid university hospitals are piloting the steepest expansion trajectory.
- Retrofitted:Detector and gantry upgrades extend functional life of existing installations without full replacement. Budget-constrained facilities in Extremadura and Castilla-La Mancha favor this pathway.
Fixed leads on scale; Integrated leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Madrid anchors the national CT installed base through dense clusters of university hospitals and specialized oncology centers that drive premium system procurement.
Madrid
Acute stroke protocols and trauma triage requirements sustain demand for high-throughput multi-slice configurations. Spain's Ministry of Health channels capital subsidies toward public hospital network modernization in the capital region. The La Paz and Gregorio Marañón hospital complexes concentrate the country's densest concentration of cardiac CT installations.
Catalonia
Preventive cardiology programs and lung cancer screening expansion are redirecting procurement budgets toward spectral imaging capabilities. The regional health service of Catalonia prioritizes early-stage cancer detection in its medical device reimbursement protocols. Barcelona's Hospital Clínic and Vall d'Hebron complexes anchor specialized oncology imaging demand.
Andalusia
Budget-constrained public hospital networks favor retrofitted detector upgrades over full system replacement cycles. The Andalusian regional health ministry pilots subscription-based per-scan pricing models for emergency department installations. Seville and Málaga hospital clusters represent the fastest-expanding portable CT deployment for intensive care neuroimaging.
Basque Country
Legacy PACS integration challenges slow reconstruction engine upgrades in older hospital information systems. Basque health authorities enforce strict CE marking compliance timelines under EU MDR requirements for new system introductions. Bilbao's hospital network maintains the densest concentration of fixed-room installations awaiting mobile configuration transitions.
Valencia
Public-private diagnostic outsourcing partnerships are reshaping equipment financing structures for outpatient imaging chains. The Valencian regional health ministry expands mobile lung cancer detection fleets into underpenetrated inland provinces. Private clinic clusters in Alicante and Castellón drive leasing-based procurement for compact system configurations.
Spain Computed Tomography Market Competitive Landscape
Service contract bundling dominates the current landscape as manufacturers leverage installed base density to lock in multi-year maintenance renewals. The vendor structure concentrates around three tiers: diversified medical technology conglomerates with full imaging portfolios, specialized diagnostic imaging equipment manufacturers, and regional service providers with retrofit expertise. Technology licensing agreements and detector material supply partnerships represent the primary competitive moves reshaping positioning.
Among diversified imaging technology providers, GE HealthCare, Siemens Healthineers, and Canon Medical Systems occupy positions shaped by direct technical training partnerships with regional health ministries. Siemens Healthineers exemplifies the premium-tier archetype through its anchoring role in Madrid and Barcelona university hospital networks. Canon Medical Systems represents the spectral imaging specialization vector, while GE HealthCare sits within the broad installed base leverage category.
| Leading Market Players |
|---|
| Canon Medical Systems |
| Carestream Health |
| GE HealthCare |
| Esaote |
| Shimadzu Corporation |
| Siemens Healthineers |
| Fujifilm Holdings Corporation |
| Hologic |
| Koninklijke Philips |
| Others |
Value Network & Pricing Analysis
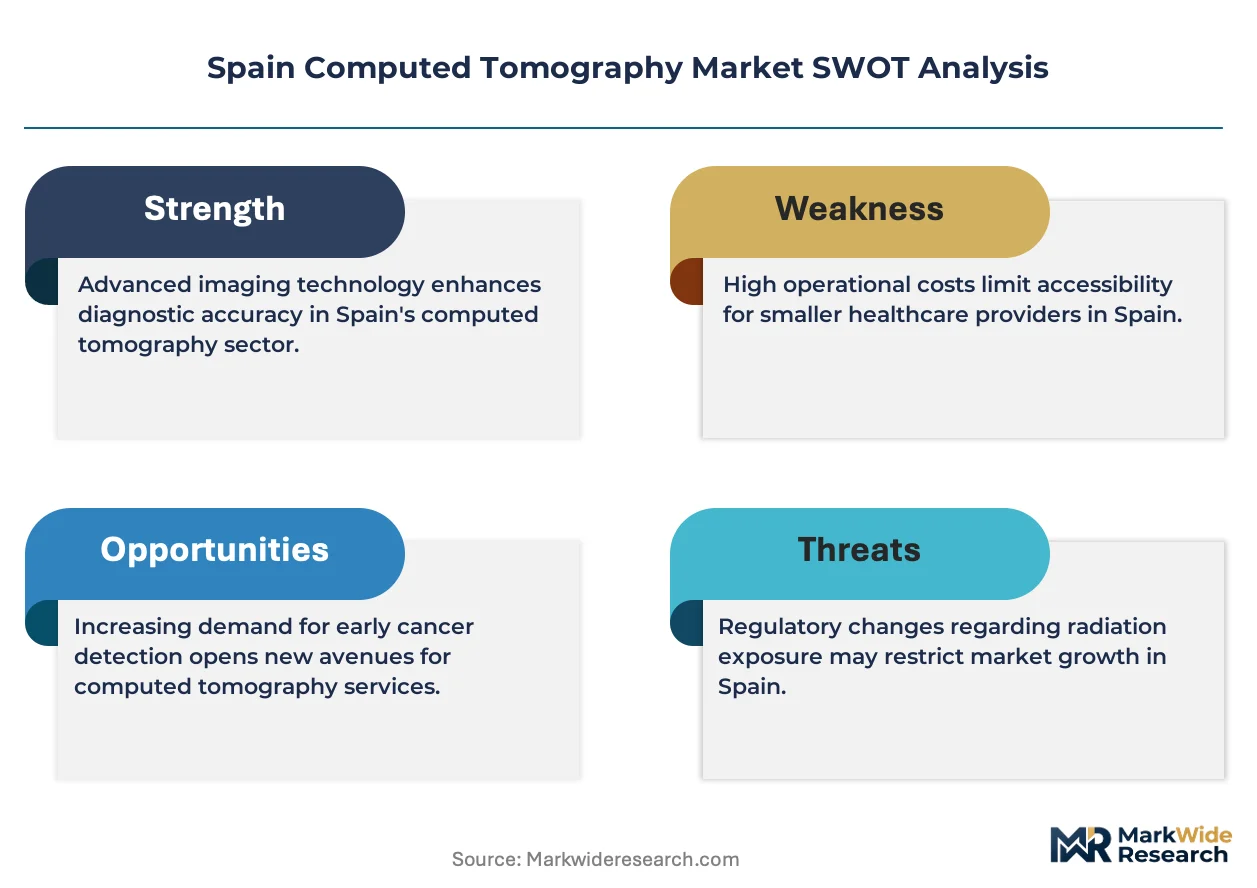
EU MDR sustainability documentation requirements gate qualified supply access and premium-tier pricing power for CT manufacturers serving Spanish hospital networks. Detector material traceability mandates compress supplier pools while elevating compliance costs into equipment pricing structures.
Pricing Analysis
Gadolinium-based scintillator cost pass-through dominates equipment economics as manufacturers absorb rare earth element volatility into service contract premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by detector row count and AI reconstruction capability. Pricing pressure stems from compressed refresh cycles as photon-counting architectures displace legacy systems. Public hospital procurement committees exhibit highest price sensitivity due to fixed capital budgets, while private diagnostic chains accept premium positioning for throughput guarantees.
Supply Chain Analysis
Trained service engineer scarcity in German and Dutch manufacturing hubs constrains detector module production capacity for Iberian deliveries. Supply chains draw from Japanese substrate foundries, Chinese rare earth processors, and German gantry assembly facilities. Single-source vulnerability concentrates in cadmium telluride wafer supply for photon-counting detector architectures. Distribution runs through manufacturer-direct technical service teams rather than third-party logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by demand migration toward spectral imaging specifications that extend equipment lifecycles without full replacement.
For Market Incumbents: Lock in multi-year service contract renewals before photon-counting detector standardization erodes maintenance revenue pools. Anchor position through direct technical training partnerships with Andalusian and Galician regional health ministries to preempt emerging entrant field service buildout. Vertical integration into detector refurbishment capabilities defends margin position against subscription-based per-scan pricing pilots. For New Entrants and Emerging Players: The mid-tier price-point gap between premium spectral systems and economy multi-slice configurations offers white-space positioning for retrofitted detector upgrade specialists. Target Extremadura and Castilla-La Mancha public hospital networks where budget constraints favor lifecycle extension over capital replacement. Pursue equipment-as-a-service financing partnerships with Valencian private diagnostic chains as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for regional service providers with retrofit expertise because installed base density in Madrid and Barcelona creates captive maintenance revenue streams. Five-to-ten year viability hinges on AI-enabled reconstruction module deployment velocity. Monitor Spanish Agency for Medicines and Health Products algorithm validation timeline announcements as the primary inflection signal for software upgrade revenue recognition.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR documentation compliance accelerates market access for photon-counting detector introductions. |
| Hospital System Partnership | Catalan regional health service procurement frameworks prioritize spectral imaging capability in tender evaluations. |
| Software Companion Development | AI-enabled lesion detection modules require standalone Class IIa device classification under EU AI Act rules. |
| Reimbursement Strategy | Spain's Ministry of Health early-stage cancer detection protocols redirect capital toward screening-optimized configurations. |
| Technical Training Partnership | Direct education agreements with regional health ministries lock in service contract renewal preference. |
Research Methodology
Coverage spans Madrid, Catalonia, Andalusia, Basque Country, and Valencia, with primary inputs from each region's hospital procurement committees and biomedical engineering directors. The analysis combines structured interviews with radiology department heads, GPO contracts managers, and regional health ministry technology officers with secondary validation from hospital procurement databases, AEMPS regulatory filings, and Catalan regional health service tender documentation. Bottom-up installation tracking and top-down healthcare expenditure modeling provide triangulation.
Granularity-level framing applies product type, application, end user, and installation configuration dimensions at the regional level, with technology refresh cycle timing modeled at the hospital-cluster level. CAGRs derive from equipment replacement velocity assumptions and AI module penetration curves across the projection horizon. Forecast inputs include detector material cost indices and EU AI Act implementation timeline scenarios.
Caveats apply where EU MDR documentation burden revisions or rare earth element supply disruptions could materially shift the outlook. Practitioners should monitor AEMPS algorithm validation queue depth and Andalusian per-scan pricing pilot expansion for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Germany Mammography Market
Medical Imaging
US and Europe Digital Pathology Market
Medical Imaging
Industrial Computed Radiography Market
Medical Imaging
Smart X-Ray Detectors Market
Medical Imaging
Asia Pacific Computed Tomography (CT) Market
Medical Imaging
Advanced Computed Tomography (CT) Scanner Market
Medical Imaging
Open Magnetic Resonance Imaging System Market
Medical Imaging
Neurophotonics Market
Medical Imaging
Australia Digital Radiology Market
Medical Imaging
Asia-Pacific Digital X-Ray Devices Market
Medical Imaging
Netherlands Diagnostic Imaging Equipment Market
Medical Imaging
Global Veterinary X-Ray Market
Medical Imaging
Mobile Gamma Cameras Market
Medical Imaging
North America Open System MRI Market
Medical Imaging
Asia Pacific Nuclear Imaging Market
Medical Imaging
Preclinical MRI Equipment Market