
 Glioblastoma Market | 2026-2036
Glioblastoma Market Size, Share, and Industry Trends Forecast 2026-2036
Glioblastoma Market Analysis
Software-defined treatment protocols embedded in tumor-treating field delivery systems is broadening what device manufacturers sell beyond hardware to ongoing therapy optimization services. Novocure leverages this shift through continuous patient monitoring and dose adjustment algorithms that sustain recurring revenue streams. Merck & Co., Inc. anchors its position with deep R&D investment in combination regimens integrating its established antineoplastic portfolio. F. Hoffmann-La Roche Ltd. differentiates through biomarker-driven patient stratification tools that extend its diagnostic-to-therapeutic control across the care pathway.
Glioblastoma constitutes a grade IV astrocytoma characterized by pseudopalisading necrosis, microvascular proliferation, and IDH-wild-type molecular status in primary cases, with temozolomide and radiation forming the standard-of-care backbone for maximal safe resection followed by adjuvant chemoradiation. Immunotherapy approaches within treatment type segmentation are capturing disproportionate development investment as checkpoint inhibitors and CAR-T protocols target the tumor's immunosuppressive microenvironment. Targeted therapy within drug type segmentation occupies concentrated margin pools where EGFR amplification and MGMT methylation status guide precision prescribing, while intratumoral delivery routes are expanding as device-pharma convergence enables localized drug deposition bypassing the blood-brain barrier.
FDA breakthrough therapy designation and EMA PRIME eligibility compress development timelines for glioblastoma agents, while WHO classification updates for CNS tumors reshape trial endpoints and diagnostic requirements. Japan's PMDA sakigake designation adds a third accelerated pathway that manufacturers navigate for priority review in Asia's second-largest pharmaceutical market. Stakeholders must monitor how evolving regulatory standards for overall survival endpoints and pseudoprogression assessment reshape competitive positioning across combination therapy development programs.
Market Dynamics
Software-defined treatment protocols embedded in tumor-treating field delivery systems are compressing development cycles and forcing device manufacturers to compete on algorithmic therapy optimization rather than hardware specifications alone.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The pathway accelerates glioblastoma agent review timelines, compressing phase transitions for novel immunotherapy candidates.
- Combination Immunotherapy Protocols:Academic medical centers in the United States, Germany, and Japan are expanding adoption of checkpoint inhibitor regimens targeting the tumor's immunosuppressive microenvironment.
- Intratumoral Delivery Routes:Device-pharma convergence enables localized drug deposition that bypasses the blood-brain barrier, opening new therapeutic modalities.
Market Restraints
- Blood-Brain Barrier Impermeability:Systemic chemotherapy faces structural pharmacokinetic limitations that reduce effective intracranial drug concentrations below therapeutic thresholds.
- Clinical Trial Endpoint Complexity:Pseudoprogression assessment and overall survival validation requirements under evolving WHO CNS tumor classification standards extend regulatory timelines.
- Specialized Neuro-Oncology Infrastructure Scarcity:Concentration of qualified treatment centers in the United States, Germany, and Japan limits patient access in secondary markets.
Strategic Opportunities
- Japan's PMDA Sakigake Designation:The accelerated review pathway offers priority access to Asia's second-largest pharmaceutical market for glioblastoma innovators.
- Biomarker-Driven Patient Stratification:EGFR amplification and MGMT methylation status enable precision prescribing that captures concentrated margin pools in targeted therapy segments.
- Recurring Revenue Service Models:Continuous patient monitoring and dose adjustment algorithms transform device sales into ongoing therapy optimization subscriptions.
Industry Challenges
- Neuro-Oncology Specialist Workforce Gap:Qualified investigators and clinical coordinators remain concentrated at major academic medical centers, constraining trial expansion capacity.
- Legacy Diagnostic-Therapeutic Integration:Pathology workflows require reconfiguration to support real-time biomarker testing that guides precision treatment selection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glioblastoma Market |
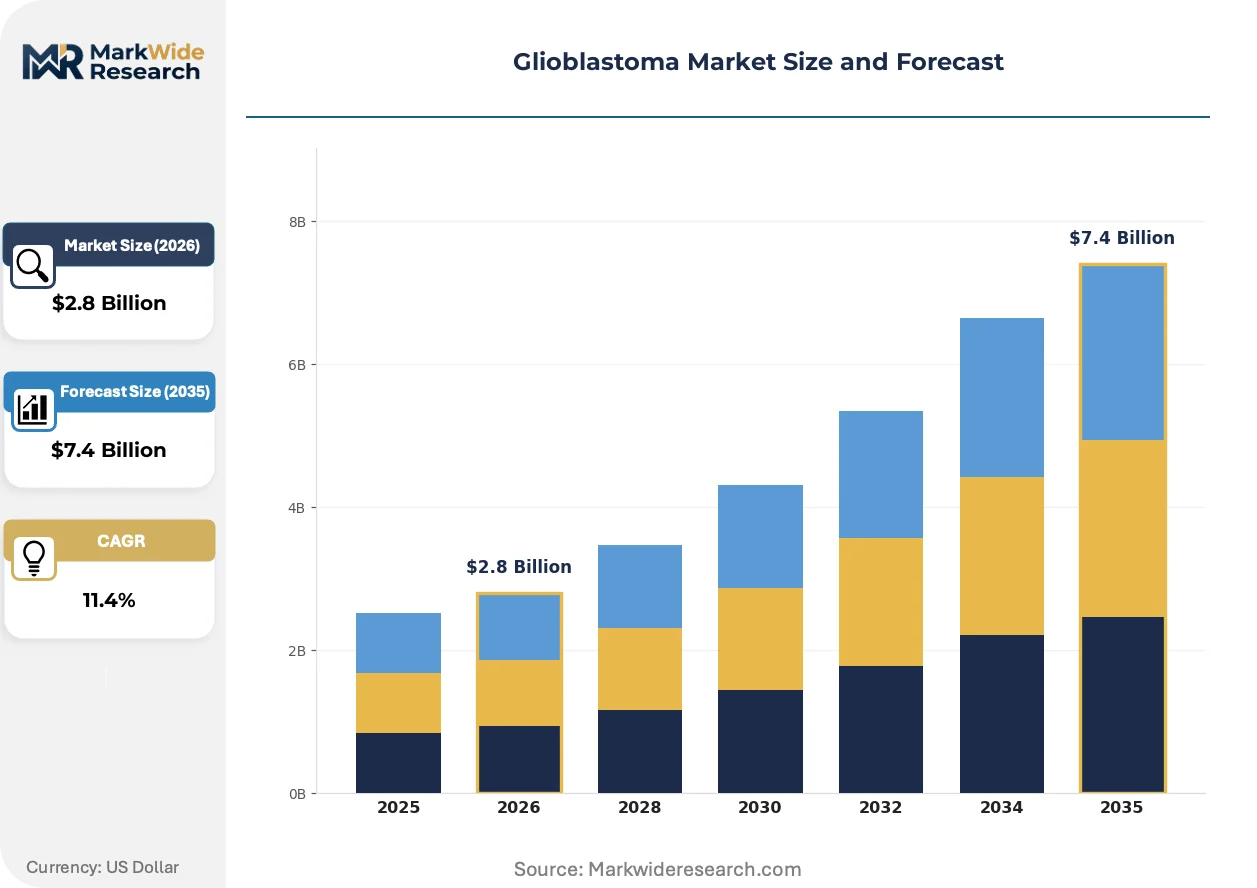
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Surgery, Chemotherapy, Radiation Therapy, Immunotherapy Drug Type: Antineoplastics, Targeted Therapy, Adjuvant Therapy, Steroids Route of Administration: Intravenous, Oral, Intratumoral, Subcutaneous End User: Hospitals, Clinics, Research Institutions, Home Care |
| Companies Covered | Merck & Co., Inc., Amgen, Inc., F. Hoffmann-La Roche Ltd., Pfizer Inc., Teva Pharmaceutical Industries Ltd., Sun Pharmaceutical Industries Ltd., Novocure, Karyopharm Therapeutics, Inc., Amneal Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glioblastoma Market Emerging Trajectories
Algorithmic therapy personalization is displacing fixed-dose protocols across glioblastoma treatment modalities, with software-defined delivery systems capturing value previously embedded in pharmaceutical compounds alone.
Tumor-treating field technology is expanding into combination regimens through continuous patient monitoring and adaptive dose adjustment algorithms. Academic medical centers in the United States and Germany are adopting these systems at accelerating pace for newly diagnosed patients. The technology is expanding into recurring revenue service models that sustain manufacturer engagement across multi-year treatment courses.
EMA PRIME eligibility for glioblastoma agents compresses European development timelines in parallel with FDA pathways. The framework accelerates scientific advice and accelerated assessment for therapies addressing unmet medical need. European developers are responding by prioritizing PRIME qualification in early-phase trial design to secure regulatory engagement advantages.
Diagnostic-to-therapeutic control is consolidating under integrated platform providers that span biomarker testing through treatment delivery. Academic medical centers and specialized neuro-oncology networks are consolidating vendor relationships around end-to-end pathway managers. This consolidation is most visible in the United States and Germany, where reimbursement infrastructure supports bundled diagnostic-therapeutic contracts.
Glioblastoma Market Segmentation
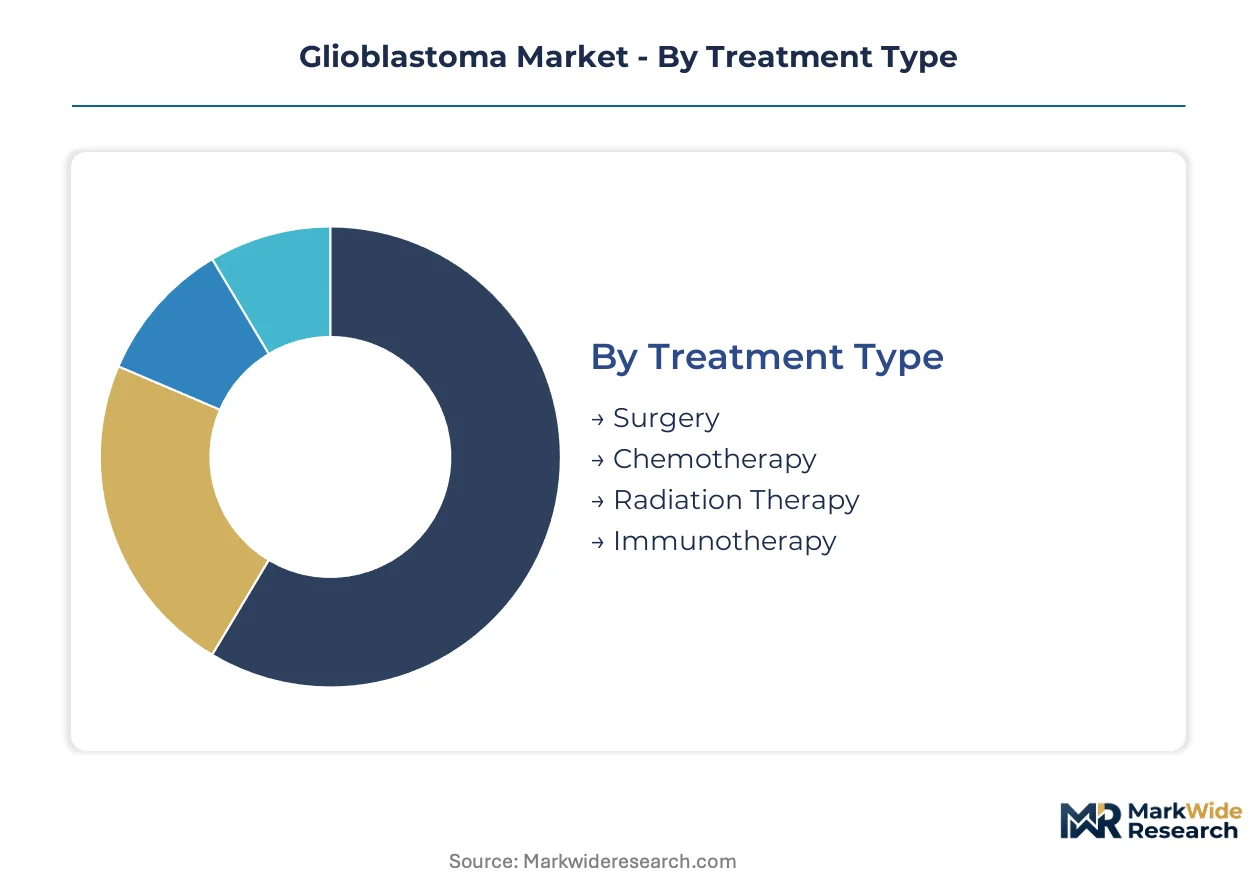
Treatment modality selection in glioblastoma hinges on molecular stratification, blood-brain barrier penetration challenges, and reimbursement infrastructure. Segmentation reveals how device-pharma convergence and precision diagnostics are reshaping competitive boundaries across the care pathway.
Treatment Type:
Surgical resection capability and adjuvant protocol integration define the technology axis across treatment modalities.
- Surgery:Maximal safe resection remains the foundation of initial intervention, with fluorescence-guided techniques and intraoperative MRI navigation concentrating demand at academic medical centers in the United States and Germany. Neurosurgical robotics and awake craniotomy protocols extend resectability thresholds for eloquent-area tumors.
- Immunotherapy:Checkpoint inhibitors, CAR-T protocols, and tumor-treating field combinations target the immunosuppressive microenvironment through programmed approaches. Academic medical centers in Japan and the United States anchor adoption as regulatory pathways compress development timelines for novel candidates.
- Chemotherapy:Temozolomide-based regimens form the standard-of-care backbone for adjuvant treatment following resection and radiation.
- Radiation Therapy:Fractionated external beam protocols integrate with chemotherapy for combined modality adjuvant courses.
Mature deployment sits with Surgery. Newer deployment is concentrated in Immunotherapy.
Drug Type:
Margin capture varies sharply by mechanism specificity and biomarker dependency across pharmaceutical categories.
- Targeted Therapy:EGFR amplification inhibitors and MGMT methylation-guided agents enable precision prescribing with concentrated margin pools. Biomarker testing infrastructure in the United States and Germany supports patient stratification that extends diagnostic-to-therapeutic control across the care pathway.
- Antineoplastics:Alkylating agents and cytotoxic compounds constitute the established pharmacologic backbone with broad applicability but narrowing differentiation.
- Adjuvant Therapy:Post-resection protocols combine chemoradiation to delay recurrence and extend progression-free intervals.
- Steroids:Corticosteroid administration manages peritumoral edema and symptomatic burden during active treatment phases.
Volume concentration rests with Antineoplastics. Value capture is climbing fastest in Targeted Therapy.
Route of Administration:
Delivery mechanics determine effective intracranial exposure and manufacturing complexity for formulation development.
- Intratumoral:Localized drug deposition bypasses blood-brain barrier limitations through convection-enhanced delivery and implantable reservoirs. Device-pharma convergence in the United States enables catheter-based and implantable systems that open therapeutic modalities previously excluded by systemic pharmacokinetics.
- Oral:Temozolomide and small-molecule inhibitors offer outpatient administration with patient convenience advantages.
- Intravenous:Systemic chemotherapy and biologic agents require repeated infusion center visits with established reimbursement pathways.
- Subcutaneous:Depot formulations and sustained-release implants extend dosing intervals for maintenance protocols.
Established utilization centers on Intravenous. Expansion momentum is strongest in Intratumoral.
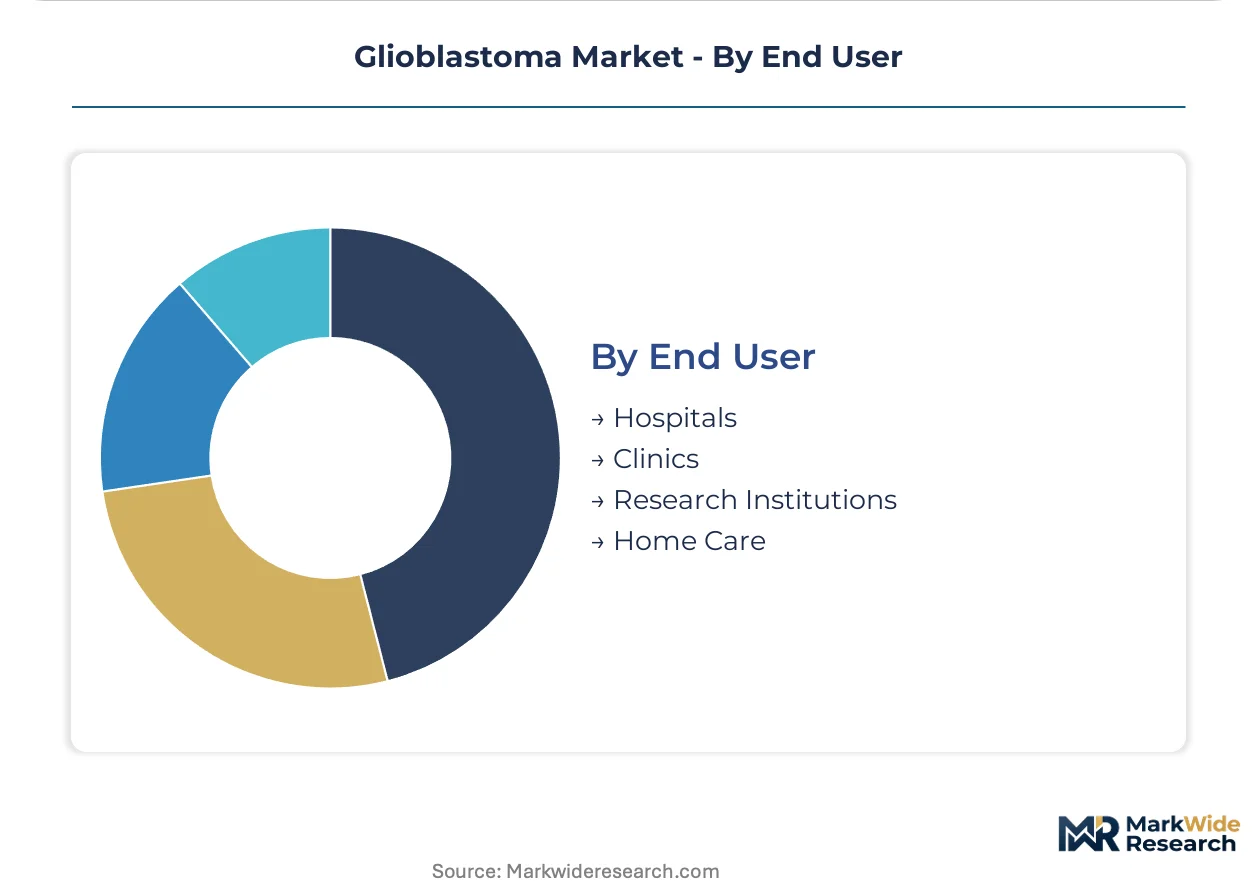
End User:
Care setting determines protocol complexity, capital equipment requirements, and specialist workforce density.
- Hospitals:Academic medical centers and comprehensive cancer centers concentrate glioblastoma care through specialized neuro-oncology infrastructure. The United States, Germany, and Japan anchor demand where reimbursement for innovative modalities and trial access are most developed.
- Research Institutions:Phase I/II trial execution and biomarker discovery programs require integrated pathology and imaging capabilities.
- Clinics:Community oncology practices manage stable patients and surveillance protocols with referral relationships to tertiary centers.
- Home Care:Oral chemotherapy administration and symptom management extend care delivery beyond institutional settings.
Capability concentration remains with Hospitals. Patient volume is dispersing most quickly toward Home Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical trial density and specialized neuro-oncology infrastructure concentrate glioblastoma treatment development in the United States, Germany, and Japan, while manufacturing of active pharmaceutical ingredients disperses across India and China. Consumption of innovative modalities clusters at academic medical centers with reimbursement access, creating geographic asymmetry between where therapies are developed and where they are administered.
United States
Academic medical centers in Boston, Houston, and San Francisco anchor global demand for tumor-treating field systems and combination immunotherapy protocols. FDA breakthrough therapy designation compresses development timelines for novel agents targeting IDH-wild-type molecular profiles. The National Cancer Institute's Neuro-Oncology Branch coordinates multi-site trials that concentrate patient access at comprehensive cancer centers with integrated pathology and imaging capabilities.
Germany
EMA PRIME eligibility accelerates scientific advice and accelerated assessment for glioblastoma therapies addressing unmet medical need. Heidelberg and Munich host specialized neuro-oncology networks that integrate fluorescence-guided surgical techniques with real-time biomarker testing workflows. German academic hospitals participate in EU-wide adaptive platform trials that reshape regulatory endpoints for pseudoprogression assessment.
Japan
PMDA sakigake designation offers priority review pathways for glioblastoma innovators seeking access to Asia's second-largest pharmaceutical market. Tokyo and Osaka academic centers concentrate adoption of device-pharma convergence technologies for intratumoral drug delivery. Japan's national health insurance system maintains distinct reimbursement categories for tumor-treating fields that sustain manufacturer engagement across multi-year treatment courses.
India
CDSCO regulatory frameworks govern manufacturing of generic temozolomide formulations that supply markets across South Asia and Africa. Hyderabad and Ahmedabad clusters host contract research organizations executing Phase I/II trials for global pharmaceutical sponsors seeking cost-efficient patient recruitment. Indian academic medical centers in Delhi and Mumbai expand neuro-oncology fellowship programs to address specialist workforce gaps.
United Kingdom
NHS England's specialized commissioning framework concentrates glioblastoma care at designated neuroscience centers in London, Manchester, and Birmingham. The MHRA's innovative licensing pathway accelerates access to novel agents for patients with limited treatment options. UK biotech clusters in Cambridge and Oxford anchor early-stage discovery programs targeting the tumor's immunosuppressive microenvironment.
Glioblastoma Market Vendor Landscape
Capital-heavy device manufacturers compete with asset-light biopharmaceutical developers for margin capture across the glioblastoma care pathway. Market structure tilts toward consolidated control at the therapeutic platform level, with diagnostic-to-therapeutic integration favoring integrated portfolio providers. Three archetypes dominate: tumor-treating field system vendors with recurring revenue service models, precision oncology specialists leveraging biomarker-driven stratification, and broad antineoplastic portfolio players anchoring combination regimen development. Competitive moves center on strategic partnerships bridging device and pharmaceutical capabilities, plus geographic expansion into Japan's sakigake pathway.
Among established pharmaceutical developers, Merck & Co., Inc. and F. Hoffmann-La Roche Ltd. occupy positions reflecting deep R&D investment in combination regimens and diagnostic-to-therapeutic platform integration. Novocure represents the device-centric archetype, embedding software-defined treatment protocols that transform hardware sales into ongoing therapy optimization subscriptions. These three entities exemplify how competitive positioning in glioblastoma increasingly depends on controlling multiple touchpoints across the care pathway rather than single-modality dominance.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Amgen, Inc. |
| F. Hoffmann-La Roche Ltd. |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Novocure |
| Karyopharm Therapeutics, Inc. |
| Amneal Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between FDA breakthrough-designated therapies and standard-of-care generics bifurcates pricing power across the glioblastoma value chain, with premium tiers commanding algorithmic service bundles while commodity formulations compete on manufacturing scale in India and China.
Pricing Analysis
Margin tightening in device-pharma convergence tiers reflects the capital intensity of tumor-treating field systems and continuous monitoring infrastructure. Three-tier pricing structure across premium algorithmic protocols, standard combination regimens, and economy generic temozolomide anchors the market. Cost-down pressure on intravenous alkylating agents accelerates because Indian and Chinese API manufacturers expand capacity. Academic medical centers in the United States and Germany exhibit lowest price sensitivity due to bundled reimbursement; community oncology clinics in secondary markets face highest budget constraints.
Supply Chain Analysis
Single-source vulnerability sits with specialized neuro-oncology device manufacturers concentrated in Israel and the United States for tumor-treating field delivery systems. Active pharmaceutical ingredient production draws from Hyderabad and Ahmedabad clusters in India, plus Shanghai and Zhejiang provinces in China, for generic temozolomide. Supply chain risk centers on regulatory restriction: FDA and EMA inspection backlogs delay facility approvals for intratumoral delivery catheter manufacturers. Distribution runs through academic medical center GPO contracts in the United States, specialized hospital networks in Germany, and national health insurance procurement in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compliance costs for FDA breakthrough therapy and EMA PRIME pathways erect formidable barriers to entry, consolidating margin capture among incumbents with established scientific advice relationships and integrated diagnostic-therapeutic platforms.
For Market Incumbents: Deploy biomarker-driven patient stratification capabilities to defend against precision oncology specialists encroaching on diagnostic-to-therapeutic control. Consolidate vendor relationships with academic medical centers through bundled algorithmic therapy optimization contracts. Deepen backward integration into implantable reservoir manufacturing to secure intratumoral delivery supply chains against catheter shortages. For New Entrants and Emerging Players: Capture Japan's PMDA sakigake designation pathway as the most penetrable accelerated review route for glioblastoma innovators, where national health insurance maintains distinct reimbursement categories for novel modalities. Target community oncology networks in the United Kingdom and secondary German markets underserved by comprehensive cancer center concentration. Pursue licensing agreements with established device manufacturers for tumor-treating field combination protocols rather than de novo hardware development. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-level acquisitions by large-cap pharmaceutical developers seeking diagnostic-to-therapeutic integration. Long-term viability hinges on controlling multiple touchpoints across the care pathway rather than single-modality dominance. Monitor FDA breakthrough therapy designation grant rates as the critical inflection signal for pipeline valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Therapy Designation | Compresses phase transitions for novel immunotherapy candidates at the NCI Neuro-Oncology Branch. |
| EMA PRIME Eligibility Pursuit | Accelerates scientific advice access for Heidelberg and Munich academic hospital networks. |
| Device-Pharma Convergence Partnership | Enables localized drug deposition through catheter-based systems bypassing blood-brain barrier limitations. |
| Biomarker-Driven Stratification Investment | Extends diagnostic-to-therapeutic control via EGFR amplification and MGMT methylation testing infrastructure. |
| Japan Sakigake Pathway Navigation | Secures priority review access to Tokyo and Osaka academic centers with distinct reimbursement categories. |
Methodological Framework
Independent corroboration across neuro-oncology clinicians, regulatory affairs leads at pharmaceutical developers, hospital procurement managers at academic medical centers, and payer access specialists underwrites the qualitative findings. Primary interviews with formulary directors and GPO contracts managers combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up patient-volume modeling and top-down pharmaceutical revenue triangulation anchored segmentation estimates.
Rate-of-change decomposition across treatment modality adoption curves, regulatory pathway velocity, and reimbursement policy shifts structured the analytical framework. Segmentation dimensions modeled include treatment line, administration route, molecular stratification biomarker status, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to diagnosed incident population projections and therapy penetration assumptions. Forecast inputs incorporated WHO CNS tumor classification updates and pseudoprogression assessment protocol evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA breakthrough therapy designation grant rate volatility, blood-brain barrier penetration technology disruption, and neuro-oncology specialist workforce expansion constraints. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Global Metastatic Melanoma Drugs Market
Oncology
Metastatic Melanoma Market
Oncology
Peritoneal Cancer Treatment Market
Oncology
US Radiation Oncology Market
Oncology
Pancreatic Cancer Therapeutics Market
Oncology
Europe Tumor Ablation Market
Oncology
Global Oncology Clinical Trials Market
Oncology
Glottic Cancer Treatment Market
Oncology
Thymus Cancer Market
Oncology
Triple-Negative Breast Cancer Market
Oncology
Head and Neck Cancer Drugs Market
Oncology
Immuno-Oncology Market
Oncology
Oncology Market
Oncology
Esophageal Cancer Drugs Market
Oncology
Gynecological Cancer Drugs Market
Oncology
Internal Radiation Therapy Market