
 Hyper Personalized Medicine Market | 2026-2036
Hyper Personalized Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Hyper Personalized Medicine Market Foresight
Market Context
Oncology is consolidating its position as the dominant demand vertical for hyper personalized medicine, displacing traditional one-size-fits-all chemotherapy protocols across major health systems. Illumina, Inc. leverages its installed base of sequencing platforms to anchor clinical genomics workflows in tertiary care centers. Roche Diagnostics competes through integrated diagnostic-drug development partnerships that span companion testing and targeted therapeutic monitoring. Exact Sciences Corporation specializes in liquid biopsy applications, extending its commercial footprint beyond colorectal screening into pan-cancer surveillance protocols.
Technical Definition and Segment Structure
Hyper personalized medicine denotes the tailoring of therapeutic interventions to individual patient profiles through genomic, proteomic, and metabolomic characterization, typically requiring next-generation sequencing with read depths exceeding 100x coverage and bioinformatics pipelines that filter variants against population allele frequencies below one percent. Its primary commercial purpose is to improve therapeutic response rates while reducing adverse drug events through predictive biomarker stratification. Genetic testing occupies the largest revenue pool among product types, though CRISPR-based technologies are capturing disproportionate R&D investment as manufacturing scales mature. Hospital end users dominate current procurement volumes, while pharmaceutical companies represent the fastest-growing customer segment as they internalize companion diagnostic capabilities.
Regulatory Framework and Outlook
FDA oversight of companion diagnostics through its In Vitro Diagnostics Program, combined with EMA's biomarker qualification pathways and Japan PMDA's Sakigake designation for regenerative medicines, creates a multi-jurisdictional compliance architecture that shapes product development timelines. These frameworks mandate co-development evidence standards that link diagnostic accuracy claims to specific therapeutic indications, effectively raising barriers for unvalidated testing platforms. Stakeholders must monitor evolving reimbursement policies for pharmacogenomic testing, as coverage determinations by CMS and analogous bodies will determine whether personalized protocols achieve sustainable adoption outside academic settings.
Market Dynamics
Companion diagnostic mandates from the FDA are forcing pharmaceutical developers to internalize genomic testing capabilities, collapsing the traditional separation between drug development and diagnostic validation workflows.
Growth Catalysts
- Companion Diagnostic Mandates:FDA In Vitro Diagnostics Program requirements now link therapeutic approvals to validated biomarker tests, compelling drug sponsors to build parallel diagnostic pipelines.
- Pharmacogenomics Infrastructure:Academic medical centers in the United States are embedding sequencing platforms directly into clinical workflows, creating institutional demand for integrated testing-therapy protocols.
- Liquid Biopsy Maturation:Cell-free DNA extraction technologies are expanding surveillance applications beyond tissue-based sampling, opening longitudinal monitoring for minimal residual disease.
Market Restraints
- Sequencing Reagent Concentration:Supply of high-fidelity polymerases and flow cell chemistries concentrates among three specialized chemical manufacturers, creating input vulnerability.
- Bioinformatics Bottleneck:Variant interpretation pipelines require rare dual expertise in clinical genomics and computational biology, constraining deployment velocity.
- Reimbursement Uncertainty:CMS coverage determinations for pharmacogenomic testing remain inconsistent across Medicare Administrative Contractors, fragmenting payment pathways.
Strategic Opportunities
- Pediatric Oncology Expansion:Germline sequencing for rare pediatric cancers represents underpenetrated clinical territory with high unmet need and favorable regulatory pathways.
- Multi-Omics Convergence:Integration of proteomic mass spectrometry with genomic sequencing is creating composite biomarker signatures with superior predictive accuracy.
- Direct-to-Consumer Channel:Pharmacogenomic testing bypassing traditional healthcare intermediaries is capturing wellness-oriented consumers seeking medication optimization guidance.
Industry Challenges
- Variant Classification Disputes:Interpretation of variants of uncertain significance generates inter-laboratory discordance, undermining clinical confidence in test results.
- Electronic Health Record Integration:Genomic data formats lack standardization across Epic, Cerner, and Meditech systems, forcing costly custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyper Personalized Medicine Market |
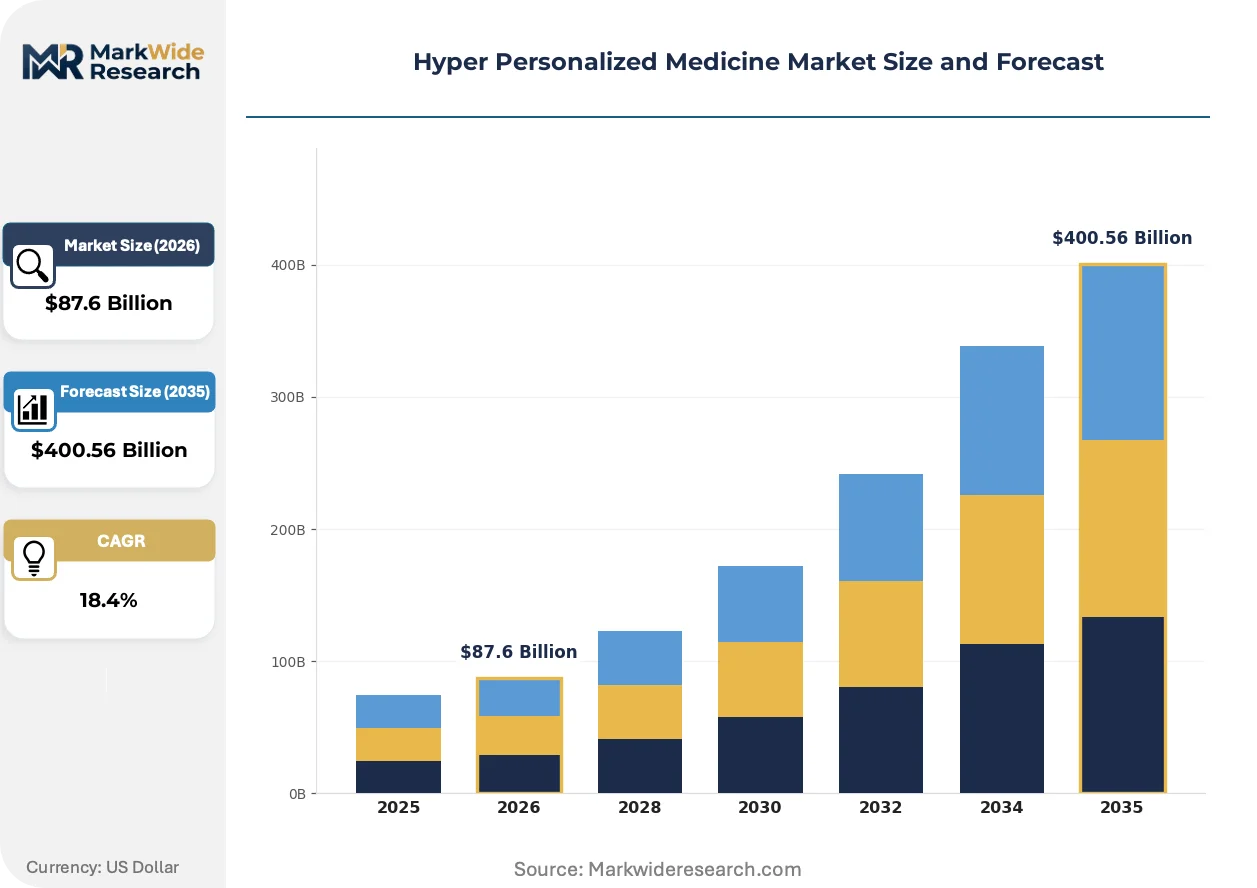
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $400.56 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Genetic Testing, Biomarkers, Personalized Drugs, Companion Diagnostics Delivery Mode: Injectables, Oral, Infusions, Topical Technology: Nucleic Acid Technology, Bioinformatics, CRISPR, Targeted Therapy End User: Pharmaceutical Companies, Research Institutions, Hospitals, Clinics |
| Companies Covered | Illumina, Inc., QIAGEN, Roche Diagnostics, Novartis, AstraZeneca PLC, Exact Sciences Corporation, Abbott, GE Healthcare, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyper Personalized Medicine Market Shifts & Advancements
Next-generation sequencing workflows are compressing turnaround times from weeks to days, enabling real-time treatment decisions that were previously impossible in acute oncology settings.
CRISPR-based diagnostic platforms are consolidating point-of-care testing capabilities into single-instrument formats previously requiring centralized laboratory infrastructure. Community oncology practices in the United States are adopting these systems to retain patients who would otherwise transfer to academic centers for molecular profiling. The technology is consolidating the historical separation between community and tertiary care access to genomic testing.
EMA biomarker qualification pathways are streamlining co-development evidence standards across European member states, reducing redundant regulatory submissions for companion diagnostics. Pharmaceutical sponsors now submit unified dossiers covering multiple jurisdictions rather than sequential national approvals. Oncology therapeutic areas with high biomarker prevalence are reorganizing development timelines around these harmonized requirements.
Hospital procurement committees are consolidating vendor relationships around integrated platform providers capable of delivering sequencing, interpretation, and clinical decision support through unified contracts. Independent laboratory service providers are losing share to vertically integrated health systems building captive pharmacogenomics capabilities. This concentration is most visible in United States integrated delivery networks with employed physician models and centralized capital allocation authority.
Hyper Personalized Medicine Market Segmentation
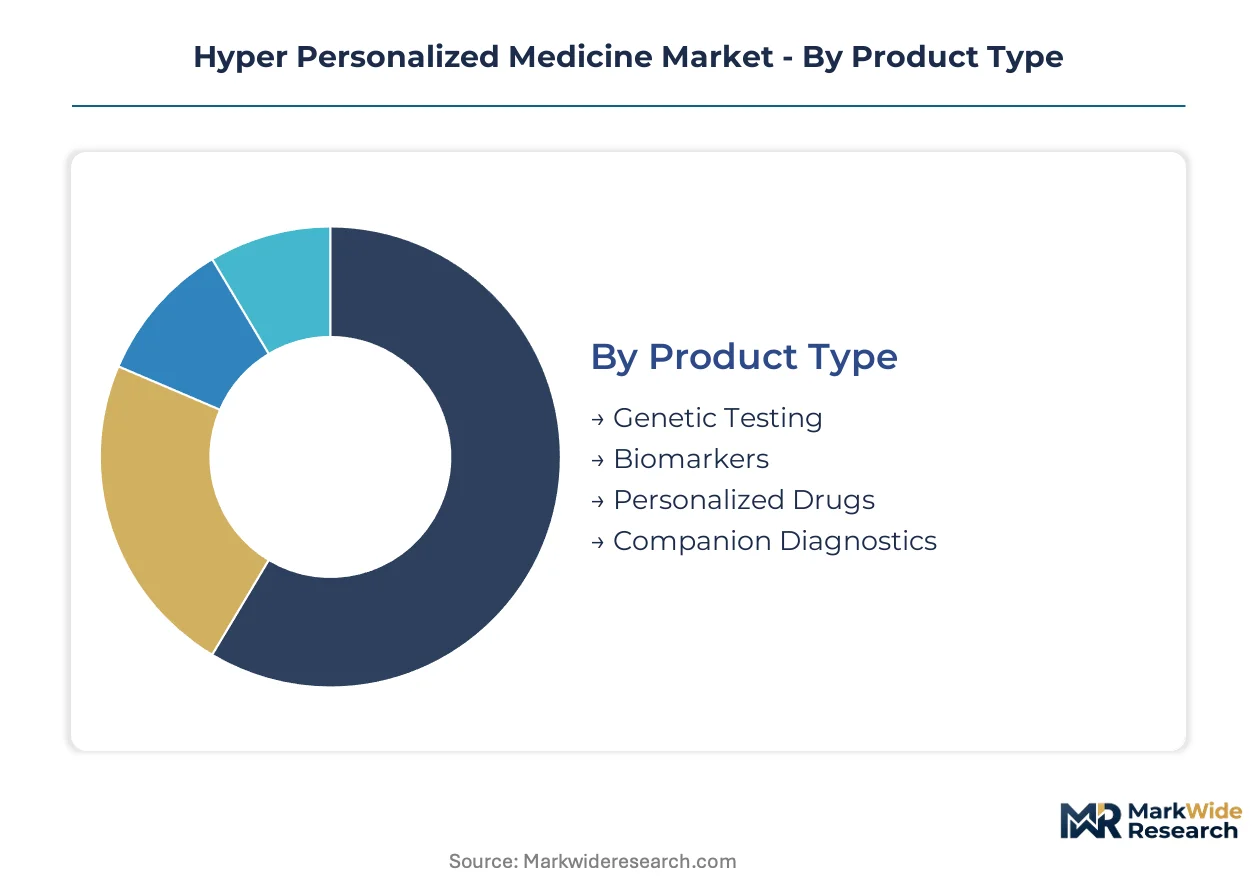
Hyper personalized medicine requires precise segmentation to capture how genomic technologies, therapeutic delivery systems, and institutional capabilities intersect. Each category reveals distinct procurement patterns and technology adoption curves that shape vendor strategies and investment priorities.
Product Type:
Genetic testing platforms anchor revenue concentration through their position as the gateway technology for all subsequent therapeutic decisions.
- Genetic Testing:Next-generation sequencing workflows with read depths exceeding 100x coverage enable variant detection against population allele frequencies below one percent. Demand concentrates in United States academic medical centers building in-house pharmacogenomics programs to retain oncology patients and capture companion diagnostic revenue streams.
- Biomarkers:Predictive protein and metabolite signatures stratify patient populations for targeted therapeutic response. Pharmaceutical developers in the United States are internalizing biomarker discovery capabilities to satisfy FDA co-development evidence standards linking diagnostic accuracy to specific therapeutic indications.
- Personalized Drugs:Patient-specific therapeutic formulations manufactured through adaptive clinical trial protocols.
- Companion Diagnostics:Co-validated testing platforms mandated by regulatory frameworks for targeted therapy approval.
Mature deployment sits with Genetic Testing. Newer deployment is concentrated in Companion Diagnostics.
Delivery Mode:
Route of administration determines manufacturing complexity, cold chain requirements, and site-of-care economics for personalized therapeutics.
- Injectables:Subcutaneous and intramuscular formulations of biologics requiring aseptic fill-finish capabilities and temperature-controlled distribution. United States hospital networks with centralized pharmacy operations are consolidating injectable procurement around integrated platform vendors capable of delivering sequencing interpretation and clinical decision support through unified contracts.
- Oral:Small-molecule targeted therapies with pharmacogenomic dosing algorithms. Community oncology practices across the United States are adopting oral personalized drugs to retain patients who would otherwise transfer to academic centers for molecular profiling and infusion-based protocols.
- Infusions:Intravenous biologics administered in supervised clinical settings with real-time genomic monitoring.
- Topical:Patient-specific dermatological and localized delivery formulations with minimal systemic exposure.
Infusions dominate current procurement volumes. Oral formulations are expanding most quickly through community practice adoption.
Technology:
Core technology platforms differentiate competitive positioning through intellectual property estates and regulatory validation status.
- Nucleic Acid Technology:Polymerase chain reaction and hybridization-based detection systems for known variant interrogation. United States integrated delivery networks with employed physician models are standardizing on nucleic acid platforms from established sequencing vendors to minimize reagent supply concentration risk among specialized chemical manufacturers.
- Bioinformatics:Variant interpretation pipelines requiring dual expertise in clinical genomics and computational biology. The bioinformatics bottleneck constrains deployment velocity as academic medical centers compete for rare talent capable of filtering variants against clinical databases and population frequency references.
- CRISPR:Gene editing platforms capturing disproportionate R&D investment as manufacturing scales mature.
- Targeted Therapy:Molecularly guided treatment protocols matched to individual tumor profiles.
Nucleic Acid Technology underpins current clinical workflows. CRISPR-based applications are gaining share fastest through point-of-care diagnostic consolidation.
End User:
Customer type determines contract structure, capital allocation authority, and integration complexity for personalized medicine vendors.
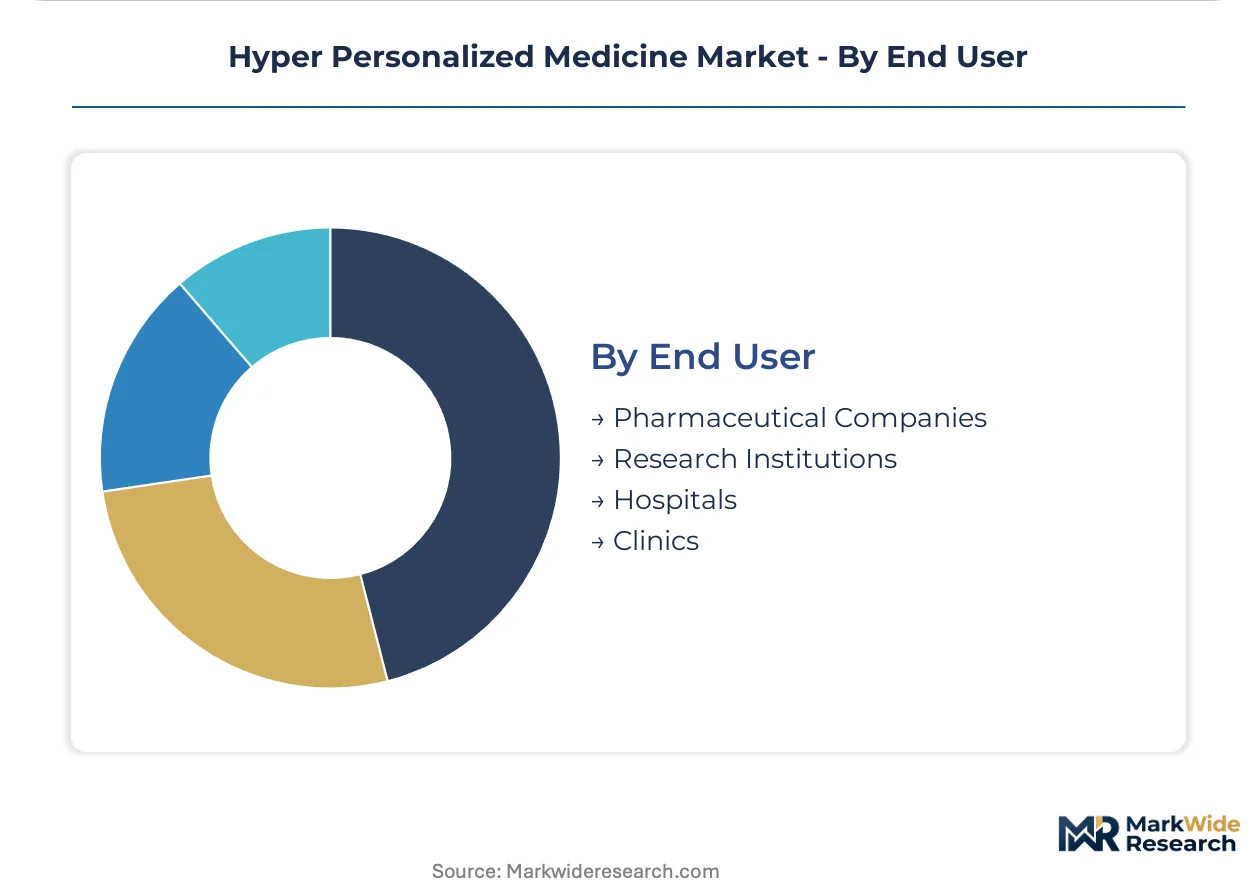
- Pharmaceutical Companies:Drug sponsors building parallel diagnostic pipelines to satisfy FDA In Vitro Diagnostics Program requirements linking therapeutic approvals to validated biomarker tests. These organizations represent the steepest expansion trajectory as they internalize companion diagnostic capabilities previously outsourced to independent laboratory service providers.
- Hospitals:Tertiary care centers and community networks embedding sequencing platforms into clinical workflows. United States hospital procurement committees are consolidating vendor relationships around integrated platform providers capable of delivering sequencing, interpretation, and clinical decision support through unified contracts.
- Research Institutions:Academic centers conducting germline sequencing for rare pediatric cancers with favorable regulatory pathways.
- Clinics:Outpatient facilities adopting liquid biopsy and pharmacogenomic testing for longitudinal patient monitoring.
Hospitals anchor current procurement volumes. Pharmaceutical companies are climbing the fastest as regulatory mandates force diagnostic internalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized economic zones for biotechnology in Research Triangle Park and the Greater Boston area concentrate pharmacogenomics infrastructure and venture deployment for precision therapeutics.
United States
FDA breakthrough therapy designations and companion diagnostic mandates accelerate co-development timelines between drug sponsors and testing manufacturers. Academic medical centers in Massachusetts and California embed sequencing platforms directly into oncology workflows. The Research Triangle Park cluster in North Carolina anchors contract research organizations supporting pharmacogenomic clinical trials.
Germany
EMA biomarker qualification pathways streamline pan-European approval processes for companion diagnostics developed in Baden-Württemberg pharmaceutical corridors. The country's national pharmaceutical regulator enforces co-validation standards linking diagnostic accuracy to therapeutic indications. Munich and Heidelberg host integrated diagnostics-therapeutics development hubs serving EU member states.
Switzerland
Basel-region pharmaceutical headquarters internalize genomic testing capabilities to satisfy multi-jurisdictional regulatory requirements. Swissmedic maintains stringent validation protocols for personalized therapeutic monitoring devices. The Lake Geneva biotech corridor concentrates proteomic mass spectrometry specialists supporting multi-omics convergence.
Japan
PMDA's Sakigake designation for regenerative medicines creates accelerated pathways for CRISPR-based therapeutic platforms. Tokyo academic hospitals deploy liquid biopsy surveillance for minimal residual disease monitoring. The Kansai region's medical device manufacturing base supplies point-of-care genomic instrumentation.
United Kingdom
NHS England's genomic medicine service mandates standardized variant interpretation pipelines across regional sequencing hubs. The Medicines and Healthcare products Regulatory Agency aligns companion diagnostic approvals with EMA qualification pathways. London's Francis Crick Institute anchors public-private consortia for pediatric oncology germline sequencing.
Hyper Personalized Medicine Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors capturing hospital procurement committees and independent laboratories losing ground to captive health system capabilities. The vendor base concentrates around three strategic tiers: sequencing instrument incumbents with installed base advantages, pharmaceutical developers internalizing diagnostic pipelines, and emerging point-of-care specialists consolidating community oncology access. Dominant competitive moves include backward integration into reagent manufacturing and strategic partnerships spanning companion test co-development.
Among United States-based sequencing specialists, Illumina, Inc. and Exact Sciences Corporation exemplify contrasting archetypes within the precision medicine ecosystem. Swiss-German pharmaceutical-diagnostics conglomerates Roche Diagnostics and Novartis occupy positions spanning therapeutic development and validated testing platforms. QIAGEN represents the sample preparation and bioinformatics tier supporting laboratory workflow standardization.
| Leading Market Players |
|---|
| Illumina, Inc. |
| QIAGEN |
| Roche Diagnostics |
| Novartis |
| AstraZeneca PLC |
| Exact Sciences Corporation |
| Abbott |
| GE Healthcare |
| Danaher Corporation |
| Others |
Supply & Pricing Matrix
Polymerase reagent spot pricing indices cascade through sequencing platform procurement contracts into three-tier pricing structures across premium, standard, and economy levels, with United States academic medical centers absorbing upstream volatility through multi-year reagent offtake agreements while community oncology practices face spot-market exposure.
Pricing Analysis
Short lead-time premiums of 15-20% apply to emergency genomic profiling orders from hospital networks facing companion diagnostic deadlines, while spot inventory discounts attract price-sensitive community clinics with flexible turnaround requirements. Pricing stratifies across premium, standard, and economy tiers based on bioinformatics interpretation depth and FDA validation status. Cost compression in economy-tier testing is intensifying because independent laboratories compete for shrinking health system outsourcing volumes. Pharmaceutical sponsors exhibit lowest price sensitivity due to co-development mandate compliance requirements, while community oncology practices demonstrate highest elasticity.
Supply Chain Analysis
Direct-to-hospital channels handle hyperscale demand from integrated delivery networks consolidating vendor relationships, while specialty distributors serve fragmented community clinic procurement. Supply concentrates among three chemical manufacturers in the United States, Germany, and Japan producing high-fidelity polymerases and flow cell chemistries. The network draws from rare earth mineral deposits for sequencing instrument components, synthetic oligonucleotide foundries, and specialized cold-chain logistics providers. Single-source vulnerability in flow cell chemistry creates systemic exposure. Distribution runs through regional laboratory supply cooperatives and direct manufacturer agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hyper personalized medicine sits at a technology-transition inflection where next-generation sequencing workflows displace older hybridization-based diagnostic platforms, compressing turnaround times from weeks to days and reorganizing procurement priorities around real-time clinical decision support.
For Market Incumbents: Hedge installed base erosion by embedding CRISPR-based point-of-care platforms into community oncology workflows before emerging specialists capture that channel. Secure backward integration into reagent manufacturing to reduce exposure to the three-supplier concentration in polymerase supply. Prioritize FDA co-validation partnerships with pharmaceutical sponsors facing In Vitro Diagnostics Program mandates.
For New Entrants and Emerging Players: Telehealth-integrated pharmacogenomic counseling represents the most penetrable route into direct-to-consumer channels bypassing traditional healthcare intermediaries. Target pediatric oncology germline sequencing where regulatory pathways favor novel entrants and academic medical centers seek external partnerships. Deploy subscription-based bioinformatics interpretation services to overcome the talent bottleneck constraining hospital deployment velocity.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap sequencing service providers in the United Kingdom facing NHS England procurement consolidation pressure. Long-term viability hinges on multi-omics convergence capabilities spanning genomic, proteomic, and metabolomic platforms. Watch EMA biomarker qualification pathway harmonization progress as the inflection signal for pan-European companion diagnostic consolidation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development Partnership | FDA In Vitro Diagnostics Program mandates link therapeutic approvals to validated biomarker tests, forcing parallel pipeline construction. |
| Multi-Omics Platform Integration | Swiss proteomic mass spectrometry specialists converge with genomic sequencing to create composite biomarker signatures. |
| Point-of-Care CRISPR Instrument Launch | Community oncology practices in the United States adopt single-instrument formats to retain patients transferring to academic centers. |
| Pharmacogenomic Reimbursement Strategy | CMS coverage determination alignment determines sustainable adoption outside academic medical center settings. |
| Pediatric Oncology Germline Sequencing Expansion | London's Francis Crick Institute anchors public-private consortia for rare cancer applications with favorable regulatory pathways. |
Research Methodology
FDA 510(k) clearance databases, EMA biomarker qualification pathway submissions, and ClinicalTrials.gov protocol registries formed the secondary backbone for this analysis, cross-referenced with CMS Medicare reimbursement determinations and hospital procurement database extracts. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists validated secondary findings and informed segmentation assumptions. Bottom-up patient population modeling and top-down pharmaceutical R&D expenditure triangulation anchored market sizing across the analysis window.
Historical trendline analysis of sequencing platform installed bases, companion diagnostic approval velocities, and pharmacogenomic test reimbursement rates informed projection frameworks. Segmentation dimensions modeled include product type, delivery mode, core technology platform, and end-user archetype, with regional regulatory cluster differentiation applied throughout the forecast period. CAGRs were derived from fitted growth curves adjusted for technology adoption S-cycles and regulatory milestone impacts.
The model holds under stable FDA-EMA regulatory alignment and continued CMS pharmacogenomic coverage expansion; deviation in reimbursement policy fragmentation or reagent supply disruption would shift trajectory. Forecasts reflect documented assumptions regarding technology maturation timelines and clinical adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Dural Graft Market
Regenerative Medicine
Autologous Fat Grafting Market
Regenerative Medicine
Hypertrophic and Keloid Scar Treatment Market
Regenerative Medicine
Th17 Driven Disease Treatment Market
Regenerative Medicine
Longevity and Anti-Senescence Therapy for Cancer Market
Regenerative Medicine
Europe Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Autologous Matrix Induced Chondrogenesis Market
Regenerative Medicine
Artificial Blood Market
Regenerative Medicine
Tooth Regeneration Market
Regenerative Medicine
Orthopedic Regenerative Medicine Market
Regenerative Medicine
Personalized Immunotherapy Market
Regenerative Medicine
Global Cartilage Repair-Cartilage Regeneration Market
Regenerative Medicine
Asia Pacific Platelet Rich Plasma Market
Regenerative Medicine
Global Orthopedic Regenerative Surgical Products Market
Regenerative Medicine
Stromal Vascular Fraction Market
Regenerative Medicine
Cartilage Degeneration Market