
 Metastatic Melanoma Market | 2026-2036
Metastatic Melanoma Market Size, Share, and Industry Trends Forecast 2026-2036
Metastatic Melanoma Market Outlook
Oncology-trained immuno-oncology specialists is bifurcating the competitive landscape into those with deep cellular therapy expertise and legacy chemotherapeutic portfolios. Bristol-Myers Squibb Company leverages its checkpoint inhibitor infrastructure to sustain leadership in combination regimens. Merck & Co. Inc. anchors its position through broad PD-1 program investments across multiple melanoma lines. Novartis AG competes via differentiated T-cell therapy manufacturing capabilities that extend into personalized medicine platforms.
Metastatic melanoma represents a stage IV cutaneous malignancy characterized by distant organ dissemination, typically requiring systemic intervention with BRAF/MEK inhibitors or anti-PD-1/anti-CTLA-4 monoclonal antibodies. Immunotherapy dominates current treatment paradigms due to durable response profiles in checkpoint-naive populations, while targeted therapy occupies a defined role in BRAF V600-mutant subsets where rapid cytoreduction is clinically indicated. Intravenous administration leads among routes due to established infusion protocols for biologics, though subcutaneous formulations are gaining traction in outpatient settings seeking reduced chair time.
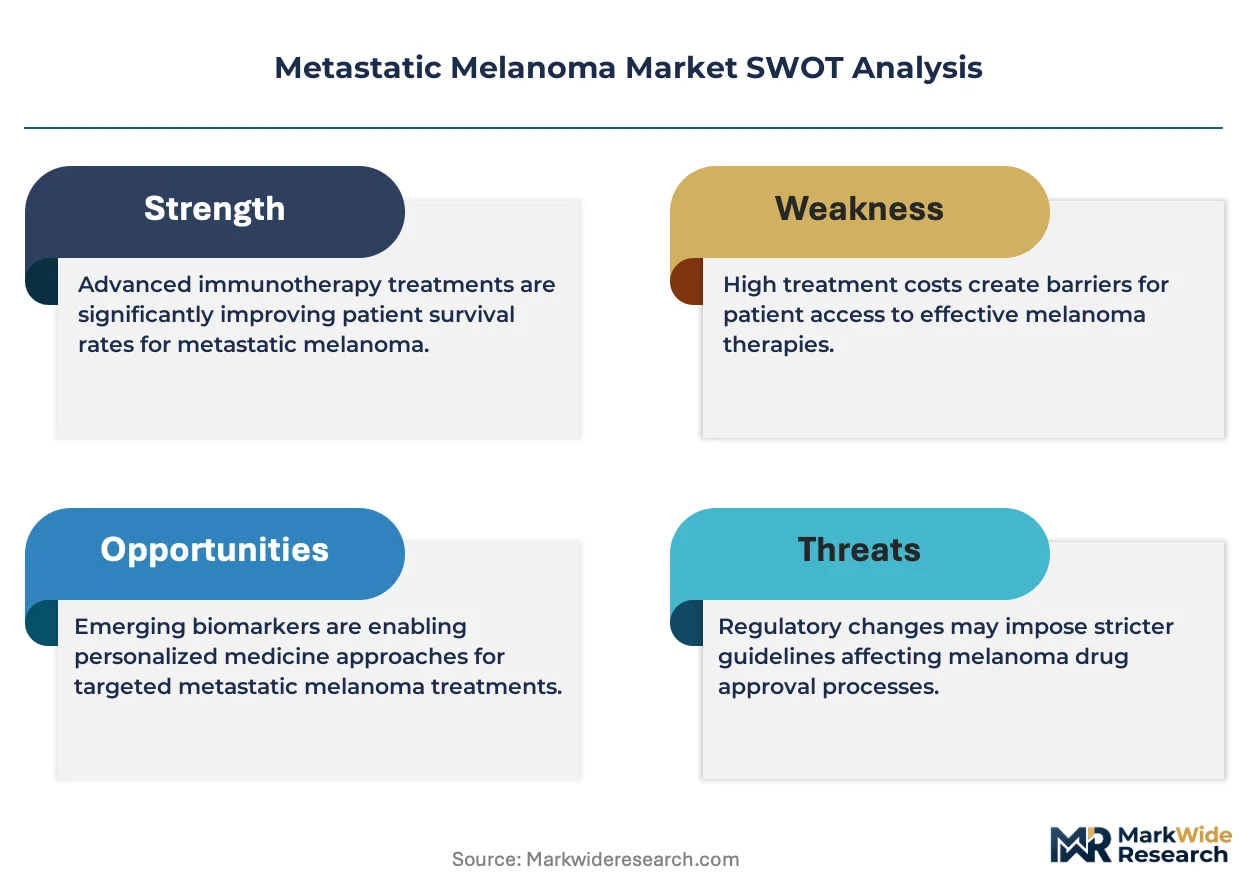
FDA breakthrough therapy designation and EMA PRIME eligibility are reshaping development economics by truncating Phase II-to-approval intervals for novel agents. The EU AI Act introduces algorithmic scrutiny for diagnostic tools supporting treatment selection, while HIPAA governs real-world evidence collection infrastructure in US oncology networks. Stakeholders must monitor evolving HTA body positioning on combination pricing versus monotherapy benchmarks across European markets.
Market Dynamics
FDA breakthrough therapy designation and EMA PRIME eligibility are compressing Phase II-to-approval intervals, fundamentally restructuring development economics for novel immuno-oncology agents. This regulatory acceleration is pulling capital toward combination regimen platforms and cellular therapy manufacturing capabilities.
Growth Catalysts
- Accelerated Approval Pathways:FDA breakthrough therapy designation truncates clinical trial timelines for checkpoint inhibitor combinations. Developers now prioritize registrational studies in treatment-naive populations.
- Reimbursement Favorability:United States Medicare and Germany's G-BA have established premium pricing frameworks for BRAF/MEK inhibitor sequences. Payers recognize durable survival benefits in Stage IV populations.
- Cellular Therapy Infrastructure:TIL and T-cell receptor platforms require specialized manufacturing facilities. Investment in closed-system bioreactors is expanding production capacity for personalized melanoma vaccines.
Market Restraints
- Input Cost Concentration:GMP-grade cytokines and viral vectors for CAR-T production concentrate among three dominant suppliers. Price volatility in IL-2 and IL-7 reagents compresses gross margins for cell therapy developers.
- Technical Limitation:Solid tumor microenvironment immunosuppression limits T-cell infiltration in liver and brain metastases. Response rates in these anatomical subsets lag nodal and pulmonary disease by substantial margins.
- Regulatory Friction:EU AI Act introduces algorithmic scrutiny for diagnostic tools supporting treatment selection. Computational pathology platforms face extended validation requirements before clinical deployment.
Strategic Opportunities
- Underpenetrated Geography:Japan's PMDA has streamlined approval for PD-1/CTLA-4 combinations, yet prescribing penetration in regional oncology centers remains below tertiary hospital benchmarks. Field medical investment can capture this gap.
- Technology Convergence:Integration of liquid biopsy ctDNA monitoring with radiographic response assessment enables adaptive therapy protocols. Real-time clonal evolution tracking supports treatment switching decisions.
- Channel Innovation:Subcutaneous checkpoint inhibitor formulations are displacing intravenous infusion in German ambulatory oncology networks. Reduced chair time aligns with outpatient cost-containment mandates.
Industry Challenges
- Specialized Manufacturing Talent:GMP-compliant cell therapy production requires operators trained in aseptic processing and closed-system automation. Workforce scarcity constrains capacity expansion at CDMO facilities.
- Combination Trial Complexity:Three-drug regimens involving checkpoint inhibitors, targeted agents, and oncolytic viruses generate overlapping toxicities. Dose-finding studies require larger patient cohorts and extended safety monitoring periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metastatic Melanoma Market |
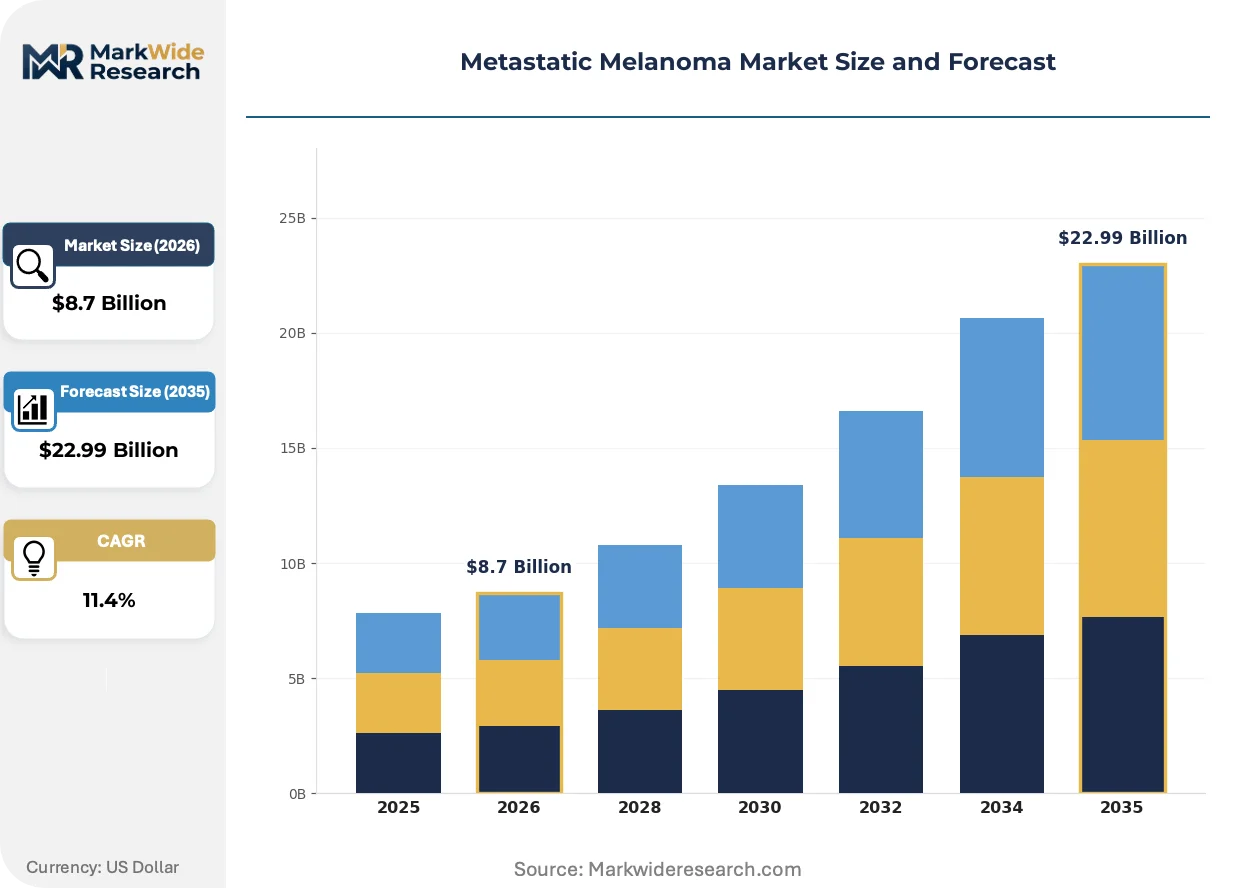
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunotherapy, Targeted Therapy, Chemotherapy, Radiation Therapy Treatment Stage: Adjuvant Therapy, Neoadjuvant Therapy, Metastatic Therapy, Maintenance Therapy Administration Route: Intravenous, Subcutaneous, Oral, Topical End User: Hospitals, Clinics, Homecare, Research Laboratories |
| Companies Covered | Novartis AG, AstraZeneca PLC, Bristol-Myers Squibb Company, Regeneron Pharmaceuticals Inc., Amgen Inc., Merck & Co. Inc., Pfizer Inc., Immunocore Holdings plc, F. Hoffmann-La Roche AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metastatic Melanoma Market Strategic Shifts
Neoadjuvant immunotherapy protocols are reshaping surgical oncology practice patterns, compressing the window between diagnosis and definitive resection. These shifts demand coordinated investment in biomarker infrastructure and multidisciplinary care pathways.
Bispecific T-cell engagers targeting gp100 and MART-1 melanoma-associated antigens are displacing single-agent checkpoint inhibition in BRAF wild-type populations. Academic medical centers in the United States and Germany are enrolling patients into Phase I/II studies at accelerated rates. This modality is displacing salvage chemotherapy in the third-line setting, forcing portfolio reallocation among developers with legacy cytotoxic assets.
EMA's PRIME eligibility criteria now explicitly reward novel biomarker-stratified trial designs, compressing scientific advice timelines for companion diagnostic submissions. Manufacturers must demonstrate analytical validity for predictive signatures prior to pivotal study initiation. BRAF V600 mutation testing platforms in European reference laboratories are expanding throughput to match enrollment velocity.
Oncology networks in the United States are unbundling infusion administration from drug acquisition, creating separate contracting streams for chair time and pharmaceutical margin. Community practices in Texas and Florida are consolidating into multi-site entities to negotiate preferred rates with commercial payers. This procurement restructuring concentrates purchasing authority among fewer decision-makers, intensifying price competition for commoditized biologics.
Metastatic Melanoma Market Segmentation
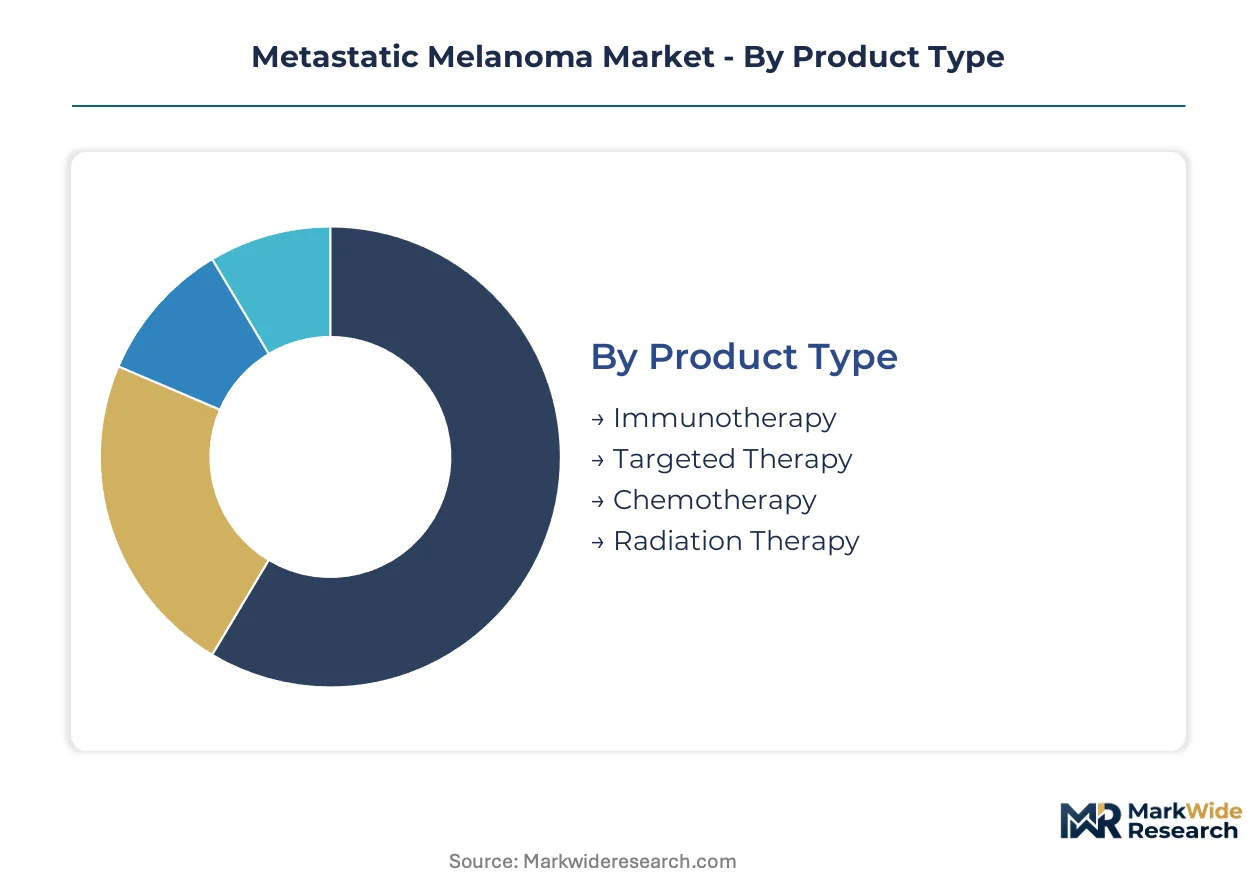
Segmentation in metastatic melanoma reveals how treatment economics bifurcate between premium biologics and commoditized modalities. Understanding these divides enables targeted portfolio positioning across reimbursement tiers and care settings.
Product Type:
Margins concentrate in immunotherapy and targeted therapy segments where patent protection sustains premium pricing against generic pressure.
- Immunotherapy:Checkpoint inhibitors and T-cell therapies command the highest reimbursement rates due to durable survival benefits. Demand clusters in tertiary oncology centers across the United States, Germany, and Japan where multidisciplinary tumor boards guide treatment selection. Manufacturing complexity and cold-chain logistics create natural barriers to biosimilar entry.
- Targeted Therapy:BRAF/MEK inhibitor combinations deliver rapid cytoreduction in V600-mutant populations. Prescribing concentrates in academic medical centers with molecular diagnostic capabilities. Resistance mechanisms limit duration of response, creating sequential therapy opportunities.
- Chemotherapy:Dacarbazine and temozolomide occupy salvage settings after immunotherapy failure. Pricing pressure from generic competition compresses margins.
- Radiation Therapy:Stereotactic body radiation addresses oligometastatic disease and symptomatic lesions. Utilization varies by regional reimbursement for palliative indications.
Immunotherapy holds installed capacity. Targeted therapy is rotating up the share rankings.
Treatment Stage:
Volume distribution tracks disease progression patterns, with metastatic therapy representing the commercial anchor and neoadjuvant protocols emerging as the expansion frontier.
- Adjuvant Therapy:Post-surgical immunotherapy reduces recurrence risk in high-risk Stage III disease. Penetration depends on lymph node staging completeness and molecular risk stratification.
- Neoadjuvant Therapy:Pre-operative checkpoint inhibition enables pathologic response assessment and organ preservation. Academic centers in the United States and Germany are expanding protocol adoption. Pathologic complete response rates inform subsequent treatment de-escalation decisions.
- Metastatic Therapy:First-line combination immunotherapy anchors the revenue base. Treatment-naive populations demonstrate superior response durability versus subsequent lines.
- Maintenance Therapy:Extended anti-PD-1 dosing maintains remission in responders. Duration protocols vary by payer policy and toxicity tolerance.
Metastatic therapy commands current volume leadership. Neoadjuvant therapy is climbing the fastest as surgical oncology protocols evolve.
Administration Route:
Cost structures diverge between infusion-based delivery requiring facility overhead and self-administered oral regimens shifting economic value toward pharmacy benefit managers.
- Intravenous:Infusion protocols for checkpoint inhibitors dominate biologic delivery. Chair time and nursing labor concentrate revenue in hospital outpatient departments.
- Subcutaneous:Self-administered formulations reduce facility dependency and enable home-based care. German ambulatory networks are adopting subcutaneous anti-PD-1 alternatives to compress site-of-service costs.
- Oral:BRAF/MEK inhibitors enable patient-managed dosing with periodic monitoring. Adherence programs and specialty pharmacy integration determine real-world effectiveness.
- Topical:Limited to superficial cutaneous metastases and palliative wound care. Utilization concentrates in dermatology and wound clinic settings.
Intravenous holds installed capacity. Subcutaneous is rotating up the share rankings.
End User:
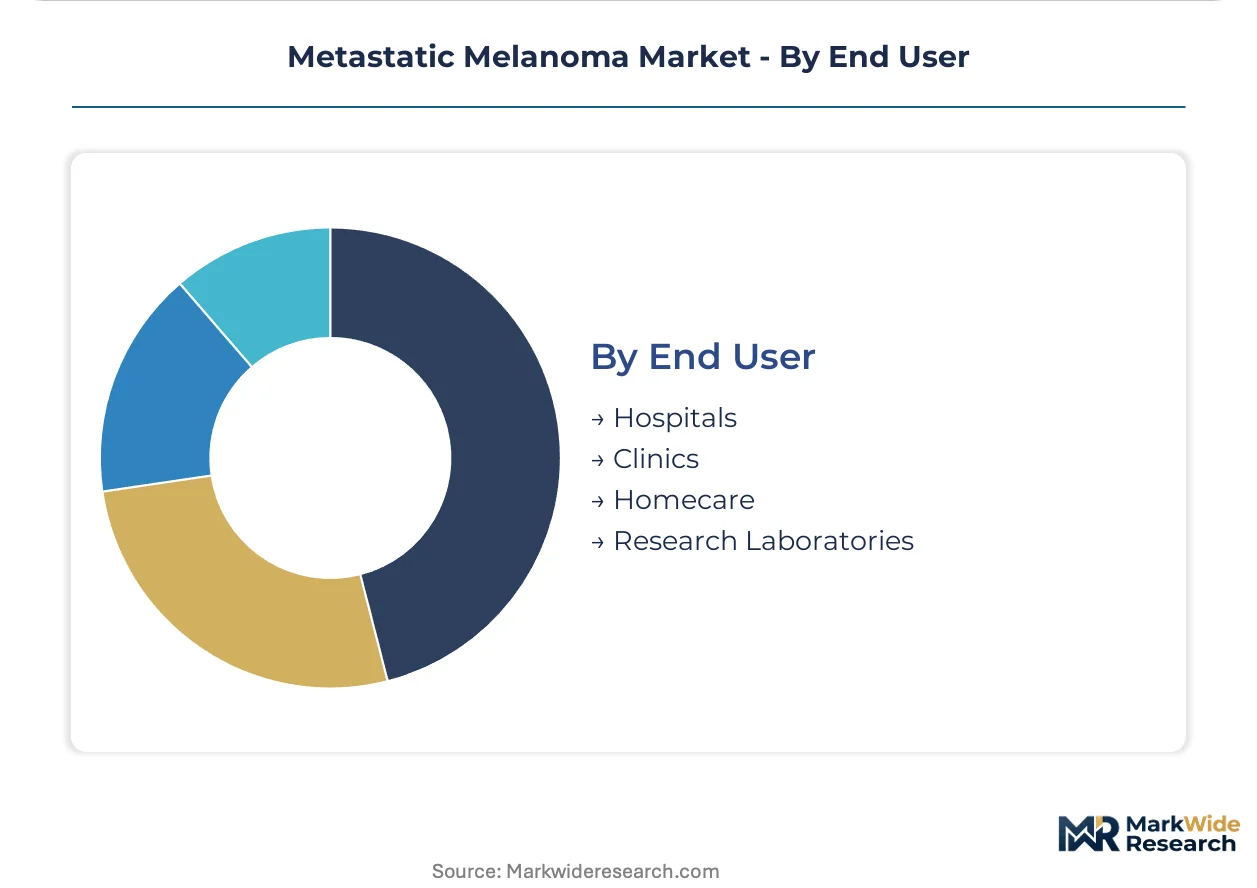
Purchasing authority concentrates in integrated hospital systems with centralized pharmacy and therapeutics committees, while homecare channels fragment decision-making across regional nursing networks.
- Hospitals:Academic medical centers and community hospital systems anchor immunotherapy infusion volume. Formulary placement depends on contract positioning with group purchasing organizations.
- Clinics:Community oncology practices handle stable patients on oral targeted therapy. Consolidation into multi-site entities in Texas and Florida is concentrating procurement leverage.
- Homecare:Subcutaneous administration and oral regimens shift care delivery outside facilities. Nursing networks manage injection training and adverse event triage.
- Research Laboratories:Biomarker testing and clinical trial operations support precision medicine adoption. Companion diagnostic partnerships link test availability to therapy access.
Hospitals hold installed capacity. Homecare is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds German benchmarks by substantial margins, while Japanese reimbursement velocity lags both markets. Oncology networks in these three countries anchor the majority of metastatic melanoma treatment volume. Regulatory pathway efficiency and companion diagnostic infrastructure determine regional competitive positioning.
United States
Medicare's premium pricing frameworks for checkpoint inhibitor combinations attract developer investment toward first-line registrational studies. FDA breakthrough therapy designation compresses Phase II-to-approval intervals below European timelines. Memorial Sloan Kettering Cancer Center and MD Anderson anchor clinical trial enrollment velocity in New York City and Houston respectively.
Germany
G-BA early benefit assessments establish reimbursement precedents that ripple through European HTA body positioning. EMA centralized procedures leverage German reference laboratory infrastructure for BRAF V600 companion diagnostic validation. Heidelberg and Munich academic medical centers concentrate neoadjuvant immunotherapy protocol adoption.
Japan
PMDA streamlined approval pathways for PD-1/CTLA-4 combinations have reduced regulatory lag versus historical oncology benchmarks. Regional oncology centers outside Tokyo and Osaka tertiary hospitals show prescribing penetration gaps addressable through field medical investment. National Health Insurance pricing reviews occur biennially, creating timing uncertainty for premium biologic launches.
United Kingdom
NICE technology appraisals impose cost-effectiveness thresholds that filter premium combination regimens from routine commissioning. NHS England's Cancer Drugs Fund provides provisional access pending real-world evidence collection. London's Royal Marsden and Manchester's Christie Hospital anchor molecular diagnostic throughput for stratified medicine programs.
Switzerland
Swissmedic approval timelines track EMA closely while maintaining independent pricing negotiation authority. Cantonal hospital procurement concentrates purchasing leverage in Zurich and Geneva oncology networks. Federal Office of Public Health reimbursement decisions reference German and French HTA outcomes with 6-12 month lag.
Metastatic Melanoma Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the metastatic melanoma market. Checkpoint inhibitor developers with established infusion infrastructure command premium pricing in first-line settings, while targeted therapy specialists compete on cytoreduction velocity in BRAF-mutant subsets. Three archetypes dominate: integrated biopharma conglomerates with cellular therapy manufacturing capabilities, mid-cap immuno-oncology specialists focused on bispecific platforms, and legacy oncology players repositioning cytotoxic portfolios toward combination backbones. Capacity expansion in closed-system bioreactors and strategic partnerships for cytokine supply security represent the dominant competitive moves.
Among integrated biopharma conglomerates, Bristol-Myers Squibb Company and Merck & Co. Inc. occupy positions exemplifying checkpoint inhibitor infrastructure scale, while Novartis AG represents the cellular therapy manufacturing archetype with T-cell platform investments. These three companies anchor distinct competitive vectors: combination regimen leadership, broad PD-1 program depth, and personalized medicine manufacturing capabilities respectively. Their positioning illustrates how oncology-trained specialist workforces bifurcate competitive advantage between cellular therapy expertise and legacy chemotherapeutic portfolios.
| Leading Market Players |
|---|
| Novartis AG |
| AstraZeneca PLC |
| Bristol-Myers Squibb Company |
| Regeneron Pharmaceuticals Inc. |
| Amgen Inc. |
| Merck & Co. Inc. |
| Pfizer Inc. |
| Immunocore Holdings plc |
| F. Hoffmann-La Roche AG |
| Others |
Value Chain & Pricing Dynamics
Subcutaneous checkpoint inhibitor formulations replacing intravenous infusion in German ambulatory networks simultaneously redistributes manufacturing investment toward prefilled syringe capacity and compresses site-of-service reimbursement spreads. This substitution dynamic concentrates pricing power with developers controlling formulation intellectual property while eroding hospital outpatient department margins across European oncology networks.
Pricing Analysis
United States Medicare reimbursement for first-line combination immunotherapy exceeds German G-BA benchmarks by substantial margins, creating geographic arbitrage opportunities for parallel trade scrutiny. Three-tier pricing structure across premium biologics, standard targeted agents, and economy generics dominates the market, with differentiation driven by survival benefit magnitude and companion diagnostic bundling. Pricing pressure stems from biosimilar entry threats in anti-PD-1 categories as patent cliffs approach. Community oncology practices in consolidated Texas and Florida networks demonstrate highest price sensitivity, while academic medical centers with dedicated tumor boards exhibit lowest sensitivity due to protocol-driven formulary placement.
Supply Chain Analysis
GMP-grade cytokine production concentrates among three dominant suppliers in the United States, Switzerland, and Germany, creating single-source vulnerability for IL-2 and IL-7 reagents essential to TIL therapy manufacturing. Viral vector production for CAR-T platforms draws from captive capacity at Novartis AG's Morris Plains facility and contracted CDMO networks across Massachusetts and North Carolina. Tariff exposure on Chinese-sourced cell culture media intensifies input cost volatility for European developers. Distribution runs through cold-chain logistics specialists with validated cryogenic transport capabilities, linking manufacturing sites to hospital outpatient departments and regional infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. FDA breakthrough therapy designation and EMA PRIME eligibility create multi-year approval headstarts that compound competitive advantage through clinical data generation.
For Market Incumbents: Compound checkpoint inhibitor infrastructure advantage through backward integration into cytokine manufacturing and captive T-cell therapy bioreactor capacity. Defend against bispecific T-cell engager displacement by accelerating neoadjuvant protocol adoption in academic medical centers. Priority lever rests on closed-system automation investments that reduce COGS for personalized vaccine platforms. For New Entrants and Emerging Players: Lead with liquid biopsy ctDNA monitoring integration as the wedge into adaptive therapy protocols, targeting regional oncology centers in Japan outside Tokyo and Osaka tertiary footprints where prescribing penetration gaps persist. White-space capture concentrates on subcutaneous formulation development for German ambulatory networks and biomarker-stratified trial designs qualifying for EMA PRIME scientific advice acceleration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed CDMO specialists holding GMP-compliant cell therapy manufacturing capabilities and aseptic processing workforce pipelines. Long-term viability favors platforms with demonstrated pathologic complete response data in neoadjuvant settings and companion diagnostic partnerships locked before pivotal study initiation. Signal to watch is HTA body positioning on combination pricing versus monotherapy benchmarks across European markets, with NICE technology appraisal thresholds as the leading indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Closed-system bioreactor investment at CDMO facilities addresses GMP-compliant cell therapy capacity constraints. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses Phase II-to-approval intervals below standard oncology timelines. |
| Licensing Agreement | Cytokine supply security partnerships insulate developers from IL-2 and IL-7 price volatility among dominant suppliers. |
| Clinical Trial Advancement | Neoadjuvant immunotherapy protocol enrollment at Memorial Sloan Kettering and MD Anderson anchors response durability data. |
| Pipeline Diversification | Bispecific T-cell engager programs targeting gp100 and MART-1 antigens displace salvage chemotherapy in third-line settings. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with immuno-oncology specialists, formulary directors at integrated hospital systems, GMP manufacturing facility managers, and payer access specialists at Medicare and Germany's G-BA. Secondary validation drew from FDA breakthrough therapy designation filings, EMA PRIME eligibility submissions, ClinicalTrials.gov enrollment data, and hospital procurement databases tracking checkpoint inhibitor contract positioning. Bottom-up patient flow modeling and top-down reimbursement framework analysis were triangulated to anchor volume and value estimates.
Across the analysis window, the quantitative framework modeled treatment line progression, administration route substitution patterns, biomarker stratification prevalence, and regional regulatory cluster differentiation to derive segment-level CAGRs. Forecast inputs incorporated BRAF V600 mutation testing throughput expansion in European reference laboratories, subcutaneous formulation adoption velocity in German ambulatory networks, and TIL therapy manufacturing capacity buildout timelines.
The analysis sits within stated boundaries; outcomes outside current FDA and EMA accelerated approval pathway continuity, sustained premium reimbursement for combination regimens, and intact cytokine supplier oligopoly structures would require recalibration. Practitioners should keep alternative scenarios live as EU AI Act algorithmic scrutiny for diagnostic tools and biennial Japanese National Health Insurance pricing reviews evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
South America Bladder Cancer Therapeutics and Diagnostics Market
Oncology
Metastases Spinal Tumor Market
Oncology
Bone Metastasis Market
Oncology
Musculoskeletal Oncology Therapeutics Market
Oncology
Low-Grade Central Osteosarcoma Treatment Market
Oncology
Precision Oncology Market
Oncology
Europe Proton Therapy Market
Oncology
Colorectal Cancer Market
Oncology
Esophageal Cancer Drugs Market
Oncology
North America Bone Metastasis Market
Oncology
Oncology Devices Market
Oncology
Europe Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Bone Cancer Treatment Market
Oncology
Global Metastatic Cancer Treatment Market
Oncology
Global Metastatic Melanoma Drugs Market
Oncology
Ustekinumab Market