
 US Veterinary Diagnostics Market | 2026-2036
US Veterinary Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
US Veterinary Diagnostics Market Insights
Veterinary pathologist and laboratory technician shortages is bifurcating the market into consolidated reference laboratories and point-of-care clinic solutions. IDEXX Laboratories, Inc. leverages extensive reference lab networks to sustain high-throughput diagnostic capacity across metropolitan veterinary markets. Zoetis Services LLC anchors its position through integrated instrument and consumable platforms that reduce clinic workflow friction. Thermo Fisher Scientific Inc. competes by extending molecular reagent portfolios into veterinary-specific assay development.
US veterinary diagnostics encompasses analytical systems, reagents, and services that detect infectious agents, metabolic disorders, and genetic conditions in companion and livestock animals, utilizing immunoassay chemistry with picogram-level sensitivity thresholds to guide treatment decisions. Molecular diagnostics and immunoassay analyzers represent the fastest-expanding product categories as PCR-based pathogen identification and chemiluminescent antibody detection displace legacy culture methods in clinical settings. Veterinary clinics dominate end-user demand through capital investment in in-house analyzers, while diagnostic laboratories capture margin pools from esoteric testing and telemedicine-integrated result reporting.
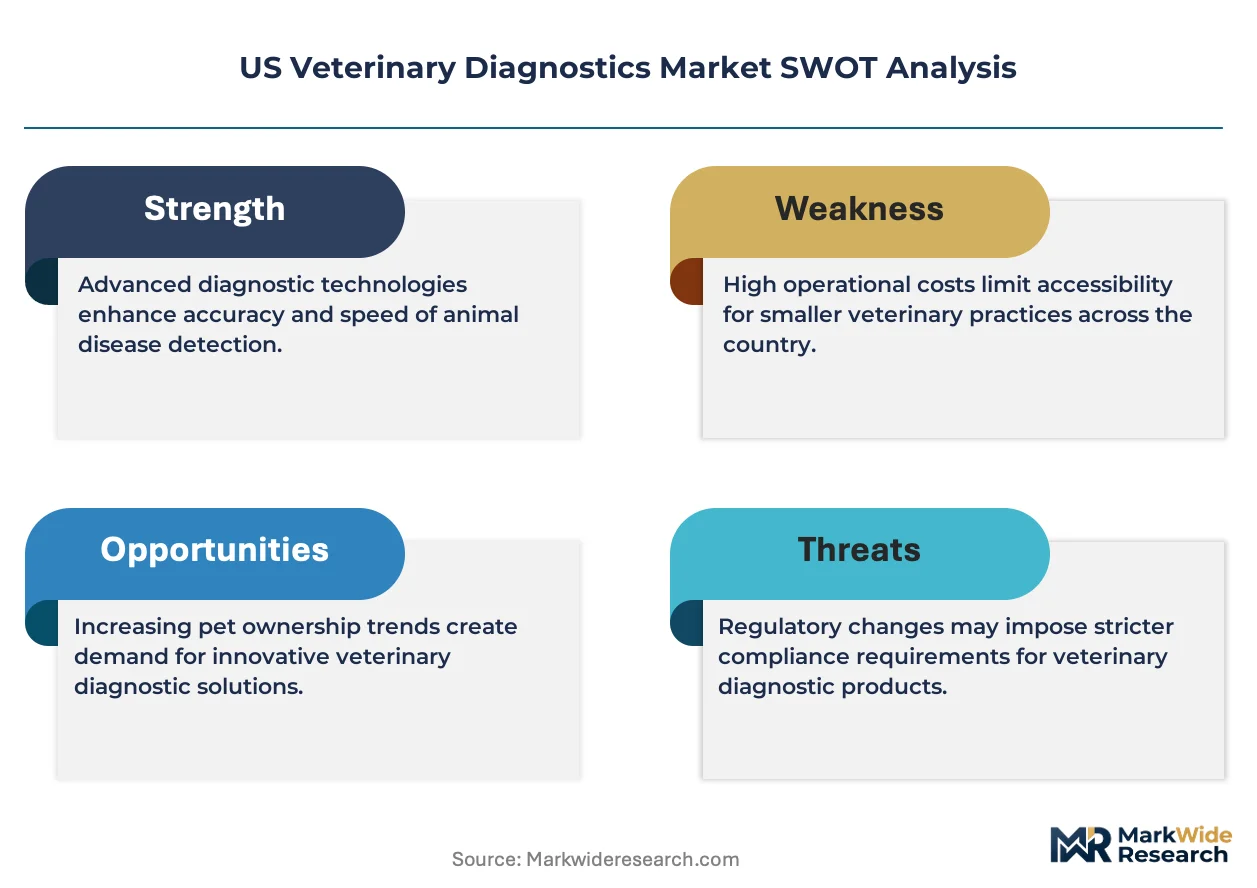
The FDA Center for Veterinary Medicine governs diagnostic kit premarket notification pathways, while USDA APHIS regulates livestock disease surveillance assays that cross state lines and international borders. CLIA standards shape quality benchmarks for veterinary reference laboratories processing human-animal comparative specimens. Stakeholders must monitor evolving FDA guidance on laboratory-developed tests as regulatory clarity determines whether clinic-based molecular platforms require formal premarket review or continued enforcement discretion.
Market Dynamics
PCR-based molecular diagnostics is fragmenting veterinary care delivery across California's specialty corridor and metropolitan clinic networks, compressing turnaround times from days to hours while straining pathologist capacity.
Growth Catalysts
- IRDA Framework:The FDA Center for Veterinary Medicine's enforcement discretion on laboratory-developed tests permits clinic-based molecular platforms to operate without premarket notification, accelerating point-of-care adoption.
- Companion Animal Expenditure:Pet owners in California and Texas corridor cities now demand same-day pathogen identification, pulling capital investment toward in-house analyzers.
- Telemedicine Integration:Diagnostic laboratories embed AI-assisted result interpretation into remote consultation workflows, capturing margin pools from geographically dispersed veterinary practices.
Market Restraints
- Reagent Supply Concentration:Polymerase and fluorescent probe manufacturing clusters in Massachusetts and California create single-source vulnerability for PCR assay production.
- CLIA Compliance Burden:Veterinary reference laboratories processing human-animal comparative specimens face quality benchmark audits that extend certification timelines by 6-12 months.
- Culture Method Persistence:Antimicrobial susceptibility testing still requires bacterial isolation, limiting full displacement of legacy workflows despite molecular speed advantages.
Strategic Opportunities
- USDA APHIS Livestock Mandates:Interstate movement regulations for cattle and swine create recurring demand for certified infectious disease surveillance assays.
- Midwest Geographic White Space:Consolidated reference laboratory networks underpenetrate rural veterinary markets across Iowa, Nebraska, and Kansas.
- CRISPR Convergence:Gene-editing diagnostic platforms paired with portable sequencing hardware enable field-deployable genetic disorder screening.
Industry Challenges
- Veterinary Pathologist Scarcity:Residency program output fails to match diagnostic caseload growth, forcing laboratories to implement AI-assisted histopathology triage.
- Analyzer Integration Complexity:Clinic staff must reconcile incompatible data formats between immunoassay and molecular platforms, increasing training overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Veterinary Diagnostics Market |
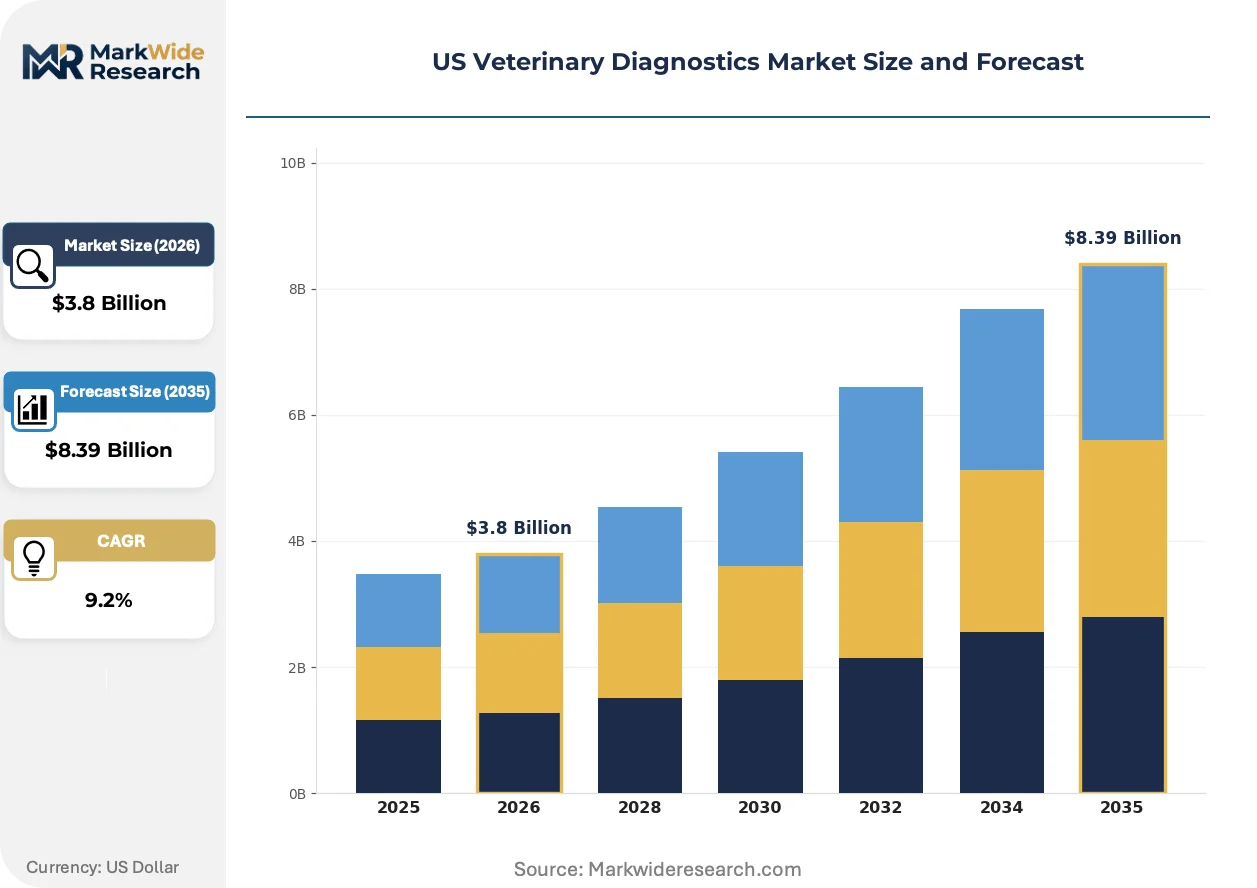
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoassay Analyzers, Hematology Analyzers, Molecular Diagnostics, Clinical Chemistry Analyzers, Microbiology Instruments Application: Infectious Disease Detection, Nutritional Deficiency Screening, Genetic Disorder Identification, Parasitic Infection Testing, Hormonal Analysis End User: Veterinary Clinics, Diagnostic Laboratories, Research Institutes, Zoos, Animal Shelters Distribution Channel: Direct Sales, Distributors, Online Platforms, Veterinary Supply Stores, Institutional Purchasing |
| Companies Covered | IDEXX Laboratories, Inc., Zoetis Services LLC, Antech Diagnostics, Inc., Heska Corporation, Thermo Fisher Scientific Inc., Virbac, Zomedica Corp., Neogen Corporation, Randox Laboratories Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Veterinary Diagnostics Market Trends and Innovations
Artificial intelligence is compressing diagnostic interpretation timelines while portable hardware extends testing capabilities beyond traditional laboratory boundaries. Three developments dominate current investment patterns.
Multiplex PCR panels is fragmenting infectious disease screening workflows by consolidating 10-20 pathogen targets into single reactions. Companion animal hospitals in California and New York corridor markets now deploy these systems for respiratory and gastrointestinal panels, collapsing send-out volumes that previously sustained reference laboratory revenue.
The FDA Center for Veterinary Medicine's evolving guidance on laboratory-developed tests is creating regulatory uncertainty for clinic-based molecular platforms. Stakeholders must monitor whether enforcement discretion persists or formal premarket review pathways emerge, with diagnostic laboratories currently investing in CLIA-waived assay development as a hedge against stricter oversight.
Telemedicine-integrated result reporting is altering how veterinary practices consume diagnostic services. Specialist veterinarians in Texas and Florida now expect real-time pathologist consultation embedded within digital result platforms, unbundling traditional laboratory service bundles and compressing account stickiness for reference providers.
US Veterinary Diagnostics Market Segmentation
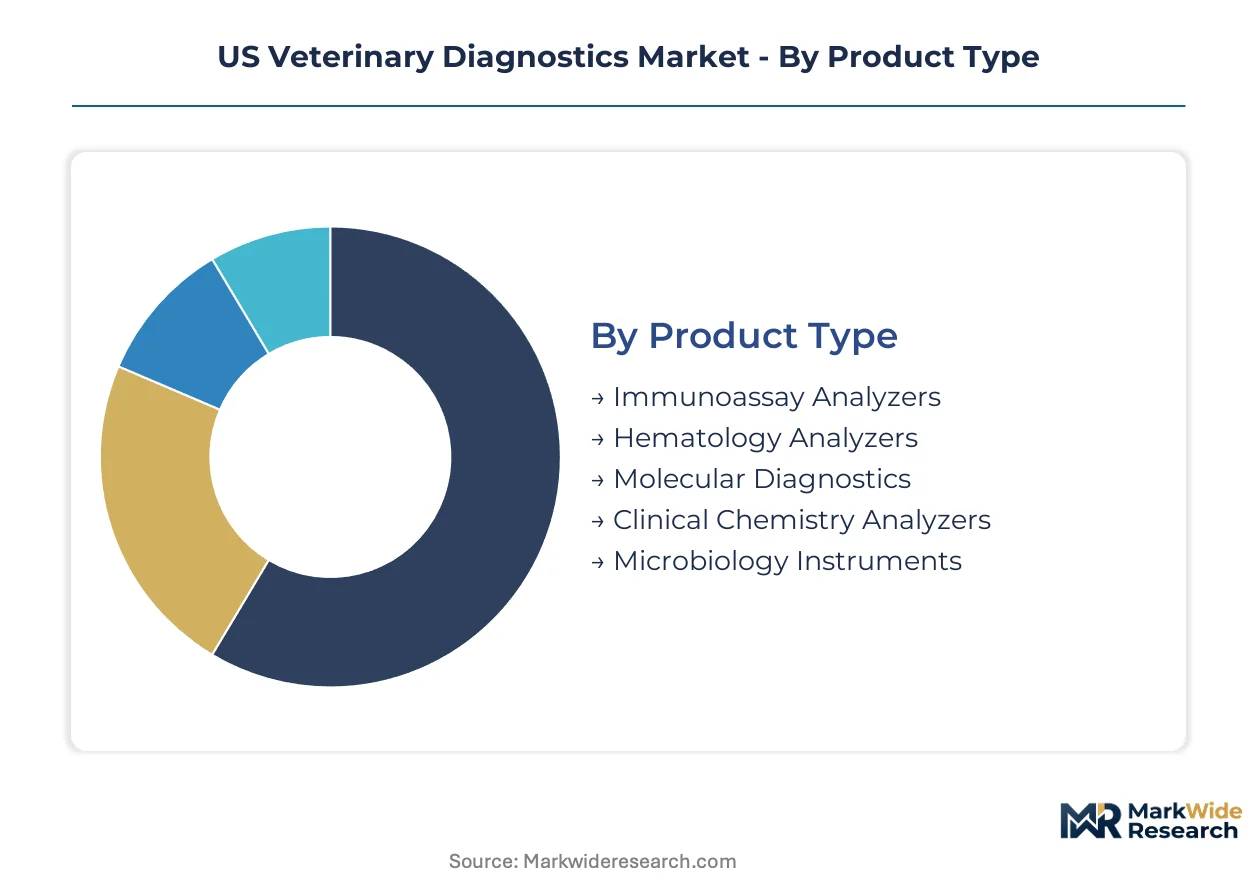
Segmentation reveals how substitution pressures and regulatory pathways reshape procurement patterns across veterinary diagnostic platforms. Understanding these divisions exposes where capital investment concentrates versus where legacy systems retain defensive positions.
Product Type:
Substitution pressure runs strongest against culture-dependent instruments as molecular platforms displace legacy workflows in high-throughput settings.
- Immunoassay Analyzers:Chemiluminescent detection systems achieve picogram-level antibody sensitivity for metabolic and hormonal panels. California specialty hospitals deploy these for same-day result delivery, though reagent supply concentration in Massachusetts creates vulnerability.
- Molecular Diagnostics:PCR-based pathogen identification compresses turnaround from days to hours with multiplexed respiratory and gastrointestinal panels. Texas and Florida corridor clinics pull capital toward in-house platforms despite FDA enforcement discretion uncertainty.
- Hematology Analyzers:Automated cell counters with species-specific algorithms dominate routine wellness screening in general practice.
- Clinical Chemistry Analyzers:Wet chemistry and dry slide systems process metabolic panels for renal and hepatic function assessment.
- Microbiology Instruments:Automated culture systems and susceptibility readers persist where antimicrobial stewardship requires isolation protocols.
Molecular Diagnostics gains share at the steepest rate while Immunoassay Analyzers anchors the volume base through installed instrument fleets.
Application:
Cost tier differentiation separates emergency diagnostic spending from routine screening budgets across practice types.
- Infectious Disease Detection:Multiplex PCR panels consolidate 10-20 pathogen targets into single reactions for respiratory and gastrointestinal screening. California and New York specialty hospitals collapse send-out volumes that previously sustained reference laboratory revenue.
- Genetic Disorder Identification:Inherited disease screening and breeding compatibility testing leverage portable sequencing hardware for field-deployable deployment. Midwest rural markets show particular appetite for cost-effective carrier detection.
- Nutritional Deficiency Screening:Vitamin and mineral panels support production animal management and exotic species husbandry.
- Parasitic Infection Testing:Fecal flotation and antigen detection remain staples of wellness protocols despite molecular alternatives.
- Hormonal Analysis:Reproductive endocrinology panels serve breeding programs and adrenal disorder diagnosis.
Infectious Disease Detection anchors the volume base while Genetic Disorder Identification climbs the fastest as breeding program sophistication advances.
End User:
Customer type determines whether procurement favors capital-intensive in-house platforms or outsourced reference laboratory relationships.
- Veterinary Clinics:General and specialty practices invest in point-of-care analyzers to capture same-day revenue and satisfy pet owner expectations for rapid turnaround. California's specialty corridor leads capital deployment per practice.
- Diagnostic Laboratories:Reference networks process esoteric testing and telemedicine-integrated consultations, capturing margin pools from geographically dispersed practices. CLIA compliance burdens extend certification timelines for human-animal comparative specimen processing.
- Research Institutes:Academic veterinary medical centers drive assay development and validation for emerging pathogen targets.
- Zoos:Exotic species diagnostic requirements demand specialized reagent formulations and interpretive expertise.
- Animal Shelters:High-volume screening programs prioritize cost-efficient infectious disease detection for intake protocols.
Veterinary Clinics anchors the volume base while Diagnostic Laboratories faces the steepest share compression from in-house platform adoption.
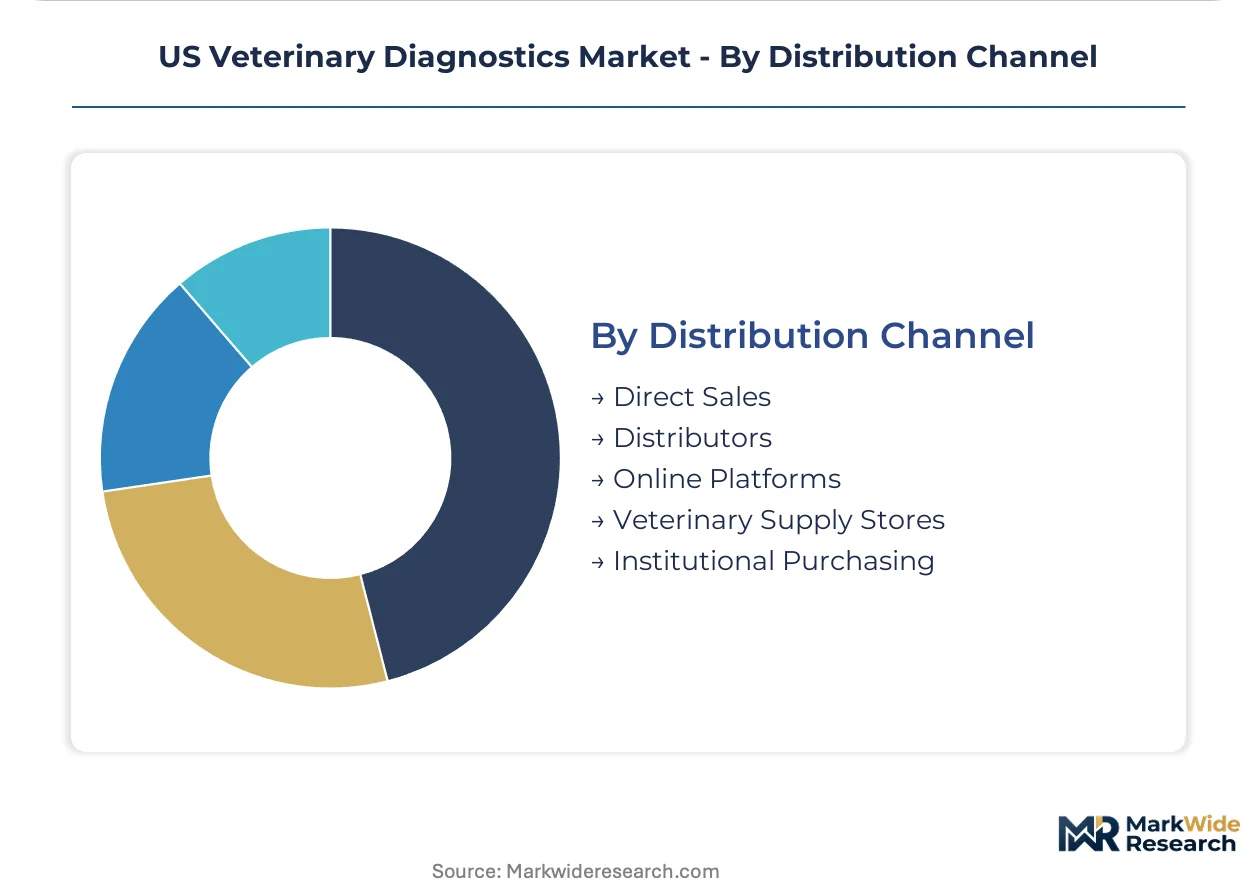
Distribution Channel:
Supply concentration in reagent manufacturing clusters shapes channel leverage and procurement risk profiles.
- Direct Sales:Instrument manufacturers deploy field service engineers for installation, training, and maintenance of capital equipment. IDEXX and Zoetis maintain dedicated sales forces for high-volume metropolitan accounts.
- Distributors:Regional veterinary supply houses consolidate consumable procurement for mid-size practice groups. Nebraska and Kansas rural markets rely heavily on distributor networks for reagent replenishment.
- Online Platforms:E-commerce penetration accelerates for standardized consumables and point-of-care test kits.
- Veterinary Supply Stores:Cooperative purchasing groups negotiate volume discounts for independent practice networks.
- Institutional Purchasing:Corporate veterinary groups and university systems centralize procurement through dedicated supply chain functions.
Direct Sales anchors the volume base for instrument placement while Online Platforms expands most quickly for consumable replenishment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA Center for Veterinary Medicine anchors regulatory oversight for diagnostic platforms across the United States, while state-level veterinary practice acts and USDA APHIS interstate movement rules shape regional deployment patterns for molecular and immunoassay systems.
California
Specialty companion animal hospitals in Los Angeles and San Francisco corridors drive capital investment in multiplex PCR panels and chemiluminescent analyzers. The California Veterinary Medical Board enforces continuing education requirements for molecular platform operation. San Diego's biotech cluster supplies polymerase and fluorescent probe reagents, creating manufacturing concentration risk for regional assay production.
Texas
Metropolitan veterinary practices in Dallas-Fort Worth and Houston demand same-day pathogen identification for respiratory and gastrointestinal panels. The Texas State Board of Veterinary Medical Examiners regulates point-of-care analyzer deployment in mixed animal practices. Austin's emerging life sciences corridor attracts reference laboratory satellite facilities serving rural central Texas markets.
New York
Specialty referral hospitals in New York City and Long Island compress turnaround times through in-house molecular diagnostics. The New York State Education Department Office of the Professions oversees veterinary laboratory certification standards. Cornell University's veterinary medical center in Ithaca anchors academic assay development for emerging infectious disease targets.
Florida
High-volume companion animal clinics in Miami and Tampa Bay prioritize rapid infectious disease screening for dense urban pet populations. The Florida Department of Business and Professional Regulation enforces veterinary laboratory quality standards. Orlando's central location supports distribution hub functions for consumable replenishment across the southeastern veterinary corridor.
Illinois
Midwest reference laboratory networks concentrate processing capacity in Chicago for esoteric testing and telemedicine-integrated consultations. The Illinois Department of Financial and Professional Regulation governs veterinary diagnostic laboratory licensure. Urbana's University of Illinois veterinary school drives research collaboration with commercial assay developers for livestock disease surveillance.
US Veterinary Diagnostics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the US veterinary diagnostics market. The upper tier commands reference laboratory networks and instrument-consumable platforms, while mid-cap specialists focus on point-of-care molecular systems or regional service coverage. Three archetypes dominate: full-stack integrators bundling hardware, reagents, and laboratory services; point-of-care platform specialists emphasizing workflow speed; and reference laboratory pure-plays capturing esoteric testing margins. Competitive moves concentrate on M&A consolidation of regional laboratory networks and strategic partnerships for reagent supply security.
Among publicly traded veterinary health companies, IDEXX Laboratories, Inc. and Zoetis Services LLC exemplify the full-stack integrator archetype through combined instrument placement and reference laboratory network control. Thermo Fisher Scientific Inc. represents the reagent and platform technology tier, extending molecular development capabilities into veterinary-specific assay formats. These three companies anchor the competitive structure through differentiated positions across the clinic-to-laboratory diagnostic value chain.
| Leading Market Players |
|---|
| IDEXX Laboratories, Inc. |
| Zoetis Services LLC |
| Antech Diagnostics, Inc. |
| Heska Corporation |
| Thermo Fisher Scientific Inc. |
| Virbac |
| Zomedica Corp. |
| Neogen Corporation |
| Randox Laboratories Ltd. |
| Others |
Pricing and Supply Chain Analysis
PCR reagent substitution for legacy culture media is redrawing procurement geography across Massachusetts biotech clusters and California specialty corridors, simultaneously elevating polymerase spot pricing volatility and compressing margin pools for distributors serving mid-tier clinics.
Pricing Analysis
Coastal California commands 15-25% premiums over Midwest veterinary markets for identical molecular assay platforms due to freight absorption and field service density requirements. Three-tier pricing structure across premium, standard, and economy levels separates CLIA-certified reference laboratories from CLIA-waived clinic systems and unregulated point-of-care test kits. Cost compression in economy-tier consumables is intensifying because distributor consolidation in Nebraska and Kansas reduces competitive quoting. General practice clinics in rural Iowa exhibit highest price sensitivity, while specialty hospitals in Los Angeles and San Francisco corridors prioritize turnaround speed over per-test economics.
Supply Chain Analysis
Strategic stockpiling of fluorescent probes and master mix reagents dominates procurement behavior among California reference laboratories anticipating Massachusetts manufacturing disruptions. Domestic supply concentrates in San Diego biotech corridors and Boston-area polymerase foundries, with critical enzymes drawing from German fermentation capacity and Japanese purification technology. Single-source vulnerability permeates Taq polymerase supply chains where three contract manufacturers service the entire US veterinary market. Distribution runs through IDEXX and Zoetis direct sales forces for capital equipment, while regional distributors handle consumable replenishment across Texas and Florida metropolitan networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reagent subscription contracts and telemedicine-integrated result interpretation layers expand at double the rate of hardware placements, converting capital expenditure relationships into recurring revenue streams that deepen account stickiness.
For Market Incumbents: Consolidate regional reference laboratory networks in Illinois and Texas to defend esoteric testing margins against in-house molecular platform adoption. Acquire CLIA-waived assay developers as regulatory hedge against FDA enforcement discretion withdrawal. Vertical integration into polymerase manufacturing mitigates Massachusetts supply concentration risk.
For New Entrants and Emerging Players: USDA APHIS certification fast-track for interstate livestock movement assays opens immediate revenue capture in Iowa, Nebraska, and Kansas corridors where consolidated networks underpenetrate. Target mid-size mixed animal practices in Austin and Nashville satellite markets with portable sequencing hardware bundled with field-deployable genetic screening services. Partner with Cornell and University of Illinois veterinary schools for assay validation credibility.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors reference laboratory pure-plays with telemedicine infrastructure and CLIA-waived development pipelines. Long-term viability hinges on recurring revenue mix exceeding 60% of total diagnostic spend. Watch FDA Center for Veterinary Medicine guidance on laboratory-developed tests as inflection indicator—formal premarket review pathways would compress point-of-care platform valuations and elevate CLIA-certified laboratory multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-Waived Assay Development | Positions laboratories for regulatory hedge against FDA enforcement discretion withdrawal. |
| Reference Laboratory Network Consolidation | Captures esoteric testing margins in Illinois and Texas metropolitan corridors. |
| Telemedicine Platform Integration | Embeds AI-assisted pathologist consultation into real-time result workflows for Florida specialists. |
| Reagent Supply Security Partnership | Reduces single-source vulnerability in Massachusetts polymerase manufacturing clusters. |
| Midwest Geographic Expansion | Addresses white-space penetration gaps across Iowa, Nebraska, and Kansas rural markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) premarket notifications, USDA APHIS assay certification records, and state veterinary medical board laboratory licensure databases. Primary interviews incorporated veterinary pathologists, reference laboratory operations directors, clinic practice managers, and diagnostic instrument procurement officers. Secondary validation drew from SEC 10-K filings of publicly traded veterinary health companies, CLIA proficiency testing records, and California Veterinary Medical Board continuing education compliance data. Bottom-up instrument placement counts triangulated against top-down diagnostic service revenue estimates.
Segmentation dimensions modeled span product type, application, end user, and distribution channel across the projection horizon. CAGRs derived from instrument replacement cycles, reagent consumption curves, and telemedicine adoption trajectories. Species-specific algorithm development timelines and FDA guidance evolution on laboratory-developed tests served as industry-specific forecast inputs throughout the modeling period.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement discretion or accelerated CLIA certification timelines would require recalibration. Forecasts reflect assumptions regarding pathologist workforce availability and polymerase manufacturing capacity expansion. Revision becomes warranted when regulatory clarity on premarket review pathways crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Medicine
United States Veterinary Healthcare Market
Veterinary Medicine
Monoclonal Antibodies in Veterinary Health Market
Veterinary Medicine
ASEAN Rabies Veterinary Vaccines Market
Veterinary Medicine
Global Veterinary Autogenous Vaccines Market
Veterinary Medicine
Veterinary Orthopedic Medicine Market
Veterinary Medicine
Veterinary Anti-Infectives Market
Veterinary Medicine
Veterinary Biologics Market
Veterinary Medicine
Over-The-Counter (OTC) Veterinary Drugs Market
Veterinary Medicine
Veterinary Skin Care Products Market
Veterinary Medicine
Veterinary Dental Elevators Market
Veterinary Medicine
US Veterinary Orthopedic Medicine Market
Veterinary Medicine
Animal Drugs Market
Veterinary Medicine
Veterinary Medicine Market
Veterinary Medicine
Global Veterinary/Animal Vaccines Market
Veterinary Medicine
Global Brucellosis Vaccines Market
Veterinary Medicine
South Africa Veterinary Medicine Market