
 48 Volt Battery System Market | 2026-2036
48 Volt Battery System Market Size, Share, and Industry Trends Forecast 2026-2036
48 Volt Battery System Market Outlook
China's expanding lithium-ion cell capacity is reshaping cost curves for 48V module suppliers worldwide. Robert Bosch leverages its integrated powertrain division to bundle 48V systems with starter-generator units for European OEMs. Continental anchors its position through captive semiconductor sourcing for battery management controllers. A123 Systems specializes in high-power lithium-iron-phosphate cells calibrated for transient load profiles in commercial vehicle applications.
A 48 volt battery system operates at a nominal voltage of 48V DC, typically configured as a 15-cell lithium-ion string or multi-string lead-acid array with integrated DC-DC conversion to 12V legacy architectures. The architecture supports mild-hybrid electric vehicles, marine auxiliary power, and telecom backup by delivering peak currents above 200A for torque-fill and regenerative braking without full high-voltage isolation requirements. Lithium-ion chemistry captures the dominant margin pool as cell energy density improvements reduce module count and packaging mass. The automotive end user segment leads absolute volume, while marine and commercial installations show faster penetration rates due to diesel displacement regulations in harbor zones. Fixed installations dominate residential and grid-tied storage, though modular formats gain traction in aftermarket retrofit channels seeking scalable capacity increments.
The EPA tailpipe standards and NHTSA CAFE rules in the United States compel OEMs to deploy 48V systems as a compliance bridge before full electrification, while ECHA REACH restrictions on lead-acid recycling are accelerating lithium-ion substitution in European supply chains. China's SAMR enforces GB standards for battery cycling durability that directly influence module warranty terms offered to fleet operators. Stakeholders must monitor how divergent certification timelines across EPA, ECHA, and SAMR jurisdictions fragment platform engineering resources and determine whether regional battery variants or unified global architectures prove more cost-efficient.
Market Dynamics
Automotive OEMs face mounting pressure to decarbonize powertrains without bearing full battery-electric vehicle costs, pushing 48V architectures into mass-market vehicle segments previously served by conventional 12V systems.
Growth Catalysts
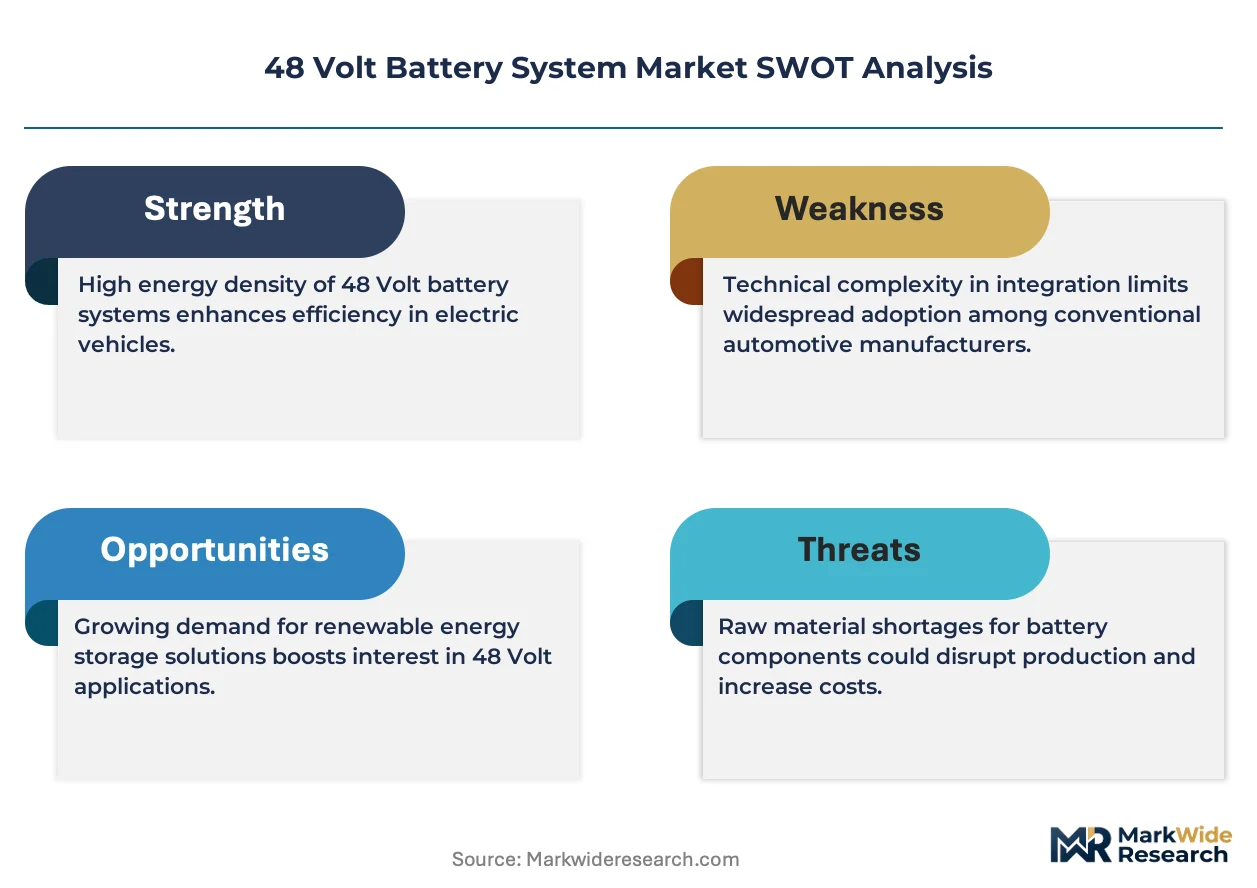
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants compels automakers to deploy 48V electric compressors, expanding auxiliary system voltage requirements across European fleets.
- Mild-hybrid torque-fill:Belt-driven starter-generator integration enables cylinder deactivation strategies that shave grams per kilometer from CO2 compliance calculations.
- Stuttgart-Munich corridor:Germany's concentrated automotive engineering ecosystem accelerates module validation cycles and reduces platform development overhead for 48V system suppliers.
Market Restraints
- Lithium carbonate volatility:Cell chemistry input costs swing with commodity markets, compressing module supplier margins on fixed-price OEM contracts.
- Semiconductor captive sourcing:Battery management controller ASICs concentrate among Taiwanese foundries, exposing tier-one integrators to single-geography supply risk.
- Lead-acid substitution economics:Flooded battery incumbent pricing in aftermarket channels delays lithium-ion penetration in price-sensitive commercial vehicle retrofits.
Strategic Opportunities
- Marine harbor electrification:Diesel displacement mandates in European and Chinese port zones open auxiliary power applications for 48V shore-power systems.
- Telecom backup convergence:Tower operators in India integrate 48V lithium modules with solar DC coupling, displacing diesel generator runtime.
- China MIIT dual carbon alignment:Domestic OEMs receive preferential NEV credit treatment for 48V mild-hybrid deployments, accelerating local module demand.
Industry Challenges
- Functional safety certification:ISO 26262 ASIL-D compliance for battery management software stretches engineering timelines and requires specialized embedded systems talent.
- Legacy 12V integration complexity:Bidirectional DC-DC converter architectures must maintain fault-tolerant operation across heterogeneous electrical loads without redesigning entire vehicle harnesses.
- Cross-jurisdiction warranty alignment:Divergent cycling durability test protocols between SAMR GB standards and EPA compliance pathways fragment platform engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 48 Volt Battery System Market |
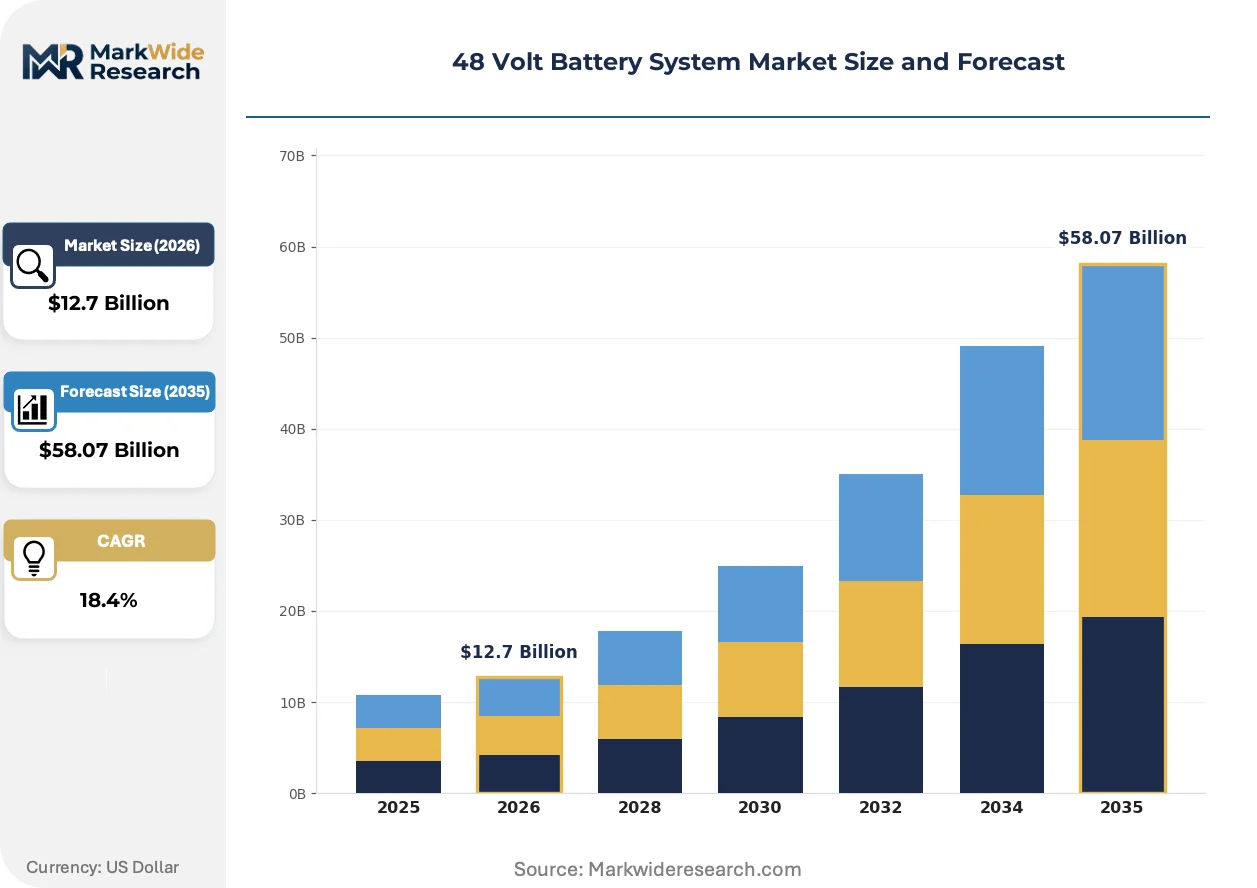
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $58.07 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead Acid, Lithium-Ion, Nickel-Cadmium, Flow Battery End User: Automotive, Marine, Commercial, Residential Installation: Fixed, Portable, Modular, Integrated Technology: Battery Management Systems, Smart Grids, Renewable Energy Integration, Fast Charging |
| Companies Covered | ZF Friedrichshafen, A123 Systems, Robert Bosch, GS Yuasa, Johnson Controls, Continental, BorgWarner, EnerSys, Valeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
48 Volt Battery System Market Strategic Shifts
Digital twin technology is compressing cell characterization timelines while silicon carbide power electronics reduce converter losses. These shifts are redefining system architecture trade-offs between energy density and thermal management.
Cell-to-pack architectures are virtualizing traditional module boundaries. Automotive OEMs in Germany and China adopt direct cooling plates that eliminate intermediate structural layers, reducing mass by fifteen to twenty percent. This topology shift enables larger format prismatic cells without sacrificing crash safety, compressing bill-of-material counts while extending vehicle electric range contributions from regenerative braking recovery.
REACH authorization requirements for nickel and cobalt compounds are forcing cathode chemistry pivots toward lithium-iron-phosphate formulations. European cell suppliers accelerate LFP pilot lines to preempt supply chain disclosure obligations. Commercial vehicle segments with high cycle-count requirements respond fastest, accepting modest energy density penalties in exchange for thermal stability and simplified recycling compliance.
Fleet procurement departments now specify total-cost-of-ownership metrics over upfront module pricing. Logistics operators in harbor zones and last-mile delivery verticals demand guaranteed residual capacity thresholds at end-of-lease, unbundling hardware supply from performance contracting. This pattern concentrates in German and Chinese markets where diesel bans and NEV mandates compress operational flexibility windows.
48 Volt Battery System Market Segmentation
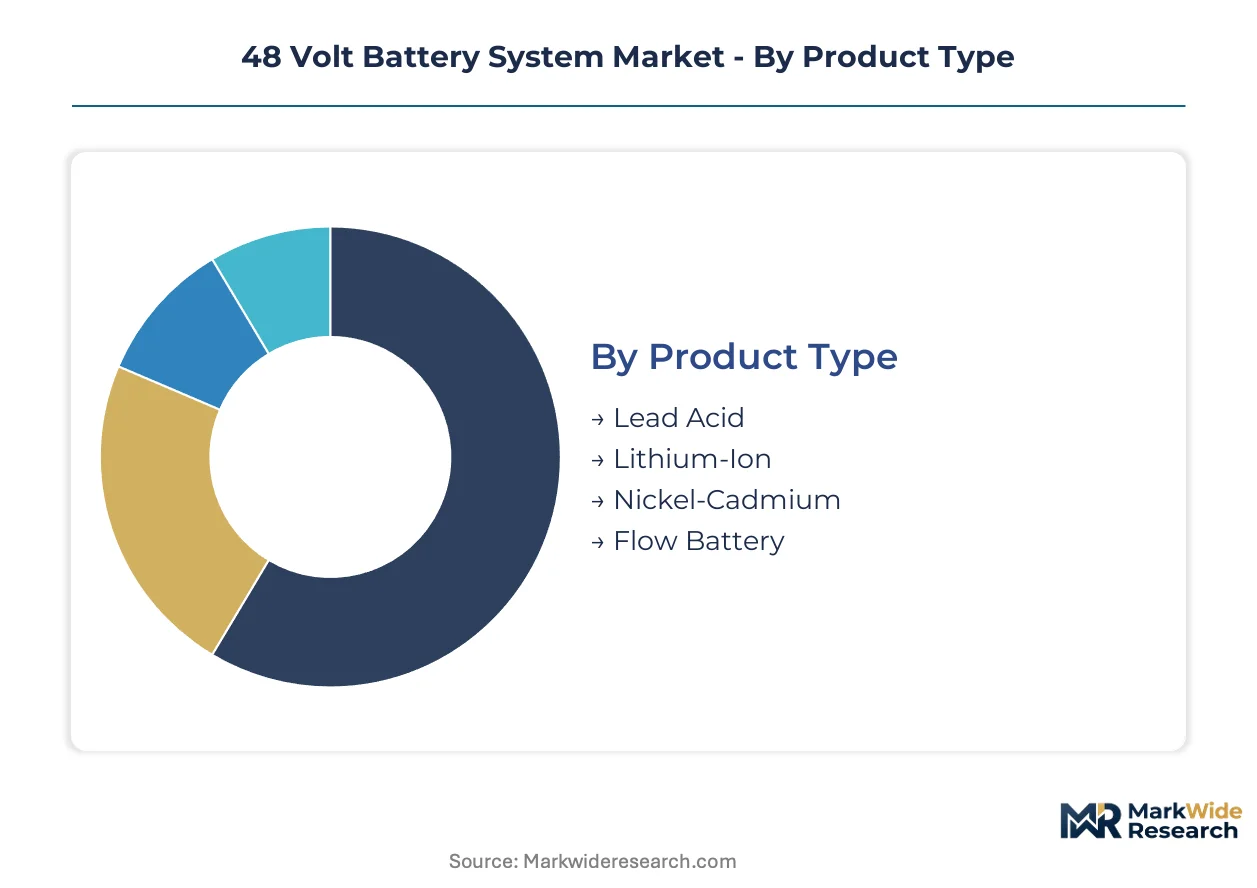
Segmentation in the 48 volt battery system market reveals divergent replacement cycles and margin structures across chemistry types and installation formats. Understanding these temporal patterns enables suppliers to align inventory and warranty terms with actual utilization profiles rather than assuming uniform depreciation curves.
Product Type:
Cycle times vary dramatically across chemistries, with some technologies requiring replacement every 3-4 years under heavy cycling while others extend beyond a decade in float applications.
- Lithium-Ion:Dominant chemistry for automotive mild-hybrid architectures, configured as 15-cell strings with integrated thermal management. German and Chinese OEMs specify these modules for regenerative braking energy recovery, where cell-level energy density above 250 Wh/kg reduces packaging mass. Demand concentrates in Stuttgart-Munich corridor validation programs and MIIT credit-eligible domestic Chinese platforms.
- Lead Acid:Flooded and absorbed glass mat variants persist in aftermarket commercial vehicle retrofits and telecom backup installations where capital constraints override lifecycle economics. ECHA REACH recycling disclosure obligations are accelerating substitution in European supply chains, though price-sensitive fleet operators in India and Southeast Asia delay conversion.
- Nickel-Cadmium:Aviation and rail auxiliary power applications exploit the chemistry's tolerance to deep discharge and temperature extremes. Regulatory restrictions on cadmium content limit new installations to specialized industrial niches with established waste handling infrastructure.
- Flow Battery:Vanadium redox configurations address stationary multi-hour storage requirements in grid-tied and marine shore-power applications. Cycle life exceeding 15,000 charge events justifies higher upfront capital against diesel displacement mandates in European harbor zones.
Lead Acid dominates installed base. Lithium-Ion is where expansion concentrates.
End User:
Application-specific duty cycles and regulatory exposure create four distinct customer archetypes with divergent procurement behaviors and technical specifications.
- Automotive:Mild-hybrid passenger vehicles and light commercial trucks integrate 48V belt-driven starter-generator systems for cylinder deactivation and torque-fill. EPA CAFE compliance pathways and EU fleet CO2 standards compel mass-market deployment across vehicle segments previously served by conventional 12V architectures.
- Marine:Harbor craft and offshore support vessels deploy 48V auxiliary banks to satisfy diesel displacement regulations in Rotterdam, Hamburg, and Shanghai port zones. Shore-power connection requirements and at-berth emissions limits accelerate lithium module adoption despite salt-air corrosion challenges.
- Commercial:Last-mile delivery fleets and construction equipment operators specify high-cycle-count configurations with guaranteed residual capacity thresholds. Total-cost-of-ownership procurement models unbundle hardware supply from performance contracting in German and Chinese logistics verticals.
- Residential:Home energy storage systems couple 48V battery banks with rooftop solar inverters, displacing lead-acid legacy installations. Modular capacity increments appeal to aftermarket retrofit channels seeking scalable upgrades without full system replacement.
Automotive commands absolute volume. Marine shows steepest expansion trajectory.
Installation:
Physical integration topology determines thermal management complexity, service accessibility, and compatibility with legacy electrical infrastructure across end-use environments.
- Fixed:Permanently mounted rack and cabinet configurations dominate grid-tied storage and telecom central office applications. These installations prioritize energy density and passive cooling over portability, with design lifecycles aligned to infrastructure depreciation schedules.
- Portable:Cased units with integrated handles and connectors serve construction site power, event production, and emergency response applications. Weight constraints below 25 kilograms enable manual handling but limit cell mass and continuous discharge ratings.
- Modular:Hot-swappable rack units with standardized form factors allow capacity scaling without system shutdown. Data center and industrial microgrid operators favor this topology for maintenance scheduling flexibility and phased capital deployment.
- Integrated:Purpose-built enclosures merged with power electronics, cooling, and control systems reduce field wiring complexity. OEM-specified automotive and marine applications demand this level of packaging to meet crash safety and vibration resistance standards.
Fixed installations anchor revenue. Modular formats gain share fastest in retrofit channels.
Technology:
System-level intelligence and interface capabilities increasingly differentiate commodity cell supply from value-captured integrated solutions.
- Battery Management Systems:ASIC-based controllers with cell balancing, state-of-charge estimation, and thermal runaway prevention. ISO 26262 ASIL-D functional safety certification stretches engineering timelines but gates automotive platform qualification.
- Smart Grids:Communication-enabled systems supporting demand response aggregation and grid ancillary services. Utility procurement specifications in Germany and California require IEEE 2030.5 protocol compliance for frequency regulation participation.
- Renewable Energy Integration:Maximum power point tracking and DC coupling architectures optimize solar and wind capture efficiency. Telecom tower operators in India deploy these configurations to minimize diesel generator runtime in off-grid and weak-grid locations.
- Fast Charging:Silicon carbide power electronics and active cooling enable C-rates above 2C for opportunity charging in commercial vehicle depots. Thermal management complexity and connector standardization gaps limit deployment beyond pilot fleets.
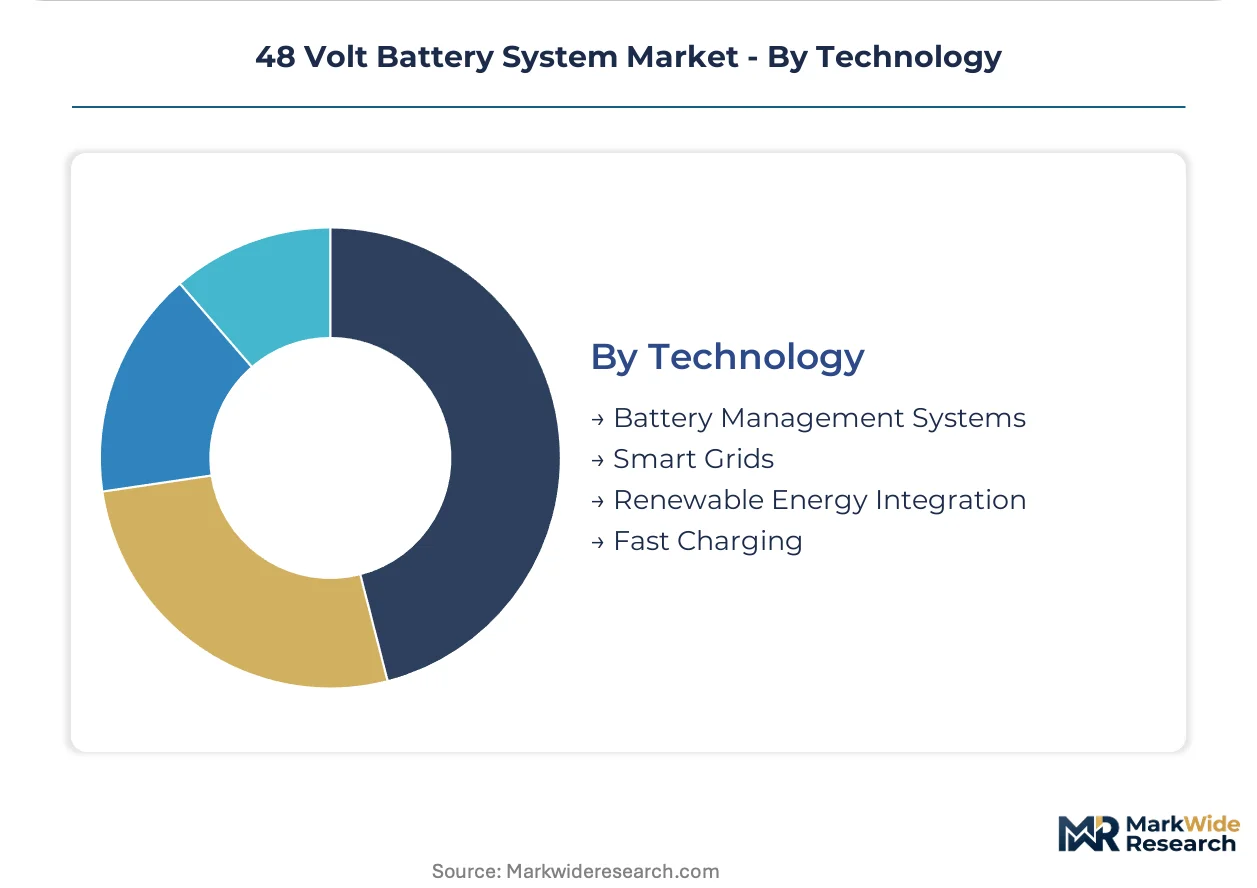
Battery Management Systems constitute the essential layer. Smart Grids represent the fastest-climbing value-add segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT dual carbon goals anchor Chinese demand for 48V mild-hybrid systems. Automakers in Germany and the United States deploy these architectures as compliance bridges against tightening fleet emissions standards. Module suppliers concentrate validation and production capacity around established automotive engineering clusters in each jurisdiction.
China
Domestic OEMs accelerate 48V deployments to capture NEV credits under MIIT dual carbon frameworks. SAMR enforces GB standards for battery cycling durability that directly shape warranty terms offered to fleet operators. Yangtze River Delta cell suppliers expand prismatic LFP pilot lines to serve local mild-hybrid platforms.
Germany
The Stuttgart-Munich corridor compresses module validation cycles through concentrated automotive engineering talent. EU F-Gas Regulation mandates 48V electric compressors, expanding auxiliary system voltage requirements across European fleets. Baden-Württemberg suppliers integrate captive semiconductor sourcing for battery management controllers.
United States
EPA tailpipe standards and NHTSA CAFE rules compel OEMs to deploy 48V systems before full electrification. Michigan and Ohio-based engineering centers adapt belt-driven starter-generator architectures for light truck segments. IRA clean vehicle provisions influence supplier location decisions for North American module assembly.
Japan
METI carbon neutrality roadmaps push domestic automakers toward mild-hybrid torque-fill strategies. JIS standards govern cell safety testing protocols that module suppliers must satisfy for platform qualification. Kansai-based manufacturers leverage existing nickel-metal-hydride expertise to transition toward lithium-ion 48V configurations.
South Korea
Seoul Capital Area battery suppliers face pressure from Chinese cell cost curves in export markets. MFDS chemical safety regulations intersect with automotive applications as conglomerates diversify beyond consumer electronics. Busan-Ulsan industrial complexes host validation facilities for marine harbor electrification projects targeting European port zones.
48 Volt Battery System Market Competitive Environment
Integrated powertrain suppliers and specialized cell manufacturers split the market between bundled system offerings and component supply. Consolidation pressure concentrates among tier-one automotive suppliers with captive semiconductor access, while independent cell specialists defend margin through chemistry differentiation. Two dominant strategic archetypes emerge: diversified industrial conglomerates with cross-sector battery portfolios, and focused automotive electrification pure-plays. Competitive moves center on backward integration into cell production and geographic expansion into MIIT-credit-eligible Chinese supply chains.
Within the diversified conglomerate tier, Robert Bosch and Continental exemplify integrated powertrain positioning through bundled 48V system offerings. A123 Systems occupies a specialist archetype focused on high-power lithium-iron-phosphate configurations. ZF Friedrichshafen and BorgWarner represent tier-one automotive suppliers with established starter-generator integration capabilities. Johnson Controls and EnerSys anchor industrial battery heritage transitioning toward automotive electrification applications. Valeo and GS Yuasa sit within European and Asian supplier networks respectively, each representing regional validation pathway expertise.
| Leading Market Players |
|---|
| ZF Friedrichshafen |
| A123 Systems |
| Robert Bosch |
| GS Yuasa |
| Johnson Controls |
| Continental |
| BorgWarner |
| EnerSys |
| Valeo |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta cell capacity expansion is compressing module supplier margins and redistributing pricing power toward downstream integrators with captive semiconductor access. Chinese lithium-ion production scale now sets the reference cost curve for 48V mild-hybrid systems sold into European and North American fleets.
Pricing Analysis
Price spreads between German-engineered modules and Chinese-origin alternatives span 25-40 percent at equivalent energy density specifications. Contract-based long-term offtake dominates OEM procurement, with pricing stratifying across automotive-grade ASIL-D certified, commercial vehicle standard, and aftermarket economy tiers. Cost compression in the economy tier is intensifying because Yangtze River Delta suppliers are absorbing lithium carbonate volatility to secure volume commitments. Fleet operators in commercial vehicle segments exhibit highest price sensitivity, while automotive OEMs prioritize certification compliance over unit cost.
Supply Chain Analysis
Extended payment terms from European automotive OEMs now stretch 90-120 days, forcing tier-one integrators to leverage supply-chain finance facilities backed by Chinese cell suppliers. Manufacturing concentrates in China, Germany, and South Korea, with prismatic cell output feeding module assembly across the Stuttgart-Munich corridor and Busan-Ulsan industrial zones. The chain draws from lithium carbonate, nickel sulfate, and silicon carbide wafer inputs. Single-source vulnerability concentrates in Taiwanese foundry capacity for battery management controller ASICs. Distribution runs through OEM direct procurement for automotive volumes, with aftermarket channels served by regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 48V battery system market is entering a cyclical recovery phase driven by EU F-Gas Regulation compliance deadlines forcing accelerated platform refreshes across European fleets.
For Market Incumbents: Pre-empt margin erosion from Chinese cell cost curves by securing captive semiconductor supply through Baden-Württemberg engineering partnerships. Prioritize backward integration into lithium-iron-phosphate cell production to defend position against Yangtze River Delta pricing pressure. Lock in multi-year ASIL-D certification pathways before SAMR GB standards divergence fragments platform engineering resources. For New Entrants and Emerging Players: India's telecom tower backup segment offers the most penetrable white-space opportunity, with tower operators seeking diesel displacement through solar-DC coupled 48V lithium modules. Marine harbor electrification in secondary Chinese port zones presents secondary expansion potential. Lead with performance contracting models that unbundle hardware supply from guaranteed residual capacity thresholds. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among battery management system software providers with ISO 26262 certification capabilities. Long-term viability over the next decade rests on exposure to MIIT credit-eligible Chinese platforms and EU F-Gas-driven compressor electrification. Target acquisition archetypes are mid-cap specialists with captive thermal management IP. Watch for lithium carbonate price stabilization as the inflection signal for margin recovery in module manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Production | Yangtze River Delta LFP pilot lines reduce dependency on external lithium-ion supply. |
| ASIL-D Certification Investment | ISO 26262 compliance gates automotive platform qualification with Stuttgart-Munich OEMs. |
| Marine Harbor Electrification Partnership | Rotterdam and Shanghai port diesel displacement mandates open auxiliary power applications. |
| Silicon Carbide Power Electronics Adoption | Reduced converter losses enable higher C-rate charging for commercial vehicle depots. |
| Performance Contracting Model Deployment | Guaranteed residual capacity thresholds align fleet procurement with total-cost-of-ownership metrics. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and marine harbor electrification project developers; and secondary validation against MIIT policy filings, SAMR GB standard drafts, EU F-Gas Regulation implementation timelines, and automotive production registration databases. Bottom-up cell demand modeling triangulated against top-down fleet CO2 compliance pathway analysis.
Forecast inputs considered vehicle class segmentation across passenger car, light commercial, and heavy-duty architectures alongside propulsion system voltage tier and regional production cluster. CAGRs were derived from installed base replacement cycles, platform refresh timelines, and regulatory deadline clustering. Chemistry mix projections incorporated REACH authorization timelines for nickel and cobalt compounds.
Practitioners should monitor lithium carbonate futures curves, SAMR-ECHA regulatory divergence signals, and Taiwanese foundry utilization rates for early indicators of forecast revision triggers. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Smart Battery Charger Market
Batteries
Asia Pacific Electric Vehicle VRLA Batteries Market
Batteries
Inverter Battery Market
Batteries
ASEAN Countries Electric Vehicle Battery Electrolyte Market
Batteries
GCC Rechargeable Battery Market
Batteries
US Motive Lead Acid Battery Market
Batteries
Middle East and Africa SLI Battery Market
Batteries
Battery Cell Market
Batteries
Seawater Battery Market
Batteries
Thin Film and Printed Battery Market
Batteries
Portable Battery Market
Batteries
Taiwan Battery Market
Batteries
Europe Battery Systems for Electric Vehicles Market
Batteries
Lithium Starters Market
Batteries
Atomic Battery Market
Batteries
North Europe Battery Market