
 Industrial Backup Battery Market | 2026-2036
Industrial Backup Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Backup Battery Market Insights
Data center operators is consolidating as the dominant buyer class for industrial backup batteries, displacing traditional manufacturing plant procurement. CATL leverages its cell-to-pack architecture to capture scale advantages in lithium-ion systems. EnerSys anchors North American distribution through its deep channel presence in motive power and reserve applications. Panasonic competes on cylindrical cell reliability for mission-critical installations.
An industrial backup battery stores electrochemical energy to deliver instantaneous power during grid interruption, typically rated for discharge durations from 15 minutes to 8 hours depending on chemistry and load profile. Lithium-ion chemistry dominates new capacity additions due to superior energy density and cycle life versus legacy alternatives. Lead-acid retains residual share in cost-sensitive telecommunications applications where weight and footprint constraints remain secondary. Flow battery technology occupies emerging niches in renewable energy storage pairing where duration requirements exceed four hours.
FCC certification governs electromagnetic compatibility for battery management systems in telecommunications deployments, while EPA hazardous waste rules constrain lead-acid end-of-life processing costs. OSHA electrical safety standards mandate specific installation protocols for on-site industrial battery rooms, shaping contractor qualification requirements. Stakeholders must monitor evolving UL 9540 fire safety testing protocols as lithium-ion energy densities climb and insurers tighten coverage terms.
Market Dynamics
The lithium-ion chemistry transition is compressing lead-acid's installed base as data center operators demand higher energy density for rack-constrained facilities. This chemistry shift reconfigures supplier economics, certification requirements, and end-user procurement criteria across the industrial backup battery sector.
Growth Catalysts
- EPA Emissions Rules:Stringent hazardous waste regulations on lead-acid battery recycling are accelerating facility upgrades toward lithium-ion alternatives in United States industrial plants.
- Data Center Buildouts:Hyperscale cloud infrastructure expansion is creating concentrated demand for 15-minute to 4-hour discharge systems in Northern Virginia, Frankfurt, and Singapore clusters.
- Cell-to-Pack Architecture:Simplified battery assembly designs are reducing system costs and enabling faster installation cycles for mission-critical power applications.
Market Restraints
- Lithium Supply Concentration:Cathode material processing depends heavily on Chinese refining capacity, exposing battery assemblers to geopolitical supply disruptions and export control risks.
- UL 9540 Certification Timeline:Fire safety testing protocols for high-density lithium-ion systems extend product qualification cycles by 6-12 months versus legacy chemistries.
- Flow Battery Duration Competition:Vanadium redox systems are capturing 4-hour-plus discharge applications in renewable pairing installations where cycle life economics favor aqueous chemistry.
Strategic Opportunities
- India Manufacturing Incentives:PLI scheme subsidies for advanced chemistry cell production are attracting module assembly investments to serve domestic data center and telecom growth.
- Second-Life Automotive Cells:Repurposed electric vehicle batteries are entering 2-4 hour industrial backup applications at 40-60% cost of new lithium-ion systems.
- Direct Utility Procurement:Grid-scale battery tenders by independent system operators are opening new volume channels beyond traditional facility-level sales.
Industry Challenges
- Battery Management System Integration:Legacy SCADA infrastructure in manufacturing plants requires costly retrofitting to communicate with lithium-ion state-of-charge algorithms.
- Thermal Runaway Containment Engineering:Fire suppression system redesigns for lithium-ion energy densities are stretching mechanical engineering talent pools and extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Backup Battery Market |
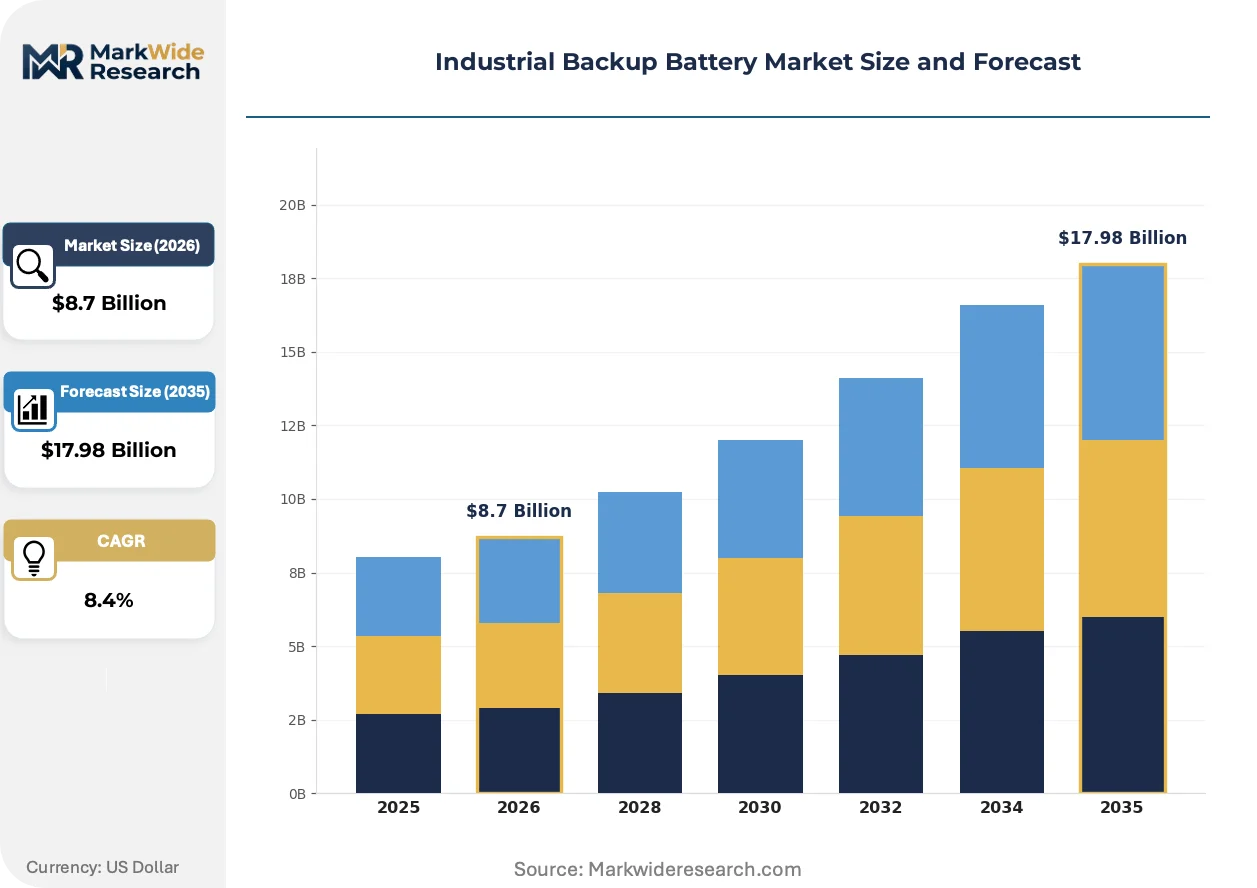
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead Acid, Lithium-Ion, Nickel-Cadmium, Flow Battery Application: Uninterruptible Power Supply, Renewable Energy Storage, Telecommunications, Data Centers End User: Manufacturing Plants, Healthcare Facilities, Telecommunications Providers, Utilities Installation: On-Site, Off-Site, Integrated Solutions, Modular Systems |
| Companies Covered | Panasonic, EVE Energy, CATL, EnerSys, Sungrow, BYD, Samsung SDI, Huawei Digital Power, LG Energy Solution, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Backup Battery Market Trends and Innovations
Solid-state electrolyte development and artificial intelligence-enabled predictive maintenance are converging to redefine reliability benchmarks and operational cost structures in industrial backup power systems.
Solid-state lithium-metal batteries are absorbing the premium segment of mission-critical installations where thermal stability and energy density constraints currently limit conventional lithium-ion deployment. Medical device manufacturers and financial trading facilities are piloting these systems for sub-15-minute discharge requirements. The technology is absorbing market share from nickel-cadmium legacy systems in European aerospace ground power applications.
OSHA electrical safety standards are mandating arc-flash hazard analysis and specific battery room ventilation protocols for lithium-ion installations above 50 kWh capacity. Industrial facility managers must now engage qualified electrical contractors for compliance documentation. German chemical processing plants are responding by consolidating battery assets into dedicated energy storage buildings rather than distributed mechanical rooms.
Power-as-a-service contracting is displacing capital purchase models for mid-sized manufacturing facilities seeking to offload battery monitoring and replacement liability. Third-party operators retain asset ownership and charge availability-based fees tied to uptime guarantees. This model is expanding fastest in United States food processing and cold storage verticals where operational continuity outweighs balance sheet preferences.
Industrial Backup Battery Market Segmentation
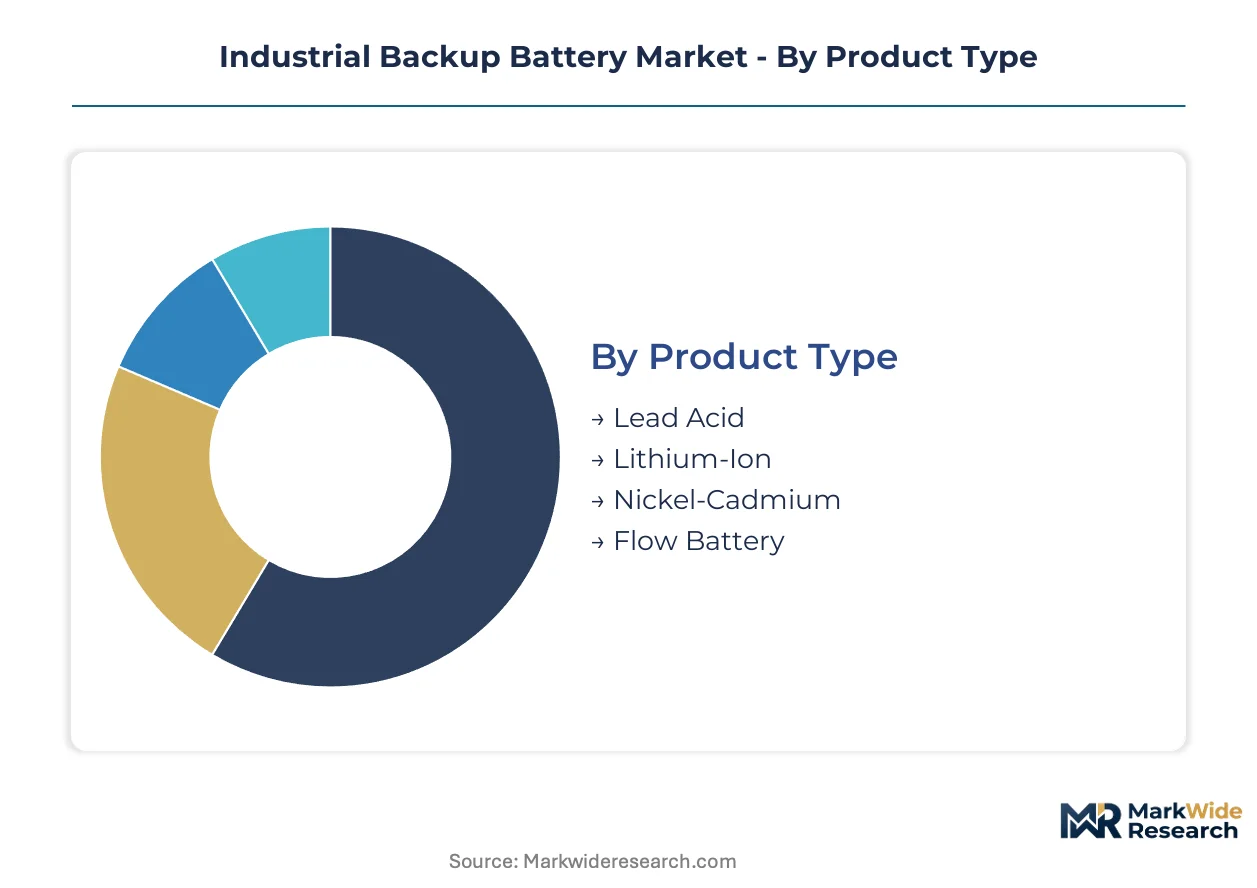
Industrial backup battery procurement varies sharply across chemistry, application, and deployment models. Each segment carries distinct certification burdens, installation protocols, and lifecycle cost profiles that reshape supplier-customer relationships.
Product Type:
UL 9540 fire safety testing applies differentially across chemistries, with lithium-ion systems facing extended qualification timelines versus legacy alternatives. EPA hazardous waste rules constrain lead-acid end-of-life processing costs in United States facilities.
- Lithium-Ion:Cell-to-pack architectures deliver superior energy density for rack-constrained data centers in Northern Virginia and Frankfurt clusters. CATL and Panasonic compete on cylindrical cell reliability as hyperscale operators consolidate procurement around 15-minute to 4-hour discharge systems.
- Lead Acid:Flooded and valve-regulated designs retain residual share in cost-sensitive telecommunications applications where weight constraints remain secondary. United States manufacturing plants face accelerating EPA emissions compliance costs that compress residual deployment economics.
- Nickel-Cadmium:Aviation ground power and cold-weather industrial sites in Germany leverage the chemistry's temperature resilience.
- Flow Battery:Vanadium redox systems capture 4-hour-plus renewable pairing installations where aqueous chemistry cycle life economics favor duration over density.
Leading the category by volume: Lithium-Ion. Expanding most quickly: Flow Battery.
Application:
Customer procurement criteria diverge by uptime requirements, with financial trading facilities demanding sub-15-minute response versus renewable integrators prioritizing multi-hour duration.
- Data Centers:Hyperscale cloud infrastructure in Singapore and Northern Virginia drives concentrated demand for high-density lithium-ion systems. Operators specify cell-to-pack architectures to minimize footprint in mechanically constrained facilities.
- Uninterruptible Power Supply:Manufacturing plants in Germany deploy integrated battery-inverter systems for seamless load transfer during grid interruption. OSHA electrical safety standards mandate arc-flash hazard analysis for installations above 50 kWh capacity.
- Telecommunications:Tower operators in India prioritize cost-optimized lead-acid for rural electrification gaps.
- Renewable Energy Storage:Utility-scale solar pairing in China favors flow battery duration economics over lithium-ion cycling degradation.
Dominant by deployment scale: Data Centers. Steepest expansion trajectory: Renewable Energy Storage.
End User:
Facility managers balance capital constraints against operational continuity requirements, with healthcare and cold storage verticals prioritizing uptime guarantees over balance sheet preferences.
- Telecommunications Providers:Tower infrastructure operators in India and Southeast Asia consolidate procurement around modular lithium-ion systems under PLI scheme manufacturing incentives. TRAI spectrum auction timelines accelerate backup power deployment cycles.
- Manufacturing Plants:German chemical processing facilities respond to OSHA-equivalent safety protocols by consolidating battery assets into dedicated energy storage buildings rather than distributed mechanical rooms.
- Healthcare Facilities:United States hospitals specify nickel-cadmium for surgical suite backup where thermal stability outweighs energy density.
- Utilities:Independent system operators in Texas and California issue grid-scale battery tenders opening volume channels beyond facility-level sales.
Highest procurement concentration: Telecommunications Providers. Gaining share fastest: Utilities.
Installation:
Project delivery models are bifurcating between capital ownership and availability-based contracting, with power-as-a-service gaining traction among mid-sized facilities.
- Integrated Solutions:Turnkey battery-inverter-thermal management packages dominate data center deployments in Frankfurt and Singapore where engineering talent scarcity stretches project timelines. Contractors must document OSHA compliance for arc-flash and ventilation protocols.
- Modular Systems:Containerized lithium-ion skids enable rapid deployment for manufacturing plants seeking to bypass on-site construction delays. German automotive suppliers pilot these configurations for production line continuity.
- On-Site:Legacy manufacturing facilities in United States industrial belts retain distributed battery rooms requiring SCADA retrofitting.
- Off-Site:Co-located utility-scale installations in Texas ERCOT territory separate generation assets from load centers.
Preferred by revenue scale: Integrated Solutions. Climbing the fastest: Modular Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Northern Virginia's data center corridor concentrates lithium-ion procurement as Loudoun County tax incentives attract hyperscale operators. Frankfurt and Singapore clusters mirror this concentration. EPA emissions rules in the United States, EU Green Deal carbon targets, and China's dual carbon goals are reshaping deployment patterns across major industrial zones.
United States
Data center buildouts in Northern Virginia and Dallas-Fort Worth drive concentrated demand for 15-minute to 4-hour discharge systems. EPA hazardous waste regulations on lead-acid battery recycling accelerate facility upgrades toward lithium-ion alternatives. OSHA electrical safety standards mandate arc-flash hazard analysis for installations above 50 kWh capacity in California and Texas industrial belts.
Germany
Automotive suppliers in Bavaria and Baden-Württemberg pilot modular lithium-ion systems for production line continuity. EU Green Deal carbon border adjustments tighten supply chain emissions disclosure requirements for battery imports. Frankfurt's data center cluster specifies cell-to-pack architectures to minimize footprint in mechanically constrained facilities.
China
Utility-scale solar pairing in the Yangtze River Delta favors flow battery duration economics over lithium-ion cycling degradation. MIIT industrial standards and dual carbon goals accelerate phase-out of lead-acid in manufacturing plants. Shenzhen and Shanghai data center operators consolidate procurement around domestic lithium-ion cell production.
India
Telecommunications tower operators in Maharashtra and Karnataka prioritize cost-optimized systems for rural electrification gaps. PLI scheme subsidies for advanced chemistry cell production attract module assembly investments. TRAI spectrum auction timelines accelerate backup power deployment cycles in Delhi-NCR and Tamil Nadu clusters.
Singapore
Hyperscale cloud infrastructure expansion creates concentrated demand for high-density lithium-ion systems in the Jurong and Tuas data center zones. The city-state's carbon pricing mechanism and green building standards constrain lead-acid deployment in new facilities. Operators specify integrated battery-inverter-thermal management packages to bypass engineering talent scarcity.
Industrial Backup Battery Market Competitive Landscape
Top-tier vendors anchor premium-tier lithium-ion supply, while mid-scale assemblers occupy cost-optimized segments. The market structure bifurcates between cell manufacturers with captive chemistry control and system integrators dependent on external supply. Two strategic archetypes dominate: chemistry-specialized producers leveraging vertical integration, and application-focused integrators competing on installation speed and service density. Capacity expansion and strategic technology licensing represent the dominant competitive moves as participants race to secure cathode material processing agreements.
Among Asia-Pacific cell producers, CATL and BYD exemplify the chemistry-specialized archetype through their integrated manufacturing positions. Panasonic occupies a position bridging premium cylindrical cell supply and established distribution channels in mission-critical installations. EnerSys anchors the system integrator tier through its North American channel presence across motive power and reserve applications.
| Leading Market Players |
|---|
| Panasonic |
| EVE Energy |
| CATL |
| EnerSys |
| Sungrow |
| BYD |
| Samsung SDI |
| Huawei Digital Power |
| LG Energy Solution |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed Chinese producers anchor cathode material processing, concentrating supply-side pricing power while compressing margins for non-integrated assemblers in United States and European markets. This ownership pattern feeds through to project-level pricing as battery management system integration costs and UL 9540 certification timelines inflate quoted system prices for data center operators.
Pricing Analysis
Premium pricing attaches to sub-90-day lead time deliveries for lithium-ion systems serving hyperscale data center buildouts in Northern Virginia and Frankfurt, while spot inventory of lead-acid alternatives trades at steep discounts in saturated telecommunications channels. Three-tier pricing structure across premium, standard, and economy levels separates UL 9540-certified lithium-ion systems from IEC-compliant mid-tier offerings and uncertified economy-grade lead-acid units. Cost compression in the economy tier is intensifying because second-life automotive cells are entering at 40-60% cost of new lithium-ion systems. Manufacturing plants in Germany exhibit highest price sensitivity due to capital constraints, while financial trading facilities in Singapore absorb premium pricing for sub-15-minute discharge reliability.
Supply Chain Analysis
Reverse-logistics flows for end-of-life lead-acid batteries are tightening as EPA hazardous waste rules constrain United States recycling capacity and elevate processing costs for industrial facility managers. Cathode material processing draws from Chinese refining concentration, South Korean precursor chemical production, and Australian spodumene concentrate exports. Lithium carbonate and nickel sulfate feedstock dependencies expose assemblers to commodity price volatility. Single-source vulnerability concentrates in Chinese cathode active material supply. Distribution runs through North American motive power channels anchored by EnerSys, Asian direct-procurement relationships for cell supply, and European system integrator networks serving automotive suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA electrical safety standards and UL 9540 fire safety protocols are erecting compliance moats that favor capital-rich incumbents with dedicated certification engineering teams and documented installation track records.
For Market Incumbents: Lock in long-term cathode material offtake agreements with Chinese refiners before export control tightening accelerates. Expand captive cell-to-pack assembly capacity in India under PLI scheme subsidies to serve accelerating data center and telecom demand. Second-life automotive cell competition and flow battery duration capture in 4-hour-plus renewable applications represent the most pressing substitution threats requiring monitoring. For New Entrants and Emerging Players: Mid-sized United States food processing and cold storage facilities seeking power-as-a-service contracting present the most penetrable buyer archetype for availability-based revenue models without capital sales friction. Target German automotive suppliers piloting modular containerized systems for production line continuity. Enter through third-party operator partnerships that retain asset ownership and charge uptime-linked fees. For Investors and Strategic Acquirers: Accelerating utility-scale battery tender issuance by Texas ERCOT and California ISO operators is the leading indicator that direct procurement channels are maturing beyond facility-level sales. Position for 5-10 year horizon consolidation around chemistry-specialized producers with backward integration into cathode processing and system integrators with dense North American service networks. Monitor PLI scheme subsidy disbursement timelines in India as inflection signal for manufacturing cost competitiveness shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Cathode Material Offtake Agreement | Secures supply continuity against Chinese export control escalation for United States assemblers. |
| Cell-to-Pack Assembly Capacity Expansion | Reduces system costs and installation cycles for rack-constrained Northern Virginia data centers. |
| Second-Life Automotive Cell Sourcing Partnership | Enters 2-4 hour industrial backup applications at 40-60% cost of new lithium-ion systems. |
| Power-as-a-Service Contracting Model Launch | Captures mid-sized manufacturing facilities prioritizing uptime guarantees over balance sheet ownership. |
| UL 9540 Fire Safety Certification Investment | Unlocks insurer coverage and hyperscale operator procurement qualification for high-density lithium-ion deployments. |
Research Methodology
Document review covered SEC 10-K filings from publicly traded battery manufacturers, EPA hazardous waste enforcement records, OSHA electrical safety standard interpretations, and FERC grid-scale battery interconnection queues, complemented by interviews with data center engineering directors, industrial facility maintenance managers, EPC contractors specializing in energy storage integration, and telecommunications tower infrastructure procurement leads. Secondary validation drew from customs trade data, MIIT industrial standard publications, and PLI scheme disbursement records. Bottom-up project pipeline aggregation and top-down macroeconomic driver modeling were cross-referenced for triangulation.
Historical deployment trajectories were cross-referenced against panel input from industry stakeholders to derive expansion assumptions across the projection horizon. Segmentation dimensions modeled include chemistry type, application discharge duration, installation delivery model, and regional regulatory framework cluster. CAGRs were synthesized from unit volume buildups and value-per-unit trends. Forecast inputs incorporated hyperscaler capex disclosure patterns, spectrum auction timelines from TRAI, and carbon pricing mechanism adoption curves.
Revisions become necessary when EPA emissions rules tighten lead-acid recycling cost structures, Chinese export controls disrupt cathode material flows, or solid-state electrolyte commercialization accelerates beyond pilot deployment timelines. Practitioners should monitor OSHA arc-flash hazard analysis mandate enforcement, UL 9540 testing protocol updates, and utility-scale battery tender award velocities for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Battery Wash System Market
Batteries
Cobalt-Free Battery Market
Batteries
Rear Rack Battery Market
Batteries
South America Consumer Battery Market
Batteries
Valve Regulated Lead-Acid (VRLA) Batteries Market
Batteries
Home Inverter Battery Market
Batteries
West Africa Battery Market
Batteries
Lead Acid Battery Market
Batteries
Europe Automotive Lead-Acid Battery Market
Batteries
Global Primary Cells Market
Batteries
France Rechargeable Battery Market
Batteries
Lithium-Fluorinated Graphite Batteries Market
Batteries
Atomic Battery Market
Batteries
Myanmar Battery Market
Batteries
Bio Based Battery Market
Batteries
Battery Binders Market