
 Solar UPS Market | 2026-2036
Solar UPS Market Size, Share, and Industry Trends Forecast 2026-2036
Solar UPS Market Insights
Hybrid inverter architecture is tilting Solar UPS design toward unified power conversion and battery management. Growatt leverages its residential inverter heritage to compete in compact solar UPS units for home energy security. SMA anchors its position through German-engineered grid-forming inverters that sustain critical loads during extended outages. Sungrow extends its utility-scale battery expertise into commercial UPS systems with high-voltage DC coupling.
Solar UPS systems combine photovoltaic arrays with uninterruptible power supply circuitry to deliver conditioned backup electricity during grid failures, typically operating at DC bus voltages between 48V and 1500V depending on scale. The primary purpose is bridging solar generation intermittency with seamless load protection for sensitive equipment. Hybrid UPS product types dominate margin pools where solar charging, grid input, and battery backup converge in single enclosures. Data center end users represent the fastest-growing demand segment as hyperscalers mandate renewable-backed redundancy for server farms.
India's BIS certification requirements and China's GB standards for solar inverter safety shape product compliance costs for manufacturers serving Asia. The EU Green Deal and F-Gas Regulation are forcing refrigerant-free thermal management in UPS battery enclosures across European markets. Stakeholders must monitor how grid interconnection rules in multiple jurisdictions redefine allowable export limits for solar UPS systems feeding surplus power back to utilities.
Market Dynamics
Data center operators are mandating renewable-backed redundancy, forcing solar UPS architectures to absorb higher power densities and faster switching speeds than traditional battery-only systems.
Growth Catalysts
- Hyperscaler procurement mandates:Cloud providers now require solar-hybrid backup for server farms, creating guaranteed demand pools for high-capacity UPS systems.
- India's PLI scheme:Domestic manufacturing incentives are accelerating local inverter assembly and reducing import dependency for battery management systems.
- Silicon carbide semiconductors:Wide-bandgap devices enable higher switching frequencies, shrinking converter footprints and improving conversion efficiency in compact units.
Market Restraints
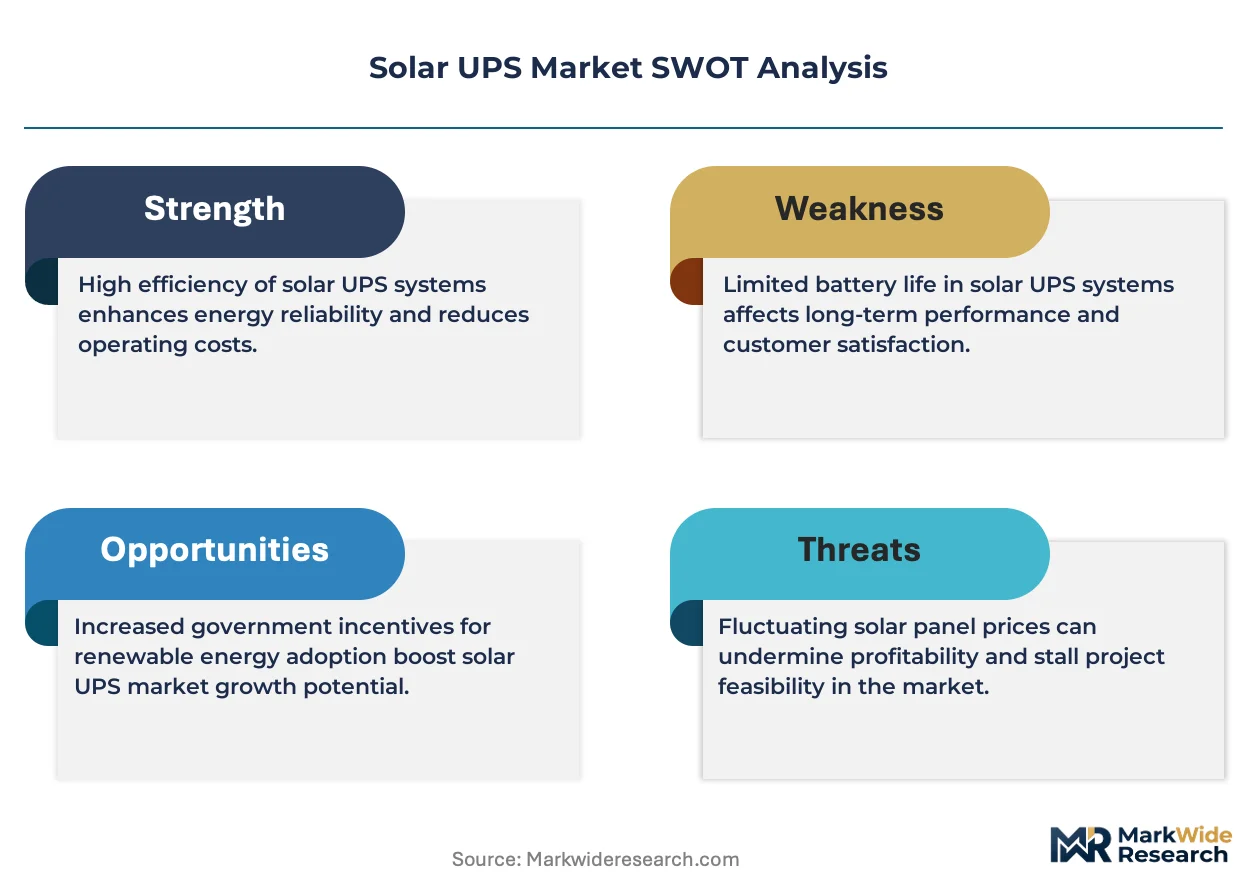
- Lithium price volatility:Battery cell costs swing with cobalt and nickel spot markets, compressing margins on fixed-price UPS contracts.
- Chinese supply concentration:Integrated PV-storage component manufacturing clusters in Jiangsu and Anhui create single-source vulnerability for non-domestic assemblers.
- Grid interconnection delays:Utility approval timelines for export-capable solar UPS systems stretch 18-24 months in multiple jurisdictions.
Strategic Opportunities
- Rural electrification in Nigeria:Off-grid commercial facilities seek solar UPS as primary power, bypassing unreliable utility infrastructure entirely.
- EU F-Gas Regulation:Refrigerant-free thermal management mandates are opening retrofit markets for liquid-cooled battery enclosures.
- Edge computing convergence:Micro data centers collocated with 5G infrastructure require sub-100kVA solar UPS with integrated DC fast-charging ports.
Industry Challenges
- Power electronics talent scarcity:Design engineers with combined PV inverter and battery management expertise command premium compensation, constraining R&D expansion.
- Multi-standard certification burden:Simultaneous UL 1741, IEC 62040, and BIS IS 16221 compliance testing extends product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar UPS Market |
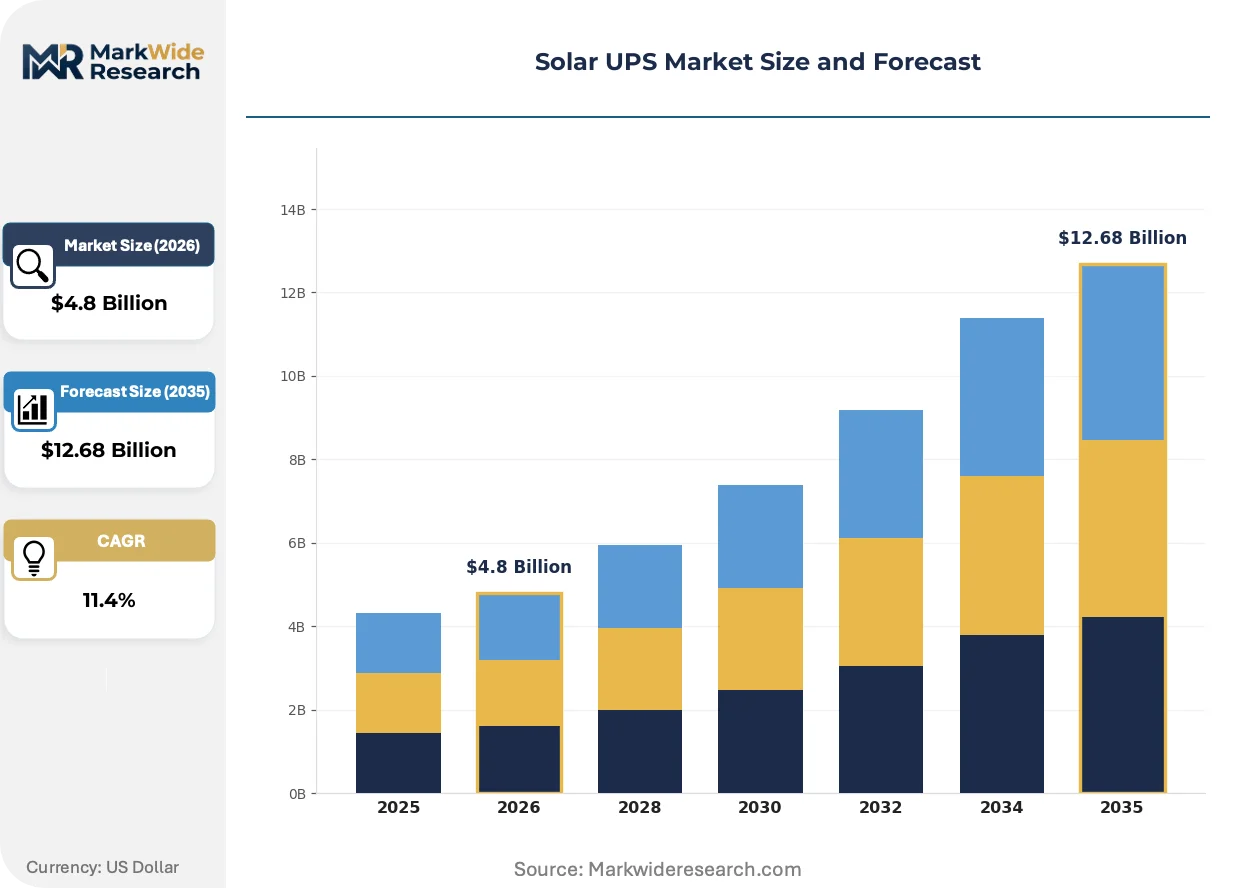
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Online UPS, Offline UPS, Line-Interactive UPS, Hybrid UPS End User: Households, Commercial Buildings, Industrial Facilities, Data Centers Technology: Solar PV, Battery Storage, Inverter Technology, Control Systems Installation Type: Grid-Tied, Off-Grid, Portable, Stand-Alone |
| Companies Covered | Growatt, SMA, Luminous, Trina Solar, Enphase, Sungrow, GoodWe, Jinko Solar, Huawei Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar UPS Market Trends and Innovations
Digital twin architectures are compressing development cycles and enabling predictive maintenance models that shift service revenue from reactive repairs to uptime guarantees.
Software-defined power conversion is virtualizing hardware functions across solar UPS fleets. Data center operators deploy centralized control planes that orchestrate thousands of edge units as unified resources. This architecture is virtualizing traditional standalone inverter management, collapsing maintenance overhead and enabling fleet-wide optimization.
REACH substance restrictions and the EU F-Gas Regulation are banning specific thermal interface materials and refrigerants in battery enclosures. Manufacturers are redesigning thermal stacks around phase-change materials and liquid cooling loops. European commercial installations face the tightest compliance deadlines, accelerating supplier qualification processes.
Leasing structures are displacing capital purchases for commercial solar UPS deployments. Energy-as-a-service providers own and operate systems, selling guaranteed uptime contracts to retail and healthcare facilities. This model concentrates fastest in Germany and California, where high electricity rates make operational expenditure structures attractive to CFOs seeking balance sheet efficiency.
Solar UPS Market Segmentation
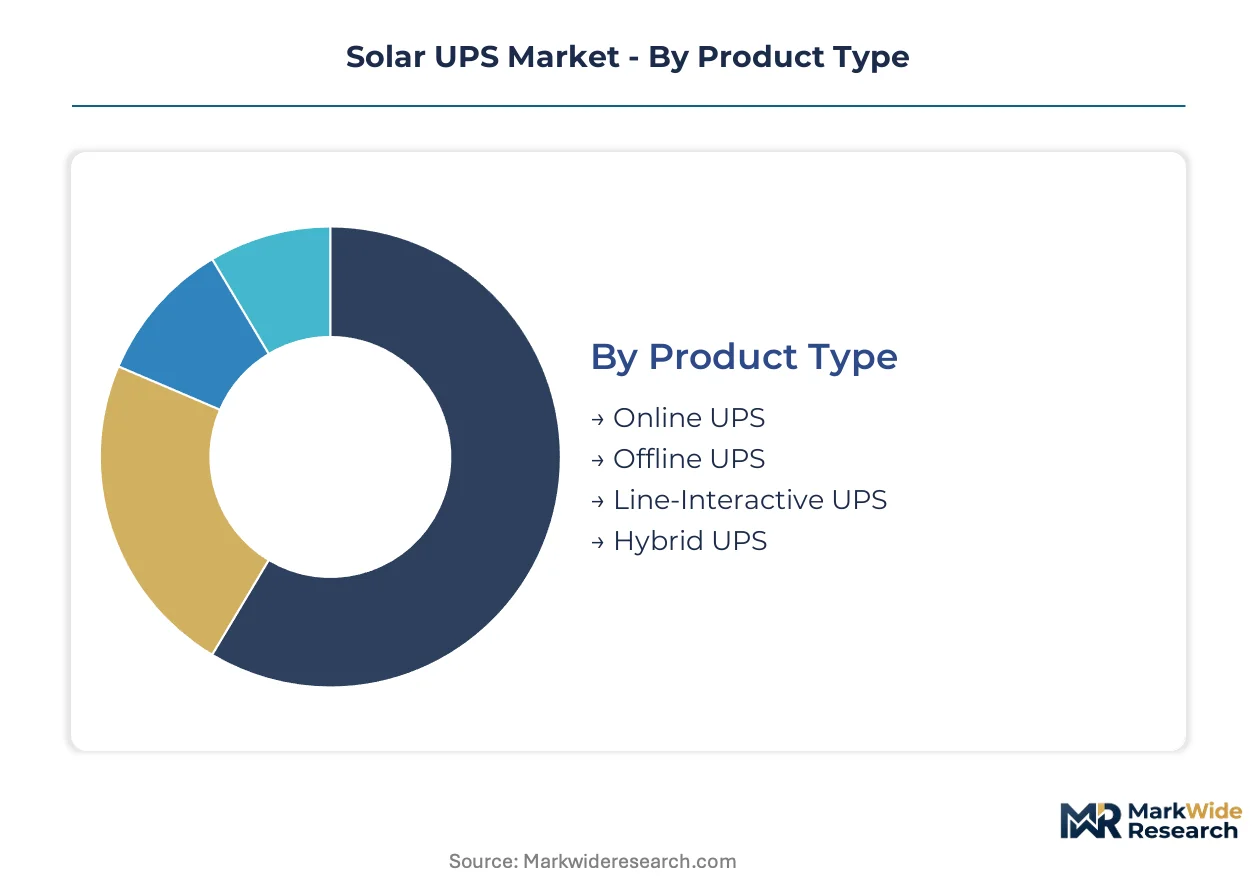
Solar UPS architectures diverge sharply across power conditioning topologies, deployment contexts, and integration depth with photovoltaic generation. Understanding these segment boundaries clarifies where margin pools concentrate and which technical specifications dominate procurement criteria.
Product Type:
Power conditioning architectures span a spectrum from continuous double-conversion to standby switching, with hybrid designs now absorbing the most engineering investment.
- Hybrid UPS:Unified enclosures merge solar charge controllers, battery management, and grid-forming inverters into single power conversion stacks. Data center operators in Virginia and Frankfurt now mandate these configurations for renewable-backed redundancy contracts.
- Online UPS:Double-conversion topology delivers zero transfer time through continuous AC-DC-AC processing, essential for semiconductor fabrication and medical imaging equipment. German industrial facilities anchor demand despite efficiency penalties versus hybrid alternatives.
- Offline UPS:Standby switching engages battery paths only during grid anomalies, minimizing conversion losses for cost-sensitive residential deployments in Indian tier-2 cities.
- Line-Interactive UPS:Tap-changing transformers regulate voltage without full conversion, dominating Southeast Asian commercial installations where grid stability fluctuates seasonally.
The dominant share belongs to Hybrid UPS, while Line-Interactive UPS is closing the gap fastest in emerging markets with constrained capital budgets.
End User:
Demand intensity correlates with outage cost exposure and sustainability disclosure requirements.
- Data Centers:Hyperscalers in Ashburn, Dublin, and Singapore now specify solar-hybrid backup with sub-10ms transfer times for AI training clusters. Microsoft's renewable procurement mandates have normalized 100% solar-backed redundancy as a baseline requirement.
- Industrial Facilities:Continuous process industries—petrochemical, pharmaceutical, semiconductor—prioritize ride-through capacity measured in hours rather than minutes. Texas chemical plants drove early adoption of high-voltage DC coupling architectures.
- Commercial Buildings:Retail and healthcare facilities in California and Germany favor leased solar UPS under energy-as-a-service contracts, transferring capital risk to specialized operators.
- Households:German and Australian residential markets concentrate demand for compact 5-15kVA units with integrated EV charging ports, though absolute volumes trail commercial segments.
Data Centers command the steepest expansion trajectory, while Commercial Buildings represent the most underpenetrated addressable base.
Technology:
Component-level innovation determines system efficiency, thermal footprint, and lifecycle service intervals.
- Battery Storage:Lithium iron phosphate chemistries displace lead-acid in commercial deployments above 50kVA, driven by cycle life advantages and BIS certification alignment in India.
- Inverter Technology:Silicon carbide power modules enable 99% peak efficiency and 50% volume reduction versus silicon IGBT equivalents, though sourcing constraints limit penetration to premium tiers.
- Solar PV:Module-level power electronics integration—optimizers and microinverters—complicates string inverter compatibility in retrofit UPS installations.
- Control Systems:Digital twin architectures and predictive maintenance algorithms now differentiate vendor offerings, shifting procurement criteria from hardware specifications to uptime guarantee terms.
Battery Storage absorbs the largest share of bill-of-materials value, though Inverter Technology is gaining differentiation weight fastest through wide-bandgap semiconductor transitions.
Installation Type:
Grid interconnection rules and load criticality dictate whether systems prioritize export revenue, autonomy duration, or mobility.
- Grid-Tied:Net-metering-enabled installations dominate German and Californian commercial markets, where export tariffs improve project economics. FERC Order 2222 compliance complexities extend commissioning timelines.
- Off-Grid:Nigerian and Kenyan commercial facilities bypass unreliable utility infrastructure entirely, treating solar UPS as primary power with diesel generators as tertiary backup.
- Stand-Alone:Remote telecommunications towers and mining camps require containerized systems with 72+ hour autonomy, specifying tropicalized enclosures and passive thermal management.
- Portable:Sub-5kVA wheeled units serve construction sites and disaster response, though margins compress against consumer power station competition from Shenzhen manufacturers.
Grid-Tied installations retain volume leadership, while Off-Grid configurations are expanding most quickly in markets with chronic utility underperformance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscaler procurement teams concentrate in jurisdictions with renewable energy mandates and favorable interconnection frameworks. Data center operators in Virginia, Frankfurt, and Singapore drive specification standards for solar-hybrid backup systems. Manufacturing clusters align with domestic content incentive zones.
United States
Virginia's data center corridor mandates solar-backed redundancy for new server farm approvals. FERC Order 2222 compliance complexities extend solar UPS commissioning timelines for export-capable installations. Ashburn and Loudoun County host the densest concentration of hyperscaler facilities specifying sub-10ms transfer hybrid systems.
Germany
Industrial facilities in Bavaria and Baden-Württemberg prioritize ride-through capacity for continuous process manufacturing. The EU F-Gas Regulation forces refrigerant-free thermal management redesigns for battery enclosures. Frankfurt anchors grid-forming inverter demand from colocation providers serving European cloud workloads.
China
Integrated PV-storage supply chains in Jiangsu and Anhui provinces lower unit costs for UPS manufacturers serving domestic and export markets. GB standards for solar inverter safety shape product compliance costs for manufacturers. Beijing-Tianjin-Hebei corridor concentrates utility-scale battery expertise migrating into commercial UPS systems.
India
Tier-2 cities drive cost-sensitive residential demand for offline UPS configurations with solar charging capability. The PLI scheme for domestic solar manufacturing accelerates local inverter assembly and reduces import dependency for battery management systems. Gujarat and Maharashtra host emerging inverter fabrication clusters serving African and Southeast Asian export markets.
Nigeria
Off-grid commercial facilities in Lagos and Abuja treat solar UPS as primary power infrastructure. Chronic utility underperformance drives bypass of grid interconnection entirely. Diesel generator tertiary backup remains common, though solar-battery systems capture expanding share of commercial power procurement budgets.
Solar UPS Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. The vendor base organizes around three strategic archetypes: residential inverter heritage brands extending into compact solar UPS, utility-scale battery specialists downstreaming into commercial power conditioning, and integrated PV manufacturers diversifying into power electronics. Dominant competitive moves include strategic partnerships with data center operators and capacity expansion into silicon carbide power module assembly.
Within the residential heritage tier, Growatt and SMA represent archetype extremes—Chinese manufacturing scale against German engineering positioning. Sungrow anchors the utility-scale downstreaming vector. These three exemplify how geographic origin and legacy segment concentration shape competitive posture without determining market share outcomes.
| Leading Market Players |
|---|
| Growatt |
| SMA |
| Luminous |
| Trina Solar |
| Enphase |
| Sungrow |
| GoodWe |
| Jinko Solar |
| Huawei Solar |
| Others |
Pricing and Supply Chain Analysis
Lithium price volatility on cobalt and nickel spot markets compresses margins on fixed-price UPS contracts while simultaneously widening spreads between premium silicon carbide-based systems and standard IGBT configurations. This commodity exposure forces manufacturers to index long-term supply agreements to London Metal Exchange benchmarks, reshaping procurement relationships across the value chain.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate commercial deployments above 100kVA, insulating integrators from cell cost swings while passing through volatility to data center operators. Price differentiation hinges on wide-bandgap semiconductor adoption and UL 1741-SA certification tier, with German-engineered grid-forming inverters commanding substantial premiums over Chinese alternatives. Pricing pressure intensifies in residential below-10kVA segments as Shenzhen manufacturers flood export markets with consumer power stations. Data center procurement teams exhibit lowest price sensitivity, prioritizing sub-10ms transfer guarantees over capital expenditure optimization.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for non-domestic assemblers sourcing power modules and battery management systems. Manufacturing gravity centers on Jiangsu and Anhui provinces for integrated PV-storage components, with South Korea and Japan anchoring premium silicon carbide substrate supply. Raw material dependencies span lithium hydroxide from Chile and Australia, refined cobalt from the Democratic Republic of Congo, and high-purity silicon wafers from Taiwan. Single-source vulnerability concentrates in wide-bandgap semiconductor foundry capacity. Distribution runs through EPC contractors and specialized energy-as-a-service providers rather than traditional electrical wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance algorithms and uptime guarantee contracts are expanding faster than hardware shipments, transforming vendor economics toward recurring service revenue. This service-attach opportunity rewards players who digitize fleet management before competitors commoditize power conversion hardware.
For Market Incumbents: Entrench position by acquiring silicon carbide packaging capabilities in-house, reducing dependency on single-source power module suppliers. Expand certified service networks in Virginia and Frankfurt data center corridors to capture predictive maintenance contracts. Counter emerging Chinese manufacturers through UL 1741-SA certification moats that delay competitor product launches by 8-14 months.
For New Entrants and Emerging Players: Build out rural electrification portfolios in Nigeria and Kenya where off-grid commercial facilities bypass utility infrastructure entirely. Target sub-100kVA edge computing deployments collocated with 5G infrastructure, a segment underserved by utility-scale incumbents. Lead with integrated DC fast-charging capability as standard configuration to differentiate against residential heritage brands.
For Investors and Strategic Acquirers: Digital-native power electronics specialists with software-defined control platforms present the most defensible acquisition targets against hardware commoditization. Frame long-term viability around 5-10 year service contract visibility rather than equipment shipment cyclicality. Monitor FERC Order 2222 implementation pace as inflection indicator for grid-tied solar UPS export economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Module Assembly | In-house packaging of wide-bandgap devices reduces supplier dependency and captures margin from 99% efficiency tiers. |
| Predictive Maintenance Platform | Digital twin architectures shift revenue from reactive repairs to guaranteed uptime contracts with data center operators. |
| Refrigerant-Free Thermal Redesign | EU F-Gas Regulation compliance opens retrofit markets for liquid-cooled battery enclosures in German industrial facilities. |
| Energy-as-a-Service Leasing Structure | Operational expenditure models attract California and German CFOs seeking balance sheet efficiency for commercial deployments. |
| Domestic Inverter Fabrication | India's PLI scheme incentives accelerate local assembly and reduce import dependency for battery management systems. |
Research Methodology
A spread of perspectives from data center procurement directors, EPC contractors, power electronics design engineers, and energy-as-a-service operators converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FERC filings, EIA project databases, IEA renewable energy reports, and customs trade data for PV-storage component flows. Bottom-up triangulation across installation type and end-use segment was cross-checked against top-down market sizing from power conversion equipment shipments.
Demand-supply balance framing anchored the forecast framework across the analysis window, with segmentation modeling spanning power conditioning topology, deployment scale, and regional regulatory cluster. CAGRs were derived from installed base growth rates and replacement cycle analysis rather than extrapolated from historical shipments. Industry-specific inputs included hyperscaler capex disclosure patterns and utility interconnection queue data for export-capable systems.
Practitioners should monitor lithium spot market volatility, Chinese export license adjustments, and FERC Order 2222 implementation pace for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Digital Power Utility Market
Power
Direct Current Power System Market
Power
Compact Substation Market
Power
Steam Turbine MRO Market
Power
Power Sled Market
Power
Wind Alarm Controller Market
Power
Solar Plants Controllers Market
Power
Canada Power Market
Power
Europe Solar Inverter Market
Power
Malaysia Power EPC Market
Power
Italy Power Market
Power
Asia-Pacific Power Purchase Agreement Market
Power
Smart PV Inverters Market
Power
Asia-Pacific Turbomachinery Control Systems Market
Power
Australia Power Market
Power
Marine Thermal Fluid Heaters Market