
 North America Gas Turbine Market | 2026-2036
North America Gas Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
North America Gas Turbine Market Analytics
Aging turbine technician cohorts is collapsing across the US and Canada as retirement outpaces apprenticeship pipelines. GE Vernova sustains manufacturing scale through its Greenville, South Carolina facility and aftermarket service network. Siemens Energy anchors European-origin technology leadership with hydrogen-capable turbine development for North American utilities. Mitsubishi Power Americas competes on combined cycle efficiency ratings and regional plant engineering capabilities.
North America gas turbines are rotating machinery systems that convert combustion energy into mechanical work through axial or centrifugal compressors, annular combustors, and multi-stage turbines operating at inlet temperatures exceeding 1,400°C, primarily serving electricity generation and mechanical drive applications. Combined cycle configurations command the dominant share of new capacity additions due to superior thermal efficiency above 60 percent, while open cycle units retain strategic value for grid peaking and emergency reserve. Natural gas fuel types underpin the installed base, though biofuel blending trials and hydrogen co-firing pilots are gaining traction among progressive operators.
EPA Clean Air Act enforcement and FERC interconnection rules shape emission limits and grid reliability obligations for turbine operators across the United States. Canadian provincial regulators and the US Department of Energy hydrogen hub program are accelerating technology roadmaps for low-carbon turbine fuels. Stakeholders must weigh capital allocation between new hydrogen-ready installations and lifecycle extension of existing assets.
Market Dynamics
EPA Clean Air Act enforcement is compressing the operational runway for legacy gas turbine fleets while hydrogen-ready retrofits absorb disproportionate capital allocation from North American utilities. This regulatory pressure vector is restructuring procurement timelines and vendor selection criteria across the region.
Growth Catalysts
- Grid Balancing Imperative:ERCOT interconnection queues in Texas are forcing utilities to install fast-ramp gas turbines to offset solar and wind intermittency. Peaking capacity contracts now prioritize sub-10-minute start capabilities.
- IRA Hydrogen Hub Funding:The US Department of Energy is channeling cost-sharing agreements toward hydrogen-capable turbine demonstrations. Regional clean hydrogen hubs in Texas and California are accelerating fuel-flexible combustion technology validation.
- LNG Export Infrastructure:Gulf Coast liquefaction terminals are expanding mechanical drive turbine installations for refrigeration compression. Cheniere and Venture Global facility expansions are concentrating demand in Louisiana and Texas.
Market Restraints
- Specialized Alloy Supply Concentration:Superalloy castings for hot gas path components depend on a limited supplier base concentrated in Schenectady, New York and Greenville, South Carolina. Single-source dependencies extend lead times for F-class and H-class turbine blades.
- NOx Emission Compliance Costs:EPA New Source Performance Standards are imposing selective catalytic retrofit obligations on pre-2010 installations. Compliance capital exceeds lifecycle extension economics for sub-100 MW units.
- Electrochemical Storage Substitution:Lithium-ion battery installations are capturing grid peaking contracts previously awarded to open-cycle gas turbines. ERCOT and CAISO markets are witnessing four-hour duration storage displace combustion peakers in interconnection queues.
Strategic Opportunities
- Alberta Carbon Capture Integration:Canadian provincial tax credits for CCUS are creating first-mover advantage for turbine operators pairing combined cycle plants with post-combustion capture. The Alberta Carbon Trunk Line offers established CO2 transport infrastructure.
- Industrial Cogeneration Revival:Petrochemical complexes in Texas and Louisiana are evaluating gas turbine-based combined heat and power for process steam and electricity. Dow and ExxonMobil Baytown facilities represent anchor demand for high-efficiency configurations.
- Green Hydrogen Co-firing:Progressive utilities in California and New York are piloting 30% hydrogen blends in existing D-class turbines. FERC interconnection rulemaking is creating tariff structures favorable to low-carbon fuel retrofits.
Industry Challenges
- Field Service Technician Shortage:GE Vernova and Siemens Energy are competing for a shrinking pool of combustion inspection specialists. Apprenticeship programs at Greenville Technical College and Houston Community College are failing to match retirement rates.
- Long-Lead Component Procurement:Hot gas path replacement schedules require 18-24 month advance ordering for transition pieces and stage 1 buckets. Supply chain synchronization with forced outage windows demands precision inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Gas Turbine Market |
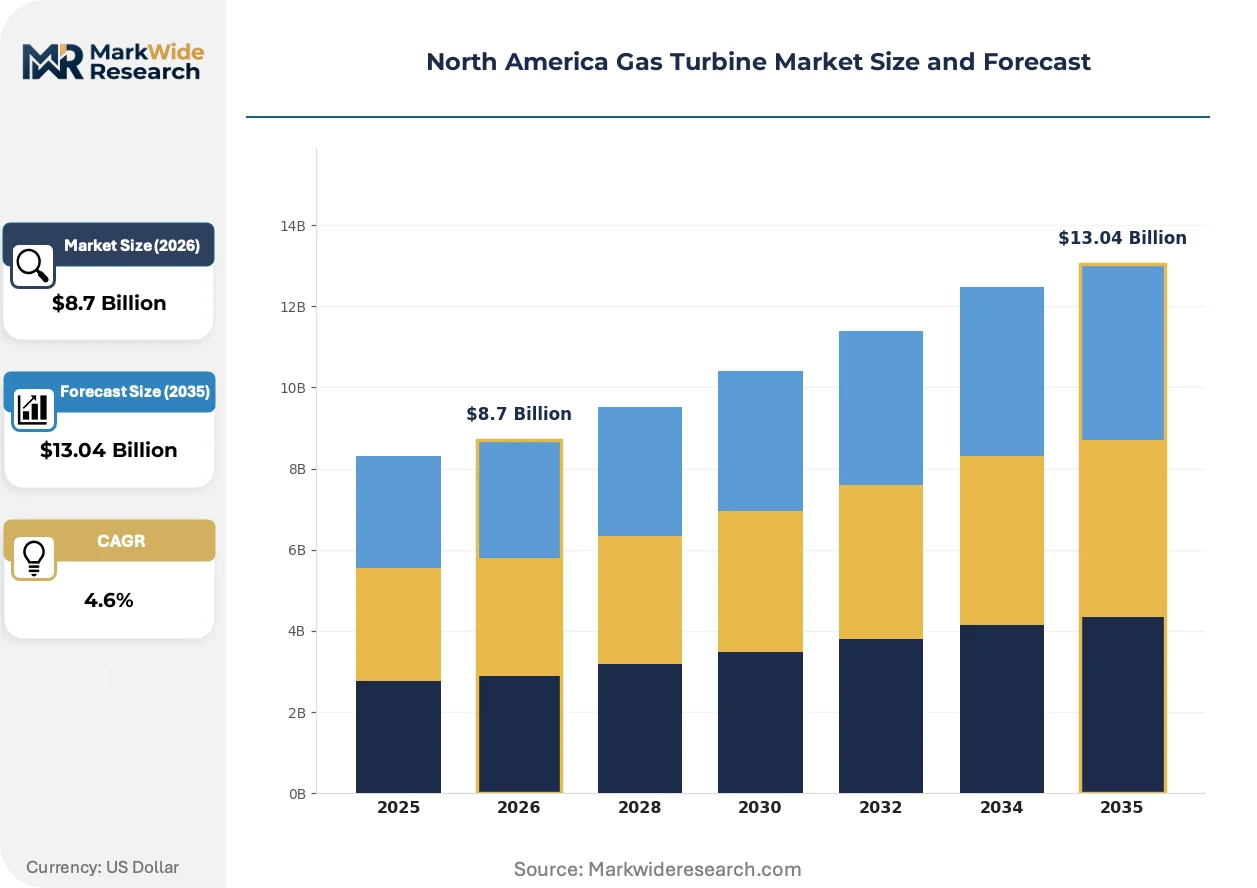
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Cycle, Combined Cycle, Industrial, Aerospace End User: Power Generation, Oil & Gas, Marine, Manufacturing Installation: Onshore, Offshore, Mobile, Stationary Fuel Type: Natural Gas, Diesel, Biofuel, Others |
| Companies Covered | GE Vernova, Siemens Energy, Mitsubishi Power Americas, Solar Turbines, Capstone Green Energy, Baker Hughes, Ansaldo Energia, Kawasaki Heavy Industries, MAN Energy Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Gas Turbine Market Evolving Landscape
Combustion technology roadmaps are pivoting from incremental efficiency gains toward fuel flexibility architectures. Equipment suppliers are repositioning around hydrogen readiness as the primary competitive differentiator.
Axial-radial hybrid compressor designs are supplanting conventional axial-only configurations in frame-type turbines. US utilities facing hydrogen blending mandates are specifying these compressors for their broader surge margin tolerance. The technology is supplanting legacy aerodynamic packages in new orders from Duke Energy and Southern California Edison.
EPA greenhouse gas performance standards for new stationary sources are mandating carbon capture readiness assessments for gas turbine projects exceeding 25 MW. Project developers are pre-positioning turbine pad and auxiliary space for future solvent-based capture integration. Combined cycle installations in Texas and Louisiana are most affected, with engineering firms incorporating stack bypass and absorber foundation provisions.
Power purchase agreement structures are unbundling long-term service agreements from equipment supply contracts. Independent power producers are negotiating aftermarket competition clauses that permit third-party maintenance during initial warranty periods. This behavioral shift is most visible in ERCOT merchant plants where operators prioritize operational flexibility over OEM exclusivity.
North America Gas Turbine Market Segmentation
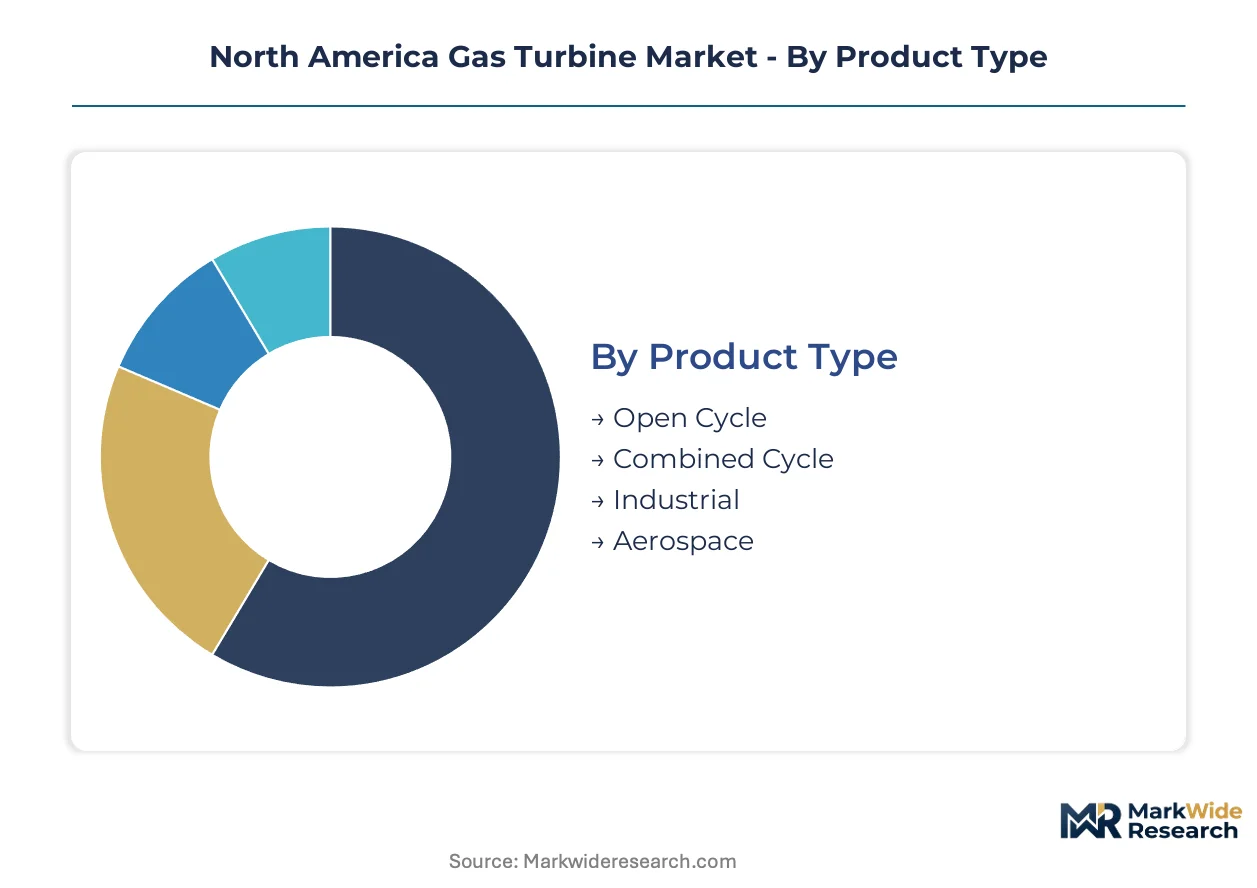
Gas turbine procurement in North America fragments across four distinct category hierarchies. Technology configuration, end-use application, installation environment, and fuel specification each reshape vendor selection criteria and lifecycle economics for operators from ERCOT merchant plants to Alberta oil sands facilities.
Product Type:
Margin pools concentrate in configurations offering thermal efficiency above 55 percent, where fuel savings compound across 30-year asset lives and service contracts extend into nine-figure territory.
- Combined Cycle:Integrated heat recovery steam generators capture exhaust thermal energy to drive secondary power generation. Duke Energy and Southern California Edison are prioritizing H-class configurations for baseload replacement, drawn by efficiency ratings exceeding 60 percent that compress fuel costs per megawatt-hour.
- Open Cycle:Aeroderivative and frame turbines deliver sub-10-minute start capabilities for grid peaking services. Texas utilities facing ERCOT intermittency challenges are installing F-class units for fast-ramp balancing against solar and wind output swings.
- Industrial:Heavy-duty mechanical drive turbines power compression and pumping applications. Gulf Coast LNG terminals specify these for refrigeration train duty cycles exceeding 8,000 annual operating hours.
- Aerospace:Modified aviation turbines serve distributed generation and mobile power roles. Military bases and remote mining camps in Alaska and northern Canada deploy these for rapid deployment and air-transport logistics.
Combined Cycle holds installed capacity. Open Cycle is rotating up the share rankings as grid balancing contracts displace pure baseload economics.
End User:
Application-specific duty cycles and reliability obligations fragment procurement specifications across four verticals with divergent operating profiles.
- Power Generation:Investor-owned utilities and independent power producers operate turbines for merchant and regulated electricity supply. PJM and ERCOT interconnection queues are concentrating new orders among operators seeking capacity market revenue and energy arbitrage.
- Oil & Gas:Upstream production and midstream processing facilities deploy turbines for mechanical drive and onsite power. Permian Basin operators and Alberta oil sands developers are specifying fuel-flexible units to hedge natural gas price volatility.
- Marine:LNG carriers and offshore supply vessels integrate aeroderivative turbines for propulsion and electrical generation. US-flagged Jones Act vessels and Canadian Arctic shipping routes drive specification for ice-class environmental tolerance.
- Manufacturing:Petrochemical complexes and steel mills utilize combined heat and power configurations. Dow Chemical and ExxonMobil Baytown facilities anchor demand for high-pressure steam extraction capabilities.
Power Generation dominates fleet megawatts. Oil & Gas is climbing the fastest as LNG export infrastructure accelerates mechanical drive procurement.
Installation:
Site constraints and mobility requirements reshape foundation engineering, acoustic treatment, and grid interconnection architecture.
- Onshore:Fixed installations at utility substations and industrial facilities constitute the majority of North American capacity. Texas and Louisiana project clusters concentrate demand where pipeline infrastructure and transmission access converge.
- Offshore:Platform-mounted turbines serve Gulf of Mexico oil production and emerging offshore wind integration hubs. Hurricane-rated enclosures and salt-air corrosion protection elevate capital intensity versus comparable onshore units.
- Mobile:Trailer-mounted aeroderivative packages provide emergency power and seasonal peak shaving. California utilities facing wildfire-related PSPS events are expanding rental fleets for grid resilience.
- Stationary:Permanent industrial installations with integrated heat recovery systems anchor combined cycle economics. Alberta carbon capture retrofit projects favor these configurations for post-combustion solvent integration.
Onshore retains the dominant footprint. Mobile is expanding most quickly as climate resilience procurement reshapes utility contingency planning.
Fuel Type:
Combustion system specifications and emissions profiles diverge sharply across fuel categories, with hydrogen readiness emerging as a decisive procurement filter.
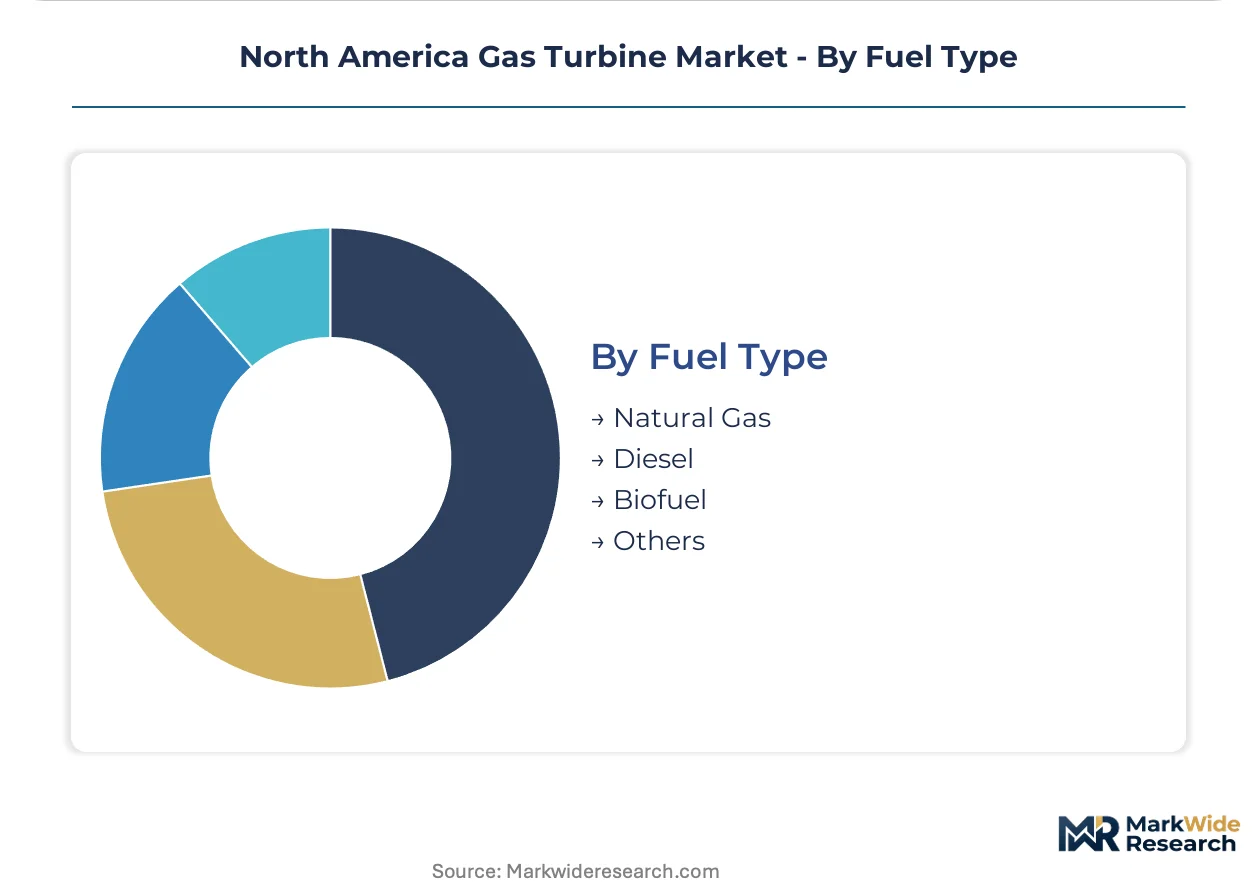
- Natural Gas:Pipeline-delivered methane underpins the installed base with established supply infrastructure and combustion stability. EPA New Source Performance Standards are tightening NOx limits for new installations, favoring dry low-NOx combustor designs.
- Diesel:Liquid fuel backup capability provides operational continuity during gas supply interruptions. Remote mining and military applications in northern Canada specify these for supply chain independence from pipeline networks.
- Biofuel:Renewable liquid and gaseous fuels from agricultural and waste feedstocks qualify for state-level low-carbon fuel standards. California LCFS credits are driving pilot blending trials at Sacramento Municipal Utility District facilities.
- Others:Hydrogen, synthetic methane, and ammonia combustion trials are advancing through DOE hub funding. Texas and California clean hydrogen hubs are validating 30 percent hydrogen blends in existing D-class turbine architectures.
Natural Gas commands the installed base. Others is gaining share fastest as IRA hydrogen hub disbursements accelerate fuel-flexible combustion technology validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Clean Air Act enforcement is compressing operational timelines for aging turbine fleets across the United States. FERC interconnection rules and IRA hydrogen hub funding are reshaping procurement patterns from Texas to Alberta.
United States
ERCOT interconnection queues in Texas are forcing utilities to install fast-ramp gas turbines for solar and wind balancing. The Department of Energy is channeling cost-sharing agreements toward hydrogen-capable turbine demonstrations through regional clean hydrogen hubs. Gulf Coast liquefaction terminals in Louisiana and Texas are expanding mechanical drive installations for refrigeration compression.
Canada
Provincial tax credits for carbon capture utilization and storage are creating first-mover advantage for combined cycle operators. Alberta's Carbon Trunk Line offers established CO2 transport infrastructure for post-combustion capture integration. Oil sands facilities in northern Alberta are specifying fuel-flexible units to hedge natural gas price volatility.
Mexico
Power sector liberalization is attracting independent power producers to combined cycle installations near pipeline corridors. Federal electricity commission interconnection standards are tightening grid reliability obligations for new capacity. Industrial clusters in Nuevo León and the Bajío Region are evaluating cogeneration for process steam and electricity supply.
North America Gas Turbine Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America gas turbine market. The vendor base concentrates around full-service OEMs with manufacturing scale and aftermarket networks, while specialized fabricators occupy niche efficiency segments. Two strategic archetypes dominate: integrated power equipment conglomerates with hydrogen-ready development pipelines, and aeroderivative specialists serving mobile and distributed generation roles. Competitive moves center on strategic partnerships for hydrogen hub participation and geographic expansion through regional engineering subsidiaries.
Among integrated power equipment conglomerates, GE Vernova and Siemens Energy occupy positions anchoring the full-service OEM tier. Mitsubishi Power Americas exemplifies the efficiency-focused archetype competing on combined cycle performance ratings. These three companies represent the primary competitive anchors shaping procurement criteria and technology roadmaps for North American utilities and industrial operators.
| Leading Market Players |
|---|
| GE Vernova |
| Siemens Energy |
| Mitsubishi Power Americas |
| Solar Turbines |
| Capstone Green Energy |
| Baker Hughes |
| Ansaldo Energia |
| Kawasaki Heavy Industries |
| MAN Energy Solutions |
| Others |
Value Network & Pricing Analysis
Long-term service agreements lock in aftermarket revenue streams for OEMs while providing utilities with cost predictability across turbine lifecycles exceeding thirty years. These contracts bundle spare parts, scheduled maintenance, and forced outage response into fixed-rate structures that insulate operators from superalloy price volatility.
Pricing Analysis
Price spreads between Gulf Coast and Midwest installations reflect regional labor cost differentials and transportation logistics for heavy-frame units. Three-tier pricing structure across premium H-class configurations, standard F-class units, and economy aeroderivative packages segments buyer budgets. Cost compression in the economy tier intensifies as battery storage captures peak-shaving contracts. Merchant IPPs in ERCOT exhibit highest price sensitivity; regulated utilities in the Southeast prioritize reliability guarantees over unit economics.
Supply Chain Analysis
Eighteen-month lead times for stage 1 buckets and transition pieces force operators into precision inventory synchronization with planned outage windows. Superalloy castings draw from concentrated domestic suppliers in Schenectady and Greenville, with nickel and cobalt feedstocks anchored in Canadian mining operations and Australian extraction sites. Single-source vulnerability for F-class and H-class hot gas path components elevates procurement risk. Distribution runs through OEM-direct channels for original equipment and authorized service networks for replacement parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry points around hydrogen-ready retrofits and aftermarket service competition as utilities unbundle long-term agreements from equipment supply.
For Market Incumbents: Shield installed base relationships through captive aftermarket networks and accelerated hydrogen combustion certification. Battery storage substitution threatens peaking turbine orders; backward integration into superalloy casting capacity secures component availability against supply bottlenecks. For New Entrants and Emerging Players: Aftermarket service gaps in combustion inspection and hot gas path repair present white-space opportunities where GE Vernova and Siemens Energy face technician shortages. Third-party maintenance contracts during warranty periods offer the most penetrable entry angle for independent service providers targeting ERCOT merchant plants. For Investors and Strategic Acquirers: Capital is best deployed toward specialized aeroderivative fabricators with established mobile power platforms and hydrogen hub participation credentials. The five-to-ten year viability window favors assets with demonstrated fuel-flexible combustion validation. Watch FERC interconnection rulemaking on hydrogen blending tariffs as the inflection signal for retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Hub Partnership | DOE cost-sharing agreements validate fuel-flexible combustion technology for progressive utilities in Texas and California. |
| Aftermarket Service Expansion | Third-party maintenance clauses in ERCOT merchant contracts break OEM exclusivity and capture recurring revenue streams. |
| Superalloy Supply Security | Domestic casting capacity in Greenville and Schenectady insulates against nickel price volatility and single-source risk. |
| Carbon Capture Integration | Alberta provincial tax credits and the Carbon Trunk Line infrastructure enable first-mover advantage for combined cycle operators. |
| Technician Apprenticeship Investment | Greenville Technical College and Houston Community College pipelines address field service specialist shortages outpacing retirement rates. |
Research Methodology
Initial hypotheses were tested against primary input from utility planning officers, IPP project developers, EPC contractors, and aftermarket service heads and refined through secondary validation. Stakeholder interviews combined with EIA data, FERC filings, IEA reports, and project development databases enabled bottom-up and top-down triangulation across the North American gas turbine fleet.
Variance decomposition across technology configuration, generation capacity tier, fuel specification, and regional grid type shaped the analytical framework over the projection horizon. CAGRs were derived from unit installation forecasts and service contract value projections. Hydrogen hub funding disbursement schedules and EPA enforcement timelines served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EPA Clean Air Act enforcement and FERC interconnection regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
US Power EPC Market
Power Equipment
Europe Power Rental Market
Power Equipment
Nigeria Power EPC Market
Power Equipment
Power Engineering, Procurement, and Construction (EPC) Market
Power Equipment
Wind Turbine Maintenance Market
Power Equipment
North America Power Plant Boiler Market
Power Equipment
Wind Power Fastener Market
Power Equipment
Turbomachinery Control Systems, Retrofitting, and Ancillary Services Market
Power Equipment
Digital Power Conversion Market
Power Equipment
Submarine Power Cable Market
Power Equipment
Deaerators Market
Power Equipment
Power Magnetics for MV AC Drive Market
Power Equipment
Wind Turbine Gearbox Repair and Refurbishment Market
Power Equipment
Heavy Duty Gas Turbine Market
Power Equipment
Global Exhaust Heat Recovery System Market
Power Equipment
Kazakhstan Power EPC Market