
 Power Distribution Unit (PDU) Market | 2026-2036
Power Distribution Unit (PDU) Market Size, Share, and Industry Trends Forecast 2026-2036
Power Distribution Unit (PDU) Market Analysis
Aftermarket service revenue for firmware updates, remote monitoring subscriptions, and predictive maintenance contracts is fragmenting across vendor ecosystems and third-party platform providers. Schneider Electric leverages its EcoStruxure IT architecture to capture recurring software attach revenue alongside hardware sales. Eaton Corporation anchors its position through integrated power chain solutions that extend from uninterruptible power supplies through rack-level distribution. Vertiv Group Corp. competes by specializing in thermal and power infrastructure co-design for high-density compute environments.
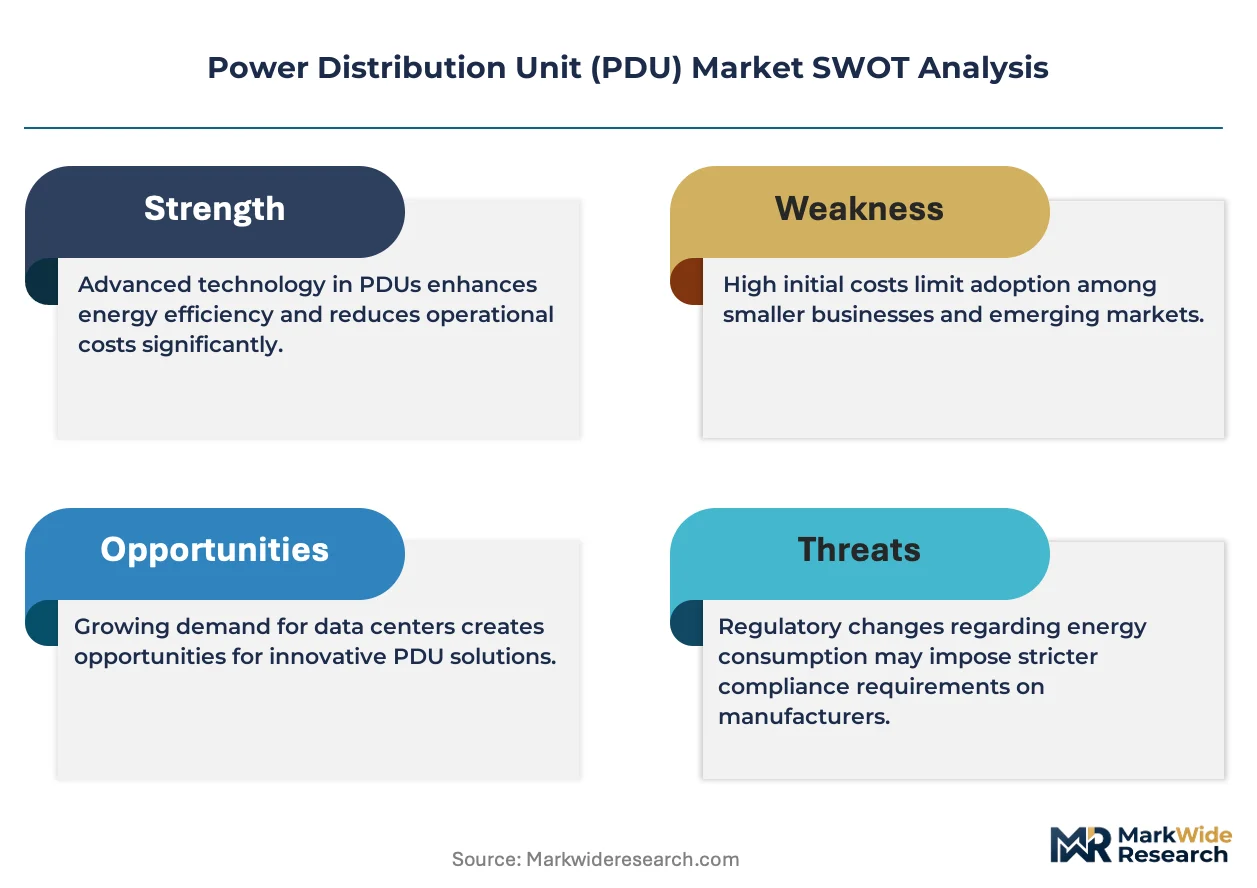
A power distribution unit is an electrical device that receives power from an uninterruptible power supply or utility feed and distributes it through multiple outlets to servers, networking gear, and storage arrays, typically supporting input voltages from 120V to 480V and current ratings up to 60A per phase with breaker protection at each circuit. Smart PDUs with outlet-level metering and environmental sensor integration command premium positioning as data center operators pursue granular power usage effectiveness tracking and stranded capacity identification. Rack-mounted form factors dominate volume shipments, while modular architectures gain traction in colocation facilities requiring rapid reconfiguration between tenants. Metered PDUs represent the fastest-growing technology category as regulatory pressure and sustainability reporting obligations push operators beyond basic switched units toward intelligent, networked infrastructure.
The EU Green Deal and F-Gas Regulation shape European procurement standards by mandating energy transparency and refrigerant accountability across digital infrastructure. In the United States, OSHA electrical safety standards and FCC electromagnetic interference certifications govern product compliance and facility installation protocols. India BIS certification requirements and the country's PLI scheme for electronics manufacturing create localized assembly incentives for multinational suppliers. Stakeholders must monitor how carbon border adjustment mechanisms and evolving data sovereignty rules reshape sourcing decisions for intelligent power infrastructure.
Market Dynamics
Hyperscale facility expansion in Northern Virginia, Frankfurt, and Singapore is compressing procurement cycles and forcing rack-level power infrastructure toward outlet-level intelligence as operators chase stranded capacity recovery and real-time power usage effectiveness optimization.
Growth Catalysts
- EU Green Deal energy transparency mandates:Germany, France, and the Netherlands now require metered outlet visibility for data center sustainability reporting, accelerating intelligent PDU deployment across European colocation facilities.
- High-density compute thermal loads:AI training clusters exceeding 30kW per rack demand granular power monitoring to prevent circuit overload and enable dynamic workload balancing.
- India PLI scheme localization:Electronics manufacturing incentives drive multinational suppliers to establish BIS-certified assembly operations, reducing import dependency for intelligent power infrastructure.
Market Restraints
- Copper and semiconductor input volatility:PDU manufacturing depends on copper busbars and metering ICs subject to commodity price swings and foundry allocation constraints.
- Supply concentration in Chinese enclosures:Sheet metal fabrication and basic PDU chassis production clusters in Guangdong and Zhejiang provinces, creating geographic single-source exposure.
- OSHA electrical safety compliance friction:US facility installations require arc-fault protection and ground-fault monitoring that add cost and engineering validation cycles.
Strategic Opportunities
- Edge computing micro-data centers:Distributed IT deployments in retail, manufacturing, and telecom tower sites remain underpenetrated by intelligent PDUs, presenting white-space expansion.
- CSRD corporate sustainability reporting:EU mandates for Scope 2 emissions disclosure create regulatory tailwind for outlet-level metering as auditable carbon accounting infrastructure.
- Software-defined power convergence:API-driven PDU control integrating with DCIM and BMS platforms enables automated demand response and predictive capacity planning.
Industry Challenges
- Embedded systems firmware talent scarcity:Intelligent PDU development requires scarce expertise in secure boot, over-the-air updates, and IEC 62443 cybersecurity standards.
- Legacy infrastructure integration complexity:Retrofitting metered PDUs into existing racks with fixed cable routing and legacy breaker configurations demands custom engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Distribution Unit (PDU) Market |
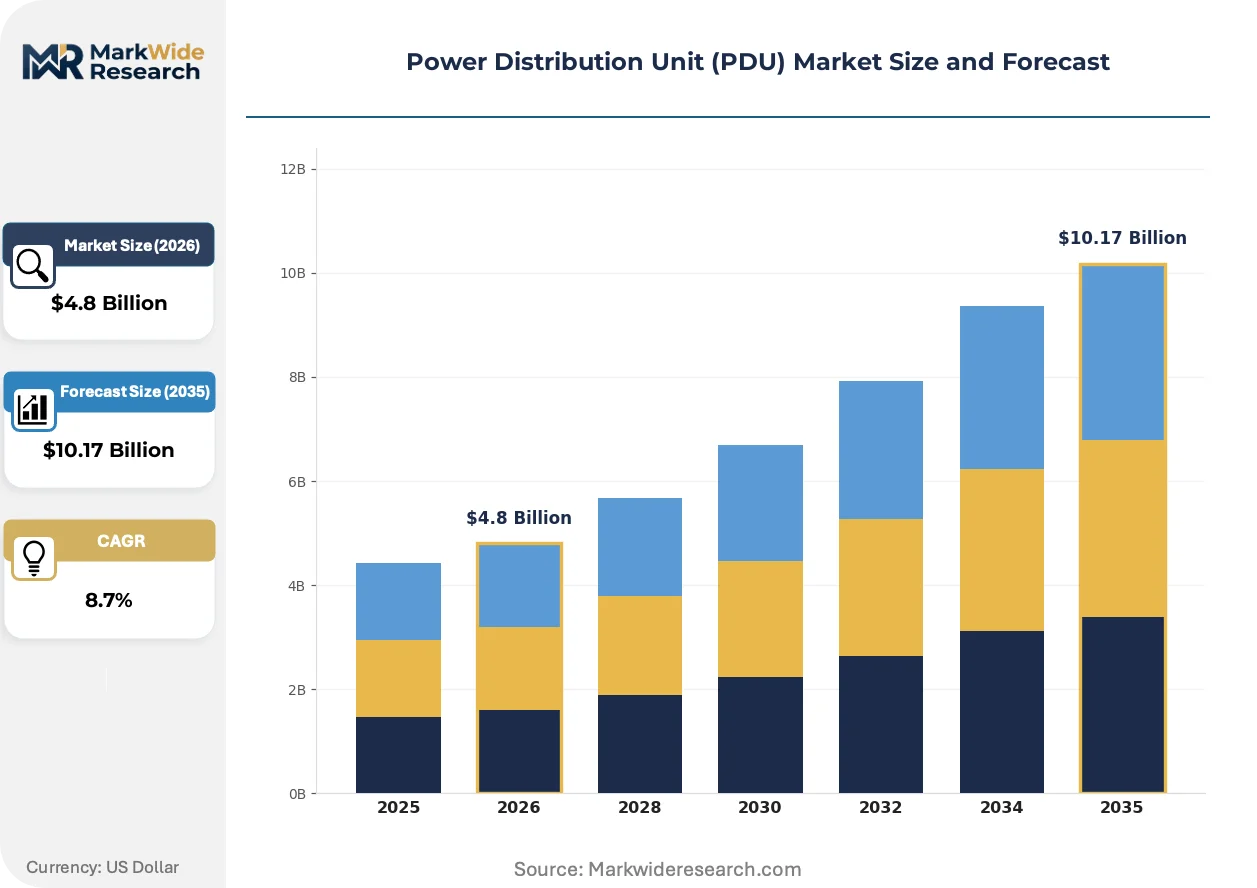
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Edge Computing, Hybrid Technology: Smart PDUs, Metered PDUs, Maintenance Bypass PDUs, Basic PDUs End User: Data Centers, Telecommunications, IT Services, Healthcare Form Factor: Rack-Mounted, Wall-Mounted, Floor-Standing, Modular |
| Companies Covered | Schneider Electric, Eaton Corporation, Vertiv Group Corp., ABB Ltd., Legrand, Delta Electronics, Hewlett Packard Enterprise, Panduit Corp., CyberPower Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Distribution Unit (PDU) Market Emerging Trajectories
Power infrastructure is virtualizing through software-defined control layers, environmental sensor fusion, and predictive analytics that transform hardware into programmable energy management platforms.
Outlet-level power monitoring is virtualizing the traditional PDU from passive distribution hardware into granular telemetry nodes. Hyperscale operators in Singapore and Northern Virginia are deploying these units at rack density exceeding 90 percent. This virtualization compresses the market for basic switched PDUs while expanding attach rates for DCIM integration licenses.
The EU F-Gas Regulation and CSRD disclosure requirements are tightening procurement specifications for refrigerant accountability and energy transparency. Data center operators must now document power chain efficiency from utility feed through server inlet. Metered PDU categories with environmental sensor integration capture premium positioning as compliance infrastructure.
Colocation buyers are unbundling hardware procurement from managed service contracts. Wholesale tenants in Frankfurt and Amsterdam now specify API-accessible PDUs while sourcing remote monitoring separately through third-party platform providers. This disintermediation fragments vendor service revenue and elevates firmware interoperability as a selection criterion.
Power Distribution Unit (PDU) Market Segmentation
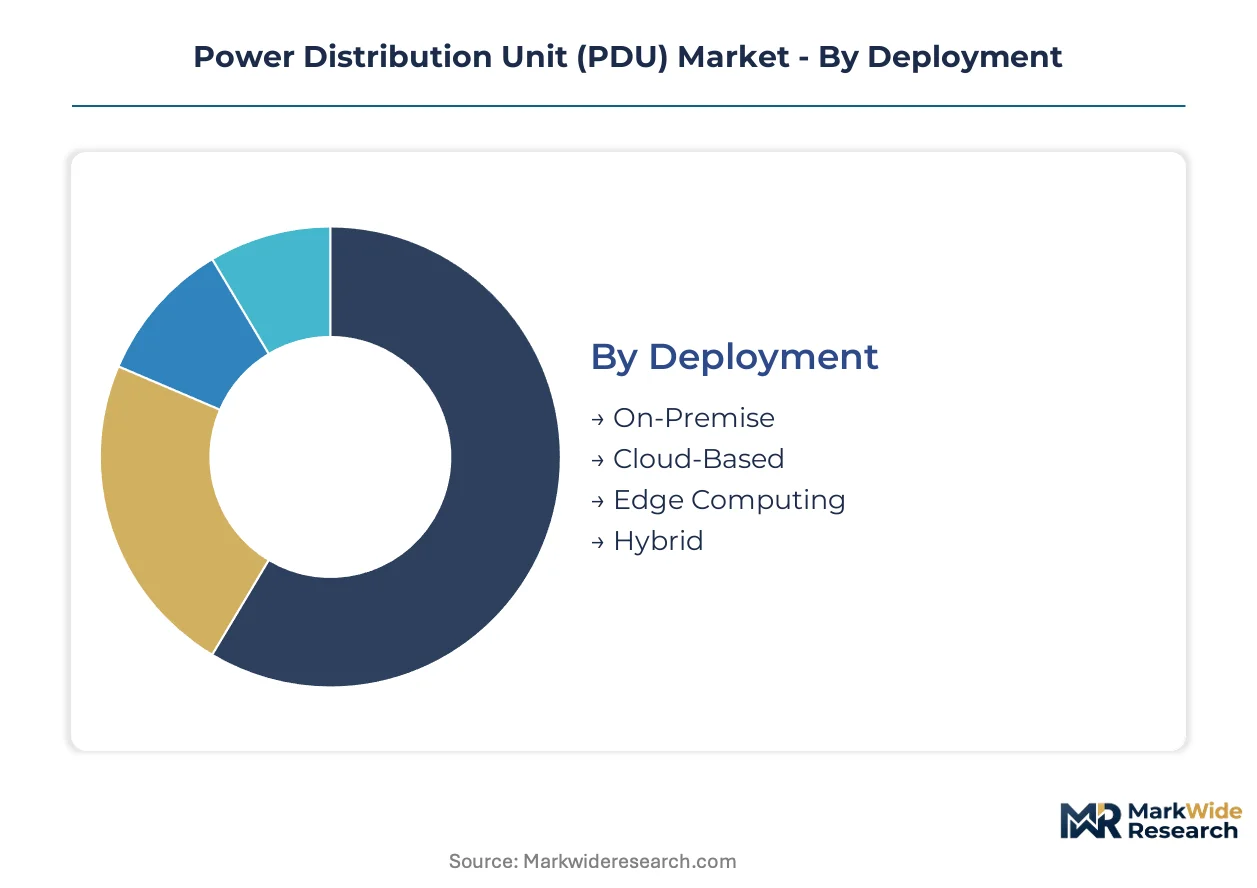
PDU segmentation reveals divergent service revenue potential across deployment models and technology tiers. Cloud and hyperscale operators generate recurring firmware subscription income, while on-premise legacy estates demand retrofit consulting.
Deployment:
After-sales-service intensity varies sharply by deployment model, with cloud-based and edge computing installations requiring continuous remote monitoring contracts.
- Cloud-Based:Multi-tenant facilities in Northern Virginia and Frankfurt mandate API-accessible PDUs with automated tenant billing reconciliation. Schneider Electric and Eaton capture recurring software attach revenue through DCIM integration licenses.
- Edge Computing:Distributed retail and telecom tower sites deploy compact intelligent units with cellular backhaul for remote diagnostics. Maintenance contracts concentrate in Singapore and Germany where tower operators outsource power monitoring.
- On-Premise:Enterprise data centers in the United States require arc-fault protection validation under OSHA standards.
- Hybrid:Colocation tenants in Amsterdam unbundle hardware from managed services, sourcing monitoring through third-party platforms.
By volume, On-Premise leads. By growth pace, Edge Computing is ahead.
Technology:
Cost tier stratification separates premium intelligent units from commodity distribution hardware, with metered categories commanding 40-60% price premiums over basic switched alternatives.
- Smart PDUs:Outlet-level metering with environmental sensor fusion supports real-time power usage effectiveness tracking. Hyperscale operators in Singapore deploy these at rack density exceeding 90 percent for stranded capacity recovery.
- Metered PDUs:Circuit-level monitoring without switching capability satisfies EU Green Deal transparency mandates in Germany, France, and the Netherlands.
- Basic PDUs:Passive distribution without telemetry dominates legacy rack refresh cycles in cost-constrained enterprise facilities.
- Maintenance Bypass PDUs:Hot-swappable architectures enable UPS servicing without load interruption in healthcare and financial services deployments.
By installed base, Basic PDUs dominate. By expansion trajectory, Smart PDUs are climbing the fastest.
End User:
Application-specific requirements drive specification divergence, with healthcare and telecommunications imposing distinct electrical safety and uptime protocols.
- Data Centers:Hyperscale, colocation, and enterprise facilities across Northern Virginia and Frankfurt constitute the primary demand concentration. Metered outlet visibility enables carbon accounting compliance under CSRD disclosure rules.
- Telecommunications:5G radio access network densification in India and Singapore drives compact rack-mounted deployment for tower power management.
- Healthcare:Patient care facilities require IEC 60601 medical-grade isolation and ground-fault monitoring per OSHA electrical safety standards.
- IT Services:Managed service providers specify API-driven control for automated capacity planning across distributed client estates.
By revenue concentration, Data Centers lead. By contract velocity, Telecommunications is gaining share fastest.
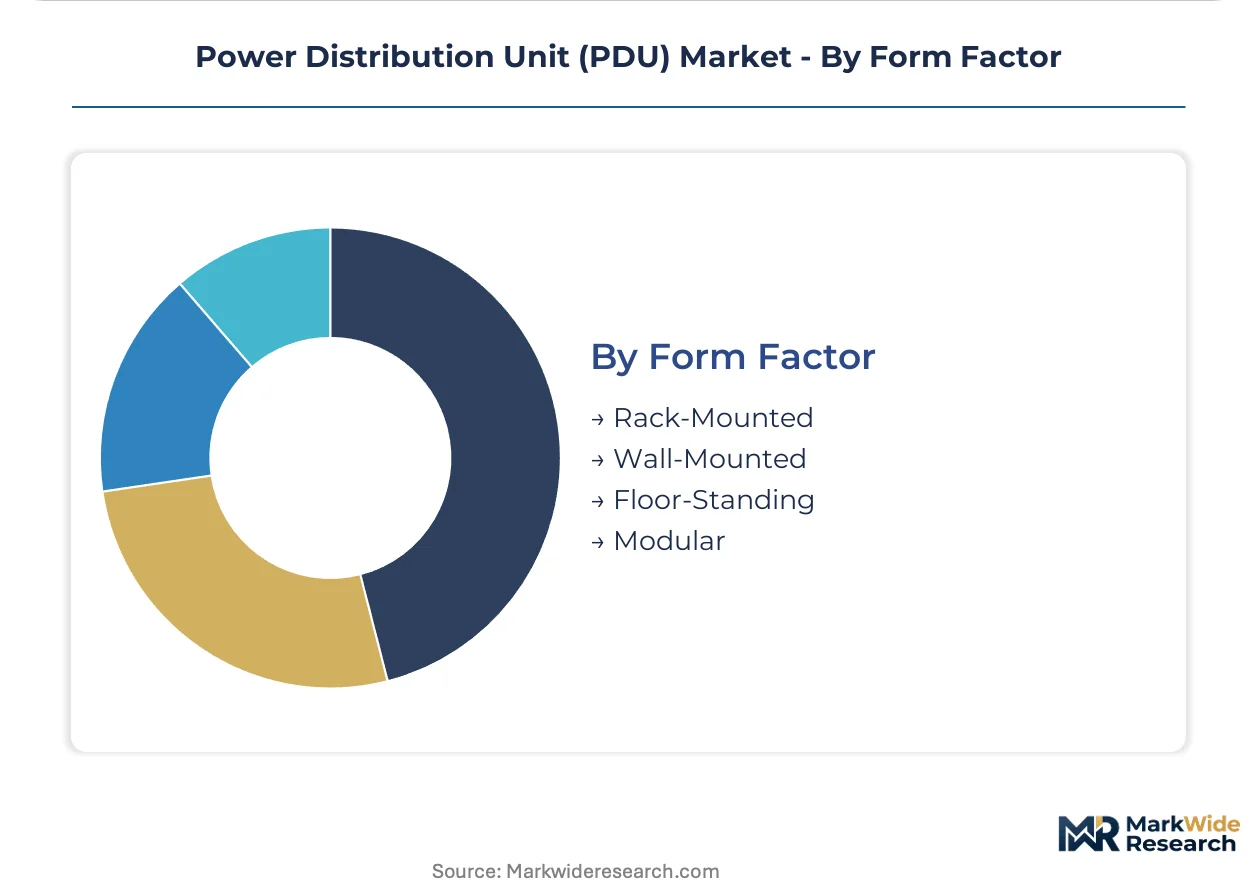
Form Factor:
Supply concentration in Chinese sheet metal fabrication clusters shapes cost structures across enclosure categories, with Guangdong and Zhejiang provinces dominating basic chassis production.
- Rack-Mounted:Standard 1U/2U vertical and horizontal configurations support 120V to 480V input with breaker protection at each circuit. Volume shipments concentrate in hyperscale facilities across Northern Virginia and Singapore.
- Modular:Hot-swappable busbar architectures enable rapid reconfiguration between colocation tenants in Frankfurt and Amsterdam.
- Wall-Mounted:Compact enclosures serve edge computing micro-data centers in retail and manufacturing sites.
- Floor-Standing:High-amperage units up to 60A per phase support main distribution frames in telecommunications central offices.
By shipment volume, Rack-Mounted leads. By configuration flexibility, Modular is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States prioritizes high-density hyperscale deployment with outlet-level intelligence. European facilities emphasize regulatory compliance infrastructure. Asian markets concentrate on localization incentives and rapid capacity scaling.
United States
Northern Virginia hosts the world's densest hyperscale concentration, driving rack-level power infrastructure toward 90 percent smart PDU penetration. OSHA electrical safety standards mandate arc-fault protection and ground-fault monitoring for all new facility installations. Data center operators in Ashburn and Loudoun County deploy metered outlet architectures to recover stranded capacity and optimize real-time power usage effectiveness.
Germany
Frankfurt anchors European colocation demand with stringent EU Green Deal energy transparency requirements. The national efficiency mandate now requires metered outlet visibility for sustainability reporting across all facilities exceeding 50kW capacity. Industrial operators in Hesse and Bavaria retrofit existing racks with intelligent PDUs to satisfy CSRD disclosure obligations for Scope 2 emissions accounting.
India
Domestic data center construction accelerates under the PLI scheme for electronics manufacturing, driving BIS-certified assembly localization. The Central Electricity Authority imposes power quality standards that favor intelligent distribution with harmonic monitoring. Multinational suppliers establish captive production in Tamil Nadu and Karnataka to serve telecom tower densification and cloud region expansion.
Singapore
The city-state's tropical climate constraints force thermal-power co-design at densities exceeding 30kW per rack. National sustainability targets require granular energy telemetry for carbon accounting across all licensed data center operations. Marina Bay and Changi digital infrastructure clusters deploy environmental sensor fusion alongside outlet-level metering to prevent circuit overload in AI training deployments.
Netherlands
Amsterdam colocation tenants unbundle hardware procurement from managed services, creating demand for API-accessible PDUs with third-party platform compatibility. National efficiency mandates align with EU Green Deal transparency requirements for metered infrastructure. Wholesale operators in the Randstad region specify modular busbar architectures enabling rapid tenant reconfiguration.
Power Distribution Unit (PDU) Market Vendor Landscape
Capability concentration sits with integrated power chain specialists; scale advantage sits with diversified electrical infrastructure conglomerates. The market structures around three tiers: full-stack platform providers, component-focused fabricators, and regional assembly specialists. Dominant competitive moves include firmware subscription attach strategies and DCIM platform integration partnerships.
Among diversified electrical infrastructure providers, Schneider Electric, Eaton Corporation, and Vertiv Group Corp. occupy positions spanning hardware manufacturing through software-defined control layers. Schneider Electric exemplifies the platform-architecture archetype through its EcoStruxure IT architecture. Eaton Corporation represents integrated power chain positioning extending from uninterruptible power supplies through rack-level distribution. Vertiv Group Corp. anchors the thermal-power co-design specialization for high-density compute environments.
| Leading Market Players |
|---|
| Schneider Electric |
| Eaton Corporation |
| Vertiv Group Corp. |
| ABB Ltd. |
| Legrand |
| Delta Electronics |
| Hewlett Packard Enterprise |
| Panduit Corp. |
| CyberPower Systems |
| Others |
Supply Flow & Price Mechanics
Chinese sheet metal fabrication clusters in Guangdong and Zhejiang provinces concentrate enclosure supply, anchoring margin pools in firmware subscription tiers and DCIM integration licensing rather than commodity hardware.
Pricing Analysis
Long-term service contracts dominate hyperscale procurement in Northern Virginia and Singapore, while spot purchasing persists for basic rack refresh cycles in cost-constrained enterprise facilities. Three-tier pricing structure across premium intelligent units, standard metered configurations, and economy basic distribution separates buyers by telemetry depth and API accessibility. Cost compression in basic switched categories intensifies because copper busbar and semiconductor metering IC volatility compresses hardware margins. Cloud operators exhibit least price sensitivity due to stranded capacity recovery value, whereas retail edge deployments remain most cost-conscious.
Supply Chain Analysis
Copper busbars, semiconductor metering ICs, and sheet metal enclosures feed from concentrated upstream bases in China, South Korea, and Taiwan. PDU manufacturing draws from Guangdong stamping operations, Korean foundry output for power monitoring chips, and Taiwanese PCB assembly for control modules. Single-source vulnerability in Chinese enclosure supply creates geographic concentration risk amid tariff exposure and logistics chokepoint sensitivity. Distribution runs through direct OEM relationships with hyperscale operators, electrical distributors serving enterprise facilities, and systems integrators for edge computing deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive positioning as API interoperability and firmware subscription ecosystems displace standalone hardware procurement across data center power infrastructure.
For Market Incumbents: Pre-empt disintermediation by colocation tenants unbundling hardware from managed services through deeper DCIM platform integration and captive firmware update infrastructure. Secure vertical integration into semiconductor metering IC sourcing to offset foundry allocation constraints and copper price volatility.
For New Entrants and Emerging Players: Edge computing micro-data centers in Southeast Asian manufacturing corridors and Indian telecom tower sites represent the most penetrable entry point given underdeveloped intelligent PDU penetration and outsourced maintenance contract concentration. Pursue cellular-backhaul-enabled compact units with third-party platform API compatibility as the primary go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed electrical infrastructure specialists holding strong positions in thermal-power co-design but lacking software-defined control layer capabilities. Five-to-ten year viability hinges on recurring revenue attach rates exceeding hardware replacement cycles. Monitor EU CSRD disclosure compliance velocity as the signal indicating acceleration in metered outlet upgrade demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Subscription Platform Launch | Captures recurring revenue from hyperscale operators in Northern Virginia pursuing real-time power usage effectiveness optimization. |
| DCIM Integration Partnership | Enables automated tenant billing reconciliation for Frankfurt colocation facilities under EU Green Deal mandates. |
| Semiconductor Metering IC Backward Integration | Reduces exposure to Korean foundry allocation constraints and copper commodity volatility. |
| Edge Computing Compact Unit Development | Addresses white-space in Singapore telecom tower sites and Indian 5G radio access network densification. |
| API Interoperability Certification Program | Supports Amsterdam colocation tenant demand for third-party platform compatibility and service unbundling. |
Methodological Framework
Initial hypotheses were tested against primary input from data center operations directors, electrical infrastructure procurement managers, colocation facility engineers, and firmware development leads and refined through secondary validation against SEC 10-K filings, hyperscaler capex disclosures, EIA facility energy data, and customs trade records. Bottom-up unit economics modeling triangulated with top-down market sizing across deployment models and technology tiers.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across cloud-based, edge computing, on-premise, and hybrid deployments plus smart, metered, basic, and maintenance bypass technology tiers. CAGRs derived from installed base replacement cycles, regulatory compliance deadlines, and hyperscale construction pipelines. Forecast inputs incorporated copper price trajectory assumptions and foundry capacity allocation patterns for metering semiconductors.
Macroeconomic conditions sit as an overlay; deviation in data center construction lending rates, copper commodity indices, or Korean semiconductor foundry utilization would shift the trajectory. Forecasts reflect documented assumptions regarding EU CSRD enforcement timing and OSHA electrical safety standard adoption velocity. Material shifts in China-U.S. tariff structures or India PLI scheme localization incentives would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Distribution
Global Power Distribution Component Market
Power Distribution
Brazil City Gas Distribution Market
Power Distribution
Power Distribution Cables Market
Power Distribution
Distribution Panel Market
Power Distribution
Medium Voltage AC Power Distribution Units (PDU) Market
Power Distribution
Distribution Board Market
Power Distribution
Lighting and Distribution Panel Board Market
Power Distribution
AI in Energy Distribution Market
Power Distribution
North America and Europe Power Distribution Component Market
Power Distribution
Europe DC Distribution Network Market
Power Distribution
Global Electric Power Distribution Automation Systems Market