
 Distribution Board Market | 2026-2036
Distribution Board Market Size, Share, and Industry Trends Forecast 2026-2036
Distribution Board Market Analysis
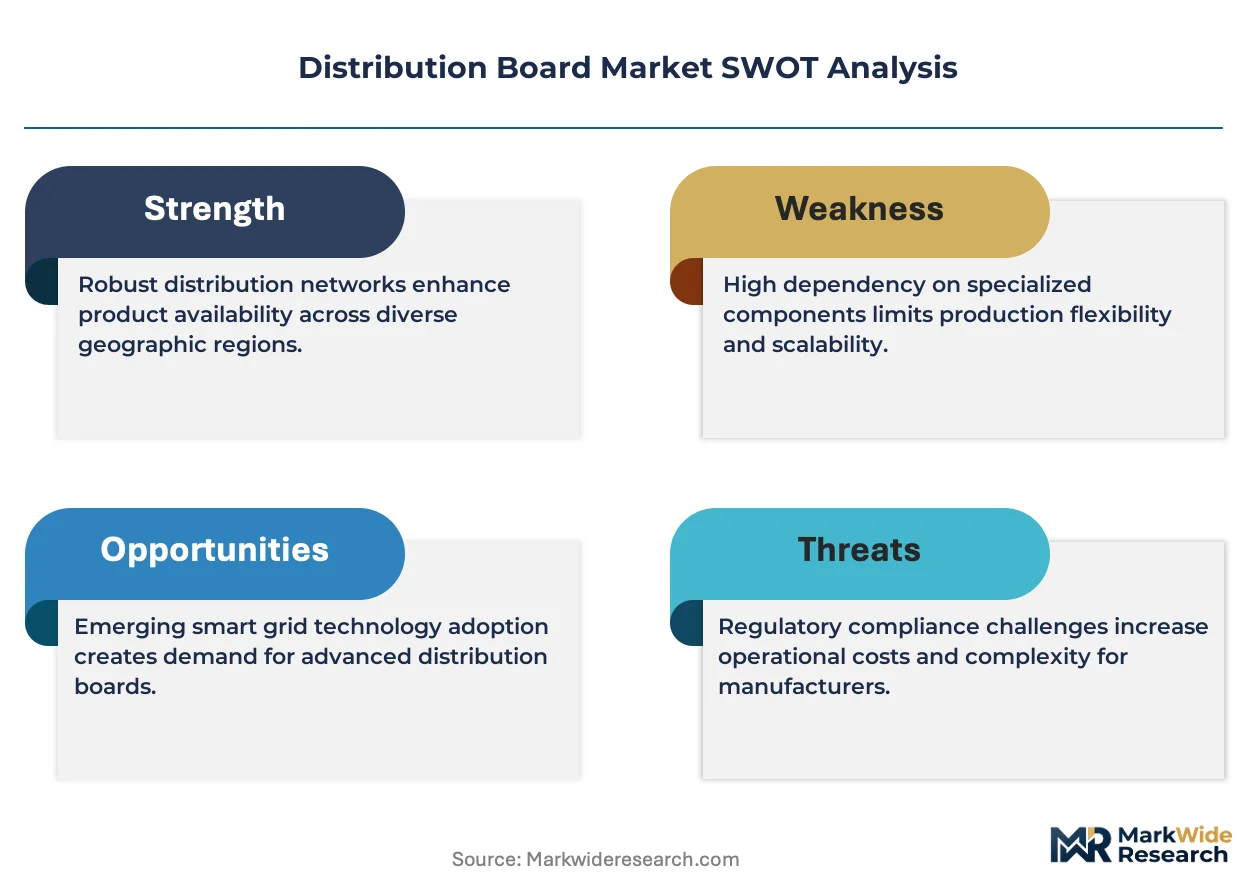
CE marking under the EU's Low Voltage Directive is hardening the cost-of-entry calculus for distribution board manufacturers seeking European market access. Eaton Corporation PLC leverages its integrated electrical portfolio to sustain specification-grade positioning across industrial verticals. Siemens AG anchors its competitive stance through digital twin integration in switchgear design, while Schneider Electric SE dominates smart distribution board architectures with embedded IoT monitoring capabilities.
A distribution board is an enclosed assembly of electrical switches, circuit breakers, and busbars that receives power from transformers or generators and distributes it to subsidiary circuits through overcurrent protection devices rated typically up to 1000V AC. Panelboards command the largest product type volume due to their ubiquity in commercial building retrofits, though smart distribution boards are outpacing analog equivalents as facility managers prioritize real-time energy analytics. The industrial end-user segment concentrates margin pools where motor control centers integrate variable frequency drives for process optimization.
FERC interconnection standards in the United States, IEC 61439 series internationally, and BIS certification requirements in India collectively shape product design, testing protocols, and market access timelines for distribution board suppliers. The EU's Ecodesign Directive and expanding CSRD reporting obligations are pushing manufacturers toward copper-aluminum hybrid busbar configurations and modular architectures that ease end-of-life recyclability. Stakeholders must monitor how grid-edge decentralization and prosumer energy trading reshape specifications for bidirectional power flow protection in next-generation distribution infrastructure.
Market Dynamics
AI-driven power density requirements in data centers are forcing wholesale redesign of electrical distribution architectures, compressing upgrade cycles from decade-long horizons to three-to-five-year refresh mandates.
Growth Catalysts
- IEC 61439 Compliance Mandates:Export-oriented manufacturing bases in India and Southeast Asia are retooling assembly lines to meet international certification requirements, expanding addressable market access for certified producers.
- Data Center Electrification:Hyperscale operators are procuring high-amperage panelboards and busway systems to support GPU clusters drawing 50-100kW per rack, creating specification-grade demand pools.
- Copper-Aluminum Hybrid Busbars:Material substitution strategies are reducing raw material exposure while maintaining conductivity thresholds, enabling cost-competitive bidding on large infrastructure tenders.
Market Restraints
- Copper Price Volatility:LME copper futures swings above $9,000 per tonne are compressing gross margins on fixed-price contracts, forcing manufacturers toward index-linked pricing clauses.
- Concentrated Semiconductor Supply:Dependency on Taiwanese and South Korean suppliers for power monitoring ICs creates vulnerability in smart distribution board production schedules.
- Legacy Substation Interoperability:Existing 480V infrastructure in industrial facilities limits adoption of 1000V-rated intelligent switchgear without complete feeder replacement.
Strategic Opportunities
- India Smart Grid Deployment:State-level utility modernization programs under the National Smart Grid Mission are accelerating procurement of remote-monitored distribution boards with embedded communication modules.
- EU CSRD Reporting Alignment:Corporate sustainability disclosure requirements are creating pull for modular, recyclable panel architectures that ease end-of-life material recovery documentation.
- Digital Twin Convergence:Integration of real-time thermal monitoring with predictive maintenance platforms is opening service-revenue streams beyond hardware sales for equipment vendors.
Industry Challenges
- Certification Timeline Compression:IEC 61439-2 testing protocols for assemblies above 630A require 12-16 week validation cycles, delaying project delivery on fast-track data center builds.
- Embedded Systems Talent Scarcity:Firmware development for IoT-enabled protection relays competes with consumer electronics and automotive sectors for limited embedded engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distribution Board Market |
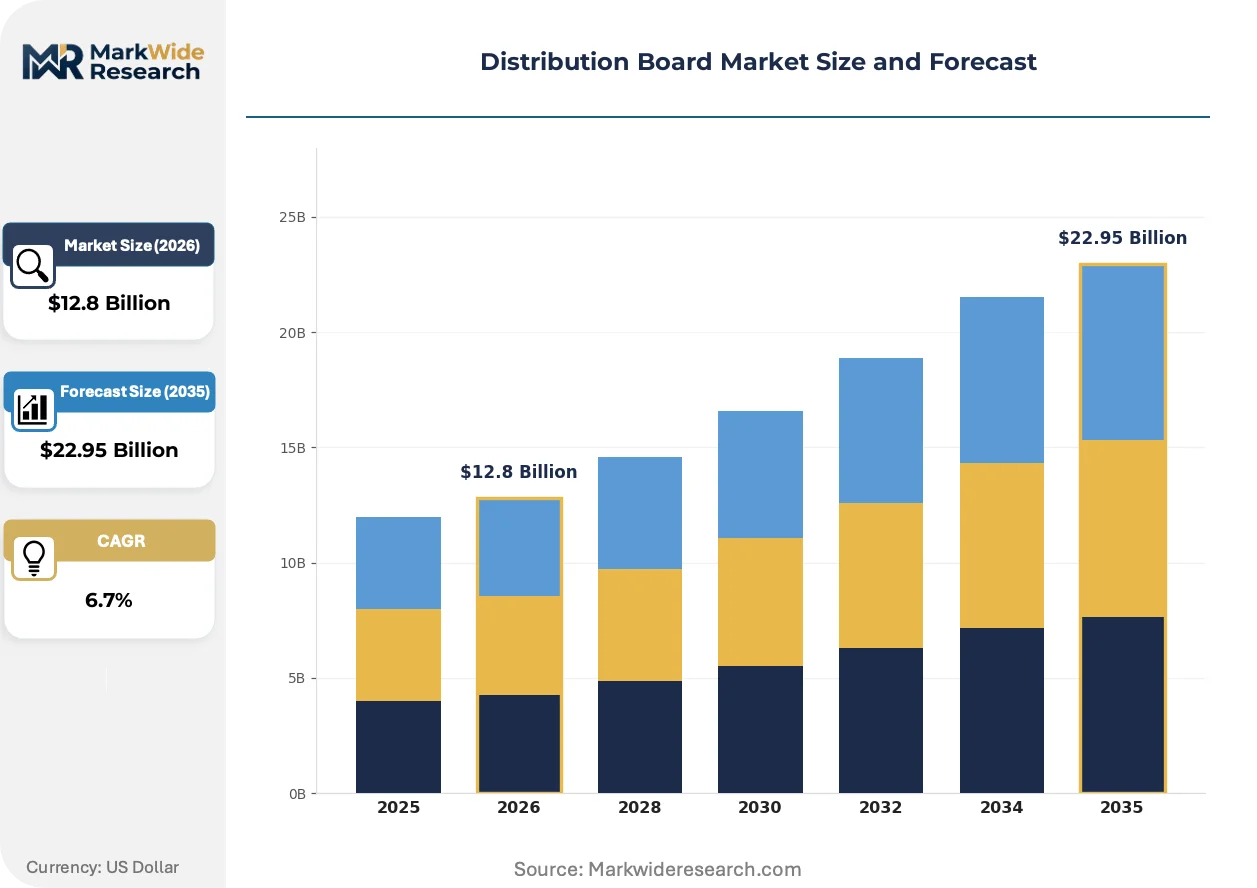
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panelboards, Switchgear, Motor Control Centers, Load Centers End User: Residential, Commercial, Industrial, Utilities Installation: Wall-mounted, Floor-mounted, Ceiling-mounted, Modular Technology: Smart Distribution Boards, Analog Distribution Boards, Digital Distribution Boards, Hybrid Distribution Boards |
| Companies Covered | Eaton Corporation PLC, Havells India Ltd., Siemens AG, Alfanar Group, Legrand SA, ABB Ltd., Larsen & Toubro Limited, Hager Group, Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distribution Board Market Emerging Trajectories
Electrification intensity across heavy industry and digital infrastructure is compressing product lifecycles and rewiring competitive advantage toward software-integrated hardware platforms.
Intelligent electronic devices with edge-computing capabilities are rewriting how protection coordination is engineered. Data center operators are specifying boards with integrated arc-flash detection and self-healing busbar configurations. This capability compression is collapsing the traditional separation between switchgear and building management systems.
CE marking enforcement under the EU's Low Voltage Directive is tightening third-party surveillance of factory production control. Manufacturers face unannounced audits and sample retesting obligations. Industrial end-users in Germany and France are now demanding full technical construction files as standard procurement documentation.
Specification-grade buyers are consolidating vendor relationships around integrated electrical platform providers. Traditional electrical distributors are losing specification influence to direct manufacturer engagement on large infrastructure projects. This channel compression is most pronounced in Nordic markets where engineering-procurement-construction firms dominate capital allocation.
Distribution Board Market Segmentation
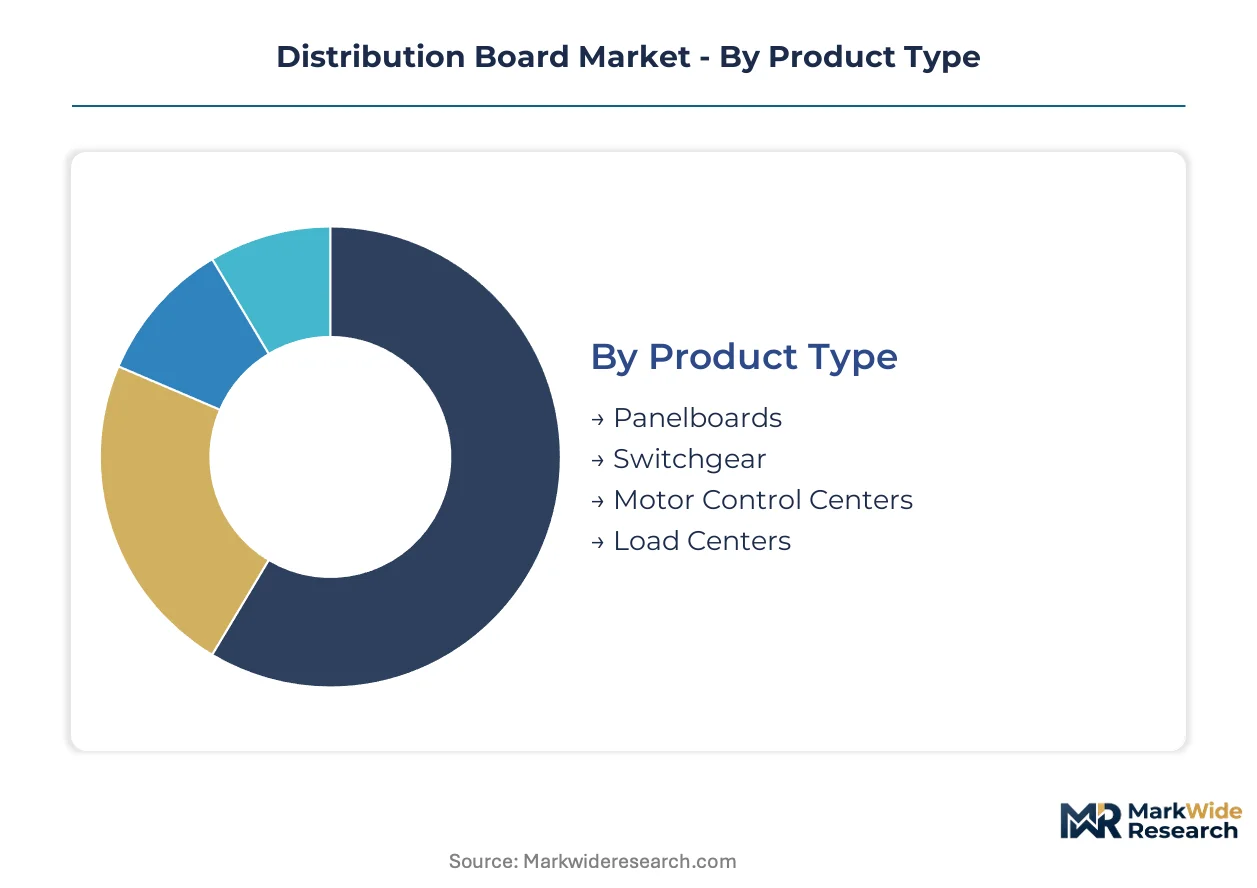
Distribution board procurement patterns diverge sharply across installation environments, power ratings, and intelligence tiers. Upgrade cycles now compress from decade-long horizons to three-to-five-year refresh mandates in data center and heavy industrial verticals. Specification-grade buyers increasingly segment vendors by integrated platform capabilities rather than discrete product catalogs.
Product Type:
Replacement cycles vary dramatically by enclosure complexity and fault-current withstand ratings, with specification-grade assemblies commanding premium procurement timelines.
- Panelboards:Enclosed assemblies of circuit breakers and busbars rated up to 600V, typically surface-mounted or flush-mounted in commercial buildings. Demand concentrates in US office retrofit markets where NEC 2023 compliance is triggering wholesale replacements of fused-switchgear legacy infrastructure.
- Switchgear:Metal-enclosed power circuit breaker assemblies rated 1000V and above with draw-out mechanisms for maintenance isolation. Data center operators in Northern Virginia and Frankfurt are procuring high-ampacity switchgear to support GPU clusters drawing 50-100kW per rack, compressing traditional specification cycles.
- Motor Control Centers:Vertical enclosures housing combination motor starters, variable frequency drives, and protection relays for process industries.
- Load Centers:Residential-grade circuit breaker enclosures with limited busbar ampacity, predominantly serving single-family and multi-family housing construction.
Volume placements concentrate in Panelboards; the faster expansion belongs to Switchgear.
End User:
Margin structures stratify sharply across customer sophistication tiers, with industrial accounts demanding embedded predictive maintenance capabilities unavailable in residential procurement channels.
- Industrial:Heavy manufacturing, petrochemical, and mining operations specifying IEC 61439-2 compliant assemblies with arc-flash mitigation and thermal monitoring. German automotive OEMs and Gulf Coast petrochemical operators are consolidating vendor relationships around integrated electrical platform providers who bundle switchgear with digital twin software.
- Utilities:Transmission and distribution network operators procuring remote-monitored distribution boards for substation automation. India's state electricity boards under the National Smart Grid Mission are accelerating procurement of boards with embedded communication modules for feeder-level visibility.
- Commercial:Office buildings, retail complexes, and healthcare facilities requiring panelboards with selective coordination and surge protection.
- Residential:Single-family and multi-family housing developers selecting load centers on cost-per-circuit metrics with minimal specification differentiation.
Industrial segments command the steepest margin premiums; utility deployments are climbing the fastest on smart grid capital allocation.
Installation:
Physical mounting constraints directly determine enclosure ingress protection ratings and thermal management architectures, with floor-mounted assemblies dominating high-ampacity industrial applications.
- Floor-mounted:Freestanding enclosures with cable compartment segregation and withdrawable circuit breaker trucks. Heavy industrial facilities in the US Midwest and Ruhr Valley specify floor-mounted switchgear for motor control centers above 2000A, where vibration isolation and maintenance access dominate procurement criteria.
- Modular:Sectionalized enclosures permitting field expansion and hot-swappable functional units. Data center engineering-procurement-construction firms in Nordic markets favor modular architectures for phased build-outs, reducing stranded capacity risk on speculative developments.
- Wall-mounted:Surface or recessed enclosures for panelboards and load centers in space-constrained commercial and residential environments.
- Ceiling-mounted:Suspended assemblies for temporary power distribution in construction and event infrastructure.
Floor-mounted configurations dominate industrial capital budgets; modular designs are expanding most quickly in hyperscale data center construction.
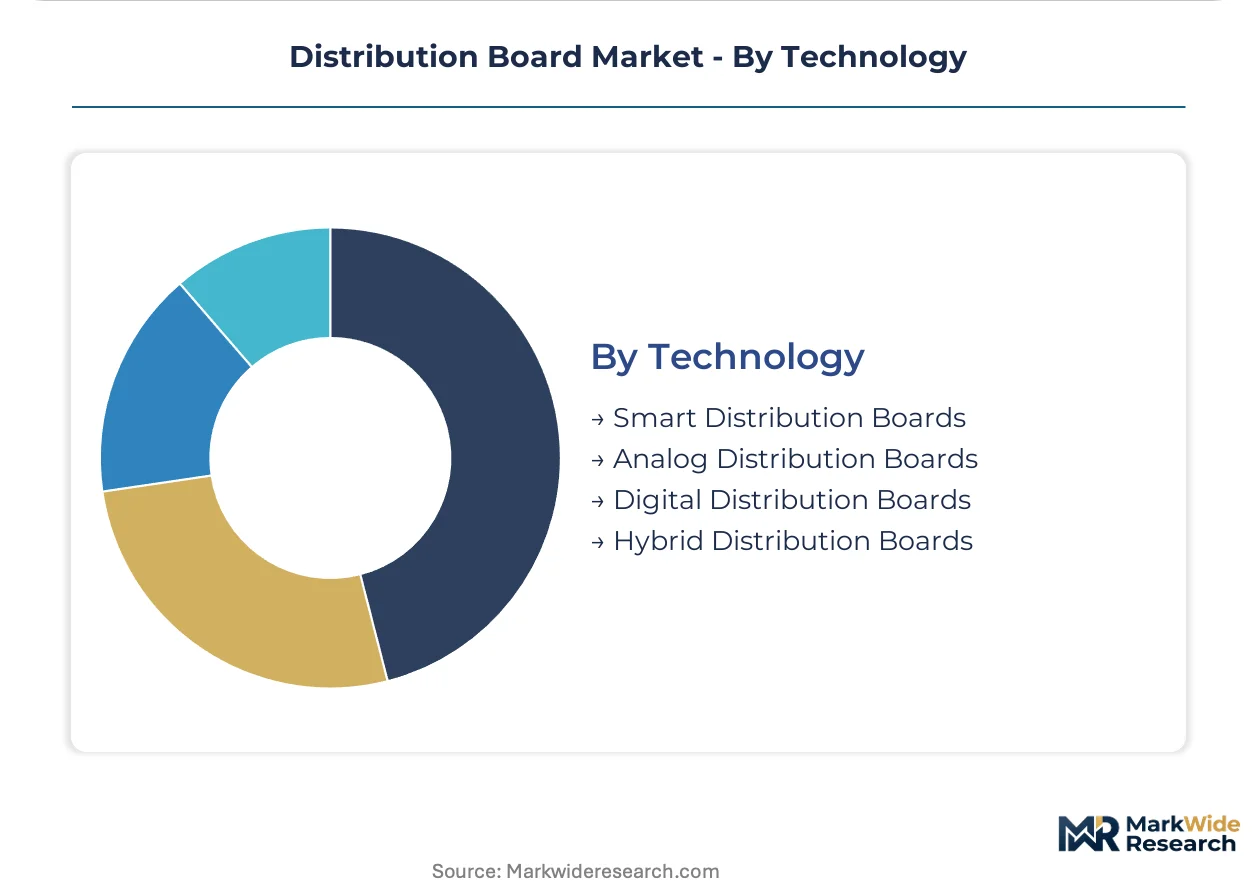
Technology:
Intelligence tier selection increasingly correlates with facility energy management sophistication, creating a three-tier procurement landscape where analog boards face displacement pressure.
- Smart Distribution Boards:Assemblies with embedded IoT sensors, edge computing, and cloud-connected energy analytics for real-time load profiling. Facility managers in Singapore and Amsterdam are specifying smart boards with integrated arc-flash detection to collapse the traditional separation between switchgear and building management systems.
- Analog Distribution Boards:Electromechanical protection devices without communication capabilities, still prevalent in cost-sensitive residential and legacy commercial installations.
- Digital Distribution Boards:Microprocessor-based protection relays with local HMI displays but limited connectivity infrastructure.
- Hybrid Distribution Boards:Mixed architectures combining electromechanical breakers with add-on communication modules for retrofit applications.
Analog boards retain volume dominance in residential channels; smart distribution boards are gaining share fastest on corporate sustainability disclosure requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's National Smart Grid Mission and special economic zones for electrical equipment manufacturing are concentrating distribution board demand in export-oriented hubs. Utility modernization programs across multiple continents are reshaping procurement specifications toward IEC 61439-compliant assemblies.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth is driving high-amperage switchgear procurement for GPU clusters. FERC interconnection standards govern grid-tied installations. Engineering-procurement-construction firms in these clusters specify integrated electrical platforms with arc-flash mitigation.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg are consolidating vendor relationships around digital twin-integrated switchgear suppliers. CE marking under the EU Low Voltage Directive hardens factory production control audits. The Ruhr Valley industrial corridor demands floor-mounted motor control centers above 2000A.
India
State electricity boards under the National Smart Grid Mission are accelerating procurement of remote-monitored distribution boards with embedded communication modules. BIS certification requirements shape product design timelines for domestic and export markets. Manufacturing concentrates in Gujarat and Maharashtra special economic zones.
China
Dual carbon goals are pushing industrial facilities toward copper-aluminum hybrid busbar configurations to reduce material intensity. GB standards and MIIT regulations govern smart grid equipment certification. Yangtze River Delta manufacturing clusters supply modular architectures for phased data center build-outs.
Singapore
Facility managers in the city-state's commercial and industrial zones specify smart distribution boards with integrated arc-flash detection and real-time energy analytics. ASEAN regulatory harmonization around IEC standards facilitates cross-border trade. The Jurong industrial estate anchors specification-grade procurement for process industries.
Distribution Board Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across three distinct tiers. The market structure consolidates around integrated electrical platform providers who bundle hardware with software services. Specification-grade vendors, cost-optimized regional fabricators, and IoT-native entrants define the competitive archetypes. Dominant competitive moves include M&A to acquire digital twin capabilities and strategic partnerships with data center engineering-procurement-construction firms.
Among diversified industrial conglomerates, Eaton Corporation PLC, Siemens AG, and Schneider Electric SE exemplify the integrated platform archetype. These entities anchor competitive positioning through specification-grade relationships with industrial and infrastructure end-users. Their geographic span and portfolio breadth enable direct engagement on large capital projects, compressing traditional electrical distributor influence. The companies represent the premium tier where digital twin integration and embedded IoT monitoring differentiate procurement outcomes.
| Leading Market Players |
|---|
| Eaton Corporation PLC |
| Havells India Ltd. |
| Siemens AG |
| Alfanar Group |
| Legrand SA |
| ABB Ltd. |
| Larsen & Toubro Limited |
| Hager Group |
| Schneider Electric SE |
| Others |
Supply Flow & Price Mechanics
Captive integration into copper-aluminum hybrid busbar production anchors both supply security and margin defense for tier-one distribution board manufacturers serving specification-grade data center and industrial accounts. This backward control over critical conductive materials buffers procurement teams against LME volatility while preserving pricing power on long-lead IEC 61439-certified assemblies.
Pricing Analysis
Short-lead-time premiums of 15-25 percent separate expedited panelboard deliveries from standard-cycle procurement in Northern Virginia and Frankfurt data center clusters. Project-based contract pricing dominates large infrastructure tenders, with index-linked copper clauses now standard on fixed-price agreements above 500kA. Cost compression in residential load centers intensifies as Chinese imports with BIS-equivalent testing displace domestic fabricators in price-sensitive Indian housing markets. Industrial end-users exhibit lowest price sensitivity, prioritizing arc-flash mitigation and digital twin integration over per-circuit economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Dubai anchor hub-and-spoke patterns for specification-grade switchgear serving EMEA and APAC project sites. Manufacturing concentrates in China, India, and Germany, with Yangtze River Delta clusters supplying modular architectures and Gujarat special economic zones feeding IEC 61439 export demand. Semiconductor dependencies for power monitoring ICs draw from Taiwanese and South Korean foundries, creating single-source vulnerability in smart distribution board production schedules. Distribution runs through direct manufacturer engagement on large capital projects, compressing traditional electrical distributor influence in Nordic engineering-procurement-construction channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor fab capacity constraints for industrial-grade power monitoring ICs prop pricing premiums across intelligent distribution board tiers. This supply bottleneck reinforces specification-grade vendor consolidation.
For Market Incumbents: Cement specification-grade positioning through captive busbar casting capacity in India and Southeast Asia, insulating margin pools from copper volatility while accelerating IEC 61439-2 certification timelines. Prioritize firmware development partnerships with embedded systems specialists to offset talent scarcity in IoT-enabled protection relay engineering. For New Entrants and Emerging Players: Engineering-procurement-construction firms in Nordic and Indian markets represent the most penetrable channel archetype for modular distribution board architectures. Target phased data center build-outs where stranded capacity risk drives procurement flexibility. Lead with hot-swappable functional units and embedded communication modules that collapse installation timelines against incumbent lead times. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated electrical platform providers seeking digital twin capabilities and smart grid software stacks. Five-to-ten-year viability hinges on firmware differentiation and recurring service revenue attachment rates. Monitor IEC 61439-2 certification backlog durations as inflection indicator for specification-grade supply tightness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Busbars | Captive copper-aluminum casting capacity insulates margins from LME volatility in Indian manufacturing zones. |
| IEC 61439-2 Certification Acceleration | Compressed validation cycles unlock fast-track data center procurement in Northern Virginia and Frankfurt clusters. |
| Digital Twin Platform Partnership | Integration with Siemens and Schneider predictive maintenance software anchors specification-grade relationships. |
| Embedded Systems Talent Acquisition | Firmware engineering capacity in Bangalore and Taipei addresses scarcity in IoT relay development pipelines. |
| Modular Architecture Expansion | Hot-swappable functional units reduce stranded capacity risk for Nordic engineering-procurement-construction firms. |
Methodological Framework
Document review covered SEC 10-K filings, IEC certification registries, and FERC interconnection databases, complemented by interviews with plant engineers at German automotive OEMs, procurement leads at Northern Virginia hyperscale operators, and aftermarket service heads at Indian state electricity boards. Secondary validation drew from customs trade data, BIS certification timelines, and EIA utility capital expenditure disclosures. Bottom-up project pipeline analysis triangulated against top-down segment sizing across product type, end user, and intelligence tier dimensions.
Installed base forecasts and replacement cycle projections emerged from integrated modeling of data center power density trajectories, utility modernization program budgets, and industrial electrification intensity metrics. Segmentation dimensions included enclosure mounting configuration, voltage rating tier, and embedded monitoring capability. CAGRs derived from regression analysis of historical procurement patterns against capital expenditure trajectories in target verticals, with copper price scenarios and semiconductor lead time assumptions as sensitivity inputs.
Several conditions sit outside the modeled scope, including unforeseen regulatory acceleration in EU Ecodesign Directive enforcement, abrupt shifts in Taiwanese semiconductor export controls, and discontinuity in Indian National Smart Grid Mission funding allocations. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Distribution
AI in Energy Distribution Market
Power Distribution
Global Power Distribution Component Market
Power Distribution
Power Distribution Unit (PDU) Market
Power Distribution
Lighting and Distribution Panel Board Market
Power Distribution
Brazil City Gas Distribution Market
Power Distribution
Power Distribution Cables Market
Power Distribution
North America and Europe Power Distribution Component Market
Power Distribution
Global Electric Power Distribution Automation Systems Market
Power Distribution
Europe DC Distribution Network Market
Power Distribution
Medium Voltage AC Power Distribution Units (PDU) Market
Power Distribution
Distribution Panel Market