
 North America and Europe Power Distribution Component Market | 2026-2036
North America and Europe Power Distribution Component Market Size, Share, and Industry Trends Forecast 2026-2036
North America and Europe Power Distribution Component Market Analytics
The gap between premium and commodity tiers is broadening as utilities demand IEC 61850-compliant digital substations while price-sensitive commercial buyers prioritize basic indoor switchgear. Schneider Electric leverages its European manufacturing footprint to anchor smart grid deployments across France and Germany. Eaton competes through specialized hazardous-location enclosures for North American oil and gas facilities. Siemens differentiates via integrated digital twin platforms that merge switchgear analytics with grid automation software.
Power distribution components encompass electromechanical and solid-state apparatus engineered to regulate, protect, and isolate electrical energy across voltage classes from 600V through 345kV, with insulating media spanning SF6 gas, vacuum interrupters, and cast-resin systems. Their primary purpose is to ensure continuity of supply while containing fault currents within milliseconds to prevent cascading grid failures. Transformers and switchgear occupy the deepest margin pools as utilities replace oil-filled units with dry-type designs rated for higher fire safety in urban underground installations. Smart grid technology is displacing analog protection relays across both regions as IEC 61850-9-2 process bus architectures reduce copper wiring density in new substations.
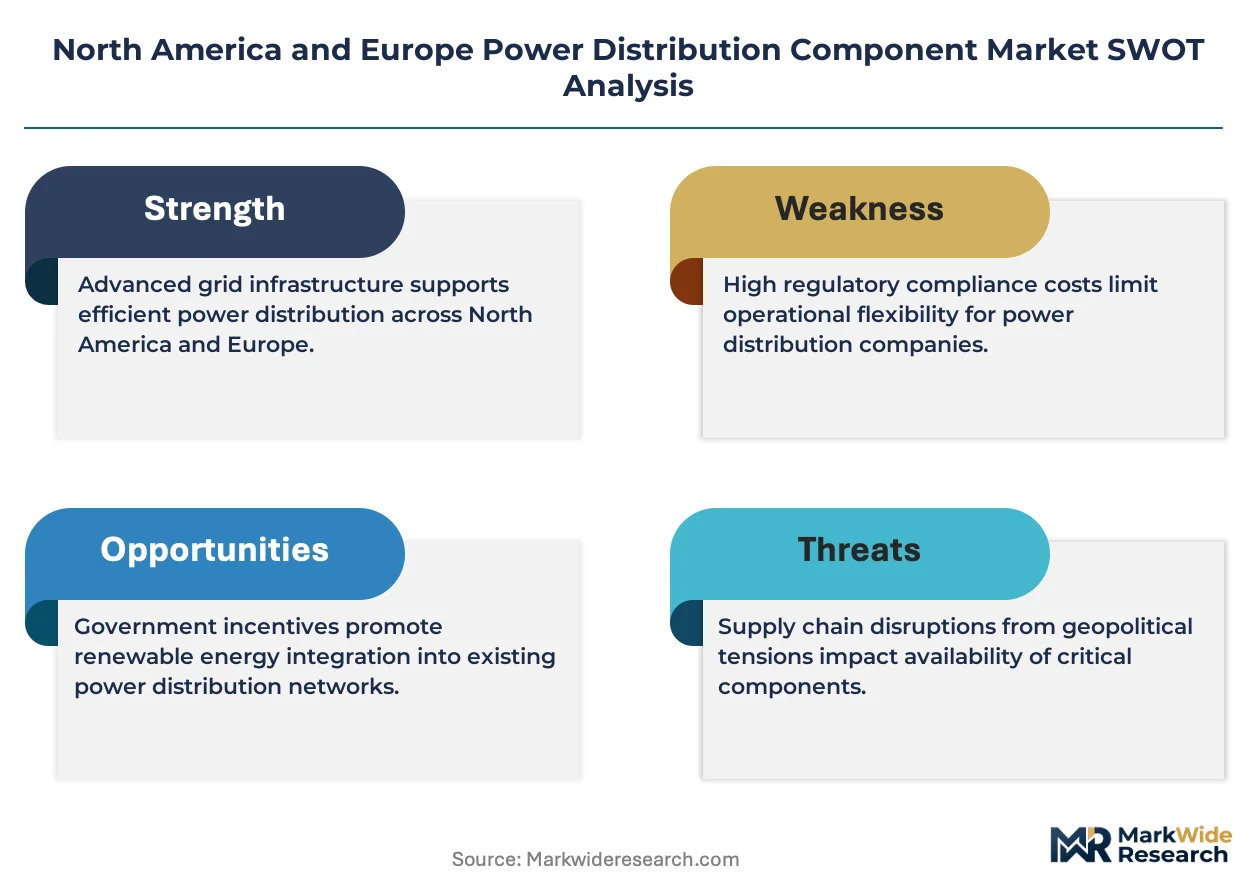
The EU Green Deal and F-Gas Regulation are forcing manufacturers to eliminate sulfur hexafluoride in new switchgear designs, while the EPA's Significant New Alternatives Policy program governs transition pathways in the United States. NERC CIP cybersecurity standards and the EU Cybersecurity Act are reshaping procurement specifications as grid operators mandate encrypted communication protocols for all digital relays. Stakeholders must monitor the pace of SF6 phase-out schedules against the readiness of vacuum and clean-air interruption technologies at transmission voltage levels.
Market Dynamics
The EU F-Gas Regulation and EPA Significant New Alternatives Policy are forcing simultaneous redesign of SF6-dependent switchgear architectures while grid operators accelerate IEC 61850 digital substation rollouts. This dual pressure is compressing product development cycles and fragmenting supplier capabilities across voltage classes.
Growth Catalysts
- Data Center Load Concentration:Hyperscale operators in Texas and Bavaria are procuring medium-voltage switchgear at unprecedented scale to support AI training clusters. This demand pull is reshaping manufacturer capacity allocation.
- EU Green Deal Efficiency Mandates:Transformer replacement programs prioritize dry-type designs for urban underground installations where fire safety regulations have tightened.
- NERC CIP Cybersecurity Standards:US grid operators now require encrypted communication protocols for all digital protection relays, creating upgrade cycles across aging substation infrastructure.
Market Restraints
- Copper and Grain-Oriented Electrical Steel Volatility:Transformer core material costs swing with energy-intensive smelting economics, compressing margins on fixed-price utility contracts.
- SF6 Alternative Technical Readiness Gap:Vacuum and clean-air interruption technologies remain unproven at transmission voltage levels above 145kV, constraining product roadmaps.
- Specialized Engineering Talent Scarcity:IEC 61850 systems integration requires rare expertise combining power engineering with IT protocol architecture.
Strategic Opportunities
- Polish and Romanian Grid Modernization:EU cohesion funds are unlocking substation upgrade budgets in member states with below-average digital relay penetration.
- Digital Twin Convergence:Integration of switchgear analytics with grid automation software creates recurring revenue streams beyond hardware sales.
- SF6-Free Product Differentiation:Early certification under evolving F-Gas phase-out schedules secures preferential positioning in German and French utility tenders.
Industry Challenges
- IEC 61850 Multi-Vendor Interoperability:Process bus implementations from different suppliers frequently fail conformance testing, extending commissioning timelines.
- Legacy Electromechanical Relay Decommissioning:Utilities face operational risk during cutover periods when analog and digital protection systems must run in parallel.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America and Europe Power Distribution Component Market |
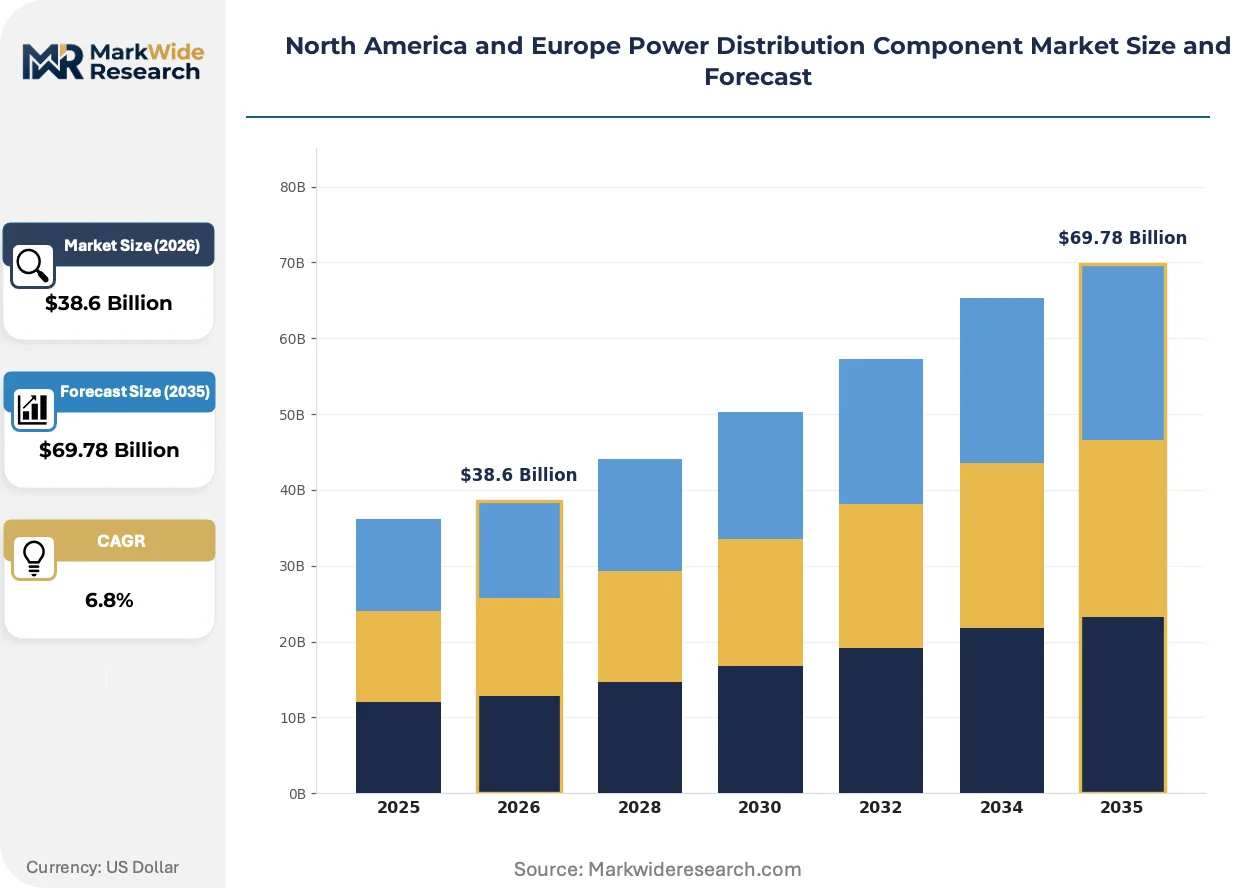
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Transformers, Circuit Breakers, Switchgear, Protective Relays End User: Utilities, Commercial Buildings, Industrial Plants, Renewable Energy Facilities Installation Type: Indoor, Outdoor, Overhead, Underground Technology: Analog, Digital, Smart Grid, Automated |
| Companies Covered | ABB, Schneider Electric, Eaton, Siemens, General Electric, Hubbell, Hitachi Energy, Lucy Electric, Powell Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America and Europe Power Distribution Component Market Evolving Landscape
Digital substation architectures are collapsing traditional copper-intensive wiring harnesses while regulatory pressure on insulating gases accelerates materials science investment. These shifts are redrawing competitive boundaries between electromechanical incumbents and software-centric entrants.
Solid-state power electronics is overtaking conventional mechanical interruption in medium-voltage distribution applications. Silicon carbide-based fault current limiters enable faster clearing times than vacuum interrupters. German utilities are piloting these systems in urban ring-main units where space constraints favor compact designs. The technology is overtaking legacy air-magnetic breakers in ratings below 15kV, compressing the addressable market for conventional switchgear.
EPA Significant New Alternatives Policy is tightening permissible global warming potential thresholds for electrical equipment insulating media. Manufacturers must submit comprehensive toxicity and atmospheric impact data for SF6 substitutes. This regulatory burden falls heaviest on North American oil and gas facility operators where hazardous-location certification requirements already extend product approval timelines.
Utilities are unbundling after-sales service contracts from initial equipment procurement. Texas municipal power authorities now separately tender ten-year maintenance agreements for digital relay fleets. This purchasing pattern shift concentrates service revenue with firms possessing localized technician networks rather than original equipment manufacturers.
North America and Europe Power Distribution Component Market Segmentation
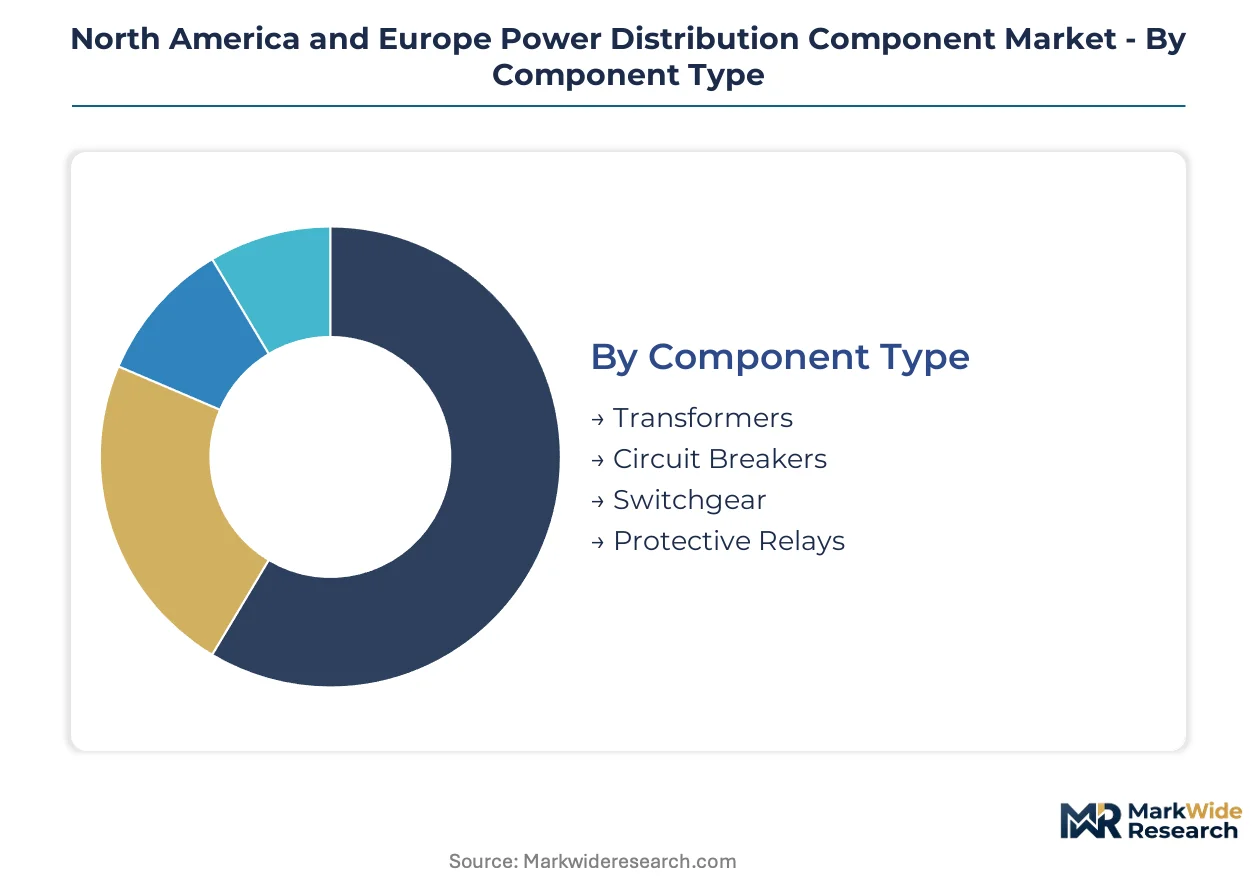
Power distribution component procurement varies sharply across voltage classes, environmental constraints, and digital maturity levels. Segment boundaries are blurring as IEC 61850 architectures force hardware-software bundling decisions that reshape traditional component categories.
Component Type:
Voltage rating and insulating medium specifications determine margin structure and replacement cycle length across each hardware category.
- Transformers:Dry-type resin-encapsulated designs are displacing oil-filled units in German urban substations where fire safety codes have tightened. Bavarian utilities are procuring these at triple the historical rate to meet underground installation mandates.
- Switchgear:Medium-voltage SF6-dependent architectures face forced redesign under EU F-Gas Regulation phase-out schedules. Texas data center operators are absorbing production capacity for gas-insulated switchgear rated 15-38kV ahead of alternative technology availability.
- Circuit Breakers:Vacuum interruption dominates distribution ratings below 36kV across both regions.
- Protective Relays:Electromechanical units still protect aging infrastructure in rural Poland and Romania.
Transformers lead on scale; switchgear leads on momentum as SF6 transition urgency accelerates procurement timelines.
End User:
Capital deployment cycles and regulatory exposure create distinct purchasing behaviors across customer categories.
- Utilities:Grid operators in Texas and Bavaria are consolidating procurement under framework agreements that span ten-year maintenance windows. NERC CIP compliance costs are embedding cybersecurity specifications into every relay purchase.
- Renewable Energy Facilities:Offshore wind interconnectors in the North Sea are demanding compact switchgear with marine-grade corrosion protection. These projects are climbing the fastest as EU Green Deal funding unlocks project finance.
- Commercial Buildings:Fire-rated dry-type transformers are standard for high-rise electrical rooms in Frankfurt and Chicago.
- Industrial Plants:Hazardous-location certifications govern switchgear selection for petrochemical facilities on the US Gulf Coast.
Utilities dominate absolute volume; renewable facilities show steepest expansion trajectory.
Installation Type:
Physical siting constraints dictate insulation system selection and access protocol requirements.
- Underground:Urban density in Frankfurt and Manhattan is forcing cable-fed substations into basement vaults where dry-type transformers are mandatory. Heat dissipation engineering now determines unit sizing more than electrical load calculations.
- Outdoor:Substation expansions in rural Texas and Bavaria favor open-air construction for maintenance access. These installations retain oil-filled transformer options where fire separation distances permit.
- Indoor:Commercial building electrical rooms require compact switchgear with arc-flash containment.
- Overhead:Distribution line hardware in Poland and Romania continues using conventional pole-mounted transformers.
Outdoor installations lead on scale; underground leads on specification intensity.
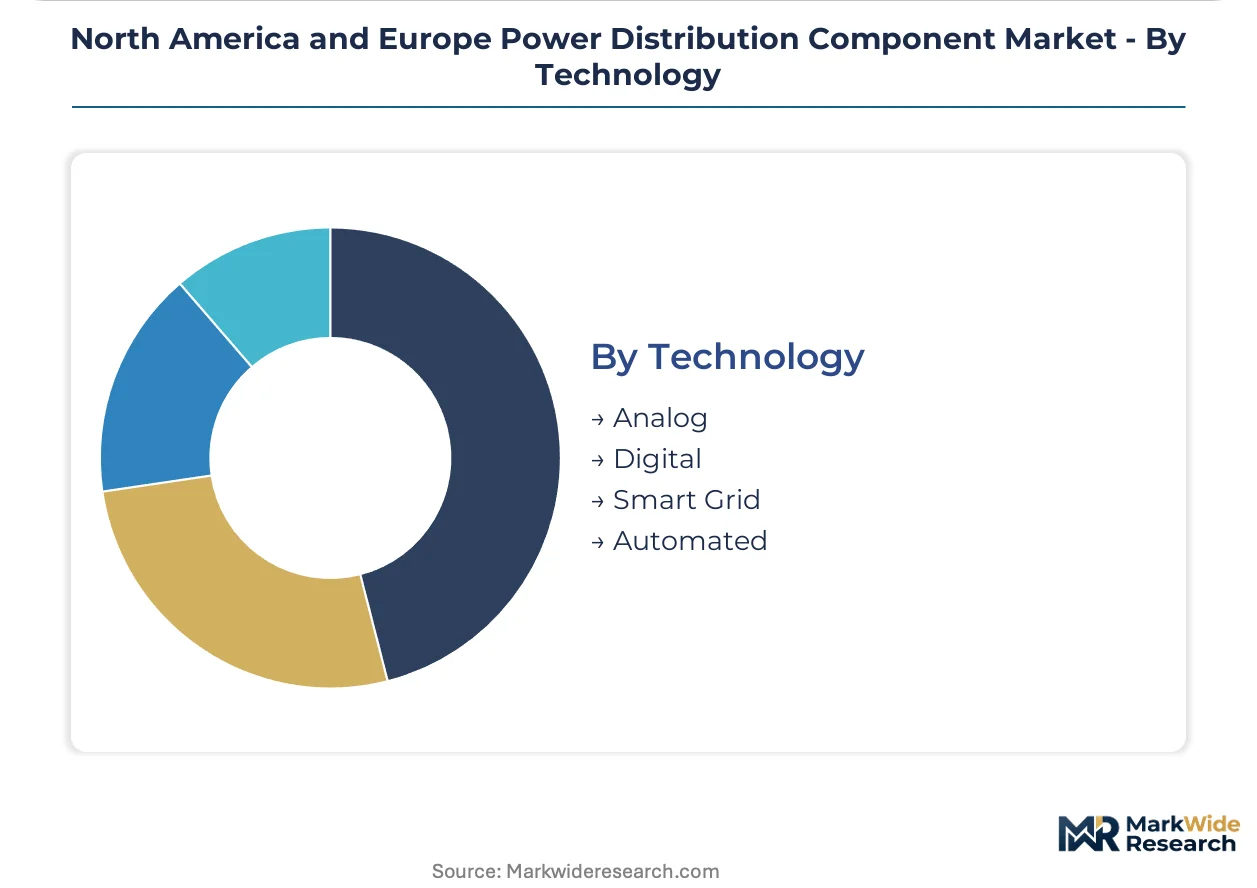
Technology:
Digital maturity tiers separate replacement-driven demand from greenfield architecture decisions.
- Smart Grid:IEC 61850-9-2 process bus implementations are collapsing copper wiring density in new German substations. These systems command premium pricing against analog alternatives but reduce lifecycle engineering costs.
- Digital:Microprocessor-based protection relays with encrypted communication protocols are becoming mandatory under NERC CIP standards. US municipal utilities are upgrading aging electromechanical fleets on compliance deadlines.
- Automated:Self-healing distribution networks in Denmark and the Netherlands use automated switchgear to isolate faults without operator intervention.
- Analog:Electromechanical relays persist in Eastern European installations with limited technical workforce for digital commissioning.
Digital systems lead on current deployment volume; smart grid architectures are gaining share fastest as greenfield substation construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces France in transformer procurement velocity, while Texas municipalities absorb switchgear capacity faster than California utilities. The EU Green Deal and F-Gas Regulation are compressing product development cycles across both regions.
United States
Texas data center operators are procuring medium-voltage switchgear at unprecedented scale for AI training clusters. The EPA's Significant New Alternatives Policy governs SF6 transition pathways for electrical equipment. Houston and Dallas-Fort Worth anchor this demand concentration as grid modernization budgets expand.
Germany
Bavarian utilities are procuring dry-type transformers at triple historical rates for underground installation mandates. The EU F-Gas Regulation forces redesign of SF6-dependent switchgear architectures. Munich and Nuremberg cluster this procurement activity where fire safety codes have tightened.
Poland
EU cohesion funds are unlocking substation upgrade budgets in regions with below-average digital relay penetration. The EU Cybersecurity Act reshapes procurement specifications for encrypted communication protocols. Warsaw and Kraków concentrate this modernization spending.
United Kingdom
Offshore wind interconnectors in the North Sea demand compact switchgear with marine-grade corrosion protection. The EU Green Deal efficiency mandates extend to UK transformer replacement programs. Aberdeen and Liverpool anchor this renewable infrastructure buildout.
Canada
NERC CIP cybersecurity standards drive upgrade cycles across aging substation infrastructure near US border interconnections. Provincial utilities prioritize encrypted digital protection relays. Ontario and Quebec concentrate this compliance-driven procurement.
North America and Europe Power Distribution Component Market Competitive Landscape
Top-tier vendors anchor premium-tier digital substation deployments, while mid-tier specialists compete on hazardous-location certifications and regional service networks. The market structure consolidates around integrated hardware-software platforms. Three archetypes dominate: European manufacturing-anchored smart grid deployers, North American oil and gas enclosure specialists, and integrated digital twin platform providers. Competitive moves center on SF6-free product certification racing and ten-year maintenance contract unbundling.
Among the integrated platform tier, ABB, Schneider Electric, and Siemens occupy positions that exemplify the convergence of switchgear hardware with grid automation software. These European-anchored entities represent the archetype of manufacturing footprint leverage for smart grid deployments. Their positioning reflects the dual pressure of F-Gas regulatory compliance and IEC 61850 digital architecture adoption.
| Leading Market Players |
|---|
| ABB |
| Schneider Electric |
| Eaton |
| Siemens |
| General Electric |
| Hubbell |
| Hitachi Energy |
| Lucy Electric |
| Powell Industries |
| Others |
Value Network & Pricing Analysis
Data center procurement consolidation in Texas and Bavaria is forcing manufacturers to allocate capacity toward medium-voltage switchgear with IEC 61850 compliance, compressing margins on legacy analog product lines and elevating price premiums for digital-native architectures.
Pricing Analysis
Capacity additions in Germany and the United States are reshaping price floors for SF6-free switchgear as EU F-Gas Regulation deadlines accelerate. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61850-certified digital substations from basic indoor switchgear. Price differentiation hinges on cybersecurity certification grade and after-sales service bundling. Cost compression in the commodity tier is intensifying because copper and grain-oriented electrical steel volatility squeezes fixed-price utility contracts. Commercial building operators exhibit highest price sensitivity; grid operators in Texas and Bavaria absorb premiums for fire-rated dry-type transformers.
Supply Chain Analysis
Single-source vulnerability sits with Chinese suppliers of grain-oriented electrical steel for transformer cores. Manufacturing concentrates in Germany, the United States, and China for switchgear assemblies and protective relay electronics. Raw material flows draw from Chilean copper smelters, Ukrainian electrical steel mills, and Japanese silicon carbide substrate producers. Tariff exposure on Chinese electrical steel imports threatens margin stability for North American transformer producers. Distribution runs through authorized distributor networks and direct utility framework agreements with ten-year maintenance windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arbitrage potential exists between German manufacturing costs under EU carbon border adjustments and Texas procurement budgets unconstrained by F-Gas Regulation compliance timelines.
For Market Incumbents: Deepen backward integration into cast-resin transformer insulation systems to defend against Asian competitors capturing standard-tier switchgear volume. Secure early F-Gas certification for SF6-free product lines ahead of German and French utility tender windows. Anchor capacity expansion in Poland and Romania where EU cohesion funds unlock substation upgrade demand. For New Entrants and Emerging Players: Silicon carbide-based fault current limiters offer a technology-first wedge into urban ring-main unit replacements below 15kV where German utilities pilot solid-state interruption. Target Polish and Romanian digital relay penetration gaps with IEC 61850 integration services rather than hardware manufacturing. Pursue hazardous-location certification partnerships with Gulf Coast petrochemical operators seeking enclosure upgrades. For Investors and Strategic Acquirers: Asymmetric upside sits with regional service networks possessing localized technician capacity for digital relay commissioning. Five-to-ten-year viability favors firms combining SF6-free product portfolios with recurring maintenance contract revenue streams. Watch German and French utility tender award patterns as inflection signals for clean-air interruption technology readiness at transmission voltage levels.| Strategic Initiative | Industry Significance |
|---|---|
| SF6-Free Product Certification | Early F-Gas compliance secures preferential positioning in German utility procurement frameworks. |
| Digital Twin Platform Integration | Switchgear analytics bundled with grid automation software creates recurring revenue beyond hardware sales. |
| Regional Service Network Expansion | Localized technician capacity captures unbundled ten-year maintenance contracts from Texas municipal authorities. |
| IEC 61850 Systems Integration Capability | Rare expertise combining power engineering with IT protocol architecture commands premium pricing in greenfield substations. |
| Backward Integration into Core Materials | In-house production of grain-oriented electrical steel insulates margin pressure from commodity volatility. |
Research Methodology
Bottom-up utility procurement modeling reconciled against top-down manufacturer capacity tracking forms the analytical core. Primary interviews with grid planning officers, substation project engineers, EPC contractors, and digital relay commissioning specialists were validated against secondary sources including FERC interconnection filings, EIA transformer shipment data, EU F-Gas Regulation implementation reports, and IEC 61850 conformance testing databases. Triangulation between demand-side budget disclosures and supply-side production schedules ensures segmentation integrity.
Historical trendline analysis of transformer replacement cycles and switchgear procurement patterns across voltage classes informs projection mechanics. The model segments by component type, end-user category, installation environment, and digital maturity tier throughout the forecast period. CAGRs were derived from regression analysis of utility capital expenditure trajectories and data center load growth assumptions. Forecast inputs incorporate EU Green Deal funding disbursement schedules and NERC CIP compliance deadline impacts on relay upgrade cycles.
The model holds under stable copper and electrical steel pricing; deviation in commodity volatility or F-Gas phase-out acceleration would shift manufacturer margin trajectories. Forecasts reflect documented assumptions about technology substitution rates and regulatory enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Distribution
Brazil City Gas Distribution Market
Power Distribution
Power Distribution Unit (PDU) Market
Power Distribution
Distribution Board Market
Power Distribution
Medium Voltage AC Power Distribution Units (PDU) Market
Power Distribution
Europe DC Distribution Network Market
Power Distribution
Distribution Panel Market
Power Distribution
Power Distribution Cables Market
Power Distribution
Lighting and Distribution Panel Board Market
Power Distribution
Global Power Distribution Component Market
Power Distribution
AI in Energy Distribution Market
Power Distribution
Global Electric Power Distribution Automation Systems Market