
 Europe DC Distribution Network Market | 2026-2036
Europe DC Distribution Network Market Size, Share, and Industry Trends Forecast 2026-2036
Europe DC Distribution Network Market Insights
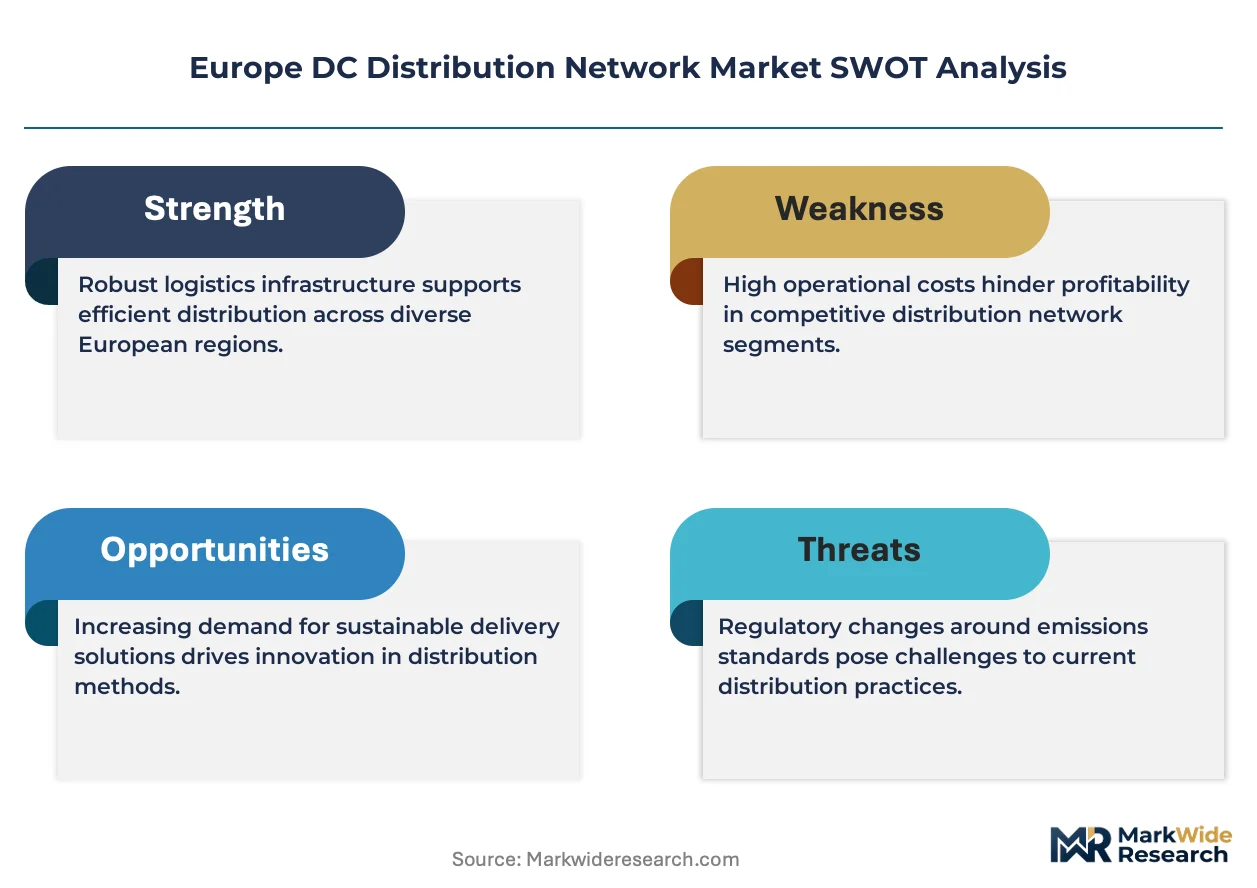
Aftermarket service revenue is fragmenting across the Europe DC Distribution Network Market as hardware commoditization pushes value toward lifecycle services and digital monitoring. ABB Ltd leverages its installed base across Nordic utilities to sustain recurring service contracts. Siemens anchors its position through deep integration with building automation and grid-edge software. Schneider Electric differentiates by controlling the channel for prefabricated modular DC power solutions.
A DC distribution network transmits direct current power from generation or conversion points to end loads through busbars, switchgear, and protection systems rated typically from 48 V to 1,500 V DC, eliminating rectification losses inherent in AC conversion chains. The primary purpose is to deliver efficient, reliable power to data centers, renewable energy installations, and electrified transport infrastructure where source and load natively operate on DC. Installation services lead the Service Type segment as hyperscale builds accelerate across Northern Europe, while Monitoring commands expanding margins through predictive analytics integration. The Data Centers end-user category occupies the fastest-growing demand pool, driven by AI training clusters requiring megawatt-scale DC feeds.
The EU Green Deal and F-Gas Regulation shape product standards by mandating lower-loss power architectures and restricting fluorinated gas use in cooling-linked electrical systems. ECHA's REACH framework governs material composition in switchgear housings and busbar insulation, affecting supplier qualification timelines. CE marking under the Low Voltage Directive remains the gate for market access across EU member states. Stakeholders must monitor how the EU AI Act's energy disclosure requirements reshape procurement criteria for DC infrastructure serving compute-intensive workloads.
Market Dynamics
AI training clusters across Frankfurt, Amsterdam, and Dublin are forcing hyperscale operators to abandon traditional AC distribution chains in favor of native DC architectures that eliminate double-conversion losses. This compute density wave is restructuring supplier relationships and certification requirements across Northern European data center corridors.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated gases in cooling-linked electrical systems accelerate DC adoption in facilities seeking refrigerant-free thermal management.
- Hyperscale compute density:AI training workloads in Frankfurt and Amsterdam clusters demand megawatt-scale DC feeds that AC infrastructure cannot economically provision.
- REACH material compliance:ECHA's framework for switchgear housings and busbar insulation creates qualification barriers that favor established DC suppliers with certified supply chains.
Market Restraints
- Copper price volatility:Busbar fabrication depends on copper cathode inputs whose price swings compress margin visibility for installation contractors.
- Nordic supply concentration:ABB Ltd's installed base dominance across Swedish and Norwegian utilities limits competitive access to replacement and upgrade cycles.
- Legacy AC asset inertia:Existing transformer and switchgear investments in German industrial parks create path dependency against full DC conversion.
Strategic Opportunities
- Polish data center corridor:Warsaw and Krakow hyperscale builds remain underpenetrated by DC-native suppliers despite accelerating cloud investment.
- EU AI Act energy disclosure:Mandatory reporting for compute-intensive workloads creates procurement preference for metered, efficient DC distribution systems.
- Prefabricated modular integration:Factory-integrated power skids combining switchgear, busbars, and monitoring collapse on-site commissioning timelines.
Industry Challenges
- DC protection engineering scarcity:Qualified engineers capable of designing 1,500 V DC fault protection remain concentrated among German and Swiss specialists.
- CE marking timeline compression:Low Voltage Directive conformity assessment for novel DC topologies extends supplier qualification beyond typical project windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe DC Distribution Network Market |
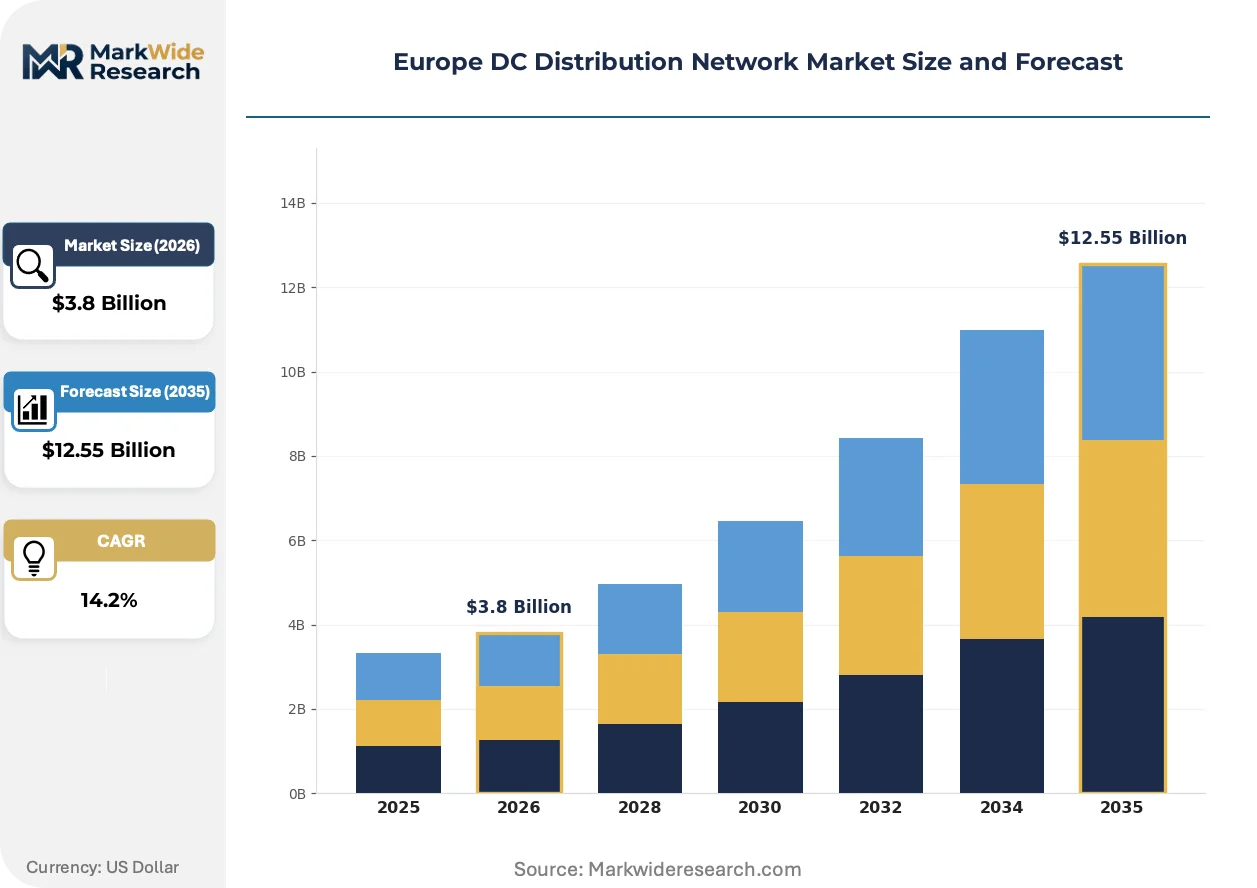
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Installation, Configuration, Monitoring End User: Retailers, Wholesalers, Data Centers, Telecom Providers Capacity: Low, Medium, High, Ultra Technology: Wireless, Wired, Hybrid, Fiber Optic |
| Companies Covered | ABB Ltd, Siemens AG, Eaton Corporation, Vertiv Group Corporation, Schneider Electric SE, Hitachi Energy Ltd, Delta Electronics Inc, GE Grid Solutions, Secheron SA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe DC Distribution Network Market Trends and Innovations
Solid-state circuit protection and digital twin monitoring are converging to redefine how DC distribution networks are commissioned, operated, and maintained across European data center infrastructure.
Wide-bandgap semiconductors in solid-state DC breakers are collapsing the physical footprint and response latency of protection systems compared to electromechanical alternatives. Hyperscale operators in Frankfurt and Amsterdam are specifying these devices for 1,500 V busbar feeds serving AI training racks. The technology is collapsing the traditional separation between power distribution and power electronics engineering teams within facility design firms.
REACH enforcement on halogen-free insulation materials is compelling busbar manufacturers to reformulate jacketing compounds and revalidate fire performance ratings. German industrial parks and Dutch logistics facilities face the tightest compliance deadlines under ECHA's authorization schedules. Suppliers with pre-certified material portfolios are capturing specification preference in public tender processes.
Lifecycle service unbundling is fragmenting the traditional EPC model for DC distribution projects across Northern Europe. Data center operators in Dublin and Frankfurt are separating hardware procurement from installation and commissioning, then layering predictive monitoring subscriptions atop asset ownership. This purchasing pattern is most pronounced among colocation providers seeking to arbitrage capital deployment against operational expenditure reporting.
Europe DC Distribution Network Market Segmentation
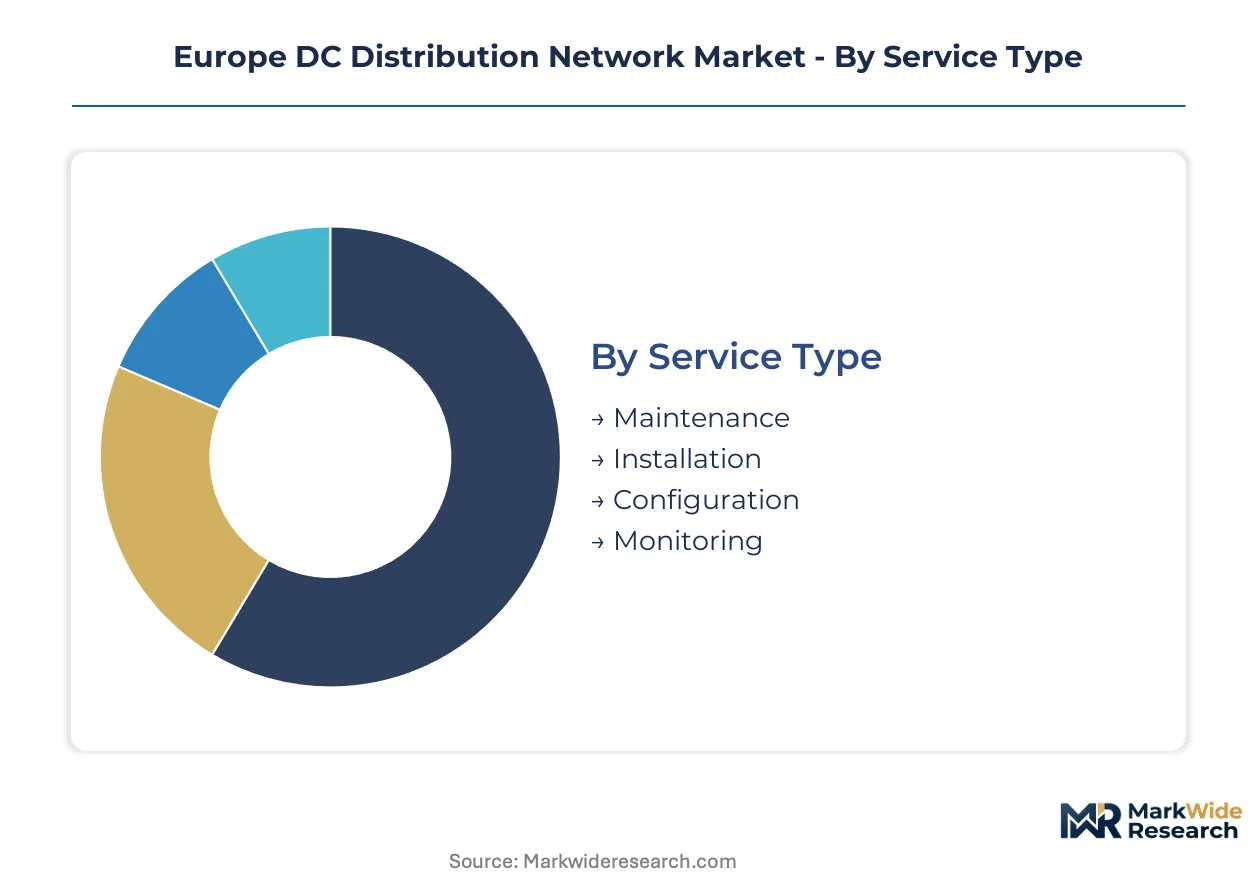
Segmentation reveals how procurement patterns fragment across technical specifications and operational requirements in the Europe DC Distribution Network Market. Understanding these divisions exposes where margin concentrates and which service lines face commoditization pressure.
Service Type:
Installation cycles compress to weeks during hyperscale construction surges, while maintenance contracts stretch across decades of asset life. Configuration and monitoring sit between these extremes, with renewal rates tied to technology refresh intervals.
- Installation:Physical deployment of busbar systems, switchgear assemblies, and protection equipment rated from 48 V to 1,500 V DC. Frankfurt and Amsterdam hyperscale clusters drive peak demand as AI training facilities require megawatt-scale native DC feeds that eliminate double-conversion losses. Copper price volatility squeezes contractor margins on fixed-bid projects.
- Monitoring:Predictive analytics platforms integrating digital twin models with real-time thermal and electrical parameter tracking. Dublin colocation providers layer these subscriptions atop asset ownership to arbitrage capital deployment against operational expenditure reporting. REACH-compliant sensor housings create qualification barriers for new entrants.
- Maintenance:Lifecycle service contracts covering breaker testing, busbar inspection, and insulation resistance verification.
- Configuration:Commissioning services for protection coordination, arc flash mitigation, and SCADA integration.
Installation anchors the volume base while Monitoring gains share at the steepest rate.
End User:
Procurement sophistication varies sharply across customer types, with data center operators demanding factory-integrated power skids while retailers accept standardized catalog configurations.
- Data Centers:Hyperscale and colocation facilities requiring 1,500 V DC busbar feeds for AI training racks and high-density compute pods. Dublin, Frankfurt, and Amsterdam clusters lead specification intensity as operators abandon AC distribution chains for native DC architectures. EU AI Act energy disclosure mandates reshape procurement criteria toward metered, efficient systems.
- Telecom Providers:Edge computing nodes and central office power upgrades driving 48 V to 400 V DC distribution demand. Nordic operators prioritize REACH-compliant materials in submarine cable landing stations and Arctic Circle facilities. F-Gas Regulation restrictions accelerate DC adoption in refrigerant-free thermal management designs.
- Wholesalers:Distribution intermediaries stocking standardized switchgear and busbar components for contractor resale.
- Retailers:Commercial facility operators deploying basic DC systems for EV charging integration and renewable self-consumption.
Data Centers command premium pricing tiers while Telecom Providers expand most quickly across the installed base.
Capacity:
Engineering complexity and protection system cost scale non-linearly with voltage and current ratings, creating distinct competitive arenas.
- High:Systems rated above 1,000 V DC serving megawatt-scale AI training clusters and utility-scale battery storage integration. German industrial parks and Dutch logistics hubs specify these tiers for renewable coupling and peak shaving applications. Qualified engineers for 1,500 V DC fault protection remain concentrated among German and Swiss specialists.
- Ultra:Emerging multi-megawatt architectures for next-generation semiconductor fabrication and fusion research facilities. CERN and ITER-adjacent projects in France drive early specification activity. CE marking timeline compression under the Low Voltage Directive extends supplier qualification beyond typical project windows.
- Medium:400 V to 1,000 V DC systems for commercial data halls and manufacturing electrification.
- Low:48 V to 400 V DC installations for telecom, retail, and light commercial applications.
Medium capacity systems dominate shipment volumes while Ultra capacity climbs the fastest as frontier applications mature.
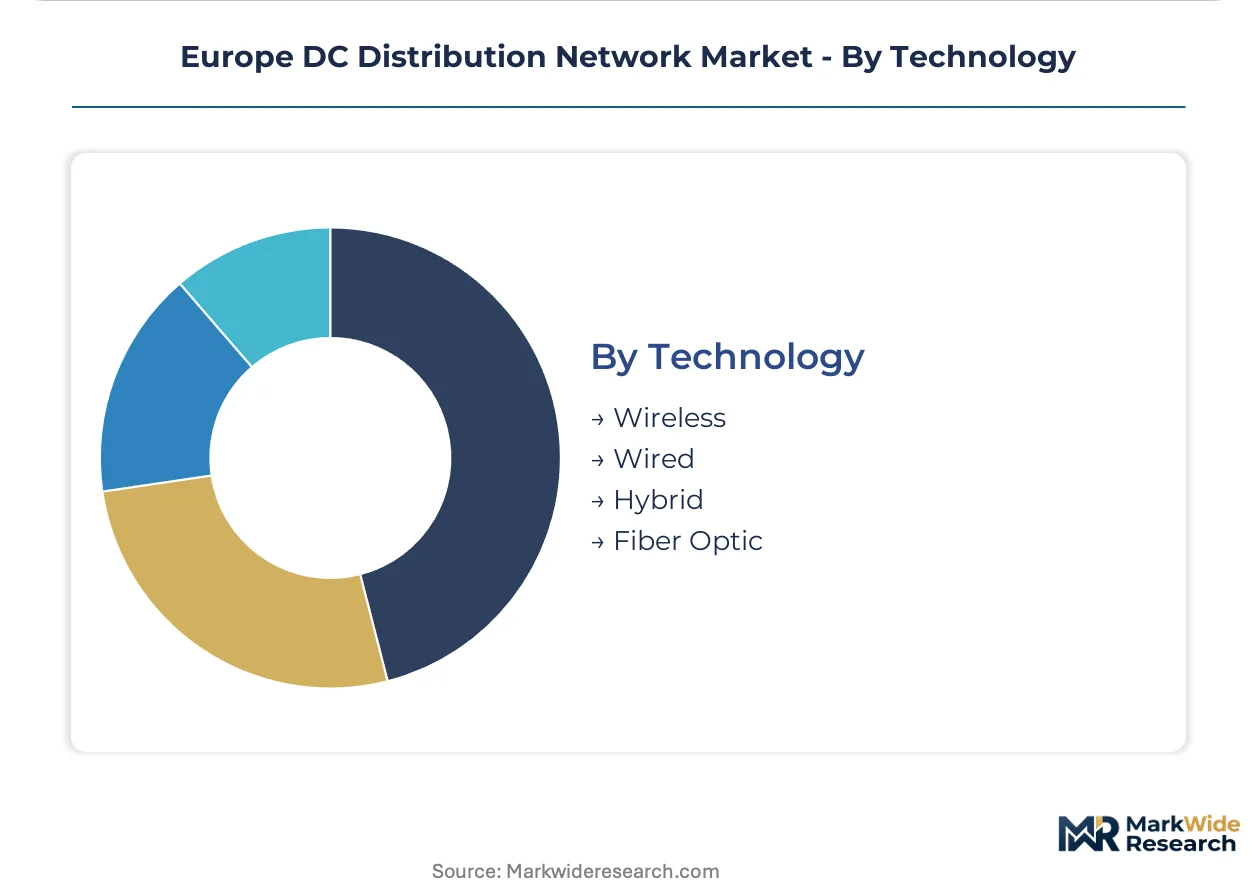
Technology:
Physical layer choices determine signal integrity, electromagnetic compatibility, and maintenance accessibility across facility lifecycles.
- Wired:Copper busbar and cable systems with established supply chains and straightforward fault location protocols. Frankfurt hyperscale operators specify these for primary power distribution where electromagnetic interference is controlled through facility shielding. Copper cathode price swings compress margin visibility for installation contractors.
- Fiber Optic:Dielectric power and communication hybrid cables eliminating ground loop risks in high-voltage environments. Amsterdam data centers deploy these for control signal integrity across large floorplates. ECHA REACH enforcement on halogen-free jacketing compounds drives material reformulation cycles.
- Wireless:Inductive and capacitive coupling systems for mobile equipment and temporary power distribution.
- Hybrid:Architectures combining conductive power paths with fiber optic monitoring and control channels.
Wired technology anchors the volume base while Fiber Optic gains specification preference at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial parks deploy DC distribution for renewable coupling, while Dutch and Irish facilities prioritize native DC architectures for AI compute density. This consumption-mix differential reflects varying regulatory pressure and infrastructure vintage across Northern European corridors.
Germany
Industrial electrification and data center expansion in Frankfurt and Berlin drive medium-to-high voltage DC demand. The EU F-Gas Regulation accelerates refrigerant-free thermal management designs in Bavarian manufacturing zones. NRW's Ruhr industrial corridor sees legacy AC-to-DC conversion projects for peak shaving and renewable integration.
Netherlands
Amsterdam's hyperscale cluster requires megawatt-scale 1,500 V DC feeds for AI training racks that AC infrastructure cannot provision economically. REACH compliance on halogen-free busbar insulation tightens qualification timelines for Eindhoven-area suppliers. The Randstad logistics hub specifies DC distribution for electrified transport and warehouse automation.
Ireland
Dublin's colocation market layers predictive monitoring subscriptions atop DC asset ownership to arbitrage capital deployment. ECHA material frameworks govern switchgear housings in submarine cable landing stations. Cork and Limerick edge computing nodes drive 48 V to 400 V DC demand for distributed power architectures.
France
Île-de-France data centers and CERN-adjacent research facilities specify ultra-high capacity DC systems for fusion and semiconductor applications. The EU AI Act's energy disclosure mandates reshape procurement toward metered DC distribution. Lyon and Grenoble industrial zones adopt DC for manufacturing electrification under Green Deal targets.
Poland
Warsaw and Krakow hyperscale builds remain underpenetrated by DC-native suppliers despite accelerating cloud investment. CE marking under the Low Voltage Directive extends supplier qualification timelines for novel topologies. The country's logistics corridor deploys medium-voltage DC for warehouse automation and EV charging integration.
Europe DC Distribution Network Market Competitive Landscape
Capability concentration sits with specialized engineering houses; scale advantage sits with diversified electrical conglomerates. The market structures around three tiers: integrated power majors with prefabricated modular portfolios, component specialists with certified material supply chains, and regional installation contractors with local commissioning expertise. Dominant competitive moves include backward integration into copper busbar fabrication and strategic partnerships with hyperscale data center developers for factory-integrated power skids.
Among Switzerland-based protection engineering specialists, Secheron SA occupies a position representing the high-voltage DC breaker archetype. ABB Ltd and Siemens AG exemplify the diversified conglomerate tier with established installed bases across Nordic utilities and deep integration with building automation systems. Schneider Electric SE anchors the prefabricated modular solutions vector, controlling distribution channels for integrated power skids.
| Leading Market Players |
|---|
| ABB Ltd |
| Siemens AG |
| Eaton Corporation |
| Vertiv Group Corporation |
| Schneider Electric SE |
| Hitachi Energy Ltd |
| Delta Electronics Inc |
| GE Grid Solutions |
| Secheron SA |
| Others |
Pricing and Supply Chain Analysis
German and Swiss protection engineering specialists concentrate high-voltage DC breaker design capability, anchoring margin pools in certification-intensive tiers where qualified engineers command specification influence over Frankfurt and Amsterdam hyperscale builds.
Pricing Analysis
Long-term offtake contracts dominate procurement for megawatt-scale 1,500 V DC installations, insulating prime contractors from copper cathode volatility while spot purchasing governs standardized 48 V to 400 V components. Pricing stratifies across premium, standard, and economy tiers based on REACH certification status and factory-integration depth. Cost compression in installation services is intensifying because hyperscale operators unbundle hardware from commissioning to arbitrage capital deployment. Colocation providers exhibit highest price sensitivity, while CERN-adjacent research facilities prioritize performance over unit economics.
Supply Chain Analysis
EU dual-use export controls on wide-bandgap semiconductor fabrication equipment constrain flows of solid-state DC breaker components from German and Swiss specialists to non-EU markets. Copper cathode supply draws from Chilean mining operations and German secondary refining, with busbar fabrication anchored in Nordic industrial zones. Single-source vulnerability sits with Secheron SA's dominance in 1,500 V DC protection engineering. Distribution runs through factory-integrated power skid channels controlled by Schneider Electric and regional installation contractors with local commissioning expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's DC distribution network market sits in early-cycle expansion as AI training clusters force native DC adoption faster than legacy AC depreciation schedules anticipated.
For Market Incumbents: Entrench installed base relationships across Nordic utilities through predictive monitoring subscriptions that convert capital equipment sales into recurring revenue streams. Backward integration into copper busbar fabrication defends margin position against contractor price compression. Prioritize REACH certification maintenance as ECHA authorization schedules tighten qualification windows for halogen-free insulation materials. For New Entrants and Emerging Players: Establish a beachhead in Poland's underpenetrated Warsaw and Krakow hyperscale corridor where CE marking timelines for novel DC topologies have delayed incumbent qualification. Target 400 V to 1,000 V medium-capacity segments serving manufacturing electrification under EU Green Deal targets. Lead with factory-integrated power skids that collapse on-site commissioning timelines relative to traditional EPC models. For Investors and Strategic Acquirers: Capital is best deployed toward specialized engineering houses with certified material supply chains and 1,500 V DC fault protection expertise concentrated among German and Swiss specialists. Long-term viability hinges on positioning for EU AI Act energy disclosure mandates that reshape procurement criteria toward metered, efficient systems. Watch for inflection when hyperscale operators in Dublin and Frankfurt accelerate unbundling of hardware procurement from lifecycle service contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Busbar Fabrication | Captures margin pools squeezed by cathode price volatility in Frankfurt hyperscale installations. |
| REACH-Compliant Material Portfolio Expansion | Secures specification preference as ECHA halogen-free deadlines tighten across Dutch logistics hubs. |
| Predictive Monitoring Platform Launch | Converts Dublin colocation hardware sales into recurring revenue streams under operational expenditure reporting. |
| Factory-Integrated Power Skid Partnership | Collapses commissioning timelines for Amsterdam AI training clusters demanding 1,500 V DC feeds. |
| 1,500 V DC Protection Engineering Certification | Addresses scarcity of qualified specialists for high-capacity German industrial park deployments. |
Research Methodology
A standing panel of data center engineering directors, EPC contractor procurement leads, switchgear manufacturer product managers, and ECHA regulatory affairs specialists provided ongoing calibration across the analysis window. Primary interviews with hyperscale operators in Frankfurt, Amsterdam, and Dublin combined with secondary validation from EU F-Gas Regulation implementation reports, ECHA authorization schedules, and hyperscaler capex disclosures. Bottom-up project pipeline tracking triangulated against top-down EU Green Deal investment flow estimates.
Scenario-bracketing around AI training cluster deployment timelines and REACH enforcement intensity bounded high and low growth paths across the projection horizon. Segmentation modeling incorporated service type, end-user category, capacity tier, and technology architecture dimensions. CAGRs derived from unit economics analysis of installation versus monitoring revenue mix shifts, with inputs including copper price forward curves and CE marking timeline distributions for novel DC topologies.
Macroeconomic conditions sit as an overlay; deviation in eurozone industrial electricity pricing or Chinese copper cathode export flows would shift the trajectory. Forecasts reflect assumptions about EU AI Act implementation pacing and wide-bandgap semiconductor supply availability. Material shifts in ECHA authorization schedules or hyperscale operator unbundling acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Distribution
Power Distribution Cables Market
Power Distribution
Lighting and Distribution Panel Board Market
Power Distribution
Brazil City Gas Distribution Market
Power Distribution
North America and Europe Power Distribution Component Market
Power Distribution
Global Power Distribution Component Market
Power Distribution
Distribution Panel Market
Power Distribution
Global Electric Power Distribution Automation Systems Market
Power Distribution
AI in Energy Distribution Market
Power Distribution
Medium Voltage AC Power Distribution Units (PDU) Market
Power Distribution
Power Distribution Unit (PDU) Market
Power Distribution
Distribution Board Market