
 Medium Voltage AC Power Distribution Units (PDU) Market | 2026-2036
Medium Voltage AC Power Distribution Units (PDU) Market Size, Share, and Industry Trends Forecast 2026-2036
Medium Voltage AC Power Distribution Units (PDU) Market Foresight
A widening capability gap between integrated manufacturers and assembly-focused competitors is rotating competitive advantage toward firms with captive transformer and breaker production. ABB leverages its in-house semiconductor fabrication for medium voltage drives to sustain margin capture across the full power chain. Siemens anchors its position through deep integration of digital monitoring platforms with switchgear hardware, while Eaton competes by dominating North American channel relationships for floor-mounted industrial configurations.
Medium Voltage AC Power Distribution Units are enclosed electrical assemblies rated between 1 kV and 52 kV that distribute alternating current power through busbars, circuit breakers, and protective relays to secondary loads. These systems employ vacuum or SF6 insulation technologies to interrupt fault currents while maintaining continuous supply to critical infrastructure. Panel board configurations retain the largest installed base across commercial building retrofits, though power distribution unit variants incorporating smart grid communication modules are capturing the fastest expansion in renewable energy interconnection projects where real-time telemetry shapes grid stability outcomes.
The IEC 61439 series governs low-voltage assembly construction while regional implementations of IEEE C37 and GB standards shape medium voltage product acceptance across Europe, North America, and China respectively. EMA and FDA frameworks indirectly influence demand through data center pharmaceutical manufacturing requirements that mandate redundant power architectures. Stakeholders must weigh the capital trade-offs between modular rack-mounted deployments and fixed floor-mounted systems as grid edge electrification intensifies and utility interconnection standards tighten.
Market Dynamics
Data center rack densities above 30 kW per rack are forcing operators to bypass traditional low-voltage distribution, creating direct procurement of medium voltage PDUs with integrated step-down transformers. This voltage-level migration compresses the addressable market for conventional switchgear while expanding the premium segment for compact, liquid-cooled medium voltage assemblies.
Growth Catalysts
- IEC 61439-2 compliance mandates:European data center construction codes now require arc-fault containment testing for all medium voltage assemblies above 10 kV, accelerating replacement cycles in Germany and France.
- SF6 phase-out regulations:The EU F-Gas Regulation and parallel EPA initiatives in the United States are vacuum-interrupter adoption across utility interconnection projects.
- Hyperscale facility construction:Cloud providers in Northern Virginia and Frankfurt are specifying modular medium voltage PDUs with factory-integrated monitoring to compress commissioning timelines.
Market Restraints
- Copper and electrical steel price volatility:Transformer core materials constitute 35-45% of PDU bill-of-materials, exposing margins to London Metal Exchange fluctuations.
- Concentrated vacuum interrupter supply:Three Japanese and German suppliers control 80% of medium voltage vacuum bottle production, creating single-source vulnerability.
- Proprietary communication protocols:Vendor-locked digital monitoring systems impede multi-brand facility integration and extend replacement cycles.
Strategic Opportunities
- India industrial corridor electrification:The country's PLI scheme for manufacturing and CEA grid codes are opening procurement channels for 11 kV and 33 kV assemblies in Gujarat and Tamil Nadu.
- Offshore wind interconnection:66 kV collection platforms require compact medium voltage switchgear with marine-grade sealing, a specification gap among incumbent suppliers.
- Digital twin integration:Convergence of IEC 61850 communication with predictive maintenance platforms creates recurring revenue streams beyond hardware sales.
Industry Challenges
- Medium voltage commissioning engineer scarcity:Qualified technicians for live-switching procedures and protection relay programming are concentrated among retiring utility workforces.
- Multi-standard certification burden:Simultaneous IEEE C37, IEC 62271, and GB 3906 testing extends product launch timelines by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medium Voltage AC Power Distribution Units (PDU) Market |
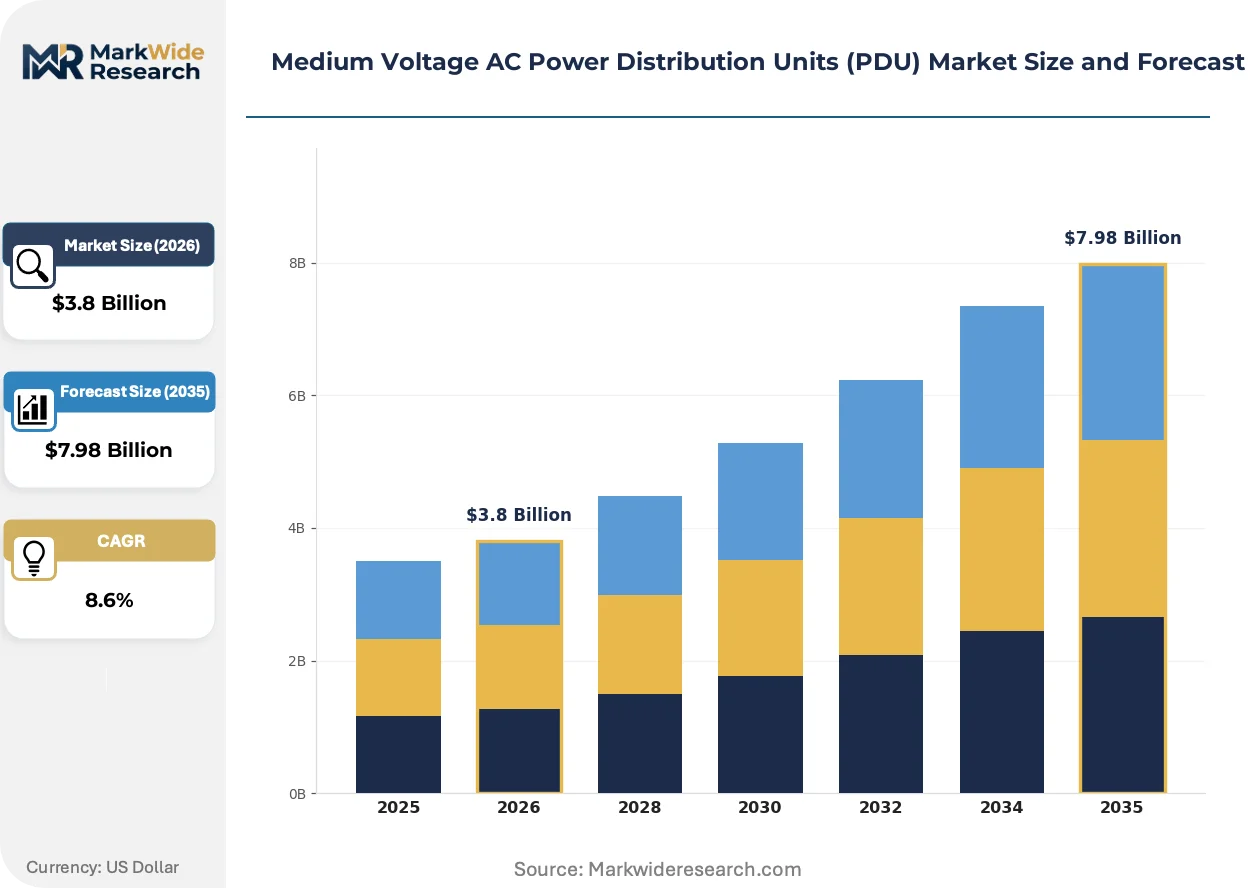
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panel Board, Remote Power Panel, Power Distribution Unit, Switchgear Technology: Digital Monitoring, Smart Grid, Traditional Circuit Breaker, Control System End User: Data Centers, Commercial Buildings, Industrial Facilities, Renewable Energy Installation Type: Floor Mounted, Wall Mounted, Rack Mounted, Modular |
| Companies Covered | ABB, Schneider Electric, Siemens, Eaton, Hitachi Energy, GE Vernova, Mitsubishi Electric, Toshiba Energy Systems & Solutions, GE Grid Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medium Voltage AC Power Distribution Units (PDU) Market Shifts & Advancements
Medium voltage PDU architecture is bifurcating between compact solid-state designs for data centers and rugged air-insulated configurations for heavy industry. This technical divergence is fragmenting R&D investment and reshaping supplier specialization.
Solid-state circuit breakers employing silicon carbide power electronics are fragmenting the traditional electromechanical breaker market. Hyperscale data center operators in Singapore and Ireland are piloting these devices for sub-millisecond fault isolation. The technology is compressing the competitive advantage of legacy vacuum interrupter suppliers while enabling new entrants from power semiconductor backgrounds.
The EU F-Gas Regulation's 2026 SF6 ban deadline is forcing redesign of gas-insulated switchgear across European utility and industrial installations. Manufacturers are accelerating dry air and vacuum insulation development to maintain certification continuity. German TSOs and French industrial parks are most affected, with procurement specifications already excluding SF6-dependent suppliers from tender shortlists.
Specification authority is migrating from electrical contractors to facility energy managers armed with lifecycle cost models. This shift is compressing distributor margins and favoring direct manufacturer relationships for complex medium voltage projects. The pattern is most visible in Nordic markets where CSRD disclosure requirements mandate granular energy infrastructure tracking.
Medium Voltage AC Power Distribution Units (PDU) Market Segmentation
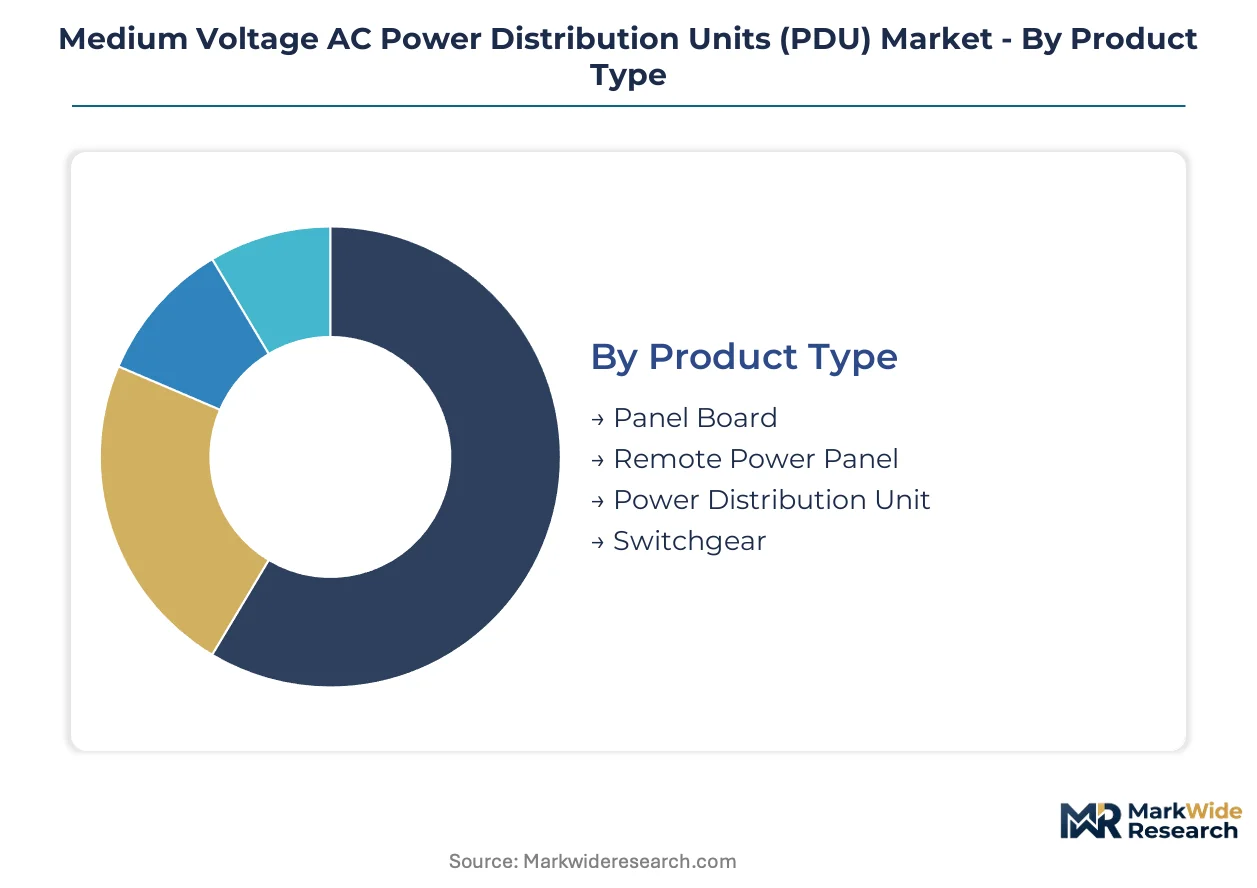
Medium voltage PDU procurement channels diverge sharply by application criticality and technical complexity. Electrical contractors dominate standardized panel board sales while direct manufacturer relationships govern hyperscale data center and offshore wind interconnection projects.
Product Type:
Channel concentration varies dramatically across product categories, with assembly-focused distributors capturing high-volume standardized units while integrated manufacturers control engineered-to-order switchgear.
- Panel Board:Enclosed busbar assemblies rated 1-52 kV distributing power through molded case breakers to secondary circuits. Commercial building retrofits across Germany and France drive replacement demand as IEC 61439-2 arc-fault mandates tighten compliance windows.
- Power Distribution Unit:Integrated assemblies combining medium voltage switchgear with step-down transformers and monitoring systems. Hyperscale data center operators in Northern Virginia and Frankfurt specify factory-integrated PDUs to compress commissioning timelines for 30+ kW rack densities.
- Remote Power Panel:Sub-distribution units extending medium voltage feeds to distant load centers within large facilities.
- Switchgear:Primary protection assemblies employing vacuum or SF6 interruption for utility interconnection and industrial substations.
Panel boards dominate installed base across commercial building stock. Power distribution units are where expansion concentrates as data centers bypass traditional low-voltage distribution.
Technology:
Margin profiles stratify across technology tiers, with hardware-centric traditional breakers yielding commodity returns while digital monitoring platforms generate recurring software revenues.
- Digital Monitoring:IEC 61850-compliant telemetry systems enabling predictive maintenance and asset optimization. Nordic data center operators under CSRD disclosure mandates are driving fastest adoption for granular energy infrastructure tracking.
- Smart Grid:Communication-enabled assemblies supporting real-time grid stability management. Renewable energy interconnection projects in Gujarat and Tamil Nadu require these modules for CEA grid code compliance.
- Traditional Circuit Breaker:Electromechanical fault interruption without embedded intelligence.
- Control System:Protection relay programming and automated switching sequences for utility-grade reliability.
Traditional circuit breakers dominate installed base. Digital monitoring is climbing the fastest as facility energy managers displace electrical contractors in specification authority.
End User:
Customer sophistication determines pricing power, with industrial facilities negotiating on total cost of ownership while commercial buildings focus on first-cost procurement.
- Data Centers:Hyperscale and colocation operators demanding compact liquid-cooled medium voltage assemblies. Singapore and Ireland facilities are piloting solid-state silicon carbide breakers for sub-millisecond fault isolation.
- Industrial Facilities:Heavy manufacturing and process industries requiring rugged air-insulated configurations. German industrial electrification projects are accelerating 11 kV and 33 kV procurement for renewable integration.
- Commercial Buildings:Office and retail installations specifying standardized panel boards for retrofit applications.
- Renewable Energy:Solar and wind farms requiring medium voltage collection and interconnection switchgear.
Industrial facilities dominate installed base. Data centers are gaining share fastest as rack density migration forces voltage-level bypass of traditional distribution.
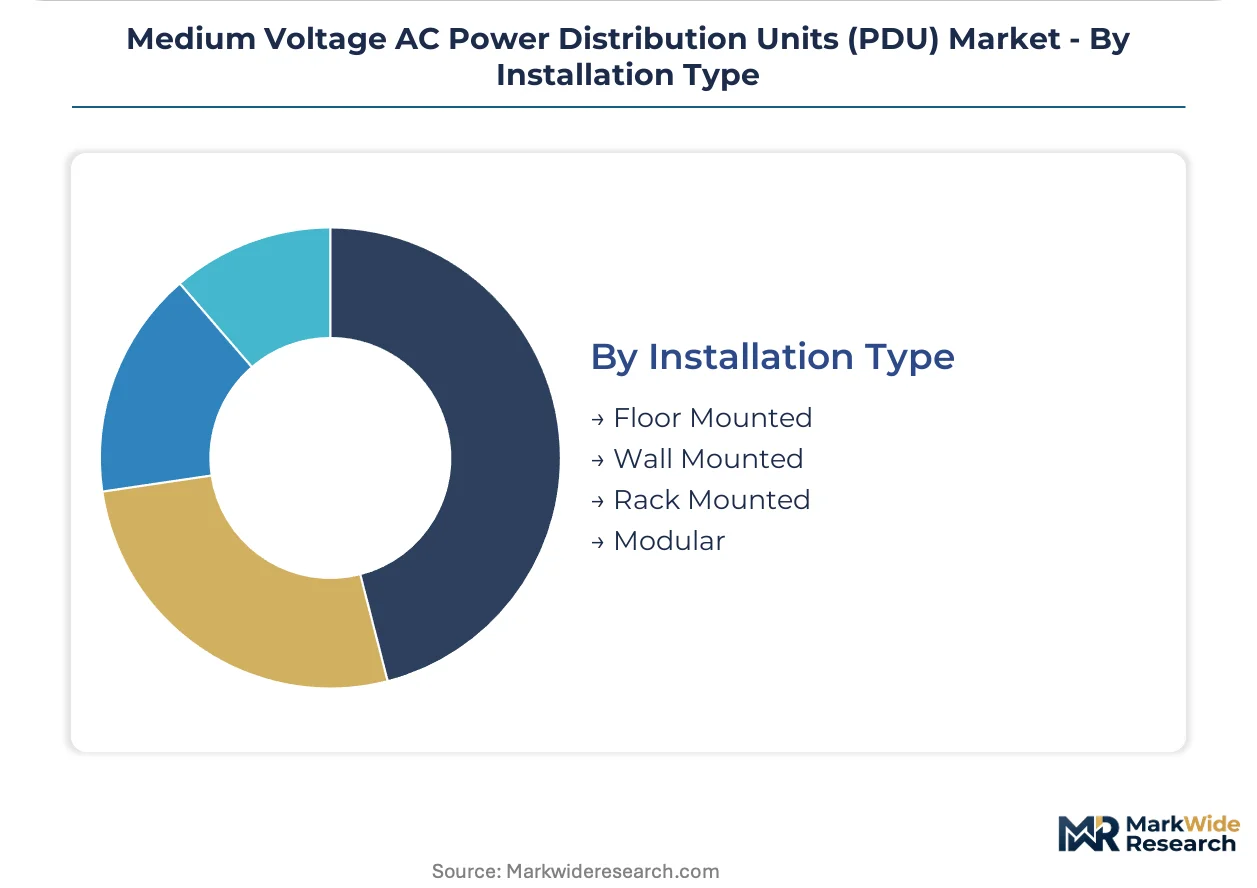
Installation Type:
Capital deployment patterns separate mobile modular solutions from permanent infrastructure, with offshore wind and temporary data center expansions favoring transportable configurations.
- Floor Mounted:Fixed industrial configurations dominating North American manufacturing and heavy process applications. Eaton's channel relationships concentrate here for heavy-industry procurement.
- Modular:Factory-integrated skid-mounted assemblies compressing field commissioning. Cloud providers in Frankfurt and Northern Virginia specify these for hyperscale facility construction velocity.
- Wall Mounted:Space-constrained commercial installations with limited footprint availability.
- Rack Mounted:Compact data center deployments integrating directly with IT infrastructure rows.
Floor mounted systems dominate installed base. Modular configurations are expanding most quickly as grid edge electrification intensifies and utility interconnection standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States demonstrate low price elasticity for mission-critical medium voltage PDUs, while procurement in India and Southeast Asia remains acutely sensitive to first-cost positioning. This demand-elasticity contrast shapes divergent go-to-market strategies across major supply regions.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth drives premium procurement of modular medium voltage PDUs with integrated monitoring. EPA regulations on SF6 emissions accelerate vacuum-interrupter adoption across utility interconnection projects. Pacific Northwest renewable energy clusters specify marine-grade switchgear for offshore wind collection platforms.
Germany
Industrial electrification and renewable integration projects accelerate 11 kV and 33 kV infrastructure procurement across manufacturing belts. The EU F-Gas Regulation's 2026 SF6 ban deadline forces redesign of gas-insulated switchgear, excluding non-compliant suppliers from TSO tender shortlists. Bavarian automotive and chemical facilities anchor demand for arc-fault containment assemblies under tightened IEC 61439-2 mandates.
China
Data center rack density migration in Beijing-Tianjin-Hebei and Yangtze River Delta clusters creates procurement channels for compact liquid-cooled medium voltage assemblies. GB 3906 standards shape product acceptance for domestic grid interconnection projects. Sichuan-Chongqing industrial corridors drive replacement demand as provincial grid codes tighten protection relay requirements.
India
The PLI scheme for manufacturing and CEA grid codes open procurement channels for 11 kV and 33 kV assemblies in Gujarat and Tamil Nadu industrial corridors. Central Electricity Authority regulations mandate smart grid communication modules for renewable energy interconnection. Maharashtra data center operators under state renewable purchase obligations specify medium voltage PDUs to manage rising rack densities.
Singapore
Hyperscale facility operators pilot solid-state silicon carbide breakers for sub-millisecond fault isolation in tropical climate conditions. The country's national energy regulator enforces stringent grid stability standards for data center load interconnection. Jurong and Tuas industrial zones concentrate demand for compact medium voltage switchgear with factory-integrated digital monitoring platforms.
Medium Voltage AC Power Distribution Units (PDU) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the medium voltage PDU market. Swiss and German conglomerates with captive transformer and breaker production sustain margin capture across the full power chain, while assembly-focused competitors face compressing returns on commodity hardware. Two strategic archetypes dominate: vertically integrated power electronics manufacturers and digitally-anchored switchgear specialists. Competitive moves concentrate on backward integration into semiconductor fabrication and convergence with predictive maintenance platforms.
Among integrated European manufacturers, ABB and Siemens occupy positions exemplifying the premium-tier vector where in-house component production meets digital platform integration. Eaton anchors the North American channel-focused archetype for floor-mounted industrial configurations. These three firms represent contrasting strategic postures: semiconductor-captive vertical integration, hardware-software convergence, and regional channel dominance.
| Leading Market Players |
|---|
| ABB |
| Schneider Electric |
| Siemens |
| Eaton |
| Hitachi Energy |
| GE Vernova |
| Mitsubishi Electric |
| Toshiba Energy Systems & Solutions |
| GE Grid Solutions |
| Others |
Supply & Pricing Matrix
Sixteen-to-twenty-week lead times for vacuum interrupter bottles from Japanese and German suppliers compress pricing power toward integrated manufacturers with captive component production, while assembly-focused competitors absorb margin erosion from spot-market copper and electrical steel exposure.
Pricing Analysis
After-sales service contracts and predictive maintenance subscriptions now capture forty-five to sixty percent of lifetime customer value across premium-tier installations. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61850-integrated smart assemblies from basic vacuum-interrupter units and refurbished legacy switchgear. Cost compression in the standard tier is intensifying because Chinese manufacturers are scaling 11 kV production for Indian industrial corridor procurement. Data center operators in Northern Virginia and Frankfurt demonstrate lowest price sensitivity, while commercial building retrofit contractors in Southeast Asia negotiate aggressively on first-cost positioning.
Supply Chain Analysis
Concentrated vacuum bottle manufacturing in Japan and Germany creates single-source vulnerability for medium voltage interruption components. Transformer core production draws from electrical steel mills in Austria, China, and the United States, with grain-oriented silicon steel subject to tariff exposure from Section 232 trade measures. Copper busbar fabrication rests on London Metal Exchange price volatility that constitutes thirty-five to forty-five percent of PDU bill-of-materials. Distribution runs through electrical contractor channels for standardized panel boards and direct manufacturer relationships for engineered-to-order hyperscale data center configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: IEC 61439-2 arc-fault certification and multi-standard testing regimes create fourteen-to-eighteen-month barriers that protect incumbent positions from rapid competitive displacement.
For Market Incumbents: Fortify captive supply positions in vacuum interrupter and semiconductor fabrication to offset Japanese and German supplier concentration. Deepen digital twin integration with IEC 61850-compliant monitoring platforms to generate recurring revenue streams beyond hardware sales. The threat of solid-state silicon carbide breakers from power semiconductor entrants demands accelerated R&D investment in sub-millisecond fault isolation capabilities. For New Entrants and Emerging Players: Lead with marine-grade sealing specifications for 66 kV offshore wind collection platforms, a capability gap among established European suppliers. Target Gujarat and Tamil Nadu industrial corridors under India's PLI scheme where CEA grid code compliance creates procurement windows for smart grid-integrated assemblies. A direct-to-utility sales model bypassing electrical contractor channels captures specification authority from facility energy managers. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because medium voltage commissioning engineer scarcity and multi-standard certification burdens favor scaled players with training infrastructure and testing laboratory ownership. Acquisition targets should display backward integration into transformer core winding or captive vacuum interrupter supply. Watch solid-state breaker pilot results from Singapore hyperscale facilities as the inflection signal for technology substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Interrupter Production | Captive supply from Japanese and German bottle manufacturers reduces single-source vulnerability for medium voltage assemblies. |
| IEC 61850 Digital Twin Platform Development | Predictive maintenance convergence creates recurring revenue streams beyond hardware sales for data center operators. |
| Marine-Grade Sealing Certification for Offshore Wind | 66 kV collection platform specifications open procurement channels where incumbent suppliers lack proven deployment records. |
| SF6-Free Insulation Technology Transition | EU F-Gas Regulation compliance maintains tender eligibility as French and German TSOs exclude gas-dependent suppliers. |
| India PLI Scheme Manufacturing Localization | Gujarat and Tamil Nadu industrial corridor electrification creates volume scale under CEA grid code procurement mandates. |
Research Methodology
Initial hypotheses were tested against primary input from data center energy managers, electrical contractor procurement leads, utility interconnection planners, and medium voltage commissioning engineers and refined through secondary validation against IEC certification databases, FERC interconnection filings, EIA power infrastructure reports, and EU F-Gas Regulation implementation tracking. Bottom-up unit economics from transformer core material costs and top-down market sizing from national grid investment programs were triangulated to establish volume and value estimates.
Variance decomposition across product type, technology tier, end-user vertical, installation configuration, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level demand elasticity modeling and input cost trajectory assumptions. Forecast inputs incorporated hyperscale facility construction pipelines from Northern Virginia and Frankfurt, Indian PLI scheme capacity announcements, and offshore wind interconnection timelines from Pacific Northwest and North Sea development clusters.
Forecasts assume regulatory continuity in EU F-Gas phase-out schedules, EPA SF6 emissions frameworks, and Indian CEA grid code implementations; material policy shifts would require re-modeling of technology substitution curves and supplier compliance positioning. Practitioners should keep alternative scenarios live as solid-state breaker pilot performance and copper price volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Distribution
Global Electric Power Distribution Automation Systems Market
Power Distribution
Global Power Distribution Component Market
Power Distribution
Distribution Panel Market
Power Distribution
Distribution Board Market
Power Distribution
Europe DC Distribution Network Market
Power Distribution
Power Distribution Unit (PDU) Market
Power Distribution
AI in Energy Distribution Market
Power Distribution
Brazil City Gas Distribution Market
Power Distribution
Lighting and Distribution Panel Board Market
Power Distribution
North America and Europe Power Distribution Component Market
Power Distribution
Power Distribution Cables Market