
 AI in Energy Distribution Market | 2026-2036
AI in Energy Distribution Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Energy Distribution Market Insights
Asset-light SaaS delivery models is rewriting competitive dynamics for grid software vendors, lowering barriers for mid-tier utilities to access enterprise-grade analytics. Siemens leverages its digital twin portfolio to anchor long-term service contracts across European transmission networks. Schneider Electric competes through edge-native architectures that reduce latency for real-time voltage control applications.
AI in energy distribution encompasses machine learning algorithms, sensor fusion systems, and predictive analytics platforms that process sub-second telemetry from transformers, feeders, and distributed energy resources to optimize power flows and prevent network failures. Cloud-based deployment now captures the fastest expansion as hyperscale infrastructure slashes model training costs for load forecasting workloads. Grid optimization solutions command the deepest margin pools due to their direct linkage to capital deferral value for transmission operators. Edge computing segments sustain premium pricing where millisecond response requirements exclude centralized processing architectures.
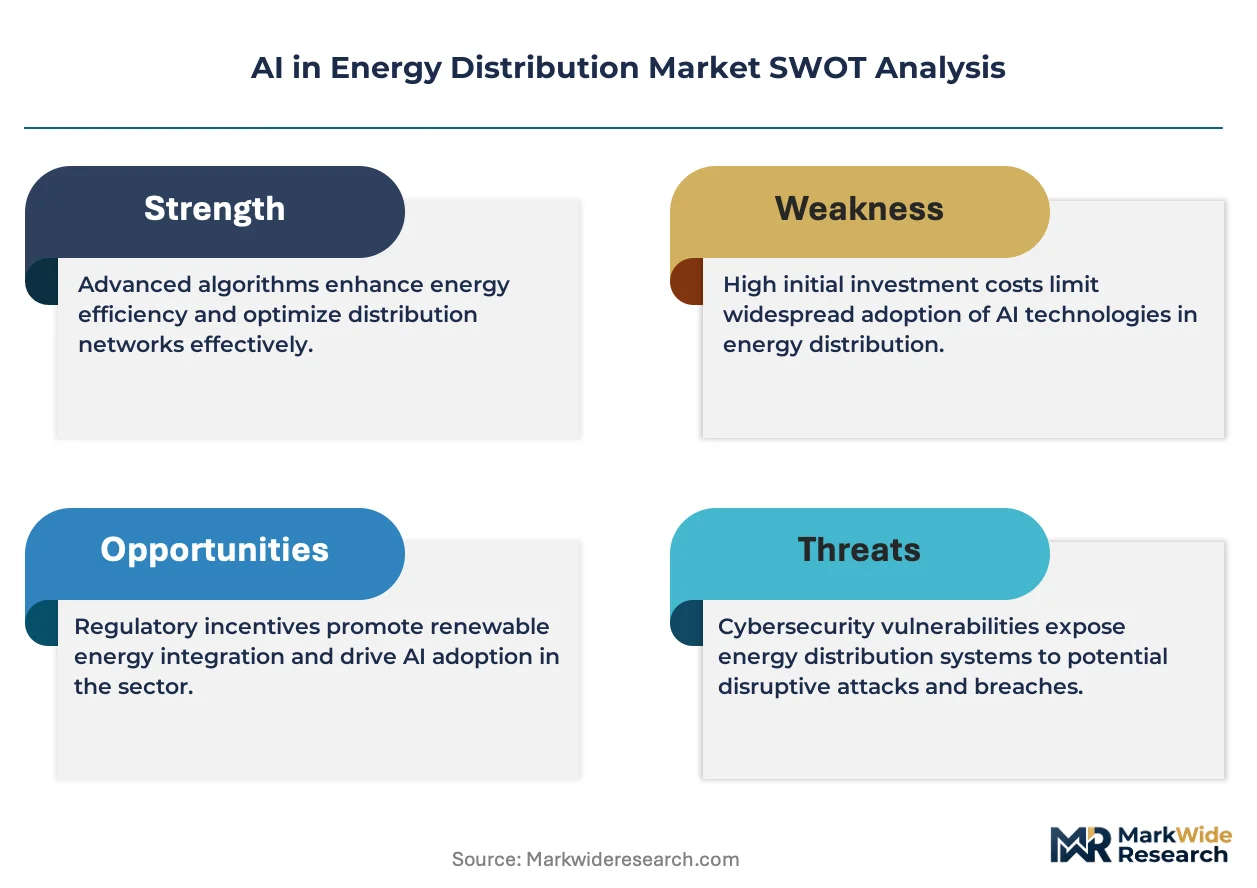
FERC Order 2222 in the United States, the EU Green Deal framework, and GB standards from China's MIIT collectively shape market access by mandating interoperability protocols and cybersecurity baselines for grid-connected AI systems. EMA and national regulators in Europe enforce data residency requirements that favor on-premises or regional cloud deployments for critical infrastructure operators. Stakeholders must monitor evolving cybersecurity certification schemes as these become gatekeeping mechanisms for vendor qualification in procurement processes.
Market Dynamics
The convergence of EU Green Deal mandates with FERC Order 2222 in the United States is forcing transmission operators to replace rule-based grid management with autonomous AI systems that optimize power flows in real time.
Growth Catalysts
- FERC Order 2222:The United States regulation enables distributed energy resource aggregation, compelling utilities to deploy AI platforms that coordinate rooftop solar, battery storage, and electric vehicle bidirectional charging across distribution networks.
- Transformer telemetry density:Sub-second sensor deployment on medium-voltage feeders generates training datasets for machine learning models that predict thermal overloads and automate switching operations.
- German transmission modernization:Four German transmission system operators are accelerating procurement of AI-driven grid optimization platforms to manage renewable intermittency from North Sea offshore wind clusters.
Market Restraints
- GPU supply concentration:Training workloads for load forecasting models depend on NVIDIA data center accelerators, creating input cost volatility and procurement lead times extending beyond eighteen months.
- Data residency requirements:EMA and national regulators in Europe mandate on-premises or regional cloud deployments, inflating infrastructure costs for critical infrastructure operators relative to hyperscale alternatives.
- Cybersecurity certification friction:Evolving IEC 62443 and NERC CIP schemes act as gatekeeping mechanisms that delay vendor qualification in procurement processes by twelve to twenty-four months.
Strategic Opportunities
- India distribution utilities:State electricity boards under CEA mandates represent underpenetrated demand for cloud-based load forecasting as renewable penetration accelerates in Maharashtra, Gujarat, and Tamil Nadu.
- Digital twin convergence:Integration of physics-based simulation with machine learning enables predictive maintenance contracts that monetize asset health scores for transformer fleets.
- Edge-native architectures:Millisecond voltage control applications favor localized inference, creating white space for hardware-software bundles that reduce latency below centralized cloud thresholds.
Industry Challenges
- Power systems-AI hybrid skill scarcity:Grid operators struggle to hire engineers who combine electrical engineering fundamentals with machine learning operations expertise.
- Legacy SCADA integration complexity:Proprietary protocols from 1990s-era control systems require expensive protocol gateways to feed telemetry into modern AI platforms.
- Model validation timelines:Regulatory approval of black-box neural networks for safety-critical switching decisions lacks standardized testing frameworks, extending deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Energy Distribution Market |
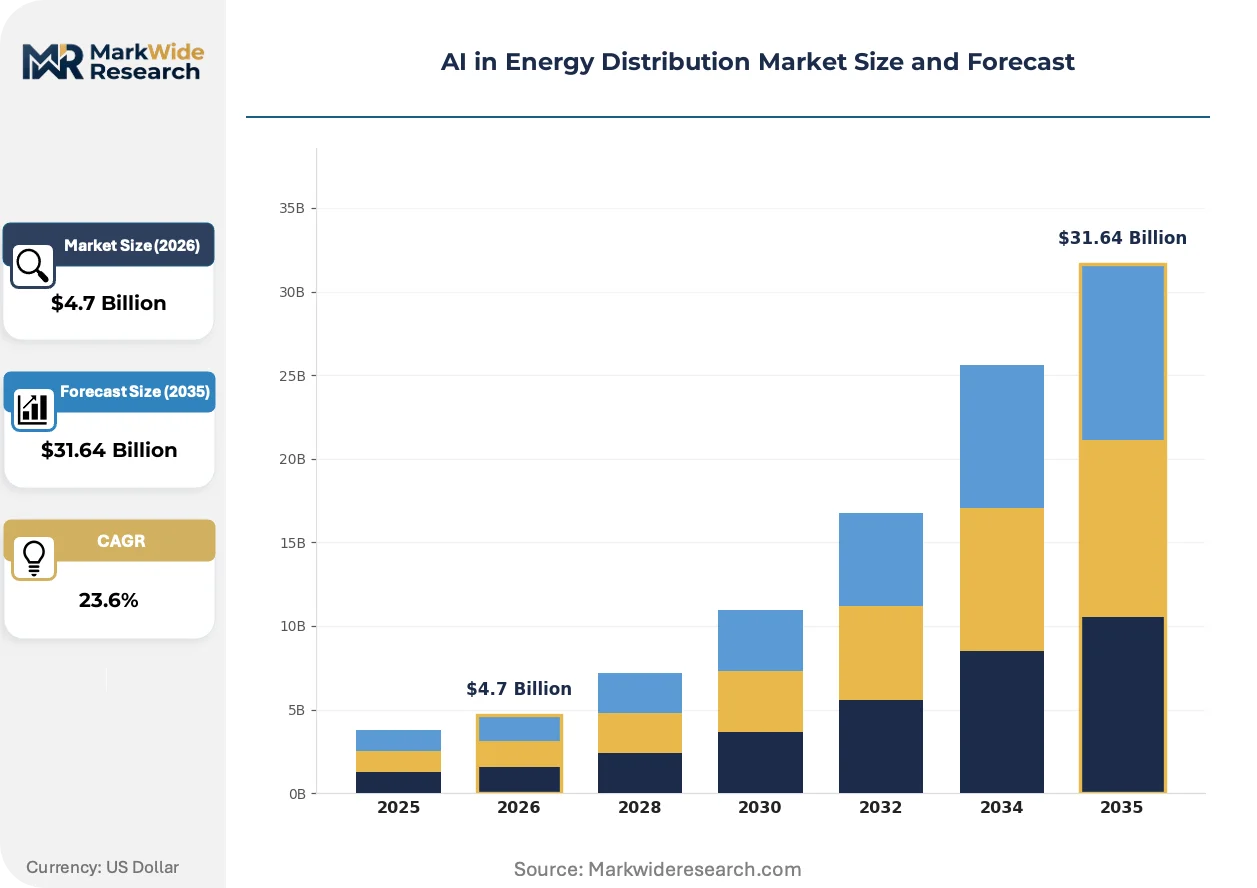
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $31.64 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Edge Computing, Hybrid Systems Solution Type: Load Forecasting, Fault Detection, Grid Optimization, Demand Response, Asset Management Application: Smart Metering, Renewable Integration, Outage Management, Voltage Control End User: Transmission Operators, Distribution Companies, Independent System Operators, Microgrid Managers |
| Companies Covered | Siemens, ABB, Schneider Electric, General Electric, Honeywell International, Atos, Alpiq, AppOrchid, Hazama Ando Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Energy Distribution Market Trends and Innovations
Autonomous grid control systems are displacing human-in-the-loop dispatch models as renewable penetration destabilizes legacy frequency regulation methods. This shift demands continuous algorithmic innovation across sensing, inference, and actuation layers.
Digital twin technology is migrating from design-phase simulation to operational decision support. Transmission operators in Germany and the Netherlands deploy physics-informed neural networks that fuse real-time transformer thermal data with historical failure patterns. The technology is compressing maintenance scheduling from calendar-based to condition-based intervals, deferring capital replacement for aging substation assets.
The EU AI Act's risk classification framework imposes conformity assessment requirements on high-risk AI systems managing critical infrastructure. Grid operators must document training data provenance and model performance metrics for national regulators. European transmission system operators are responding by establishing internal AI governance boards and procuring only from vendors with pre-certified algorithmic transparency toolkits.
Buyers are unbundling software licenses from long-term service agreements that previously bundled analytics with hardware supply. Mid-tier utilities in the United States now procure SaaS-based load forecasting through competitive RFPs rather than sole-source OEM contracts. This pattern concentrates in municipal and cooperative utilities seeking to avoid vendor lock-in from vertically integrated equipment suppliers.
AI in Energy Distribution Market Segmentation
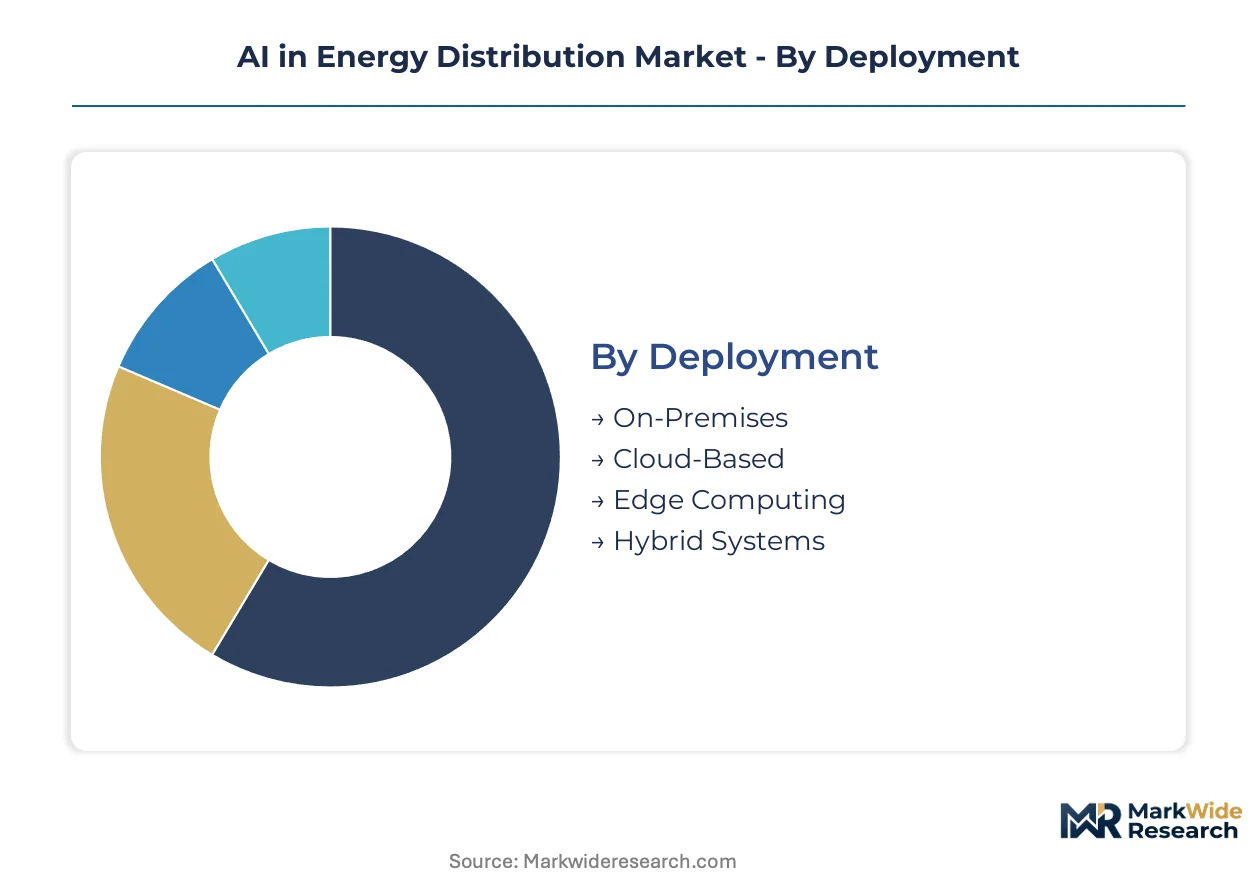
Segmentation in AI energy distribution reveals how deployment architectures, solution types, and user profiles fragment procurement patterns across transmission and distribution networks. Understanding these divides exposes where capital concentrates and where SaaS models disrupt legacy vendor relationships.
Deployment:
Cost tier determines infrastructure ownership and operational overhead for grid operators managing critical infrastructure.
- Cloud-Based:Hyperscale infrastructure slashes model training costs for load forecasting workloads. United States municipal utilities under FERC Order 2222 procurement mandates favor this tier to avoid capital-intensive on-premises builds.
- Edge Computing:Millisecond inference latency for real-time voltage control applications demands localized processing. German transmission operators deploy these architectures across North Sea offshore wind clusters where centralized cloud response times fail safety thresholds.
- On-Premises:EMA data residency requirements and NERC CIP cybersecurity baselines compel European critical infrastructure operators to maintain sovereign control over training data and model weights.
- Hybrid Systems:Orchestration layers split inference workloads between edge nodes and regional cloud instances, accommodating variable latency requirements across distribution feeder classes.
Cloud-based deployment holds installed capacity. Edge computing is rotating up the share rankings.
Solution Type:
Application maturity separates proven revenue streams from emerging capability investments.
- Grid Optimization:Autonomous power flow algorithms defer transmission capital expansion by maximizing existing conductor thermal ratings. Siemens anchors long-term service contracts across European transmission networks through digital twin integration.
- Load Forecasting:Machine learning models process sub-second telemetry from transformers and distributed energy resources to predict demand curves. United States utilities under FERC Order 2222 deploy these platforms to coordinate rooftop solar and battery storage aggregation.
- Fault Detection:Sensor fusion systems identify incipient transformer failures through dissolved gas analysis and thermal pattern recognition.
- Demand Response:AI platforms orchestrate bidirectional electric vehicle charging and industrial load curtailment against wholesale price signals.
- Asset Management:Predictive maintenance contracts monetize transformer health scores, compressing maintenance intervals from calendar-based to condition-based schedules.
Grid optimization commands margin concentration. Load forecasting is climbing the fastest as renewable penetration destabilizes dispatch planning.
Application:
Functional use case determines sensor density requirements and algorithmic complexity for deployment teams.
- Voltage Control:Real-time reactive power management prevents thermal overloads on medium-voltage feeders with high distributed solar penetration. Edge-native inference architectures from Schneider Electric reduce latency below centralized cloud thresholds for these safety-critical loops.
- Renewable Integration:AI systems forecast intermittency from offshore wind and rooftop solar, automating switching operations to balance supply-demand mismatches. German transmission operators accelerate procurement here to manage North Sea cluster variability.
- Smart Metering:AMI data streams train consumption pattern models for theft detection and demand forecasting.
- Outage Management:Predictive algorithms locate fault segments before customer calls trigger truck rolls.
Voltage control dominates capital allocation. Renewable integration is gaining share fastest as decarbonization timelines compress.
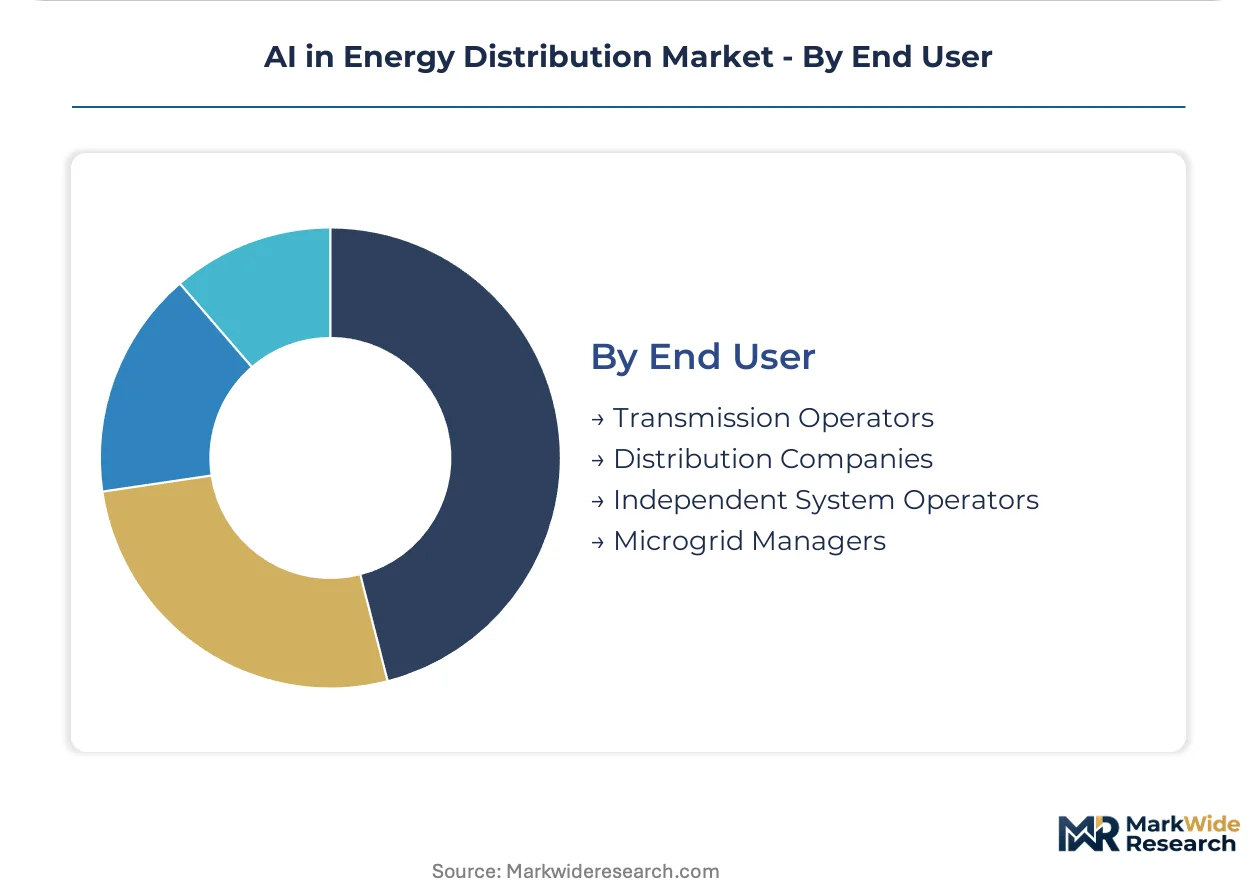
End User:
Customer type shapes contract structure, procurement authority, and vendor relationship duration.
- Transmission Operators:National and regional grid owners procure enterprise-grade optimization platforms with decade-long service agreements. Four German TSOs under EU Green Deal mandates represent concentrated demand for AI-driven grid management.
- Distribution Companies:Municipal and cooperative utilities in the United States unbundle software licenses from hardware supply, procuring SaaS load forecasting through competitive RFPs rather than sole-source OEM contracts.
- Independent System Operators:Wholesale market operators deploy AI for real-time dispatch and frequency regulation across balancing authority footprints.
- Microgrid Managers:Campus and industrial facility operators optimize behind-the-meter generation, storage, and load through localized control systems.
Transmission operators anchor contract value. Distribution companies are rotating up the share rankings as SaaS procurement models democratize access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transmission operators concentrate procurement authority in Germany and the United States, while distribution utilities in India and Brazil represent emerging demand for cloud-based platforms. Regulatory mandates in each geography determine deployment architecture preferences and vendor qualification timelines.
United States
FERC Order 2222 compels utilities to aggregate distributed energy resources through AI coordination platforms. The regulation enables rooftop solar and battery storage participation in wholesale markets, forcing procurement of real-time optimization software. Municipal utilities in California and Texas favor SaaS load forecasting to avoid capital-intensive infrastructure builds.
Germany
Four transmission system operators accelerate AI-driven grid management to handle North Sea offshore wind intermittency. EU Green Deal decarbonization mandates require modernization of legacy infrastructure by 2030. The country enforces EMA data residency requirements that favor on-premises or regional cloud deployments for critical infrastructure operators.
China
MIIT GB standards mandate interoperability protocols and cybersecurity baselines for grid-connected AI systems. State Grid Corporation deploys machine learning platforms across Yangtze River Delta load centers to manage industrial demand volatility. Provincial utilities in Guangdong and Jiangsu integrate edge-native architectures for millisecond voltage control.
India
CEA mandates drive state electricity boards toward cloud-based load forecasting as renewable penetration accelerates. Maharashtra, Gujarat, and Tamil Nadu distribution utilities represent underpenetrated demand for predictive analytics platforms. The national grid operator procures sensor fusion systems to automate switching operations across high-solar penetration feeders.
United Kingdom
Ofgem regulatory frameworks push distribution network operators toward autonomous grid control systems. National Grid ESO deploys physics-informed neural networks for real-time frequency regulation as renewable penetration destabilizes legacy methods. Scottish and Welsh transmission networks prioritize digital twin integration for condition-based maintenance of aging transformer fleets.
AI in Energy Distribution Market Competitive Landscape
Channel-controlling players compete with product-specialist players across deployment architecture tiers. The market structures around three layers: industrial conglomerates with embedded software portfolios, pure-play analytics vendors, and hardware-integrated solution providers. Siemens leverages digital twin capabilities to anchor long-term service contracts. Schneider Electric competes through edge-native architectures. General Electric and ABB pursue vertical integration strategies that bundle hardware supply with predictive maintenance subscriptions.
Among European-based industrial conglomerates, Siemens and ABB exemplify the integrated-platform archetype, combining equipment manufacturing with software analytics. Schneider Electric occupies a position bridging edge hardware and cloud-native orchestration. General Electric represents the North American challenger, competing through turbine-to-grid digital thread capabilities. Honeywell International and Atos sit within the IT-services tier, procuring algorithmic components from specialist vendors rather than developing core machine learning IP in-house. Alpiq, AppOrchid, and Hazama Ando Corporation represent regional specialists concentrated in Swiss, Indian, and Japanese markets respectively, each anchoring niche procurement relationships with national utilities.
| Leading Market Players |
|---|
| Siemens |
| ABB |
| Schneider Electric |
| General Electric |
| Honeywell International |
| Atos |
| Alpiq |
| AppOrchid |
| Hazama Ando Corporation |
| Others |
Pricing and Supply Chain Analysis
GPU supply concentration creates procurement bottlenecks that compress SaaS margins for load forecasting vendors while inflating hardware-integrated solution premiums. This input dependency stratifies pricing tiers between asset-light software subscriptions and edge-native bundled offerings, reshaping vendor procurement strategies across transmission and distribution utilities.
Pricing Analysis
Cost-plus contracts indexed to NVIDIA data center accelerator pricing dominate enterprise procurement for training-intensive workloads. Three-tier pricing structure across premium, standard, and economy levels separates hyperscale cloud deployments from regional cloud instances and sovereign on-premises builds. Pricing pressure stems from eighteen-month GPU procurement lead times extending vendor qualification cycles. Municipal utilities in the United States exhibit highest price sensitivity, while German transmission system operators accept premium tiers for EMA-compliant regional deployments.
Supply Chain Analysis
Contract manufacturing for edge inference hardware concentrates with Foxconn, Jabil, and Flex holding capacity for industrial-grade enclosures and ruggedized compute modules. Taiwan and South Korea anchor semiconductor wafer supply for AI accelerators, while China dominates sensor component fabrication for transformer telemetry systems. Raw material dependencies span gallium nitride substrates, high-purity copper for thermal management, and rare earth elements for magnetic components. Single-source vulnerability around NVIDIA H100/H200 allocations creates procurement risk for training workload vendors. Distribution runs through direct OEM channels for transmission operators and value-added resellers for mid-tier distribution utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AI in Energy Distribution Market is recovering from cyclical infrastructure investment lows as EU Green Deal enforcement deadlines and FERC Order 2222 implementation timelines synchronize procurement waves.
For Market Incumbents: Build switching cost moats through digital twin integration that fuses physics-based simulation with operational telemetry, locking transmission operators into decade-long service agreements. Siemens anchors European contracts through this architecture. Defend against pure-play SaaS entrants by certifying algorithms under IEC 62443 and NERC CIP schemes ahead of procurement cycles, creating twelve-to-twenty-four-month qualification barriers. Prioritize backward integration into edge hardware manufacturing to capture margin pools currently leaking to contract manufacturers. For New Entrants and Emerging Players: Indian state electricity boards under CEA mandates represent the most penetrable demand cluster for cloud-native load forecasting platforms, with Maharashtra and Gujarat distribution utilities accelerating renewable integration without legacy SCADA lock-in. Target SaaS procurement patterns among United States municipal and cooperative utilities seeking to unbundle software licenses from vertically integrated OEM contracts. Lead with API-first architectures that bypass proprietary protocol gateway costs, reducing total cost of ownership against incumbent integrated stacks. For Investors and Strategic Acquirers: EU AI Act risk classification implementation reshapes the acquisition landscape by devaluing black-box neural network vendors lacking algorithmic transparency toolkits while premiuming explainable AI platforms with pre-certified governance frameworks. Long-term viability centers on vendors serving critical infrastructure operators with recurring revenue models across ten-year service horizons. Target acquisition profile emphasizes edge-native architecture specialists with millisecond-latency voltage control deployments. Monitor cybersecurity certification backlog clearance rates at national regulators as the primary inflection signal for vendor qualification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native Architecture Development | Schneider Electric reduces latency below centralized cloud thresholds for German North Sea wind clusters. |
| Digital Twin Platform Integration | Siemens anchors long-term service contracts across European transmission networks through physics-informed neural networks. |
| Cybersecurity Certification Pre-Investment | Early IEC 62443 compliance creates twelve-month procurement advantage against uncertified competitors. |
| API-First SaaS Deployment | Mid-tier United States utilities bypass legacy SCADA protocol gateway costs through competitive RFP procurement. |
| Regional Cloud Sovereignty Partnership | EMA data residency requirements favor on-premises or regional cloud deployments for critical infrastructure operators. |
Research Methodology
Operator-level perspectives from transmission planning officers, distribution utility procurement managers, grid optimization software engineers, and EPC contractors anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from FERC filings, EIA load data, IEA grid integration reports, and EU Green Deal implementation tracking. Bottom-up triangulation across deployment architecture tiers, solution types, and end-user segments converged with top-down market sizing from regulatory mandate timelines and capital expenditure disclosures.
Scenario-bracketing framed analytical approaches across the projection horizon, modeling sensitivity to GPU supply availability, cybersecurity certification velocity, and renewable penetration acceleration. Segmentation dimensions spanned deployment architecture, solution type, application function, and end-user category. CAGRs derived from installed base growth rates, replacement cycle compression, and new build procurement patterns. Forecast inputs incorporated transformer telemetry density trajectories, FERC Order 2222 implementation pacing, and EU AI Act conformity assessment timelines.
Practitioners should monitor NVIDIA data center accelerator allocation announcements, national regulator cybersecurity certification backlog clearance rates, and CEA mandate enforcement pacing in Maharashtra and Gujarat for early signals of forecast revision. Quarterly review of transmission operator RFP issuance volumes, SaaS vendor churn rates among municipal utilities, and edge hardware lead time extensions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Distribution
Global Electric Power Distribution Automation Systems Market
Power Distribution
Distribution Panel Market
Power Distribution
Brazil City Gas Distribution Market
Power Distribution
North America and Europe Power Distribution Component Market
Power Distribution
Power Distribution Cables Market
Power Distribution
Europe DC Distribution Network Market
Power Distribution
Lighting and Distribution Panel Board Market
Power Distribution
Power Distribution Unit (PDU) Market
Power Distribution
Medium Voltage AC Power Distribution Units (PDU) Market
Power Distribution
Global Power Distribution Component Market
Power Distribution
Distribution Board Market