
 Lighting and Distribution Panel Board Market | 2026-2036
Lighting and Distribution Panel Board Market Size, Share, and Industry Trends Forecast 2026-2036
Lighting and Distribution Panel Board Market Analysis
UL 891 qualification for switchboard assemblies is unwinding the competitive set as smaller fabricators struggle with retesting costs and documentation burdens. ABB leverages captive copper busbar production to stabilize lead times across European project pipelines. Schneider Electric anchors its position through deep channel partnerships with electrical wholesalers in France and the United Kingdom. Siemens competes on digital twin integration, embedding power-monitoring software directly into its SIVACON panel board platforms.
Lighting and distribution panel boards are enclosed assemblies of overcurrent protective devices, busbars, and metering instruments rated for voltages from 120V to 600V, designed to distribute electrical power while enabling circuit isolation and fault protection in commercial and industrial environments. Structural dynamics favor smart panels within the technology dimension, where real-time energy analytics command pricing premiums over analog alternatives. Circuit breakers dominate the product type mix by installed value, though fuse panels retain share in heavy industrial settings where short-circuit current ratings exceed standard molded-case limits. Commercial buildings represent the most contested end user segment, with infrastructure projects offering longer contract visibility but thinner margins.
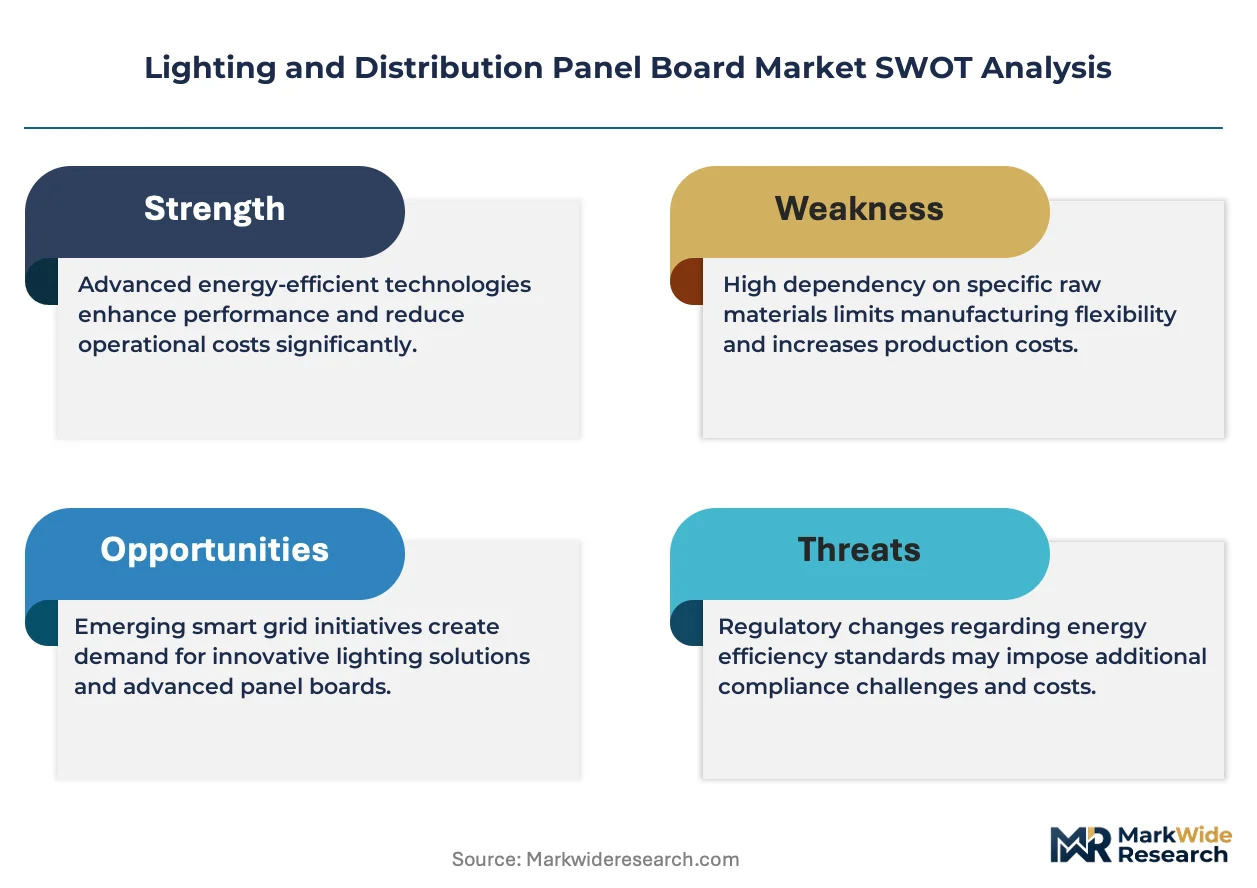
NFPA 70 (NEC) in the United States, IEC 61439 across European markets, and BIS IS 8623 in India collectively dictate enclosure ratings, busbar sizing, and short-circuit withstand thresholds that determine product eligibility. These frameworks raise compliance costs but also consolidate procurement toward certified manufacturers with in-house testing laboratories. Stakeholders must track evolving arc-energy reduction requirements and digital interoperability standards as the primary axes of product differentiation and market access.
Market Dynamics
Electrification mandates across industrial and commercial verticals are forcing wholesale replacement cycles in legacy electrical infrastructure, compressing procurement timelines while expanding specification complexity for panel board assemblies.
Growth Catalysts
- Data center power density escalation:Hyperscale facilities in the United States are specifying 400A+ busbar configurations to support GPU clusters, pulling premium panel board volumes through specialized electrical contractors.
- IEC 61439-2 harmonization:European standardization of assembly verification protocols is reducing cross-border qualification friction for certified manufacturers, accelerating project timelines in Germany and France.
- Copper busbar captive supply:Integrated foundry operations among tier-one fabricators are insulating delivery schedules from commodity volatility, stabilizing lead times for infrastructure contractors.
Market Restraints
- NEMA arc-fault compliance costs:UL 1699B retesting requirements for branch circuit protection are stretching qualification budgets for mid-tier fabricators without captive laboratories.
- Specialized enclosure steel concentration:Galvanized cold-rolled steel supply clusters in East Asian mill networks are exposing European project pipelines to freight cost volatility and tariff exposure.
- Fuse panel substitution ceiling:Molded-case circuit breakers face current-limiting constraints above 200kA interrupting ratings, preserving fuse technology in heavy industrial smelting and chemical processing installations.
Strategic Opportunities
- Grid modernization procurement waves:Germany's Stromnetze 2030 investment framework is mandating smart metering integration at distribution points, creating specification windows for digitally-enabled panel boards.
- Energy-as-a-service channel emergence:Third-party facility optimization vendors in the United Kingdom are bundling panel board monitoring into long-term efficiency contracts, bypassing traditional wholesaler relationships.
- Digital twin convergence:Integration of power monitoring software with building management systems is enabling predictive maintenance offerings that command recurring revenue streams from commercial real estate operators.
Industry Challenges
- Arc-energy reduction engineering shortage:Qualified protection engineers capable of coordinating selective trip schemes under NFPA 70E constraints are concentrated among aging specialist consultancies, constraining project execution capacity.
- Legacy 480V system integration friction:Retrofit installations in aging US commercial stock require custom busbar configurations to interface with existing switchgear footprints, extending engineering cycles and warranty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lighting and Distribution Panel Board Market |
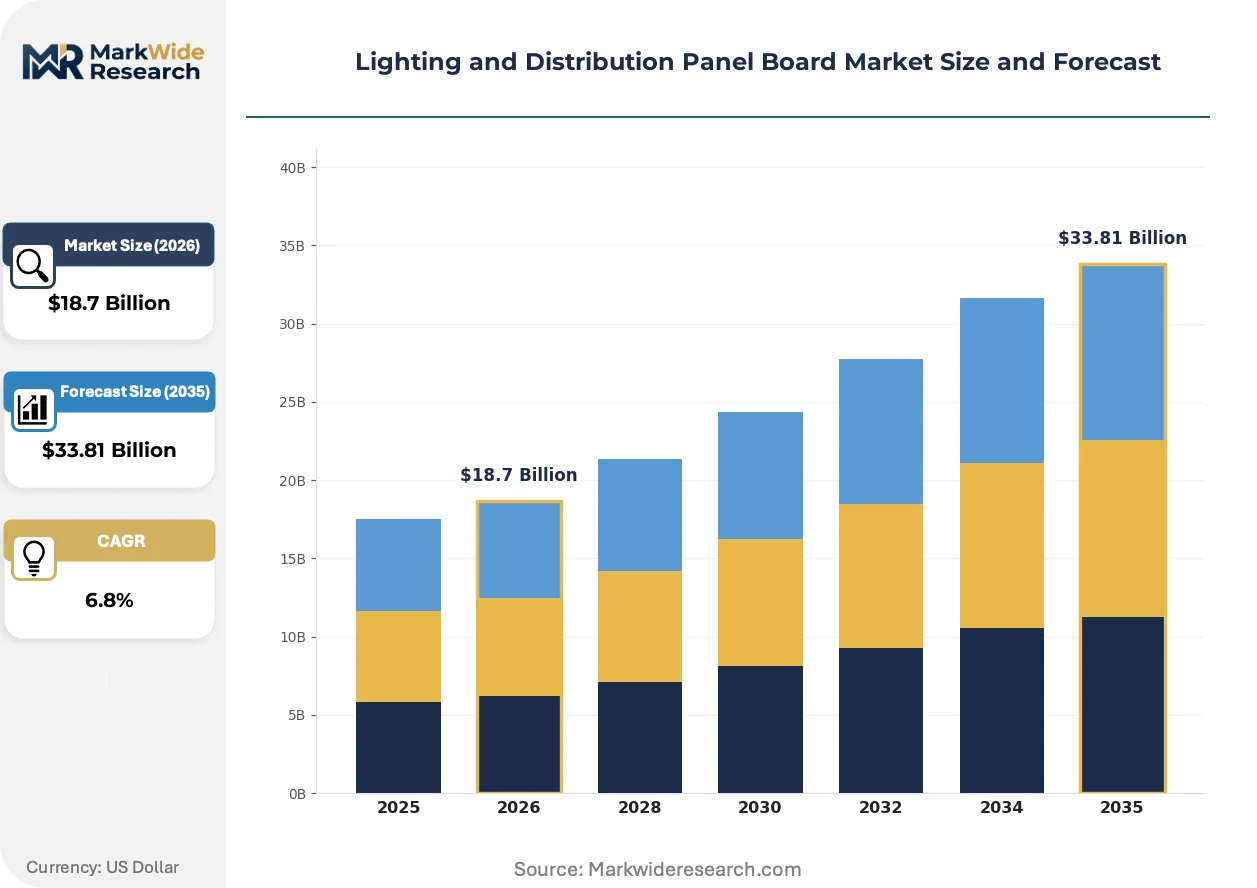
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switchgear, Circuit Breakers, Fuse Panels, Relay Panels Technology: Smart Panels, Digital Panels, Analog Panels, Traditional Panels End User: Commercial Buildings, Industrial Facilities, Residential Homes, Infrastructure Projects Installation: Indoor, Outdoor, Surface Mounted, Flush Mounted |
| Companies Covered | ABB, Legrand, Schneider Electric, Hubbell, Hager Group, Eaton, General Electric, Emerson Electric, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lighting and Distribution Panel Board Market Emerging Trajectories
Smart panel technology is compressing the traditional separation between power distribution hardware and energy management software, forcing specification changes across procurement channels.
Intelligent busbar monitoring systems with embedded temperature and current sensors are bifurcating the product landscape. Data center operators in Northern Virginia and Phoenix are specifying these assemblies as standard for new builds. The technology is bifurcating procurement patterns between analytics-enabled premium tiers and commodity analog alternatives.
REACH restrictions on hexavalent chromium in galvanized coatings are forcing European fabricators to transition to trivalent passivation chemistries. Surface treatment suppliers are qualifying alternative formulations under accelerated corrosion protocols. German industrial buyers are absorbing modest cost premiums to maintain CE marking compliance without supply interruption.
Consolidated procurement through national electrical wholesalers is fragmenting as large facility operators establish direct specification relationships with panel board manufacturers. Engineering-procurement-construction firms in the United States are bypassing traditional distribution layers for complex custom assemblies. This channel compression is most visible in healthcare and data center verticals where technical pre-qualification requirements exceed distributor capabilities.
Lighting and Distribution Panel Board Market Segmentation
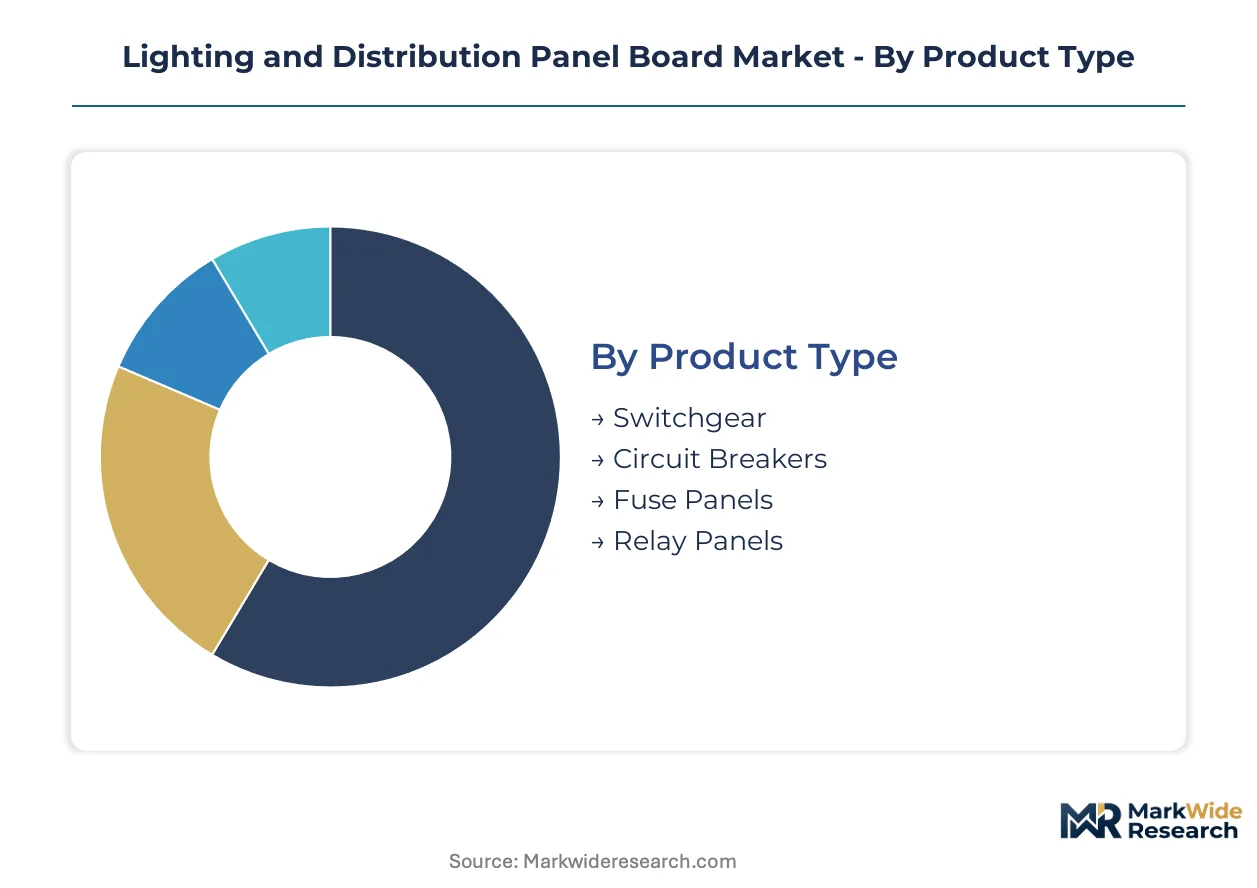
Panel board procurement channels fragment sharply across segment boundaries. Electrical wholesalers dominate standard product categories, while direct manufacturer relationships govern complex custom assemblies in data center and healthcare verticals.
Product Type:
Circuit breakers and switchgear flow through national distribution networks, while fuse panels and relay assemblies often bypass wholesalers for engineered-to-order channels.
- Circuit Breakers:Molded-case and air-break configurations handle overcurrent protection for 120V to 600V distribution networks. Data center operators in Northern Virginia specify 400A+ frame sizes to support GPU cluster power density, pulling premium volumes through specialized electrical contractors.
- Switchgear:Metal-enclosed assemblies integrate busbars, protective devices, and control apparatus for primary power distribution. Grid modernization mandates in Germany are accelerating procurement of IEC 61439-2 certified switchgear for utility-scale substation upgrades.
- Fuse Panels:Current-limiting fuse technology retains installed base in heavy industrial smelting and chemical processing where short-circuit ratings exceed molded-case interrupting limits.
- Relay Panels:Protection and control relay assemblies coordinate selective trip schemes for complex distribution architectures.
Circuit breakers dominate installed base. Fuse panels are where expansion concentrates in heavy industrial electrification projects.
Technology:
Cost tiers separate procurement channels sharply, with smart panels commanding direct manufacturer relationships and traditional panels flowing through wholesale distribution.
- Smart Panels:Embedded sensors and communication modules enable real-time energy analytics and predictive maintenance protocols. Facility operators in the United Kingdom are bundling smart panel monitoring into long-term energy-as-a-service contracts.
- Digital Panels:Microprocessor-based metering and protection functions bridge analog infrastructure with building management system integration.
- Analog Panels:Electromechanical metering and thermal-magnetic protection remain standard in cost-sensitive commercial retrofits and residential applications.
- Traditional Panels:Basic overcurrent protection without metering or communication capabilities serves legacy infrastructure replacement cycles.
Smart panels command pricing premiums. Traditional panels retain volume concentration in residential and small commercial replacement demand.
End User:
Application complexity determines channel structure, with infrastructure and industrial projects favoring direct specification while commercial and residential segments concentrate through wholesale distribution.
- Commercial Buildings:Office, retail, and hospitality installations require coordinated lighting and power distribution with tenant improvement flexibility. Engineering-procurement-construction firms are bypassing traditional distribution layers for complex custom assemblies.
- Industrial Facilities:Manufacturing, processing, and heavy industrial sites demand high short-circuit withstand ratings and selective coordination. German industrial electrification targets are pulling premium panel board volumes for factory automation upgrades.
- Residential Homes:Single-family and multi-family dwelling units specify standard load centers with branch circuit protection through electrical contractor wholesale purchasing.
- Infrastructure Projects:Transportation, water treatment, and public facility installations require extended warranty terms and specialized corrosion-resistant enclosures.
Commercial buildings represent the most contested segment. Industrial facilities are climbing the fastest as electrification mandates force wholesale replacement cycles.
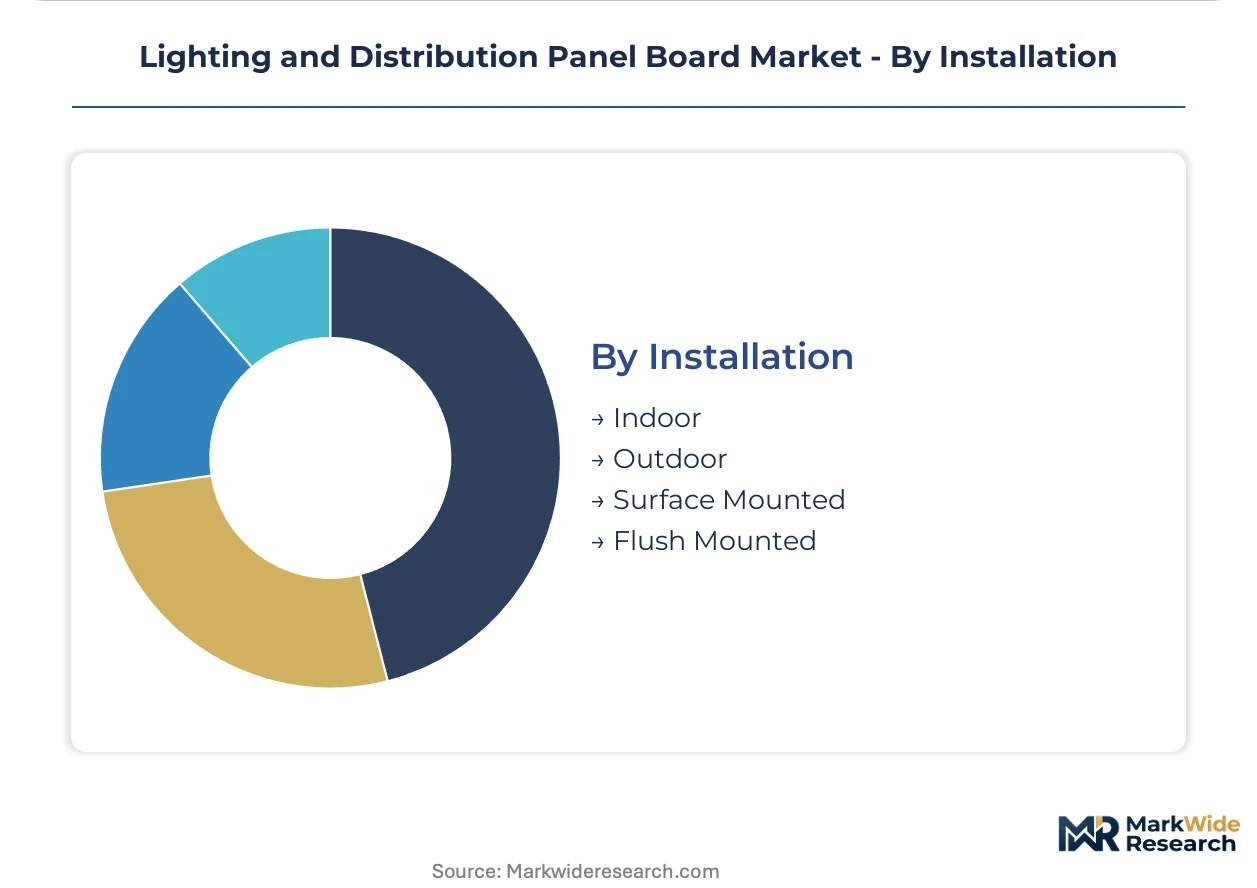
Installation:
Volume concentration varies by mounting configuration and environmental exposure, with indoor surface-mounted units dominating unit shipments and outdoor flush-mounted assemblies commanding project value.
- Indoor:Climate-controlled electrical room installations specify standard NEMA 1 or IEC IP30 enclosure ratings for commercial and industrial building cores.
- Outdoor:Weather-resistant NEMA 3R or IP65 enclosures serve utility distribution points and remote facility applications.
- Surface Mounted:Wall-mounted configurations simplify retrofit installation in existing commercial stock with constrained electrical room footprints.
- Flush Mounted:Recessed installations integrate with architectural finishes in healthcare, hospitality, and premium commercial interiors.
Indoor installations dominate unit volume. Outdoor specifications are gaining share fastest in grid modernization and data center campus expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center operators and industrial electrification buyers concentrate procurement in Germany, the United States, and India, with qualification timelines stretching across multiple quarters due to evolving certification requirements.
United States
Hyperscale data center construction in Northern Virginia and Phoenix drives 400A+ busbar specifications for GPU cluster support. NFPA 70 (NEC) arc-fault compliance requirements under UL 1699B extend qualification periods for branch circuit protection. Electrical contractors in Ashburn and Loudoun County command premium pricing for specialized panel board installations.
Germany
Grid modernization mandates and industrial electrification targets pull premium panel board volumes for factory automation upgrades. The Stromnetze 2030 investment framework mandates smart metering integration at distribution points. Manufacturing clusters in Bavaria and North Rhine-Westphalia specify IEC 61439-2 certified assemblies for utility-scale substation projects.
India
Rapid commercial infrastructure expansion and residential electrification programs accelerate load center replacement cycles. BIS IS 8623 standards dictate enclosure ratings and short-circuit withstand thresholds for product eligibility. Industrial corridors in Maharashtra and Gujarat concentrate procurement for manufacturing facility upgrades.
United Kingdom
Energy-as-a-service channel emergence enables third-party facility optimization vendors to bundle panel board monitoring into long-term efficiency contracts. Building regulations mandate improved energy monitoring in commercial structures. London and Southeast England healthcare facilities establish direct specification relationships for complex custom assemblies.
China
Data center power density escalation and industrial electrification programs expand distribution infrastructure investment. GB standards govern enclosure construction and busbar sizing for domestic market access. Yangtze River Delta manufacturing hubs specify smart panels with embedded sensors for real-time energy analytics.
Lighting and Distribution Panel Board Market Vendor Landscape
Player mix skews toward integrated electrical conglomerates with captive component supply and specialized fabricators focused on custom engineered-to-order assemblies. Tier-one manufacturers leverage backward integration into copper busbar production to stabilize lead times. Two strategic archetypes dominate: scale-driven diversified industrials with global project execution capabilities, and regional specialists with deep certification expertise in single markets. Competitive moves concentrate on channel compression through direct specification relationships and technology licensing for digital twin integration.
Among European-based fabricators, ABB, Schneider Electric, and Siemens occupy positions across the premium technology tier. ABB exemplifies the vertically integrated archetype through captive copper busbar operations. Schneider Electric sits within the channel partnership model with established wholesaler networks. Siemens represents the digital convergence approach with embedded power-monitoring capabilities. Legrand, Eaton, and Hubbell anchor the mid-market segment with broad product portfolios spanning standard and intelligent configurations.
| Leading Market Players |
|---|
| ABB |
| Legrand |
| Schneider Electric |
| Hubbell |
| Hager Group |
| Eaton |
| General Electric |
| Emerson Electric |
| Siemens |
| Others |
Supply Flow & Price Mechanics
Twelve-week lead times for IEC 61439-2 certified assemblies in Germany concentrate pricing power among fabricators with captive copper busbar operations, while buyers without long-term offtake contracts absorb spot-market volatility in galvanized steel enclosures.
Pricing Analysis
Cost-plus contracts indexed to LME copper futures dominate project-based procurement for industrial panel board installations. Three-tier pricing structure across premium smart panels, standard digital configurations, and economy analog tiers separates buyers by certification grade and analytics capability. Pricing pressure stems from NEMA arc-fault compliance retesting costs stretching qualification budgets for mid-tier fabricators. Data center operators in Northern Virginia exhibit lowest price sensitivity due to GPU cluster power density requirements, while residential electrical contractors in India face acute cost compression.
Supply Chain Analysis
Strait of Malacca transit congestion exposes European project pipelines to galvanized cold-rolled steel delivery delays from East Asian mill networks. Manufacturing concentration in China, South Korea, and Germany feeds downstream assembly operations across voltage classes and enclosure ratings. Copper busbar sourcing draws from Chilean mining output and Chinese semis processing, with tariff exposure on finished steel components amplifying cost volatility. Distribution runs through national electrical wholesalers for standard products, while direct manufacturer relationships govern engineered-to-order assemblies in healthcare and data center verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities proliferate as procurement channel compression bypasses traditional wholesalers for complex custom assemblies, creating specification niches for specialized fabricators with deep certification expertise.
For Market Incumbents: Fortify market position through backward integration into copper busbar production and captive testing laboratory investments. ABB's foundry operations demonstrate how upstream control insulates delivery schedules from commodity volatility. Deepen channel partnerships with electrical wholesalers in France and the United Kingdom to resist direct specification encroachment from engineering-procurement-construction firms.
For New Entrants and Emerging Players: Lead with smart panel monitoring capabilities targeting energy-as-a-service vendors in the United Kingdom seeking bundled efficiency contracts. The most penetrable white space sits in predictive maintenance software integration for commercial real estate operators. Pursue go-to-market alignment with third-party facility optimization vendors rather than traditional distribution layers.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because arc-energy reduction engineering capacity concentrates among aging specialist consultancies, constraining project execution and creating acquisition targets with irreplaceable technical credentials. Regional specialists with IEC 61439-2 certification depth in single European markets represent priority target archetypes. Monitor Germany's Stromnetze 2030 procurement waves as inflection signal for smart metering integration demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Busbar Production | Captive foundry operations stabilize lead times against LME volatility for infrastructure contractors. |
| Digital Twin Platform Integration | Siemens embeds power-monitoring software into SIVACON platforms, commanding recurring revenue streams. |
| IEC 61439-2 Certification Investment | Harmonized assembly verification protocols accelerate cross-border project timelines in Germany and France. |
| Direct Specification Relationship Development | Healthcare and data center operators bypass wholesalers for complex custom assemblies with extended warranties. |
| Smart Metering Integration Capability | Germany's Stromnetze 2030 mandates digitized distribution points, opening specification windows. |
Methodological Framework
The analysis maps circuit breaker, switchgear, fuse panel, and relay panel sub-sectors, each validated through electrical contractor interviews, utility procurement officer consultations, and distribution channel partner discussions. Primary fieldwork with EPC firms in the United States, Germany, and India combined with secondary validation against BIS filings, IEC certification registries, and customs trade data. Bottom-up project pipeline tracking and top-down infrastructure investment forecasts triangulate volume estimates.
Consistency checks against external benchmarks validated model outputs across the projection horizon. Segmentation dimensions span product type, technology tier, end-user vertical, and installation configuration, with regional regulatory clusters as an additional modeled layer. CAGRs derive from fitted growth curves applied to disclosed capital expenditure patterns and electrification mandate timelines. Data center power density escalation curves and grid modernization procurement schedules serve as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained copper price stability and tariff regime continuity would require recalibration. Forecasts reflect documented assumptions regarding certification timeline extensions and channel structure evolution. Practitioners should keep alternative scenarios live as NFPA 70E arc-energy reduction requirements and REACH coating chemistry restrictions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Distribution
Medium Voltage AC Power Distribution Units (PDU) Market
Power Distribution
Global Power Distribution Component Market
Power Distribution
AI in Energy Distribution Market
Power Distribution
Distribution Board Market
Power Distribution
Global Electric Power Distribution Automation Systems Market
Power Distribution
Power Distribution Cables Market
Power Distribution
Power Distribution Unit (PDU) Market
Power Distribution
Distribution Panel Market
Power Distribution
North America and Europe Power Distribution Component Market
Power Distribution
Brazil City Gas Distribution Market
Power Distribution
Europe DC Distribution Network Market