
 Distribution Panel Market | 2026-2036
Distribution Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Distribution Panel Market Analysis
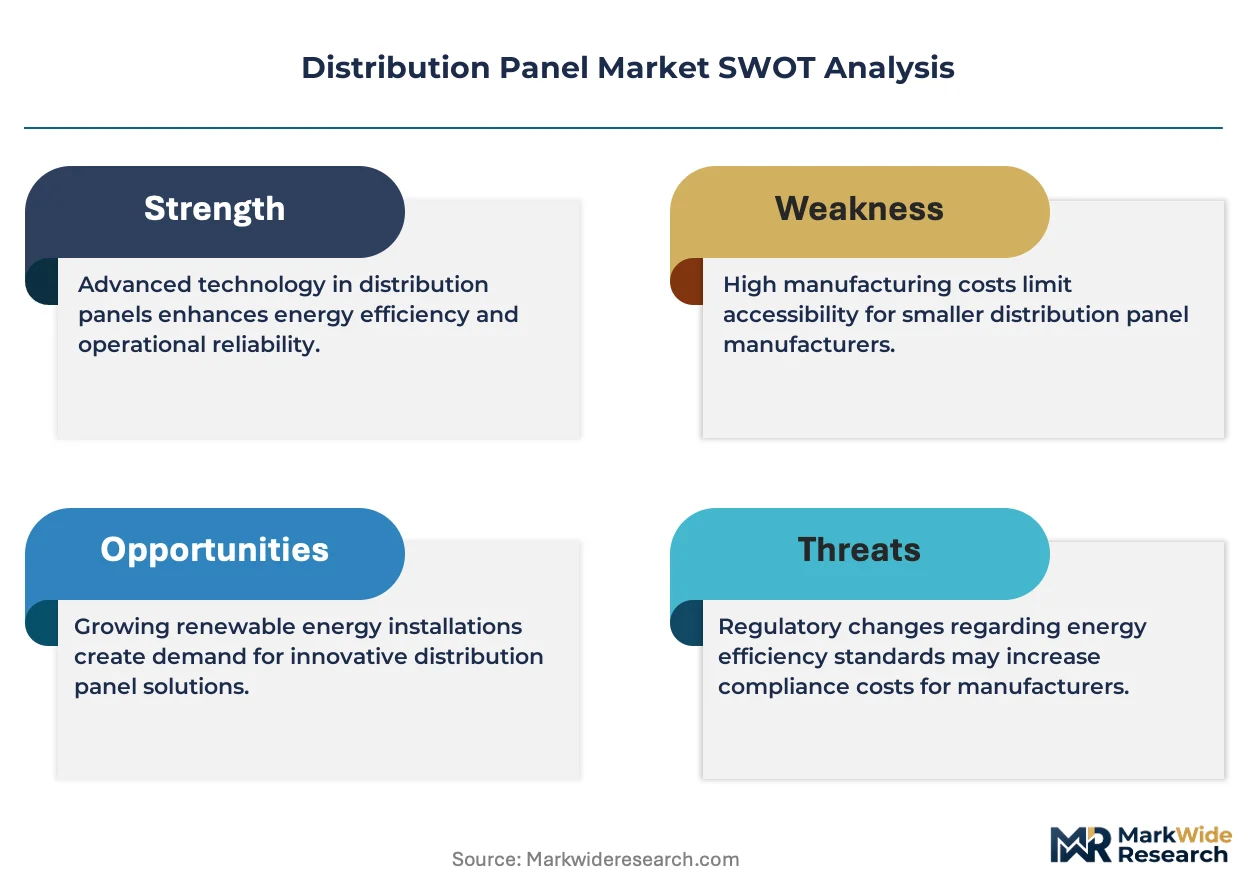
Multi-source procurement for critical electrical components is pivoting toward vertically integrated supply chains as lead times for copper busbars and molded-case circuit breakers remain volatile. Schneider Electric leverages captive manufacturing across multiple continents to buffer regional supply shocks. Siemens anchors its competitive position through intensive R&D in digital twin-enabled panel design. ABB Ltd. dominates the medium-voltage segment through specialized arc-flash mitigation technologies.
A distribution panel is an enclosed assembly of circuit breakers, busbars, metering devices, and protective relays designed to receive electrical power and distribute it through multiple feeder circuits to downstream loads, typically rated from 240 volts to 35 kilovolts depending on application scale. The assembly must maintain IP ratings against dust and moisture ingress while providing selective coordination between protective devices to isolate faults without cascading outages. Low-voltage panels constitute the mature volume base, though data center end users represent the fastest-expanding demand pool as hyperscale facilities push beyond 50-megawatt substation thresholds. Indoor installation types command premium pricing due to space-constrained retrofit conditions in urban commercial buildings, whereas outdoor freestanding configurations serve heavy industrial corridors where environmental hardening justifies higher capital outlay.
IEC 61439 and UL 891 standards govern panel construction and short-circuit withstand ratings, compelling manufacturers to maintain dual certification laboratories for transatlantic market access. The US National Electrical Code and EU CE marking directives further fragment compliance requirements, with local inspectors interpreting grounding and arc-energy containment provisions differently across jurisdictions. India's BIS certification mandates additional testing for tropical climate degradation resistance, creating a distinct regulatory entry barrier. Stakeholders must monitor evolving short-circuit current ratings as renewable inverter-based generation alters fault current profiles in legacy grid configurations.
Market Dynamics
AI-driven power density requirements in hyperscale data centers are forcing rapid electrical infrastructure upgrades, compressing procurement cycles and elevating short-circuit withstand specifications across low-voltage panel assemblies.
Growth Catalysts
- Data Center Electrification:Hyperscale facilities exceeding 50-megawatt substation thresholds are driving specialized panel configurations with enhanced arc-flash mitigation and selective coordination capabilities.
- IEC 61439 Certification Expansion:Tightened low-voltage switchgear assembly standards are mandating upgraded testing protocols that favor manufacturers with captive certification laboratories across export markets.
- India Grid Modernization:Industrial corridor electrification and rural distribution network upgrades are accelerating procurement of tropical-climate-rated panels with BIS certification compliance.
Market Restraints
- Copper Busbar Volatility:Concentrated mining output from Chile and Peru creates input cost instability that compresses margin predictability for panel fabricators.
- Molded-Case Circuit Breaker Supply Concentration:Limited qualified suppliers for high-interrupting-capacity breakers extend lead times and create single-source vulnerability in critical component tiers.
- Dual Certification Burden:Simultaneous UL 891 and IEC 61439 compliance requirements fragment R&D budgets and extend product launch timelines for transatlantic market access.
Strategic Opportunities
- Digital Twin Integration:Virtual commissioning and predictive thermal modeling are converging with panel design workflows, enabling remote diagnostics and reduced commissioning labor.
- Rural Electrification in India:Government-mandated village electrification programs under CEA directives create demand for cost-optimized outdoor distribution panels with IP65 hardening.
- Renewable Inverter Integration:Solar and wind farm interconnection requirements are opening specification windows for panels with modified fault current profiles and bi-directional metering.
Industry Challenges
- Arc-Flash Engineering Talent Scarcity:Qualified power systems engineers capable of calculating incident energy and coordinating protective devices command premium compensation and extend project staffing timelines.
- Legacy Substation Retrofit Complexity:Space-constrained urban commercial buildings require custom panel configurations that increase engineering hours and compress standardization benefits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distribution Panel Market |
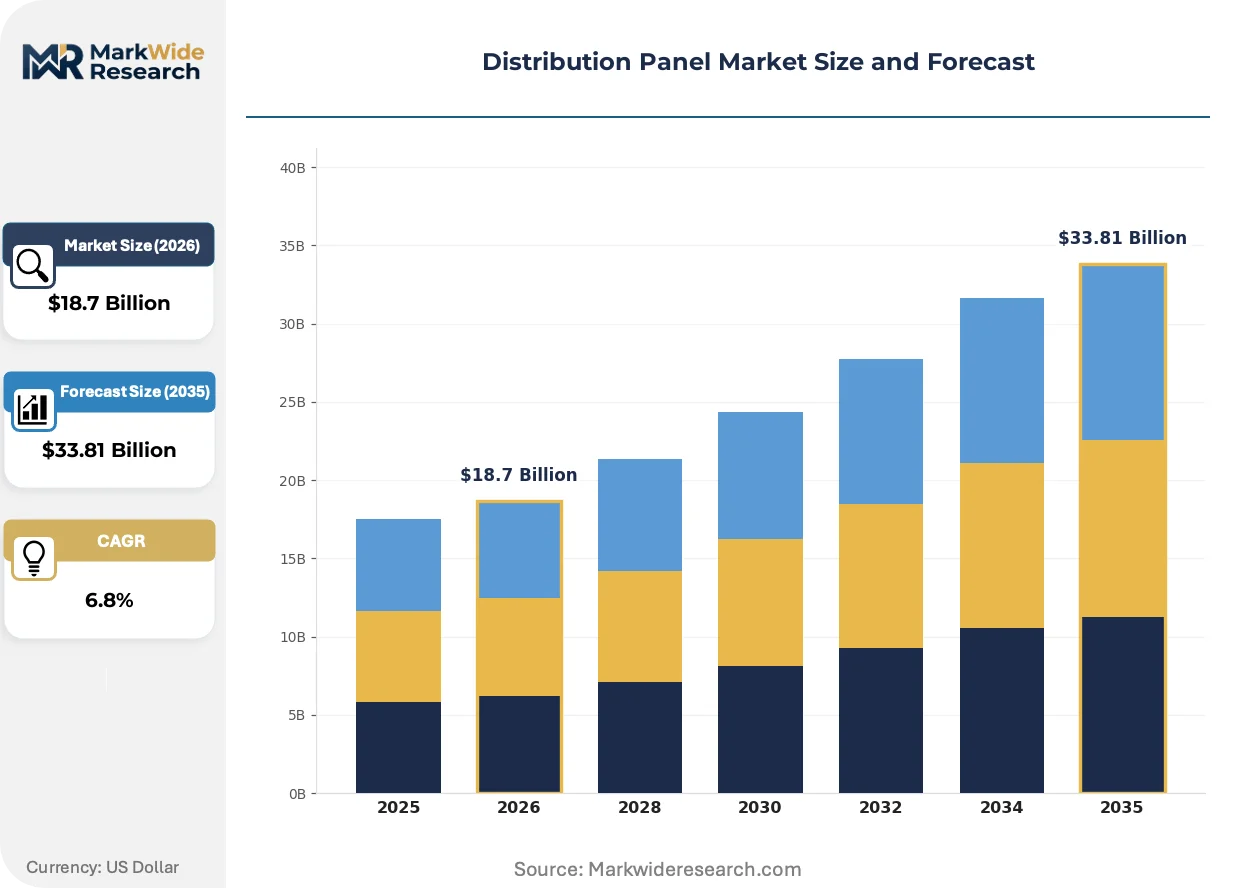
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Panels, Main Distribution Boards, Switchboards, Protection Panels End User: Commercial Buildings, Industrial Facilities, Residential Units, Data Centers Installation Type: Indoor, Outdoor, Wall-mounted, Freestanding Voltage Rating: Low Voltage, Medium Voltage, High Voltage, Extra High Voltage |
| Companies Covered | Schneider Electric, Siemens AG, ABB Ltd., Eaton Corporation, General Electric, Mitsubishi Electric Corporation, Legrand SA, Larsen & Toubro Limited, Hager Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distribution Panel Market Emerging Trajectories
Busbar material substitution and intelligent monitoring architectures are reshaping competitive positioning, while regulatory fragmentation accelerates regional specialization in certification capabilities.
Copper-aluminum hybrid busbar systems are expanding into data center and heavy industrial applications where weight reduction and cost stabilization outweigh conductivity trade-offs. Hyperscale operators in Northern Virginia and Frankfurt are specifying these configurations for rooftop and elevated installations. The technology is expanding into premium panel tiers previously reserved for solid copper assemblies.
EU F-Gas Regulation phase-down mandates are compelling manufacturers to redesign sealed panel compartments and explore natural insulation mediums for medium-voltage assemblies. Industrial fabricators face retrofit obligations for installed base equipment containing synthetic fluorinated gases. German and French panel OEMs are accelerating R&D partnerships with gas-insulated switchgear specialists to maintain CE marking compliance.
Consolidated procurement frameworks among data center developers are compressing vendor qualification cycles and elevating lifecycle service obligations over upfront capital cost. Engineering-procurement-construction firms are bundling panel specifications into substation turnkey contracts, displacing traditional distributor channels. This concentration is most visible in Phoenix and Singapore, where hyperscale clusters have centralized supply base management through designated master service agreements.
Distribution Panel Market Segmentation
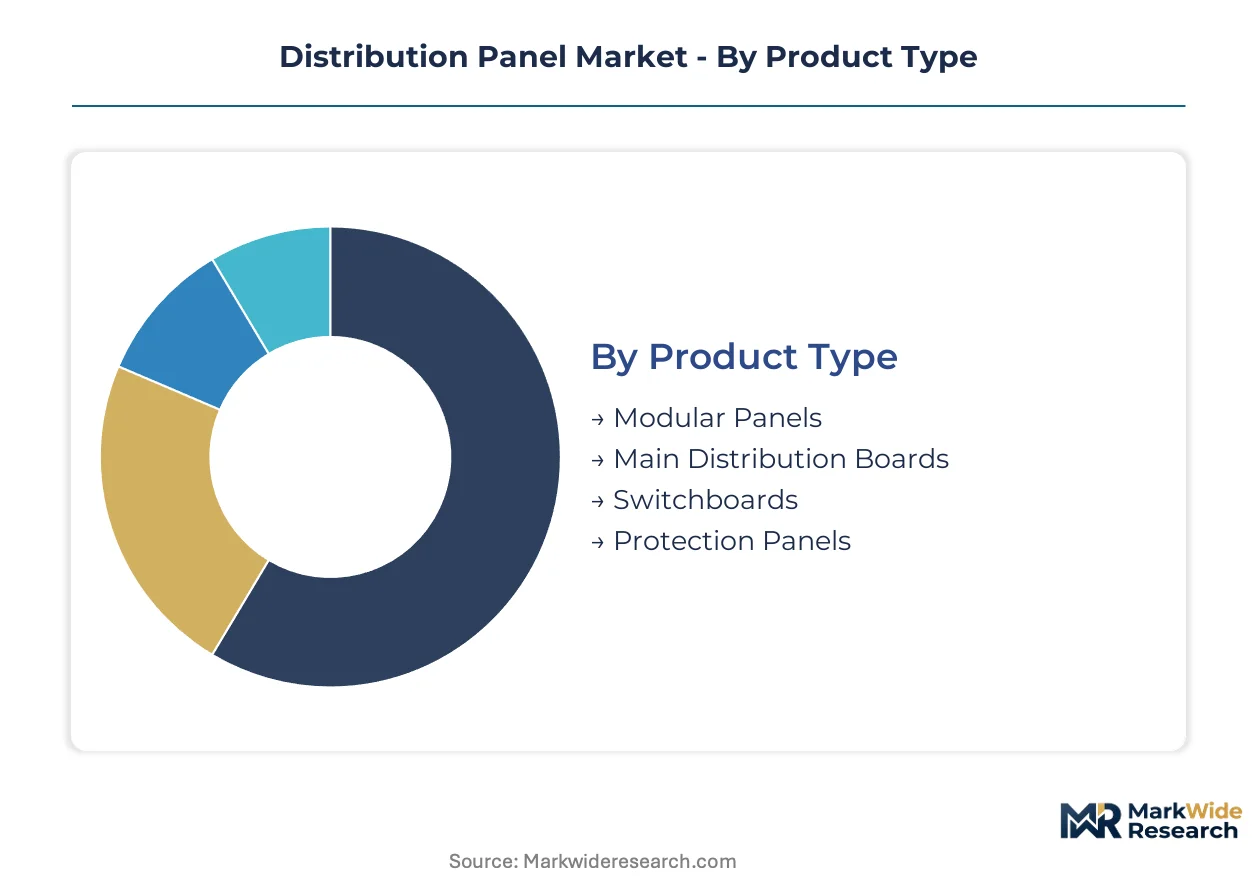
Distribution panel segmentation reveals divergent engineering priorities across voltage tiers and installation environments. Specification requirements from data center operators versus industrial facilities create distinct product development tracks that manufacturers must balance against certification cost burdens.
Product Type:
Volume concentration sits with standardized configurations, while premium engineering hours flow toward custom arc-flash mitigated assemblies for hyperscale substations.
- Modular Panels:Standardized busbar and breaker compartments enable rapid field configuration without custom engineering. Demand concentrates in German industrial corridors where facility expansion cycles favor plug-and-play electrical infrastructure over engineered-to-order alternatives.
- Main Distribution Boards:Centralized power distribution nodes rated for 400-600 ampere main breaker capacity serve as primary feed points for multi-tenant commercial buildings. Mumbai and Bangalore commercial developments specify these for high-rise electrical risers where selective coordination mandates dominate specification criteria.
- Switchboards:Front-accessible breaker arrangements with draw-out capabilities support maintenance-intensive heavy industrial applications.
- Protection Panels:Relay-based fault isolation systems for medium-voltage substation integration.
Today's leader: Main Distribution Boards. Tomorrow's challenger: Modular Panels.
End User:
Application-driven specification divergence separates mission-critical uptime requirements from cost-optimized commodity procurement.
- Data Centers:Hyperscale facilities in Northern Virginia and Frankfurt specify panels with enhanced arc-flash mitigation and selective coordination capabilities to support 50-megawatt substation thresholds. Procurement cycles compress as AI-driven power density requirements force rapid electrical infrastructure upgrades.
- Industrial Facilities:Heavy manufacturing corridors in India demand tropical-climate-rated outdoor configurations with IP65 hardening and BIS certification compliance. Arc-flash engineering talent scarcity extends project staffing timelines for complex coordination studies.
- Commercial Buildings:Space-constrained urban retrofits drive premium pricing for indoor installations.
- Residential Units:Cost-optimized standardized panels for multi-dwelling unit developments.
Data Centers command premium engineering attention. Industrial Facilities anchor volume scale.
Installation Type:
Environmental exposure determines enclosure engineering investment and IP rating certification pathways.
- Indoor:Space-constrained retrofit conditions in urban commercial buildings command premium pricing due to dimensional customization requirements. Legacy substation complexity increases engineering hours and compresses standardization benefits for Manhattan and London financial district upgrades.
- Outdoor:Freestanding configurations with tropical climate degradation resistance serve Indian industrial corridors where government-mandated village electrification programs under CEA directives create demand for cost-optimized IP65-hardened assemblies.
- Wall-mounted:Compact footprint configurations for commercial building electrical closets.
- Freestanding:Elevated structural bases for flood-prone industrial sites.
Indoor captures margin concentration. Outdoor drives unit volume expansion.
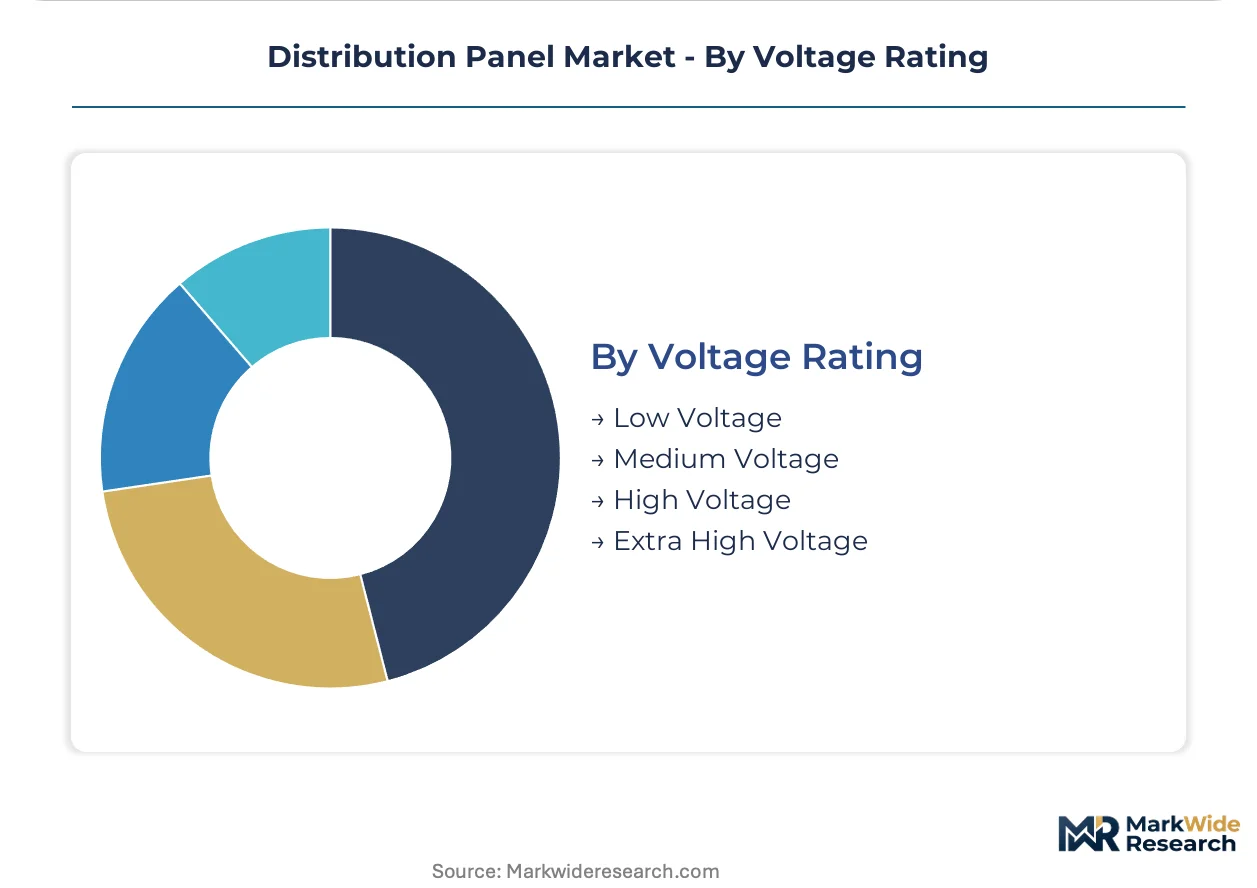
Voltage Rating:
Maturity gradients separate established low-voltage competition from specialized medium-voltage engineering barriers.
- Low Voltage:Mature volume base rated 240-1000 volts constitutes the standardized panel market where copper busbar volatility and molded-case circuit breaker supply concentration compress margin predictability. IEC 61439 and UL 891 dual certification requirements fragment R&D budgets for transatlantic market access.
- Medium Voltage:Specialized arc-flash mitigation technologies and gas-insulated switchgear integration dominate competitive positioning as EU F-Gas Regulation phase-down mandates compel sealed compartment redesign. German and French OEMs accelerate R&D partnerships to maintain CE marking compliance.
- High Voltage:Utility-scale substation integration requiring specialized relay protection engineering.
- Extra High Voltage:Transmission-level interconnection infrastructure for grid backbone applications.
Low Voltage anchors revenue scale. Medium Voltage holds technology differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting production capacity toward jurisdictions with streamlined certification pathways, as dual UL-IEC compliance burdens erode margin predictability for manufacturers serving transatlantic markets.
United States
Hyperscale data center clusters in Northern Virginia and Phoenix are compressing procurement cycles for arc-flash mitigated panel assemblies. FERC interconnection standards and NEC Article 408 requirements govern selective coordination mandates. Dallas-Fort Worth industrial corridors are absorbing relocated fabrication capacity from higher-compliance-cost jurisdictions.
Germany
EU F-Gas Regulation phase-down mandates are compelling sealed compartment redesign for medium-voltage gas-insulated switchgear integration. CE marking directives and REACH compliance frameworks elevate testing overhead for export-bound fabricators. The Ruhr industrial basin and Bavarian manufacturing zones are consolidating captive certification laboratory investments.
India
Grid modernization under CEA directives and rural electrification programs are accelerating tropical-climate-rated panel procurement. BIS certification mandates for degradation resistance create distinct entry barriers against non-compliant imports. Mumbai-Pune and Delhi-Mumbai Industrial Corridor zones are concentrating demand for IP65-hardened outdoor configurations.
China
Dual carbon goals and MIIT industrial efficiency standards are reshaping specification criteria for low-voltage switchgear in manufacturing zones. GB standards compliance anchors domestic procurement while IEC alignment supports Belt and Road export markets. Yangtze River Delta clusters are integrating copper-aluminum hybrid busbar production for weight-sensitive data center applications.
United Arab Emirates
Mega-project electrification for NEOM and Red Sea tourism developments is driving premium panel specifications with enhanced environmental hardening. MOHAP-adjacent infrastructure standards and Saudi SABER conformity requirements fragment Gulf market access. Dubai Industrial City and Jebel Ali Free Zone are emerging as re-export hubs for Africa and South Asia.
Distribution Panel Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue digital twin-enabled service models and regional certification specialization. The vendor base stratifies across captive manufacturing networks, R&D-intensive engineering houses, and regionally focused fabricators. Three archetypes dominate: vertically integrated electrical conglomerates, specialist arc-flash engineering firms, and cost-optimized tropical-climate panel suppliers. Competitive moves center on backward integration into copper busbar production and strategic partnerships with gas-insulated switchgear specialists.
Among European-based electrical conglomerates, Schneider Electric and Siemens AG exemplify the vertically integrated archetype with multi-continental manufacturing footprints. ABB Ltd. anchors the specialist tier through medium-voltage arc-flash mitigation capabilities. These three occupy positions that reflect divergent strategic postures toward certification burden management and service-led revenue expansion.
| Leading Market Players |
|---|
| Schneider Electric |
| Siemens AG |
| ABB Ltd. |
| Eaton Corporation |
| General Electric |
| Mitsubishi Electric Corporation |
| Legrand SA |
| Larsen & Toubro Limited |
| Hager Group |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between IEC 61439-compliant premium assemblies and commodity-grade domestic panels manifests in divergent margin structures and sourcing strategies across manufacturer tiers. Premium-tier fabricators absorb captive laboratory investments into unit economics, while commodity suppliers in India and Southeast Asia compete on copper-aluminum hybrid busbar configurations and regional logistics optimization.
Pricing Analysis
Distributor markups compress as engineering-procurement-construction firms consolidate procurement through master service agreements in hyperscale data center clusters. Three-tier pricing structure across premium certified, standard industrial, and economy rural electrification levels reflects dual UL-IEC certification overhead versus BIS-only compliance. Cost compression in low-voltage commodity tiers intensifies because copper busbar volatility transfers directly to spot-contract renegotiations. Data center developers exhibit lowest price sensitivity due to lifecycle service bundling, while rural electrification contractors in India face acute budget constraints under CEA directive mandates.
Supply Chain Analysis
Regional distribution centers in Germany, India, and the United States anchor hub-and-spoke patterns for finished panel logistics, with captive manufacturing co-located in high-demand corridors. Raw material dependencies center on Chilean and Peruvian copper concentrate, Chinese aluminum smelter output, and specialized molded-case circuit breaker supply from concentrated Tier 1 electrical component manufacturers. Single-source vulnerability in high-interrupting-capacity breaker tiers creates procurement risk during capacity allocation cycles. Distribution runs through authorized distributor networks for standardized configurations, while custom arc-flash mitigated assemblies ship direct-to-site under EPC contractor coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in medium-voltage arc-flash mitigation tiers where engineering scarcity and certification barriers protect pricing power against commodity low-voltage competition.
For Market Incumbents: Deepen backward integration into copper busbar production to buffer Chilean mining concentration risk and stabilize input cost predictability. Expand captive certification laboratory footprint across India and Germany to capture CEA directive and EU F-Gas Regulation compliance premiums before regional specialists consolidate access. Defend against digital twin-enabled service competitors by embedding predictive thermal modeling into standard maintenance contracts. For New Entrants and Emerging Players: Digital twin-enabled remote diagnostics capabilities offer technology-first wedge into data center lifecycle service contracts where incumbent engineering-procurement-construction relationships remain underdeveloped. Target rural electrification procurement under India's CEA directives through cost-optimized IP65-hardened outdoor configurations with localized BIS certification partnerships. Pursue direct sales-to-utility models bypassing traditional distributor markups in government-mandated village electrification programs. For Investors and Strategic Acquirers: Consolidation pressure builds where arc-flash engineering talent scarcity and dual certification overhead fragment mid-tier fabricators into distressed sale opportunities. Long-term viability favors specialists with captive medium-voltage gas-insulated switchgear partnerships and tropical-climate testing infrastructure. Watch hyperscale data center capex announcements in Northern Virginia and Frankfurt as inflection indicators for premium panel demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Busbar Production | Captive supply from Chilean concentrate insulates margin volatility from mining output disruptions. |
| Captive Certification Laboratory Expansion | Dual UL 891 and IEC 61439 testing capacity accelerates transatlantic product launch timelines. |
| Digital Twin Platform Development | Virtual commissioning reduces on-site engineering hours for hyperscale data center deployments. |
| Gas-Insulated Switchgear Partnership | EU F-Gas Regulation compliance secures CE marking for medium-voltage sealed compartment redesigns. |
| Tropical Climate Testing Infrastructure | BIS certification capability unlocks CEA-mandated rural electrification procurement in India. |
Methodological Framework
Multiple input streams — primary interviews with electrical infrastructure procurement managers, EPC contractor project directors, and arc-flash engineering specialists; secondary validation through IEC certification databases, FERC interconnection filings, and CEA directive documentation; plus customs trade data on copper busbar and circuit breaker imports — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured specification criteria from hyperscale data center developers in Northern Virginia and Frankfurt, industrial facility engineers in India's Delhi-Mumbai Industrial Corridor, and distributor inventory managers across German industrial zones. Secondary sources included SEC 10-K disclosures from listed electrical conglomerates, BIS certification registries, and EU F-Gas Regulation compliance filings.
Data-stream reconciliation anchored volume and value outputs across the projection horizon through segmented modeling of voltage tier, installation environment, and end-use application. Segmentation dimensions encompassed low-voltage versus medium-voltage ratings, indoor versus outdoor configurations, and data center versus industrial versus commercial building demand pools. CAGRs were derived from regression analysis against hyperscale facility power density trajectories and grid modernization capex cycles. Industry-specific forecast inputs incorporated AI-driven substation upgrade timelines and renewable inverter interconnection specifications.
The model holds under stable copper concentrate supply and sustained hyperscale data center expansion; deviation in Chilean mining output or FERC interconnection queue delays would shift demand timing and margin distribution across manufacturer tiers. Forecasts reflect documented assumptions on certification harmonization progress and regional electrification program funding continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Distribution
Global Electric Power Distribution Automation Systems Market
Power Distribution
AI in Energy Distribution Market
Power Distribution
Europe DC Distribution Network Market
Power Distribution
Medium Voltage AC Power Distribution Units (PDU) Market
Power Distribution
Power Distribution Cables Market
Power Distribution
Power Distribution Unit (PDU) Market
Power Distribution
Distribution Board Market
Power Distribution
North America and Europe Power Distribution Component Market
Power Distribution
Lighting and Distribution Panel Board Market
Power Distribution
Brazil City Gas Distribution Market
Power Distribution
Global Power Distribution Component Market