
 Power Assisted Steering Market | 2026-2036
Power Assisted Steering Market Size, Share, and Industry Trends Forecast 2026-2036
Power Assisted Steering Market Intelligence
The power assisted steering supply base is consolidating around two distinct performance tiers. Premium electric steering architectures with integrated ECUs and torque sensors now command disproportionate engineering resources, while commodity hydraulic rack-and-pinion systems face pricing compression in emerging markets. JTEKT Corporation leverages its bearing heritage to control precision gear manufacturing for column-assist systems. Nexteer Automotive anchors North American production with dedicated capacity for full-size truck platforms. ZF Friedrichshafen AG dominates integrated steer-by-wire development through its chassis systems division.
Power assisted steering encompasses electromechanical and hydraulic actuation systems that reduce driver steering effort through supplemental torque generation, typically operating at voltages between 12V and 48V depending on architecture. These systems serve the essential function of enabling precise vehicle directional control across varying speeds and load conditions. Electric power steering now leads value creation as automakers prioritize CO2 reduction and ADAS compatibility, while electro-hydraulic power steering retains share in heavy truck applications where hydraulic auxiliary circuits remain entrenched. Rack assist technology is accelerating fastest among passenger car variants due to its packaging efficiency and direct road feel calibration.
NHTSA crashworthiness standards and EPA corporate average fuel economy mandates in the United States compel OEMs to specify lighter electric steering architectures. ECE R79 in Europe governs steering system safety performance, while China's GB standards for passenger car steering establish domestic certification thresholds. Stakeholders must monitor how 48V electrical architecture proliferation and steer-by-wire validation timelines reshape supplier qualification requirements and platform sourcing decisions.
Market Dynamics
Stricter emissions mandates across major automotive markets are forcing rapid phase-out of hydraulic power steering architectures in favor of electromelectric systems that reduce parasitic engine load and enable ADAS integration.
Growth Catalysts
- EPA Corporate Average Fuel Economy mandates:US OEMs must achieve fleet-wide efficiency targets that electric power steering directly supports through eliminated hydraulic pump drag.
- China's dual carbon goals:Domestic automakers face binding CO2 reduction commitments that accelerate electrified steering adoption across passenger vehicle platforms.
- 48V electrical architecture proliferation:Higher voltage systems enable more powerful rack-assist motors required by heavier electrified vehicles and advanced driver assistance functions.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings embedded in permanent magnet motors create input cost unpredictability for electric steering suppliers.
- Precision gear manufacturing concentration:Cold-forged rack and pinion production clusters in specific industrial regions create geographic supply vulnerability.
- Hydraulic system legacy entrenchment:Heavy commercial truck segments retain electro-hydraulic architectures due to auxiliary hydraulic circuit requirements for lifts and pumps.
Strategic Opportunities
- India passenger car electrification:Domestic OEMs expanding EV production create fresh demand for column-assist electric systems in compact vehicle segments.
- Steer-by-wire regulatory validation:Anticipated ECE R79 amendments enabling fully electronic steering without mechanical backup open architecture redesign possibilities.
- Software-defined steering calibration:Over-the-air update capabilities allow tier-one suppliers to monetize continuous handling optimization services post-sale.
Industry Challenges
- Functional safety engineering scarcity:ISO 26262 ASIL-D certification expertise for steering ECUs remains concentrated among limited specialist engineering pools.
- Legacy platform integration complexity:Retrofitting electric steering onto existing vehicle architectures originally designed for hydraulic systems demands extensive chassis recalibration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Assisted Steering Market |
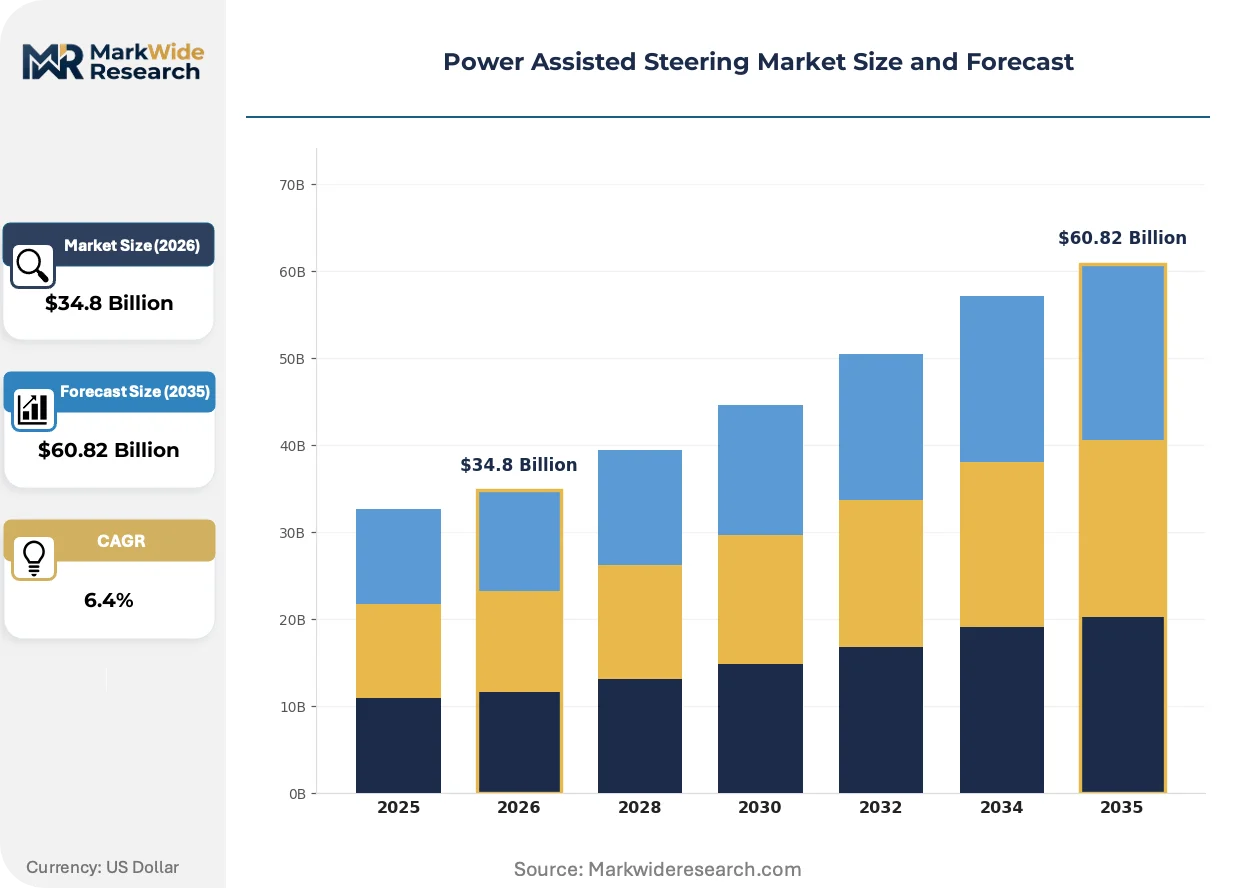
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $60.82 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
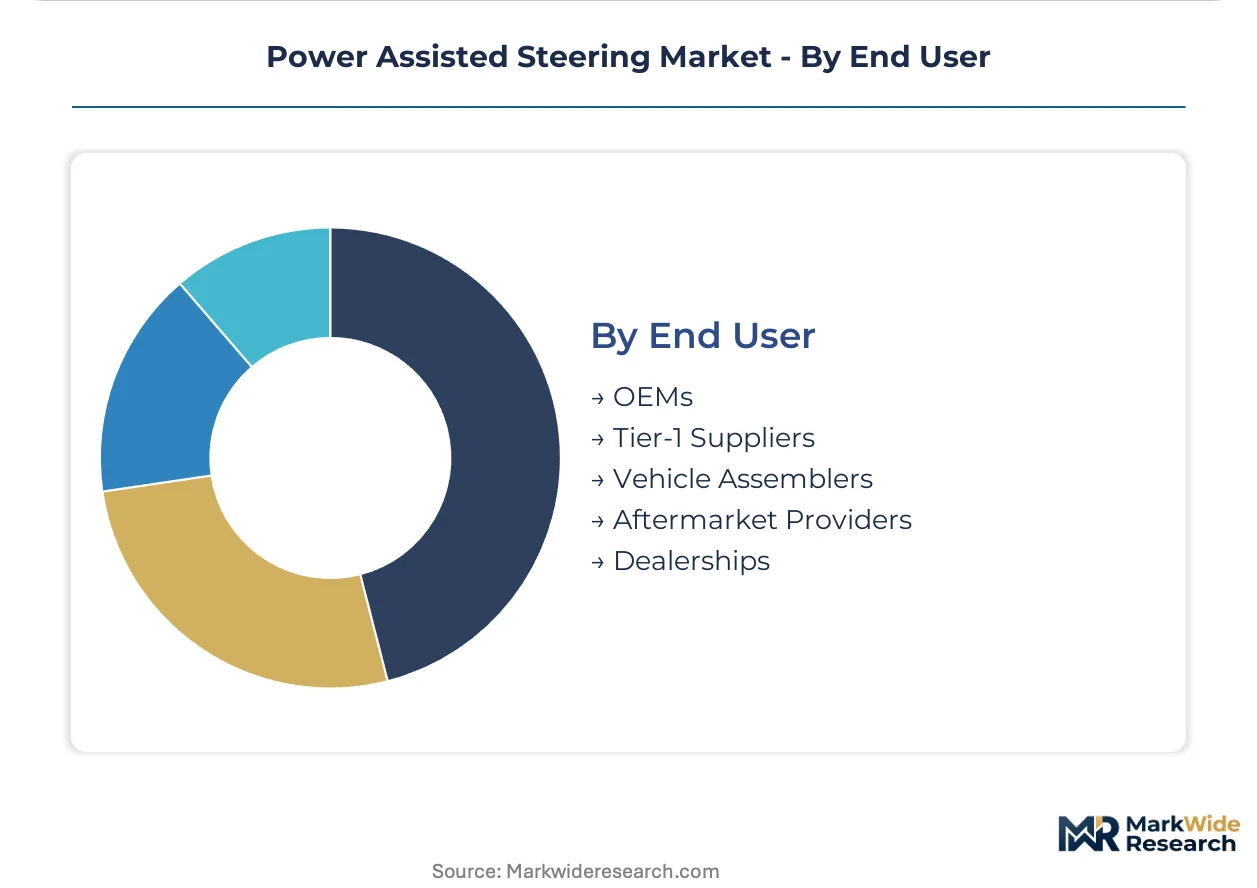
| Segmentation | Product Type: Hydraulic Power Steering, Electric Power Steering, Electro-Hydraulic Power Steering, Variable Gear Ratio Steering Technology: Steer-By-Wire, Column Assist, Rack Assist, Pinion Assist, Dual Pinion Application: Passenger Cars, Light Commercial Vehicles, Heavy Trucks, Commercial Vans, Off-highway Vehicles End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers, Dealerships |
| Companies Covered | JTEKT Corporation, Nexteer Automotive, ZF Friedrichshafen AG, Robert Bosch GmbH, NSK Ltd, Hyundai Mobis, Mando Corp, Hitachi Astemo Ltd, SHOWA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Assisted Steering Market Strategic Shifts & Innovations
Active steering systems are converging with autonomous driving architectures, creating demand for software-intensive platforms that merge path-following algorithms with tactile feedback generation.
Steer-by-wire technology is automating the mechanical connection between steering wheel and road wheels, replacing physical linkages with electronic signal transmission. Luxury electric vehicle manufacturers are piloting production implementations ahead of regulatory approval timelines. This architecture is automating cabin packaging flexibility and crash safety design by eliminating steering column intrusion paths.
ECE R79 revisions in Europe are mandating redundant electronic control systems for any steering architecture lacking mechanical backup, effectively setting validation standards for next-generation steer-by-wire deployment. Tier-one suppliers are restructuring development organizations around functional safety compliance. Full-size truck platforms in North America face the steepest recertification burdens given their higher kinetic energy profiles.
Fleet procurement departments are consolidating supplier relationships around integrated chassis system vendors capable of bundling steering, braking, and suspension electronics. Single-source contracts are displacing multi-vendor component sourcing for platform simplification. This concentration is most visible among German premium OEMs pursuing unified software stacks across vehicle lines.
Power Assisted Steering Market Segmentation
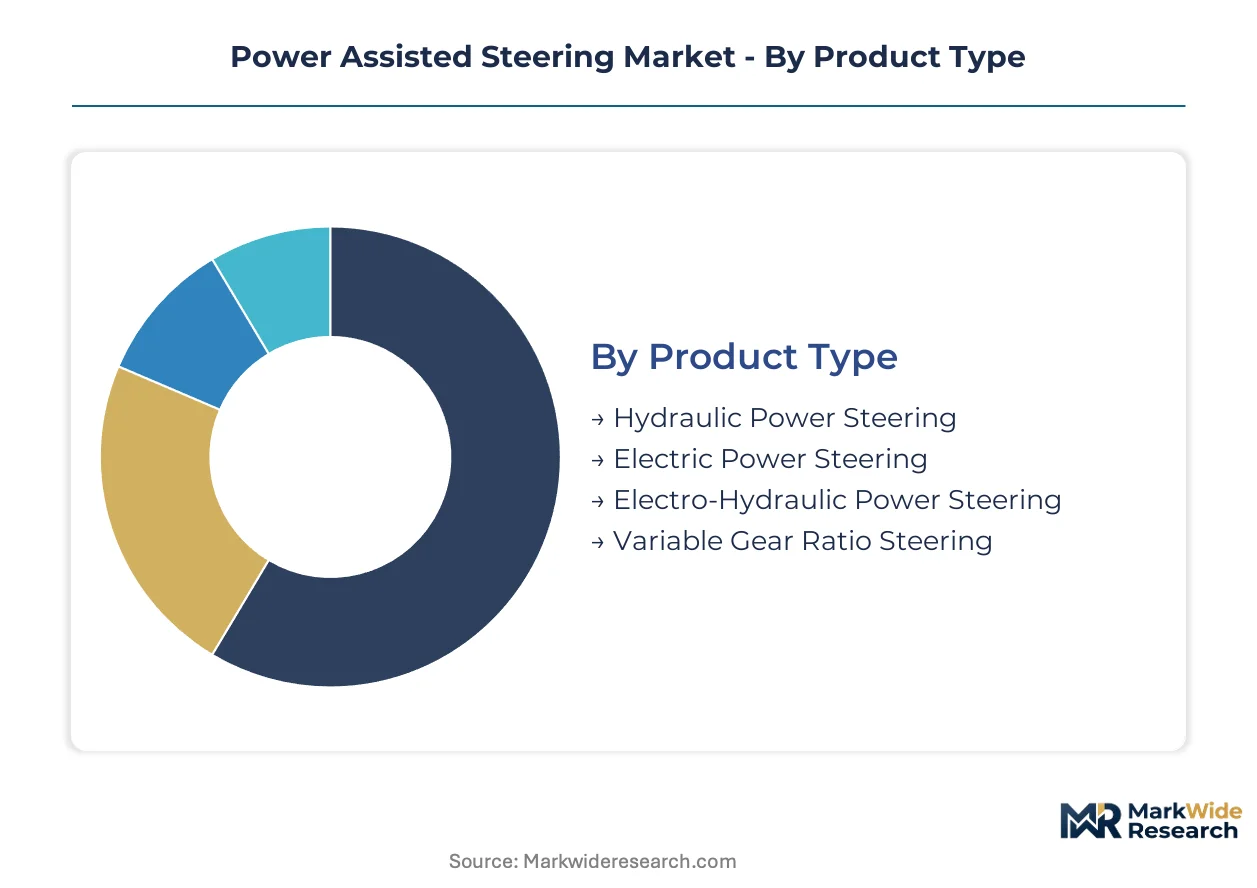
Power assisted steering procurement varies sharply by vehicle architecture and electrification roadmap. OEM sourcing strategies diverge based on platform voltage requirements, ADAS integration depth, and regional emissions compliance timelines.
Product Type:
Cost tier and fuel efficiency mandates separate buyers across this category.
- Electric Power Steering:Eliminates engine-driven hydraulic pumps through brushless DC motors and ECU-controlled torque assistance. Passenger car manufacturers in China and Europe specify this architecture to meet binding CO2 reduction targets and enable lane-keeping assist integration.
- Hydraulic Power Steering:Relies on engine-belt-driven pumps and pressurized fluid circuits for torque multiplication. Demand concentrates in legacy vehicle platforms and budget commercial segments where electrification retrofit costs prove prohibitive.
- Electro-Hydraulic Power Steering:Combines electric motor-driven pumps with retained hydraulic actuation for heavy load scenarios. Retains share in commercial truck applications requiring auxiliary hydraulic circuits for body equipment.
- Variable Gear Ratio Steering:Modulates steering ratio based on vehicle speed through planetary gearsets or software-controlled rack geometries. German premium OEMs deploy this technology to differentiate handling precision in performance vehicle lines.
Volume sits with Electric Power Steering; growth tilts toward Variable Gear Ratio Steering.
Technology:
Maturity stage and functional safety certification requirements differentiate procurement approaches.
- Rack Assist:Positions the assist motor directly on the steering rack for direct road feel and packaging efficiency. Compact passenger cars and electrified crossovers specify this architecture for its space-saving advantages and calibration flexibility.
- Steer-By-Wire:Replaces mechanical linkages with electronic signal transmission between steering wheel and road wheels. Luxury electric vehicle pilots in Germany and California are validating redundant ECU architectures ahead of anticipated ECE R79 amendments.
- Column Assist:Mounts the assist motor on the steering column for simplified integration and service access. Indian and Southeast Asian compact vehicle producers favor this cost-optimized configuration for entry-level platforms.
- Pinion Assist:Locates the assist mechanism at the steering gear pinion for intermediate packaging solutions. Mid-size sedans and crossover utilities deploy this architecture balancing cost and performance attributes.
- Dual Pinion:Employs two pinion gears separating driver input from assist motor torque for enhanced precision. Premium sports cars and performance electric vehicles specify this configuration for track-capable steering response.
Volume sits with Column Assist; growth tilts toward Steer-By-Wire.
Application:
Vehicle mass and duty cycle severity determine assist power requirements and architecture selection.
- Passenger Cars:Encompasses sedans, hatchbacks, crossovers, and SUVs for personal transportation. Chinese domestic automakers and European volume manufacturers drive specification shifts toward rack-assist electric systems across electrified platforms.
- Heavy Trucks:Covers Class 8 commercial vehicles and long-haul tractors with sustained high-load steering demands. North American fleet operators retain electro-hydraulic architectures to preserve auxiliary hydraulic capacity for trailer and body equipment.
- Light Commercial Vehicles:Includes pickup trucks, delivery vans, and chassis-cab configurations under 6,000 kg GVWR. Urban last-mile delivery electrification in California and the Netherlands accelerates electric steering conversion for regenerative braking compatibility.
- Commercial Vans:Encompasses medium-duty parcel and service vehicles with frequent stop-start operation. European city logistics operators specify electric steering to reduce fuel consumption in dense urban duty cycles.
- Off-highway Vehicles:Covers agricultural tractors, construction equipment, and mining vehicles operating in unimproved terrain. Brazilian and Australian mining fleet operators demand ruggedized electro-hydraulic systems for contamination resistance.
Volume sits with Passenger Cars; growth tilts toward Light Commercial Vehicles.
End User:
Integration depth and warranty liability exposure separate sourcing relationships.
- OEMs:Original equipment manufacturers specifying steering systems for captive vehicle platforms. German and Japanese OEMs are consolidating sourcing around integrated chassis system suppliers capable of bundling steering, braking, and suspension electronics.
- Tier-1 Suppliers:System integrators assembling steering modules for OEM platform supply. JTEKT, Nexteer, and ZF structure manufacturing footprints around regional vehicle production clusters to minimize logistics costs.
- Vehicle Assemblers:Contract manufacturers and joint venture operations building vehicles under license or partnership arrangements. Chinese-foreign JV assemblers adopt parent-company steering specifications with localized component sourcing.
- Aftermarket Providers:Independent distributors and remanufacturers serving vehicle service and repair channels. North American and European aftermarket specialists focus on remanufactured rack-and-pinion units for aging vehicle parc maintenance.
- Dealerships:Authorized service networks performing warranty repairs and recommended maintenance. US dealership groups report rising electric steering module replacement rates as early EPS-equipped vehicles age.
Volume sits with OEMs; growth tilts toward Tier-1 Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European power assisted steering engineering density, hosting multiple tier-one supplier headquarters and validation facilities serving premium OEM platforms.
China
Domestic automakers BYD and NIO expand electrified vehicle production requiring rack-assist electric systems. MIIT enforces GB standards for passenger car steering certification. Yangtze River Delta manufacturing clusters around Shanghai supply precision gear components to global tier-one integrators.
Germany
Premium OEMs consolidate sourcing around integrated chassis system vendors bundling steering and braking electronics. KBA administers ECE R79 compliance for steer-by-wire validation timelines. Baden-Württemberg engineering centers drive redundant ECU architecture development for next-generation platforms.
United States
Full-size truck manufacturers retain electro-hydraulic capacity for auxiliary hydraulic circuits in commercial applications. NHTSA crashworthiness standards compel lighter electric steering architectures for passenger vehicles. Michigan-based production facilities anchor North American supply for Detroit Three electrification roadmaps.
Japan
Keiretsu-affiliated suppliers leverage bearing heritage for precision gear manufacturing in column-assist systems. METI coordinates automotive component export standards with ASEAN markets. Kanto region R&D centers focus on torque sensor integration for ADAS-compatible platforms.
India
Domestic OEMs Tata Motors and Mahindra expand EV production creating demand for cost-optimized column-assist systems. BIS establishes certification thresholds for electric steering component safety. Tamil Nadu automotive corridors attract tier-one supplier manufacturing investments for compact vehicle segments.
Power Assisted Steering Market Key Industry Players
Capital-heavy producers compete with asset-light designers across distinct performance tiers. The supply base concentrates around two structural poles: integrated chassis system vendors bundling steering, braking, and suspension electronics, and specialized component manufacturers controlling precision gear or sensor subsystems. Strategic archetypes include full-system integrators, precision component specialists, and software-defined platform developers. Dominant competitive moves encompass regional capacity expansion to follow OEM production clusters and functional safety certification investments to qualify for steer-by-wire programs.
Within the full-system integrator tier, ZF Friedrichshafen AG and JTEKT Corporation exemplify divergent geographic anchoring strategies. Nexteer Automotive occupies a position bridging North American truck platform specialization with passenger car electrification transitions. These three entities represent distinct competitive postures: European-integrated chassis dominance, Japanese precision manufacturing heritage, and North American regional production dedication.
| Leading Market Players |
|---|
| JTEKT Corporation |
| Nexteer Automotive |
| ZF Friedrichshafen AG |
| Robert Bosch GmbH |
| NSK Ltd |
| Hyundai Mobis |
| Mando Corp |
| Hitachi Astemo Ltd |
| SHOWA Corporation |
| Others |
Cost & Logistics Intelligence
Backward integration into precision gear manufacturing anchors tier-one suppliers' supply positions and pricing power, with JTEKT and ZF leveraging captive production of cold-forged rack components to defend margin structures against commodity hydraulic system competitors.
Pricing Analysis
Value-based pricing anchored to fuel efficiency outcomes and ADAS integration depth structures tier differentiation across electric steering architectures. Three-tier pricing separates steer-by-wire development programs from rack-assist production volumes from column-assist economy platforms, with ISO 26262 ASIL-D certification tier commanding substantial premiums. Cost compression in hydraulic legacy systems is intensifying because Chinese domestic OEMs are forcing component localization. Fleet procurement departments at North American truck operators exhibit lowest price sensitivity due to auxiliary hydraulic circuit requirements, while Indian compact vehicle producers demonstrate highest sensitivity to per-unit system costs.
Supply Chain Analysis
ISO 26262 functional safety certification gates tier-one supplier qualification, concentrating production among engineering pools capable of ASIL-D ECU validation. Precision gear manufacturing clusters in Germany, China, and Japan, with cold-forged rack and pinion production drawing from specialized industrial regions. Neodymium and dysprosium magnet supply rests on concentrated rare earth processing capacity, creating single-source vulnerability for permanent magnet motor inputs. Distribution runs through integrated chassis system vendors bundling steering, braking, and suspension electronics for German premium OEM platform simplification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with tier-one suppliers pursuing upstream control over torque sensor and precision gear production to capture value migrating from mechanical to electronic content.
For Market Incumbents: Lock in steer-by-wire validation timelines ahead of anticipated ECE R79 amendments by concentrating functional safety engineering resources in Baden-Württemberg and Kanto region centers. Deepen backward integration into rare earth magnet supply through offtake agreements with Australian and Vietnamese processing facilities to offset neodymium price volatility threatening electric steering margins.
For New Entrants and Emerging Players: Software-defined steering calibration capabilities offer entry wedge into post-sale monetization streams, with over-the-air handling optimization services representing penetrable white space unclaimed by incumbent hardware-centric suppliers. Target Indian compact vehicle electrification roadmaps with cost-optimized column-assist architectures, leveraging Tamil Nadu automotive corridor manufacturing partnerships for localized component sourcing.
For Investors and Strategic Acquirers: Exit pathways concentrate in integrated chassis system acquisitions by brake and suspension electronics vendors seeking steering capabilities. Long-term viability favors suppliers with validated steer-by-wire architectures and captive precision gear production over component specialists exposed to hydraulic system phase-out. Watch ECE R79 amendment publication as inflection signal triggering OEM platform redesign cycles and supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Steer-by-Wire Regulatory Validation | ECE R79 compliance unlocks next-generation architecture deployment for German luxury OEM pilots. |
| Precision Gear Manufacturing Expansion | Cold-forged rack capacity additions in Yangtze River Delta anchor Chinese domestic OEM supply relationships. |
| 48V Electrical Architecture Integration | Higher voltage rack-assist motors enable heavier electrified vehicle platforms with ADAS compatibility. |
| Software-Defined Steering Calibration | Over-the-air update capabilities transform tier-one suppliers into recurring revenue service providers. |
| Rare Earth Supply Security Programs | Magnet offtake agreements with Australian processors reduce input cost unpredictability for electric steering motors. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and dealership service operations. Vehicle production databases, IHS Markit registration data, NHTSA crashworthiness filings, and MIIT certification records supplied volume and specification benchmarks. Bottom-up platform build-up and top-down market sizing triangulated electric steering content per vehicle across passenger car and commercial vehicle segments.
Data-stream reconciliation across OEM electrification roadmaps, supplier capacity announcements, and regulatory amendment timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed product type, assist technology, vehicle application, and regional production cluster, with CAGRs derived from vehicle production forecasts weighted by electrification penetration assumptions. 48V architecture proliferation curves and steer-by-wire validation milestones served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced regulatory delays, rare earth supply disruptions, and OEM platform cancellation decisions. Forecasts reflect assumptions regarding ECE R79 amendment timing and Chinese dual carbon goal enforcement intensity. A model refresh is warranted upon material change in steer-by-wire regulatory approval timelines or significant rare earth price shock.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Electric Vehicle Powertrain Market
Powertrain
Automotive Oil Sump Market
Powertrain
Brazil Automotive Engine Oils Market
Powertrain
Canada Automotive Engine Oils Market
Powertrain
Automotive Engine Degreasers Market
Powertrain
Automotive Variable Oil Pump Market
Powertrain
Fuel Cell Powertrain Market
Powertrain
India Automotive Engine Oils Market
Powertrain
Global Automotive Powertrain Management System Market
Powertrain
Automotive Transmission System Market
Powertrain
Global Automotive Engine Pulley Market
Powertrain
Automotive Crank Trigger Market
Powertrain
Automotive Fuel Pressure Regulator Market
Powertrain
Automotive Balance Shaft Market
Powertrain
Drive Mode-Linked Powertrain Actuator Systems Market
Powertrain
Global Industrial Turbocharger Market