
 Ostomy Care and Accessories Market | 2026-2036
Ostomy Care and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Ostomy Care and Accessories Market Intelligence
Asset-light leasing models for advanced ostomy appliances is narrowing the competitive field for smaller manufacturers that lack capital reserves. Coloplast A/S leverages its vertical integration across silicone adhesives and barrier films to sustain premium positioning in skin barrier systems. ConvaTec Group PLC anchors its presence through extensive direct-to-patient subscription programs that lock in recurring revenue streams. Hollister Incorporated differentiates via proprietary hydrocolloid formulations that dominate hospital procurement channels in North America and Europe.
Ostomy care and accessories encompass medical devices and consumables designed to collect waste from surgically created stomas, typically constructed from medical-grade polymers, hydrocolloid adhesives, and odor-resistant films with wear times ranging from one to seven days depending on product configuration and patient activity level. These systems serve the essential clinical purpose of maintaining skin integrity, preventing peristomal complications, and preserving patient mobility and dignity during post-surgical recovery and chronic disease management. Colostomy bags occupy the largest volume share within product type segmentation due to the prevalence of colorectal cancer interventions, while skin barriers command disproportionate margin pools because of their specialized adhesive chemistry and higher replacement frequency. Home care settings within end user segmentation represent the fastest-growing demand channel as discharge protocols accelerate and remote patient monitoring technologies reduce the need for facility-based follow-up.
The FDA's Class II medical device controls govern premarket notification requirements for ostomy appliances in the United States, while the EU Medical Device Regulation mandates clinical evidence and post-market surveillance for CE marking across European member states. Japan's PMDA enforces comparable biocompatibility and sterilization standards that shape export compliance burdens for multinational manufacturers. Stakeholders must monitor evolving reimbursement banding decisions by national health technology assessment bodies, as these determinations directly influence patient access thresholds and manufacturer pricing flexibility across priority markets.
Market Dynamics
Home care discharge acceleration is compressing hospital procurement cycles and forcing manufacturers to build direct-to-patient fulfillment capabilities that bypass traditional distributor networks entirely.
Growth Catalysts
- Aging surgical populations:Germany's statutory health insurance framework guarantees full ostomy supply reimbursement, eliminating patient cost barriers and sustaining replacement frequency for barrier films and collection pouches.
- EU Medical Device Regulation (MDR):Enhanced clinical evidence requirements for CE marking are elevating quality thresholds, advantaging manufacturers with robust post-market surveillance infrastructure over commodity suppliers.
- Silicone adhesive chemistry:Advanced skin barrier formulations with extended wear times reduce peristomal dermatitis incidence and lower total nursing intervention hours in post-acute settings.
Market Restraints
- Medical-grade polymer feedstock concentration:Specialized hydrocolloid and film substrates depend on petrochemical supply chains concentrated in German and US Gulf Coast production clusters, exposing margins to input volatility.
- FDA 510(k) pathway complexity:Substantial equivalence determinations for novel barrier adhesives extend premarket timelines, delaying revenue recognition for iterative product improvements.
- Adhesive tape substitutes:Low-cost conventional wound care tapes capture price-sensitive segments in emerging markets where reimbursement infrastructure remains underdeveloped.
Strategic Opportunities
- Remote patient monitoring convergence:Integration of moisture sensors and smartphone-connected wearables with ostomy appliances enables proactive leak detection and reduces emergency department visits.
- Japan's PMDA fast-track pathway:Streamlined approval for breakthrough medical devices accelerates market entry for novel odor-control film technologies that demonstrate superior biocompatibility profiles.
- Subscription direct-to-patient channels:Automated replenishment platforms bypass hospital purchasing committees and capture lifetime value through predictable recurring revenue streams.
Industry Challenges
- Specialized wound-ostomy-continence nursing shortage:Certified WOCN practitioners represent a bottleneck in patient education and product fitting, constraining effective adoption of advanced appliance systems.
- Legacy sterilization validation:Transition from ethylene oxide to radiation sterilization methods requires extensive bioburden studies and facility requalification that extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ostomy Care and Accessories Market |
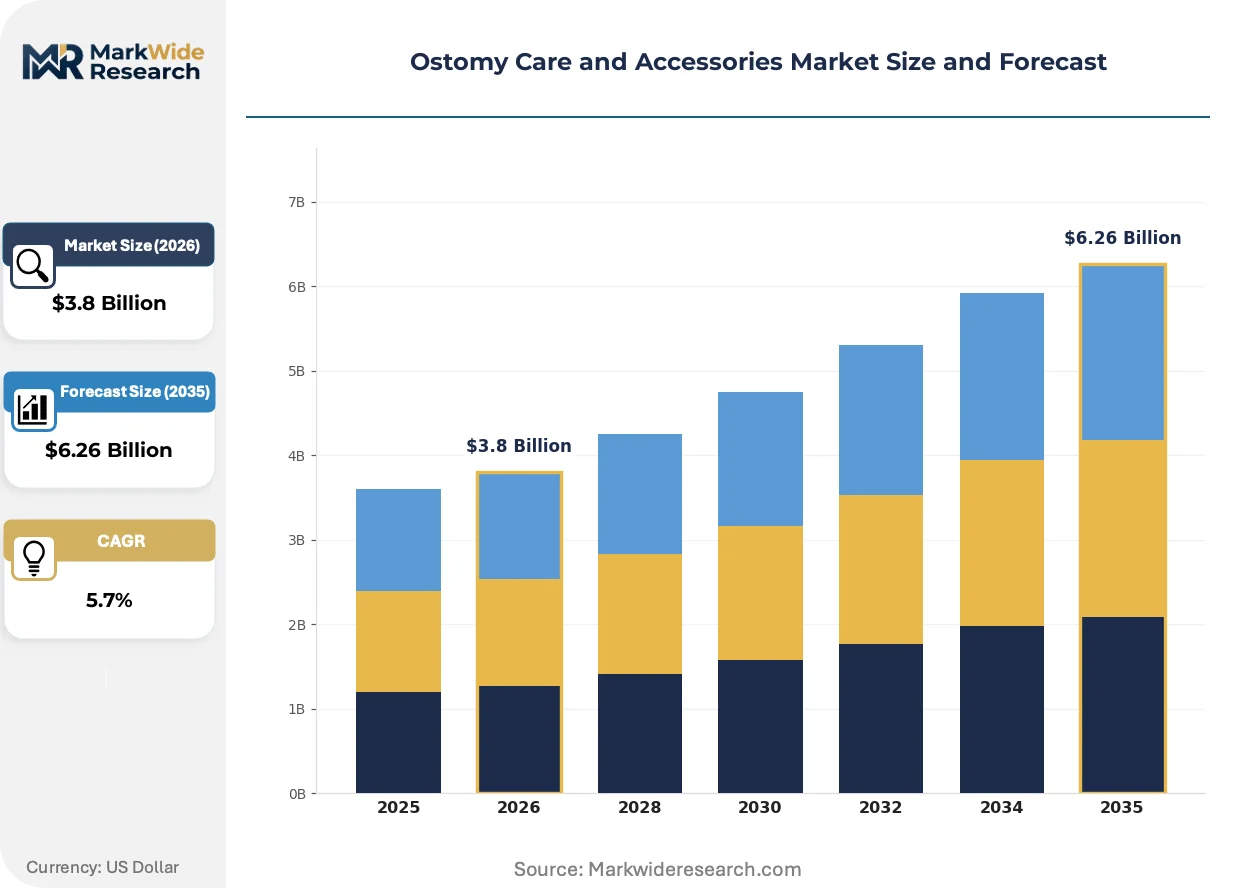
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colostomy Bags, Ileostomy Bags, Urostomy Bags, Skin Barriers Application: Post-Surgical Care, Chronic Condition Management, Wound Care, Patient Education End User: Hospitals, Clinics, Home Care, Long-Term Care Facilities Distribution Channel: Pharmacy, Online Retail, Direct Sales, Healthcare Distributors |
| Companies Covered | Coloplast A/S, ConvaTec Group PLC, Hollister Incorporated, B. Braun Melsungen AG, 3M Company, Welland Medical Limited, Smith & Nephew PLC, Salts Healthcare, Alcare Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ostomy Care and Accessories Market Strategic Shifts & Innovations
Digital health integration and materials science advances are converging to transform ostomy care from reactive symptom management into predictive, patient-directed intervention systems.
Smart ostomy appliances with embedded humidity sensors and Bluetooth connectivity are migrating from pilot programs in academic medical centers to standard-of-care protocols in integrated health networks. Post-surgical clinics in the Netherlands and Denmark are deploying these systems to reduce home health nursing visits. The technology is migrating from premium-tier experimental positioning toward mid-market accessibility as sensor component costs decline and reimbursement codes crystallize.
The EU Medical Device Regulation's post-market surveillance mandates are compelling manufacturers to maintain active clinical registries tracking real-world barrier performance and skin complication rates. This obligation is reshaping R&D resource allocation toward longitudinal evidence generation rather than incremental feature development. German and French notified bodies are enforcing these requirements most stringently, delaying CE certificates for applicants lacking robust vigilance systems.
Patients are consolidating purchasing decisions through specialized online retailers that aggregate multiple manufacturer catalogs and offer personalized fitting support via video consultation. This channel compression is displacing traditional medical supply house relationships in the United States and United Kingdom. Ostomy associations in Australia and Canada are endorsing these platforms as mechanisms to improve product access in rural and remote communities.
Ostomy Care and Accessories Market Segmentation
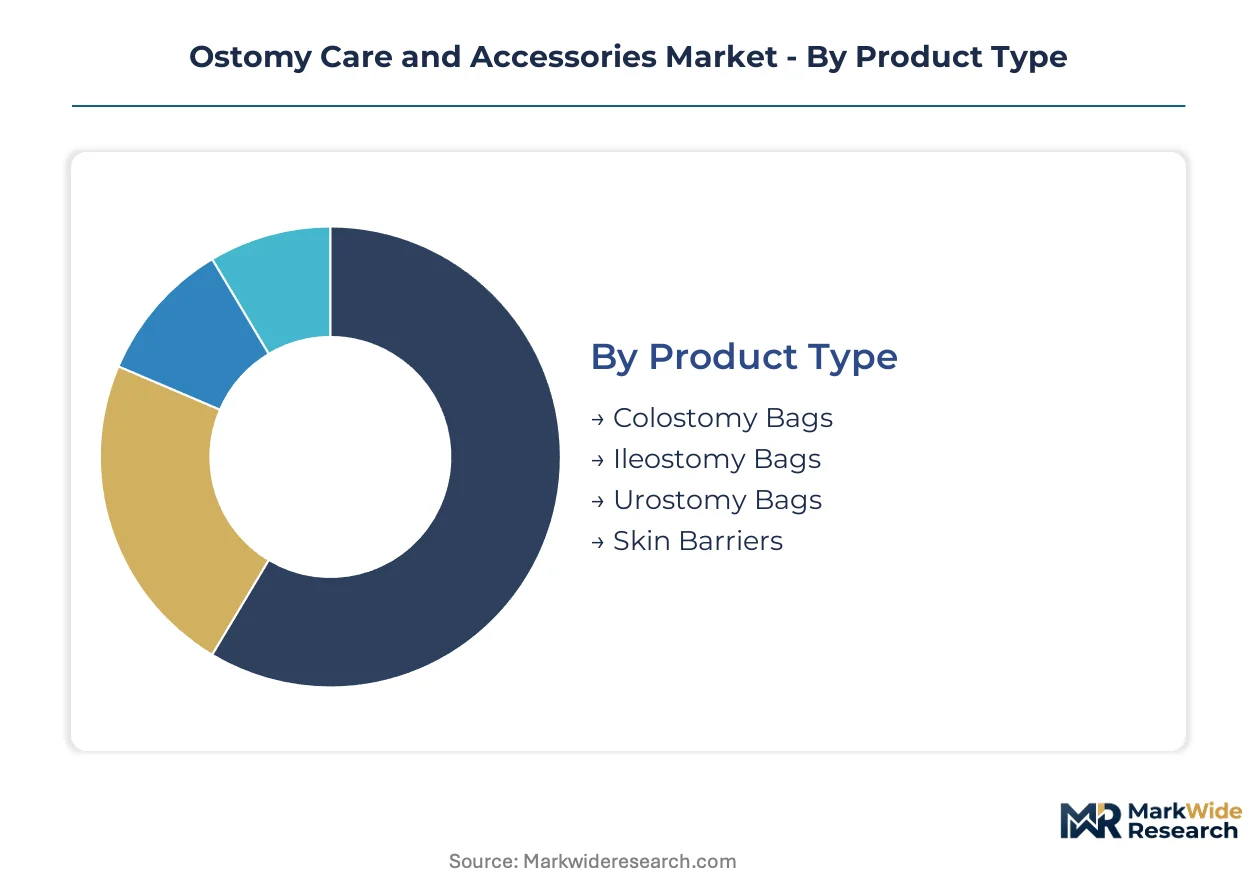
Ostomy care segmentation reflects divergent clinical workflows and patient autonomy levels across care settings. Manufacturers must calibrate product portfolios to match both acute-care procurement specifications and direct-to-patient fulfillment requirements.
Product Type:
Mature collection systems dominate hospital formulary placement, while emerging barrier technologies command premium positioning through extended wear claims.
- Colostomy Bags:These one-piece or two-piece collection systems utilize odor-resistant films and integrated charcoal filters for gas neutralization. Demand concentrates in post-colorectal cancer surgical units across Germany and the United States, where standardized discharge protocols drive high-volume procurement.
- Skin Barriers:Hydrocolloid and silicone-based adhesive wafers protect peristomal skin integrity while enabling pouch attachment. German statutory insurance reimbursement eliminates patient cost sensitivity, sustaining replacement frequencies that exceed other markets by substantial margins.
- Ileostomy Bags:High-output drainage systems with enhanced capacity and erosion-resistant materials serve small intestine diversion procedures.
- Urostomy Bags:Night drainage adapters and anti-reflux valves characterize these urinary diversion collection systems.
Colostomy bags handle the majority of throughput; skin barriers are expanding most quickly on share.
Application:
Cost tier stratification separates acute intervention from ongoing maintenance, with reimbursement banding determining accessible technology levels.
- Post-Surgical Care:Immediate postoperative management requires frequent barrier changes and specialized fitting support from certified WOCN practitioners. Hospital procurement committees in the United States prioritize standardized appliance kits that reduce nursing time per patient encounter.
- Chronic Condition Management:Long-term stoma care demands durable appliances with extended wear times and minimal skin complications. Home care settings in the Netherlands and Denmark leverage remote monitoring to sustain patient autonomy while reducing facility-based follow-up.
- Wound Care:Peristomal complication treatment integrates specialized barrier rings and paste formulations.
- Patient Education:Preoperative counseling and postoperative training programs determine long-term adherence and product satisfaction outcomes.
Post-surgical care absorbs the largest reimbursement allocation; chronic condition management is climbing the fastest as discharge acceleration continues.
End User:
Customer type fragmentation creates channel conflict between institutional procurement and direct-to-patient subscription models.
- Home Care:Discharged patients managing stomas independently drive demand for user-friendly appliances with simplified application. Australian and Canadian ostomy associations endorse specialized online retailers that aggregate manufacturer catalogs and provide video consultation fitting support for remote communities.
- Hospitals:Acute care facilities prioritize procurement efficiency through standardized appliance contracts and consolidated supplier relationships. North American hospital networks favor hydrocolloid-based barrier systems with established clinical evidence portfolios.
- Clinics:Outpatient wound-ostomy-continence centers provide specialized fitting and complication management.
- Long-Term Care Facilities:Nursing home populations with limited mobility require caregiver-friendly appliance systems with extended wear intervals.
Hospitals maintain the dominant volume position; home care is gaining share fastest as remote patient monitoring technologies mature.
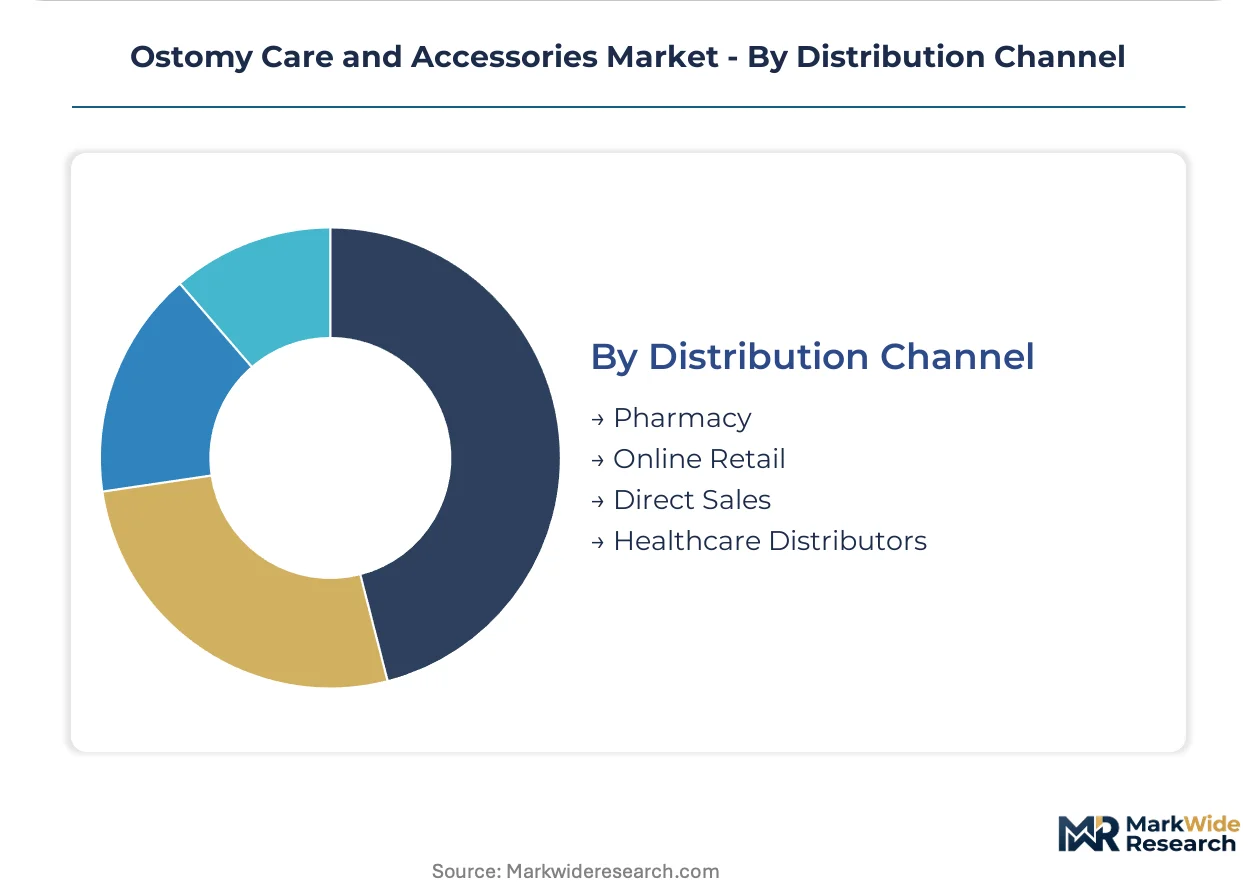
Distribution Channel:
Geography determines channel viability, with reimbursement infrastructure shaping whether patients access products through institutional procurement or direct purchase.
- Online Retail:Specialized platforms aggregate multiple manufacturer catalogs and offer personalized fitting support via video consultation. Channel compression in the United States and United Kingdom displaces traditional medical supply house relationships.
- Healthcare Distributors:Regional medical supply networks maintain hospital and long-term care contracts through field-based clinical support.
- Pharmacy:Community-based retail access serves patients with immediate replacement needs and prescription-integrated reimbursement.
- Direct Sales:Manufacturer subscription programs bypass purchasing committees and capture lifetime value through automated replenishment.
Healthcare distributors process the majority of institutional volume; online retail is expanding most quickly on patient-direct transactions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany exceeds that in India by substantial margins, reflecting divergent reimbursement infrastructure and patient cost sensitivity. This asymmetry shapes manufacturer portfolio allocation and margin expectations across priority markets.
United States
Hospital procurement consolidation and direct-to-patient subscription channels drive demand concentration. FDA Class II device controls govern premarket notification pathways for barrier adhesives and collection systems. Manufacturing clusters in the US Gulf Coast region supply specialized hydrocolloid and film substrates to domestic appliance producers.
Germany
Aging surgical populations and statutory health insurance guarantees sustain replacement frequency for skin barriers and pouches. EU Medical Device Regulation mandates clinical evidence and post-market surveillance for CE marking across member states. Industrial concentration in Baden-Württemberg and North Rhine-Westphalia supports advanced polymer processing capabilities for medical-grade adhesives.
Japan
PMDA fast-track pathways for breakthrough medical devices accelerate entry for novel odor-control technologies. METI standards enforcement shapes biocompatibility and sterilization compliance burdens for multinational exporters. Tokyo-Osaka medical device corridors host specialized distribution networks serving acute care and home care channels.
Netherlands
Post-surgical clinics deploy remote monitoring systems to reduce home health nursing visits and sustain patient autonomy. EMA-aligned regulatory frameworks facilitate cross-border product circulation within European markets. Eindhoven-region health technology clusters pioneer sensor-integrated ostomy appliances for predictive leak detection.
Australia
Ostomy associations endorse specialized online retailers to improve product access in rural and remote communities. TGA medical device standards align with international harmonization initiatives while maintaining local vigilance requirements. Sydney and Melbourne metropolitan areas concentrate wound-ostomy-continence nursing capacity and patient education infrastructure.
Ostomy Care and Accessories Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in adhesive chemistry and film substrates. The market exhibits moderate consolidation with three to five dominant participants controlling hospital formulary placement and direct-to-patient channels. Strategic archetypes span vertically integrated silicone adhesive producers, subscription-based direct fulfillment operators, and diversified medical device conglomerates with ostomy as a specialty division. Competitive moves concentrate on M&A for sensor technology capabilities and capacity expansion in radiation sterilization facilities to replace legacy ethylene oxide processes.
Within the integrated platform tier, Coloplast A/S and ConvaTec Group PLC exemplify divergent strategic postures. Coloplast anchors premium positioning through captive control of barrier film supply chains. ConvaTec occupies a position emphasizing recurring revenue capture via patient-direct subscription infrastructure. Hollister Incorporated represents the specialized manufacturer archetype with concentrated presence in North American and European hospital procurement channels.
| Leading Market Players |
|---|
| Coloplast A/S |
| ConvaTec Group PLC |
| Hollister Incorporated |
| B. Braun Melsungen AG |
| 3M Company |
| Welland Medical Limited |
| Smith & Nephew PLC |
| Salts Healthcare |
| Alcare Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Overcapacity in German medical-grade polymer production clusters is compressing raw material margins while simultaneously enabling tier-one manufacturers to extend payment terms and lock in multi-year adhesive supply contracts at favorable rates.
Pricing Analysis
The customization-premium spread between configured-to-order silicone barrier systems and standard hydrocolloid wafers spans approximately three-to-one in reimbursement-eligible markets, with Germany's statutory health insurance framework eliminating patient cost sensitivity entirely. Three-tier pricing structure across premium, standard, and economy levels stratifies primarily by wear-time claims and dermatitis prevention certification, with FDA 510(k) clearance tier commanding substantial brand premiums. Cost compression in emerging-market economy tiers is intensifying because low-cost adhesive tape substitutes capture price-sensitive segments where reimbursement infrastructure remains underdeveloped. Hospital procurement committees in North America exhibit lowest price sensitivity due to consolidated formulary contracts, while direct-to-patient subscribers in Australia and Canada demonstrate highest elasticity when video-consultation fitting support is unavailable.
Supply Chain Analysis
Export-control regimes limiting advanced sensor-component flows from Netherlands and Denmark health technology clusters are constraining smart ostomy appliance production scaling for manufacturers lacking in-house microelectronics capabilities. Geographic supply concentration centers on Germany for specialized hydrocolloid and silicone adhesive substrates, the United States for medical-grade polymer films, and Japan for odor-control barrier technologies. Raw material dependencies rest on petrochemical feedstocks, medical-grade silicone elastomers, and activated carbon filtration media. Single-source vulnerability in ethylene oxide sterilization capacity presents acute supply chain risk as radiation sterilization facility requalification extends product launch timelines. Distribution runs through healthcare distributors for institutional volume, with online retail platforms capturing fastest expansion in patient-direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in home care settings is accelerating as remote patient monitoring technologies reduce facility-based follow-up requirements and discharge protocols compress hospital procurement cycles.
For Market Incumbents: Entrench premium positioning through captive control of barrier film supply chains and backward integration into silicone adhesive chemistry to defend against commodity supplier encroachment. Accelerate radiation sterilization facility requalification to preempt legacy ethylene oxide regulatory restrictions. Lock in hospital formulary placement through standardized appliance kit contracts that reduce nursing time per patient encounter.
For New Entrants and Emerging Players: Establish a beachhead in Australia's rural and remote communities where ostomy association-endorsed online retailers aggregate manufacturer catalogs and video consultation fitting support remains underserved. Target chronic condition management applications in Netherlands and Denmark post-surgical clinics deploying remote monitoring systems. Pursue sensor-integrated appliance development partnerships with Eindhoven-region health technology clusters to bypass proprietary hydrocolloid formulation barriers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-based direct-to-patient operators with automated replenishment platforms that bypass hospital purchasing committees entirely. Long-term viability over the five-to-ten year horizon favors manufacturers with robust post-market surveillance infrastructure capable of satisfying EU Medical Device Regulation clinical evidence mandates. Acquisition target archetype: vertically integrated mid-cap specialists with captive silicone adhesive production and established CE marking portfolios. Signal to watch: reimbursement code crystallization for smartphone-connected wearables enabling proactive leak detection.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU Medical Device Regulation mandates clinical evidence and post-market surveillance for barrier adhesive approvals. |
| Hospital System Partnership | Consolidated formulary contracts with North American networks secure high-volume procurement for hydrocolloid systems. |
| Software Companion Development | Bluetooth-enabled moisture sensors integrated with smartphone applications reduce emergency department visit frequency. |
| Reimbursement Strategy | Germany's statutory health insurance guarantees eliminate patient cost barriers and sustain replacement frequency. |
| Backward Integration | Captive silicone adhesive production insulates margins from petrochemical feedstock volatility in German clusters. |
Research Approach
Cross-validation between primary interviews with wound-ostomy-continence nursing directors and secondary validation through hospital procurement database analysis anchors the qualitative findings in observable contract patterns. The study combines structured discussions with certified WOCN practitioners, biomedical engineers at integrated health networks, GPO contracts managers, and direct-to-patient platform operators with regulatory filing reviews, CMS Medicare reimbursement data, and EU notified body CE certificate registries. Bottom-up demand modeling from patient discharge protocols and top-down supply verification from medical-grade polymer production capacity triangulate market sizing across the analysis window.
Calibration against historical replacement frequency data and statutory insurance reimbursement banding adjustments ensures forecast consistency throughout the projection horizon. Segmentation dimensions modeled include product type, application setting, end-user channel, and regional regulatory cluster complexity. CAGRs were derived from trend extrapolation of home care discharge acceleration rates and sensor-component cost decline curves, with cross-reference to aging surgical population demographics and remote patient monitoring adoption trajectories.
Macroeconomic conditions sit as an overlay; deviation in petrochemical feedstock pricing or statutory health insurance reimbursement rates would shift the trajectory. Forecasts reflect assumptions regarding EU Medical Device Regulation enforcement stringency and FDA 510(k) pathway timeline stability. Material shifts in sterilization method validation requirements or breakthrough device fast-track eligibility would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Forensic Swabs Market
Medical Supplies
Europe Medical Gloves Market
Medical Supplies
Diagnostic Vials Market
Medical Supplies
Disposable Medical Supplies Market
Medical Supplies
Sperm Processing Media Market
Medical Supplies
Nucleic Acid Isolation and Purification Kits Market
Medical Supplies
Disposable Hospital Gowns Market
Medical Supplies
Venipuncture Needles and Syringes Market
Medical Supplies
Safety Lancet Market
Medical Supplies
Global Synthetic Absorbable Sutures Market
Medical Supplies
Enteral Syringes Market
Medical Supplies
Smart Face Masks Market
Medical Supplies
Slip Tip Syringe Market
Medical Supplies
North America Intravenous Solutions Market
Medical Supplies
Pressure Relief Mattress Market
Medical Supplies
Global IV Flush Syringe Market