
 Powder Fire Suppression System Market | 2026-2036
Powder Fire Suppression System Market Size, Share, and Industry Trends Forecast 2026-2036
Powder Fire Suppression System Market Analytics
Certified fire suppression technician shortages across industrialized economies is unwinding installation capacity and extending project backlogs. Johnson Controls leverages its building-automation integration to bundle powder systems with HVAC and access-control contracts. Amerex Corporation specializes in portable and wheeled dry chemical units for oilfield and marine environments. SIEX anchors European demand through its clean-agent manufacturing footprint in Spain and Italy.
Powder fire suppression systems deploy pressurized dry chemical agents—typically sodium bicarbonate or mono-ammonium phosphate—to interrupt combustion chain reactions via total flooding or local application. These systems achieve extinguishing concentrations within ten seconds and suit Class B and Class C hazards where water-based methods risk equipment damage or electrical conductivity. Dry chemical products dominate volume due to their cost position and compatibility with legacy infrastructure across manufacturing and transportation end users. Clean agent installations command premium positioning in aviation and data center applications where residue-free discharge protects sensitive electronics. The automatic installation category leads growth as facilities replace manual pull-stations with sensor-triggered networks tied to building management platforms.
NFPA standards in the United States, the EU F-Gas Regulation, and REACH chemical restrictions collectively shape agent formulations, cylinder testing intervals, and cross-border equipment certification requirements. The EPA's Significant New Alternatives Policy program continues evaluating fluorinated gas replacements, directly influencing R&D allocation among formulation suppliers. Stakeholders must monitor regulatory divergence between North American and European halocarbon phase-down schedules when planning multi-region product portfolios.
Market Dynamics
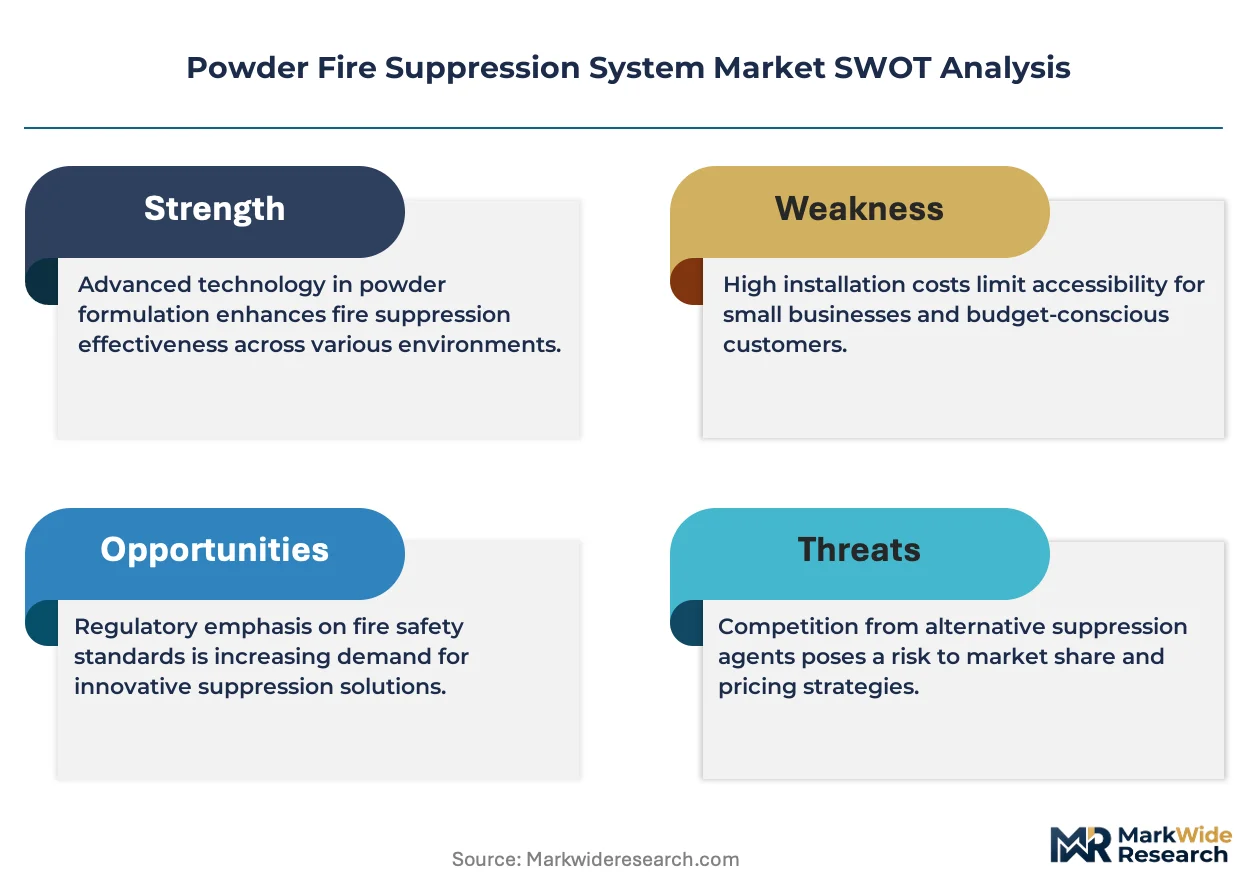
The EU F-Gas Regulation's halocarbon phase-down is forcing rapid agent reformulation across European manufacturing bases while certified technician shortages compress installation throughput in industrialized markets.
Growth Catalysts
- Data center infrastructure buildout:Hyperscale operators in the United States and Germany are specifying clean agent systems to protect server racks from electrical fire hazards without residue damage.
- REACH chemical restrictions:The European framework is accelerating substitution of legacy suppressants with fluorine-free dry chemical formulations in automotive paint booths and chemical processing plants.
- NFPA 10 and NFPA 17 standards:Updated testing intervals and cylinder recertification mandates in the United States are driving replacement cycles for aging fixed-installation networks in manufacturing facilities.
Market Restraints
- Specialized technician scarcity:Certified fire suppression installer shortages across Germany, the United States, and Japan are extending project backlogs and inflating labor costs for system commissioning.
- Raw material concentration:Mono-ammonium phosphate supply concentrates in Chinese chemical manufacturing clusters, exposing formulators to input cost volatility and trade friction.
- Water mist substitution:Advanced water mist systems are capturing share in marine and heritage building applications where residue concerns previously favored dry chemical solutions.
Strategic Opportunities
- India's industrial corridor expansion:The country's PLI scheme for manufacturing and chemical processing is creating first-time fixed-installation demand in Gujarat and Maharashtra states.
- Aviation MRO integration:Aircraft hangar operators are bundling clean agent suppression with building automation platforms to reduce insurance premiums and streamline inspection compliance.
- EPA SNAP program evolution:The Significant New Alternatives Policy's evaluation of fluorinated gas replacements is opening formulation pathways for domestic suppliers seeking to bypass import dependency.
Industry Challenges
- Cross-border certification complexity:Divergent cylinder testing protocols between UL standards in the United States and CE marking requirements in Europe force dual-track product development and inventory duplication.
- Legacy system integration:Facilities with 1980s-era halon infrastructure face expensive piping retrofit requirements when upgrading to modern dry chemical or clean agent networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Powder Fire Suppression System Market |
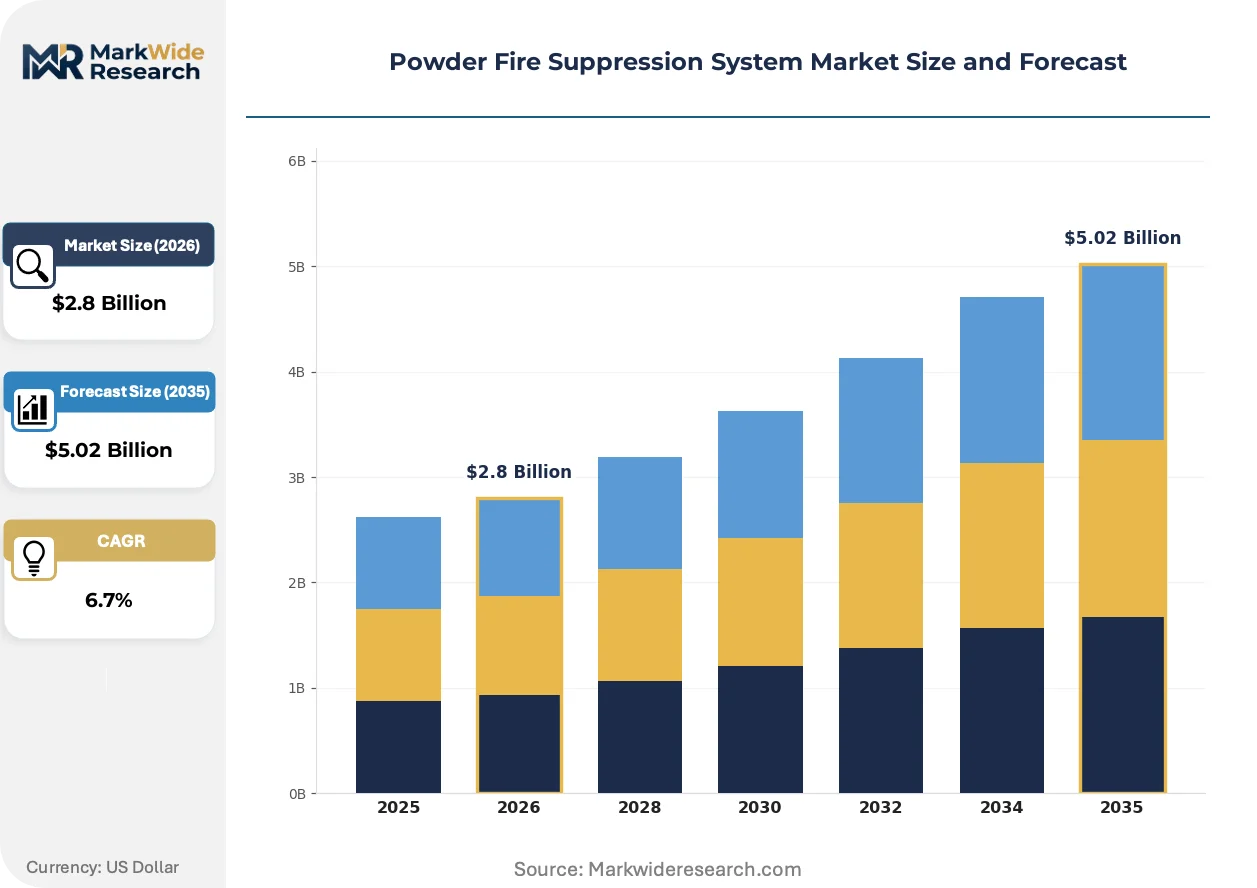
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Chemical, Wet Chemical, Clean Agent, Foam End User: Manufacturing, Transportation, Aviation, Marine Application: Industrial, Commercial, Residential, Oil & Gas Installation: Automatic, Manual, Portable, Fixed |
| Companies Covered | Reliable Fire & Security, Gielle Group, Johnson Controls, Buckeye Fire Equipment Company, Afex Fire Suppression Systems, Carrier, Koorsen Fire & Security, SIEX, Amerex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Powder Fire Suppression System Market Evolving Landscape
Agent formulation chemistry and detection sensor architecture are converging to enable faster discharge with reduced collateral damage to protected assets.
Micro-particle dry chemical technology is miniaturizing. Sodium bicarbonate and mono-ammonium phosphate agents now deploy at sub-10-micron particle sizes to achieve faster flame knockdown with reduced agent mass. Aviation ground support equipment manufacturers in France and Germany are adopting these formulations to meet strict weight limits on mobile extinguishing carts. The technology is miniaturizing portable unit design and enabling single-operator deployment in confined machinery spaces previously requiring wheeled systems.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are tightening discharge thresholds for fluorinated clean agents. Formulators in Italy and Spain are accelerating fluorine-free hydrofluoroolefin alternatives through ECHA pre-registration to secure market access before 2026 sunset dates. Data center operators in the Netherlands and Ireland are front-loading procurement of compliant systems to avoid stranded asset risk.
Buyer consolidation among facility management outsourcing firms is compressing specification authority. Integrated building services contractors in the United Kingdom and Australia are mandating unified suppression-HVAC-access control platforms from single-source vendors, displacing independent fire protection specialists. This concentration is most visible in commercial real estate portfolios where standardized equipment reduces spare parts inventory and technician training overhead across multi-site operations.
Powder Fire Suppression System Market Segmentation
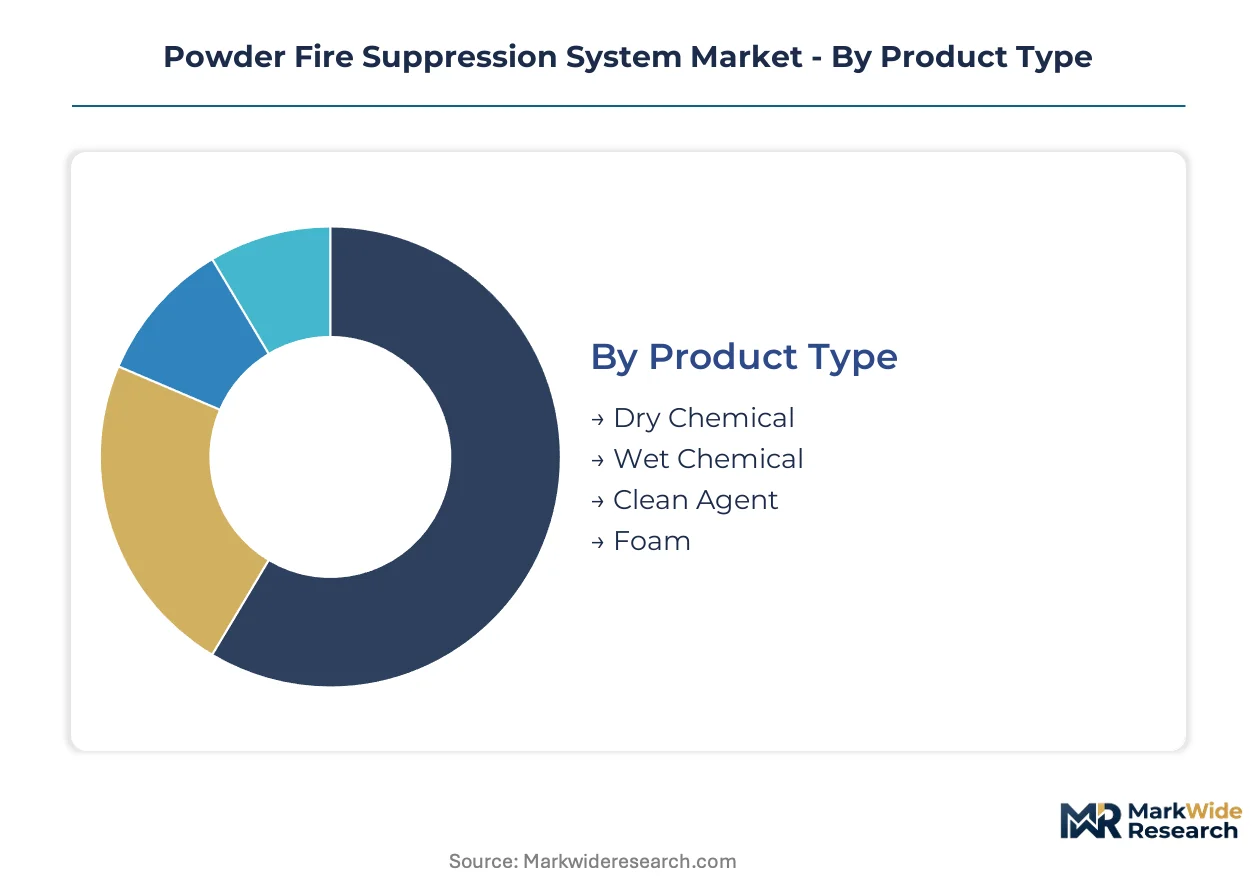
Powder fire suppression systems fragment across four distinct dimensions, each shaped by divergent regulatory thresholds and hazard-classification protocols. Understanding these segment boundaries clarifies why dry chemical formulations dominate manufacturing procurement while clean agents command aviation and data center premiums.
Product Type:
REACH Annex XVII and the EU F-Gas Regulation impose divergent chemical restrictions across European manufacturing bases, forcing formulators to maintain parallel agent portfolios for cross-border compliance.
- Dry Chemical:Sodium bicarbonate and mono-ammonium phosphate formulations interrupt combustion through radical scavenging at sub-10-micron particle sizes. Demand concentrates in Germany's automotive paint booths and chemical processing corridors, where REACH chemical restrictions accelerate substitution of legacy suppressants.
- Clean Agent:Fluorine-free hydrofluoroolefin alternatives discharge without residue, protecting server racks and avionics from electrical fire hazards. Data center operators in the Netherlands and Ireland front-load procurement to avoid stranded asset risk before ECHA pre-registration deadlines.
- Wet Chemical:Potassium carbonate-based solutions target Class K cooking oil fires in commercial kitchen installations.
- Foam:Aqueous film-forming concentrates seal flammable liquid surfaces in petroleum storage terminals.
Established volume favors dry chemical; emerging adoption favors clean agent.
End User:
Customer procurement authority varies sharply by sector, with manufacturing buyers prioritizing cost-per-unit-extinguished-capacity and aviation operators mandating residue-free performance regardless of price tier.
- Manufacturing:Automotive and chemical clusters in Germany's industrial corridor require upgraded fixed-installation networks. NFPA 17 standards drive replacement cycles for aging systems in United States facilities.
- Transportation:Rail and logistics operators specify portable and wheeled units for mobile hazard response. India's PLI scheme for manufacturing creates first-time fixed-installation demand in Gujarat and Maharashtra states.
- Aviation:Aircraft hangar operators bundle clean agent suppression with building automation platforms to reduce insurance premiums.
- Marine:Advanced water mist systems capture share in heritage vessel applications where residue concerns previously favored dry chemical solutions.
Manufacturing absorbs the largest absolute volume; aviation delivers the steepest expansion trajectory.
Application:
Hazard classification density determines system specification complexity, with oil and gas environments requiring explosion-proof enclosures absent in standard commercial deployments.
- Industrial:Heavy manufacturing and processing plants deploy total flooding networks for Class B and Class C hazards where water-based methods risk equipment damage.
- Commercial:Integrated building services contractors in the United Kingdom mandate unified suppression-HVAC-access control platforms from single-source vendors.
- Residential:Multi-family developments specify compact automatic units for electrical panel protection.
- Oil & Gas:Offshore platforms and refineries demand corrosion-resistant fixed installations with remote monitoring capabilities.
Industrial installations retain the deepest retrofit backlog; oil and gas commands the highest specification premiums.
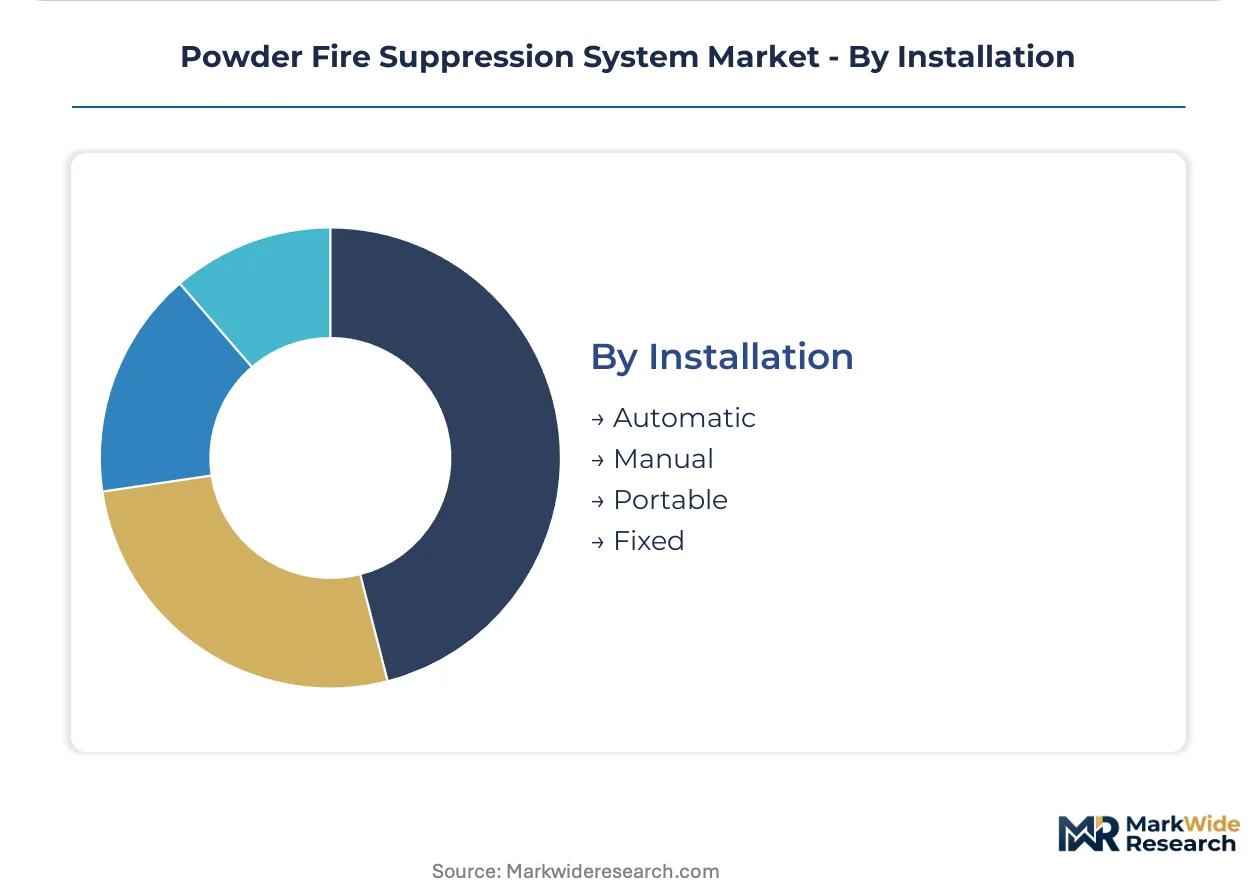
Installation:
Sensor-triggered networks are displacing manual pull-stations as facilities integrate fire suppression with building management platforms, though technician scarcity constrains commissioning velocity.
- Automatic:Sensor-triggered discharge achieves extinguishing concentrations within ten seconds. Hyperscale data center operators in the United States and Germany specify these systems to protect high-value server infrastructure.
- Manual:Pull-station activation persists in legacy manufacturing facilities facing expensive piping retrofit requirements when upgrading to modern networks.
- Portable:Single-operator units serve confined machinery spaces previously requiring wheeled systems. Aviation ground support equipment manufacturers in France adopt micro-particle formulations to meet strict weight limits.
- Fixed:Permanent piping networks dominate automotive and chemical manufacturing clusters requiring continuous hazard coverage.
Automatic installations gain share fastest; manual systems face accelerated replacement pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA's Significant New Alternatives Policy shapes North American procurement patterns while ECHA pre-registration deadlines compress European purchasing timelines. India's PLI scheme for manufacturing and chemical processing unlocks first-time fixed-installation demand across Gujarat and Maharashtra. Japan's METI efficiency mandates accelerate automatic system retrofits in aging industrial corridors.
United States
Hyperscale data center operators in Virginia and Oregon specify clean agent systems to protect server infrastructure from electrical fire hazards. NFPA 10 and NFPA 17 standards drive replacement cycles for aging fixed-installation networks across Midwest manufacturing facilities. Johnson Controls leverages building-automation integration to bundle powder systems with HVAC contracts in commercial real estate portfolios.
Germany
Automotive and chemical manufacturing clusters in Baden-Württemberg and North Rhine-Westphalia require upgraded fixed-installation networks under REACH chemical restrictions. The EU F-Gas Regulation accelerates substitution of halon-based suppressants with fluorine-free alternatives across paint booths and processing plants. Certified technician shortages in Bavaria extend project backlogs and inflate labor costs for system commissioning.
China
Mono-ammonium phosphate supply concentrates in chemical manufacturing clusters, exposing formulators to input cost volatility and trade friction. GB standards and MIIT industrial safety mandates drive automatic system adoption in steel and petrochemical corridors. Yangtze River Delta facilities replace manual pull-stations with sensor-triggered networks tied to building management platforms.
India
The PLI scheme for manufacturing creates first-time fixed-installation demand in Gujarat's industrial corridor and Maharashtra's chemical processing zones. BIS certification requirements and CEA electrical safety codes shape agent formulation specifications for domestic suppliers. Rail and logistics operators in Haryana specify portable and wheeled units for mobile hazard response across freight terminals.
Japan
METI energy efficiency mandates accelerate automatic system retrofits in Chubu and Kansai manufacturing belts facing aging infrastructure challenges. JIS standards govern cylinder testing intervals and cross-border equipment certification requirements for imported suppressants. Aviation ground support equipment manufacturers adopt micro-particle formulations to meet strict weight limits on mobile extinguishing carts.
Powder Fire Suppression System Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the powder fire suppression system market. The upper tier commands specification authority through bundled building-automation contracts, while mid-cap specialists dominate portable and wheeled unit fabrication for oilfield and marine environments. Three archetypes define competitive positioning: integrated building-systems providers, clean-agent formulation specialists, and portable-equipment fabricators. M&A activity concentrates on regional fire-protection distributors, while technology licensing agreements accelerate fluorine-free agent development.
Among integrated building-systems providers, Johnson Controls anchors the premium tier through HVAC-access-control bundling, while Carrier occupies a comparable position in commercial real estate portfolios. SIEX exemplifies the clean-agent specialist archetype with European manufacturing footprints in Spain and Italy. Amerex Corporation represents the portable-equipment fabricator tier, serving oilfield and marine hazard applications. Buckeye Fire Equipment Company and Koorsen Fire & Security sit within the regional distributor-specialist segment, capturing retrofit demand across Midwest industrial corridors. Afex Fire Suppression Systems and Gielle Group anchor niche positions in aviation and heritage building applications respectively.
| Leading Market Players |
|---|
| Reliable Fire & Security |
| Gielle Group |
| Johnson Controls |
| Buckeye Fire Equipment Company |
| Afex Fire Suppression Systems |
| Carrier |
| Koorsen Fire & Security |
| SIEX |
| Amerex Corporation |
| Others |
Value Network & Pricing Analysis
REACH Annex XVII and the EU F-Gas Regulation simultaneously gate supplier qualification and stratify price tiers, forcing formulators to maintain parallel agent portfolios that fragment procurement economics across European manufacturing bases. Buyers in Germany's automotive corridor face 15-25% price spreads between fluorine-compliant clean agents and legacy dry chemical formulations, with certification-grade premiums widening as ECHA deadlines compress.
Pricing Analysis
Clean agent systems in the Netherlands and Ireland command 40-60% premiums over dry chemical equivalents, driven by residue-free performance requirements in data center applications and aviation MRO facilities. Three-tier pricing structure across premium, standard, and economy levels separates UL-certified automatic installations from CE-marked manual systems and unbranded portable units. Cost compression in the standard tier is intensifying because Chinese mono-ammonium phosphate suppliers are passing through input volatility. Manufacturing buyers in India's Gujarat corridor exhibit the highest price sensitivity, while aviation operators in Japan's Chubu belt prioritize performance over unit economics.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane are inflating inbound logistics costs for European formulators sourcing sodium bicarbonate precursors. Mono-ammonium phosphate supply concentrates in China's Yangtze River Delta chemical clusters, with secondary production anchored in South Korea and Japan. Raw material dependencies span phosphate rock from Morocco, fluorinated gas feedstocks from the US Gulf Coast, and specialized cylinder alloys from German steel mills. Single-source vulnerability in Chinese phosphate processing exposes formulators to export license disruptions. Distribution runs through regional fire protection distributors in the US Midwest and integrated building services contractors in the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The powder fire suppression system market sits in early-cycle expansion as data center infrastructure buildouts and REACH-driven agent reformulation create first-time specification opportunities across three continents. Clean agent penetration in hyperscale facilities remains below 35%, leaving substantial runway for fluorine-free alternatives.
For Market Incumbents: Fortify specification authority by embedding powder systems within unified building-automation platforms, countering the threat of independent fire protection specialists displaced by integrated services contractors. Prioritize backward integration into cylinder manufacturing in Germany's industrial corridor to offset certified technician scarcity and compress commissioning timelines.
For New Entrants and Emerging Players: After-sales service gaps in legacy system retrofitting present immediate white-space opportunities, particularly in US Midwest manufacturing facilities facing NFPA 17 recertification mandates. India's Maharashtra chemical processing zones offer the most penetrable geography given PLI-scheme-driven first-time demand. Pursue technician-training partnerships with regional distributors as the primary go-to-market angle.
For Investors and Strategic Acquirers: The EPA SNAP program's fluorinated gas evaluation reshapes the acquisition landscape by privileging domestic suppliers with formulation pathways bypassing import dependency. Long-term viability hinges on 5-10 year regulatory compliance positioning rather than commodity volume capture. Target clean-agent specialists with ECHA pre-registered fluorine-free portfolios. Watch for stranded asset risk realization in Netherlands data centers as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Agent Formulation | ECHA pre-registration secures market access before REACH sunset deadlines in European manufacturing corridors. |
| Building Automation Integration | Johnson Controls and Carrier bundle suppression with HVAC to displace independent specialists in commercial real estate. |
| Micro-Particle Technology Licensing | Aviation ground support manufacturers in France adopt sub-10-micron formulations to meet strict weight limits. |
| Regional Distributor Acquisition | Buckeye Fire Equipment captures retrofit demand across Midwest industrial corridors facing NFPA recertification. |
| Technician Training Program Expansion | German automotive clusters address certified installer shortages extending project backlogs in Bavaria. |
Research Methodology
A spread of perspectives from fire suppression system manufacturers, certified installation contractors, data center facility managers, and chemical formulators converged on the working assumptions underlying volume and value estimates. Primary fieldwork encompassed structured interviews with plant engineers at automotive paint booths, procurement leads at hyperscale operators, and aftermarket service heads at regional distributors. Secondary validation drew from EPA SNAP program filings, ECHA pre-registration databases, NFPA standard revision records, and customs data tracking mono-ammonium phosphate trade flows. Bottom-up unit economics triangulated against top-down sectoral spending patterns to anchor projection credibility.
Segmentation dimensions modeled span product type, end user vertical, application environment, and installation modality across the projection horizon. The analytical framework disaggregated dry chemical, clean agent, wet chemical, and foam formulations by manufacturing, transportation, aviation, and marine demand clusters. CAGRs were derived from agent substitution elasticity estimates, regulatory phase-down schedules, and infrastructure investment pipelines. Industry-specific forecast inputs included data center capex disclosures from Virginia and Oregon operators, plus PLI scheme implementation timelines from India's Gujarat and Maharashtra states.
Material uncertainties — technician certification bottlenecks, phosphate export license disruptions, and divergent UL-CE testing protocol harmonization — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and trade lane stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Fire Hose Market
Fire Safety & Protection
Fire Resistant Glass Market
Fire Safety & Protection
Fire Extinguisher Inspection Services Market
Fire Safety & Protection
Earthing Lightning Protection System Market
Fire Safety & Protection
Fire Protection Valves and Fittings Market
Fire Safety & Protection
Wireless Fire Detection Systems Market
Fire Safety & Protection
Fire Protection Systems Market
Fire Safety & Protection
China Thermal Protector Market
Fire Safety & Protection
Heptafluoropropane Fire Suppression System Market
Fire Safety & Protection
Africa Fire Suppression Market
Fire Safety & Protection
Fire Protection Coating Market
Fire Safety & Protection
Fire Safety Systems Market
Fire Safety & Protection
Flame Barrier Market
Fire Safety & Protection
Commercial Smoke Alarm Market
Fire Safety & Protection
Global Fire Control System Market
Fire Safety & Protection
Australia Emergency Lighting Market