
 Africa Fire Suppression Market | 2026-2036
Africa Fire Suppression Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Fire Suppression Market Analysis
Certified fire systems engineering talent is unwinding across North and West Africa as training institutes in Lagos, Casablanca, and Cairo expand technician pipelines. ZimFire Solutions leverages its Harare manufacturing base to anchor distribution across Southern African mining belts. Morocco Fire Solutions S.A. competes through specialized foam system production serving Mediterranean port facilities. SavChem International Ltd. dominates chemical suppressant supply into Nigeria's oil storage terminals.
Fire suppression encompasses engineered systems designed to detect, control, or extinguish combustion events through automated discharge of water, chemical agents, foam, or inert gas, typically maintaining response activation thresholds between 57°C and 74°C for thermal detectors and 0.05–0.15 optical density for smoke sensors. These installations protect personnel, structural assets, and operational continuity in environments where uncontrolled fire would cause catastrophic loss. Water-based systems sustain the largest installed base across African commercial real estate due to lower capital cost and maintenance burden. Chemical suppressants occupy the fastest-expanding margin pool as data centers and telecom switching facilities adopt clean-agent halocarbon alternatives to water-damaging infrastructure. Foam systems lead in petrochemical and aviation fuel storage applications where hydrocarbon pool fires demand blanket suppression.
South Africa's National Regulator for Compulsory Specifications enforces SANS 10139 fire detection standards while Egypt's Housing and Building National Research Center updates high-rise suppression mandates under revised building codes. Nigeria's Federal Fire Service coordinates with the Standards Organisation of Nigeria to align port and petroleum storage installations with NFPA-referenced active protection protocols. Stakeholders must monitor how pending regional harmonization of suppression certification affects cross-border equipment procurement and service licensing.
Market Dynamics
Underground mining depths across Southern Africa now exceed 4,000 meters, forcing extraction operators to abandon water-based suppression for chemical clean-agent alternatives that protect electrified hoisting infrastructure. This operational pivot is compressing equipment replacement cycles and rewiring procurement specifications across the continent's mineral belts.
Growth Catalysts
- High-rise mandates:South Africa's National Building Regulations now require active suppression in commercial towers above 21 meters, forcing retrofit installations across Johannesburg and Cape Town CBDs.
- Port infrastructure:Nigeria's Federal Fire Service is aligning petroleum storage terminals with NFPA-referenced protocols, mandating foam blanket systems for hydrocarbon pool fire risks.
- Clean-agent chemistry:Data centers and telecom switching facilities are adopting halocarbon alternatives that eliminate water damage to server racks and fiber optic backbones.
Market Restraints
- Steel and copper volatility:Sprinkler fabrication depends on copper alloy components whose price swings compress margin visibility for installation contractors.
- Import concentration:Egypt, Nigeria, and Morocco source over 80 percent of detection sensor hardware from East Asian contract manufacturers, exposing procurement to shipping lane disruptions.
- Technical ceiling:Current thermal detectors maintain 57°C to 74°C activation thresholds that lag behind lithium-ion thermal runaway signatures in battery storage facilities.
Strategic Opportunities
- East African corridor:Kenya's Mombasa-Nairobi industrial belt lacks certified installation capacity for chemical suppressant systems, creating first-mover positioning for trained engineering teams.
- Aviation fuel storage:Ethiopia's expanding Addis Ababa airport logistics zone requires ARFF-grade foam systems that continental suppliers currently underserve.
- Regional certification harmonization:Pending alignment of SABS, SON, and Egyptian building codes would streamline cross-border equipment procurement and service licensing.
Industry Challenges
- Certified technician scarcity:Lagos, Casablanca, and Cairo training institutes graduate fewer than 400 suppression systems engineers annually against mining and petrochemical demand.
- Legacy integration friction:Johannesburg and Durban commercial towers built under 1990s codes require structural core modifications to accommodate modern sprinkler riser pressures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Fire Suppression Market |
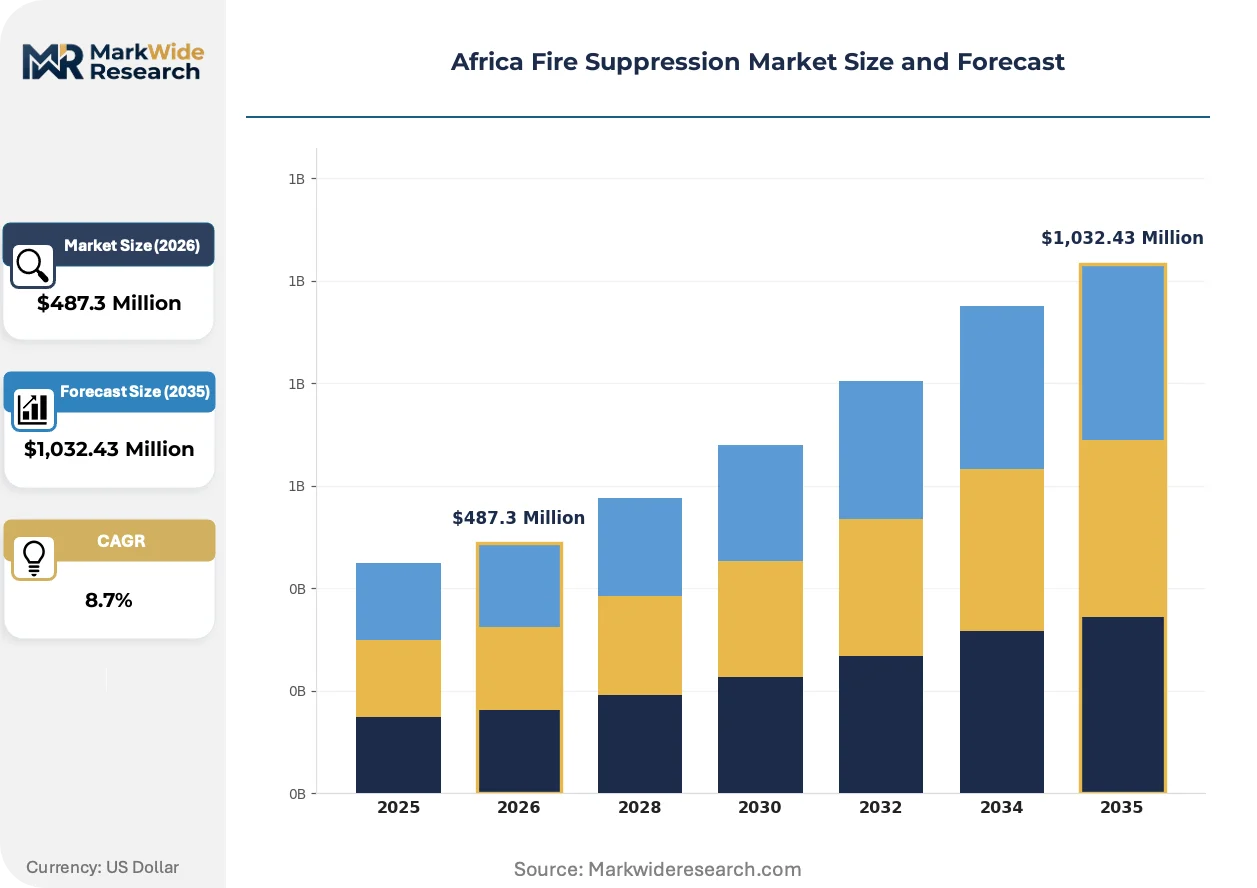
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based Systems, Chemical Suppressants, Foam Systems, Dry Powder Systems End User: Manufacturing Facilities, Commercial Buildings, Residential Properties, Transportation Technology: Active Fire Protection, Passive Fire Protection, Integrated Systems, Manual Systems Application: Industrial Safety, Building Safety, Vehicle Safety, Marine Safety |
| Companies Covered | ZimFire Solutions Pvt Ltd., Morocco Fire Solutions S.A., SavChem International Ltd., Senegal FireTech Group, FireSafety Angola Plc, FireChem™ Kenya Ltd., Egypt Flame Control Co., Advanced Fire Global, FlameGuard Limited, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Fire Suppression Market Emerging Trajectories
Detection and suppression architectures are converging around addressable loop technology that pinpoints ignition coordinates before discharge, compressing response latency from minutes to seconds. This shift is redrawing equipment specifications and maintenance contract structures across African industrial and commercial installations.
Addressable fire detection loops with individual device identification are displacing conventional zoned wiring in Nigerian petrochemical terminals and South African mining headgear. Extraction operators at platinum and gold belts below 3,500 meters now specify looped architectures that isolate fault segments without system-wide shutdown. The technology is displacing maintenance models built on quarterly physical inspection rounds, substituting continuous digital monitoring with predictive replacement scheduling.
South Africa's National Regulator for Compulsory Specifications is tightening SANS 10139 enforcement for high-occupancy commercial towers, mandating redundant detection pathways and documented commissioning protocols. The regulation is compressing project timelines for Johannesburg developers who must now engage certified fire engineering consultants prior to municipal occupancy approval. Egypt's Housing and Building National Research Center is observing this enforcement pattern as it drafts revised suppression mandates for Cairo's new administrative capital high-rises.
After-sales service contracts are unbundling from initial equipment supply as Lagos and Nairobi facility managers demand standalone maintenance agreements with guaranteed response time clauses. Mining houses in Zambia and DRC are negotiating performance-based arrangements where contractor penalties attach to system downtime duration rather than parts replacement frequency. This shift is most visible in copper belt operations where production continuity losses dwarf equipment capital costs.
Africa Fire Suppression Market Segmentation
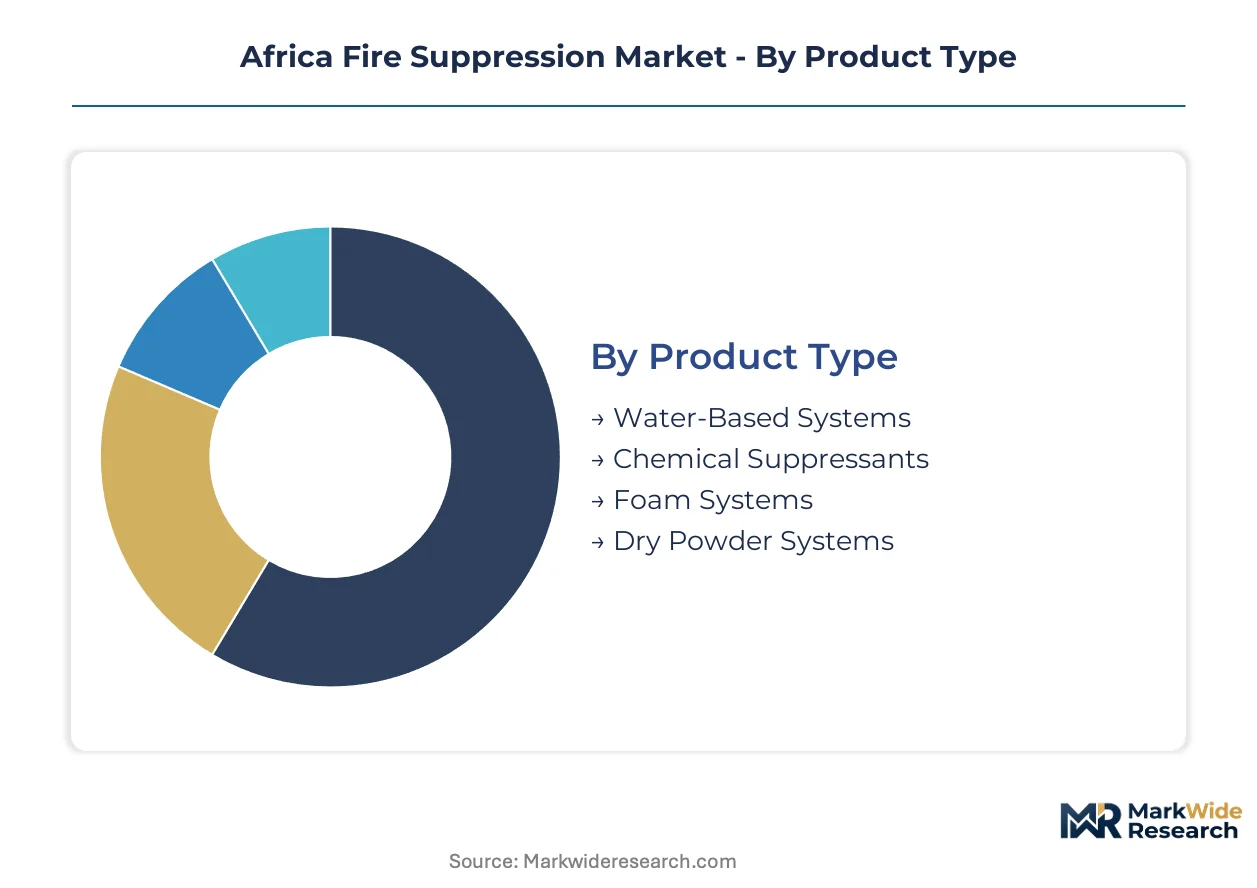
Fire suppression procurement across Africa fragments along operational risk profiles rather than simple asset categories. Mining houses, petrochemical terminals, and high-rise developers each demand engineered configurations that match ignition chemistry, response speed requirements, and maintenance infrastructure availability.
Product Type:
Margin pools concentrate in chemical clean-agent formulations where halocarbon chemistry commands premium positioning against commoditized water infrastructure.
- Water-Based Systems:Sprinkler and deluge configurations utilizing wet, dry, or pre-action pipe networks dominate installed base across South African commercial towers and Nigerian retail complexes. Johannesburg retrofit mandates are accelerating replacement of 1990s-era steel risers with pressure-rated copper alloy components. Water systems hold installed capacity. Chemical suppressants are rotating up the share rankings.
- Chemical Suppressants:Clean-agent halocarbon and inert gas systems discharge without residue, protecting electrified hoisting gear in platinum belts below 4,000 meters and server racks in Lagos data centers. Extraction operators at depth are abandoning water suppression to protect electrified infrastructure from conductive damage. Chemical suppressants hold installed capacity. Foam systems are rotating up the share rankings.
- Foam Systems:Aqueous film-forming foam blankets hydrocarbon pool fires at Nigeria's petroleum storage terminals and aviation fuel depots.
- Dry Powder Systems:ABC and BC powder cartridges serve mobile applications and localized metal fire risks in mining maintenance bays.
Foam systems hold installed capacity. Dry powder systems are rotating up the share rankings.
End User:
Volume concentrates in manufacturing and commercial verticals where regulatory enforcement has hardened, while residential penetration remains constrained by informal construction patterns.
- Manufacturing Facilities:Mining headgear, mineral processing plants, and petrochemical refineries specify addressable loop detection with zoned suppression discharge. Zambia's copper belt operations are negotiating performance-based maintenance contracts where contractor penalties attach to system downtime duration. Manufacturing facilities hold installed capacity. Commercial buildings are rotating up the share rankings.
- Commercial Buildings:High-rise towers above 21 meters in Johannesburg and Cape Town face retrofit mandates under tightened SANS 10139 enforcement. Developers must engage certified fire engineering consultants prior to municipal occupancy approval, compressing project timelines. Commercial buildings hold installed capacity. Residential properties are rotating up the share rankings.
- Residential Properties:Formal housing estates in Nairobi and Lagos satellite towns are adopting basic sprinkler coverage as mortgage insurers impose protection riders.
- Transportation:Rail yards, bus terminals, and port logistics clusters require specialized detection for hydrocarbon and electrical fire risks.
Residential properties hold installed capacity. Transportation is rotating up the share rankings.
Technology:
Adoption velocity splits between automated response architectures in high-value assets and manual standby systems where technical infrastructure remains underdeveloped.
- Active Fire Protection:Automated detection and suppression discharge systems with thermal thresholds between 57°C and 74°C protect platinum extraction operations below 3,500 meters. Addressable loop technology isolates fault segments without system-wide shutdown, displacing quarterly physical inspection rounds. Active fire protection holds installed capacity. Integrated systems are rotating up the share rankings.
- Passive Fire Protection:Compartmentation, intumescent coatings, and fire-rated structural elements contain combustion spread in Cairo's new administrative capital high-rises. Egypt's Housing and Building National Research Center is observing South African enforcement patterns as it drafts revised suppression mandates. Passive fire protection holds installed capacity. Integrated systems are rotating up the share rankings.
- Integrated Systems:Converged detection, suppression, and building management architectures enable continuous digital monitoring with predictive replacement scheduling.
- Manual Systems:Hand-operated extinguishers and hose reel installations serve secondary coverage and emergency backup roles.
Manual systems hold installed capacity. Integrated systems are rotating up the share rankings.
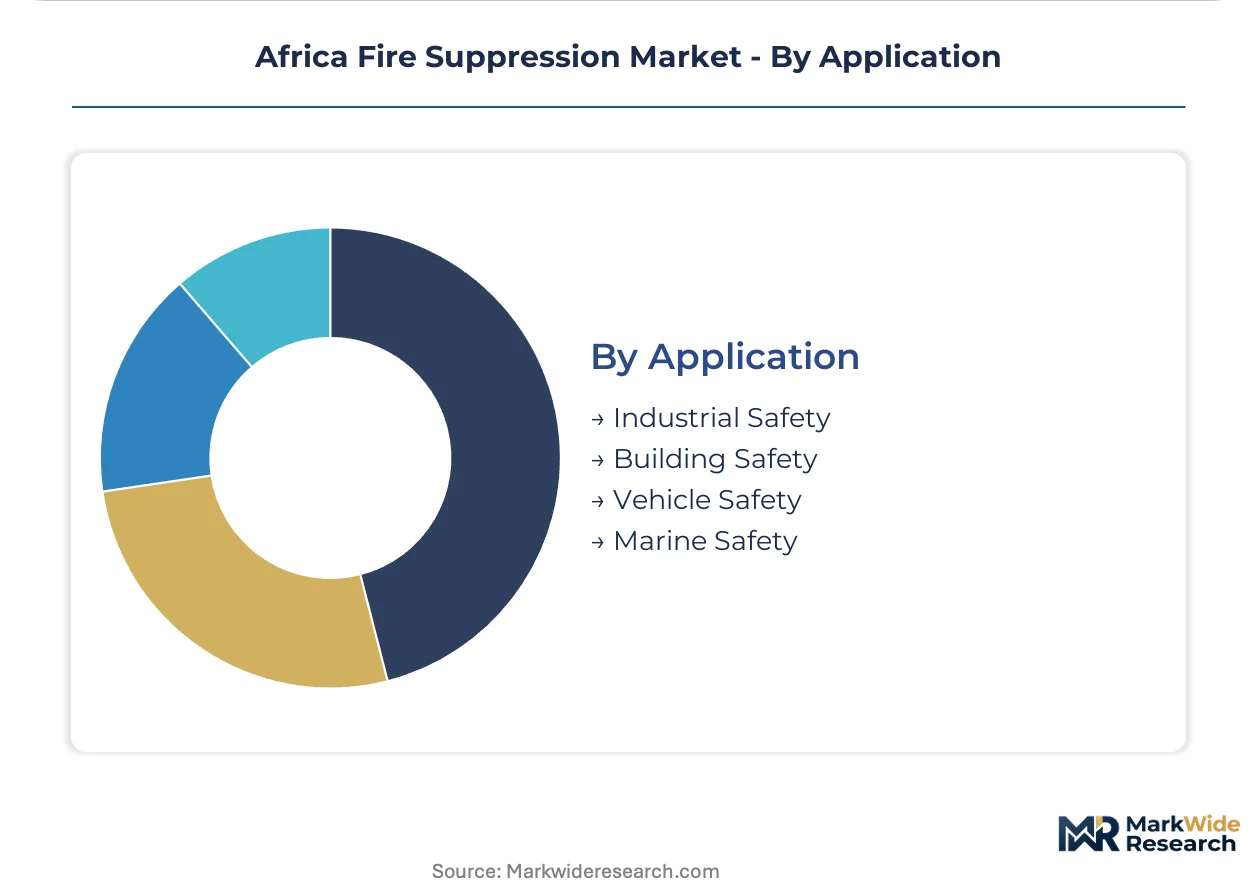
Application:
Demand intensity tracks capital stock vulnerability, with industrial safety commanding engineering resources and marine safety remaining undersupplied.
- Industrial Safety:Mining, petrochemical, and manufacturing installations specify redundant detection pathways and documented commissioning protocols under tightening enforcement. Nigeria's Federal Fire Service alignment with NFPA-referenced protocols is mandating foam blanket systems for hydrocarbon pool fire risks. Industrial safety holds installed capacity. Building safety is rotating up the share rankings.
- Building Safety:High-occupancy commercial towers require redundant detection pathways under South Africa's National Regulator for Compulsory Specifications. After-sales service contracts are unbundling from initial equipment supply as facility managers demand standalone maintenance agreements with guaranteed response time clauses. Building safety holds installed capacity. Vehicle safety is rotating up the share rankings.
- Vehicle Safety:On-board suppression protects heavy mining equipment and public transit fleets from hydraulic fluid and electrical ignition.
- Marine Safety:Port vessel protection and offshore platform systems remain dependent on international supplier networks with limited local service capacity.
Marine safety holds installed capacity. Vehicle safety is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa commands premium pricing for certified fire engineering services while Nigerian procurement runs on compressed margins driven by import dependency. This asymmetry shapes cross-border equipment flows and technician migration patterns across the continent.
South Africa
Johannesburg and Cape Town CBDs face retrofit mandates for commercial towers above 21 meters under tightened SANS 10139 enforcement. The National Regulator for Compulsory Specifications mandates redundant detection pathways and documented commissioning protocols. Mining headgear at platinum belts below 3,500 meters now specifies addressable loop architectures that isolate fault segments without system-wide shutdown.
Nigeria
Lagos-Ibadan industrial corridor drives demand for chemical suppressant systems at petrochemical storage and port logistics clusters. The Federal Fire Service coordinates with the Standards Organisation of Nigeria to align petroleum terminals with NFPA-referenced active protection protocols. SavChem International Ltd. anchors chemical suppressant supply into oil storage terminals at Apapa and Onne ports.
Egypt
Cairo's new administrative capital high-rises require revised suppression mandates as the Housing and Building National Research Center observes South African enforcement patterns. Passive fire protection through compartmentation and intumescent coatings contains combustion spread in commercial towers. Egypt Flame Control Co. represents local fabrication capacity serving Nile Delta manufacturing zones.
Morocco
Mediterranean port facilities at Casablanca and Tangier-Med drive specialized foam system production for hydrocarbon pool fire risks. Morocco Fire Solutions S.A. competes through concentrated foam manufacturing serving North African maritime logistics. The country's training institutes expand technician pipelines alongside port infrastructure upgrades.
Kenya
Mombasa-Nairobi industrial belt lacks certified installation capacity for chemical suppressant systems, creating positioning opportunities for trained engineering teams. FireChem Kenya Ltd. represents local distribution presence as data center and telecom switching facilities adopt halocarbon alternatives. Mortgage insurers impose protection riders on formal housing estates in satellite towns.
Africa Fire Suppression Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the African fire suppression landscape. The market structures around three tiers: multinational system integrators with NFPA-aligned certification, regional fabricators with SABS or SON accreditation, and local installation contractors competing on response speed. Two dominant competitive moves are reshaping positioning: backward integration into chemical agent formulation by regional specialists, and geographic expansion through trained technician deployment into underserviced corridors like the East African belt.
Within the regional specialist tier, ZimFire Solutions and Morocco Fire Solutions exemplify divergent geographic anchoring strategies. ZimFire leverages its Harare manufacturing base to distribute across Southern African mining belts, while Morocco Fire Solutions concentrates foam production capacity for Mediterranean port facilities. SavChem International occupies a position as a chemical suppressant supplier focused on Nigeria's petroleum infrastructure. These three players represent the archetype of regional scale with specialized formulation capabilities rather than broad system integration.
| Leading Market Players |
|---|
| ZimFire Solutions Pvt Ltd. |
| Morocco Fire Solutions S.A. |
| SavChem International Ltd. |
| Senegal FireTech Group |
| FireSafety Angola Plc |
| FireChem™ Kenya Ltd. |
| Egypt Flame Control Co. |
| Advanced Fire Global |
| FlameGuard Limited |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for copper alloy sprinkler components compress margin visibility for Johannesburg installation contractors while reinforcing pricing power among chemical agent formulators with captive synthesis capacity. This lead-time asymmetry between water-based infrastructure and clean-agent chemistry is segmenting procurement strategies across African mining and data center verticals.
Pricing Analysis
Configured-to-order pricing for addressable loop detection systems commands a forty-percent premium over standard zoned wiring configurations in South African commercial retrofits. Three-tier pricing structure across premium, standard, and economy levels stratifies by SANS 10139 certification grade and after-sales service bundling. Cost compression in water-based sprinkler tiers is intensifying because Egyptian and Nigerian contractors compete on copper alloy sourcing efficiency. Mining houses demonstrate the lowest price sensitivity, absorbing premium chemical suppressant costs to protect electrified hoisting infrastructure, while residential developers in Nairobi satellite towns resist sprinkler mandates until mortgage insurers impose protection riders.
Supply Chain Analysis
Strait of Malacca transit chokepoints expose Egyptian and Nigerian procurement to detection sensor hardware delays, as over eighty percent of thermal and smoke sensor assemblies originate from East Asian contract manufacturers. Supply concentration in China, South Korea, and Taiwan for semiconductor-dependent addressable loop controllers creates single-source vulnerability for South African mining headgear upgrades. Copper alloy riser fabrication draws from Zambian and Chilean concentrate, with price volatility feeding through to Johannesburg retrofit margins. Distribution runs through certified fire engineering consultancies that control municipal occupancy approval pathways in Lagos, Casablanca, and Cairo.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Standalone maintenance agreements with guaranteed response time clauses are expanding faster than hardware supply across Lagos and Nairobi facility management markets, reframing competitive positioning around service-attach revenue rather than equipment margin alone.
For Market Incumbents: Compound technician certification capacity through Lagos, Casablanca, and Cairo training institute partnerships to defend against emerging regional specialists with backward integration into chemical agent formulation. Anchor SANS 10139 and NFPA-aligned certification credentials to maintain municipal approval gatekeeper status as Egypt's Housing and Building National Research Center drafts revised suppression mandates. For New Entrants and Emerging Players: Lead with certified installation capacity deployment into Kenya's Mombasa-Nairobi industrial belt, where chemical suppressant system demand from data centers and telecom facilities outstrips qualified engineering supply. Target performance-based maintenance contracts with copper belt mining houses in Zambia and DRC, where production continuity losses dwarf equipment capital costs and contractor penalties attach to system downtime duration. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational industrial conglomerates with dormant fire protection divisions lacking Africa-specific certification footprints. Long-term viability hinges on regulatory harmonization execution across SABS, SON, and Egyptian building codes. Watch for alignment momentum on cross-border equipment procurement standards as the inflection signal for scalable platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Pipeline Expansion | Lagos and Cairo training institute graduates address mining and petrochemical demand exceeding four hundred engineers annually. |
| Backward Integration into Chemical Agent Formulation | Regional specialists capture margin pools in halocarbon clean-agent supply for platinum belt operations below four thousand meters. |
| Performance-Based Maintenance Contract Structuring | Zambian copper belt operators tie contractor penalties to system downtime duration rather than parts replacement frequency. |
| Addressable Loop Technology Deployment | South African mining headgear specifications isolate fault segments without system-wide shutdown, displacing quarterly inspection rounds. |
| Regional Certification Harmonization Engagement | Pending SABS-SON-Egyptian code alignment would streamline cross-border equipment procurement and service licensing. |
Methodological Framework
Operator-level perspectives from fire systems engineering directors, mining house safety officers, petrochemical terminal managers, and municipal building control officers anchored the qualitative base for this analysis. Primary field engagement combined with secondary validation through SANS 10139 enforcement documentation, Nigerian Federal Fire Service protocol alignments, Egyptian Housing and Building National Research Center mandate drafts, and copper alloy trade flow records. Bottom-up project pipeline assessment and top-down regulatory mandate quantification provided cross-referencing discipline across market sizing.
Sensitivity analysis on CAGRs incorporated variation in mining depth extension timelines, high-rise retrofit mandate enforcement intensity, and port infrastructure investment cycles across the projection horizon. Segmentation modeling spanned product type, end-user vertical, technology architecture, and application intensity, with additional dimensioning by certification tier and after-sales contract structure. Addressable loop adoption velocity and chemical suppressant rotation rates from water-based systems served as primary forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained enforcement of South African National Building Regulations, Nigerian petroleum terminal alignment with NFPA protocols, and Egyptian high-rise mandate finalization would require recalibration. Forecasts reflect documented assumptions on technician pipeline expansion, copper price band stability, and East Asian sensor hardware supply continuity. Practitioners should keep alternative scenarios live as regional certification harmonization negotiations and lithium-ion thermal runaway detection threshold revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Fire Extinguisher Market
Fire Safety & Protection
Fire Door Market
Fire Safety & Protection
Fire Pump Market
Fire Safety & Protection
Australia Emergency Lighting Market
Fire Safety & Protection
UAE Firefighting Foam Market
Fire Safety & Protection
Fire Protection Valves and Fittings Market
Fire Safety & Protection
Automatic Fire Suppression System (AFSS) Market
Fire Safety & Protection
Powder Fire Suppression System Market
Fire Safety & Protection
Fire Extinguisher Inspection Services Market
Fire Safety & Protection
Fire and Explosion Proof Lights Market
Fire Safety & Protection
Civil Combustible Gas Alarm Market
Fire Safety & Protection
Global Fire Suppression System Market
Fire Safety & Protection
UAE Fire Protection System Market
Fire Safety & Protection
North America Fire Protection Water Storage Tanks Market
Fire Safety & Protection
Fire and Rescue Helmets Market
Fire Safety & Protection
Smoke Pressure System Market