
 Fire Hose Market | 2026-2036
Fire Hose Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Hose Market Intelligence
NFPA 1962-certified attack hose is collapsing the price premium between municipal-spec and commercial-grade products, forcing manufacturers to consolidate quality tiers. North American Fire Hose Corp. leverages captive weaving capacity to anchor its position in wildland applications. Kuriyama of America Inc. sustains distribution density across industrial MRO channels. Albert Ziegler GmbH dominates European tender compliance through DIN-certified layflat engineering.
A fire hose is a high-pressure flexible conduit constructed from woven textile reinforcement with elastomeric or thermoplastic inner linings, engineered to convey water or fire-retardant agents at operating pressures exceeding 150 psi. Its primary purpose is to deliver suppressant volumes rapidly from source to firefront while resisting abrasion, kinking, and thermal degradation under emergency deployment conditions. Rubber fire hose occupies the premium tier in municipal procurement, where burst-strength specifications and 10-year service life requirements concentrate margin pools. Layflat hose is expanding fastest in industrial and forestry sectors, driven by rapid-deployment logistics and reduced storage footprint demands. PVC fire hose competes primarily on first-cost in commercial and temporary setup applications, where replacement cycles are shorter and performance thresholds are less severe.
NFPA standards, Underwriters Laboratories certification, and EU CE marking under the Pressure Equipment Directive collectively govern hose construction, testing protocols, and market access across major economies. OSHA workplace safety mandates and EPA spill-response preparedness rules extend demand into industrial petrochemical and marine segments. Stakeholders must monitor evolving NFPA 1962 edition requirements and synthetic material flame-resistance benchmarks to anticipate specification shifts before tender cycles reset.
Market Dynamics
Synthetic polymer weave technology is decomposing the traditional rubber-municipal duopoly, collapsing certification-grade price premiums and forcing manufacturers to consolidate around NFPA 1962-compliant synthetic construction or exit municipal tender cycles entirely.
Growth Catalysts
- NFPA 1962 inspection mandates:Municipal departments across the United States face compressed replacement cycles for aging rubber inventory, creating pull-through demand for certified synthetic alternatives.
- Wildland fire suppression logistics:Forestry agencies prioritize rapid-deployment layflat hose for reduced storage footprint and helicopter transport compatibility.
- Industrial petrochemical safety:OSHA workplace mandates and EPA spill-response rules extend specification-grade procurement into marine and refinery maintenance channels.
Market Restraints
- Aramid fiber cost volatility:Synthetic reinforcement feedstock prices fluctuate with aerospace and defense demand, compressing margin stability for weave-dependent manufacturers.
- Weaving capacity concentration:Captive textile production clusters in the southeastern United States create geographic supply vulnerability for non-integrated competitors.
- NFPA certification timeline friction:Extended third-party testing protocols delay new product commercialization by 18-24 months, freezing innovation returns.
Strategic Opportunities
- European tender compliance gap:DIN-certified layflat engineering capacity remains underdeveloped relative to CE-marked demand, creating white space for certified entrants.
- Smart hose integration:Convergence of pressure-monitoring IoT sensors with synthetic weave construction enables predictive maintenance contracts in industrial MRO channels.
- EU Green Deal procurement incentives:Public tender scoring shifts toward recyclable thermoplastic linings, favoring manufacturers with circular material programs.
Industry Challenges
- Composite weaving technician scarcity:Specialized loom operation and elastomer-lamination skills concentrate among aging workforces in legacy textile regions.
- Legacy rubber-municipal integration:Departments with decade-old hose inventories face training and compatibility friction when transitioning to synthetic attack lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Hose Market |
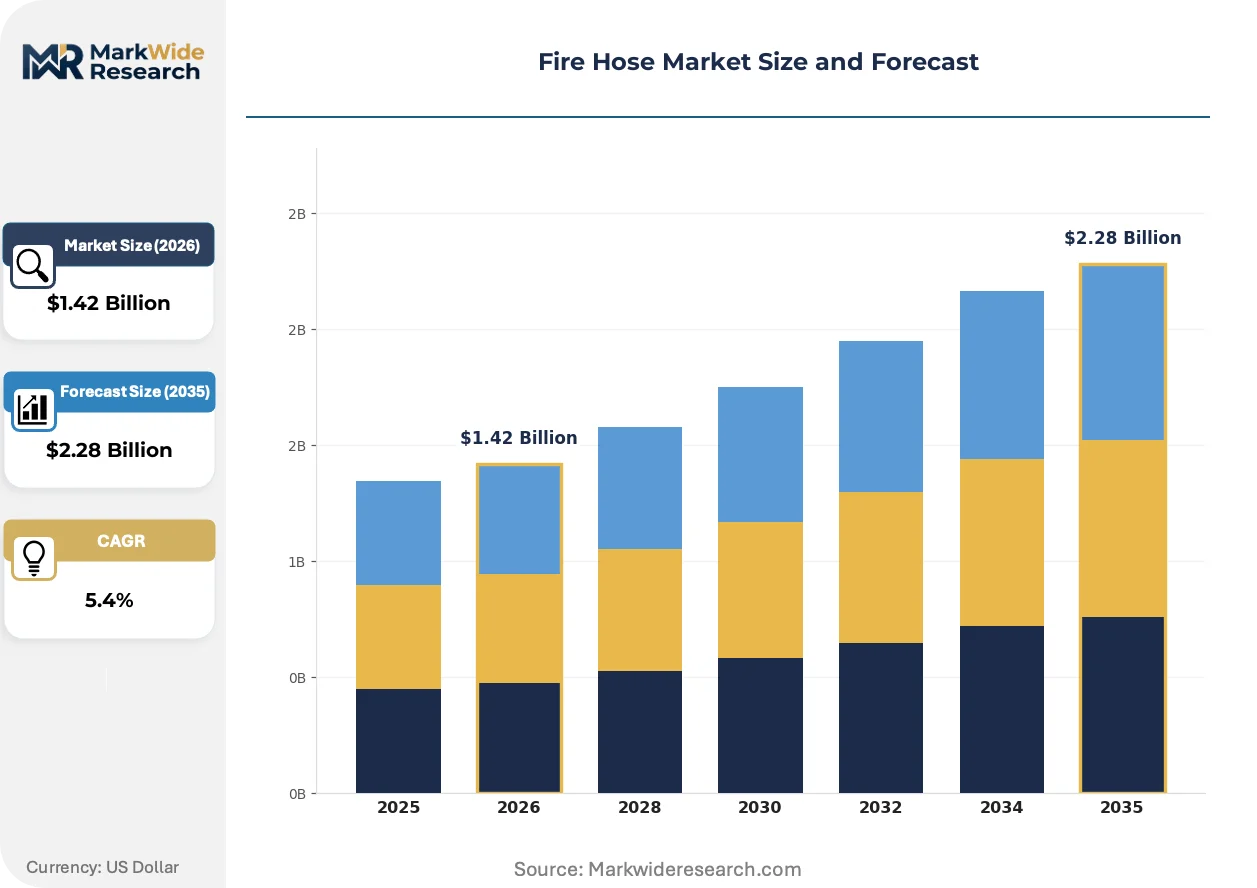
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Fire Hose, PVC Fire Hose, Reinforced Hose, Cloth Covered Hose, Suction Hose, Layflat Hose Application: Municipal Firefighting, Industrial Fire Protection, Forest Fire Management, Marine Fire Suppression, Military Firefighting, Commercial Fire Safety End User: Fire Departments, Petrochemical Plants, Forestry Departments, Shipping Companies, Armed Forces, Construction Sites Deployment: Stationary Installation, Portable Equipment, Vehicle Mounted, Fixed Systems, Temporary Setup, Emergency Response Units |
| Companies Covered | NORTH AMERICAN FIRE HOSE CORP., Kuriyama of America Inc., Albert Ziegler GmbH, Superior Fire Hose Corp., Puck Enterprises, Angus Fire Ltd., Dixon Valve and Coupling Co. LLC, National Fire Equipment Ltd., Mercedes Textiles Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Hose Market Strategic Shifts & Innovations
Material science advances and regulatory recertification cycles are compressing product lifecycles while expanding performance thresholds across municipal, industrial, and wildland deployment contexts.
Thermoplastic polyurethane (TPU) inner lining technology is decomposing the traditional rubber-municipal specification hierarchy. TPU delivers comparable burst strength at reduced wall thickness, enabling lighter attack hose for extended fireground maneuverability. Municipal procurement departments in high-rise urban jurisdictions are accelerating adoption to reduce firefighter fatigue during vertical deployment.
The EU Pressure Equipment Directive's expanded scope for flexible pressure conduits is forcing CE-marking upgrades across export-oriented manufacturers. Compliance costs are filtering marginal producers from European tender participation. German and French municipal buyers now require dual NFPA-DIN certification, compressing vendor pools to multi-standard engineering specialists.
Specification-driven buyer concentration is consolidating procurement authority within centralized municipal purchasing cooperatives. Individual fire departments are losing autonomous sourcing discretion as regional entities aggregate volume for tender leverage. This pattern is most visible in the western United States, where state-level wildfire mitigation budgets flow through consolidated acquisition frameworks.
Fire Hose Market Segmentation
NFPA 1962 certification tiers and DIN-compliant engineering standards fragment procurement specifications across municipal, industrial, and wildland deployment contexts. Manufacturers must align construction chemistry and weave architecture to distinct pressure ratings, abrasion thresholds, and storage logistics demanded by each segment cluster.
Product Type:
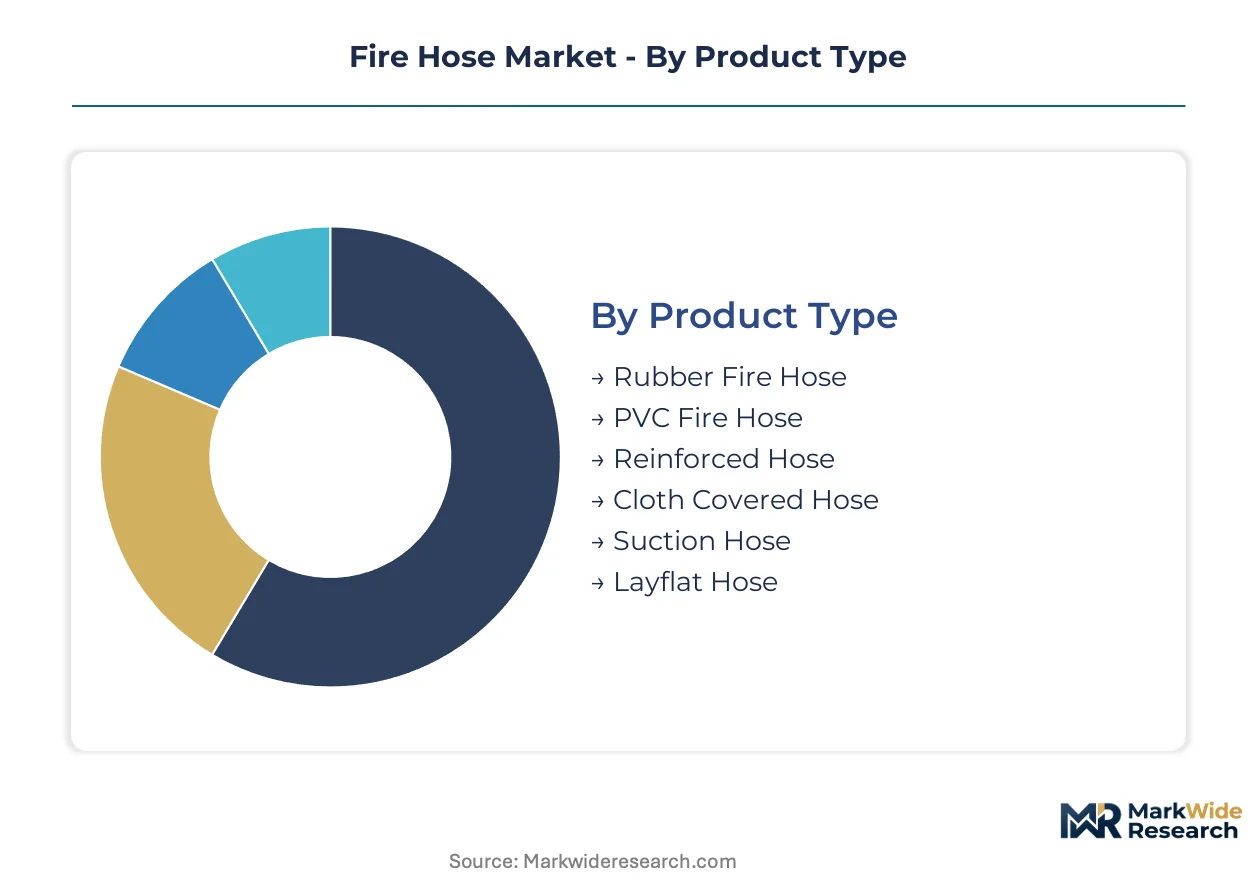
NFPA 1962 and DIN-certified construction standards bifurcate municipal procurement between legacy rubber specifications and emerging synthetic polymer weaves, collapsing traditional price premiums and forcing material science investment decisions.
- Rubber Fire Hose:Woven textile reinforcement with vulcanized elastomer inner lining delivers burst strength exceeding 800 psi for high-pressure municipal attack lines. United States urban departments specify rubber construction for NFPA 1962 ten-year service life compliance, though synthetic alternatives are compressing specification share.
- Layflat Hose:Collapsible thermoplastic construction with synthetic polymer weave enables rapid deployment and helicopter transport compatibility for wildland suppression logistics. Forestry agencies in California and Australia prioritize reduced storage footprint and extended reach capability in remote terrain access.
- PVC Fire Hose:Lightweight thermoplastic construction competes on first-cost for commercial temporary setups with shorter replacement cycles.
- Reinforced Hose:Multi-layer synthetic fiber architecture targets industrial petrochemical applications requiring chemical resistance.
- Cloth Covered Hose:Traditional cotton-jacket construction persists in heritage building protection and museum fire suppression protocols.
- Suction Hose:Rigid-wall corrugated construction maintains structural integrity under negative pressure for drafting operations from open water sources.
Rubber construction handles the majority of municipal throughput; layflat hose is gaining share fastest in wildland and industrial logistics channels.
Application:
End-use concentration varies sharply by pressure specification, deployment frequency, and regulatory inspection cycle intensity.
- Municipal Firefighting:Urban departments in high-rise jurisdictions prioritize lightweight attack hose for vertical deployment fatigue reduction. NFPA 1962 inspection mandates compress replacement cycles for aging inventory across United States metropolitan procurement cooperatives.
- Industrial Fire Protection:Petrochemical refineries and marine terminals specify chemical-resistant construction for OSHA workplace safety compliance and EPA spill-response preparedness. Kuriyama of America sustains distribution density across MRO channels serving this segment.
- Forest Fire Management:Rapid-deployment logistics and helicopter transport compatibility drive layflat specification for extended reach in remote terrain.
- Marine Fire Suppression:Saltwater corrosion resistance and compact storage requirements shape procurement for shipping companies and port authorities.
- Military Firefighting:NATO-standard interoperability and rapid deployment specifications govern defense procurement cycles.
- Commercial Fire Safety:First-cost sensitivity and shorter replacement horizons favor PVC construction in retail, hospitality, and temporary facility applications.
Municipal firefighting commands the largest installed base; industrial fire protection is expanding most quickly on regulatory mandate extension.
End User:
Procurement authority concentration varies from centralized municipal cooperatives to fragmented construction site rentals.
- Fire Departments:Consolidated regional purchasing cooperatives in the western United States aggregate volume for tender leverage, compressing vendor pools to NFPA 1962-certified specialists.
- Petrochemical Plants:OSHA mandates and EPA rules extend specification-grade procurement into marine and refinery maintenance channels with predictive maintenance contract potential.
- Forestry Departments:State-level wildfire mitigation budgets flow through consolidated acquisition frameworks prioritizing layflat rapid-deployment capability.
- Shipping Companies:International Maritime Organization compliance drives marine-specific corrosion-resistant specifications.
- Armed Forces:Defense logistics agencies require multi-standard certification for interoperability across allied deployment contexts.
- Construction Sites:Temporary setup applications favor rental channel PVC products with minimal specification overhead.
Fire departments maintain the deepest specification expertise; petrochemical plants are driving the steepest contract value expansion through integrated safety service agreements.
Deployment:
Physical installation constraints determine wall thickness, coupling compatibility, and storage system integration requirements.
- Stationary Installation:Fixed building risers and standpipe systems require NFPA 14-compliant pressure ratings with decade-long service life guarantees.
- Portable Equipment:Attack line maneuverability drives weight reduction priorities in high-rise urban jurisdictions.
- Vehicle Mounted:Aerial platform and pumper truck integration demands abrasion-resistant outer jackets for road transit exposure.
- Fixed Systems:Industrial facility permanent installation requires chemical compatibility certification for specific suppressant agents.
- Temporary Setup:Event security and construction site applications prioritize rapid deployment and retrieval logistics.
- Emergency Response Units:Mobile command and hazardous materials teams specify modular rapid-connection systems for multi-agent deployment flexibility.
Stationary installation represents the largest cumulative footage; portable equipment is climbing fastest on urban vertical deployment requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Captive weaving capacity concentrates in the southeastern United States, creating geographic supply vulnerability for non-integrated competitors. Synthetic polymer feedstock access and municipal procurement density shape regional competitive positioning across major economies.
United States
Urban infrastructure renewal and wildfire mitigation budgets are expanding procurement volumes for NFPA 1962-certified hose. OSHA workplace safety mandates extend specification-grade demand into petrochemical and marine segments. The southeastern weaving belt anchors captive textile production for municipal attack line supply.
Germany
DIN-certified layflat engineering capacity serves European tender compliance requirements with precision manufacturing standards. The EU Pressure Equipment Directive's expanded scope for flexible pressure conduits forces CE-marking upgrades across export-oriented suppliers. Bavarian engineering clusters specialize in dual NFPA-DIN certification for cross-border municipal procurement.
China
Domestic fire safety infrastructure investment accelerates demand for synthetic polymer weave technology in high-rise urban jurisdictions. GB standards and MIIT industrial policy guide domestic certification requirements for pressure equipment. Yangtze River Delta manufacturing bases supply cost-competitive thermoplastic lining capacity for Asian export markets.
Canada
Forestry agency procurement prioritizes rapid-deployment layflat hose for remote terrain access and helicopter transport compatibility. Health Canada and PMRA regulate chemical compatibility for industrial spill-response applications. Ontario-based distribution networks serve cross-border municipal cooperatives with NFPA-compliant inventory.
Australia
Extended bushfire seasons intensify state-level wildfire mitigation budget flows through consolidated acquisition frameworks. The TGA and state-level workplace safety regulators govern industrial fire protection specifications. Queensland and New South Wales forestry departments drive layflat specification for extended reach in remote terrain.
Fire Hose Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics across certification-grade segments. The vendor base stratifies around NFPA 1962-certified synthetic specialists, DIN-compliant European engineers, and cost-optimized thermoplastic fabricators. Three archetypes dominate: captive weaving integrators, distribution-heavy industrial suppliers, and precision certification specialists. Consolidation pressure favors M&A activity among synthetic weave technology holders and strategic partnerships for European tender compliance access.
Among North American-based suppliers, North American Fire Hose Corp. and Kuriyama of America Inc. exemplify the captive weaving and distribution density archetypes respectively. Albert Ziegler GmbH anchors the European precision engineering tier. These three occupy positions spanning municipal specification compliance, industrial MRO channel penetration, and cross-border certification expertise.
| Leading Market Players |
|---|
| NORTH AMERICAN FIRE HOSE CORP. |
| Kuriyama of America Inc. |
| Albert Ziegler GmbH |
| Superior Fire Hose Corp. |
| Puck Enterprises |
| Angus Fire Ltd. |
| Dixon Valve and Coupling Co. LLC |
| National Fire Equipment Ltd. |
| Mercedes Textiles Ltd. |
| Others |
Cost & Logistics Intelligence
Eighteen-month NFPA 1962 recertification lead times concentrate pricing power among captive weaving integrators in the southeastern United States, while aramid fiber inventory cycles amplify margin volatility for non-integrated competitors bidding municipal tender cycles.
Pricing Analysis
NFPA 1962 certification dictates the pricing tier structure across municipal procurement, separating NFPA-certified synthetic weaves from commercial-grade PVC construction. Pricing stratifies across premium rubber-municipal specifications, mid-tier synthetic attack lines, and economy PVC temporary setups. Cost compression in synthetic reinforcement tiers is intensifying because aerospace and defense demand absorbs aramid fiber supply. Industrial petrochemical buyers exhibit lowest price sensitivity due to OSHA mandate compliance requirements, while construction site rentals show highest sensitivity to first-cost positioning.
Supply Chain Analysis
Textile loom capacity concentration in the southeastern United States anchors global supply for NFPA-certified attack hose, creating single-source vulnerability for European and Asian municipal buyers. Feedstock supply draws from aramid fiber producers in the United States and Japan, with TPU lining compounds sourced from Yangtze River Delta chemical clusters. Tariff exposure on synthetic polymer imports threatens margin stability for DIN-certified European exporters. Distribution runs through regional municipal purchasing cooperatives in the western United States and industrial MRO channel partners serving petrochemical facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart hose IoT integration is redefining this market as a platform-economics inflection, where predictive maintenance contracts and sensor-enabled service bundling displace pure hardware procurement across industrial MRO channels.
For Market Incumbents: Shield municipal specification share by accelerating backward integration into aramid fiber weaving capacity, countering aerospace demand absorption that threatens reinforcement supply security. Secure dual NFPA-DIN certification engineering ahead of German and French municipal procurement shifts, as single-standard vendors face exclusion from consolidated tender pools. For New Entrants and Emerging Players: Anchor in European DIN-certified layflat engineering capacity, where CE-marking compliance gaps persist relative to cross-border municipal demand. Target forestry agency procurement in Australia and Canada, where helicopter transport compatibility and rapid-deployment logistics favor collapsible thermoplastic construction over legacy rubber inventory. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant fire hose divisions lacking NFPA 1962 synthetic weave capabilities. Five-to-ten year viability hinges on certification-grade manufacturing consolidation and smart hose technology integration. Watch for aramid fiber price inflection signals as aerospace demand cycles compress synthetic reinforcement margins.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Hose Sensor Integration | IoT pressure monitoring enables predictive maintenance contracts in industrial MRO channels. |
| Dual Certification Engineering Investment | NFPA-DIN compliance secures access to German and French municipal procurement pools. |
| Aramid Fiber Weaving Capacity Expansion | Captive reinforcement production insulates margins from aerospace demand volatility. |
| EU Green Deal Material Transition | Recyclable thermoplastic lining programs capture public tender scoring advantages. |
| Forestry Agency Distribution Partnerships | Layflat rapid-deployment logistics align with California and Australia wildfire mitigation budgets. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with municipal fire chiefs, industrial safety officers, and textile manufacturing engineers, combined with secondary validation through NFPA certification databases, OSHA enforcement records, and customs trade data. Bottom-up triangulation across hose footage shipment records and top-down reconciliation with municipal procurement budget disclosures anchored volume estimates. Conversations with regional purchasing cooperative administrators and petrochemical facility maintenance directors supplied tender cycle and replacement horizon intelligence.
Across the projection horizon, the analytical framework modeled segmentation across product type, application, end user, and deployment configuration dimensions. CAGRs derived from historical replacement cycle analysis and regulatory mandate acceleration patterns, with synthetic polymer adoption curves and wildland fire suppression budget trajectories serving as primary forecast inputs.
Material uncertainties — aramid fiber cost volatility, NFPA edition revision timelines, and EU Pressure Equipment Directive scope expansions — sit outside the modeled envelope. Forecasts reflect assumptions about certification continuity and municipal procurement consolidation trajectories. Practitioners should keep alternative scenarios live as aerospace demand cycles and synthetic material flame-resistance benchmarks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Automatic Fire Ball Extinguisher Market
Fire Safety & Protection
Smoke and Carbon Monoxide Alarm Market
Fire Safety & Protection
Fire Suppression Market
Fire Safety & Protection
Fire Protection Coating Market
Fire Safety & Protection
Global Fire Extinguisher Cylinders Market
Fire Safety & Protection
Passive Fire Proofing System Market
Fire Safety & Protection
North America Fire Extinguisher Market
Fire Safety & Protection
Global Smoke Evacuation Systems Market
Fire Safety & Protection
Flame Barrier Market
Fire Safety & Protection
Fire Alarm Systems Market
Fire Safety & Protection
Smart Smoke Detector Market
Fire Safety & Protection
Global Flame Arrestors Market
Fire Safety & Protection
Marine Fire Extinguishing System Market
Fire Safety & Protection
Europe Passive Fire Protection Market
Fire Safety & Protection
Smoke Detector Market
Fire Safety & Protection
Fire Resistant Glass Market