
 Oilfield Biocides and Bio-Solvents Market | 2026-2036
Oilfield Biocides and Bio-Solvents Market Size, Share, and Industry Trends Forecast 2026-2036
Oilfield Biocides and Bio-Solvents Market Analysis
Multi-source procurement of active biocide ingredients is rebalancing toward vertically integrated suppliers with captive amine and quaternary ammonium compound production. BASF SE leverages its Ludwigshafen chemical complex to sustain backward integration into biocide precursors, insulating margin pools from feedstock volatility. Dow Chemicals anchors North American supply through its Texas Gulf Coast manufacturing footprint, while Solvay competes on specialty surfactant chemistry for high-salinity reservoir conditions.
Oilfield biocides and bio-solvents comprise formulated chemical systems designed to control microbial proliferation, reduce surface tension, and dissolve hydrocarbon deposits in subsurface and surface oilfield operations; quaternary ammonium compounds and glutaraldehyde-based biocides typically target sulfate-reducing bacteria at concentrations between 100-500 ppm in injection water systems. Bio-solvents derived from corn-derived ethyl lactate or soy methyl esters serve as alternatives to xylene and toluene in tank cleaning and pipeline maintenance applications. Biocides command the largest value share among product types due to non-negotiable microbial control requirements in waterflooding operations, while bio-solvent demand accelerates fastest as operators face escalating disposal costs for hazardous aromatic solvents. Well treatment applications generate the highest volume consumption because each fracturing stage requires continuous biocide dosing to prevent biofouling of proppant packs.
The EPA regulates biocide discharge under the Clean Water Act NPDES program, while OSHA mandates exposure limits for glutaraldehyde and acrolein in oilfield chemical handling. REACH registration requirements in Europe constrain export eligibility for non-compliant biocide actives, redirecting formulation investments toward PRTR-listed alternatives. Stakeholders must monitor pending EPA reassessment of quaternary ammonium compound ecotoxicity, as a restrictive determination would force rapid reformulation across fracturing fluid portfolios.
Market Dynamics
The EPA's pending reassessment of quaternary ammonium compound ecotoxicity is compressing formulation timelines across fracturing fluid portfolios, forcing operators to pre-validate alternative biocide actives before restrictive determinations take effect.
Growth Catalysts
- Texas Permian Basin drilling intensity:Water recycling programs in this formation consume elevated biocide volumes to control sulfate-reducing bacteria in produced water reinjection systems.
- Clean Water Act NPDES enforcement:EPA discharge limitations for oil and gas extraction effluent are accelerating substitution of conventional aromatic solvents with bio-based alternatives in tank cleaning operations.
- Glutaraldehyde demand in hydraulic fracturing:Multi-stage well completions require continuous biocide dosing to prevent biofouling of proppant packs, sustaining chemical throughput per well.
Market Restraints
- Feedstock volatility in amine supply:Captive production of quaternary ammonium precursors concentrates among Ludwigshafen-scale chemical complexes, exposing non-integrated formulators to ethylene oxide and ammonia price swings.
- REACH registration barriers:European biocide actives lacking PRTR-compliant dossiers face export exclusion, constraining formulation flexibility for North American suppliers serving dual-continent operators.
- Technical performance gaps in high-salinity reservoirs:Bio-solvents derived from soy methyl esters exhibit reduced efficacy above 150,000 ppm total dissolved solids compared to xylene alternatives.
Strategic Opportunities
- Underpenetrated Bakken formation waterflooding:North Dakota operators are expanding biocide-intensive enhanced oil recovery programs as mature wells require microbial control in recycled injection water.
- EU Green Deal bio-based solvent mandates:REACH-aligned incentives for renewable chemical content are creating preferential procurement channels for ethyl lactate formulations in European offshore maintenance.
- Convergence of real-time monitoring and automated dosing:Integration of downhole microbial sensors with surface chemical injection systems enables precision biocide application, reducing over-treatment volumes.
Industry Challenges
- Specialized formulation chemist scarcity:Expertise in high-pressure high-temperature biocide stability testing remains concentrated among legacy oilfield chemical laboratories in Houston and Calgary.
- Multi-jurisdiction compliance synchronization:Operators must reconcile OSHA exposure limits for glutaraldehyde with EPA effluent guidelines and state-level oil and gas chemical disclosure rules simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oilfield Biocides and Bio-Solvents Market |
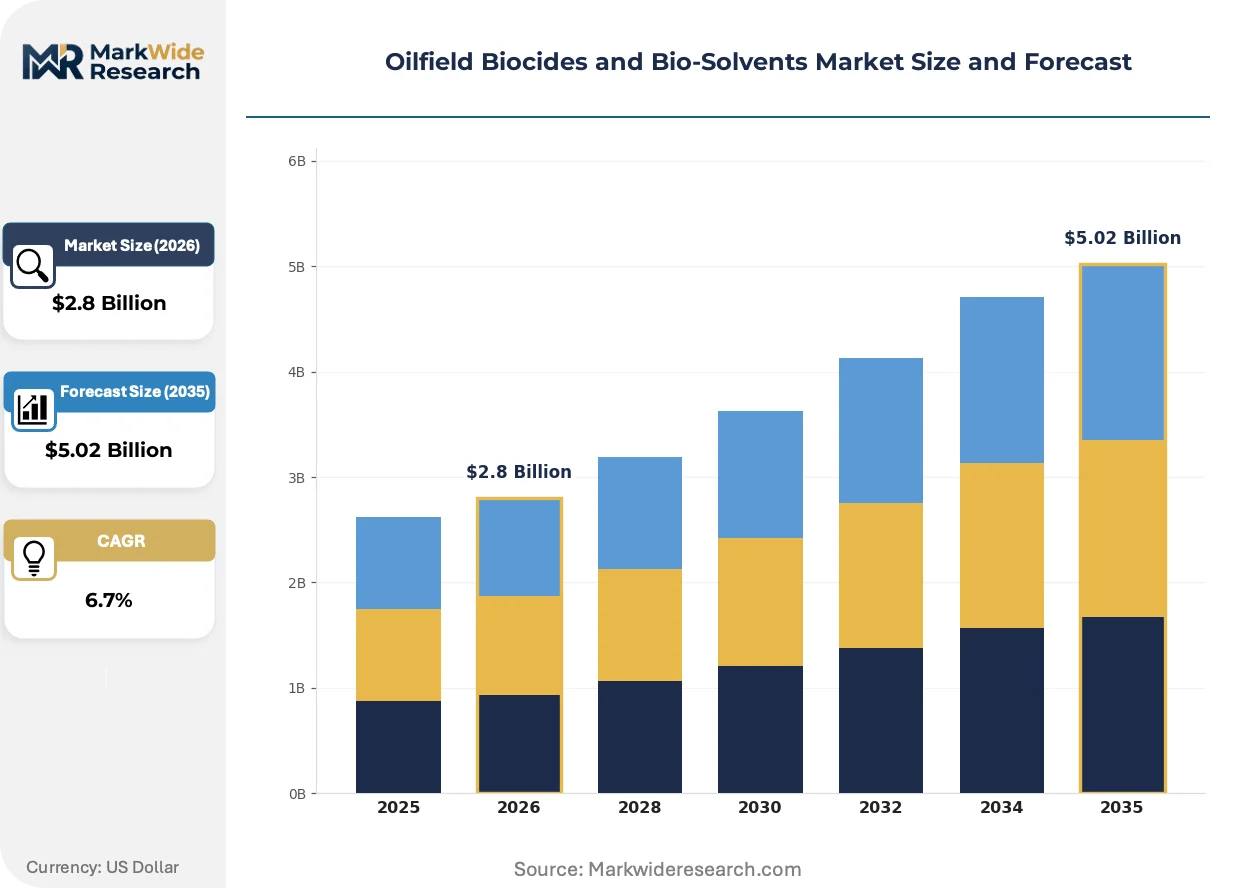
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biocides, Surfactants, Solvents, Antimicrobials Application: Well Treatment, Water Treatment, Chemical Enhanced Oil Recovery, Bioremediation End User: Oil & Gas Companies, Environmental Services, Chemical Manufacturers, Water Treatment Facilities Delivery Mode: Liquid, Powder, Emulsion, Concentrate |
| Companies Covered | BASF SE, Solvay, Dow Chemicals, Stepan Company, Ecolab, Pilot Chemicals, Nalco Companies, Baker Hughes, Locus Bio-Energy Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oilfield Biocides and Bio-Solvents Market Emerging Trajectories
Electrochemical biocide generation at the wellsite is compressing supply chains for traditional batch-delivered quaternary ammonium compounds. Real-time microbial monitoring combined with automated dosing protocols is reshaping how operators manage sulfate-reducing bacteria populations.
On-site chlorine dioxide generation systems are electrifying microbial control economics in Permian Basin water recycling facilities. Pioneer Natural Resources and other large independents have deployed mobile electrochemical units at multi-pad drilling sites, eliminating transportation costs for bulk glutaraldehyde deliveries while enabling precise residual control in produced water reinjection systems.
REACH registration requirements for biocide actives are forcing rapid portfolio rationalization among European oilfield chemical suppliers. ECHA's stricter data requirements for quaternary ammonium compound environmental fate studies are redirecting formulation investments toward PRTR-listed alternatives, with offshore North Sea operators now specifying glutaraldehyde-thiocyanate blends to preempt compliance gaps.
Integrated service contracts bundling biocide supply with water treatment infrastructure are displacing transactional chemical procurement in Texas shale plays. Large independents now contract directly with backward-integrated suppliers for full-loop microbial management, compressing distributor margins while locking in volume commitments across multi-year drilling programs in the Delaware and Midland sub-basins.
Oilfield Biocides and Bio-Solvents Market Segmentation
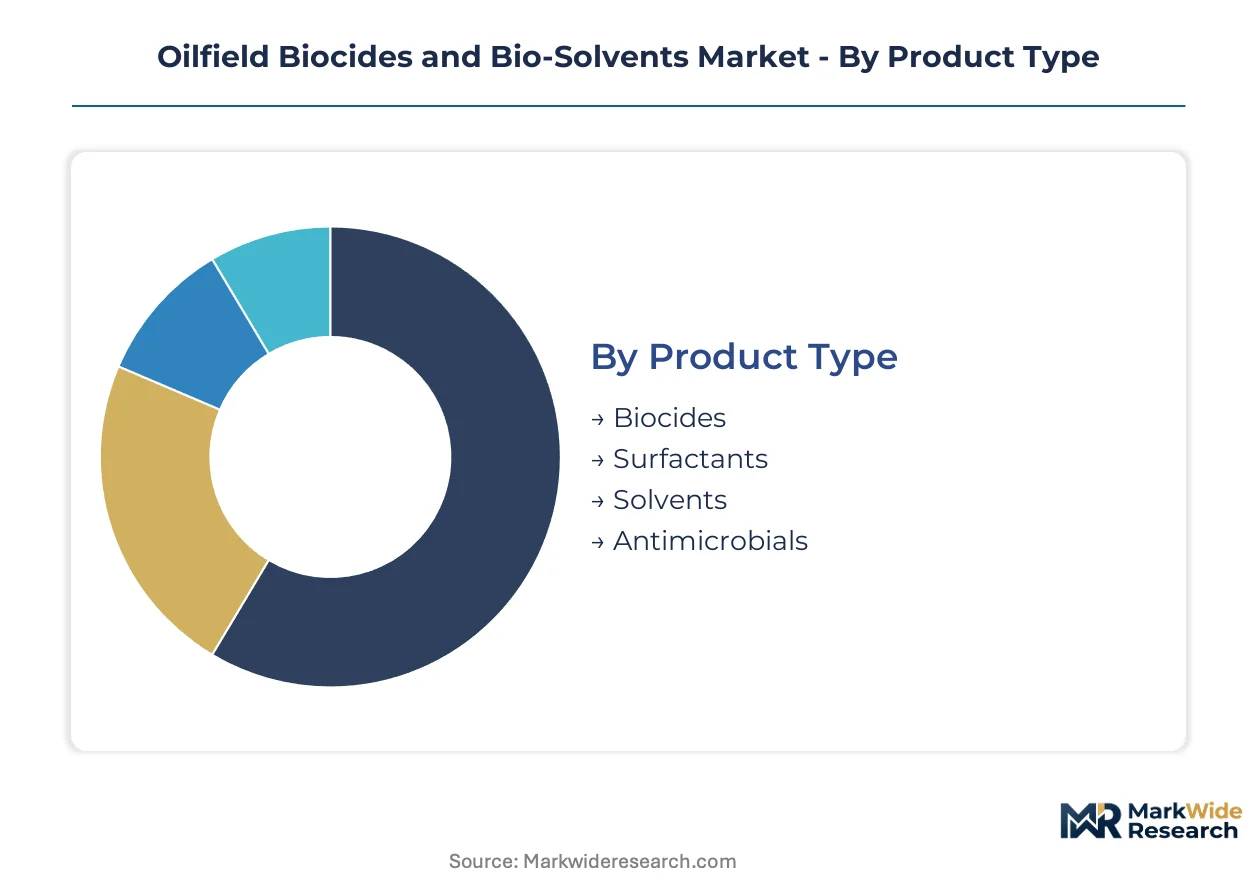
Oilfield biocides and bio-solvents demand fragments across four structural dimensions that determine procurement patterns and margin capture. Product chemistry dictates performance thresholds in high-pressure reservoir conditions. Application context and delivery format shape logistics economics and dosing precision.
Product Type:
Volume concentrates in commodity biocides while specialty solvents command premium positioning.
- Biocides:Quaternary ammonium compounds and glutaraldehyde formulations deliver microbial control at 100-500 ppm dosing in injection water systems. Permian Basin water recycling intensity sustains the highest throughput volumes as sulfate-reducing bacteria control becomes non-negotiable for proppant pack integrity.
- Solvents:Bio-based alternatives derived from corn ethyl lactate and soy methyl esters substitute xylene and toluene in tank cleaning and pipeline maintenance. EPA effluent limitation guidelines under the Clean Water Act NPDES program accelerate substitution rates as hazardous aromatic disposal costs escalate.
- Surfactants:Specialty chemistry for high-salinity reservoir conditions above 150,000 ppm total dissolved solids.
- Antimicrobials:Broad-spectrum actives targeting acid-producing bacteria in surface facility applications.
Today's leader: Biocides. Tomorrow's challenger: Solvents.
Application:
Well intervention intensity separates high-volume recurring demand from project-based chemical consumption.
- Well Treatment:Multi-stage hydraulic fracturing operations require continuous biocide dosing to prevent biofouling of proppant packs. Each completion stage drives chemical throughput that scales directly with drilling program intensity in Texas Delaware and Midland sub-basins.
- Water Treatment:Produced water recycling for reinjection demands elevated biocide volumes to control sulfate-reducing bacteria populations. North Dakota Bakken formation operators are expanding these programs as mature wells require microbial management in recycled injection water.
- Chemical Enhanced Oil Recovery:Surfactant-polymer flooding in mature fields.
- Bioremediation:Soil and groundwater treatment at legacy production sites.
Well Treatment generates the steepest expansion trajectory through fracturing stage proliferation.
End User:
Operator scale determines whether procurement flows through integrated service contracts or transactional distributor relationships.
- Oil & Gas Companies:Large independents and majors now contract directly with backward-integrated suppliers for full-loop microbial management, compressing distributor margins while locking multi-year volume commitments across drilling programs.
- Environmental Services:Remediation contractors handling site closure and reclamation.
- Chemical Manufacturers:Formulators sourcing active ingredients for captive blending operations.
- Water Treatment Facilities:Third-party processors managing produced water for multiple operators.
Integrated operators capture procurement efficiency gains that fragmented service providers cannot match.
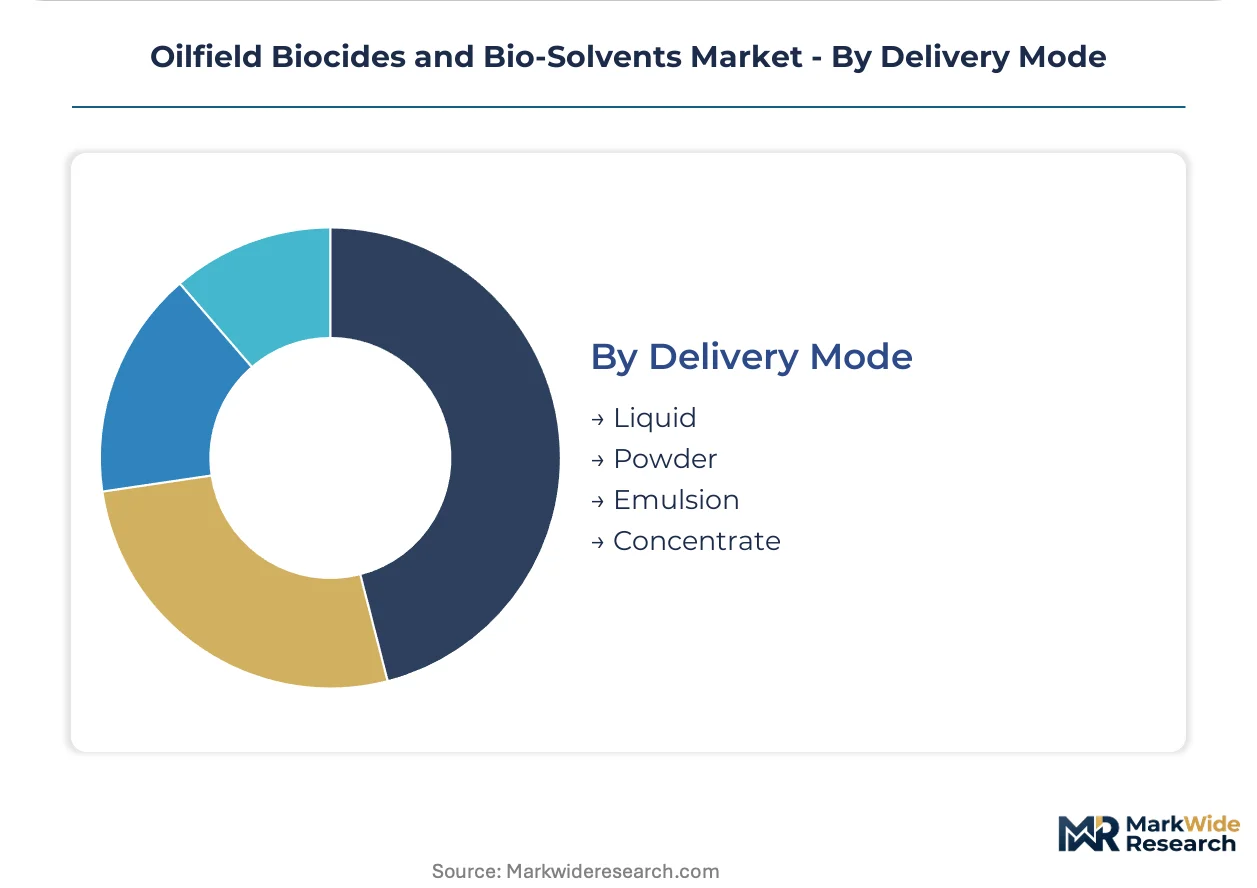
Delivery Mode:
Physical form factor shapes transportation economics and field handling requirements.
- Liquid:Standard bulk delivery for continuous injection systems dominates Permian Basin logistics where pipeline-connected storage minimizes handling costs.
- Concentrate:Reduced-volume formulations for remote location deployment where transportation distance amplifies freight burden.
- Powder:Dry formulations for extended shelf-life in inventory-constrained operations.
- Emulsion:Stabilized dispersions for controlled-release applications in high-temperature reservoirs.
Liquid formats retain share leadership while concentrate formats gain traction in remote pad development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of oilfield biocides and bio-solvents is migrating toward jurisdictions with lower compliance costs for quaternary ammonium compound handling, while regulatory arbitrage between EPA and REACH jurisdictions reshapes supplier location decisions.
United States
Texas Permian Basin drilling programs consume the highest biocide volumes globally as water recycling intensity drives chemical throughput for sulfate-reducing bacteria control. EPA's updated effluent limitation guidelines under the Clean Water Act NPDES program are pressuring operators to substitute conventional aromatic solvents with bio-based alternatives. Midland and Delaware sub-basin operators now contract directly with backward-integrated suppliers for full-loop microbial management.
Germany
BASF SE's Ludwigshafen chemical complex sustains captive production of amine and quaternary ammonium precursors, insulating margin pools from feedstock volatility. REACH registration requirements constrain export eligibility for non-compliant biocide actives, redirecting formulation investments toward PRTR-listed alternatives. The country's national chemical regulator enforces stricter environmental fate studies for quaternary ammonium compounds than EPA counterparts.
China
Domestic shale gas development in Sichuan Basin is expanding demand for glutaraldehyde-based biocides in multi-stage hydraulic fracturing operations. The Ministry of Ecology and Environment's dual carbon goals are accelerating scrutiny of conventional solvent discharge in oilfield maintenance applications. Yangtze River Delta chemical clusters are scaling ethyl lactate production capacity to serve regional tank cleaning substitution demand.
Saudi Arabia
Offshore North Field expansion programs are specifying glutaraldehyde-thiocyanate biocide blends to preempt REACH compliance gaps for European-exported crude. The national oil company is integrating electrochemical biocide generation systems at coastal water recycling facilities. Eastern Province industrial cities are attracting formulation investments targeting Middle East shale plays.
Canada
Alberta oil sands operators face escalating disposal costs for hazardous aromatic solvents in pipeline maintenance, accelerating bio-solvent substitution rates. Health Canada's PMRA regulates biocide discharge under stricter ecotoxicity thresholds than EPA guidelines for cross-border operators. Calgary-based oilfield chemical laboratories retain concentrated expertise in high-pressure high-temperature biocide stability testing.
Oilfield Biocides and Bio-Solvents Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue electrochemical on-site generation and bio-based formulation niches. The supplier base concentrates among backward-integrated chemical conglomerates with captive amine production, while specialty surfactant formulators compete on high-salinity reservoir performance. Three archetypes dominate: Ludwigshafen-scale integrated complexes, Texas Gulf Coast manufacturing anchors, and regional electrochemical technology deployers. Competitive moves center on multi-year integrated service contracts bundling biocide supply with water treatment infrastructure, and rapid reformulation pipelines to preempt regulatory determinations.
Within the integrated chemical tier, BASF SE, Dow Chemicals, and Solvay exemplify contrasting geographic and technological positioning. BASF SE represents European backward integration into biocide precursors through its Ludwigshafen complex dominance. Dow Chemicals anchors North American supply security through its Texas Gulf Coast manufacturing footprint. Solvay occupies a specialty surfactant position competing on high-salinity reservoir chemistry rather than commodity biocide volume.
| Leading Market Players |
|---|
| BASF SE |
| Solvay |
| Dow Chemicals |
| Stepan Company |
| Ecolab |
| Pilot Chemicals |
| Nalco Companies |
| Baker Hughes |
| Locus Bio-Energy Solutions |
| Others |
Supply Flow & Price Mechanics
Commodity-grade glutaraldehyde and quaternary ammonium formulations diverge sharply from specialty surfactant chemistry in both procurement economics and supply chain configuration. BASF SE's Ludwigshafen complex and Dow Chemicals' Texas Gulf Coast facilities capture premium positioning through captive amine production, while non-integrated formulators absorb ethylene oxide and ammonia volatility in spot markets.
Pricing Analysis
Distributor margins compress as large Permian Basin operators contract directly with backward-integrated suppliers for full-loop microbial management. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Cost compression in commodity biocides intensifies because electrochemical on-site generation eliminates bulk delivery markups. Small environmental services contractors exhibit highest price sensitivity, while majors prioritize performance guarantees over unit economics.
Supply Chain Analysis
Specialized formulation chemist scarcity in Houston and Calgary constrains capacity expansion for high-pressure high-temperature biocide stability testing. Manufacturing gravity centers on Germany, the United States, and China, with ethyl lactate production scaling in the Yangtze River Delta. Feedstock supply draws from ethylene oxide, ammonia, and corn-derived lactate streams. Single-source vulnerability concentrates in Ludwigshafen-scale quaternary ammonium precursor complexes. Distribution runs through pipeline-connected bulk storage in Texas shale plays and containerized concentrate formats for remote pad development.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in bio-solvent premium tiers as EPA effluent guidelines accelerate aromatic substitution, while electrochemical generation compresses commodity biocide cost structures.
For Market Incumbents: Anchor procurement efficiency through multi-year integrated service contracts bundling biocide supply with water treatment infrastructure in Texas Delaware and Midland sub-basins. Deepen upstream control over amine and quaternary ammonium precursor production to insulate margin pools from ethylene oxide volatility. Pre-validate alternative biocide actives before EPA quaternary ammonium ecotoxicity reassessments take effect. For New Entrants and Emerging Players: EPA's updated Clean Water Act NPDES enforcement in the United States opens a window for bio-based solvent formulations targeting tank cleaning and pipeline maintenance substitution demand. Electrochemical biocide generation technology penetrates fastest in Permian Basin water recycling facilities where transportation costs burden bulk glutaraldehyde deliveries. Pursue pilot deployments with large independents seeking to eliminate chemical distributor markups. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH registration barriers exclude non-compliant biocide actives from European export eligibility. Long-term viability favors suppliers with captive precursor production and rapid reformulation pipelines spanning the projection horizon. Target acquisition archetypes include regional electrochemical technology deployers with proven on-site generation economics. Monitor EPA reassessment timing for quaternary ammonium compound ecotoxicity as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biocide Precursors | BASF SE's Ludwigshafen complex insulates margin pools from ethylene oxide and ammonia price swings. |
| Electrochemical On-Site Generation Deployment | Pioneer Natural Resources eliminates bulk glutaraldehyde transportation costs through mobile wellsite units. |
| Long-Term Integrated Service Contracting | Permian Basin operators lock multi-year volume commitments while compressing distributor margins. |
| Bio-Based Solvent Formulation Investment | Ethyl lactate producers in the Yangtze River Delta capture EPA-driven aromatic substitution demand. |
| REACH-Aligned Portfolio Rationalization | European suppliers redirect investments toward PRTR-listed alternatives ahead of ECHA data requirements. |
Methodological Framework
Bottom-up well treatment and water treatment modeling reconciled against top-down chemical manufacturing tracking forms the analytical core of this study. Primary interviews with oilfield chemical procurement managers, drilling program engineers, formulation R&D directors, and water treatment facility operators combined with secondary validation from EPA effluent guideline filings, ECHA REACH registration databases, ACC industry reports, and SEC 10-K chemical segment disclosures. Triangulation across supply-side capacity assessments and demand-side drilling program intensity metrics ensures consistency.
Input-output matrices map biocide consumption per fracturing stage, produced water recycling intensity, and bio-solvent substitution rates across the modeling period. Segmentation dimensions include product chemistry grade, application context, operator scale tier, and delivery format. CAGRs derive from production capacity buildouts, regulatory enforcement timelines, and technology adoption curves in electrochemical generation. Forecast inputs incorporate Permian Basin drilling program announcements and EU Green Deal bio-based mandate implementation schedules.
Revisions become necessary when EPA quaternary ammonium ecotoxicity determinations, REACH registration requirement amendments, or electrochemical generation cost breakthroughs materialize. Forecasts reflect documented assumptions about water recycling intensity and aromatic solvent disposal cost trajectories. Practitioners should monitor EPA reassessment publication timelines and ECHA data requirement updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Glycidyl Ether Market
Industrial Chemicals
Well Stimulation Materials Sales Market
Industrial Chemicals
Global Sponge Applicator Market
Industrial Chemicals
Babassu Oil Market
Industrial Chemicals
South Africa Gypsum Plaster Market
Industrial Chemicals
Chrome Plating Market
Industrial Chemicals
Perchloroethylene Market
Industrial Chemicals
Wood Vinegar Market
Industrial Chemicals
Draft Tube Baffle (DTB) Crystallizers Market
Industrial Chemicals
Isononanol (INA) Market
Industrial Chemicals
Global Phosphate Esters Market
Industrial Chemicals
Hydrogenated Bisphenol a Market
Industrial Chemicals
Dewatering Aids Market
Industrial Chemicals
LAMEA Deoxidizer Market
Industrial Chemicals
Potassium Acetate Market
Industrial Chemicals
Emulsifiable Metalworking Fluid Market