
 Global Plating on Plastics Market | 2026-2036
Global Plating on Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plating on Plastics Market Foresight
Asian electroplating capacity is decoupling from traditional European supply networks as domestic chemical formulators scale technical-grade production. Atotech leverages its integrated chemical supply and equipment portfolio to sustain high-volume automotive contracts across multiple continents. MacDermid Incorporated anchors North American demand through specialized electroless nickel systems for electronics housings. Phillips Plating Corporation differentiates via custom job-shop finishing for medical and telecom grade applications.
Plating on plastics deposits conductive or decorative metal layers onto polymer substrates through electroless catalysis, vacuum deposition, or electrolytic reduction, typically achieving thicknesses from 0.1 to 50 microns depending on functional requirements. The process enables electromagnetic shielding, corrosion resistance, and aesthetic chrome-like finishes on components that would be impractical or overweight in solid metal. Electroplating methods currently dominate volume throughput for automotive interior trim, while vacuum metallization leads growth in consumer electronics where miniaturization and thermal management converge. ABS substrates occupy the largest share of plastic types processed due to favorable etching characteristics and paint adhesion, though polycarbonate blends are gaining share in aerospace component applications requiring higher impact resistance.
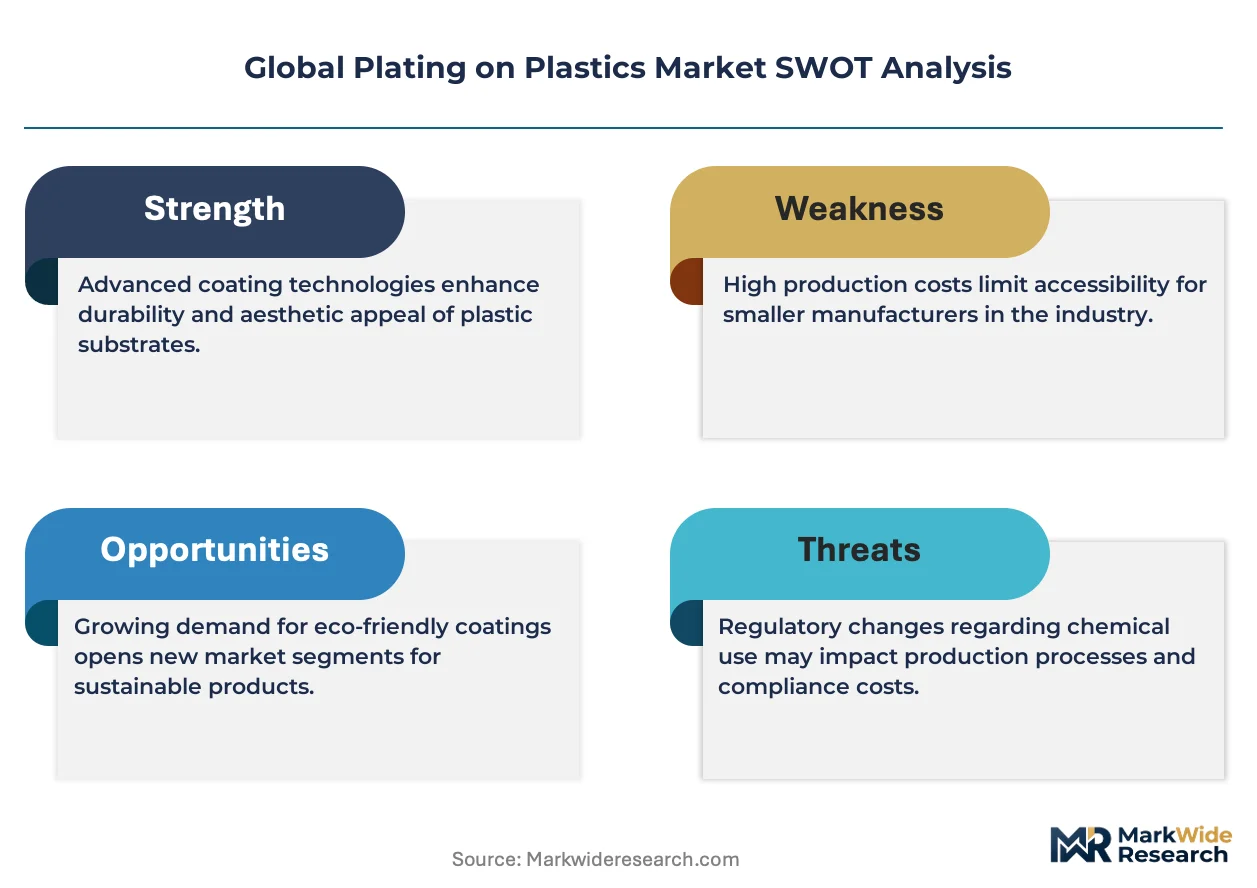
EPA effluent guidelines in the United States restrict hexavalent chromium discharge from plating operations, forcing capital investment in closed-loop rinse systems and trivalent conversion coatings. ECHA maintains REACH authorization requirements for nickel compounds and certain etching additives, directly influencing formulation decisions by European chemical suppliers. China's MEE enforces wastewater discharge standards that tighten allowable heavy metal concentrations in electroplating clusters across Guangdong and Jiangsu provinces. Stakeholders must monitor evolving substance restrictions and assess captive recycling infrastructure before committing to multi-year capacity expansion.
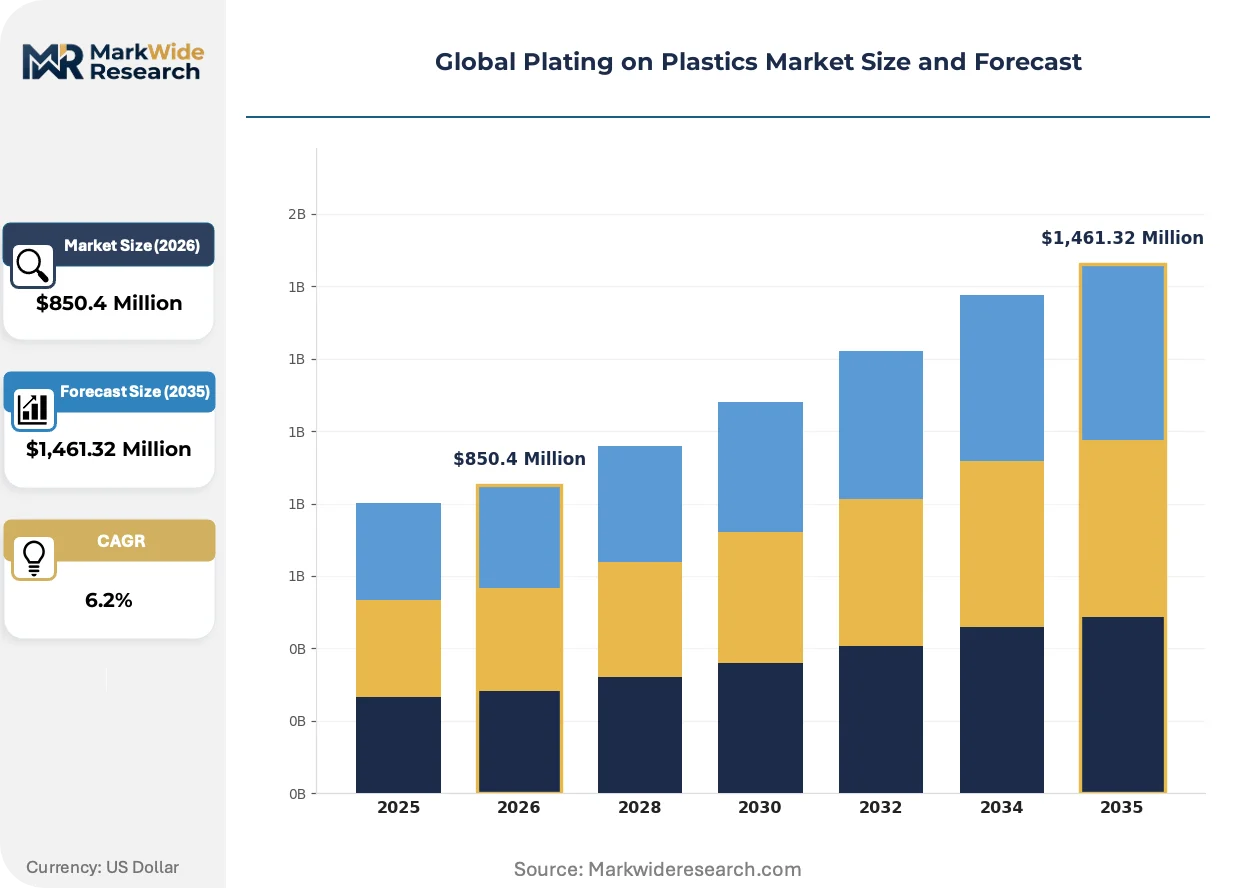
Market Dynamics
Automotive OEMs are forcing a structural recalibration of plating on plastics supply chains as lightweighting mandates collide with decorative chrome bans across multiple jurisdictions simultaneously.
Growth Catalysts
- REACH substance restrictions:European automakers are accelerating trivalent chromium adoption ahead of authorization deadlines, creating captive demand for compliant plating chemistry.
- Electronics miniaturization:5G infrastructure deployment requires electromagnetic interference shielding on polymer housings that vacuum metallization delivers at sub-50 micron precision.
- Guangdong plating clusters:Chinese domestic formulators have achieved technical-grade electroless nickel production, reducing import dependency for automotive interior contracts.
Market Restraints
- Palladium catalyst volatility:Electroless plating relies on palladium activation layers exposed to precious metal price swings that compress job-shop margins unpredictably.
- German chemical supplier concentration:Specialty etching additives for ABS substrates remain concentrated among three European formulators, creating single-source vulnerability.
- Hexavalent chromium substitution ceiling:Decorative chrome aesthetics from trivalent formulations still fail to match legacy brilliance for luxury automotive trim applications.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for mobile device production are attracting plating capacity to Noida and Chennai industrial corridors.
- Polycarbonate aerospace adoption:Higher impact resistance specifications in aircraft interior components are displacing ABS in premium seating and panel applications.
- Closed-loop water recycling:MEE wastewater standards in Jiangsu province are creating first-mover advantage for operators with captive zero-liquid-discharge infrastructure.
Industry Challenges
- Electroless chemistry expertise:Formulation tuning for novel polymer blends requires tacit knowledge that aging European technician populations struggle to transfer.
- Multi-jurisdiction compliance synchronization:Simultaneous EPA effluent rulemakings and ECHA authorization reviews force parallel technical documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plating on Plastics Market |
| Market Size in 2026 | $850.4 Million |
| Market Size in 2035 | $1,461.32 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Plating Method: Electroless Nickel, Electroplating, Vacuum Metallization, Chemical Copper, Sputtering Plastic Substrate Type: ABS, Polycarbonate, Polystyrene, Acrylic, Nylon End Use Industry: Consumer Electronics, Automotive OEMs, Aerospace Components, Household Appliances, Telecommunications Surface Treatment: Pre-Treatment, Activation, Etching, Sealing, Post-Treatment |
| Companies Covered | Atotech, MacDermid Incorporated, Phillips Plating Corporation, Uyemura, Coventya, Galva Decoparts Pvt. Ltd., Sharretts Plating Company, Covestro AG, Technic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plating on Plastics Market Shifts & Advancements
Process automation and direct-to-substrate deposition methods are compressing traditional equipment-supplier hierarchies while fragmenting buyer procurement patterns across automotive and electronics verticals.
Direct metallization chemistry is decentralizing captive plating capacity away from centralized job-shop networks. Automotive tier-1 suppliers in Stuttgart and Detroit are installing in-house electroless lines for just-in-sequence interior trim delivery. This technology is decentralizing volume from traditional merchant platers toward OEM-controlled finishing operations.
China's MEE has tightened allowable cadmium and nickel discharge concentrations in electroplating wastewater effective across Jiangsu and Guangdong clusters. Operators face capital decisions on tertiary treatment upgrades or cluster consolidation. Electronics-focused job-shops in Shenzhen are responding faster than automotive suppliers due to tighter margin structures.
Specification-driven vendor consolidation is compressing approved supplier lists at major automotive OEMs. Tier-1 buyers in Germany and Japan now demand dual-continent plating capability as a qualification threshold. This pattern is most visible in premium vehicle programs where single-source risk mitigation overrides unit cost optimization.
Global Plating on Plastics Market Segmentation
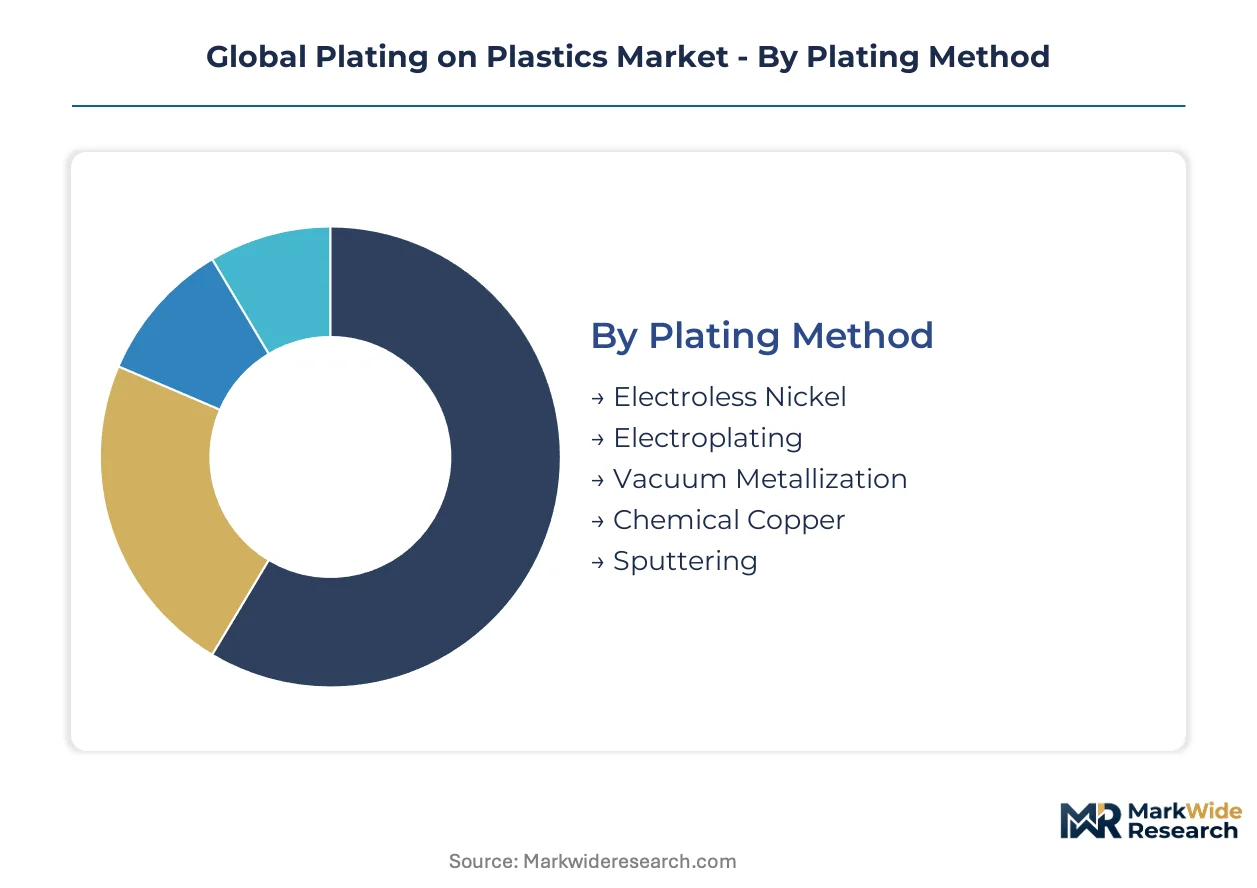
Capital allocation across plating on plastics segments diverges sharply based on equipment complexity, chemistry sophistication, and regulatory compliance burdens. Understanding these structural cost layers reveals where margin compression concentrates and where technical differentiation commands premium positioning.
Plating Method:
Electroplating lines demand the heaviest upfront capital outlays due to multi-stage tank systems, rectifier infrastructure, and wastewater treatment integration.
- Electroplating:Electrolytic deposition applies metal layers through external current, achieving precise thickness control for decorative chrome finishes. Automotive interior trim contracts in Germany and China absorb the majority of installed capacity, though EPA effluent guidelines force continuous scrubber investment.
- Electroless Nickel:Autocatalytic chemistry deposits uniform coatings without electrical current, excelling on complex geometries for EMI shielding. Electronics housings in Shenzhen and Noida industrial corridors drive volume expansion as 5G infrastructure deployment accelerates.
- Vacuum Metallization:Physical vapor deposition creates ultra-thin functional films for miniaturized components.
- Chemical Copper:Seed layer deposition enables subsequent electrolytic buildup on non-conductive substrates.
- Sputtering:Ion bombardment targets deposit high-purity metal films for aerospace-grade precision.
Electroplating absorbs the bulk of installed capacity; electroless nickel is expanding most quickly.
Plastic Substrate Type:
Material selection dictates etching chemistry requirements, process yield rates, and final mechanical performance specifications.
- ABS:Acrylonitrile butadiene styrene offers superior etching characteristics and paint adhesion through controlled rubber phase dissolution. Automotive interior components across Stuttgart, Detroit, and Shanghai manufacturing clusters standardize on ABS for chrome-look trim with proven durability.
- Polycarbonate:Engineering thermoplastic delivers impact resistance exceeding ABS by factor of three, enabling thinner wall sections. Aircraft seating and panel applications in Toulouse and Hamburg aerospace supply chains are displacing metal alternatives as weight reduction mandates intensify.
- Polystyrene:Cost-effective substrate for decorative applications with limited structural load requirements.
- Acrylic:Optical clarity and weather resistance suit lighting lens and display applications.
- Nylon:High-temperature stability supports under-hood automotive components and industrial equipment.
ABS commands dominant volume share; polycarbonate demonstrates the steepest expansion trajectory as aerospace specifications tighten.
End Use Industry:
Customer procurement patterns separate into long-term automotive contracts versus short-cycle electronics orders with diverging margin structures.
- Automotive OEMs:Decorative and functional plating on lightweight polymer components supports interior trim, badges, and mirror housings. REACH substance restrictions across European manufacturing are accelerating trivalent chromium conversion ahead of authorization deadlines.
- Consumer Electronics:Miniaturization demands drive vacuum metallization for smartphone and laptop housings requiring electromagnetic interference shielding. Guangdong province job-shops are consolidating capacity to meet MEE wastewater discharge standards.
- Aerospace Components:Polycarbonate-based seating and panel applications require flame-retardant plating systems with full traceability.
- Household Appliances:Decorative finishes on control panels and trim pieces prioritize cost efficiency over technical sophistication.
- Telecommunications:Base station and router housings require consistent EMI shielding across high-volume production runs.
Automotive OEMs anchor the revenue base; consumer electronics is climbing the fastest on 5G infrastructure deployment.
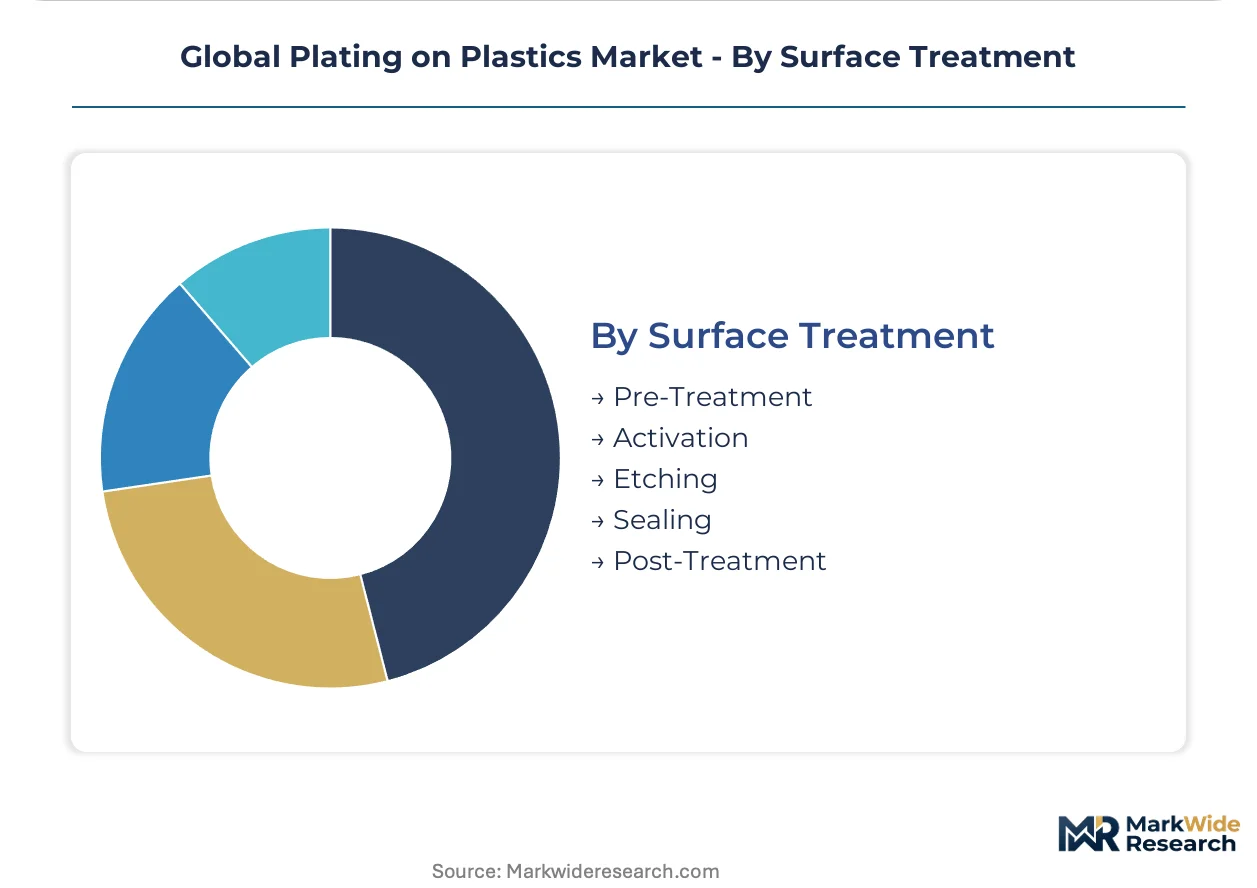
Surface Treatment:
Process step sequencing determines chemical consumption intensity and wastewater generation volumes that regulators track.
- Pre-Treatment:Degreasing and conditioning steps prepare polymer surfaces for subsequent metal deposition. Jiangsu province operators face capital decisions on tertiary treatment upgrades as MEE standards tighten allowable heavy metal discharge.
- Etching:Chromic acid or permanganate solutions create micro-roughness for mechanical adhesion of metal layers. ECHA authorization requirements for specific etching additives concentrate supply among limited European formulators.
- Activation:Palladium catalyst deposition initiates electroless plating autocatalysis.
- Sealing:Post-plate treatments enhance corrosion resistance and cosmetic durability.
- Post-Treatment:Final rinsing and drying stages generate concentrated effluent streams requiring closed-loop recovery.
Etching commands the largest chemistry spend; pre-treatment is gaining share fastest as zero-liquid-discharge systems proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chromic acid etching chemistry for ABS substrates concentrates in German and Chinese chemical formulator networks, while palladium catalyst supply chains thread through South African and Russian mining operations before reaching electroless plating facilities.
China
Guangdong and Jiangsu provinces host dense electroplating clusters serving automotive interior and electronics housing contracts. MEE wastewater standards tightened allowable cadmium and nickel discharge concentrations, forcing capital decisions on tertiary treatment upgrades. Shenzhen job-shops are consolidating faster than automotive suppliers due to tighter margin structures.
Germany
Stuttgart automotive tier-1 suppliers are installing in-house electroless lines for just-in-sequence interior trim delivery. REACH authorization requirements for specific etching additives concentrate supply among limited domestic formulators. Bavaria-based chemical suppliers anchor European technical-grade electroless nickel production for premium vehicle programs.
United States
Detroit automotive OEMs demand dual-continent plating capability as a qualification threshold for premium vehicle programs. EPA effluent guidelines restrict hexavalent chromium discharge, forcing investment in closed-loop rinse systems and trivalent conversion coatings. Midwest job-shops face parallel technical documentation burdens from simultaneous federal rulemakings.
India
Noida and Chennai industrial corridors are attracting plating capacity through PLI scheme incentives for mobile device production. BIS standards for surface treatment quality create compliance benchmarks for domestic and export contracts. Maharashtra-based automotive suppliers are expanding decorative plating lines for two-wheeler and passenger vehicle interior components.
Japan
Kanto region electronics manufacturers drive vacuum metallization demand for 5G infrastructure components requiring electromagnetic interference shielding. METI industrial standards shape formulation decisions for high-reliability applications. Osaka-based precision platers specialize in sub-50 micron deposition for miniaturized consumer device housings.
Global Plating on Plastics Market Competitive Landscape
Global majors compete with regional champions across integrated chemical supply and equipment portfolios. The vendor base separates into three tiers: multinational formulators with captive equipment divisions, specialized job-shop operators, and domestic chemical suppliers scaling technical-grade production. Two strategic archetypes dominate competitive positioning: integrated chemistry-equipment providers and pure-play finishing specialists. M&A activity concentrates on captive chemical formulation assets, while capacity expansion targets zero-liquid-discharge infrastructure in regulated clusters.
Among integrated chemistry-equipment providers, Atotech exemplifies the multinational archetype with continent-spanning automotive contracts. MacDermid Incorporated occupies a position within North American specialized systems supply. Phillips Plating Corporation represents the custom job-shop tier serving medical and telecom grade applications. These three anchors illustrate how competitive positioning fragments across chemistry ownership, geographic reach, and end-use specialization.
| Leading Market Players |
|---|
| Atotech |
| MacDermid Incorporated |
| Phillips Plating Corporation |
| Uyemura |
| Coventya |
| Galva Decoparts Pvt. Ltd. |
| Sharretts Plating Company |
| Covestro AG |
| Technic |
| Others |
Supply & Pricing Matrix
Captive in-house plating capacity at automotive tier-1 suppliers anchors both supply security and pricing power against merchant job-shop networks. This backward integration into electroless nickel systems insulates Stuttgart and Detroit manufacturers from palladium catalyst volatility while compressing margins for independent finishers competing on spot contracts.
Pricing Analysis
Warranty-backed chemistry supply contracts bundle technical support and formulation updates into multi-year automotive agreements. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade polycarbonate plating from commodity ABS interior trim. Price differentiation hinges on REACH compliance certification and volume scale. Pricing pressure stems from Chinese domestic formulators achieving technical-grade electroless nickel production. Electronics job-shops in Guangdong exhibit highest price sensitivity due to thinner margin structures.
Supply Chain Analysis
Single-source vulnerability sits with South African and Russian palladium suppliers feeding electroless activation chemistry. Chromic acid etching additives concentrate among German and Chinese formulators. Raw material dependencies span palladium salts, nickel sulfate, and chromic acid. Supply chain risk centers on precious metal price volatility disrupting job-shop cost structures. Distribution runs through chemical suppliers with captive equipment divisions serving automotive OEMs directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around operators with zero-liquid-discharge infrastructure as MEE wastewater standards in Jiangsu and Guangdong force capital-intensive upgrades that weaker players cannot finance.
For Market Incumbents: Hedge against palladium catalyst volatility through long-term offtake agreements with South African mining operations. Secure dual-continent plating capability as qualification thresholds tighten at German and Japanese OEMs. Invest in captive trivalent chromium formulation capacity ahead of REACH authorization deadlines. For New Entrants and Emerging Players: REACH substance restrictions in Europe open a window for compliant plating chemistry suppliers to capture automotive interior trim contracts. Target India's PLI scheme corridors in Noida and Chennai for electronics housing capacity. Enter through direct metallization technology partnerships that bypass traditional job-shop networks. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated chemical-equipment providers seeking captive formulation assets. Five-to-ten year viability favors operators with zero-liquid-discharge infrastructure in regulated Chinese clusters. Watch for MEE enforcement intensity in Guangdong as the inflection signal for consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palladium Supply | Long-term offtake agreements with South African miners stabilize electroless plating cost structures. |
| Zero-Liquid-Discharge Capacity Buildout | MEE wastewater standards in Jiangsu province reward first-movers with regulatory compliance advantage. |
| Trivalent Chromium Formulation Investment | REACH authorization deadlines in Europe create captive demand for compliant plating chemistry. |
| Dual-Continent Plating Capability | German and Japanese OEMs now require geographic redundancy as supplier qualification threshold. |
| Direct Metallization Technology Licensing | Automotive tier-1 suppliers in Detroit decentralize volume from traditional merchant job-shop networks. |
Research Methodology
Multi-period observation of palladium price volatility, MEE enforcement intensity, and REACH authorization timelines anchored the trend analysis, supplemented by interviews with plating line engineers, automotive tier-1 procurement leads, chemical formulator R&D directors, and electronics job-shop operators. Secondary validation drew from EPA effluent guideline filings, ECHA substance restriction databases, Chinese MEE discharge standard updates, and SEC 10-K disclosures from listed chemical suppliers. Bottom-up capacity assessments across Guangdong and Jiangsu clusters were triangulated against top-down automotive production forecasts.
Input-output matrices mapped electroless nickel consumption to 5G infrastructure deployment and automotive lightweighting mandates across the projection horizon. Segmentation dimensions modeled include plating method, plastic substrate type, end-use industry, and regional regulatory cluster. CAGRs were derived from iterative convergence of demand-side adoption curves and supply-side capacity expansion schedules. Industry-specific forecast inputs incorporated palladium market dynamics and trivalent chromium conversion rates at European automotive OEMs.
Caveats apply where palladium supply disruptions or accelerated REACH substance bans could materially shift the outlook for electroless plating economics. Forecasts reflect assumptions about MEE enforcement consistency and automotive OEM qualification timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Plastic Contract Manufacturing Market
Industrial Chemicals
Global Cyanuric Chloride Market
Industrial Chemicals
Honing Oil Market
Industrial Chemicals
Process Chromatography Market
Industrial Chemicals
Cryogenic Column Market
Industrial Chemicals
Food Grade Sodium Hypochlorite Market
Industrial Chemicals
Detergent Making Machinery Market
Industrial Chemicals
Antiscalant Market
Industrial Chemicals
CDU Heat Exchanger Antifoulants Market
Industrial Chemicals
HFO (Hydrofluoro-Olefin) Refrigerants Market
Industrial Chemicals
Surface Treatment Chemicals Market
Industrial Chemicals
North America Molecular Sieve Market
Industrial Chemicals
Rodenticides Market
Industrial Chemicals
Kraft Lignin Products Market
Industrial Chemicals
Global Electronic Grade Sulfuric Acid Market
Industrial Chemicals
Screw Separators Market