
 Sulphur Recovery Technologies Market | 2026-2036
Sulphur Recovery Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Sulphur Recovery Technologies Market Outlook
Middle Eastern engineering contractors is consolidating around large integrated refinery and gas processing projects. Fluor Corporation leverages its modular construction expertise to reduce field assembly time for offshore sulphur recovery trains. Shell PLC anchors its position through proprietary SuperClaus technology licensing across European and Asian downstream complexes. Bechtel Corporation competes on mega-project execution capability for greenfield refinery installations in North America.
Sulphur recovery technologies encompass thermal, catalytic, and solvent-based processes designed to extract elemental sulphur from hydrogen sulphide streams, with Claus units typically achieving recovery rates above 95 percent through staged catalytic conversion. These systems serve primarily to convert toxic acid gas byproducts into saleable elemental sulphur while ensuring atmospheric emissions compliance. The technology dimension shows Claus Process installations dominating existing capacity bases while SuperClaus retrofits capture margin pools from efficiency-focused operators. Application demand concentrates in refineries processing high-sulphur crude slates, with natural gas processing representing the fastest-growing segment as sour gas developments expand.
The EPA enforces refinery sector emissions standards that mandate minimum sulphur recovery efficiency, while the EU F-Gas Regulation and REACH framework constrain process chemical selection and venting protocols. India's Central Pollution Control Board implements refinery emission norms that drive adoption of extended Claus configurations and tail gas treatment units. Stakeholders must monitor regulatory tightening in major refining corridors and assess whether current technology portfolios satisfy next-phase recovery efficiency thresholds.
Market Dynamics
Refinery operators face mounting pressure to retrofit Claus units as the EPA's updated emissions standards and China's dual carbon goals force wholesale technology replacement cycles across high-sulphur crude processing corridors.
Growth Catalysts
- EPA Refinery Sector Rules:The EPA mandates minimum sulphur recovery efficiency thresholds that accelerate Claus unit upgrades and tail gas treatment installations across United States Gulf Coast processing clusters.
- Natural gas processing:Sour gas developments in the Middle East and Central Asia drive fastest-growing application demand for incremental sulphur capture capacity.
- Dual carbon goals:China's MEE enforcement of carbon intensity targets pushes domestic refiners toward SuperClaus retrofits and extended recovery configurations.
Market Restraints
- Catalyst supply concentration:Specialty alumina and titania catalyst production concentrates in German and Japanese chemical suppliers, exposing operators to input cost volatility and extended lead times.
- Technical limitation:Conventional Claus processes hit thermodynamic ceilings near 97 percent recovery, forcing costly tail gas treatment investments to reach 99.9 percent compliance thresholds.
- EU F-Gas Regulation:REACH framework constraints on process chemical selection and venting protocols complicate solvent-based alternative adoption in European downstream complexes.
Strategic Opportunities
- India's Central Pollution Control Board norms:Refinery emission standards drive adoption of extended Claus configurations and tail gas treatment units across Reliance and Indian Oil installations.
- Modular offshore construction:Fabrication yards in South Korea and Singapore enable skid-mounted sulphur recovery trains that compress field assembly schedules for remote gas processing developments.
- Hydrogen economy convergence:Integration of sulphur recovery with blue hydrogen production streams creates captive acid gas processing demand at carbon capture hubs.
Industry Challenges
- Specialized welding and refractory skills:Field construction of high-temperature Claus reaction furnaces faces acute shortages of certified alloy welders and ceramic installation technicians.
- Legacy control system integration:Digital retrofit of 1980s-era distributed control systems with modern advanced process control creates commissioning delays and operability risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sulphur Recovery Technologies Market |
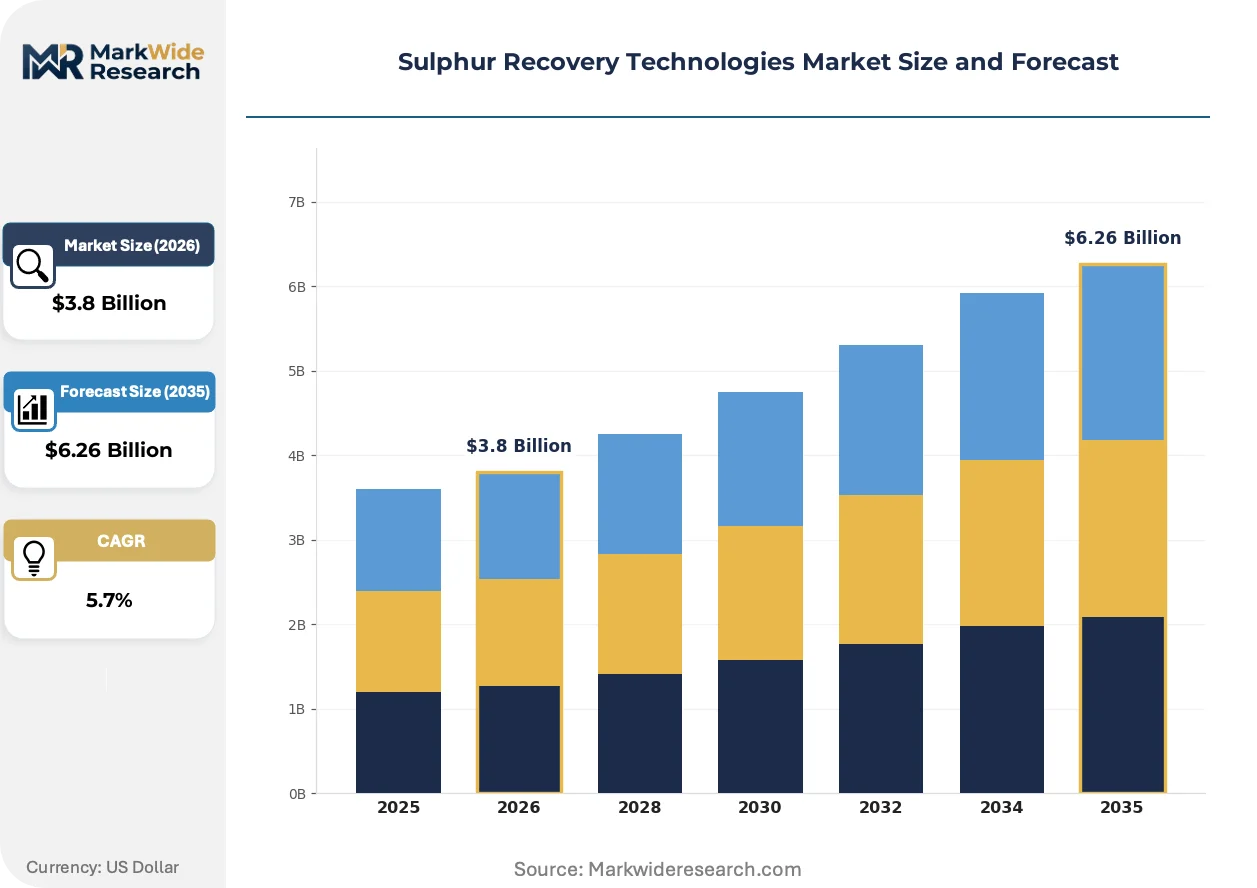
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Claus Process, Rectisol Process, SuperClaus, Biogas Upgrading Application: Refineries, Natural Gas Processing, Petrochemical Industries, Chemical Manufacturing End User: Oil & Gas Companies, Chemical Manufacturers, Power Plants, Waste Management Facilities Installation Type: Onshore, Offshore, Modular, Fixed |
| Companies Covered | WorleyParsons Limited, Fluor Corporation, Bechtel Corporation, Shell PLC, Air Liquide SA, Chiyoda Corporation, Black & Veatch, Amec Foster Wheeler, Enersul Limited Partnership, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sulphur Recovery Technologies Market Strategic Shifts
Technology suppliers are racing to commercialize next-generation catalytic systems and modular construction methods that compress project timelines while pushing recovery efficiency past conventional thermodynamic limits.
Oxygen-enriched Claus technology is rewriting project economics for high-capacity refinery expansions. Operators in the United States Gulf Coast and Middle East are adopting air separation unit integration to double throughput within existing footprints. This approach is compressing greenfield construction demand while enabling brownfield debottlenecking at a fraction of historical capital intensity.
The EU F-Gas Regulation and REACH framework are forcing solvent selection revisions across European gas processing installations. Industrial consequence includes accelerated phase-out of fluorinated absorption chemicals in favour of proprietary amine formulations. German and Dutch refiners are responding by front-loading tail gas treatment investments to preempt 2027 compliance deadlines.
Engineering-procurement-construction contracts are unbundling into separate technology licensing and modular fabrication awards. Large refinery operators now source SuperClaus licences directly from Shell while contracting construction to specialist module yards. This pattern is most visible in Middle Eastern integrated refinery and gas processing projects where schedule certainty outweighs single-source accountability.
Sulphur Recovery Technologies Market Segmentation
Sulphur recovery technology selection directly determines capital intensity, emissions compliance pathways, and operational flexibility across downstream processing corridors. Segment boundaries reflect divergent certification burdens, with offshore and modular installations triggering marine classification society approvals absent from onshore fixed configurations.
Technology:
EPA refinery sector rules and China's MEE carbon intensity enforcement create tiered approval landscapes—Claus units face baseline efficiency mandates while SuperClaus retrofits trigger enhanced monitoring protocols under EU REACH chemical registration.
- Claus Process:Staged catalytic conversion of hydrogen sulphide through thermal reaction furnaces and catalytic reactors achieves recovery rates approaching 97 percent. United States Gulf Coast refiners processing high-sulphur Maya and Venezuelan crudes anchor demand, though thermodynamic ceilings force costly tail gas treatment add-ons for 99.9 percent compliance.
- SuperClaus:Extended oxidation catalyst beds push recovery past conventional limits without full tail gas treatment trains. Shell's proprietary licensing dominates European and Asian downstream complexes where China's dual carbon goals accelerate retrofit cycles at Sinopec and PetroChina installations.
- Rectisol Process:Low-temperature methanol absorption for bulk acid gas removal in syngas and natural gas processing.
- Biogas Upgrading:Emerging solvent-based and membrane configurations for renewable natural gas purification.
Claus Process installations sit at the top of the volume ranking, with SuperClaus climbing the fastest as efficiency-focused operators prioritize brownfield debottlenecking over greenfield construction.
Application:
Cost tier stratification separates mega-refinery investments exceeding $500 million from mid-scale gas processing deployments, with petrochemical integration commanding premium engineering margins.
- Refineries:Complex acid gas handling from coker, hydrocracker, and fluid catalytic cracker offgases demands multi-train Claus configurations. Reliance Jamnagar and Indian Oil refineries drive India's Central Pollution Control Board-mandated tail gas treatment upgrades.
- Natural Gas Processing:Sour gas developments in Kazakhstan's Tengiz and Shah Deniz Phase 2 expansions require incremental sulphur capture for pipeline specification compliance. This segment expands most quickly as Middle Eastern and Central Asian field developments accelerate.
- Petrochemical Industries:Steam cracker and gasification byproduct processing for ammonia and methanol feedstock production.
- Chemical Manufacturing:Carbon disulphide and sulphuric acid production integration with captive acid gas sources.
Refinery applications dominate current installed base value, though natural gas processing gains share fastest on sour gas development timelines.
End User:
Customer type determines procurement leverage—integrated supermajors negotiate direct technology licenses while independent operators bundle through EPC contractors.
- Oil & Gas Companies:ExxonMobil, Aramco, and ADNOC anchor project pipelines with standardized Claus specifications across global refining and gas processing portfolios.
- Chemical Manufacturers:BASF and Dow operate captive sulphur recovery for sulphuric acid and fertilizer intermediate production.
- Power Plants:Integrated gasification combined cycle facilities with acid gas removal for turbine fuel conditioning.
- Waste Management Facilities:Landfill gas and anaerobic digester biogas upgrading for renewable natural gas injection.
Oil & Gas companies command the largest procurement volumes, with chemical manufacturers expanding most aggressively on fertilizer and industrial chemical capacity additions.
Installation Type:
Supply concentration in South Korean and Singapore fabrication yards shapes modular project economics, while fixed onshore construction faces certified welder shortages across North American and European labor markets.
- Modular:Skid-mounted sulphur recovery trains fabricated in controlled yard environments compress field assembly schedules. Fluor Corporation leverages this approach for remote Middle Eastern gas processing developments where schedule certainty outweighs single-source accountability.
- Onshore:Conventional stick-built construction for large refinery complexes with established infrastructure and maintenance access.
- Offshore:Platform-integrated compact Claus units for FPSO and fixed platform acid gas processing, requiring ABS or DNV marine classification approvals.
- Fixed:Permanent installations with 25-year design life for anchor refinery and gas processing hubs.
Onshore fixed installations retain the largest cumulative installed base, with modular configurations gaining fastest on offshore and remote gas processing demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping sulphur recovery investment flows as refiners migrate capacity toward jurisdictions with phased compliance timelines. The cost-of-compliance gap between mature environmental regimes and emerging enforcement zones drives technology deployment patterns across downstream processing corridors.
United States
Gulf Coast coker and hydrocracker expansions at ExxonMobil Baytown and Motiva Port Arthur demand incremental Claus capacity. EPA refinery sector rules mandate minimum recovery efficiency thresholds that accelerate tail gas treatment installations. The Texas-Louisiana processing cluster concentrates brownfield retrofit demand as operators face 2025-2027 compliance deadlines.
China
Sinopec and PetroChina refineries processing high-sulphur Middle Eastern crudes require SuperClaus retrofits to meet carbon intensity targets. MEE enforcement of dual carbon goals pushes domestic operators toward extended recovery configurations. The Shandong and Yangtze River Delta refining corridors anchor technology replacement cycles at state-owned installations.
India
Reliance Jamnagar and Indian Oil refineries drive tail gas treatment upgrades under Central Pollution Control Board emission norms. The regulator mandates extended Claus configurations for facilities processing sour domestic and imported crudes. Gujarat's Koyali and Vadodara refining complexes concentrate procurement activity for multi-train sulphur capture systems.
Germany
REACH framework constraints and EU F-Gas Regulation accelerate solvent selection revisions at BASF Ludwigshafen and Shell Rheinland. German refiners front-load tail gas treatment investments to preempt 2027 compliance deadlines. The Rhineland petrochemical corridor anchors demand for proprietary amine formulations replacing fluorinated absorption chemicals.
Saudi Arabia
Aramco's Jazan and Satorp joint ventures require integrated sulphur recovery for high-sulphur crude processing and gas treatment. The national oil company standardizes Claus specifications across greenfield refinery and gas processing portfolios. The Eastern Province industrial zone concentrates mega-project execution demand for modular offshore and onshore installations.
Sulphur Recovery Technologies Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue modular fabrication and digital retrofit specializations. The vendor base clusters around three strategic archetypes: integrated engineering-procurement-construction contractors, technology licensors with proprietary catalytic systems, and specialist module fabricators serving remote gas processing developments. Competitive positioning hardens through technology licensing unbundling and schedule-certain construction awards. Market participants defend margin positions via direct licensor relationships and captive fabrication yard access.
Within the integrated EPC tier, Fluor Corporation and Bechtel Corporation exemplify scale-driven execution capability for North American and Middle Eastern mega-projects. Shell PLC anchors the technology licensor archetype through proprietary SuperClaus positioning across European and Asian downstream complexes. WorleyParsons Limited occupies a position within the specialist engineering segment serving offshore and remote gas processing developments. These three company structures represent divergent competitive vectors: construction-led, technology-led, and geography-led respectively.
| Leading Market Players |
|---|
| WorleyParsons Limited |
| Fluor Corporation |
| Bechtel Corporation |
| Shell PLC |
| Air Liquide SA |
| Chiyoda Corporation |
| Black & Veatch |
| Amec Foster Wheeler |
| Enersul Limited Partnership |
| Others |
Value Chain & Pricing Dynamics
Certified alloy welder shortages across Texas and Louisiana compress field construction margins while expanding pricing spreads between premium SuperClaus retrofits and standard Claus unit replacements. Labor-cost differentials between Gulf Coast fabrication yards and South Korean module shops directly determine the premium tier for schedule-certain offshore deliveries.
Pricing Analysis
Distributor margins on specialty alumina and titania catalysts widen pricing spreads between European and Asian supply channels. Project-based contracting dominates, with price differentiation resting on catalyst certification grade and volume scale. Cost compression in standard Claus configurations is intensifying because German and Japanese chemical suppliers extend lead times. Independent refinery operators exhibit highest price sensitivity, while integrated supermajors prioritize schedule certainty over unit economics.
Supply Chain Analysis
Welder availability constraints in North American and European labor markets force module fabrication concentration toward South Korea and Singapore. Geographic supply centers on Germany and Japan for specialty catalysts, with China capturing growing share of amine solvent production. Raw material dependencies include high-purity alumina, titanium dioxide, and proprietary oxidation catalyst substrates. Single-source vulnerability concentrates in titania catalyst supply. Distribution runs through engineering-procurement-construction contractors unbundling into separate technology licensing and modular fabrication awards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EPA-mandated tail gas treatment investments in the United States Gulf Coast run 18-24 months ahead of India's Central Pollution Control Board enforcement timeline, creating phased procurement windows for identical technology configurations.
For Market Incumbents: Anticipate margin erosion from modular construction specialists capturing offshore project share. Deepen backward integration into captive catalyst production to offset German and Japanese supplier concentration. Prioritize direct licensing relationships with Sinopec and Aramco to preempt EPC unbundling trends. For New Entrants and Emerging Players: Mid-scale Indian refiners under Central Pollution Control Board compliance deadlines represent the most penetrable buyer archetype. Target Reliance and Indian Oil tail gas treatment upgrade pipelines with skid-mounted configurations. Pursue partnership routes with South Korean fabrication yards to compress field assembly schedules. For Investors and Strategic Acquirers: Valuations sit cheapest among specialist module fabricators with captive yard access in Singapore or South Korea. Five-to-ten year viability hinges on hydrogen economy convergence creating captive acid gas processing demand. Watch carbon capture hub announcements as inflection indicators for sulphur recovery technology bundling.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Unbundling | Shell's direct SuperClaus licensing to Sinopec bypasses traditional EPC markups. |
| Modular Fabrication Scale-Up | Fluor's Singapore yard expansion compresses schedules for Shah Deniz Phase 2. |
| Backward Integration into Catalysts | Captive alumina production insulates against German supplier lead time volatility. |
| Hydrogen Economy Convergence | Blue hydrogen carbon capture hubs create integrated acid gas processing demand. |
| Digital Control System Retrofit | Advanced process control upgrades at 1980s-era Claus units reduce operability risks. |
Study Parameters
Multiple input streams — regulatory filing analysis, EPC contract documentation, and catalyst procurement databases — were reconciled against primary interviews with refinery operations directors, environmental compliance officers, and technology licensing managers. Secondary validation drew from EPA enforcement records, EU REACH chemical registration filings, and customs trade data on specialty catalyst imports. Bottom-up project pipeline enumeration and top-down refinery capacity modeling were triangulated to establish market sizing.
Data-stream reconciliation across technology type, application segment, and installation configuration anchored the analytical framework over the projection horizon. Segmentation dimensions modeled include process technology tier, end-use industry, and regional regulatory cluster. CAGRs were derived from weighted average of unit deployment forecasts and capital intensity trends. Industry-specific inputs incorporated sour gas development timelines in Kazakhstan and carbon intensity enforcement trajectories under China's MEE.
Underlying measurement precision varies by segment; SuperClaus retrofit volumes carry tighter precision than emerging biogas upgrading applications. Forecasts reflect assumptions on regulatory enforcement timing and catalyst supply chain stability. Material deviation in EPA compliance deadline extensions or German catalyst export restrictions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Draft Tube Baffle (DTB) Crystallizers Market
Industrial Chemicals
India Precipitated Silica Market
Industrial Chemicals
Knitting Oils Market
Industrial Chemicals
Butadiene Extraction Market
Industrial Chemicals
Middle East and Africa Non-Phthalate Plasticizers Market
Industrial Chemicals
1,3-Propanediol (PDO) Market
Industrial Chemicals
Industrial Closures Market
Industrial Chemicals
Aerosol Sprayers Market
Industrial Chemicals
Dipropylene Glycol (DPG) Market
Industrial Chemicals
Toluene Diisocyanates (TDI) Market
Industrial Chemicals
Global Battery Grade Lithium Hydroxide Market
Industrial Chemicals
Aminic Antioxidants Market
Industrial Chemicals
Oilfield Scale Inhibitors Market
Industrial Chemicals
Mining Explosives Consumables Market
Industrial Chemicals
Fluidizers in Plasterboard Market
Industrial Chemicals
Explosion Venting Market