
 Surface Green Mining Market | 2026-2036
Surface Green Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Green Mining Market Insights
Software-defined fleet management is decoupling equipment ownership from operational control in surface green mining. Rio Tinto leverages autonomous haulage networks across its Pilbara iron ore operations. Komatsu anchors its position through integrated electric drive systems for ultra-class trucks. Caterpillar differentiates via predictive maintenance platforms that extend asset life cycles.
Surface green mining encompasses open-pit and strip extraction methods utilizing electrified, autonomous, and low-emission equipment to minimize land disturbance, water consumption, and carbon output while recovering target minerals. Hydraulic shovels and hybrid excavators dominate capital deployment, with power ratings exceeding 1,000 kW enabling single-pass loading of 400-ton haul trucks. Autonomous haulage systems command premium pricing due to integration complexity and safety certification requirements. Mineral extractors and green processing equipment concentrate margin pools where OEMs bundle emissions monitoring with hardware sales.
EPA tailpipe standards and OSHA silica exposure limits shape equipment specifications in US surface operations. The EU F-Gas Regulation and REACH chemical restrictions constrain coolant and lubricant choices for European fleets. Australia's Clean Energy Regulator and state-based mine rehabilitation bonds drive adoption of land rehabilitation technologies. Stakeholders must weigh electrification capex against regulatory compliance timelines and residual fuel infrastructure value.
Market Dynamics
Electrification of ultra-class haul fleets is restructuring capital allocation across open-pit operations, with powertrain decisions now binding 15-year asset cycles to grid decarbonization trajectories rather than fuel hedging strategies.
Growth Catalysts
- EU Carbon Border Adjustment Mechanism:Import charges on embodied carbon in processed minerals are forcing Australian and Chilean exporters to certify emissions from extraction through port loading.
- Autonomous haulage integration:Mine operators in the Pilbara and Atacama are retrofitting existing truck fleets with perception systems and V2X communication modules rather than full replacement.
- Lithium:Direct shipping ore requirements from battery cell manufacturers are pulling investment into sensor-based ore sorting that reduces downstream processing energy intensity.
Market Restraints
- Grid interconnection queues:Remote mine sites in Western Australia and northern Chile face 3-5 year delays for transmission upgrades needed to support 10+ MW charging infrastructure for electric haul trucks.
- Copper concentrate:Smelter capacity concentration in China creates pricing power asymmetry that compresses margins for green-certified concentrate producers elsewhere.
- Battery energy density:Current lithium-ion cell chemistry limits electric ultra-class trucks to 400-ton payload capacity versus 500+ tons for diesel equivalents, constraining productivity in deep-pit operations.
Strategic Opportunities
- Kazakhstan:Untapped copper porphyry belts with legacy Soviet rail infrastructure offer lower-carbon logistics integration for operators willing to accept sovereign risk exposure.
- Green hydrogen:Fuel cell retrofit kits for existing diesel haul trucks are emerging as a bridge technology where grid extension proves uneconomical.
- EU F-Gas Regulation phase-down:Accelerated refrigerant transition timelines are creating aftermarket demand for electric air conditioning systems in operator cabins across European-owned African operations.
Industry Challenges
- Electrical trades:Shortage of high-voltage technicians capable of maintaining 1,000+ kW drive systems is extending mean time to repair and inflating service contract premiums.
- ISO 14064-1 verification:Third-party carbon accounting certification for Scope 1 and 2 emissions requires 18-24 month implementation cycles that misalign with annual procurement tenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface Green Mining Market |
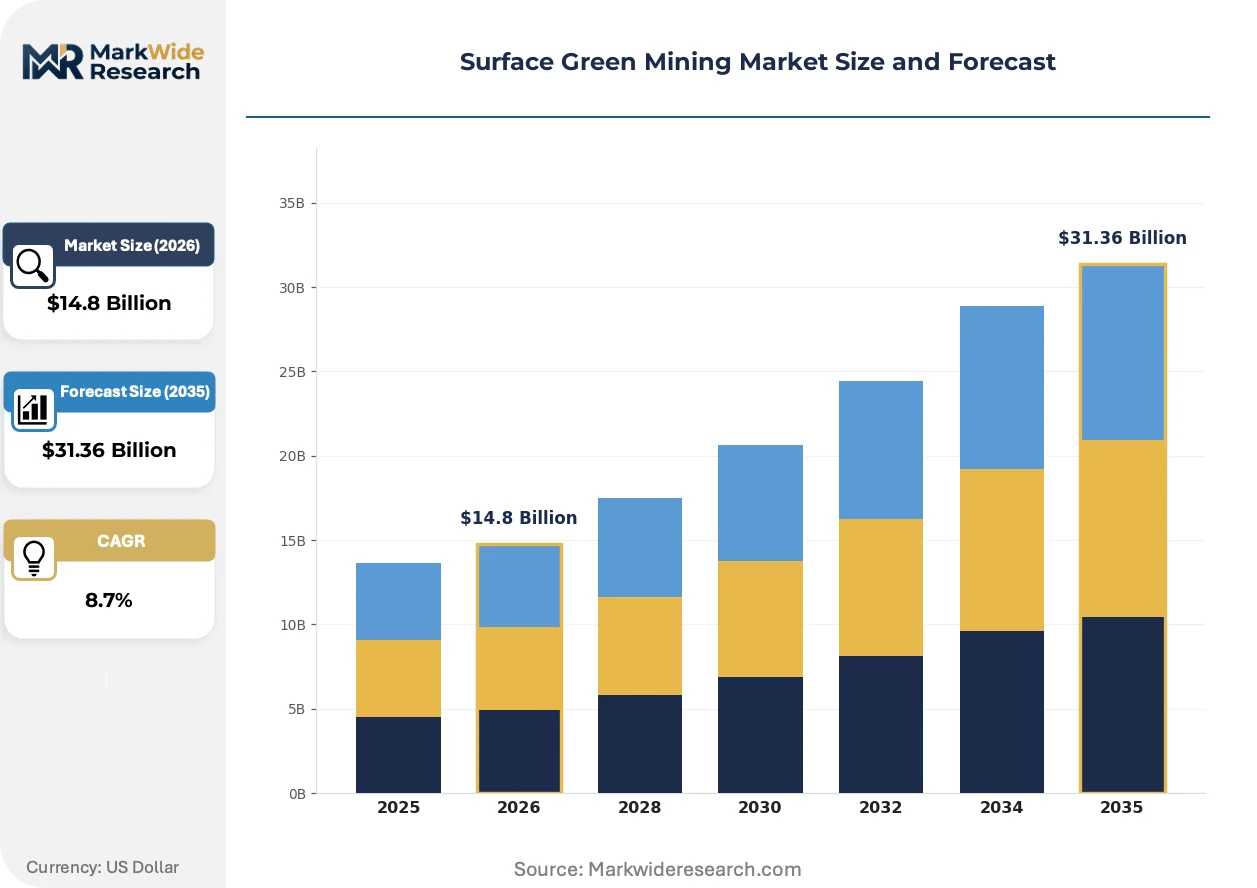
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Hydraulic Shovels, Electric Drills, Autonomous Haulage Systems, Hybrid Excavators Product Type: Mineral Extractors, Waste Management Systems, Eco-friendly Machinery, Green Processing Equipment End User: Mining Companies, Environmental Consultants, Government Agencies, Research Institutions Application: Mineral Extraction, Site Remediation, Resource Recovery, Land Rehabilitation |
| Companies Covered | Rio Tinto, Anglo American, BHP, Glencore, Vale S.A., Freeport-McMoRan, Caterpillar, Komatsu, Liebherr, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Green Mining Market Trends and Innovations
Software-defined control architectures are decoupling hardware refresh cycles from operational capability upgrades, allowing mine operators to extend asset life through over-the-air functionality deployment.
High-voltage battery-electric powertrains for 240-ton class haul trucks are electrifying the mid-tier fleet segment previously considered uneconomical for full electrification. Contractors operating shorter haul cycles in strip mining configurations are adopting these platforms faster than deep-pit operators. The technology is compressing the total cost of ownership parity point against diesel from 2030 projections to current deployment decisions.
EPA tailpipe standards for non-road diesel engines are tightening particulate matter limits to 0.015 g/kWh for engines above 560 kW. US surface coal and metal operations must either retrofit exhaust aftertreatment systems or accelerate electric transition timelines. The regulation is driving aftermarket demand for engine repower kits in Appalachia and the Powder River Basin.
Equipment-as-a-service contracting is displacing traditional capital purchase models for autonomous haulage systems. Mining contractors in Western Australia are preferring per-ton-mile pricing structures that transfer technology obsolescence risk to OEMs. This shift is most visible among mid-tier iron ore producers lacking balance sheet capacity for 300+ million dollar fleet commitments.
Surface Green Mining Market Segmentation
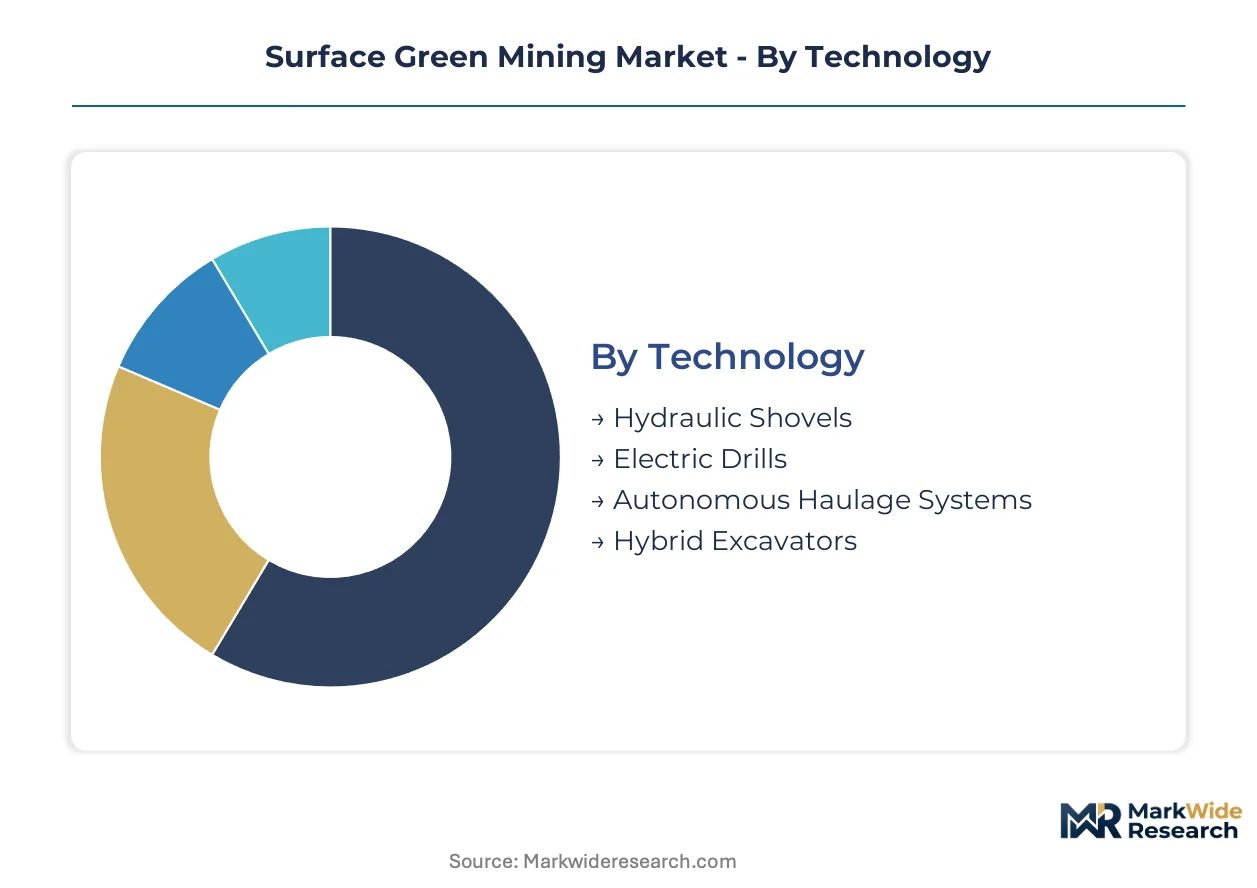
Segmentation in surface green mining reveals how capital flows cluster around electrification-ready equipment versus legacy retrofits. Understanding these divisions helps suppliers align R&D pipelines with regulatory enforcement timelines and ore-body geology constraints.
Technology:
Standalone electrified platforms dominate greenfield investments, while embedded autonomy modules retrofit existing fleets at brownfield sites.
- Hydraulic Shovels:These 1,000+ kW loading platforms integrate electric drive systems for single-pass filling of ultra-class haul trucks. Australian iron ore operators in the Pilbara specify these for 24-hour continuous duty cycles where grid stability supports high-voltage charging.
- Autonomous Haulage Systems:Perception arrays and V2X communication modules transform conventional trucks into self-navigating fleets. Chilean copper porphyry operations favor retrofit kits over full replacement to preserve residual diesel asset value during 15-year electrification transitions.
- Electric Drills:Blasthole rigs with battery-electric powertrains eliminate diesel particulate exposure in confined pit benches.
- Hybrid Excavators:Dual-power systems blend grid electricity with onboard generation for mobility between remote excavation faces.
Hydraulic shovels lead volumes today; autonomous haulage systems are gaining share fastest.
Product Type:
Margin concentration follows hardware-software bundling intensity, with emissions monitoring platforms commanding premium pricing over standalone machinery.
- Mineral Extractors:Electrified shovels, drills, and loading equipment form the core capital deployment category. OEMs bundle predictive maintenance software with hardware sales to lock in decade-long service contracts.
- Green Processing Equipment:Sensor-based ore sorting and dry-stack tailings systems reduce downstream energy intensity. Battery cell manufacturers in South Korea and Japan specify direct shipping ore standards that pull investment into these pre-concentration technologies.
- Waste Management Systems:Automated tailings handling and water recovery infrastructure supports closed-loop operations.
- Eco-friendly Machinery:Low-emission auxiliary equipment including electric lighting towers and charging stations.
Mineral extractors anchor current procurement volumes; green processing equipment shows the steepest expansion trajectory as battery supply chains tighten ore quality specifications.
End User:
Balance sheet capacity determines procurement model preference, with asset-heavy miners favoring ownership and contractors shifting toward equipment-as-a-service structures.
- Mining Companies:Integrated majors deploy electrified fleets across owned operations, binding 15-year asset cycles to grid decarbonization trajectories. Rio Tinto and BHP anchor demand through direct OEM relationships that secure allocation priority during supply-constrained periods.
- Environmental Consultants:Third-party verification firms specify monitoring equipment for ISO 14064-1 carbon accounting compliance. These actors intermediate between extractors and EU Carbon Border Adjustment Mechanism enforcement, creating pull-through demand for emissions tracking hardware.
- Government Agencies:State mining departments procure rehabilitation technologies for bond compliance and post-closure site management.
- Research Institutions:Universities and national laboratories pilot next-generation extraction methods including in-situ leaching and bio-mineralization.
Mining companies dominate absolute spend; environmental consultants are expanding most quickly as carbon certification timelines compress.
Application:
Revenue timing diverges between extraction (immediate, volume-based) and rehabilitation (deferred, compliance-triggered) use cases.
- Mineral Extraction:Open-pit and strip mining operations deploy electrified loading and hauling equipment to reduce Scope 1 emissions. Copper and lithium operations in Chile and Australia concentrate demand as both nations accelerate decarbonization of major mineral belts.
- Land Rehabilitation:Post-closure restoration technologies including automated re-vegetation and soil stabilization systems. Australia's Clean Energy Regulator and state-based mine rehabilitation bonds create enforceable demand timelines that pull capital into this category ahead of actual site closure dates.
- Site Remediation:Contaminated soil and groundwater treatment at legacy mining properties.
- Resource Recovery:Reprocessing of tailings and waste rock for secondary metal extraction.
Mineral extraction commands current capital allocation; land rehabilitation is climbing the fastest as regulatory bond structures harden closure obligations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia and Chile concentrate surface green mining technology adoption, while Kazakhstan's untapped copper belts attract operators willing to navigate sovereign risk for lower-carbon logistics integration.
Australia
Pilbara iron ore operations anchor electrified fleet deployment through 24-hour continuous duty cycles. The Clean Energy Regulator and state-based mine rehabilitation bonds enforce land restoration technology procurement ahead of closure dates. Perth-based service clusters support high-voltage technician training for 1,000+ kW drive system maintenance.
Chile
Atacama copper porphyry operations favor autonomous haulage retrofit kits over full fleet replacement during 15-year electrification transitions. The national mining regulator aligns with EU Carbon Border Adjustment Mechanism enforcement timelines for Scope 1 emissions certification. Antofagasta mineral corridors concentrate demand for sensor-based ore sorting that meets direct shipping ore specifications from battery cell manufacturers.
United States
Appalachian surface coal and Powder River Basin metal operations face EPA tailpipe standards tightening particulate matter limits to 0.015 g/kWh for engines above 560 kW. OSHA silica exposure limits shape equipment specifications alongside EPA enforcement. Arizona copper districts deploy predictive maintenance platforms that extend asset life cycles under capital constraints.
Kazakhstan
Legacy Soviet rail infrastructure offers lower-carbon logistics integration for copper porphyry belt development. The national mining code is adapting to attract foreign operators for greenfield electrified extraction. Karaganda industrial zones concentrate early pilot deployments of fuel cell retrofit kits where grid extension proves uneconomical.
Germany
Ruhr Valley equipment manufacturers supply integrated electric drive systems for ultra-class trucks across export markets. The EU F-Gas Regulation and REACH chemical restrictions constrain coolant and lubricant choices for European fleet operators. Düsseldorf engineering clusters develop software-defined fleet management architectures that decouple equipment ownership from operational control.
Surface Green Mining Market Competitive Landscape
Top-tier vendors anchor integrated electrification systems, while mid-tier specialists occupy retrofit autonomy modules and emissions monitoring platforms. The vendor structure consolidates around full-stack OEMs bundling hardware with decade-long service contracts, with fragmentation persisting in aftermarket retrofit and verification services. Two strategic archetypes dominate: diversified mining majors operating captive technology development programs, and pure-play equipment manufacturers licensing autonomy stacks to contractor fleets. Competitive moves concentrate on equipment-as-a-service contracting structures and strategic partnerships for high-voltage charging infrastructure deployment.
Within the diversified mining major archetype, Rio Tinto and BHP exemplify operators binding 15-year asset cycles to grid decarbonization trajectories through direct OEM relationships. Among equipment-focused manufacturers, Komatsu occupies a position representing integrated electric drive system development, while Caterpillar sits within the predictive maintenance platform tier that extends asset life cycles. These three entities collectively illustrate how balance sheet capacity and technology licensing strategies are bifurcating competitive positioning across ownership-heavy and service-contracting procurement models.
| Leading Market Players |
|---|
| Rio Tinto |
| Anglo American |
| BHP |
| Glencore |
| Vale S.A. |
| Freeport-McMoRan |
| Caterpillar |
| Komatsu |
| Liebherr |
| Others |
Pricing and Supply Chain Analysis
Backward integration into high-voltage battery cell production anchors both supply security and pricing power for OEMs bundling electrified haul systems with decade-long service contracts. Komatsu and Caterpillar leverage captive cell sourcing to offset grid interconnection delays that inflate charging infrastructure costs for Australian and Chilean operators.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for integrated electric drive systems as Ruhr Valley manufacturers expand output. Equipment-as-a-service contracting dominates, with per-ton-mile structures transferring obsolescence risk to OEMs. Price differentiation rests on autonomy integration depth and ISO 14064-1 certification bundling. Cost compression in retrofit autonomy modules is intensifying because electrical trades shortages extend service contract premiums. Mid-tier contractors show highest price sensitivity; integrated majors with direct OEM relationships exhibit lowest.
Supply Chain Analysis
ISO 14064-1 verification requirements gate supplier qualification for emissions monitoring hardware bundled with ultra-class trucks. Manufacturing concentrates in Germany, Japan, and the United States for integrated drive systems. Cell chemistry draws from lithium carbonate processed in Chile and Australia, plus refined cobalt from the DRC. Single-source vulnerability runs through high-voltage power electronics fabrication. Distribution runs through Perth and Antofagasta service clusters supporting Pilbara and Atacama operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surface green mining operates as a geographic-arbitrage play where Kazakhstan's legacy rail infrastructure offers lower-carbon logistics costs against Australian grid interconnection premiums.
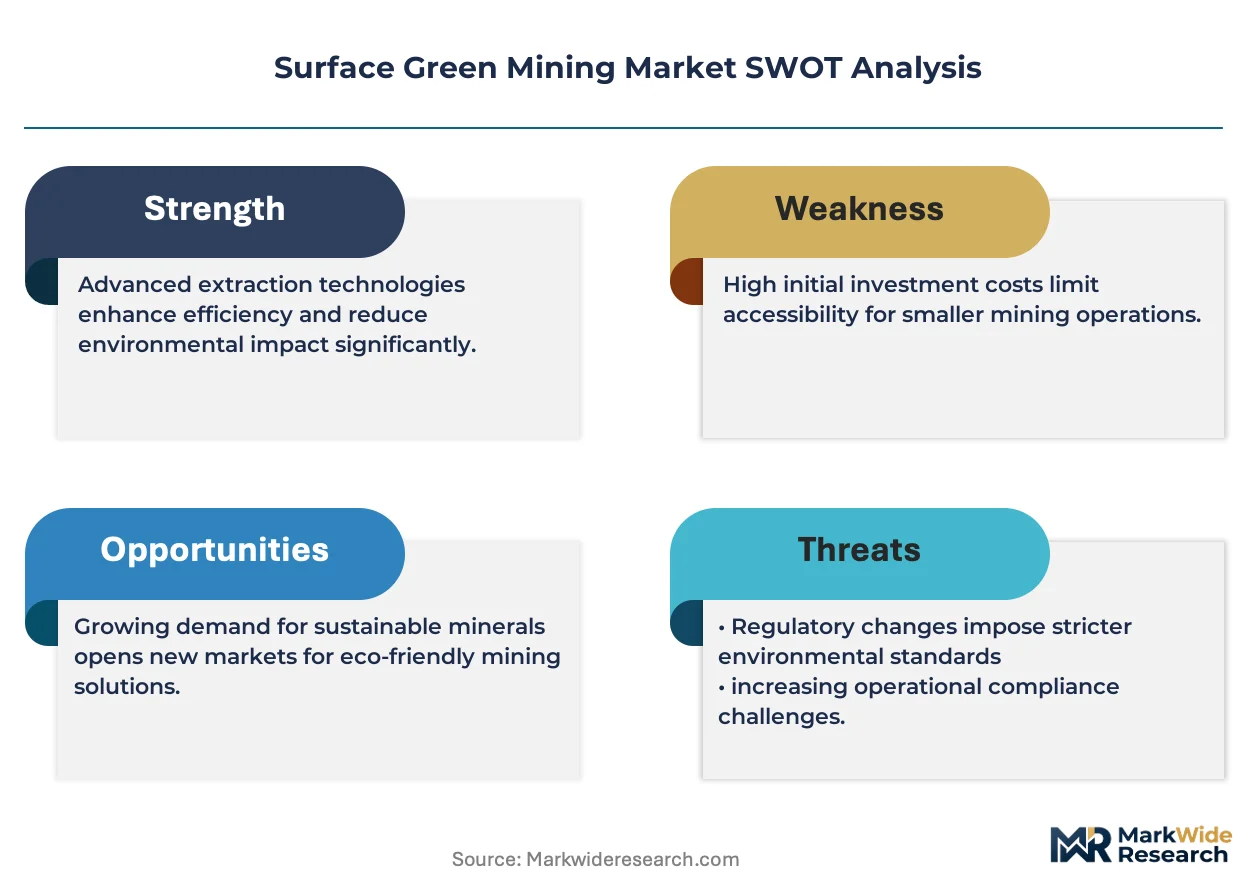
For Market Incumbents: Anticipate margin compression from fuel cell retrofit kit specialists attacking the bridge-technology window before grid extension completes. Lock in high-voltage technician training partnerships now. Defend position by accelerating software-defined fleet management deployment that decouples hardware refresh from capability upgrades. For New Entrants and Emerging Players: Enter via Kazakhstan's untapped copper porphyry belts where sovereign risk discounts create first-mover cost advantages. Target environmental consultant intermediaries for EU Carbon Border Adjustment Mechanism compliance hardware. White-space exists in aftermarket electric air conditioning retrofits for African operations facing EU F-Gas Regulation phase-down. For Investors and Strategic Acquirers: Roll-up economics work for emissions verification platforms because ISO 14064-1 certification cycles create sticky 18-24 month customer relationships. Long-term viability favors providers with captive high-voltage maintenance networks. Watch electrical trades graduation rates as inflection indicator for service contract pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Contracting | Per-ton-mile structures transfer technology obsolescence risk from Pilbara contractors to OEMs. |
| Fuel Cell Retrofit Kit Development | Bridge technology captures demand where Chilean grid extension proves uneconomical. |
| High-Voltage Technician Training Partnerships | Perth-based clusters address electrical trades shortages inflating mean time to repair. |
| Sensor-Based Ore Sorting Deployment | Antofagasta corridors adopt pre-concentration to meet Korean battery cell manufacturer specifications. |
| Software-Defined Fleet Management | Over-the-air functionality extends asset life for BHP's 15-year electrification cycles. |
Research Methodology
Coverage spans Australia, Chile, Germany, Kazakhstan, and the United States, with primary inputs from each mining jurisdiction. The analysis combines interviews with mine maintenance directors, OEM procurement teams, environmental consultants, and high-voltage service contractors with secondary validation from EPA filings, EU ETS registry data, Australian Clean Energy Regulator reports, and Chilean mining ministry production statistics. Bottom-up equipment deployment tracking triangulates against top-down mineral output projections.
Granularity extends to powertrain type, autonomy integration level, and procurement model across the projection horizon. The analytical framework models technology, product type, end user, and application dimensions. CAGRs derive from equipment replacement cycle analysis tied to regulatory compliance timelines. Forecast inputs include grid decarbonization trajectories and EU Carbon Border Adjustment Mechanism enforcement schedules.
Inputs from Australian state mining departments and Chilean copper producers were available through the study window; gaps in Kazakh sovereign risk pricing introduce uncertainty bands around Central Asian expansion scenarios. Forecasts reflect assumptions regarding electrical trades training pipeline recovery and lithium-ion energy density improvement curves. A model refresh is warranted upon material change in EU F-Gas Regulation phase-down timelines or high-voltage battery cell chemistry breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Molecular Spectroscopy Market
Others
AC Switchgear Market
Others
Agitation System Market
Others
Security Envelopes Market
Others
Europe Electric Forklift Market
Others
France Automotive LED Lighting Market
Others
Asia-Pacific Medical Simulation Market
Others
Lightweight Compact Wheel Loader Market
Others
Global Digital Market
Others
Asia-Pacific 3D Printing Construction Market
Others
Mobile Computing Devices Market
Others
Military 4D Printing Market
Others
Smart Home Solutions Market
Others
Aircraft Exterior Lighting Market
Others
Global Enterprise Mobility in Healthcare Market
Others
US Tablet Market