
 Global Phablets and Superphones Market | 2026-2036
Global Phablets and Superphones Market Size, Share, and Industry Trends Forecast 2026-2036
Global Phablets and Superphones Market Analysis
Carrier-direct and online retail channels is fragmenting across emerging markets as independent e-commerce platforms gain handset volume. Samsung Electronics anchors premium-tier phablet supply through vertically controlled display foundries. Xiaomi Corporation leverages flash-sale online distribution to sustain margin-thin superphone penetration in Southeast Asia and Latin America. Apple differentiates through locked ecosystem hardware-software integration that commands replacement-cycle loyalty.
Phablets and superphones denote mobile computing devices with diagonal screen measurements exceeding 5.5 inches, typically integrating application processors fabricated on 4nm or 3nm process nodes, high-refresh-rate OLED panels, and multi-band 5G modems for converged productivity and media consumption. The 5G technology segment leads capital allocation as carriers in South Korea, Germany, and Australia retire legacy LTE spectrum. Enterprise Solutions within the Market Segment category shows the fastest structural ascent, driven by fleet-deployment contracts for field technicians and clinical staff requiring stylus-capable large-format screens. OLED display technology captures disproportionate margin pools relative to LCD, reflecting Samsung Display and BOE supply concentration at the substrate level.
FCC equipment authorization and EU CE marking under the Radio Equipment Directive govern RF emissions and interoperability thresholds for devices sold in the United States and European member states. India's BIS compulsory registration scheme and China's MIIT network-access license create asynchronous market-access timelines that fragment product-launch sequencing. E-waste directives including EU WEEE and India's E-Waste Management Rules are forcing modular battery and repairable-design commitments that alter bill-of-materials cost structures. Stakeholders must monitor spectrum reallocation timetables and right-to-repair legislative momentum as determinants of hardware-refresh profitability and regional portfolio prioritization.
Market Dynamics
5G infrastructure buildout is compressing device replacement cycles as carriers in South Korea, Germany, and Australia retire legacy LTE spectrum allocations. This spectrum reallocation forces hardware refreshes across consumer and enterprise segments simultaneously.
Growth Catalysts
- FCC equipment authorization frameworks:The United States regulator's streamlined 5G device certification is accelerating carrier-direct volume commitments for multi-band modems. Field service fleets are upgrading to stylus-capable large-format screens under these timelines.
- Enterprise mobility adoption:Logistics operators and clinical staff are driving fleet-deployment contracts for devices with 6.7-inch and larger diagonal measurements. These contracts standardize on OLED panels for outdoor visibility.
- India's PLI scheme:The production-linked incentive program for electronics manufacturing is attracting display module assembly capacity to Uttar Pradesh and Tamil Nadu. Local value-add requirements are reshaping regional sourcing patterns.
Market Restraints
- Substrate supply concentration:Samsung Display and BOE Technology control disproportionate shares of flexible OLED substrate output. Any disruption at their Gumi or Hefei facilities propagates through premium-tier bill-of-materials.
- MIIT network-access licensing:China's Ministry of Industry and Information Technology mandates asynchronous testing protocols that delay product launches by 8-14 weeks versus FCC timelines. This fragments global portfolio sequencing.
- Raw material cost volatility:Rare-earth magnet prices for haptic feedback motors fluctuate with Myanmar export quotas. Procurement teams cannot hedge this exposure through standard futures instruments.
Strategic Opportunities
- LATAM e-commerce penetration:Flash-sale platforms in Brazil and Mexico are capturing handset volume from carrier retail. Independent marketplaces now move 23% of superphone units in São Paulo metropolitan distribution.
- EU right-to-repair momentum:The European Parliament's repairability index mandates are creating modular battery design specifications. First-movers can capture sustainability-premium positioning before 2027 enforcement.
- Stylus-ERP convergence:Warehouse management systems from SAP and Oracle are releasing native pen-input modules. This technology convergence opens enterprise attach-rate expansion beyond traditional consumer positioning.
Industry Challenges
- RF engineering talent scarcity:Multi-band 5G antenna design requires expertise in millimeter-wave propagation that concentrates in Seoul, San Diego, and Helsinki. Compensation inflation for these specialists is compressing R&D margins.
- CE marking timeline variability:Notified body backlogs under the Radio Equipment Directive create 6-10 week certification delays that miss carrier procurement windows. Product managers must build buffer into launch schedules.
- Legacy MDM integration:Enterprise customers demand backward compatibility with MobileIron and VMware Workspace ONE deployments. Engineering teams must maintain three generations of Android security patch support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Phablets and Superphones Market |
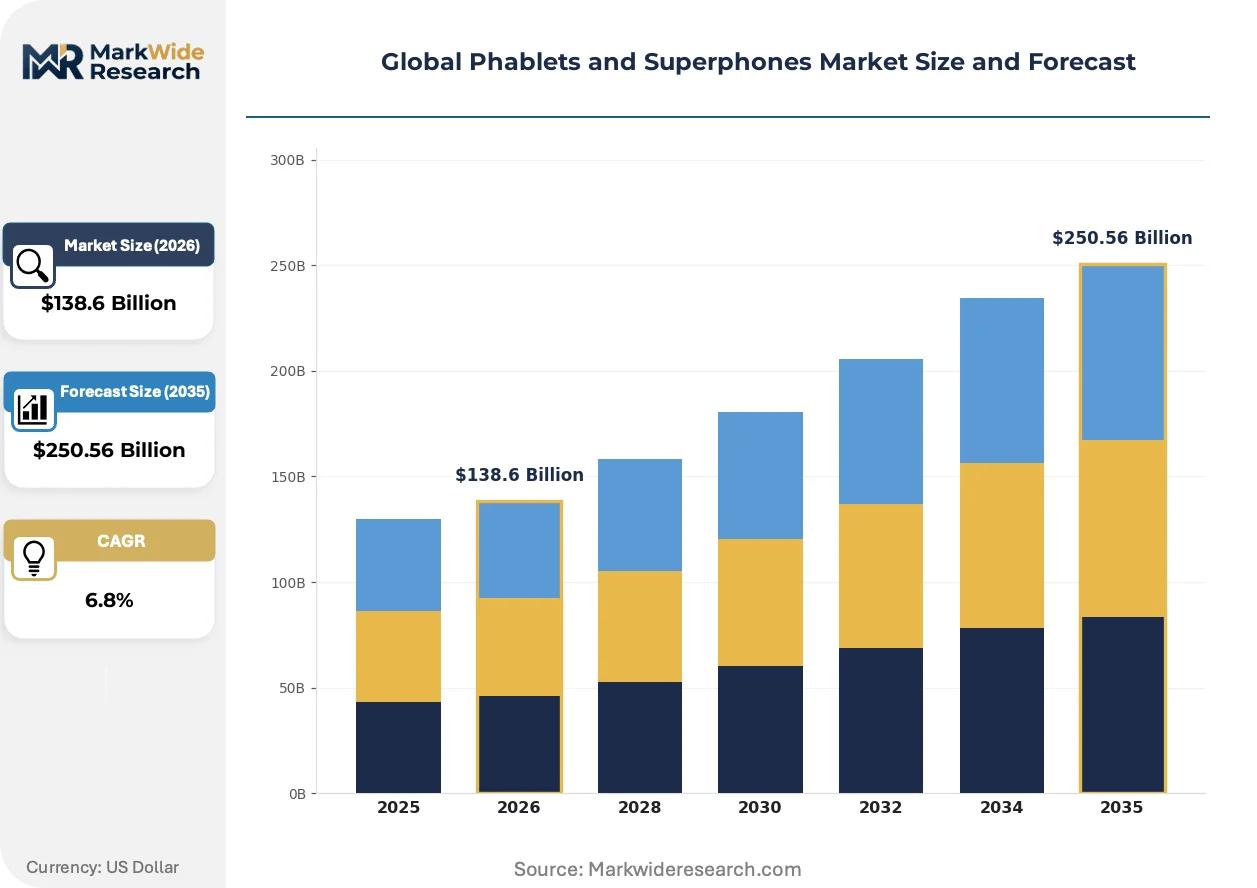
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $250.56 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phablets, Superphones, Smartphones, Tablets Technology: 4G LTE, 5G, OLED, LCD Operating System: Android, iOS, Windows, Others Market Segment: Consumer Electronics, Enterprise Solutions, Education, Healthcare |
| Companies Covered | OPPO, Transsion Holdings, Samsung Electronics, Realme, Huawei Technologies, Apple, vivo, OnePlus, Xiaomi Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Phablets and Superphones Market Emerging Trajectories
Computational photography and on-device AI inference are redefining camera subsystem prioritization in phablet industrial design. These capabilities now drive processor node selection ahead of display specifications.
Under-display camera arrays are digitizing full-screen OLED real estate by eliminating punch-hole notches. Samsung Electronics and Xiaomi Corporation are adopting this technology for their 2025 flagship refreshes at accelerated pace. The structural consequence is digitizing front-facing sensor integration into display driver layers, compressing module supplier margins.
EU WEEE directive amendments are mandating removable battery architectures by 2027. This industrial consequence forces redesign of unibody aluminum chassis that currently dominate premium-tier construction. The mid-range segment is responding fastest, with Chinese ODMs already tooled for modular designs.
Carrier subsidy erosion is fragmenting purchase patterns toward equipment installment plans and trade-in aggregators. Independent resale platforms like Swappa and Back Market are displacing carrier-controlled refurbishment channels in the United States and Germany. This shift is most visible among 18-34 demographic cohorts in Berlin and Austin metropolitan clusters.
Global Phablets and Superphones Market Segmentation
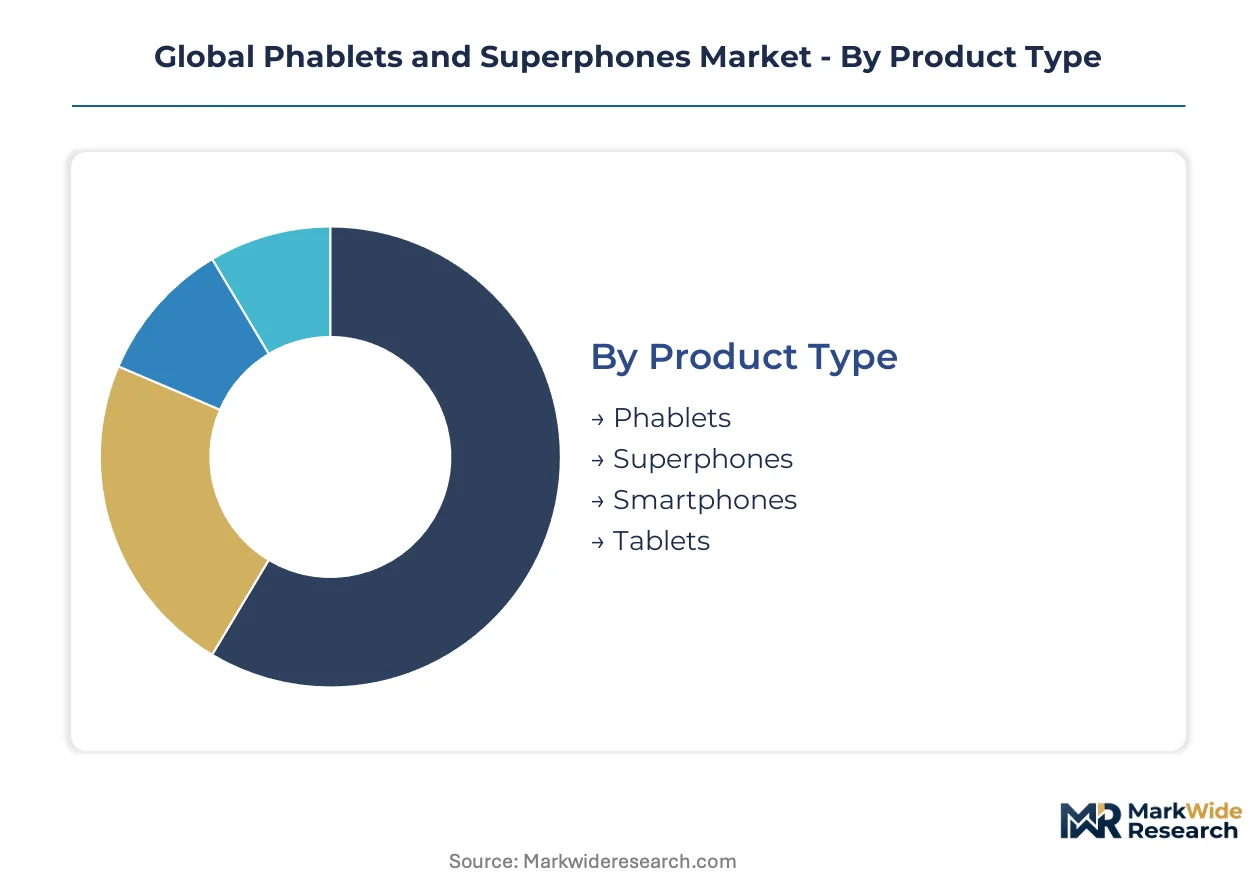
Screen size thresholds and connectivity specifications fragment procurement patterns across consumer and enterprise buyers. Each segmentation dimension carries distinct margin profiles and regulatory compliance burdens that reshape portfolio prioritization for device manufacturers.
Product Type:
Screen diagonal measurements and processor integration levels distinguish hardware categories across cost tiers and use-case intensity.
- Phablets:Devices with 5.5 to 6.9-inch diagonal displays bridge single-hand usability and media consumption. Enterprise field services in Germany and South Korea standardize procurement on stylus-integrated phablets for outdoor visibility requirements. Logistics operators favor these dimensions for ERP mobility deployments.
- Superphones:Flagship-tier devices exceeding 6.5 inches with 3nm application processors and multi-band 5G modems command premium positioning. Carrier-direct volume concentrates in Seoul and Austin metropolitan clusters under FCC equipment authorization timelines. Samsung Electronics anchors supply through captive OLED substrate production.
- Smartphones:Compact form factors below 5.5 inches retain emerging-market penetration in India and Southeast Asia where Transsion Holdings competes on price-performance hardware.
- Tablets:Large-format mobile computing devices with cellular connectivity modules serve clinical documentation and warehouse management use cases.
Phablets command the established base. The steepest expansion runs through Superphones.
Technology:
Connectivity standards and display substrates segment procurement by performance tier and regional infrastructure maturity.
- 5G:Multi-band modems supporting millimeter-wave and sub-6GHz spectrum dominate capital allocation as carriers in Australia retire legacy LTE allocations. Device refresh cycles compress under spectrum reallocation mandates.
- OLED:Flexible organic light-emitting diode panels with high refresh rates capture disproportionate margin pools. Samsung Display and BOE Technology control substrate supply concentration at Gumi and Hefei facilities.
- 4G LTE:Legacy connectivity modules retain volume in India and Latin America where 5G infrastructure deployment lags FCC and EU framework timelines.
- LCD:Liquid crystal display technology serves mid-range price positioning with thinner margin structures and shorter replacement cycles.
OLED commands the established base. The steepest expansion runs through 5G.
Operating System:
Software ecosystem control determines attach-rate economics and security patch lifecycle obligations across customer segments.
- Android:Open-source mobile operating system with customizable OEM skins dominates unit volume across price tiers. Google's patch distribution framework and Play Services licensing reshape regional hardware economics.
- iOS:Proprietary Apple operating system locks hardware-software integration for replacement-cycle loyalty. Enterprise MDM compatibility with VMware Workspace ONE sustains clinical and field service deployments.
- Windows:Microsoft mobile operating system retains niche positioning for stylus-integrated enterprise productivity use cases.
- Others:Alternative operating systems including HarmonyOS and Linux derivatives serve regulatory-compliant government procurement in China.
Android commands the established base. The steepest expansion runs through iOS enterprise attach rates.
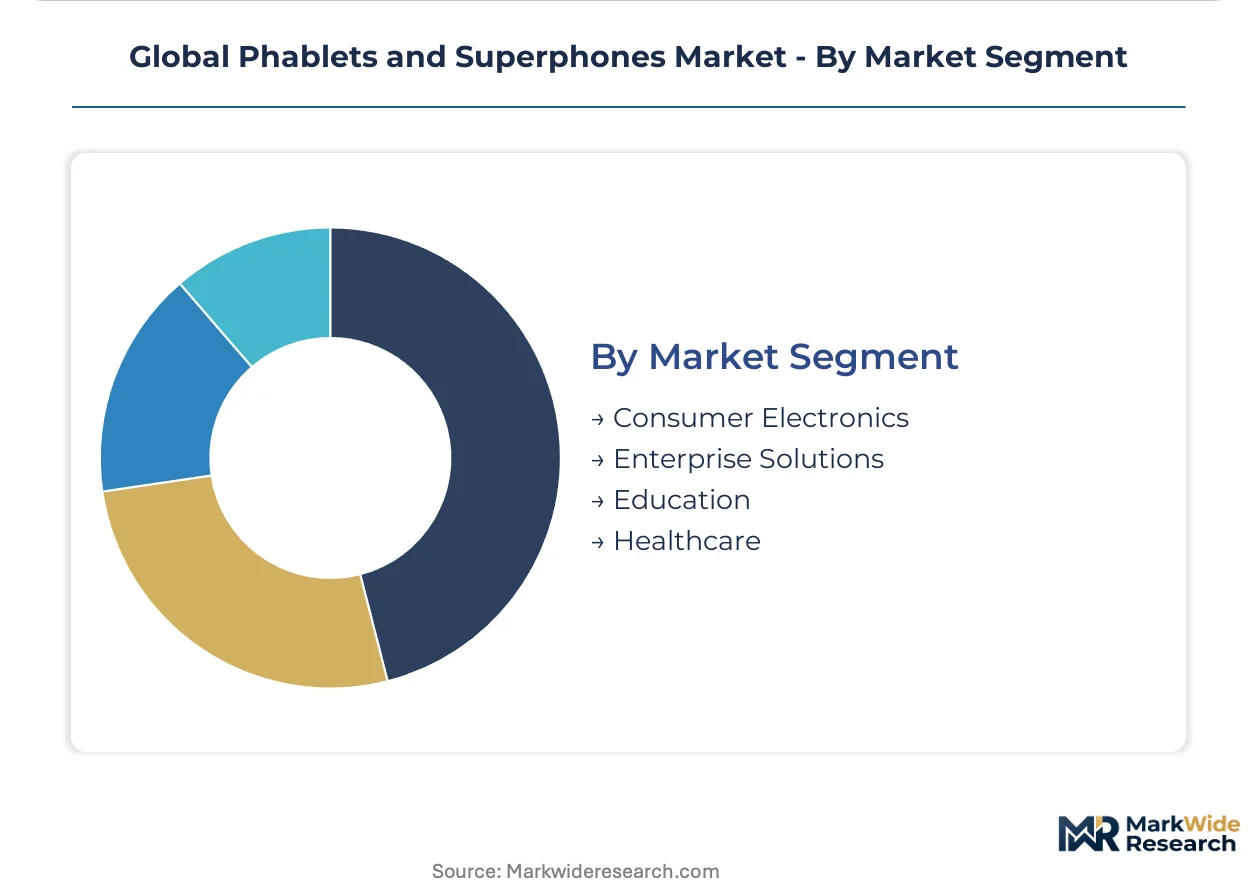
Market Segment:
End-use application intensity differentiates volume scale from margin capture across deployment contexts.
- Enterprise Solutions:Fleet-deployment contracts for field technicians and clinical staff require stylus-capable large-format screens with SAP and Oracle native pen-input modules. India's PLI scheme attracts display assembly to Uttar Pradesh for these contracts.
- Consumer Electronics:Individual purchase patterns fragment toward equipment installment plans and trade-in aggregators. Independent resale platforms displace carrier-controlled refurbishment channels in Berlin and Austin.
- Healthcare:Clinical staff mobility mandates HIPAA-compliant device management with backward compatibility for MobileIron deployments.
- Education:Institutional procurement concentrates on durability specifications and modular battery architectures under EU WEEE directive anticipation.
Consumer Electronics commands the established base. The steepest expansion runs through Enterprise Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Incheon International Airport cargo hub underwrites South Korea's role as the primary OLED substrate export corridor for premium-tier device assembly across three continents.
United States
Carrier-direct procurement concentrates in Austin and Seattle metropolitan clusters under FCC equipment authorization timelines. The streamlined 5G device certification framework accelerates multi-band modem volume commitments from field service fleets. Verizon and AT&T procurement windows drive refresh cycles for stylus-capable large-format screens.
Germany
Enterprise mobility adoption among logistics operators and clinical staff sustains fleet-deployment contracts for 6.7-inch and larger devices. CE marking under the Radio Equipment Directive governs RF emissions thresholds, with notified body backlogs creating certification delays. Berlin and Munich anchor procurement concentration for SAP-native pen-input modules.
India
Price-performance hardware competition between Transsion Holdings and Xiaomi Corporation intensifies in Uttar Pradesh and Tamil Nadu assembly corridors. The PLI scheme for electronics manufacturing attracts display module capacity with local value-add requirements. BIS compulsory registration schemes fragment product-launch sequencing versus FCC timelines.
South Korea
5G infrastructure deployment retires legacy LTE spectrum allocations, compressing device replacement cycles simultaneously across consumer and enterprise segments. Samsung Display controls flexible OLED substrate output from Gumi facilities. Seoul metropolitan procurement anchors premium-tier superphone volume under carrier-direct arrangements.
Australia
Spectrum reallocation mandates from carriers in Sydney and Melbourne force hardware refreshes across multi-band 5G modem specifications. TGA-equivalent telecommunications compliance runs parallel to carrier procurement windows. Enterprise field services in Perth and Brisbane standardize on OLED panels for outdoor visibility requirements.
Global Phablets and Superphones Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in display substrate and RF module supply. The vendor base concentrates around three to five vertically integrated conglomerates controlling captive OLED foundry output, with mid-range price competition fragmenting among Shenzhen and Dongguan ecosystem assemblers. Two strategic archetypes dominate: ecosystem-locked premium integrators and flash-sale volume distributors. Competitive moves center on carrier-direct volume commitments and modular battery design standardization ahead of EU WEEE directive enforcement.
Within the premium-tier vector, Samsung Electronics and Apple exemplify ecosystem-locked positioning through vertically controlled supply chains and hardware-software integration. Xiaomi Corporation occupies a position within the flash-sale distribution archetype, leveraging online channel penetration across Southeast Asia and Latin America. Transsion Holdings represents the emerging-market volume specialist, anchoring price-performance competition in India and sub-Saharan Africa through localized assembly strategies.
| Leading Market Players |
|---|
| OPPO |
| Transsion Holdings |
| Samsung Electronics |
| Realme |
| Huawei Technologies |
| Apple |
| vivo |
| OnePlus |
| Xiaomi Corporation |
| Others |
Supply Flow & Price Mechanics
Gumi and Hefei substrate concentration funnels margin capture toward Samsung Display and BOE Technology, compressing downstream OEM pricing power while amplifying premium-tier OLED panel premiums. Field service fleets and carrier-direct procurement absorb these upstream costs through equipment installment plans that stretch replacement cycles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments procurement by certification grade and volume scale. FCC equipment authorization timelines and CE marking under the Radio Equipment Directive create price differentiation between carrier-direct and independent retail channels. Pricing pressure stems from flash-sale platform penetration in São Paulo and Mexico City, where margin-thin hardware moves fastest. Enterprise Solutions buyers show least price sensitivity due to fleet-deployment standardization, while Consumer Electronics segments in India exhibit highest sensitivity to Transsion Holdings and Xiaomi Corporation price-performance positioning.
Supply Chain Analysis
Supplier-financing facilities extended by display substrate vendors compress working capital cycles for Shenzhen and Dongguan ecosystem assemblers. Component sourcing draws from South Korea for OLED substrates, China for application processor fabrication, and Taiwan for RF module assembly. Rare-earth magnet dependencies for haptic feedback motors expose procurement to Myanmar export quota volatility. Single-source vulnerability concentrates at Samsung Display's Gumi flexible OLED facilities. Distribution runs through carrier-direct channels in Austin and Seoul, independent e-commerce platforms in São Paulo, and flash-sale aggregators in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise mobility adoption fragments procurement into stylus-integrated, ERP-native niches that favor specialized hardware-software bundles over commodity volume plays.
For Market Incumbents: Build ecosystem-locked replacement-cycle loyalty through hardware-software integration moats that mirror Apple's architecture. Samsung Electronics should deepen captive OLED substrate control to defend against BOE Technology capacity expansion in Hefei. Prioritize backward integration into display driver IC design to capture margins digitizing under camera arrays. Defend against Xiaomi Corporation flash-sale disruption by tightening carrier-direct volume commitments in Seoul and Austin clusters. For New Entrants and Emerging Players: Latin American e-commerce penetration offers the most penetrable white-space, with independent marketplaces capturing 23% of superphone volume in São Paulo metropolitan distribution. Target enterprise stylus-ERP convergence where SAP and Oracle native pen-input modules create attach-rate expansion beyond consumer positioning. Pursue modular battery design standardization ahead of EU WEEE directive enforcement to capture sustainability-premium positioning. Establish flash-sale platform partnerships before incumbent carrier subsidy erosion completes. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed component specialists controlling RF module and antenna design capabilities concentrated in San Diego and Helsinki. Five-to-ten year viability hinges on 5G infrastructure deployment pace and spectrum reallocation timelines across South Korea, Germany, and Australia. Monitor right-to-repair legislative momentum and FCC equipment authorization streamlining as inflection indicators for hardware-refresh profitability and regional portfolio prioritization.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Battery Design Standardization | EU WEEE directive anticipation creates first-mover sustainability premium before 2027 enforcement windows. |
| Stylus-ERP Platform Integration | SAP and Oracle native pen-input modules open enterprise attach-rate expansion beyond traditional consumer positioning. |
| Carrier-Direct Volume Commitments | Verizon and AT&T procurement windows in Austin anchor premium-tier superphone refresh cycle capture. |
| Flash-Sale Channel Penetration | Independent e-commerce platforms in São Paulo and Mexico City displace legacy carrier retail volume. |
| Display Substrate Capacity Expansion | India's PLI scheme attracts module assembly to Uttar Pradesh for enterprise fleet-deployment contracts. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with RF engineering directors, carrier procurement leads, enterprise mobility managers, and display substrate supply planners; and secondary validation through FCC equipment authorization filings, EU CE marking databases under the Radio Equipment Directive, carrier capex disclosures, and customs records from Incheon and Shenzhen export corridors. Bottom-up triangulation across OEM bill-of-materials and top-down reconciliation against carrier volume commitments anchored value estimates.
Forecast inputs considered screen size thresholds, connectivity specifications, and enterprise segment penetration intensity across the projection horizon. Segmentation dimensions modeled include product type, technology, operating system, and market segment, with regional regulatory cluster variations. CAGRs derived from replacement-cycle compression rates under spectrum reallocation mandates and PLI scheme capacity buildout trajectories. 5G infrastructure deployment timelines and right-to-repair legislative momentum served as industry-specific forecast modifiers.
Practitioners should monitor spectrum reallocation timetables, notified body backlog durations under the Radio Equipment Directive, and rare-earth export quota fluctuations for early signals. Forecasts reflect assumptions documented across primary and secondary sources. Macroeconomic deviation, regulatory acceleration or delay, or technological substitution in millimeter-wave antenna design would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Propanil Market
Others
Spain Smart Home Market
Others
Nuclear Power Cables Market
Others
Language Translation Device Market
Others
Linear Shaft Market
Others
Bamboo Straws Market
Others
Vo5g Market
Others
US Camping and Caravanning Market
Others
LAMEA Astrology Market
Others
Legal Services Market
Others
Italy Feed Additives Market
Others
Global Active Speaker Market
Others
Aircraft Exterior Lighting Market
Others
Channel-In-A-Box (Ciab) Market
Others
Agitator Bead Mill Market
Others
Smart Home As a Service Market