
 Boston Round Bottle Market | 2026-2036
Boston Round Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Boston Round Bottle Market Outlook
USP-compliant pharmaceutical-grade specifications is collapsing the gap between commodity glass and high-performance primary packaging. Gerresheimer AG leverages its European blow-mold expertise to dominate regulated drug containment. O-I Glass, Inc anchors North American supply through furnace-scale production of borosilicate and soda-lime variants. Berlin Packaging differentiates by controlling distribution channels across mid-size pharmaceutical and cosmetics contract manufacturers.
A Boston round bottle is a cylindrical container with rounded shoulders and a narrow neck, traditionally manufactured from amber or flint glass through IS machine blowing or tubular conversion, designed to protect light-sensitive and oxidation-prone contents from degradation. Glass product type sustains premium positioning in injectable and oral-dose pharmaceutical applications where USP Type I/II/III hydrolytic resistance is mandatory. PET product type is displacing glass in over-the-counter and cosmetic segments where weight reduction and shatter resistance outweigh barrier requirements; 2 oz and 4 oz sizes occupy the fastest-expanding niche in travel-size personal care and unit-dose pharmaceuticals.
FDA enforces current Good Manufacturing Practice requirements for container closure systems under 21 CFR Part 211, compelling suppliers to validate extractables and leachables profiles for each material family. USP Chapter <661> and <1661> frameworks define glass hydrolytic resistance and surface durability standards that directly determine qualification timelines for new bottle submissions. EPA and state-level environmental regulations on recycled glass content and plastic resin sourcing are reshaping material selection criteria for procurement teams. Stakeholders must monitor how tightening pharmacopeial standards interact with sustainability mandates to avoid stranded inventory in dual-certified product lines.
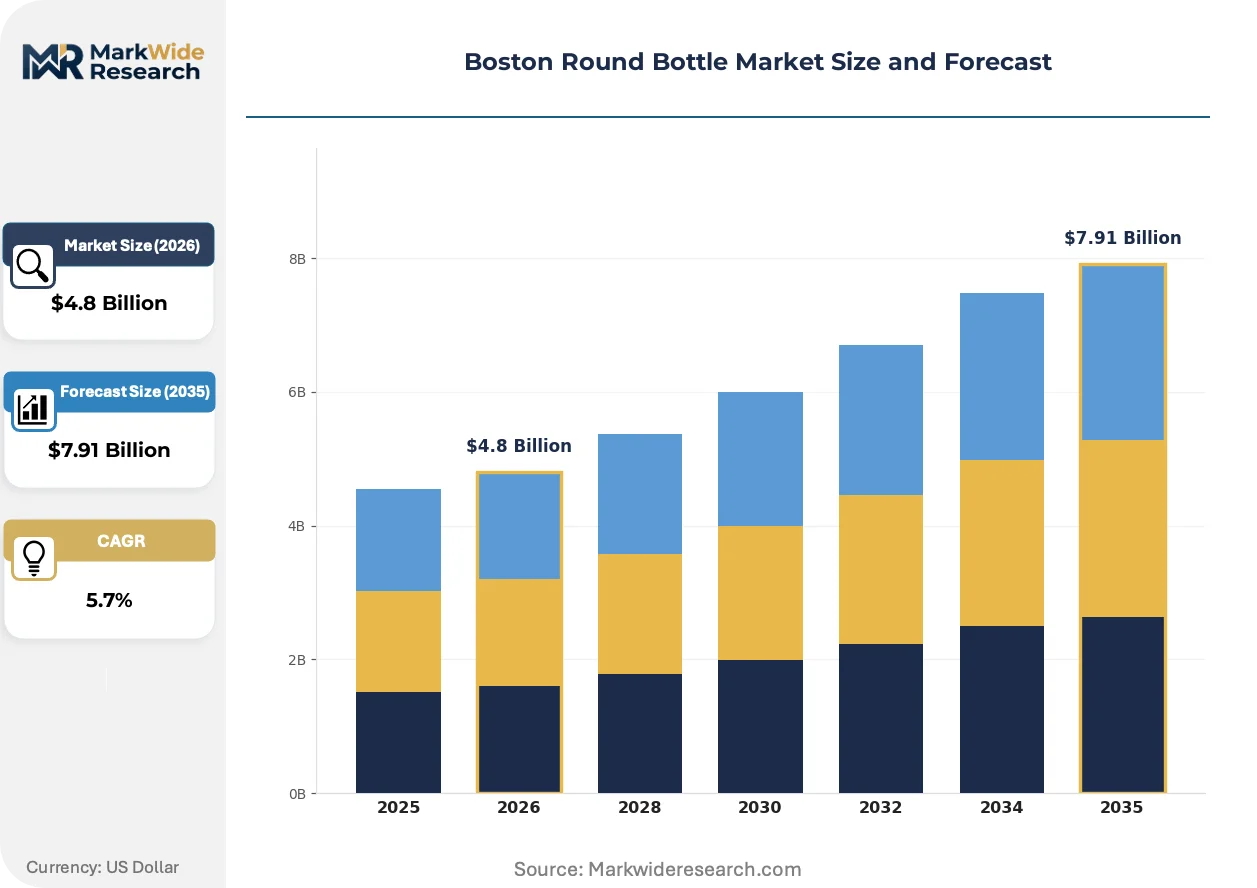
Market Dynamics
USP Chapter <661> hydrolytic resistance testing is compressing qualification timelines for new glass formulations while simultaneously fragmenting supplier tiers between certified and uncertified producers.
Growth Catalysts
- Injectable drug containment surge:Biologics manufacturers in Massachusetts and New Jersey are mandating Type I borosilicate bottles for parenteral formulations, pulling capacity from cosmetic applications.
- FDA extractables validation:Container closure system requirements under 21 CFR Part 211 are forcing brand owners to dual-source from validated suppliers, expanding addressable market for qualified converters.
- Tubular glass conversion:IS machine blowing is yielding to precision tubular forming for small-volume (2 oz–8 oz) pharmaceutical SKUs requiring dimensional tightness.
Market Restraints
- Energy-intensive furnace operations:Natural gas price volatility in the US Northeast and Germany is squeezing margin on soda-lime and borosilicate melting.
- Single-source silica sand deposits:High-purity silica supply concentrates in Wisconsin and Missouri, creating geographic concentration risk for domestic glass production.
- PET barrier limitations:Oxygen transmission rates in uncoated PET remain unsuitable for oxidation-sensitive APIs, blocking substitution in prescription drug segments.
Strategic Opportunities
- Indian pharmaceutical exports:CDSCO alignment with USP standards is opening qualification pathways for Indian injectable manufacturers sourcing US-compliant primary packaging.
- Swiss biologics cluster:Swissmedic's accelerated approval pathways for biosimilars are compressing supplier onboarding timelines for specialized containment.
- Deposit-return systems:EU Green Deal packaging waste directives are creating infrastructure for closed-loop glass recovery, reducing virgin material cost exposure.
Industry Challenges
- Extractables chemist scarcity:Qualified analytical talent for USP <1661> leachables profiling is concentrated among legacy pharmaceutical contractors, extending validation timelines.
- Furnace reconfiguration capex:Converting soda-lime capacity to Type I borosilicate requires crucible and control system investments exceeding standard maintenance cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boston Round Bottle Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass, Plastic, Polyethylene, PET Size: 2 oz, 4 oz, 8 oz, 16 oz Cap Type: Dropper, Screw Caps, Pump Dispenser, Plug Application: Pharmaceuticals, Cosmetics, Food & Beverage, Chemicals |
| Companies Covered | O-I Glass, Inc, Ardagh Group, Gerresheimer AG, Berlin Packaging, O.Berk, SKS Bottle & Packaging, Inc., The Cary Company, E.D. Luce Packaging, MJS Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boston Round Bottle Market Strategic Shifts
Container closure integrity testing and surface chemistry engineering are converging to redefine competitive advantage in regulated drug containment, separating specification-grade suppliers from commodity converters.
Plasma-enhanced chemical vapor deposition (PECVD) silicon oxide coatings on PET substrates are decomposing the traditional glass monopoly in oral-dose pharmaceuticals. Generic drug manufacturers in New Jersey are adopting coated PET for moisture-sensitive tablets, accepting marginal barrier tradeoffs for freight cost reduction. This technology is decomposing the historical correlation between drug value and packaging material premium.
EMA's revised Annex 1 sterile manufacturing guidelines are mandating particle contamination controls that extend to primary packaging wash and depyrogenation processes. Blow-fill-seal integrators must now validate bottle surface endotoxin levels prior to aseptic filling. European sterile injectable facilities are responding by qualifying dedicated bottle washing tunnels with validated rinse water quality.
Direct contracting between biopharma quality assurance teams and tier-two glass converters is collapsing traditional distribution markups. Mid-size CDMOs in the Research Triangle and San Diego clusters are bypassing master distributors to audit furnace operations personally, demanding lot-level dimensional certificates. This pattern is most visible in gene therapy viral vector containment, where bottle-to-bottle consistency affects fill-volume precision.
Boston Round Bottle Market Segmentation
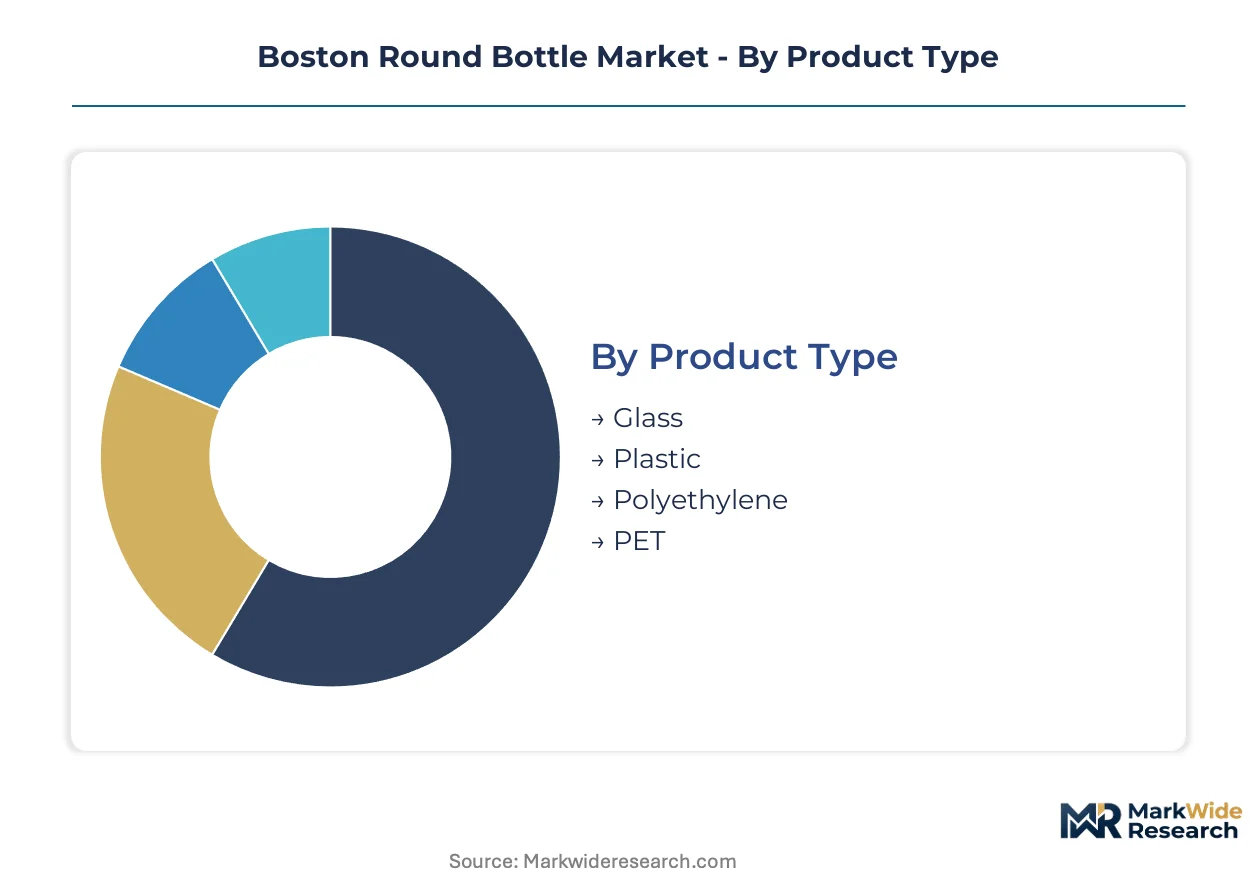
Segmentation in Boston round bottles reveals how material specifications, dimensional standards, and closure systems partition value across regulated and unregulated end-uses. Procurement teams navigate tradeoffs between USP compliance, freight economics, and barrier performance when selecting across these dimensions.
Product Type:
Glass formats face the most acute substitution pressure from barrier-coated polymers in oral-dose applications, while retaining irreplaceable status in parenteral containment.
- Glass:Amber and flint variants manufactured through IS machine blowing or tubular conversion deliver USP Type I/II/III hydrolytic resistance mandatory for injectable and light-sensitive formulations. Massachusetts biologics manufacturers specify borosilicate glass for gene therapy viral vectors where dimensional tightness affects fill-volume precision.
- PET:Plasma-enhanced chemical vapor deposition silicon oxide coatings are decomposing glass dominance in moisture-sensitive oral tablets. New Jersey generic drug manufacturers accept marginal oxygen barrier tradeoffs for freight cost reduction and shatter resistance in distribution.
- Plastic:Unspecified polymer blends serve cosmetic and household chemical segments where regulatory burden remains minimal and cost sensitivity dominates procurement decisions.
- Polyethylene:HDPE and LDPE variants occupy chemical and agricultural applications requiring chemical inertness and squeeze dispensing functionality at economy price points.
Glass retains volume leadership in prescription pharmaceutical containment; PET holds the steepest expansion curve as barrier coating technologies mature.
Size:
Volume concentration in smaller formats reflects unit-dose pharmaceutical trends and travel-size personal care proliferation, while larger sizes anchor chemical and bulk cosmetic applications.
- 2 oz:The dimensional sweet spot for travel-size personal care and unit-dose pharmaceuticals where TSA compliance and patient adherence intersect. Precision tubular forming yields dimensional tolerances critical for automated filling lines in compact footprints.
- 4 oz:Cosmetic contract manufacturers in New Jersey and Massachusetts favor this format for serum and essential oil positioning where premium perception supports margin extraction. Sampling programs and subscription box economics drive repeat procurement.
- 8 oz:Mid-volume pharmaceutical and professional cosmetic applications where multi-dose regimens meet countertop storage convenience.
- 16 oz:Bulk chemical, food service, and institutional pharmaceutical compounding where cost-per-ounce minimization outweighs premium positioning.
2 oz formats command the densest revenue per cubic meter in freight; 4 oz sizes are climbing the fastest as direct-to-consumer cosmetic brands scale.
Cap Type:
Closure selection increasingly determines container qualification timelines as FDA extractables validation extends to the full closure system assembly.
- Dropper:Glass and polymer droppers with bulb assemblies dominate essential oil, serum, and ophthalmic applications where dose precision and contamination control intersect. Bulb material compatibility testing under USP Chapter 661 extends supplier onboarding.
- Screw Caps:Child-resistant and continuous thread variants span the widest application range from oral solids to chemical reagents. Tamper-evident band integration is becoming standard for pharmaceutical distribution security.
- Pump Dispenser:Lotion and foam pumps serve cosmetic and topical pharmaceutical segments where viscosity handling and metered dosing enhance user experience.
- Plug:Orifice reducer plugs and friction-fit stoppers occupy low-cost chemical and fragrance applications where resealability requirements remain minimal.
Screw caps retain volume leadership across all end-use categories; dropper assemblies are gaining share fastest as serum and tincture formats proliferate in wellness positioning.
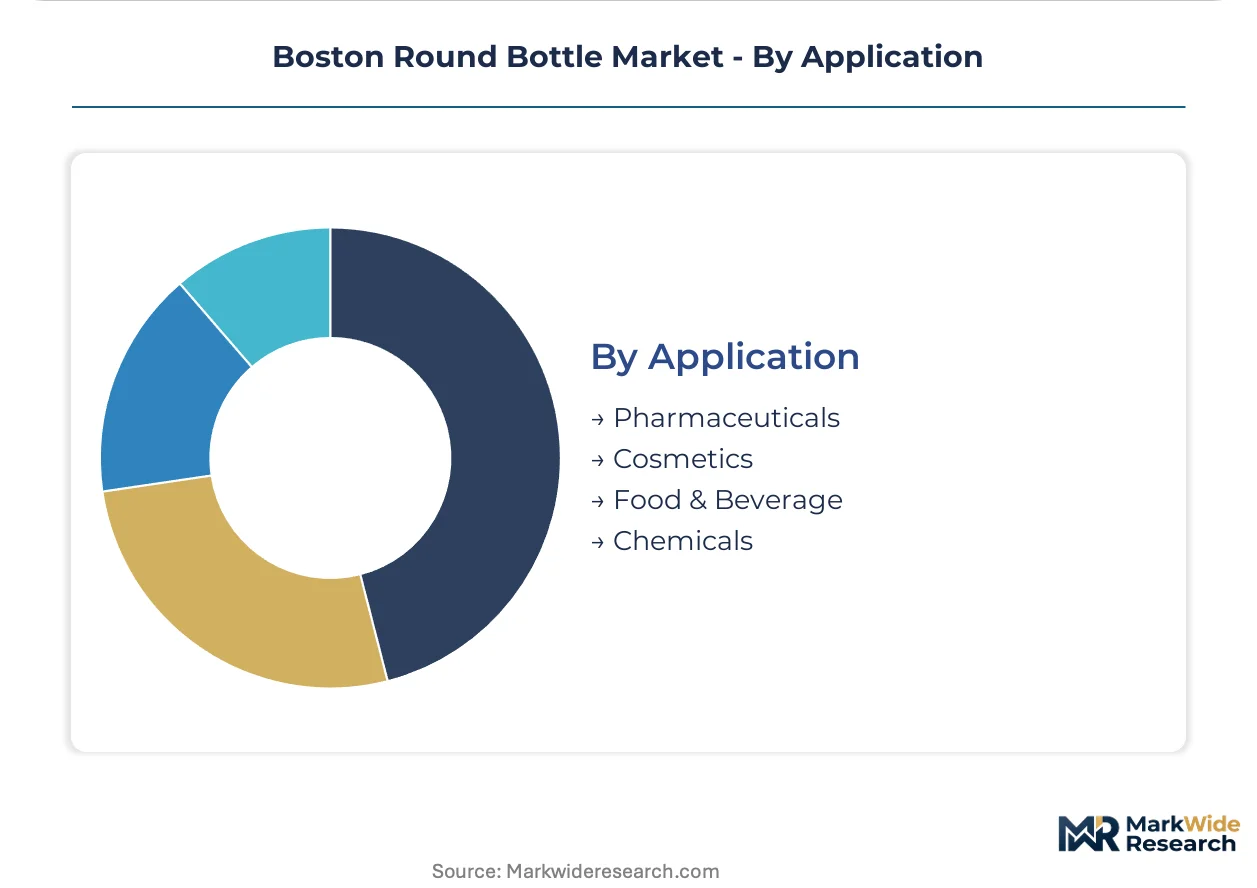
Application:
Regulatory intensity stratifies profitability across end-uses, with pharmaceutical qualification creating captive supplier relationships that cosmetic and chemical segments cannot replicate.
- Pharmaceuticals:Parenteral and oral-dose drug containment demands USP Type I borosilicate or validated polymer systems with documented extractables profiles. FDA 21 CFR Part 211 compliance and USP Chapter 1661 leachables testing compress the qualified supplier base to validated converters.
- Cosmetics:Skincare, fragrance, and personal care applications prioritize aesthetic differentiation and freight economics over barrier performance. Coated PET and colored glass support brand positioning with minimal regulatory friction.
- Food & Beverage:Flavor extracts, hot sauces, and specialty oils leverage amber glass light protection and acid resistance where FDA food contact notification requirements apply.
- Chemicals:Laboratory reagents, agricultural formulations, and industrial solvents emphasize chemical compatibility and UN-rated shipping compliance over premium material specifications.
Pharmaceuticals retain volume leadership in value terms; cosmetics are expanding most quickly as direct-to-consumer brands fragment order patterns toward smaller batch sizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity silica sand deposits in Wisconsin and Missouri anchor domestic glass production, while pharmaceutical demand clusters along the United States Northeast corridor. Natural gas price volatility in Germany and the US Northeast squeezes furnace margins, compressing supplier tiers between certified and uncertified producers.
United States
FDA 21 CFR Part 211 extractables validation requirements compress supplier qualification timelines for parenteral drug containment. Massachusetts biologics manufacturers specify Type I borosilicate bottles for gene therapy viral vectors. New Jersey's pharmaceutical manufacturing belt drives demand for 2 oz–8 oz precision tubular forming with dimensional tightness for automated filling.
Germany
Gerresheimer AG leverages European blow-mold expertise to dominate regulated drug containment supply. EMA's revised Annex 1 sterile manufacturing guidelines mandate particle contamination controls extending to primary packaging wash processes. Furnace-scale production of borosilicate variants concentrates in industrial glassmaking regions facing natural gas cost pressure.
Switzerland
Swissmedic's accelerated approval pathways for biosimilars compress supplier onboarding timelines for specialized containment. The Swiss biologics cluster generates demand for validated container closure systems with documented leachables profiles. Precision glass forming for small-volume pharmaceutical SKUs serves injectable drug manufacturers.
India
CDSCO alignment with USP standards opens qualification pathways for Indian injectable manufacturers sourcing US-compliant primary packaging. Pharmaceutical export growth drives demand for Type I borosilicate bottles meeting USP Chapter 661 hydrolytic resistance requirements. Contract manufacturing clusters in Maharashtra and Gujarat seek dual-certified supply chains.
China
NMPA pharmaceutical packaging regulations tighten material compatibility requirements for drug storage applications. Domestic glass converters expand borosilicate capacity to serve biologics manufacturers targeting export markets. Yangtze River Delta pharmaceutical clusters demand validated extractables profiles for container closure systems.
Boston Round Bottle Market Competitive Environment
Concentration sits with furnace-scale glass manufacturers and specialized pharmaceutical packaging converters. The supplier base fragments between validated producers serving regulated drug containment and commodity converters supplying cosmetic and chemical segments. Two strategic archetypes dominate: European blow-mold specialists with USP certification depth, and North American distributors controlling mid-size contract manufacturer channels. Competitive moves center on furnace reconfiguration for Type I borosilicate capacity and direct contracting with biopharma quality assurance teams.
Among Germany-based specialists, Gerresheimer AG exemplifies the European blow-mold archetype with regulated drug containment focus. O-I Glass, Inc anchors North American supply through furnace-scale production. Berlin Packaging occupies the distribution-controlled channel position, serving mid-size pharmaceutical and cosmetics contract manufacturers.
| Leading Market Players |
|---|
| O-I Glass, Inc |
| Ardagh Group |
| Gerresheimer AG |
| Berlin Packaging |
| O.Berk |
| SKS Bottle & Packaging, Inc. |
| The Cary Company |
| E.D. Luce Packaging |
| MJS Packaging |
| Others |
Value Chain & Pricing Dynamics
Ninety-day qualification timelines for USP Type I borosilicate certification concentrate pricing power among furnace-scale manufacturers while compressing margins for uncertified converters serving cosmetic and chemical segments.
Pricing Analysis
FDA 21 CFR Part 211 dictates the pricing tier structure across the Boston round bottle market, separating validated pharmaceutical-grade supply from commodity cosmetic and chemical alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects hydrolytic resistance certification depth, with Type I borosilicate commanding substantial premia over soda-lime variants. Cost compression in standard-grade soda-lime runs through natural gas price volatility in the US Northeast and Germany, squeezing furnace margins. Generic drug manufacturers in New Jersey exhibit highest price sensitivity, accepting coated PET tradeoffs for freight reduction, while Massachusetts gene therapy developers show lowest sensitivity due to fill-volume precision requirements.
Supply Chain Analysis
High-purity silica sand deposits in Wisconsin and Missouri anchor domestic glass production, creating geographic concentration risk for borosilicate and soda-lime melting operations. Wisconsin and Missouri silica deposits, combined with German furnace-scale expertise, supply the majority of pharmaceutical-grade glass feedstock. Raw material dependencies center on high-purity silica, natural gas for furnace energy, and cobalt-based amber colorants for light-protection variants. Single-source silica vulnerability exposes supply chains to geological disruption or export restrictions. Distribution runs through master distributors serving mid-size contract manufacturers, though direct contracting between biopharma quality teams and tier-two converters is collapsing traditional channel markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified USP <1661> extractables chemists and validated furnace operators represent acute capability scarcity, extending qualification timelines and concentrating supplier power among legacy pharmaceutical contractors.
For Market Incumbents: Compound certification depth by investing in tubular glass conversion capacity for 2 oz–8 oz precision pharmaceutical SKUs, defending against PECVD-coated PET substitution in oral-dose applications. Capture gene therapy viral vector containment demand through lot-level dimensional certificate programs that mid-size CDMOs now require. Prioritize furnace reconfiguration capex toward Type I borosilicate crucible upgrades before soda-lime margin erosion accelerates.
For New Entrants and Emerging Players: Rapid-turnaround extractables validation services represent the most penetrable service-layer gap, as incumbent furnace operators under-serve CDMOs facing compressed supplier onboarding timelines. Target Indian pharmaceutical export manufacturers seeking dual-certified supply chains aligned with CDSCO and USP standards. Enter through analytical chemistry partnerships offering USP Chapter <661> pre-qualification testing, converting service relationships into captive bottle supply contracts.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because pharmacopeial compliance creates irreversible switching costs and captive supplier relationships that commodity converters cannot replicate. Acquisition targets should display validated furnace operations with existing Type I borosilicate output and established extractables documentation libraries. Monitor Swissmedic accelerated approval pathway volumes as an inflection indicator for specialized containment demand compression.
| Strategic Initiative | Industry Significance |
|---|---|
| USP Type I Borosilicate Furnace Conversion | Captures Massachusetts gene therapy viral vector containment demand from precision tubular forming. |
| Extractables Validation Laboratory Buildout | Addresses USP Chapter 1661 chemist scarcity compressing supplier qualification timelines. |
| Direct CDMO Quality Team Contracting | Bypasses master distributor markups as Research Triangle and San Diego clusters demand lot-level certificates. |
| PECVD Coating Technology Licensing | Enables PET barrier enhancement decomposing glass monopoly in moisture-sensitive oral tablets. |
| Indian Dual-Certification Supply Chain | Serves CDSCO-aligned export manufacturers targeting US-compliant primary packaging qualification pathways. |
Study Parameters
A standing panel of pharmaceutical packaging procurement managers, biologics quality assurance directors, glass furnace operations engineers, and regulatory affairs specialists provided ongoing calibration against secondary validation through FDA 21 CFR Part 211 guidance documents, USP Chapter <661> and <1661> pharmacopeial standards, EMA Annex 1 sterile manufacturing revisions, and CDSCO alignment notifications with USP requirements. Bottom-up volume modeling across material type, size format, cap configuration, and end-use application triangulated against top-down value estimates derived from furnace capacity disclosures and distributor channel revenue patterns.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window, with segmentation modeling incorporating product type, dimensional specification, closure system, and regulatory intensity tiers. CAGRs were derived from trend extrapolation of pharmaceutical containment demand, cosmetic freight economics shifts, and barrier coating technology diffusion curves. Forecast inputs included Massachusetts and New Jersey biologics manufacturing expansion, Indian pharmaceutical export growth trajectories, and EU Green Deal packaging waste directive implementation pacing.
Forecasts assume regulatory continuity in FDA, USP, EMA, and CDSCO regimes; material policy shifts in extractables validation requirements or hydrolytic resistance standards would require re-modeling. Scenario boundaries exclude radical substitution technologies beyond PECVD-coated PET and unanticipated furnace fuel source transitions. Practitioners should keep alternative scenarios live as Swissmedic biosimilar approval velocities and EU deposit-return system infrastructure buildouts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Mobile Computer Cart Market
Others
Global Car Wax Market
Others
Asia Pacific Automotive LED Lighting Market
Others
Europe Smart Homes Market
Others
Global Extruded Plastics Market
Others
Mexico Retail Market
Others
Asia Pacific Contract Packaging Market
Others
Rotary Evaporators Market
Others
Dried Egg Market
Others
Japan Smart Home Market
Others
Europe Polycarbonate Sheets Market
Others
Automotive Smart Lighting Market
Others
China Cloud Gaming Technology Market
Others
Africa Lime Market
Others
Cellular-Connected Laptops Market
Others
Global Microcontroller Embedded Systems Market