
 Potato Soup Market | 2026-2036
Potato Soup Market Size, Share, and Industry Trends Forecast 2026-2036
Potato Soup Market Analytics
The price-performance gap between premium and commodity potato soup is hardening. Artisanal brands with clean-label positioning now command shelf space at double the unit price of conventional offerings. Campbell Soup Company leverages its distribution network to sustain volume leadership in North American retail channels. Nestlé S.A. anchors its European position through regional recipe variants that compete on taste localization rather than price.
Potato soup comprises dehydrated or fresh potato bases combined with dairy, broth, and seasonings, then thermally processed for shelf stability or quick reconstitution; water content typically ranges from seventy-five to eighty-five percent for ready-to-eat formats versus below ten percent for instant powders. The product serves both convenience-seeking households and food service operators requiring consistent, scalable menu components. Ready-to-Eat formats occupy the dominant margin pool as consumers trade preparation time for immediate consumption, while Instant segments lead volume growth in emerging markets where cold-chain infrastructure remains limited. Online Retail distribution is accelerating fastest among channels, though Supermarket placements still control the majority of premium product discovery.
The FDA enforces nutrition labeling and sodium disclosure requirements that shape reformulation priorities for US-manufactured potato soup, while EFSA guidelines on acrylamide mitigation influence European thermal processing standards. These frameworks elevate compliance costs for smaller producers and favor operators with dedicated regulatory affairs capacity. Stakeholders must monitor evolving front-of-pack labeling mandates and decide whether to absorb reformulation expenses or reposition toward premium tiers where consumers accept cleaner ingredient panels at higher price points.
Market Dynamics
Clean-label reformulation mandates from the FDA and EFSA are compressing product development cycles while simultaneously elevating R&D costs for thermal processing optimization. Food service operators facing labor inflation are accelerating soup menu automation, creating dual pressure on manufacturers to deliver consistent quality at scale.
Growth Catalysts
- Single-serve format adoption:Convenience-seeking households in the United States are trading bulk preparation for portion-controlled packaging that reduces food waste and preparation time.
- EFSA acrylamide mitigation guidelines:European thermal processing standards are driving investment in low-temperature cooking technologies that improve safety profiles while maintaining sensory attributes.
- Food service labor automation:Rising wage pressures in commercial kitchens are pushing operators toward pre-portioned, heat-and-serve soup components that minimize skilled labor dependency.
Market Restraints
- Dairy input cost volatility:Cream and butter price fluctuations destabilize margin structures for premium formulations that depend on dairy fat for mouthfeel.
- Sodium disclosure mandates:FDA labeling requirements create reformulation friction for heritage recipes where salt functions as both preservative and flavor carrier.
- Fresh potato supply concentration:Processing-grade potato sourcing clusters in specific growing regions, exposing manufacturers to weather-driven crop variability and transportation cost spikes.
Strategic Opportunities
- Online retail channel expansion:Direct-to-consumer subscription models for shelf-stable soup kits are capturing repeat purchase behavior outside traditional supermarket placements.
- Plant-based dairy convergence:Oat and coconut cream technologies are opening clean-label positioning for lactose-intolerant and vegan consumer segments previously excluded from creamy soup categories.
- India cold-chain infrastructure gaps:Instant powder formats face limited competition in emerging markets where refrigeration penetration remains below ready-to-eet threshold requirements.
Industry Challenges
- Clean-label R&D talent scarcity:Food scientists capable of replacing modified starches and emulsifiers with functional natural ingredients command premium compensation in tight labor markets.
- Thermal processing equipment retooling:Acrylamide reduction targets require capital-intensive oven and kettle modifications that strain mid-tier manufacturer balance sheets.
- Legacy ERP integration friction:Lot traceability requirements for ingredient origin documentation clash with decades-old manufacturing execution systems resistant to real-time data capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potato Soup Market |
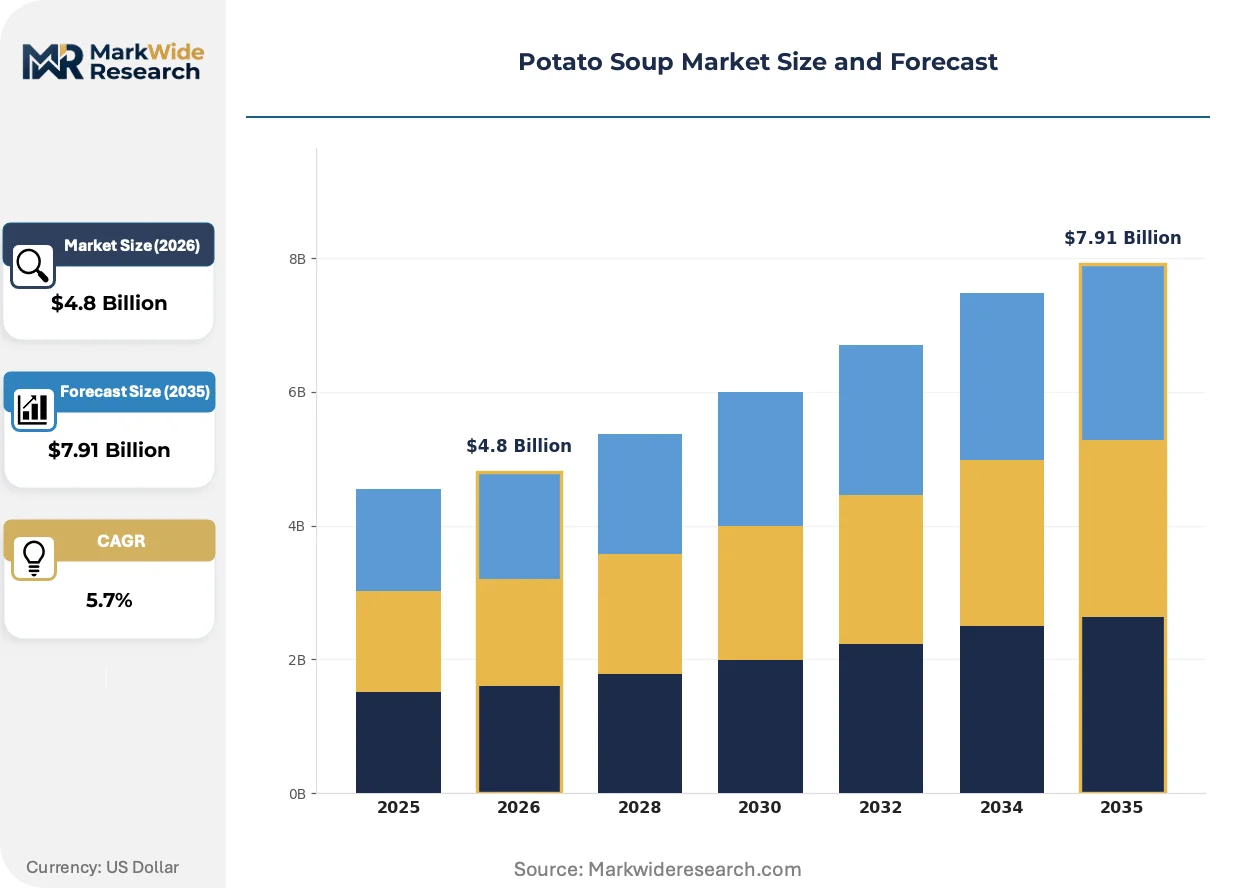
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-to-Eat, Instant, Creamy, Chunky Packaging Type: Carton, Can, Sachet, Glass Jar Distribution Channel: Supermarket, Online Retail, Convenience Store, Specialty Stores End User: Household, Restaurants, Cafes, Food Service |
| Companies Covered | Campbell Soup Company, Knorr, Nestlé S.A, General Mills, Inc., Conagra Brands, Inc., The Kraft Heinz Company, Baxters Food Group Limited, Hindustan Unilever Limited, Ottogi Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potato Soup Market Evolving Landscape
Reformulation science is converging with digital quality monitoring to reshape how potato soup achieves shelf stability without synthetic preservatives. Manufacturers are racing to deploy sensor-equipped production lines that verify thermal kill steps while preserving volatile flavor compounds.
High-pressure processing (HPP) is electrifying clean-label shelf extension for refrigerated ready-to-eat formats. Premium brands in the United States are adopting HPP systems to bypass traditional retort cooking. This technology is compressing the acceptable trade-off between convenience and ingredient transparency.
EFSA front-of-pack nutritional scoring mandates are recalibrating European formulation priorities. Manufacturers must now optimize Nutri-Grade ratings alongside sensory performance. Ready-to-eat segments in France and Germany are responding with stealth sodium reduction and vegetable density increases.
Direct subscription procurement is displacing supermarket impulse purchases among urban millennials. Meal-kit aggregators are bundling premium soup SKUs with complementary bread and garnish components. This pattern concentrates in coastal United States metropolitan markets where delivery density supports unit economics.
Potato Soup Market Segmentation
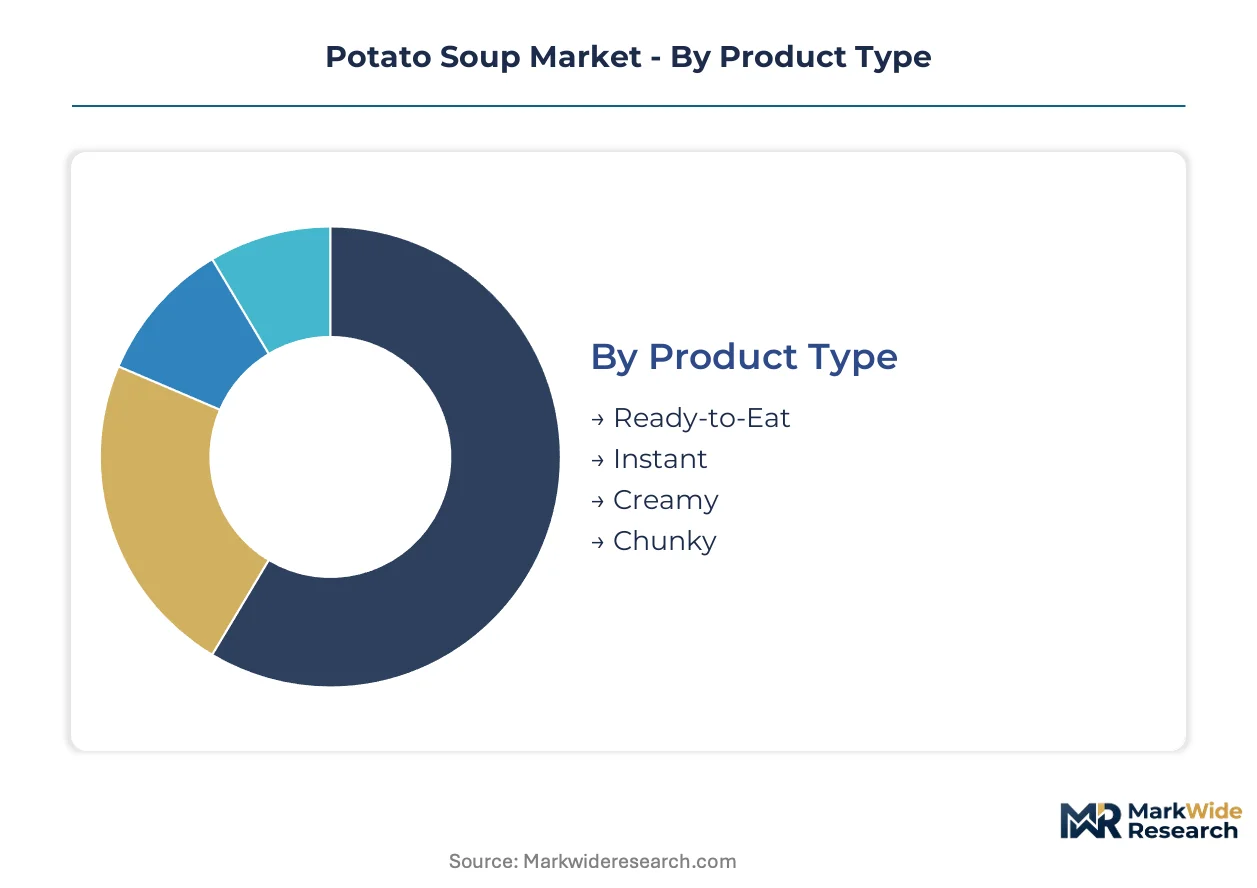
Segmentation in potato soup reveals how preparation format, shelf stability, and channel access shape purchasing decisions across divergent consumer contexts. Manufacturers must align thermal processing investments with the specific convenience expectations and storage constraints of each segment cluster.
Product Type:
Format selection hinges on the trade-off between immediate consumption convenience and preparation flexibility in kitchen environments.
- Ready-to-Eat:Thermally processed soups with seventy-five to eighty-five percent water content packaged for direct consumption after gentle reheating. United States households seeking comfort food without preparation steps drive repeat purchases in this segment, with single-serve formats reducing food waste concerns.
- Instant:Dehydrated potato bases with below ten percent moisture requiring hot water reconstitution. India and emerging markets with limited cold-chain infrastructure favor this format for ambient storage and extended shelf life without refrigeration dependency.
- Creamy:Dairy-fat emulsified formulations delivering rich mouthfeel through butter or cream integration.
- Chunky:Heterogeneous textures with visible potato pieces and vegetable inclusions for sensory differentiation.
Ready-to-Eat leads on scale; Instant leads on momentum.
Packaging Type:
Material selection reflects the tension between shelf-life extension, sustainability positioning, and microwave compatibility in target channels.
- Carton:Multilayer paperboard with aluminum barrier layers enabling microwave heating and lightweight logistics. European retailers favor this format for reduced carbon footprint claims and efficient shelf stacking, though thermal processing must accommodate seal integrity under retort conditions.
- Can:Tinplate or aluminum cylindrical containers with hermetic sealing for ambient shelf stability exceeding twenty-four months. United States mass retail channels depend on this format for inventory durability and damage resistance during transportation.
- Sachet:Flexible film pouches for single-serve powder portions minimizing packaging material per serving.
- Glass Jar:Transparent containers supporting premium positioning through visual product appeal and reusability signaling.
Can dominates volume throughput; Carton dominates sustainability-driven channel expansion.
Distribution Channel:
Channel strategy determines whether discovery happens through physical browsing or algorithmic recommendation engines.
- Supermarket:Branded shelf placements and end-cap promotions controlling premium product discovery in the United States. This channel captures planned purchase occasions where consumers compare unit pricing across format variants.
- Online Retail:Direct-to-consumer subscription models and meal-kit bundling accelerating fastest among coastal United States metropolitan markets. Delivery density supports unit economics for shelf-stable soup kits with complementary garnish components.
- Convenience Store:Impulse-oriented single-serve formats for immediate consumption without household inventory commitment.
- Specialty Stores:Curated artisanal selections targeting clean-label seekers with regional recipe variants.
Supermarket anchors current revenue; Online Retail climbs the fastest in customer acquisition metrics.
End User:
End-use segmentation separates household discretionary spending from operational procurement with scale and consistency requirements.
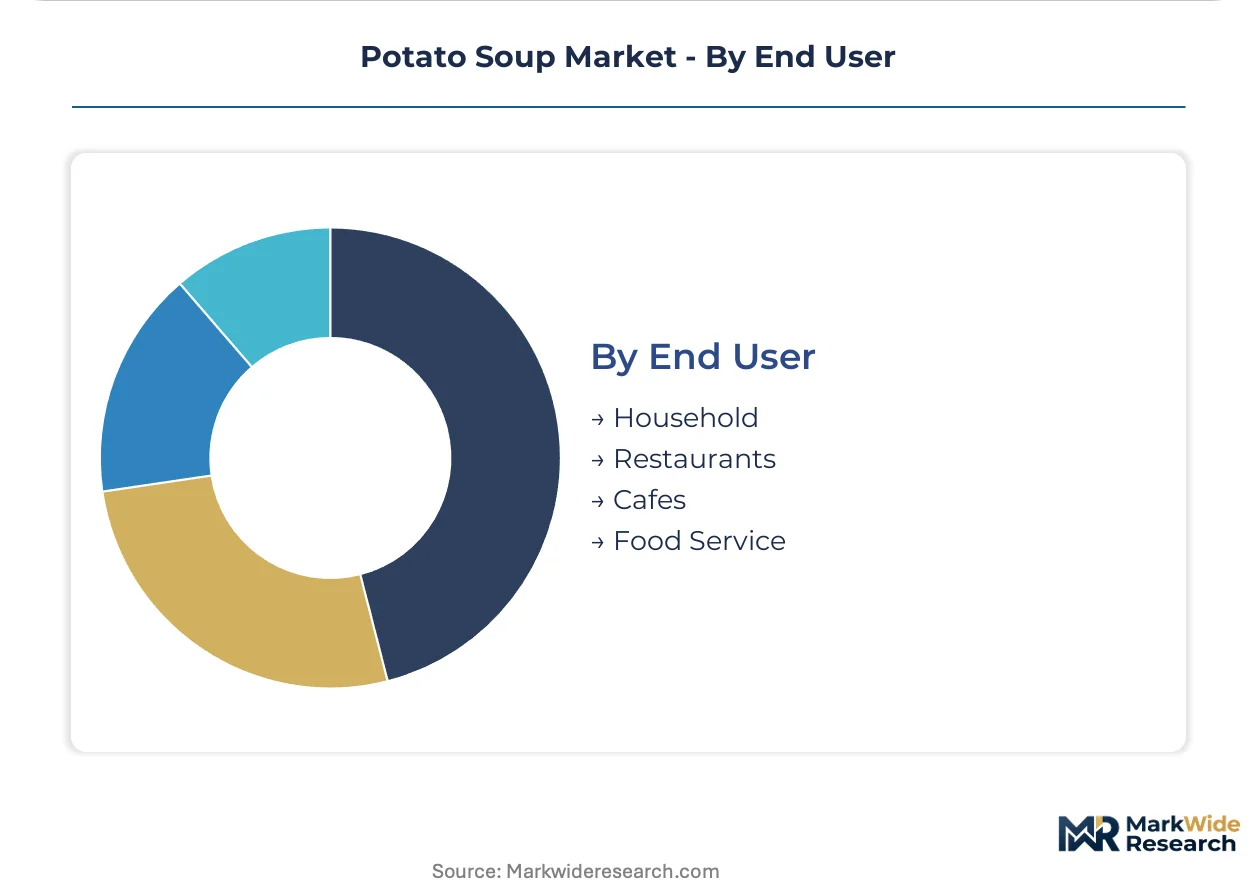
- Household:Individual consumers purchasing for home consumption across convenience-seeking and cooking-enthusiast segments. United States comfort food consumption patterns concentrate demand here, with portion-controlled packaging reducing preparation time and waste.
- Restaurants:Full-service operators requiring consistent, scalable menu components that minimize skilled labor dependency. Rising wage pressures in commercial kitchens accelerate adoption of pre-portioned, heat-and-serve soup components.
- Cafes:Limited-service formats with smaller batch requirements and faster menu rotation cycles.
- Food Service:Institutional caterers and contract feeding operations prioritizing cost predictability and nutritional compliance.
Household leads on transaction frequency; Restaurants lead on volume per procurement event.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food processing talent clusters in the American Midwest and European manufacturing belts anchor potato soup production networks. Regulatory divergence between FDA sodium mandates and EFSA acrylamide protocols splits R&D investment flows across Atlantic markets.
United States
Comfort food consumption patterns and single-serve format adoption drive household demand concentration in the Northeast and Midwest. FDA nutrition labeling and sodium disclosure requirements compress reformulation cycles for heritage recipes. Chicago and Minneapolis-St. Paul processing corridors host thermal processing facilities serving retail and food service channels.
Germany
EFSA front-of-pack Nutri-Grade scoring recalibrates formulation priorities toward stealth sodium reduction. The country's central location within European distribution networks enables efficient cross-border supply to France and Benelux markets. Bavaria and North Rhine-Westphalia concentrate clean-label R&D facilities adapting regional potato varieties.
India
Cold-chain infrastructure gaps below ready-to-eat threshold requirements favor instant powder formats in Maharashtra and Gujarat. FSSAI labeling mandates shape packaging investments for ambient-stable products. Mumbai and Ahmedabad manufacturing hubs serve domestic demand while testing export formulations for Middle Eastern markets.
Japan
Single-serve premium positioning aligns with metropolitan household size trends in Tokyo and Osaka. METI food safety guidelines influence thermal processing equipment specifications. Kanto and Kansai industrial zones integrate high-pressure processing technologies for refrigerated clean-label segments.
United Kingdom
Meal-kit subscription models concentrate in Greater London and Southeast England delivery corridors. EFSA-aligned post-Brexit food standards maintain acrylamide mitigation requirements. Midlands manufacturing clusters balance retail supermarket supply with direct-to-consumer channel expansion.
Potato Soup Market Competitive Landscape
Top-tier vendors anchor volume leadership through distribution network scale, while mid-tier specialists compete on clean-label positioning and regional recipe localization. The market exhibits consolidated retail shelf access alongside fragmented artisanal segments. Three archetypes dominate: multinational CPG conglomerates with thermal processing scale, regional dairy-integrated soup specialists, and direct-to-consumer subscription brands. Competitive moves center on M&A for regional taste portfolios and capacity expansion for high-pressure processing lines.
Within the multinational tier, Campbell Soup Company and Nestlé S.A. exemplify divergent geographic anchoring strategies. Campbell occupies a position tied to North American retail channel density. Nestlé S.A. sits within European taste-localization approaches. Conagra Brands, Inc. represents the mid-tier consolidation archetype.
| Leading Market Players |
|---|
| Campbell Soup Company |
| Knorr |
| Nestlé S.A |
| General Mills, Inc. |
| Conagra Brands, Inc. |
| The Kraft Heinz Company |
| Baxters Food Group Limited |
| Hindustan Unilever Limited |
| Ottogi Co., Ltd |
| Others |
Value Network & Pricing Analysis
Food service procurement concentration among institutional caterers and chain restaurant operators anchors contract-based volume pricing for potato soup manufacturers. These buyers negotiate long-term offtake agreements that compress margins for mid-tier suppliers while rewarding thermal processing scale.
Pricing Analysis
Ready-to-eat and instant format bundles separate premium HPP-treated refrigerated lines from economy retort-stable cans. Three-tier pricing structure across premium, standard, and economy levels reflects clean-label certification intensity and dairy fat content. Cost compression in the economy tier is intensifying because private-label retailers are backward-integrating into co-manufacturing partnerships. Food service operators exhibit the highest price sensitivity due to menu cost targets, while direct-to-consumer subscription buyers accept premium positioning for ingredient transparency.
Supply Chain Analysis
FDA and EFSA domestic-content mandates for nutritional disclosure and acrylamide documentation are reshaping sourcing toward traceable potato growing regions in the United States, Germany, and the Netherlands. Processing-grade potato supply draws from Idaho and North Dakota in the United States, Lower Saxony in Germany, and Flevoland in the Netherlands. Dairy inputs including cream and butter introduce single-source vulnerability from concentrated dairy cooperative networks. Distribution runs through temperature-controlled logistics hubs serving retail and food service channels with distinct cold-chain requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
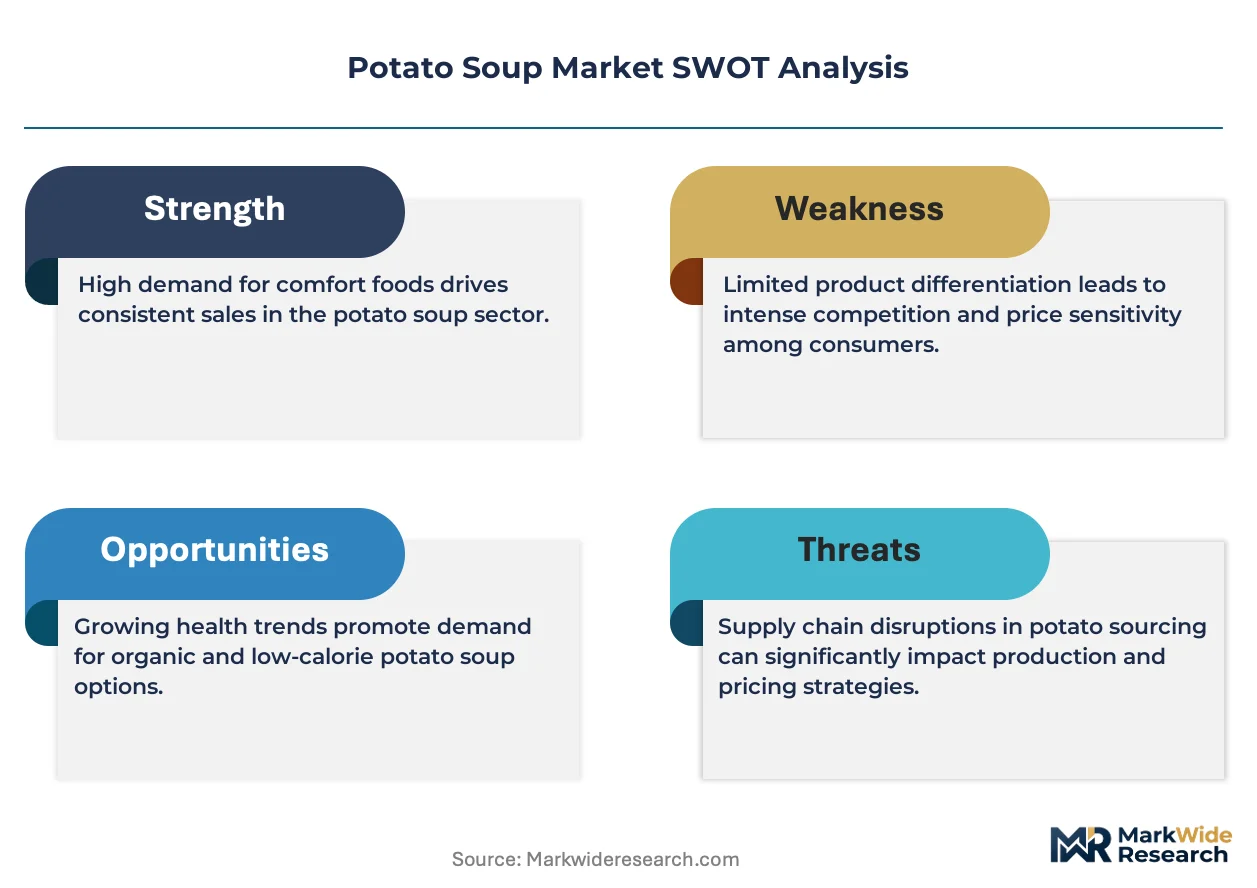
This market operates as a regulatory compounder where FDA sodium disclosure mandates and EFSA acrylamide protocols continuously force reformulation investment, elevating compliance costs that favor scaled operators with dedicated regulatory affairs capacity.
For Market Incumbents: Lock in thermal processing scale advantages by expanding high-pressure processing capacity in coastal United States metropolitan corridors where subscription channel density supports premium pricing. Acquire regional clean-label specialists before Nestlé S.A. and Campbell Soup Company consolidate remaining independent R&D talent pools. Defend against plant-based dairy convergence threats by captive supply of oat and coconut cream technologies through partnership with ingredient technology firms. For New Entrants and Emerging Players: FSSAI labeling mandates in India open a window for instant powder formats with localized spice profiles targeting Maharashtra and Gujarat manufacturing hubs. White-space concentration exists in direct-to-consumer subscription models for shelf-stable soup kits with complementary garnish components. Target coastal United States metropolitan markets where delivery density supports unit economics and incumbent brand loyalty remains penetrable through meal-kit aggregator partnerships. For Investors and Strategic Acquirers: Regional dairy-integrated soup specialists are the most active acquirer in this space, seeking thermal processing capacity and clean-label R&D talent. Long-term viability centers on five-to-ten-year regulatory compliance cost trajectories favoring operators with dedicated regulatory affairs capacity over mid-tier manufacturers. Watch for FDA front-of-pack labeling mandate proposals as the inflection signal accelerating consolidation toward scaled operators.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | EFSA acrylamide protocols and FDA sodium mandates elevate R&D spending for natural preservative alternatives. |
| High-Pressure Processing Capacity Expansion | Refrigerated ready-to-eat segments in United States coastal markets bypass traditional retort cooking for premium positioning. |
| Direct-to-Consumer Channel Development | Subscription models capture repeat purchase behavior outside supermarket placements in delivery-dense metropolitan corridors. |
| Plant-Based Dairy Technology Partnership | Oat and coconut cream integration opens lactose-intolerant and vegan consumer segments previously excluded from creamy categories. |
| Regional Recipe Localization Acquisition | Taste-variant portfolios in Germany and India defend against multinational CPG conglomerates competing on distribution scale. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with food service procurement directors, thermal processing plant managers, retail category buyers, clean-label R&D scientists, and regulatory affairs leads with secondary validation from FDA guidance documents, EFSA scientific opinions, FSSAI labeling notifications, Nielsen retail audit data, and customs trade records. Bottom-up segment sizing and top-down macroeconomic anchoring were triangulated to converge on market estimates.
Historical reference periods spanning pre-regulatory mandate implementation through current compliance phase transitions anchored the forecast window. Segmentation dimensions modeled include preparation format, packaging type, distribution channel, and end-user vertical across the projection horizon. CAGRs were derived from growth driver elasticity analysis calibrated to input cost trajectories and channel shift velocities. Forecast inputs incorporated dairy commodity price volatility indices and cold-chain infrastructure penetration rates by geography.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme weather events affecting processing-grade potato harvests or abrupt regulatory acceleration in sodium reduction timelines. Forecasts reflect assumptions on clean-label R&D talent availability and thermal processing equipment lead times. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Processed Superfruits Market
Processed Foods
Fruit Processing Market
Processed Foods
Processed Meat Market
Processed Foods
Soup & Broth Market
Processed Foods
Tomato Puree Market
Processed Foods
India Ready to Mix Food Market
Processed Foods
North America Soup Market
Processed Foods
Low Fat Soups Market
Processed Foods
Tomato Paste Market
Processed Foods
Asia-Pacific Ice Cream Market
Processed Foods
High-Pressure Processing (HPP) Foods Market
Processed Foods
United States Food Spread Market
Processed Foods
Fermented Food and Drinks Market
Processed Foods
Global Potato Flake Market
Processed Foods
Low Fat Chicken Soup Market
Processed Foods
Ready to Serve Prefabricated Dishes Market