
 Soup & Broth Market | 2026-2036
Soup & Broth Market Size, Share, and Industry Trends Forecast 2026-2036
Soup & Broth Market Insights
The premium-commodity split in soup and broth is rebalancing around ingredient transparency, with clean-label broths commanding price multiples over conventional canned formats while mass-market segments compete on volume efficiency. Campbell Soup Company leverages its manufacturing scale to sustain shelf-stable dominance across North American retail channels. Nestlé S.A anchors its position through specialized health-focused broth portfolios targeting wellness-oriented households. Unilever competes in emerging markets with localized flavor adaptations that extend its brand architecture.
Soup and broth comprise liquid or semi-liquid food preparations produced through simmering meat, vegetables, or legumes in water, typically achieving solids content between 2% and 8% for clear broths and 15% to 25% for cream-based soups, with thermal processing or aseptic filling ensuring shelf stability for commercial distribution. Canned soup remains the largest revenue pool though liquid broth is displacing it in velocity growth as refrigerated distribution infrastructure matures. Tetra Packs capture margin expansion in broth concentrates where oxygen barrier properties preserve volatile aromatic compounds through extended supply chains. Food service providers represent the fastest-growing end-user channel as restaurant operators reduce scratch-cooking labor through prepared broth bases.
FDA nutrition labeling requirements and USDA organic certification standards shape formulation decisions and market access thresholds for manufacturers distributing across United States retail and food service channels. The EU Green Deal and F-Gas Regulation indirectly pressure packaging transitions as European importers demand lower-carbon aseptic alternatives to steel cans. Stakeholders must monitor evolving sodium-reduction mandates from health regulators and decide whether to front-load reformulation investments or segment portfolios across compliant and legacy variants.
Market Dynamics
Clean-label reformulation under FDA and USDA frameworks is forcing ingredient sourcing restructuring across shelf-stable and refrigerated formats, compressing legacy supply chains while opening premium positioning for transparent broth portfolios.
Growth Catalysts
- Refrigerated Distribution Infrastructure:Cold-chain expansion into secondary US metropolitan markets enables velocity growth for perishable broth concentrates previously constrained to coastal urban centers.
- EU Green Deal Packaging Mandates:European import requirements for lower-carbon aseptic alternatives accelerate Tetra Pack adoption for volatile aromatic preservation in extended supply chains.
- Quick-Service Restaurant Broth Bases:Labor cost pressures in North American food service drive prepared broth substitution for scratch-cooking, expanding commercial volume demand.
Market Restraints
- Organic Input Cost Volatility:USDA organic certification requirements for clean-label portfolios expose margins to weather-driven vegetable and bone supply fluctuations.
- Steel Can Supply Concentration:Domestic US can manufacturing consolidation creates single-source vulnerability for mass-market shelf-stable producers.
- Sodium Reduction Technical Limits:FDA nutrition labeling thresholds clash with consumer taste expectations, forcing portfolio segmentation that fragments production scale economies.
Strategic Opportunities
- Functional Ingredient Convergence:Collagen peptides and adaptogenic herb integration into premium broths targets wellness-oriented household segments with elevated willingness-to-pay.
- Direct-to-Consumer Subscription Channels:Refrigerated last-mile delivery partnerships bypass traditional retail slotting constraints for emerging regional broth brands.
- IRA Clean Energy Tax Credits:Domestic US processing facility thermal efficiency upgrades qualify for federal incentives that offset aseptic filling equipment capital requirements.
Industry Challenges
- Clean-Label R&D Talent Scarcity:Formulation chemistry expertise for natural preservative systems without synthetic additives commands premium compensation in competitive labor markets.
- Multi-Jurisdiction Certification Timelines:Simultaneous USDA organic and FDA facility registration approvals delay new product commercialization by 8-14 months.
- Legacy ERP Integration Friction:Cold-chain inventory tracking requirements for refrigerated SKUs strain shelf-stable-optimized enterprise systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soup & Broth Market |
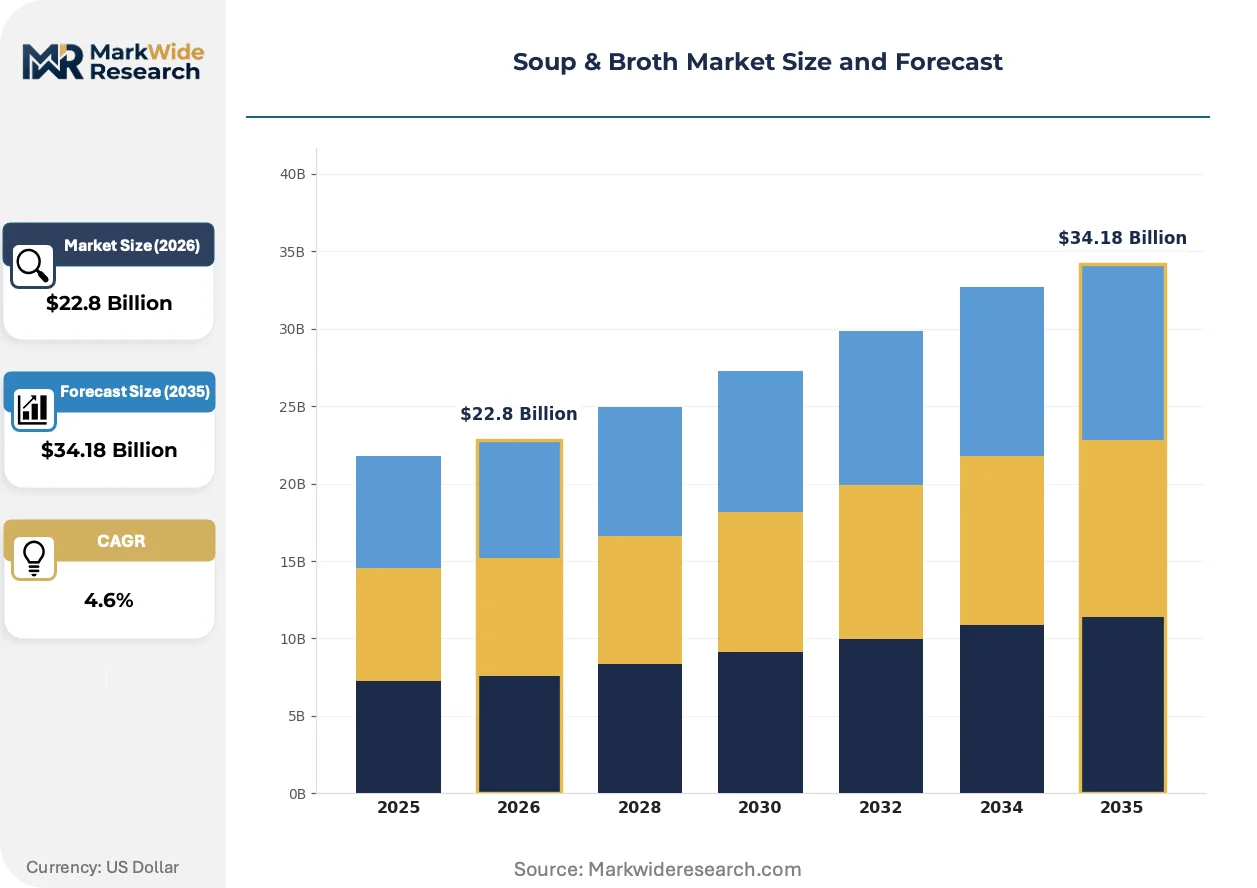
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $34.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned Soup, Instant Noodle Soup, Broth Concentrates, Liquid Broth Packaging Type: Tetra Packs, Glass Bottles, Pouches, Cans Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Food Stores End User: Households, Restaurants, Cafeterias, Food Service Providers |
| Companies Covered | Campbell Soup Company, Nestlé S.A, General Mills, The Kraft Heinz Company, Conagra Brands, Unilever, Baxters Food Group Limited, Pacific Foods of Oregon, College Inn, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soup & Broth Market Trends and Innovations
Electrification of thermal processing and precision fermentation are compressing traditional simmering timelines while aseptic barrier technologies preserve volatile compounds through extended distribution. These shifts reconfigure capital allocation between equipment, formulation, and packaging.
High-pressure processing (HPP) is electrifying cold-pasteurization for refrigerated broths, eliminating thermal degradation of heat-sensitive amino acids. Premium wellness brands and regional start-ups are adopting HPP at accelerating pace. The technology is electrifying shelf-life extension without chemical preservatives, compressing the advantage gap between refrigerated and shelf-stable formats.
REACH chemical restriction expansions and F-Gas Regulation phase-downs are forcing European importers to reject steel-can shipments with high-carbon coating chemistries. Manufacturers serving EU markets are accelerating aseptic carton transitions. Tetra Pack oxygen barrier specifications are tightening procurement standards for aromatic compound preservation.
Food service operators are unbundling broth procurement from protein purchasing, creating specialized vendor relationships for prepared bases distinct from raw ingredient suppliers. Restaurant groups with 50-plus unit footprints are consolidating broth sourcing through approved manufacturer lists. This behavior is most visible in Texas and Florida metropolitan clusters where labor cost pressures exceed national averages.
Soup & Broth Market Segmentation
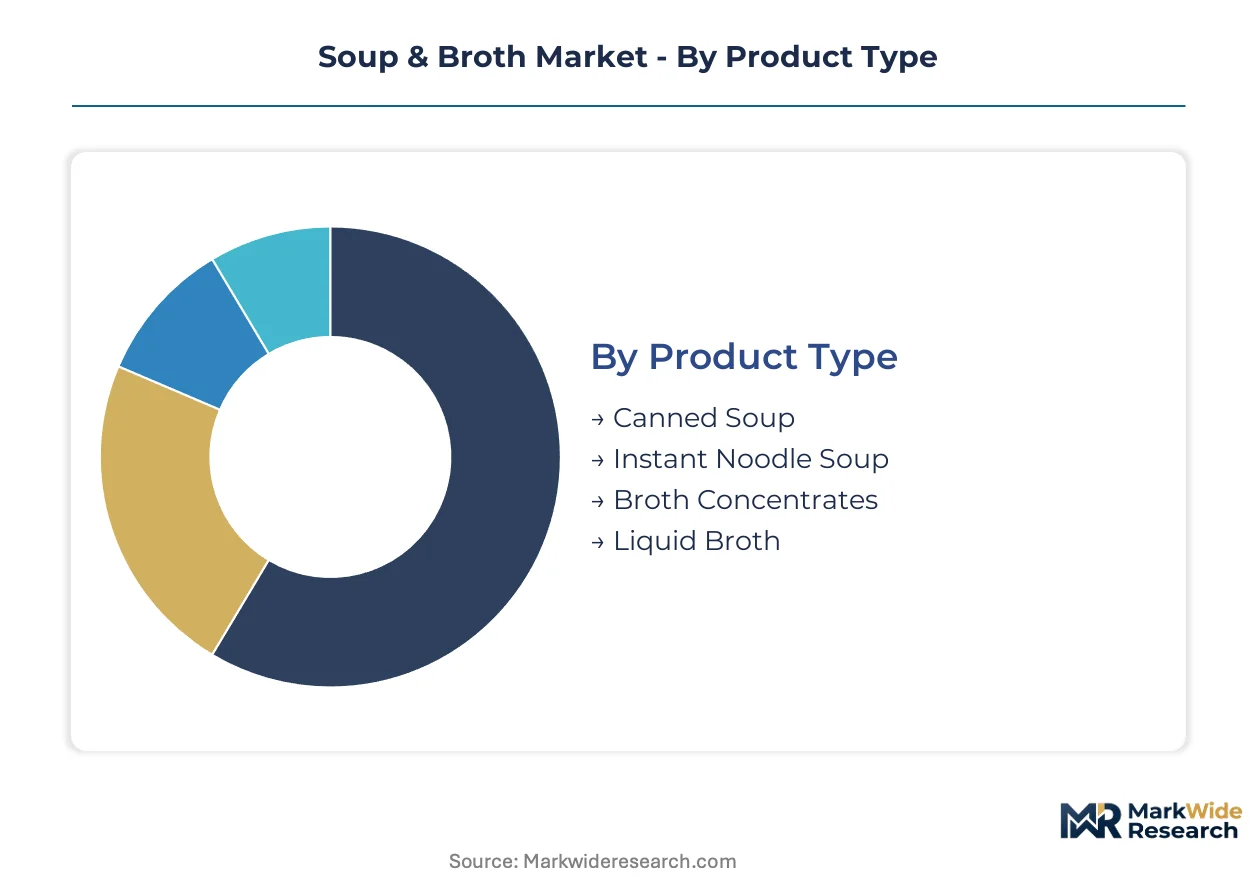
Soup and broth manufacturers configure product portfolios across four intersecting dimensions where packaging technology, channel access, and end-use specifications determine margin capture. Segmentation choices directly constrain formulation flexibility, cold-chain requirements, and pricing architecture.
Product Type:
Buyers trade off convenience against preparation control, with shelf-stable formats competing against perishable alternatives on storage flexibility and flavor fidelity.
- Canned Soup:Thermal processing achieves commercial sterility in steel or aluminum vessels, with sodium levels and cream-base formulations optimized for ambient distribution. Mass-market retail in the United States and Germany absorbs the highest volumes, though velocity is plateauing as refrigerated alternatives expand shelf space.
- Liquid Broth:Aseptic or refrigerated filling preserves volatile aromatic compounds at 2-8% solids content, commanding price premiums in wellness-oriented households. United States coastal metropolitan markets and direct-to-consumer subscription channels are absorbing capacity expansions fastest.
- Instant Noodle Soup:Dehydrated vegetable and protein components require reconstitution, with flavor sachet chemistry adapted to regional taste profiles in Asia-Pacific markets.
- Broth Concentrates:Reduced-moisture formulations enable freight efficiency and extended ambient shelf life, with dilution ratios calibrated for food service portion control.
Canned Soup leads on scale; Liquid Broth leads on momentum.
Packaging Type:
Material selection locks in oxygen barrier performance, thermal processing compatibility, and end-of-life disposal pathways that shape regulatory compliance costs.
- Tetra Packs:Laminated paperboard with aluminum oxygen barriers preserves heat-sensitive compounds through aseptic filling, with F-Gas Regulation and EU Green Deal mandates accelerating adoption for European import compliance. Carton recycling infrastructure gaps in secondary United States markets constrain penetration.
- Cans:Steel and aluminum formats dominate shelf-stable soup economics, with domestic United States manufacturing consolidation creating supply vulnerability for high-volume producers. Coating chemistry restrictions under REACH are forcing reformulation of interior lacquers for EU-bound shipments.
- Pouches:Flexible multilayer films reduce freight cube and enable microwave-venting features, with retort processing compatibility expanding into premium soup applications.
- Glass Bottles:Inert surfaces eliminate migration concerns for organic-certified broths, though weight and fragility limit distribution radius to premium retail channels.
Cans dominate volume; Tetra Packs are climbing the fastest.
Distribution Channel:
Channel selection determines slotting fee exposure, temperature control obligations, and consumer demographic access that shape promotional investment levels.
- Supermarkets:Refrigerated case placement in United States conventional and natural grocery chains drives velocity for perishable broth SKUs, with planogram negotiations favoring multi-format suppliers. Secondary metropolitan expansion into Texas and Florida clusters is absorbing cold-chain infrastructure investment.
- Online Retail:Direct-to-consumer and third-party marketplace fulfillment bypass slotting constraints, with insulated packaging and last-mile cold-chain partnerships enabling regional brand reach. Subscription models for bone broth and functional varieties are gaining share fastest in wellness segments.
- Convenience Stores:Grab-and-go soup cups and microwaveable formats target immediate consumption occasions, with shelf-stable dominance and limited refrigerated capacity.
- Specialty Food Stores:Curated organic and artisanal broth selections command premium positioning, with smaller case quantities and higher service levels.
Supermarkets anchor volume; Online Retail shows steepest expansion trajectory.
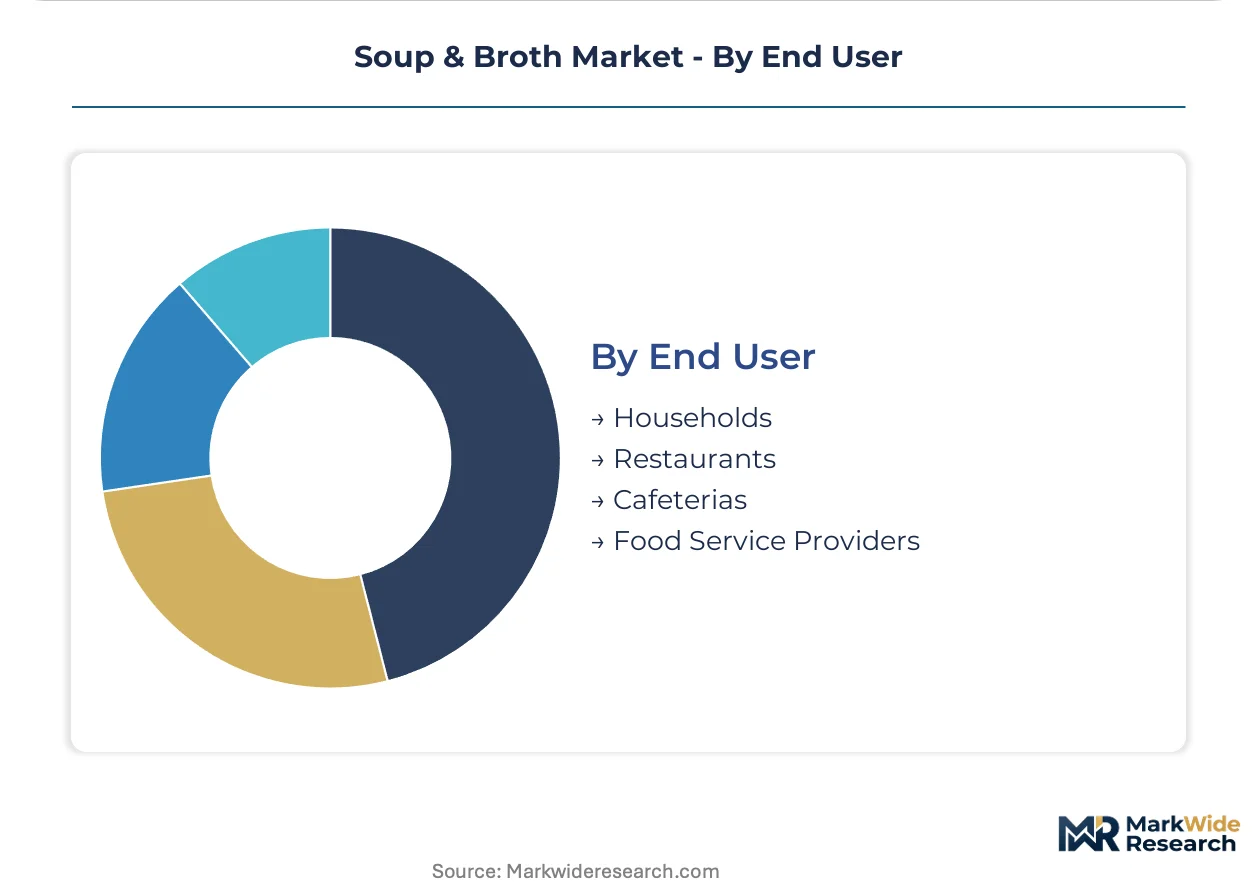
End User:
Volume concentration and specification stringency diverge sharply between household preparation and commercial food service procurement.
- Food Service Providers:Quick-service restaurants and multi-unit operators in North America are consolidating prepared broth sourcing through approved manufacturer lists, with labor cost pressures driving substitution for scratch-cooking. Texas and Florida metropolitan clusters exhibit highest adoption velocity for prepared bases.
- Households:Wellness-oriented consumers in United States coastal markets are expanding refrigerated broth and functional soup purchases, with clean-label and collagen-fortified variants commanding price multiples.
- Restaurants:Independent operators balance prepared base convenience against menu differentiation claims, with broth procurement unbundling from protein purchasing.
- Cafeterias:Institutional feeding operations in schools, hospitals, and corporate facilities prioritize cost control and nutritional compliance over flavor complexity.
Households lead on absolute volume; Food Service Providers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food science talent clusters in the United States, Switzerland, and Japan anchor premium broth innovation, while manufacturing scale concentrates in Brazil and India for commodity soup production.
United States
Quick-service restaurant chains in Texas and Florida metropolitan clusters are consolidating prepared broth sourcing through approved manufacturer lists. FDA nutrition labeling requirements and USDA organic certification standards shape formulation decisions for manufacturers distributing across retail and food service channels. Greater Los Angeles and New York Metro absorb the highest volumes of refrigerated bone broth and functional varieties through direct-to-consumer subscription channels.
Germany
EU Green Deal packaging mandates and REACH chemical restrictions are accelerating Tetra Pack adoption for soup and broth exports to European markets. ECHA oversight of coating chemistries forces reformulation of interior lacquers for steel-can shipments bound for EU importers. The North Rhine-Westphalia industrial corridor hosts concentrated aseptic filling equipment manufacturing serving Central European processing facilities.
China
Instant noodle soup manufacturing scales in the Yangtze River Delta and Pearl River Delta supply Asia-Pacific demand with regionally adapted flavor sachet formulations. SAMR food safety standards and GB technical regulations govern additive thresholds and labeling requirements for domestic distribution. Zhengzhou and Wuhan metropolitan clusters specialize in dehydrated vegetable and protein component processing for reconstitution formats.
Brazil
Commodity soup production leverages domestic agricultural supply chains for vegetable and legume inputs serving Latin American markets. ANVISA sanitary surveillance requirements establish facility registration and good manufacturing practice standards for processed food distribution. São Paulo state concentrates canning infrastructure and thermal processing capacity for shelf-stable format export to Mercosur trade partners.
Japan
Precision fermentation and high-pressure processing adoption for premium dashi and broth concentrates targets wellness-oriented households with elevated willingness-to-pay. METI industrial policy and PMDA food sanitation law frameworks regulate novel processing technology deployment and functional ingredient claims. The Kanto region around Tokyo anchors R&D talent for natural preservative system development without synthetic additives.
Soup & Broth Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the soup and broth market, where integrated manufacturing groups hold shelf-stable scale advantages while regional start-ups capture refrigerated premium niches. The structure tiers between multinational conglomerates with diversified pantry portfolios, specialized broth houses with wellness positioning, and private-label manufacturers serving retail channel consolidation. Strategic moves concentrate on cold-chain infrastructure partnerships for last-mile refrigerated distribution and aseptic barrier technology licensing for volatile aromatic preservation.
Within the multinational conglomerate tier, Campbell Soup Company and Nestlé S.A occupy positions exemplifying scale-driven shelf-stable dominance and health-focused portfolio diversification respectively. Pacific Foods of Oregon represents the specialized wellness archetype with premium refrigerated broth positioning. Unilever sits within the emerging market adaptation segment where localized flavor architectures extend brand reach across diverse taste profiles.
| Leading Market Players |
|---|
| Campbell Soup Company |
| Nestlé S.A |
| General Mills |
| The Kraft Heinz Company |
| Conagra Brands |
| Unilever |
| Baxters Food Group Limited |
| Pacific Foods of Oregon |
| College Inn |
| Others |
Pricing and Supply Chain Analysis
Quick-service restaurant chains in Texas and Florida metropolitan clusters command contract-based long-term offtake agreements that compress margins for prepared broth suppliers while locking in volume commitments. This buyer concentration forces manufacturers to segment portfolios across compliant premium tiers and legacy mass-market variants.
Pricing Analysis
Bundled procurement of broth bases with protein purchasing is unbundling as restaurant operators separate prepared base sourcing from raw ingredient suppliers. Three-tier pricing structure across premium, standard, and economy levels stratifies by clean-label certification grade and refrigerated distribution reach. Cost compression in mass-market canned formats is intensifying because steel can supply consolidation limits alternative sourcing. Food service providers exhibit highest price sensitivity due to labor-cost pressures, while wellness-oriented households in coastal markets show lowest sensitivity for collagen-fortified functional varieties.
Supply Chain Analysis
Single-source vulnerability sits with domestic United States can manufacturing consolidation that exposes high-volume shelf-stable producers to supply disruption. Raw material sourcing draws from Brazil for vegetable and legume inputs, China for dehydrated components, and United States for organic-certified bone and vegetable supplies. Supply chain risk centers on tariff exposure for aluminum and steel inputs under shifting trade frameworks. Distribution runs through refrigerated last-mile partnerships for perishable SKUs and traditional retail slotting for ambient formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Soup and broth functions as a stable compounder where clean-label reformulation under FDA and USDA frameworks drives steady portfolio premiumization across retail and food service channels.
For Market Incumbents: Hedge against refrigerated format displacement by securing cold-chain infrastructure partnerships in secondary United States metropolitan markets. Campbell Soup Company and Nestlé S.A should accelerate aseptic barrier technology licensing to preserve volatile aromatic compounds through extended distribution. Threat of regional wellness start-ups capturing premium niches demands defensive certification investment in USDA organic and collagen-fortified product lines.
For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer the most penetrable route for emerging regional broth brands to bypass traditional retail slotting constraints. Target wellness-oriented households in Greater Los Angeles and New York Metro with functional ingredient convergence featuring adaptogenic herbs and collagen peptides. White-space exists in prepared broth bases for quick-service restaurant chains consolidating sourcing through approved manufacturer lists in Texas and Florida.
For Investors and Strategic Acquirers: Food service distributors are the most active acquirer in this space, consolidating prepared base suppliers to capture labor-cost-driven substitution trends. Long-term viability frames around cold-chain infrastructure maturity and clean-label R&D talent capture. Acquisition target archetype: regional wellness brands with HPP-equipped facilities and established direct-to-consumer fulfillment. Signal to watch is velocity of Tetra Pack adoption for EU Green Deal compliance among export-oriented processors.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | USDA organic certification unlocks price multiples over conventional canned formats in wellness segments. |
| Cold-Chain Infrastructure Partnership | Refrigerated last-mile delivery networks enable regional brands to bypass retail slotting constraints. |
| Aseptic Barrier Technology Licensing | Tetra Pack oxygen barriers preserve volatile aromatic compounds for EU Green Deal import compliance. |
| Functional Ingredient Integration | Collagen peptides and adaptogenic herbs target wellness households with elevated willingness-to-pay. |
| Direct-to-Consumer Channel Launch | Subscription models for bone broth bypass traditional supermarket planogram negotiations. |
Research Methodology
Direct dialogue with food service procurement directors, retail category buyers, R&D formulation chemists, and cold-chain logistics operators anchors qualitative grounding. Secondary validation draws from FDA nutrition labeling databases, USDA organic certification records, Nielsen retail audit data, and customs trade flows. Bottom-up and top-down triangulation cross-checks manufacturer capacity announcements against channel inventory velocity and end-user purchasing patterns.
Bottom-up modeling builds from individual SKU velocity across packaging formats, product types, and distribution channels. Segmentation dimensions include product type, packaging technology, channel access, and end-use specifications. CAGRs were derived from weighted average of historical trajectory and forward-looking capacity expansion announcements. Industry-specific forecast inputs incorporate cold-chain infrastructure buildout timelines and clean-label certification approval pipelines.
Regulatory timeline delays, organic input cost volatility, and cold-chain equipment financing constraints are the dominant revision risks. Forecasts reflect documented assumptions about substitution rates between shelf-stable and refrigerated formats. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Africa Soup Market
Processed Foods
United States Processed Meat Market
Processed Foods
Global Take Out Fried Chicken Market
Processed Foods
Imitation Whipped Cream Market
Processed Foods
India Spray Dried Food Market
Processed Foods
Fresh Pasta Market
Processed Foods
Coffee Creamer Market
Processed Foods
Yogurt Dip Market
Processed Foods
North America Ice Cream Market
Processed Foods
Shelf-Stable Soup Market
Processed Foods
United States Fresh Noodles Market
Processed Foods
Asia-Pacific Ice Cream Market
Processed Foods
South America Processed Meat Market
Processed Foods
Processed Meat Market
Processed Foods
Processed Cashew Market
Processed Foods
Low Moisture Food Market